
 Medical Flexible Packaging Market | 2026-2036
Medical Flexible Packaging Market Size, Share, and Industry Trends Forecast 2026-2036
Medical Flexible Packaging Market Intelligence
Asset-light leasing models for coextrusion lines is narrowing the capital barrier for mid-tier converters seeking pharmaceutical-grade certification. Amcor plc leverages backward integration into resin compounding to sustain margin control across multi-layer films. Berry Global Inc. anchors North American supply through high-speed pouch conversion capacity. Huhtamaki Oyj competes via specialized healthcare printing and sterilization-compatible coatings.
Medical flexible packaging comprises sterilizable, multi-layer polymer structures engineered to maintain barrier integrity against oxygen, moisture, and microbial ingress, typically constructed through coextrusion or adhesive lamination processes with seal strengths exceeding specified medical standards. Pouches and roll stock dominate unit volume due to compatibility with automated filling lines in pharmaceutical operations. Polyethylene and polypropylene laminates command the fastest expansion as converters replace PVC in response to REACH and RoHS pressures. Stand-up pouches and sachet formats are gaining share in hospital and clinic settings where unit-dose dispensing reduces contamination risk.
FDA enforces 21 CFR Part 820 quality system regulations that mandate validated sealing processes for sterile medical packaging, while the EU MDR requires documented barrier-performance testing for device市场准入. ISO 11607 standards govern seal strength and microbial barrier validation across both jurisdictions, creating compliance costs that favor suppliers with in-house testing laboratories. Stakeholders must monitor evolving ECHA restrictions on per- and polyfluoroalkyl substances that threaten existing high-barrier coating chemistries.
Market Dynamics
Pharmaceutical manufacturers are consolidating sterile barrier packaging specifications around multi-layer coextrusion technologies, forcing converters to recalibrate capital deployment toward validated cleanroom capacity and in-house barrier testing infrastructure.
Growth Catalysts
- EU MDR compliance deadlines:Device manufacturers across Germany, France, and Italy are accelerating qualification of ISO 11607-validated pouch suppliers to meet notified body submission timelines.
- Hospital unit-dose dispensing:Stand-up pouch formats are displacing bulk vial packaging in surgical centers and outpatient clinics where contamination control protocols have tightened.
- Polyethylene laminate substitution:REACH Article 33 restrictions on PVC phthalates are redirecting formulation R&D toward PE-PP multilayer structures with comparable oxygen barrier performance.
Market Restraints
- Ethylene feedstock volatility:Crude-linked PE resin pricing swings compress converter margins on fixed-price pharmaceutical supply agreements.
- Cleanroom capacity concentration:Sterile barrier film extrusion lines cluster in southern Germany and northern Italy, creating single-source risk for pan-European device manufacturers.
- Perfluorinated coating phase-out:ECHA restriction proposals threaten existing high-barrier coating chemistries before fluorine-free alternatives achieve equivalent moisture protection.
Strategic Opportunities
- Indian pharmaceutical export packaging:CDSCO-aligned sterile barrier certification programs are opening qualification pathways for converters serving US and EU-bound generic drug manufacturers.
- Biologics cold-chain formats:Insulated pouch structures with integrated phase-change materials address temperature excursion risks in cell therapy distribution.
- Digital printing integration:Healthcare-compliant inkjet systems enable lot-specific serialization without plate changeover downtime, compressing short-run economics.
Industry Challenges
- ISO 11607 validation timelines:Sterile barrier qualification protocols require 18-24 month accelerated aging studies, delaying new product revenue recognition.
- Coextrusion technician scarcity:Specialized knowledge of multilayer die geometry and MDO stretching ratios is concentrated among aging workforces in Germany and Switzerland.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Medical Flexible Packaging Market |
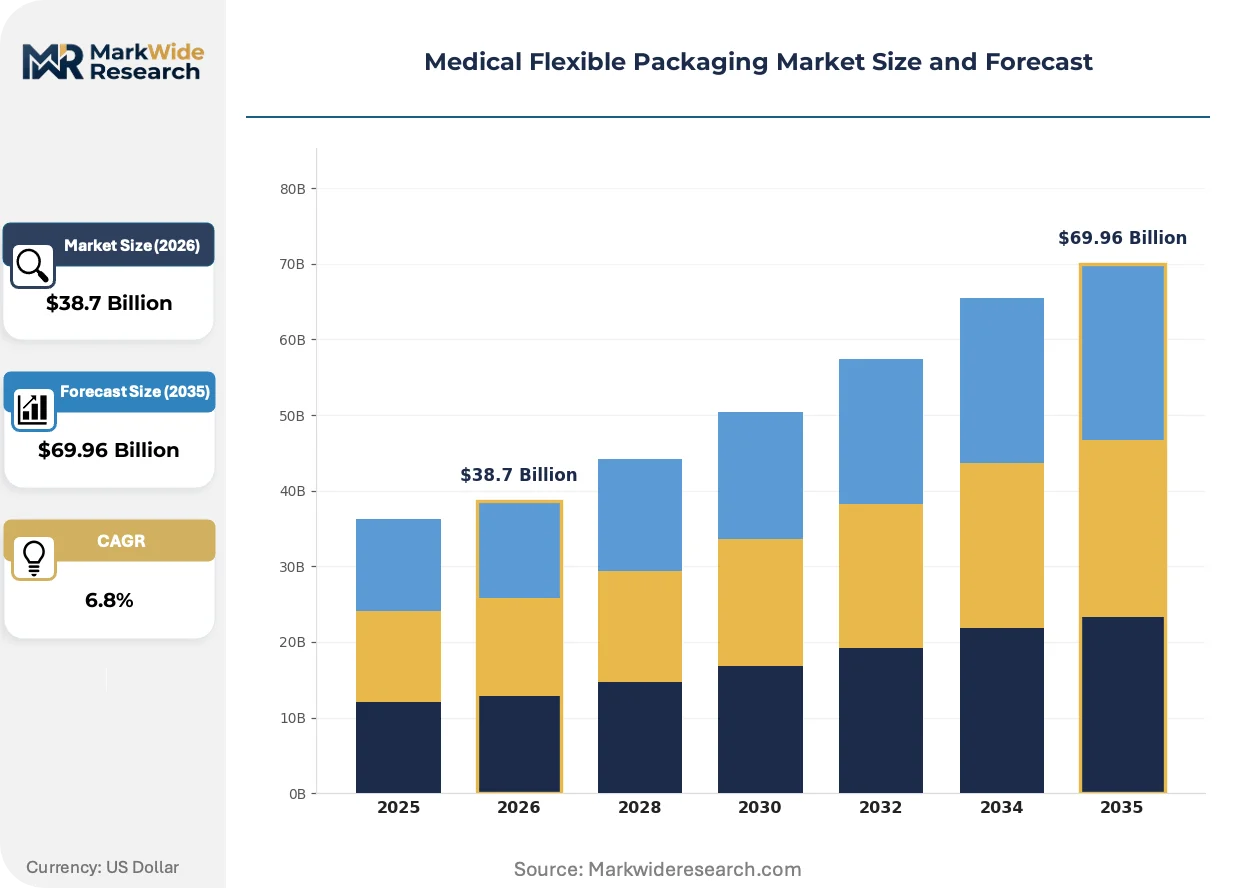
| Market Size in 2026 | $38.7 Billion |
| Market Size in 2035 | $69.96 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Pouches, Bags, Films, Laminates Material: Polyethylene, Polypropylene, PVC, Paper End User: Pharmaceuticals, Hospitals, Clinics, Laboratories Packaging Type: Stand-Up Pouches, Sachets, Blisters, Roll Stock |
| Companies Covered | Amcor plc, Berry Global Inc., Sealed Air, AptarGroup, Inc., WINPAK LTD., Mondi, Huhtamaki Oyj, Coveris, WestRock Company, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Medical Flexible Packaging Market Strategic Shifts & Innovations
Digital traceability infrastructure and sustainable material transitions are restructuring how pharmaceutical packaging specifications are developed, tested, and enforced across sterile barrier supply chains.
Machine vision inspection systems are digitizing seal integrity verification on high-speed pouch conversion lines. Contract packagers serving orthopedic device manufacturers are retrofitting existing thermoforming equipment with AI-driven defect detection at throughput rates exceeding 400 units per minute. This technology is digitizing quality documentation workflows, compressing batch release timelines from days to hours while satisfying FDA 21 CFR Part 11 electronic record requirements.
REACH Annex XVII restrictions on intentionally added microplastics are compelling reformulation of medical film slip agents and anti-static coatings. ECHA consultation timelines suggest enforcement against polymer processing aids will tighten between 2026 and 2028. German and Dutch converters are accelerating qualification of bio-based alternatives ahead of regulatory deadlines, prioritizing peelable lidstock applications where coefficient of friction performance is most critical.
Consolidated procurement of sterile barrier systems is displacing fragmented multi-vendor sourcing at large pharmaceutical manufacturers. Pfizer, Novartis, and Roche have centralized packaging specification authority under global supply chain functions, reducing qualified supplier lists by 40-60 percent. This concentration is most visible in Switzerland and Germany, where device-packing operations now favor converters with integrated printing, sterilization, and distribution capabilities over specialized single-process vendors.
Medical Flexible Packaging Market Segmentation
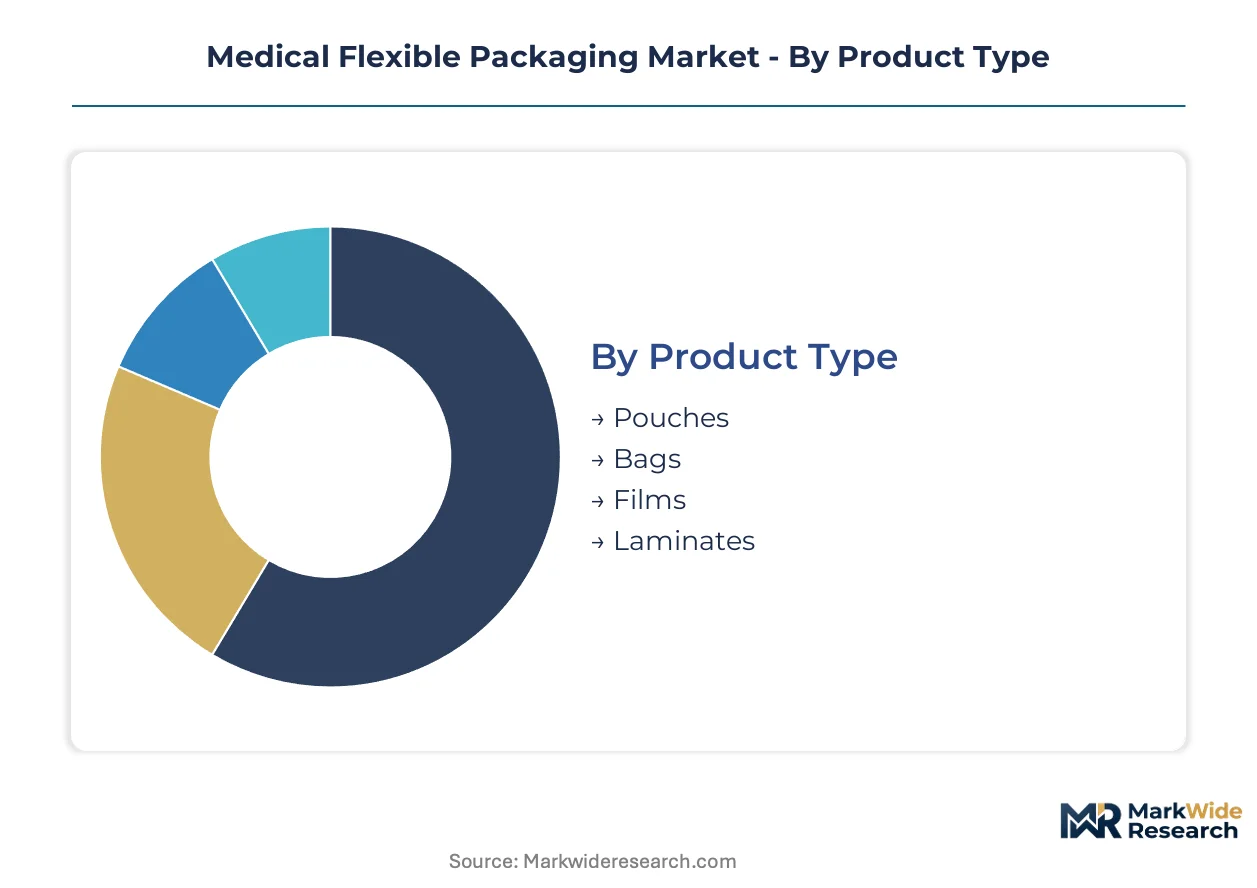
Segmentation in medical flexible packaging reflects divergent sterilization protocols, barrier-performance requirements, and automation compatibility across pharmaceutical manufacturing and clinical settings. Understanding these divisions illuminates where capital deployment concentrates and which specifications command premium pricing.
Product Type:
Pouches and roll stock turn over fastest due to continuous consumption on automated filling lines, while laminates and bags cycle more slowly through qualification-intensive procurement processes.
- Pouches:Sterilizable, multi-layer polymer structures with validated seal strengths exceeding ISO 11607 thresholds. Demand concentrates in German orthopedic device manufacturing where automated sterile barrier systems require high-throughput pouch formats compatible with gamma and ethylene oxide sterilization cycles.
- Roll Stock:Continuous-web flexible materials supplied to pharmaceutical contract packagers for in-line forming and sealing operations. Swiss and German generic drug manufacturers favor roll stock for cost efficiency at scale, though qualification timelines stretch 18-24 months for new supplier onboarding.
- Bags:Larger-format flexible containers for bulk pharmaceutical ingredients and medical device kits.
- Films:Single-layer or coextruded sheet materials requiring secondary conversion into finished packaging formats.
Pouches dominate installed base. Roll stock is where expansion concentrates.
Material:
Cost tiers separate commodity resins from engineered multi-layer structures, with substitution dynamics driven by regulatory pressure on legacy chemistries.
- Polyethylene:Dominant resin in coextruded sterile barrier constructions, offering moisture resistance and sealability. REACH Article 33 restrictions on PVC phthalates are redirecting formulation R&D toward PE-PP multilayer structures with comparable oxygen barrier performance in French and Italian device packaging operations.
- Polypropylene:High-clarity, heat-resistant polymer critical for autoclave-sterilizable applications. German converters prioritize PP-rich laminates for surgical kit packaging where steam sterilization compatibility is mandatory.
- PVC:Legacy material facing phased reduction across EU medical packaging due to ECHA scrutiny on plasticizers and chlorinated polymer waste streams.
- Paper:Fiber-based substrates for breathable sterile barrier systems, typically paired with polymer films in Tyvek-style constructions.
Polyethylene commands the largest volume position. Polypropylene is climbing the fastest as autoclave-compatible demand expands.
End User:
Customer-type segmentation reveals divergent specification authority, with pharmaceutical manufacturers driving standardization while hospital procurement favors flexible, small-lot formats.
- Pharmaceuticals:Drug manufacturers and contract development organizations requiring validated sterile barrier systems for FDA and EMA submissions. Consolidated procurement at Pfizer, Novartis, and Roche has reduced qualified supplier lists by 40-60 percent, concentrating volume with converters offering integrated printing, sterilization, and distribution capabilities.
- Hospitals:Surgical centers and inpatient facilities shifting toward unit-dose dispensing formats. Stand-up pouches are displacing bulk vial packaging in German and Swiss hospital systems where contamination control protocols have tightened.
- Clinics:Outpatient and specialty care settings with lower volume but higher format variety requirements.
- Laboratories:Diagnostic and research facilities requiring sterile barrier packaging for reagents, controls, and specimen transport.
Pharmaceuticals anchor revenue concentration. Hospitals are gaining share fastest as point-of-care packaging specifications proliferate.
Packaging Type:
Maturity gradients separate established formats from emerging structures, with digital printing integration reshaping economics for short-run segments.
- Stand-Up Pouches:Self-supporting flexible containers with bottom gusset construction enabling vertical display and dispensing. Hospital and clinic adoption in Germany and France is accelerating where unit-dose protocols reduce contamination risk in surgical and outpatient settings.
- Roll Stock:Continuous-web supply format for high-speed automated packaging lines. Pharmaceutical manufacturers in Switzerland and Germany favor roll stock for cost efficiency at scale, though the format requires substantial downstream conversion investment.
- Sachets:Small, single-dose flexible packets for oral solid dosage and topical applications.
- Blisters:Thermoformed cavity-plus-lidding structures, technically rigid-flexible hybrids, for tablet and capsule unit-dose packaging.
Roll stock dominates installed base. Stand-up pouches are gaining share fastest as hospital procurement shifts toward unit-dose formats.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany runs a structural surplus in sterile barrier film exports to neighboring EU device manufacturers, while the United States and China remain net importers of pharmaceutical-grade coextrusion capacity. Switzerland and India are emerging as specialized qualification hubs serving cross-border regulatory submissions.
Germany
Orthopedic device manufacturers in Bavaria and Baden-Württemberg consume half of Europe's certified sterile barrier pouch output. EU MDR notified body deadlines through 2026 are compressing supplier qualification timelines to 12 months. The Stuttgart-Tübingen corridor hosts the densest concentration of cleanroom extrusion lines serving pan-European pharmaceutical packaging demand.
United States
FDA 21 CFR Part 820 enforcement has intensified post-2023 inspection cycles for sterile barrier validation documentation. Pharmaceutical contract packagers in New Jersey and North Carolina are consolidating qualified supplier lists to reduce audit burden. The Research Triangle Park cluster anchors domestic capacity for gamma-compatible multi-layer film production.
Switzerland
Roche and Novartis procurement centralization has reduced their sterile barrier vendor pools by 50 percent since 2022. Swissmedic device packaging guidelines exceed baseline EU MDR requirements for seal-strength documentation. The Basel-Zurich corridor concentrates Europe's highest-value pharmaceutical packaging specification authority.
China
NMPA alignment with ISO 11607 standards since 2021 has opened qualification pathways for domestic converters serving export markets. Yangtze River Delta pharmaceutical manufacturers are importing German coextrusion technicians to accelerate sterile barrier certification. The Suzhou-Wuxi cluster hosts the fastest-growing cleanroom film capacity serving Asia-Pacific biologics distribution.
India
CDSCO sterile barrier certification programs are attracting investment from converters targeting US ANDA and EU MDR submissions. Gujarat and Maharashtra pharmaceutical exporters are qualifying local pouch suppliers to replace European import dependency. The Ahmedabad-Pune corridor is consolidating domestic capacity for FDA-inspected generic drug packaging.
Medical Flexible Packaging Market Key Industry Players
On the supply side, the industry is consolidating around three strategic tiers: integrated resin-to-converter operators, specialized healthcare packaging pure-plays, and regional contract conversion networks. Tier-one players control captive resin compounding and cleanroom extrusion infrastructure. Tier-two competitors differentiate through sterilization-compatible coating formulations and healthcare-compliant printing. Tier-three participants compete on short-run flexibility and regional logistics proximity. M&A activity concentrates on cleanroom capacity acquisition and backward integration into resin supply.
Among integrated packaging conglomerates, Amcor plc and Berry Global Inc. exemplify the scale-driven archetype with captive control over multi-layer film supply chains. Huhtamaki Oyj occupies a specialized position within the healthcare-dedicated tier, anchoring European demand for sterilization-compatible printed formats. These three entities collectively represent the competitive spectrum from resin integration through downstream conversion.
| Leading Market Players |
|---|
| Amcor plc |
| Berry Global Inc. |
| Sealed Air |
| AptarGroup, Inc. |
| WINPAK LTD. |
| Mondi |
| Huhtamaki Oyj |
| Coveris |
| WestRock Company |
| Others |
Cost & Logistics Intelligence
Undercapacity in southern German cleanroom extrusion lines is tightening supplier pricing power while forcing pharmaceutical manufacturers into longer-term offtake commitments. This utilization squeeze elevates barriers for mid-tier converters seeking ISO 11607 certification, concentrating margin capture among established operators with validated capacity.
Pricing Analysis
Industrial OEM buyers anchor contract-based long-term offtake structures, with three-tier pricing stratification across FDA-validated premium grades, standard ISO 11607-compliant tiers, and economy formats for non-sterile applications. Price differentiation hinges on barrier-performance certification and volume scale, with gamma-compatible multilayer structures commanding substantial premiums over ethylene-oxide-only alternatives. Cost compression in standard-grade polyethylene laminates is intensifying because REACH-driven PVC substitution has flooded mid-market capacity. Hospital procurement teams exhibit highest price sensitivity due to centralized GPO contracting, while Swiss biologics manufacturers show lowest sensitivity given cold-chain performance requirements.
Supply Chain Analysis
Ethylene feedstock supply draws from German petrochemical complexes, Saudi Arabian crackers, and US Gulf Coast export terminals, with polypropylene resin sourcing concentrated in Belgian and Dutch polymer plants. Raw material dependencies rest on naphtha-linked PE pricing, propylene monomer availability, and specialized sterilization-compatible coating chemistries. Single-source vulnerability concentrates in fluorinated moisture-barrier coatings threatened by ECHA restriction proposals. Distribution runs through regional converter hubs serving pan-European device manufacturers, with just-in-time roll stock deliveries dominating pharmaceutical contract packaging workflows.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Barrier testing and validation services represent a service-attach opportunity expanding faster than base film supply, as pharmaceutical manufacturers outsource ISO 11607 documentation to accelerate notified body submissions.
For Market Incumbents: Entrench through backward integration into resin compounding and captive cleanroom capacity expansion in the Stuttgart-Tübingen corridor. Consolidate position by acquiring specialized healthcare printing operations threatened by digital printing displacement. Prioritize in-house barrier testing laboratory investment to compress customer qualification timelines. For New Entrants and Emerging Players: Pursue CDSCO-aligned sterile barrier certification for Indian pharmaceutical export packaging, where European import dependency creates qualification gaps. Target Gujarat and Maharashtra generic drug manufacturers with FDA-inspected pouch supply. Lead with asset-light leasing models for coextrusion lines to bypass capital barriers. For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among converters with integrated validation services and multi-year pharmaceutical supply agreements. Five-to-ten year viability favors operators with EU MDR and FDA dual-certification infrastructure. Acquisition focus should center on mid-tier German cleanroom extrusion assets. The signal to watch is ECHA fluorinated coating restriction timelines, which would force accelerated capital redeployment toward fluorine-free barrier technologies.| Strategic Initiative | Industry Significance |
|---|---|
| Cleanroom Capacity Expansion | Validates sterile barrier output for EU MDR notified body submissions in Germany. |
| Backward Integration into Resin Compounding | Captures margin control amid ethylene feedstock volatility from crude-linked pricing. |
| Digital Printing Integration | Enables lot-specific serialization without plate changeover for short-run biologics formats. |
| Fluorine-Free Barrier Coating Development | Preempts ECHA restriction enforcement threatening existing high-moisture protection chemistries. |
| CDSCO Certification Program Investment | Opens qualification pathways for US ANDA and EU MDR-bound Indian generic drug exports. |
Research Approach
Demand-side practitioners and supply-side operators were both consulted through structured primary interviews with sterile barrier packaging engineers, pharmaceutical procurement directors, notified body auditors, and coextrusion line technicians. Secondary validation drew from FDA 510(k) filings, EU MDR technical documentation databases, ECHA restriction proposal consultations, and ISO 11607 certification registries. Bottom-up volume modeling triangulated against top-down resin consumption data from European polymer trade associations.
Calibration against historical qualification timeline data and sterilization protocol adoption curves anchored projections across the analysis window. Segmentation dimensions included product format, material composition, sterilization compatibility, end-user type, and regional regulatory cluster. CAGRs derived from elasticity-adjusted demand modeling incorporating REACH substitution dynamics and EU MDR compliance deadline effects. Forecast inputs included pharmaceutical contract manufacturing growth and biologics cold-chain expansion rates.
Macroeconomic conditions sit as an overlay; deviation in crude oil price trajectories or ethylene cracker operating rates would shift the trajectory of resin-linked pricing and converter margin structures. Forecasts reflect documented assumptions regarding regulatory enforcement timelines and substitution elasticity parameters. Cross-checking against EMA notified body submission statistics and pharmaceutical packaging import customs data is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pharmaceutical Packaging
Global Parenteral Packaging Market
Pharmaceutical Packaging
Pharmaceutical Printed Cartons Market
Pharmaceutical Packaging
Pharmaceuticals Pouch Market
Pharmaceutical Packaging
Injection Bottles Market
Pharmaceutical Packaging
Single Dose Dispensers Market
Pharmaceutical Packaging
Pharmaceutical 3PL Market
Pharmaceutical Packaging
Tablet Bottle Market
Pharmaceutical Packaging
Clinical Trial Packaging Market
Pharmaceutical Packaging
Europe Pharmaceutical Packaging Market
Pharmaceutical Packaging
United States Pharmaceutical Contract Packaging Market
Pharmaceutical Packaging
APAC Pharmaceutical Packaging Market
Pharmaceutical Packaging
Topical Drugs Packaging Market
Pharmaceutical Packaging
Pharmaceutical Vial Fillers Market
Pharmaceutical Packaging
Vaccine Packaging Market
Pharmaceutical Packaging
Middle East and Africa Ampoules Packaging Market
Pharmaceutical Packaging
Glass Medicine Bottles Market