
 Oridonin Market | 2026-2036
Oridonin Market Size, Share, and Industry Trends Forecast 2026-2036
Oridonin Market Insights
Synthetic oridonin analogs are repositioning cost structures for compound suppliers serving pharmaceutical clients. Tauto Biotech leverages captive extraction capabilities from Rabdosia rubescens biomass to sustain margin control across the value chain. Chengdu Biopurify Phytochemicals anchors its competitiveness on chromatographic purification scale, while Beijing Mesochem Technology differentiates through custom synthesis of oridonin derivatives for research institutions.
Oridonin is a bioactive ent-kaurane diterpenoid extracted primarily from Isodon rubescens, characterized by a molecular weight of 364.43 g/mol and demonstrated activity against NF-κB and STAT3 signaling pathways; pharmaceutical applications exploit its antitumor, anti-inflammatory, and antibacterial properties in investigational drug development. Powder formulations dominate current manufacturing output due to stability in bulk ingredient handling, while injection delivery modes command premium positioning as clinical trials advance parenteral administration protocols. Agricultural applications represent an emerging segment where oridonin's pesticidal properties against plant pathogens are gaining trial traction.
China's NMPA governs botanical drug substance registration through revised technical guidelines, while the FDA maintains botanical drug guidance requiring phase-appropriate characterization of complex mixtures. Japan's PMDA recognizes kampo-derived compounds within its regulatory framework, creating differentiated market access conditions across these three jurisdictions. Stakeholders must monitor evolving pharmacopoeial monograph standards that will determine specification thresholds for export-grade material.
Market Dynamics
Pharmaceutical formulators are consolidating procurement around captive extraction capabilities as Chinese NMPA botanical drug reforms compress approval timelines, forcing mid-scale suppliers to secure biomass contracts or exit oncology ingredient supply.
Growth Catalysts
- Botanical drug pathway acceleration:China's NMPA streamlined technical guidelines for complex mixtures, reducing registration friction for oridonin-based investigational drugs entering oncology pipelines.
- Kampo integration protocols:Japan's PMDA recognition of traditional compound derivatives within modern pharmacology frameworks creates regulatory precedent for oridonin formulations in East Asian markets.
- NF-κB inhibitor demand:Immunology research programs targeting STAT3 signaling pathways are expanding compound procurement for preclinical and phase-appropriate characterization studies.
Market Restraints
- Biomass supply concentration:Rabdosia rubescens cultivation clusters in Henan and Hubei provinces create geographic dependency risk for extraction-dependent suppliers.
- Chromatographic purification cost structure:High-performance liquid chromatography scale-up requires substantial solvent and resin expenditure, compressing margins for non-integrated processors.
- Synthetic substitute development:Semi-synthetic ent-kaurane analogs from laboratory fermentation routes threaten to displace plant-derived material in cost-sensitive research applications.
Strategic Opportunities
- Agricultural biocide registration:Oridonin's demonstrated activity against plant pathogens opens crop protection applications pending EPA and PMRA residue tolerance determinations.
- Parenteral formulation advancement:Injection delivery mode development for clinical trials commands premium positioning as sponsors advance parenteral administration protocols beyond powder bulk.
- Dual carbon alignment:China's MEE biomass utilization incentives favor sustainable extraction operations with verified carbon accounting for export-grade material.
Industry Challenges
- Pharmacopoeial monograph harmonization:Divergent specification thresholds between USP, ChP, and JP standards complicate multi-jurisdiction batch release for international shipments.
- Specialized purification talent scarcity:Chromatographic method development expertise for diterpenoid isolation concentrates among senior analytical chemists in Shanghai and Chengdu clusters.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Oridonin Market |
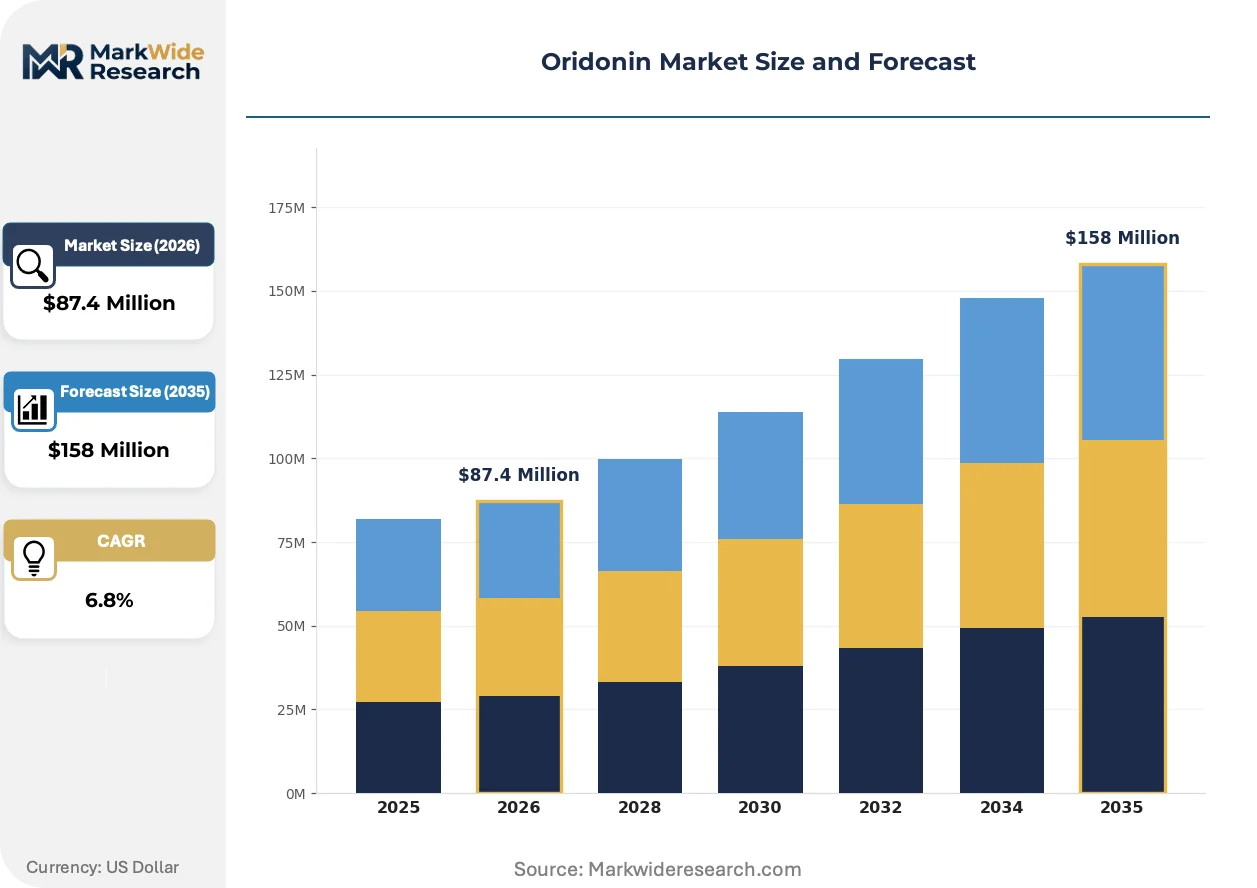
| Market Size in 2026 | $87.4 Million |
| Market Size in 2035 | $158 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Powder, Capsule, Tablet, Liquid Application: Pharmaceutical, Nutraceutical, Cosmetic, Agricultural Delivery Mode: Oral, Topical, Injection, Transdermal End User: Healthcare Providers, Research Institutions, Consumers, Farmers |
| Companies Covered | Di ErGe, Fei Yu, MacLin, Tauto Biotech, Chengdu Biopurify Phytochemicals, Xi'an Natural Field Bio-Technique, Hefei TNJ Chemical, Shanghai Tauto Biotechnology, Beijing Mesochem Technology, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Oridonin Market Trends and Innovations
Continuous processing technologies and regulatory science advances are compressing development timelines for botanical drug substances, while demand-side consolidation favors suppliers with integrated quality systems.
Synthetic biology routes to ent-kaurane scaffolds are overtaking traditional extraction for research-grade material supply. Contract research organizations in Boston and Basel are adopting fermentation-derived oridonin analogs to reduce batch-to-batch variability in screening libraries. This technology is overtaking agricultural sourcing for early-phase pharmaceutical applications, forcing biomass processors to defend position through GMP certification rather than cost alone.
REACH registration requirements for novel botanical substances are tightening substance characterization obligations for EU market access. ECHA guidance on complex mixture identification creates compliance overhead for multi-component Isodon extracts. European pharmaceutical sponsors are responding by demanding single-entity oridonin certificates of analysis with specified impurity profiles, shifting procurement toward chromatographic purification specialists.
Formulators are consolidating supplier relationships around qualified vendors with dual US FDA and China NMPA inspection histories. Oncology drug developers in Suzhou and San Diego are reducing approved supplier lists from multiple extraction houses to single-source arrangements with integrated quality control. This concentration pattern is most visible in parenteral-grade material procurement, where sponsor audit burden drives preference for vertically integrated manufacturers with captive biomass and in-house analytical capabilities.
Oridonin Market Segmentation
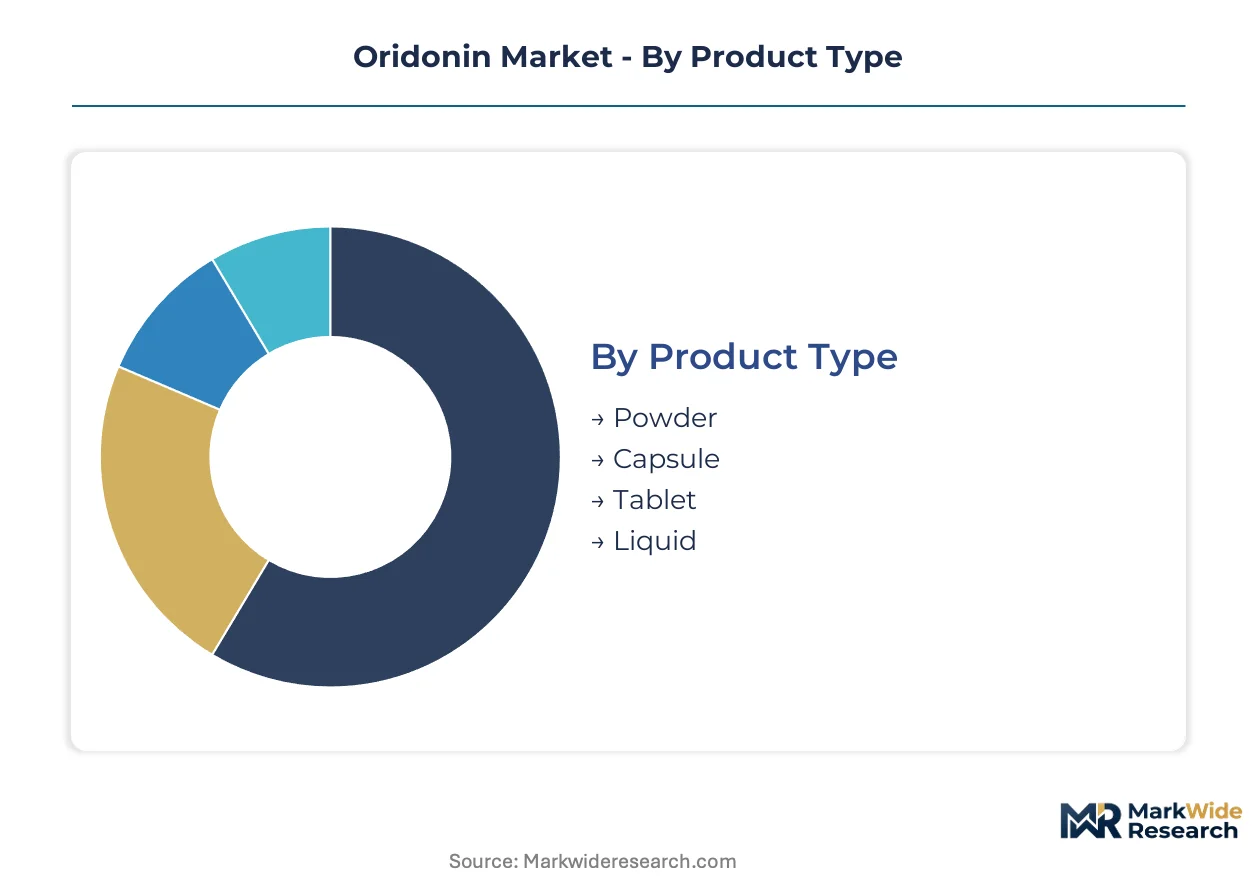
Oridonin procurement patterns diverge sharply across formulation formats and end-use specifications. Pharmaceutical sponsors demand parenteral-grade purity thresholds that agricultural biocide developers ignore entirely.
Product Type:
Buyers select powder versus finished dosage forms based on in-house formulation capability and regulatory filing strategy.
- Powder:Bulk diterpenoid material with standardized ent-kaurane content serves as the foundational input for pharmaceutical compounding and research-scale screening. Demand concentrates among CDMOs in Suzhou and Basel seeking GMP-certified starting material for oncology pipeline candidates.
- Capsule:Encapsulated oridonin enables direct-to-consumer nutraceutical positioning and simplifies investigator-initiated trial protocols. Japanese kampo formulators in Tokyo and Osaka prefer this format for traditional medicine modernization applications.
- Tablet:Compressed dosage forms suit high-volume nutraceutical manufacturing with established excipient compatibility profiles.
- Liquid:Solution formulations facilitate pediatric and geriatric administration where solid dosage swallowability presents barriers.
Volume sits with powder; growth tilts toward capsule.
Application:
End-use economics separate pharmaceutical-grade specifications from agricultural tolerance thresholds.
- Pharmaceutical:Investigational drug development targeting NF-κB and STAT3 pathways commands the most stringent analytical characterization. Sponsors in Boston and Shanghai require certificates of analysis with specified impurity profiles for IND-enabling studies.
- Nutraceutical:Dietary supplement applications leverage oridonin's anti-inflammatory positioning in functional food formulations. Chinese TCM-derived brands in Guangzhou and Chengdu dominate this segment through e-commerce distribution.
- Cosmetic:Topical formulations exploit antibacterial properties for acne and dermatitis indications in K-beauty and J-beauty product lines.
- Agricultural:Biocide development against plant pathogens represents the steepest expansion trajectory pending EPA and PMRA residue determinations.
Pharmaceutical procurement anchors revenue; agricultural trials are climbing the fastest.
Delivery Mode:
Route of administration selection tracks clinical trial phase and bioavailability requirements.
- Oral:First-pass metabolism limits systemic exposure but enables convenient chronic administration in outpatient settings. Nutraceutical manufacturers in Hangzhou and Los Angeles standardize on this delivery mode for consumer-accessible products.
- Injection:Parenteral administration bypasses hepatic metabolism for maximum plasma concentration in acute oncology protocols. Phase-appropriate material commands substantial price premiums from sponsors advancing IV formulations.
- Topical:Dermal application targets localized inflammatory conditions with minimal systemic absorption.
- Transdermal:Patch-based delivery sustains therapeutic levels through controlled release kinetics for chronic immunomodulation.
Oral formats dominate unit volume; injection commands value concentration.
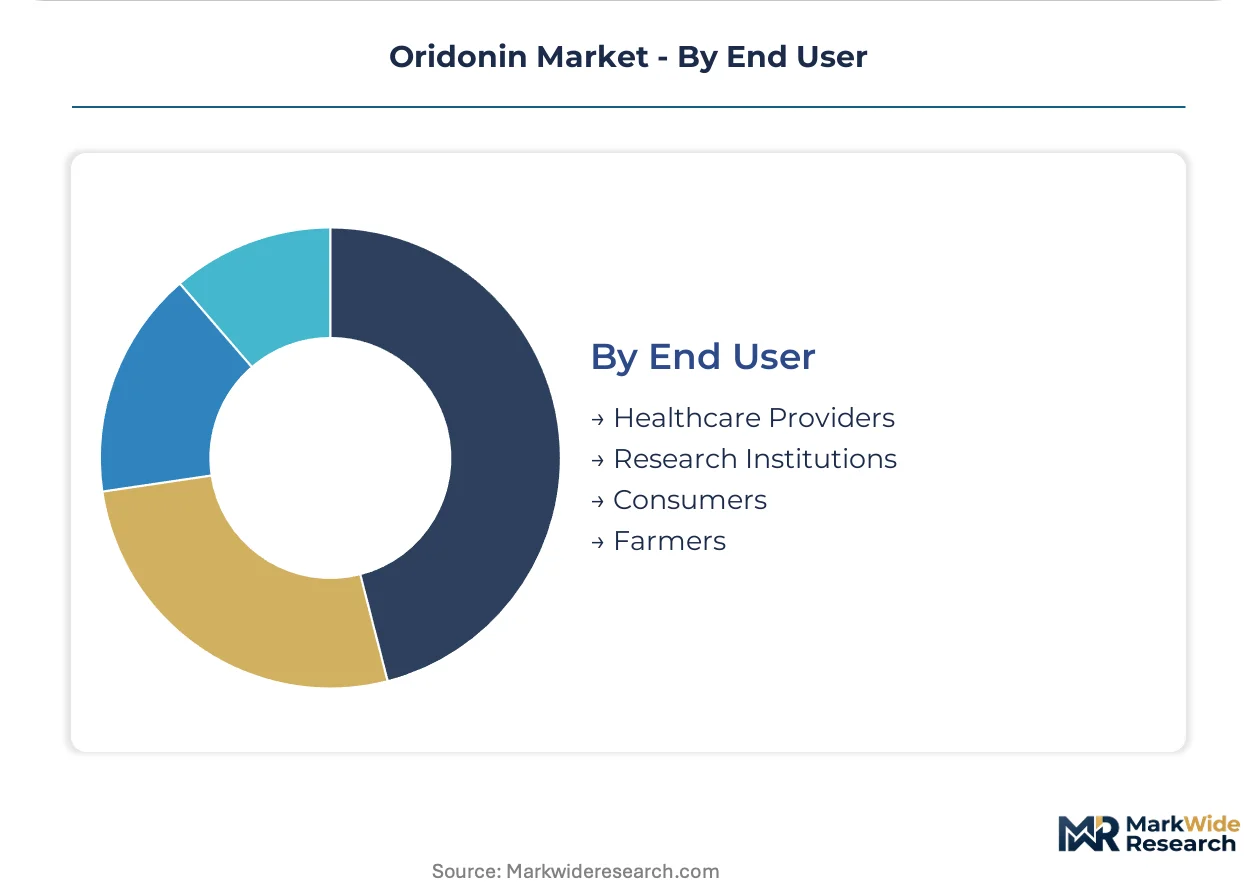
End User:
Customer type determines specification tier, audit intensity, and contract structure.
- Healthcare Providers:Hospital systems and specialty clinics sourcing compounded preparations require documentation of USP or ChP compliance. Major academic medical centers in Beijing and Philadelphia drive demand for standardized extract protocols.
- Research Institutions:Universities and CROs prioritize batch-to-batch consistency for reproducible preclinical data. Synthetic biology laboratories in Basel and Cambridge increasingly specify fermentation-derived analogs to reduce phytochemical variability.
- Consumers:Direct purchasers through TCM pharmacies and wellness platforms respond to traditional medicine branding and origin claims.
- Farmers:Agricultural cooperatives trial oridonin-based biocides for fungal pathogen control in high-value fruit and vegetable cultivation.
Research institutions absorb the most SKU variety; healthcare providers are consolidating supplier lists fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China's Yangtze River Delta special economic zones concentrate extraction capacity for Rabdosia rubescens biomass, drawing pharmaceutical sponsors seeking NMPA-registered starting material. Japan's Kansai region anchors kampo modernization demand, while North American research clusters in Boston and San Diego drive fermentation-derived analog procurement.
China
Henan and Hubei provinces host the dominant Rabdosia rubescens cultivation belts, supplying biomass to extraction facilities in Suzhou and Chengdu. NMPA's 2023 botanical drug technical guidelines compressed IND timelines for oridonin-based oncology candidates. Shanghai chromatography specialists now command premium positioning for parenteral-grade purification.
Japan
PMDA recognition of kampo-derived compounds within modern pharmacology frameworks creates regulatory precedent for oridonin formulations. Tokyo and Osaka formulators prefer encapsulated formats for traditional medicine modernization. Osaka-based research institutions drive demand for standardized ent-kaurane reference materials.
United States
FDA botanical drug guidance requires phase-appropriate characterization of complex mixtures, shaping sponsor procurement toward single-entity certificates. Boston and San Diego CROs increasingly specify fermentation-derived analogs to reduce phytochemical variability. EPA residue tolerance determinations pending for agricultural biocide applications.
Switzerland
Basel contract research organizations anchor European demand for synthetic biology routes to ent-kaurane scaffolds. Swissmedic oversight of botanical investigational drugs creates compliance overhead favoring purified single-entity supply. Geneva-based sponsors demand REACH-registered material with specified impurity profiles.
South Korea
K-beauty formulators in Seoul exploit oridonin's antibacterial properties for topical dermatitis applications. MFDS cosmetic ingredient registration requirements concentrate procurement around GMP-certified extract houses. Busan biomass traders trial import arrangements with Henan cultivation cooperatives.
Oridonin Market Competitive Landscape
Branded specialists and contract manufacturers split share differently across segments, with extraction-dependent processors defending position through biomass control while synthetic biology entrants capture research-grade supply. The vendor base concentrates among Chinese purification houses with captive cultivation arrangements and fermentation specialists serving North American CROs. Three archetypes dominate: vertically integrated biomass processors, chromatographic purification specialists, and custom synthesis laboratories. Capacity expansion in continuous processing equipment and strategic partnerships for dual US-China regulatory filing support represent the dominant competitive moves.
Among China-based extraction houses, Tauto Biotech exemplifies the vertically integrated archetype through its captive Rabdosia rubescens biomass capabilities, while Chengdu Biopurify Phytochemicals occupies a position within the chromatographic purification tier. Beijing Mesochem Technology represents the custom synthesis vector serving research institutions with derivative production. These three anchors illustrate how geographic clustering around Henan cultivation belts and Shanghai analytical talent pools shapes competitive positioning.
| Leading Market Players |
|---|
| Di ErGe |
| Fei Yu |
| MacLin |
| Tauto Biotech |
| Chengdu Biopurify Phytochemicals |
| Xi'an Natural Field Bio-Technique |
| Hefei TNJ Chemical |
| Shanghai Tauto Biotechnology |
| Beijing Mesochem Technology |
| Others |
Pricing and Supply Chain Analysis
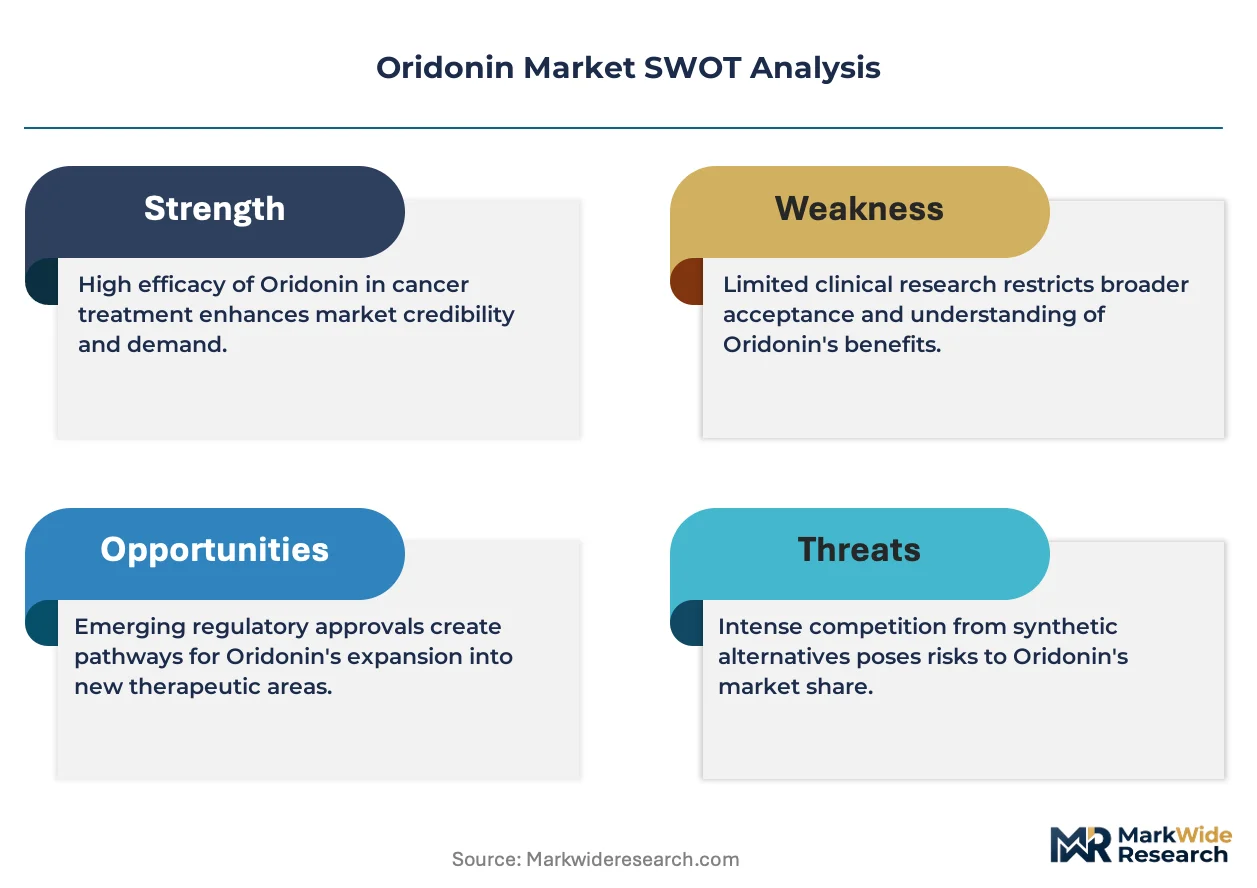
Family-owned extraction houses in Henan and Hubei provinces anchor upstream biomass control, translating cultivation scale into pricing discipline that resists spot-market volatility while forcing smaller processors toward contract manufacturing or exit.
Pricing Analysis
Short lead-time premiums for parenteral-grade oridonin separate urgent clinical trial sponsors from contract-negotiated volume buyers. Three-tier pricing structure across GMP-certified parenteral, research-grade chromatographic, and agricultural biocide specifications reflects certification burden and analytical intensity. Cost compression in research-grade powder stems from synthetic biology substitutes displacing plant-derived material. Agricultural cooperatives exhibit highest price sensitivity; oncology sponsors advancing IV formulations show lowest.
Supply Chain Analysis
Dual-sourcing mandates from Boston and San Diego CROs now require qualified backup suppliers for IND-enabling studies, fragmenting procurement across Henan biomass processors and Basel fermentation specialists. Raw material flows draw from Rabdosia rubescens cultivation belts, chromatographic resin inventories, and ent-kaurane precursor feedstocks. Single-source vulnerability concentrates in Shanghai analytical talent pools for high-resolution purification method development. Distribution runs through qualified vendor lists managed by sponsor quality assurance teams.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market consolidates around extraction-dependent processors with captive biomass and in-house chromatographic capabilities, as NMPA botanical drug reforms and synthetic biology substitution pressure weaker, non-integrated suppliers toward acquisition or closure.
For Market Incumbents: Cement biomass lock-in through long-term cultivation contracts with Henan and Hubei cooperatives before fermentation-derived analogs capture additional research-grade share. Expand Chengdu and Shanghai analytical headcount to defend parenteral-grade purification positioning against CDMOs building captive capabilities. NMPA dual-inspection history represents the critical lever for sponsor audit reduction. For New Entrants and Emerging Players: Agricultural cooperatives in California's Central Valley and Spain's Valencia region represent the most penetrable buyer archetype pending EPA and EFSA residue tolerance determinations. Fermentation-derived ent-kaurane scaffolds for preclinical screening libraries offer white-space entry with lower capital intensity than agricultural extraction. Partner with Boston CROs on synthetic biology routes to bypass biomass dependency entirely. For Investors and Strategic Acquirers: First parenteral-grade oridonin IND approval by a major oncology sponsor is the leading indicator that chromatographic purification specialists will command sustained premium pricing. Five-to-ten-year viability favors vertically integrated processors with dual US-China regulatory filing support over standalone extraction houses. Watch for NMPA botanical drug approval acceleration as the inflection signal for consolidation timing.| Strategic Initiative | Industry Significance |
|---|---|
| Captive Biomass Contracting | Long-term Rabdosia rubescens cultivation agreements in Henan secure upstream supply against fermentation substitution. |
| GMP Certification Investment | Dual NMPA-FDA inspection readiness qualifies suppliers for parenteral-grade oncology sponsor procurement. |
| Synthetic Biology Partnership | Fermentation-derived ent-kaurane scaffolds reduce batch-to-batch variability for Boston CRO screening libraries. |
| Agricultural Biocide Registration | EPA residue tolerance submissions open crop protection applications beyond pharmaceutical boundaries. |
| Continuous Processing Scale-Up | Chromatographic purification automation in Chengdu compresses unit costs for research-grade material. |
Research Methodology
Independent corroboration across extraction house operations directors, oncology drug development executives, and regulatory affairs leads at NMPA-registered manufacturers underwrites the qualitative findings on supply consolidation dynamics. Secondary validation draws from NMPA botanical drug technical guidelines, FDA botanical drug guidance documents, ClinicalTrials.gov oridonin protocol registrations, and customs trade data for Isodon-derived extract shipments. Bottom-up procurement pattern analysis triangulates against top-down market sizing from pharmaceutical ingredient demand models.
Comparable-period anchoring to pre- and post-2023 NMPA guideline revision windows structures the forecast framework across the projection horizon. Segmentation dimensions span formulation format, application grade tier, delivery mode, and regional regulatory cluster. CAGRs derive from sponsor pipeline progression rates and biomass cultivation expansion trajectories. Forecast inputs incorporate synthetic biology substitution elasticities and kampo integration protocol adoption curves.
Revisions become necessary when NMPA botanical drug approval timelines extend beyond sponsor planning assumptions or when EPA agricultural residue determinations accelerate biocide registration pathways. Deviation in synthetic biology cost curves or chromatographic resin supply disruptions would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pharmaceutical Ingredients
Piperacillin Sodium API Market
Pharmaceutical Ingredients
Kitasamycin Market
Pharmaceutical Ingredients
Global High Potency Active Pharmaceutical Ingredient (HPAPI) Market
Pharmaceutical Ingredients
Global Antazoline Market
Pharmaceutical Ingredients
Folinic Acid Market
Pharmaceutical Ingredients
Global Small Molecule API Market
Pharmaceutical Ingredients
Germany Active Pharmaceutical Ingredients (API) Market
Pharmaceutical Ingredients
Ferrous Succinate Market
Pharmaceutical Ingredients
Oral Doxycycline Hyclate Market
Pharmaceutical Ingredients
Antipyretic Analgesic Active Pharmaceutical Ingredients Market
Pharmaceutical Ingredients
Asia-Pacific Pharmaceutical Glycerine Market
Pharmaceutical Ingredients
Acetaminophen API Market
Pharmaceutical Ingredients
Large Molecule Drug Substance CDMO Market
Pharmaceutical Ingredients
Calcium Citrate Market
Pharmaceutical Ingredients
Rizatriptan Market
Pharmaceutical Ingredients
Silver Sulfadiazine Market