
 Mitotic Inhibitors Market | 2026-2036
Mitotic Inhibitors Market Size, Share, and Industry Trends Forecast 2026-2036
Mitotic Inhibitors Market Foresight
Albumin-bound paclitaxel formulations is rebalancing cost structures against conventional solvent-based delivery, compressing per-dose manufacturing economics while preserving efficacy profiles. Bristol Myers Squibb leverages its immuno-oncology portfolio to anchor combination regimens that incorporate mitotic inhibitors alongside checkpoint inhibitors. Novartis sustains manufacturing scale across European and North American injectable facilities, securing supply continuity for high-volume taxane production. Teva Pharmaceuticals competes through generic docetaxel and paclitaxel portfolios that occupy price-sensitive hospital procurement channels.
Mitotic inhibitors comprise a class of antineoplastic agents that arrest cell division by disrupting microtubule polymerization or depolymerization, with paclitaxel stabilizing microtubule bundles against disassembly while vincristine prevents tubulin polymerization entirely; these mechanisms enable cytotoxic selectivity against rapidly proliferating malignant tissues. Among product types, paclitaxel and docetaxel dominate hospital formularies due to established reimbursement codes and decades of clinical validation, though albumin-bound nanoparticle formulations command premium positioning in metastatic breast and pancreatic indications. Application segmentation reveals cancer treatment as the mature revenue core, while research applications represent the fastest-expanding category as academic centers probe resistance mechanisms and novel combination indices.
FDA oncology center review standards, EMA's centralized marketing authorization procedures, and WHO prequalification requirements collectively govern market access, with each framework imposing distinct stability testing and bioequivalence thresholds that shape development priorities. The EPA regulates manufacturing effluent from multi-ton semi-synthetic taxane production, adding environmental compliance costs that favor producers with captive fermentation or extraction capabilities. Stakeholders must monitor evolving biosimilar interchangeability designations and their cascading effects on procurement behavior across integrated delivery networks.
Market Dynamics
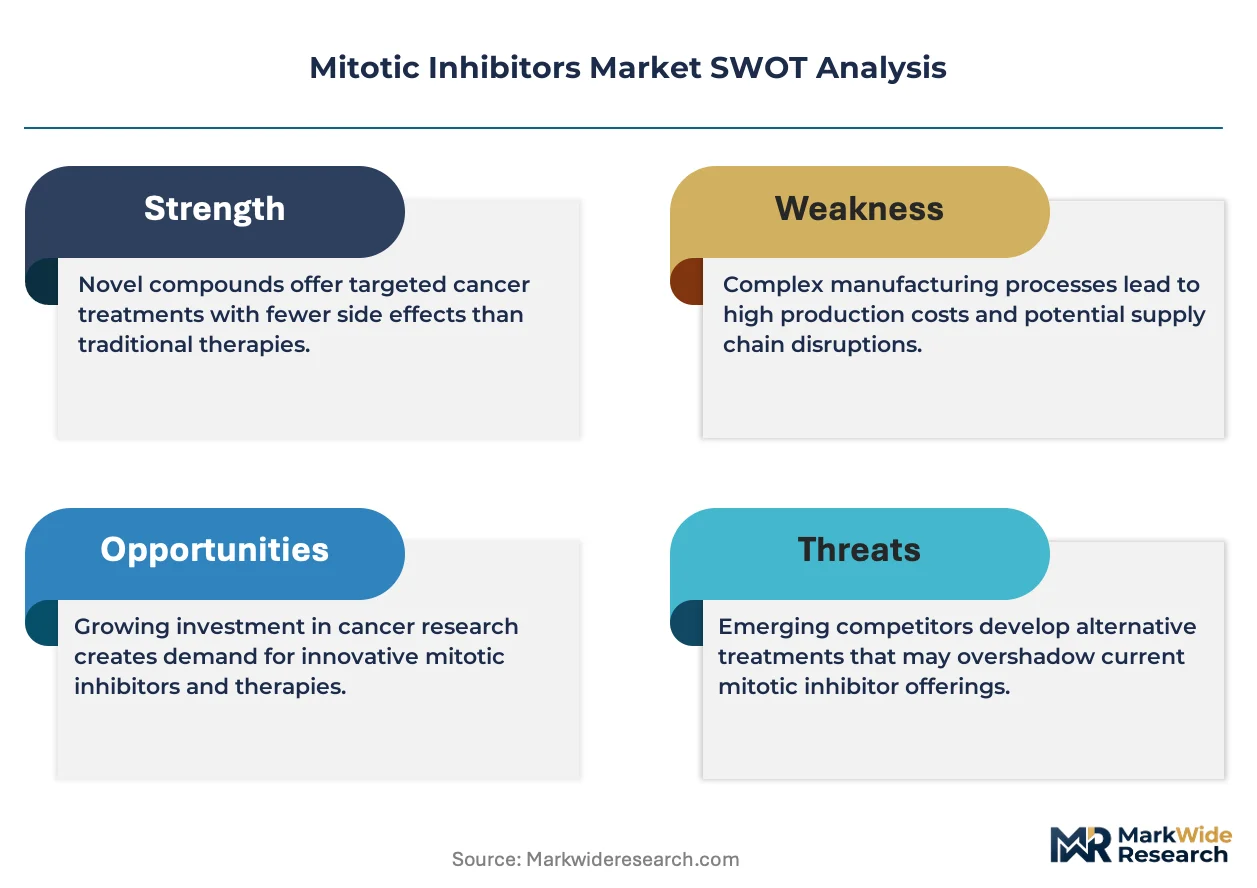
Albumin-bound nanoparticle formulations are compressing manufacturing economics against conventional solvent-based taxanes, forcing incumbents to reconfigure production assets and procurement contracts around high-yield fermentation or semi-synthetic extraction capabilities.
Growth Catalysts
- Accelerated FDA oncology pathways:The FDA's breakthrough therapy and fast track designations compress development timelines for novel taxane combinations, enabling earlier revenue capture for sponsors targeting metastatic indications.
- First-line chemotherapy protocol expansion:Oncology departments in tertiary hospitals are embedding paclitaxel-docetaxel regimens into standard-of-care pathways for breast, lung, and ovarian malignancies, institutionalizing recurring demand.
- Medicare reimbursement favorability:US Centers for Medicare & Medicaid Services reimbursement codes for infused taxane therapy sustain hospital formulary placement against oral oncology alternatives.
Market Restraints
- Taxane raw material concentration:Pacific yew bark and semi-synthetic precursors concentrate extraction capacity in limited fermentation facilities, exposing producers to botanical supply shocks.
- EPA manufacturing effluent compliance:Multi-ton taxane production generates solvent-laden wastewater requiring captive treatment infrastructure, elevating fixed costs for non-integrated manufacturers.
- Biosimilar interchangeability uncertainty:Pending FDA interchangeability designations for generic paclitaxel create procurement hesitation across integrated delivery networks awaiting substitution clarity.
Strategic Opportunities
- Indian hospital procurement expansion:CDSCO streamlined oncology approvals and government hospital tender programs create volume anchors for cost-optimized taxane suppliers.
- Research application acceleration:Academic centers probing microtubule resistance mechanisms represent uncaptured demand for high-purity mitotic inhibitor reference standards and combination screening libraries.
- EMA centralized authorization leverage:Mutual recognition procedures enable single-market authorization to cascade across EU member states, reducing redundant stability testing for European injectable facilities.
Industry Challenges
- Microtubule biology specialization gap:Formulation scientists with expertise in nanoparticle stabilization and lyophilization cycle development command scarcity premiums, constraining R&D throughput.
- Injectable facility certification timelines:EMA GMP inspections and FDA pre-approval manufacturing site reviews extend 18-24 months, delaying market entry for new production capacity.
- Combination regimen IP complexity:Patent thickets around checkpoint inhibitor-taxane pairings require intricate licensing negotiations, fragmenting development freedom-to-operate.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Mitotic Inhibitors Market |
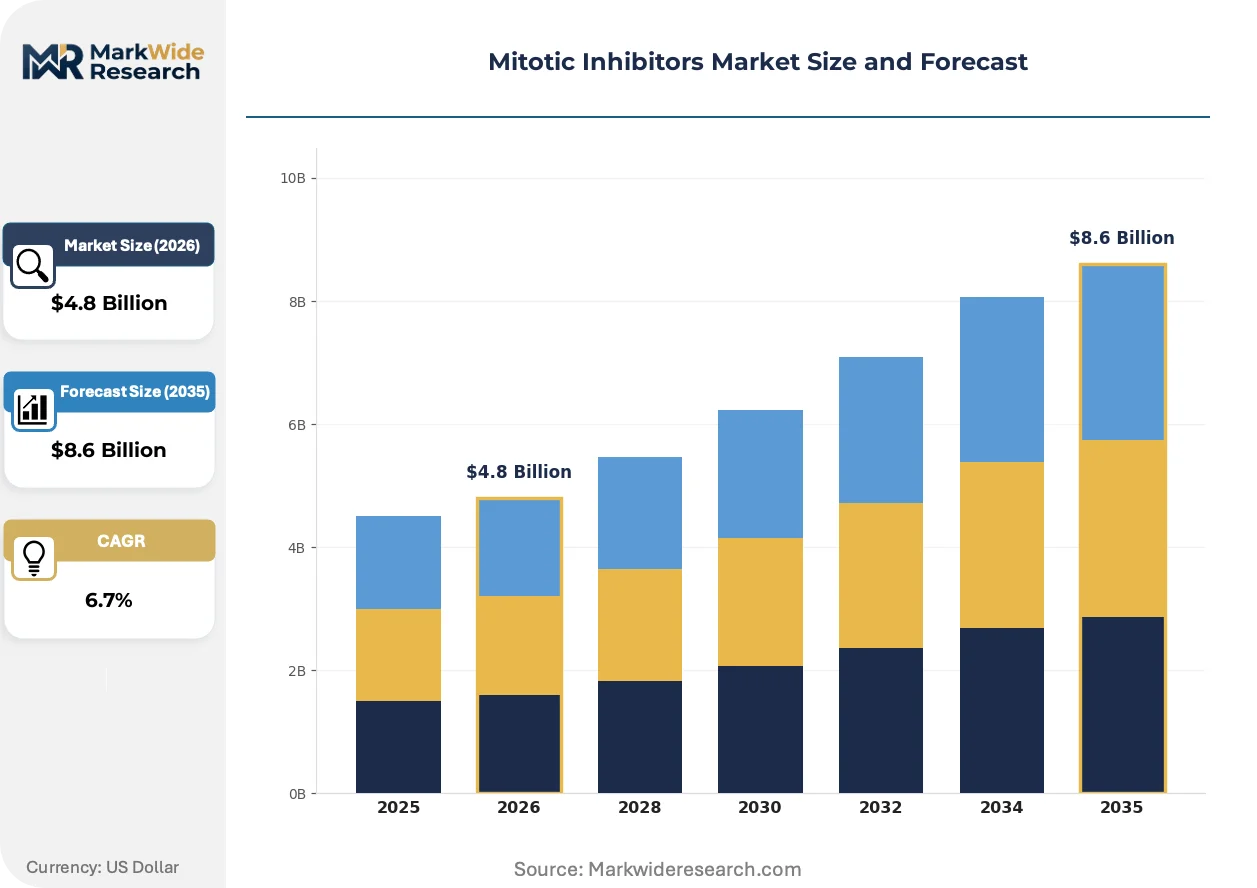
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $8.6 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Paclitaxel, Vincristine, Docetaxel, Etoposide Application: Cancer Treatment, Chemotherapy, Antitumor Therapy, Research Applications End User: Hospitals, Clinics, Research Institutes, Pharmacies Distribution Channel: Online Pharmacies, Retail Pharmacies, Wholesalers, Direct Sales |
| Companies Covered | Bristol Myers Squibb, Pfizer, Novartis, Merck & Co., Roche Holding, Teva Pharmaceuticals, Fresenius Kabi, Hikma Pharmaceuticals, Oasmia Pharmaceuticals, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Mitotic Inhibitors Market Shifts & Advancements
Formulation science and regulatory science are converging to redefine competitive moats in taxane delivery, with nanoparticle engineering and accelerated approval mechanics displacing traditional solvent-based manufacturing advantages.
Albumin-bound paclitaxel nanoparticles is rewriting the cost-efficacy calculus for metastatic breast and pancreatic protocols. Oncology infusion centers are adopting these formulations at the expense of conventional Cremophor-based delivery, compressing per-dose reimbursement differentials while preserving clinical outcome profiles. This technology is rewriting procurement specifications across US integrated delivery networks, forcing solvent-dependent manufacturers toward backward integration or exit.
EMA's centralized marketing authorization procedures are harmonizing bioequivalence thresholds across EU member states, reducing redundant clinical bridging studies for generic taxane sponsors. The industrial consequence is accelerated cross-border formulary placement for European injectable manufacturers with captive stability testing infrastructure. High-volume taxane producers in Germany and Switzerland are responding by consolidating batch release documentation under single qualified-person accountability.
Hospital procurement committees are unbundling after-sales technical support from drug acquisition contracts, treating taxane supply as commodity input rather than partnership relationship. Group purchasing organizations are displacing direct manufacturer negotiations in US hospital systems, compressing price transparency and service-level differentiation. This behavioral shift is most visible in Medicare-dependent oncology practices across the southeastern United States, where purchasing consortiums dominate formulary decision-making.
Mitotic Inhibitors Market Segmentation
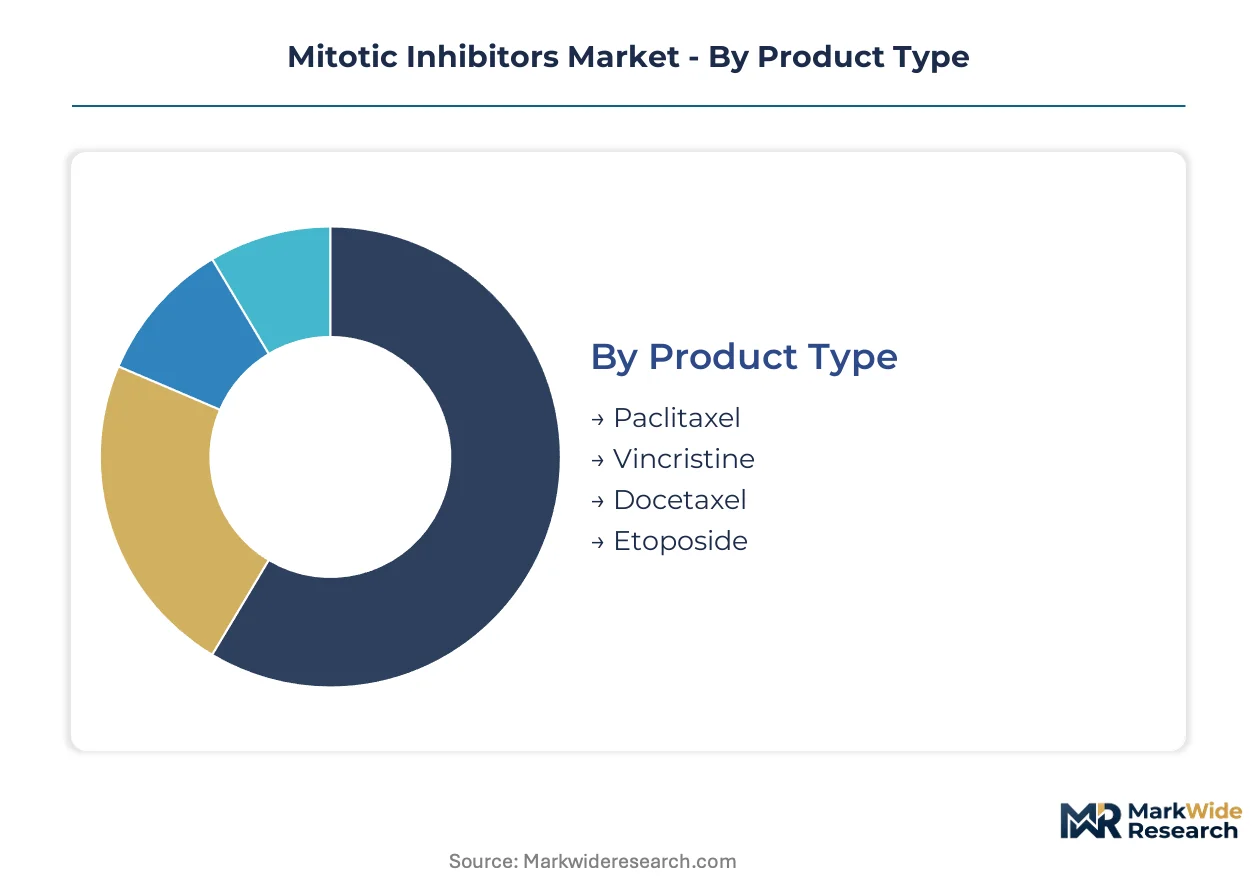
Mitotic inhibitor procurement patterns diverge sharply across buyer categories, with reimbursement status, clinical setting, and research intensity creating distinct demand profiles. Taxane selection and distribution pathways reflect institutional scale, regulatory environment, and therapeutic indication complexity.
Product Type:
Buyers in this category differentiate by formulation stability, solvent compatibility, and nanoparticle delivery capability rather than molecular mechanism alone.
- Paclitaxel:Stabilizes microtubule bundles against depolymerization through tubulin binding, with albumin-bound nanoparticle formulations commanding premium positioning in metastatic breast and pancreatic protocols across US integrated delivery networks. Demand concentrates in tertiary hospital oncology departments where Medicare reimbursement codes sustain infused therapy against oral alternatives.
- Docetaxel:Semi-synthetic taxane with higher aqueous solubility enabling solvent-free infusion protocols, preferred in prostate and gastric malignancy regimens where neuropathy profiles favor its selection. European hospital formularies in Germany and Switzerland anchor volume through EMA centralized procurement frameworks.
- Vincristine:Vinca alkaloid preventing tubulin polymerization entirely, restricted to pediatric leukemia and lymphoma protocols due to dose-limiting neurotoxicity.
- Etoposide:Topoisomerase II inhibitor with distinct microtubule-independent mechanism, deployed in testicular cancer and small-cell lung carcinoma combination regimens.
Volume sits with paclitaxel; growth tilts toward albumin-bound nanoparticle formulations.
Application:
Clinical validation depth and reimbursement maturity separate mature therapeutic deployment from emerging research demand in this dimension.
- Cancer Treatment:Established first-line protocols for breast, ovarian, and non-small-cell lung malignancies with decades of outcome data supporting hospital formulary placement. US tertiary oncology centers and European university hospitals drive recurring demand through protocol standardization.
- Research Applications:Academic centers probing microtubule resistance mechanisms and novel combination indices require high-purity reference standards and screening libraries. Demand is expanding most quickly at institutions with NIH and Wellcome Trust funding in Boston, London, and Singapore.
- Chemotherapy:Adjuvant and neoadjuvant regimens incorporating taxane backbones in curative-intent treatment sequences.
- Antitumor Therapy:Targeted delivery approaches and antibody-drug conjugates incorporating mitotic payloads.
Revenue concentrates in cancer treatment; steepest expansion trajectory belongs to research applications.
End User:
Procurement scale and technical sophistication determine access to formulation innovations and pricing tiers across buyer types.
- Hospitals:Tertiary oncology departments with captive infusion infrastructure and group purchasing organization membership capture preferential taxane pricing. Medicare-dependent systems across the southeastern United States institutionalize paclitaxel-docetaxel demand through protocol embedding.
- Research Institutes:Academic medical centers with NIH funding and core facility infrastructure drive high-purity standard demand for resistance mechanism studies. Cambridge, Massachusetts and Heidelberg anchor concentration.
- Clinics:Community oncology practices with limited infusion capacity rely on referral relationships for complex taxane administration.
- Pharmacies:Retail and specialty channels handling oral etoposide and limited injectable distribution in markets with relaxed infusion regulations.
Procurement volume aggregates at hospitals; capability investment flows toward research institutes.
Distribution Channel:
Cold-chain requirements and regulatory documentation intensity fragment channel selection by product format and geography.
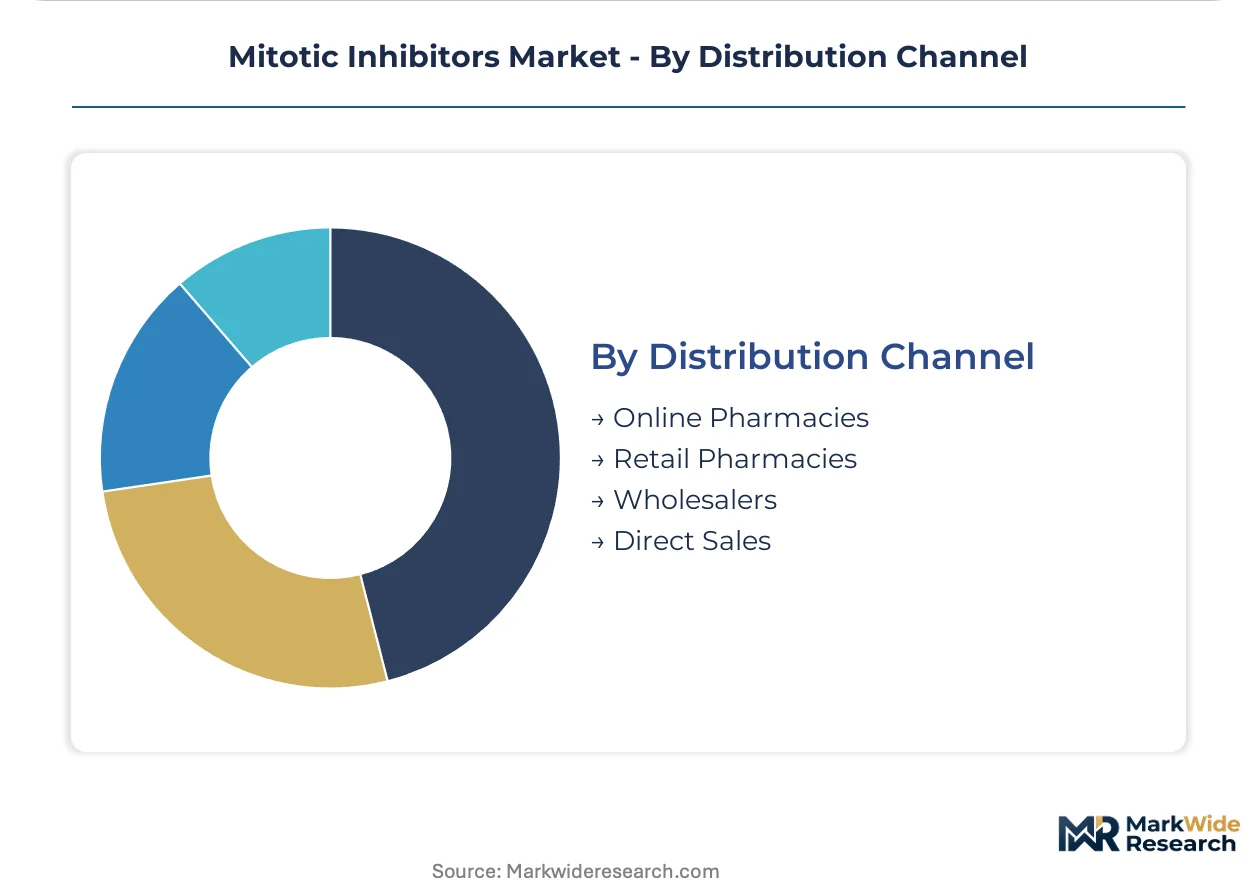
- Direct Sales:Manufacturer-to-hospital contracts for high-volume taxane supply with embedded technical support and batch traceability documentation. US integrated delivery networks and German hospital procurement consortia favor this channel for paclitaxel and docetaxel.
- Wholesalers:McKesson and AmerisourceBergen in the United States, plus Phoenix and Alliance Healthcare in Europe, handle temperature-controlled distribution to mid-tier hospitals and clinics lacking direct manufacturer relationships.
- Online Pharmacies:Limited to oral etoposide and research-grade standards in jurisdictions with explicit telemedicine oncology prescribing frameworks.
- Retail Pharmacies:Minimal role restricted to supportive care medications and oral oncology agents in select markets.
Direct sales capture hospital volume; wholesaler channels gain share in clinic and mid-tier expansion.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Special economic zones in India and tax-advantaged manufacturing corridors in Ireland concentrate active pharmaceutical ingredient production for taxane derivatives. FDA oncology review divisions in Maryland and EMA centralized authorization in Amsterdam govern market access timelines. Hospital procurement clusters in Massachusetts, Basel, and Hyderabad anchor demand concentration.
United States
Medicare reimbursement codes for infused taxane therapy sustain hospital formulary placement across tertiary oncology centers. FDA breakthrough therapy designations compress development timelines for novel paclitaxel combinations. The National Cancer Institute's clinical trial networks in Bethesda and Boston drive protocol standardization that institutionalizes recurring demand.
Germany
EMA centralized marketing authorization procedures enable single-market authorization to cascade across EU member states for injectable taxane facilities. Bavarian and Baden-Württemberg pharmaceutical clusters anchor high-volume fermentation capacity for semi-synthetic docetaxel precursors. German hospital procurement consortia favor direct manufacturer contracts with embedded batch traceability documentation.
India
CDSCO streamlined oncology approvals and government hospital tender programs create volume anchors for cost-optimized taxane suppliers. Pharmaceutical special economic zones in Hyderabad and Ahmedabad offer tax holidays that concentrate generic paclitaxel manufacturing. Indian contract research organizations in Bangalore and Mumbai support bioequivalence studies for export-oriented sponsors.
Switzerland
Swissmedic marketing authorization procedures align with EMA standards while preserving national flexibility for innovative formulation approvals. Basel-based injectable manufacturing facilities leverage proximity to German distribution networks for cross-border hospital supply. Swiss taxane producers maintain captive fermentation capabilities that buffer against Pacific yew bark supply volatility.
United Kingdom
NICE technology appraisals determine National Health Service reimbursement for albumin-bound paclitaxel formulations against conventional solvent-based alternatives. London and Cambridge academic medical centers drive research application demand for high-purity mitotic inhibitor reference standards. MHRA post-Brexit regulatory autonomy creates parallel review pathways that diverge from EMA centralized procedures.
Mitotic Inhibitors Market Competitive Landscape
Branded specialists and contract manufacturers split share differently across segments, with research-grade standard suppliers occupying distinct pricing tiers from hospital formulary incumbents. The vendor base organizes around three archetypes: multinational oncology portfolio holders with immuno-oncology combination capabilities, generic injectable specialists competing on cost-optimized fermentation yield, and niche formulation innovators developing nanoparticle delivery platforms. Consolidation pressure manifests through strategic partnerships anchoring checkpoint inhibitor-taxane regimens and backward integration into semi-synthetic precursor supply.
Among branded oncology portfolio holders, Bristol Myers Squibb and Novartis exemplify the combination-regimen archetype, anchoring development freedom-to-operate through intricate licensing negotiations. Teva Pharmaceuticals occupies a position within the generic injectable tier, competing through cost-optimized taxane portfolios that penetrate price-sensitive hospital procurement channels. These three entities collectively represent the competitive tension between premium formulation innovation and commodity-scale manufacturing efficiency that defines current market structure.
| Leading Market Players |
|---|
| Bristol Myers Squibb |
| Pfizer |
| Novartis |
| Merck & Co. |
| Roche Holding |
| Teva Pharmaceuticals |
| Fresenius Kabi |
| Hikma Pharmaceuticals |
| Oasmia Pharmaceuticals |
| Others |
Supply & Pricing Matrix
EPA manufacturing effluent regulations gate qualified supply for premium-tier taxane producers, with compliant fermentation facilities commanding pricing power over solvent-dependent competitors while non-integrated manufacturers absorb environmental remediation costs that compress margin structures.
Pricing Analysis
Lead-time-driven pricing separates contract manufacturers from spot-market suppliers, with albumin-bound paclitaxel nanoparticles commanding premium positioning against conventional solvent-based formulations. Three-tier pricing structure across premium nanoparticle, standard solvent-based, and economy generic tiers reflects formulation complexity and regulatory certification depth. Cost compression in the economy tier is intensifying as Indian contract manufacturers scale semi-synthetic docetaxel output. Hospital procurement committees exhibit highest price sensitivity, while research institutes demonstrate lowest sensitivity due to grant-funded reference standard requirements.
Supply Chain Analysis
Dual-sourcing requirements from US integrated delivery networks and German hospital consortia mandate multi-supplier qualification for Pacific yew bark extract and semi-synthetic taxane precursors. Production gravity centers on India, Switzerland, and Germany for fermentation-derived APIs, with formulation finishing concentrated in North American and European injectable facilities. Raw material dependencies include Pacific yew bark, 10-deacetylbaccatin III semi-synthetic precursors, and human serum albumin for nanoparticle stabilization. Single-source vulnerability in Pacific yew cultivation regions exposes producers to botanical supply shocks. Distribution runs through direct manufacturer-to-hospital contracts for high-volume taxanes, with temperature-controlled wholesalers serving mid-tier clinics.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market operates as a vertical-integration race, with players pursuing backward control over semi-synthetic precursor supply to secure margin capture against raw material volatility.
For Market Incumbents: Anchor formulation innovation leadership through captive lyophilization infrastructure and EMA centralized authorization leverage. Defensive consolidation should prioritize nanoparticle delivery platform acquisitions that block generic biosimilar interchangeability pathways. Capacity expansion in Swiss and German injectable facilities protects against FDA pre-approval manufacturing site review delays that constrain competitor entry.
For New Entrants and Emerging Players: Direct-to-research-institute digital channels offer the most penetrable route for high-purity reference standard supply, bypassing entrenched hospital formulary relationships. White-space targets include microtubule resistance mechanism screening libraries for NIH-funded academic centers in Boston and Singapore. Go-to-market positioning should emphasize technical documentation superiority and rapid custom synthesis turnaround against incumbent commodity portfolios.
For Investors and Strategic Acquirers: FDA interchangeability designation announcements for generic paclitaxel are the leading indicator that procurement consolidation will accelerate across US integrated delivery networks. Long-term viability favors vertically integrated specialists with captive fermentation capabilities and EMA GMP-certified injectable infrastructure. Acquisition target archetypes include nanoparticle formulation innovators with freedom-to-operate in checkpoint inhibitor combination regimens.
| Strategic Initiative | Industry Significance |
|---|---|
| Manufacturing Scale-Up | High-volume fermentation capacity in Indian special economic zones captures government hospital tender volume. |
| Regulatory Approval Pathway | EMA centralized marketing authorization reduces redundant stability testing for cross-border EU hospital supply. |
| Backward Integration | Captive semi-synthetic precursor production buffers against Pacific yew bark supply volatility and EPA compliance costs. |
| Licensing Agreement | Checkpoint inhibitor-taxane pairing patents require intricate freedom-to-operate negotiations with Bristol Myers Squibb and Roche. |
| Pipeline Diversification | Research application expansion into microtubule resistance mechanisms opens grant-funded demand at Wellcome Trust centers. |
Research Methodology
FDA filings, EMA centralized authorization records, and ClinicalTrials.gov protocol databases formed the secondary backbone for this analysis, cross-referenced with primary interviews involving oncology formulary directors, hospital procurement managers, regulatory affairs leads at injectable manufacturers, and payer access specialists. Bottom-up demand modeling from hospital formulary placement data and top-down supply validation from fermentation capacity disclosures were triangulated to constrain estimate ranges.
Historical trendline analysis of taxane reimbursement code utilization and nanoparticle formulation adoption rates informed the projection framework across the analysis window. Segmentation dimensions modeled include product type, application, end-user institution scale, and regional regulatory cluster. CAGRs were derived from elasticity-adjusted demand curves incorporating Medicare reimbursement policy trajectories and biosimilar interchangeability designation timelines.
Inputs from FDA oncology center review databases and EMA GMP inspection records were available through the study window; gaps in real-time hospital procurement contract terms introduce uncertainty bands around price elasticity assumptions. Deviation in EPA effluent regulation enforcement intensity or Pacific yew bark harvest quotas would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pharmaceutical Ingredients
Global Tacrolimus Market
Pharmaceutical Ingredients
Germany Active Pharmaceutical Ingredients (API) Market
Pharmaceutical Ingredients
France Active Pharmaceutical Ingredients (API) Market
Pharmaceutical Ingredients
Synthetic Small Molecule API Market
Pharmaceutical Ingredients
Pharmaceutical Excipients for Taste Masking Market
Pharmaceutical Ingredients
Immunosuppressants Market
Pharmaceutical Ingredients
Global Aspirin Market
Pharmaceutical Ingredients
Pharmaceutical Grade Sodium Carbonate Market
Pharmaceutical Ingredients
United States Active Pharmaceutical Ingredients (API) Market
Pharmaceutical Ingredients
Synthetic Lethality-Based Drugs and Targets Market
Pharmaceutical Ingredients
Global Sugar-Based Excipients Market
Pharmaceutical Ingredients
Global Pharmaceutical Grade Silica Gel Market
Pharmaceutical Ingredients
Global High Potency Active Pharmaceutical Ingredient (HPAPI) Market
Pharmaceutical Ingredients
Piperacillin Sodium API Market
Pharmaceutical Ingredients
Rizatriptan Market
Pharmaceutical Ingredients
Fosfomycin Trometamol Powder Market