
 Global Pharmaceutical Excipients Market | 2026-2036
Global Pharmaceutical Excipients Market Size, Share, and Industry Trends Forecast 2026-2036
Global Pharmaceutical Excipients Market Foresight
The EU Green Deal is rebalancing procurement priorities across European formulation houses, pushing excipient buyers toward bio-based and sustainably sourced alternatives. BASF SE leverages its integrated chemical platform to secure renewable feedstock pathways for high-purity binders. Evonik Industries AG specializes in functional polymers for parenteral applications, anchoring its position in sterile-grade excipient supply. Kerry Group plc competes through nutritional-bioactive crossovers that extend its excipient portfolio into controlled-release formats.
Pharmaceutical excipients are pharmacologically inactive substances formulated alongside active pharmaceutical ingredients to confer stability, enhance bioavailability, or enable specific delivery mechanisms, with purity grades typically exceeding 99.5% for parenteral grades and particle size distributions tightly controlled for direct compression. These materials serve as the structural backbone of dosage form design, transforming APIs into manufacturable, patient-compliant products. Binders and fillers together occupy the largest volume share as oral solid dosage forms remain the dominant delivery format across chronic therapy categories. Disintegrants represent the fastest-expanding functional class as orally disintegrating tablet demand rises in geriatric and pediatric populations.
FDA, EMA, and ICH Q3D guidelines collectively tighten elemental impurity thresholds, forcing excipient makers to validate supply chains against evolving pharmacopeial standards. REACH registration requirements in Europe and USP-NF monograph updates in the United States are reshaping qualification timelines for new excipient introductions. Stakeholders must monitor regulatory divergence between pharmacopeias to avoid dual-qualification costs that erode margin on multi-regional supply contracts.
Market Dynamics
Biopharmaceutical companies are accelerating adoption of novel delivery systems, forcing excipient suppliers to reconfigure purity specifications and functional performance around complex biologics rather than traditional small-molecule formulations.
Growth Catalysts
- Orally Disintegrating Tablet Demand:Geriatric and pediatric populations are driving volume expansion for rapid-dissolve formats, pulling disintegrant-grade excipients into chronic therapy supply chains.
- ICH Q3D Implementation:Tightened elemental impurity thresholds are creating qualification barriers that favor established suppliers with validated analytical capabilities.
- India Contract Manufacturing:CDSCO-registered facilities are scaling sterile-grade excipient consumption as global sponsors outsource parenteral production to Indian CMOs.
Market Restraints
- Petrochemical Feedstock Volatility:Polymer-based functional excipients face margin compression from naphtha and propylene price swings that resist hedging.
- European Supply Concentration:REACH-registered specialty excipient production clusters in Germany and the Netherlands, creating single-source vulnerability for parenteral-grade materials.
- Plant-Derived Substitution Limits:Bio-based alternatives struggle to match the batch-to-batch consistency of synthetic cellulose derivatives for direct compression applications.
Strategic Opportunities
- Brazil ANVISA Alignment:Mercosur harmonization with ICH guidelines is opening qualification pathways for excipient suppliers seeking entry into Latin American formulation markets.
- Continuous Manufacturing Integration:Real-time release testing requirements are converging with excipient functionality specifications, creating demand for engineered particle properties.
- EU Green Deal Sourcing Mandates:Renewable feedstock verification is becoming a procurement differentiator for European formulation houses seeking CSRD-compliant supply chains.
Industry Challenges
- Pharmacopeial Divergence Management:USP-NF, EP, and JP monograph misalignment forces suppliers to maintain parallel qualification dossiers, extending new product introduction timelines.
- Sterile Processing Capital Requirements:Aseptic manufacturing suites for parenteral-grade excipients demand facility investments that strain mid-tier supplier balance sheets.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Pharmaceutical Excipients Market |
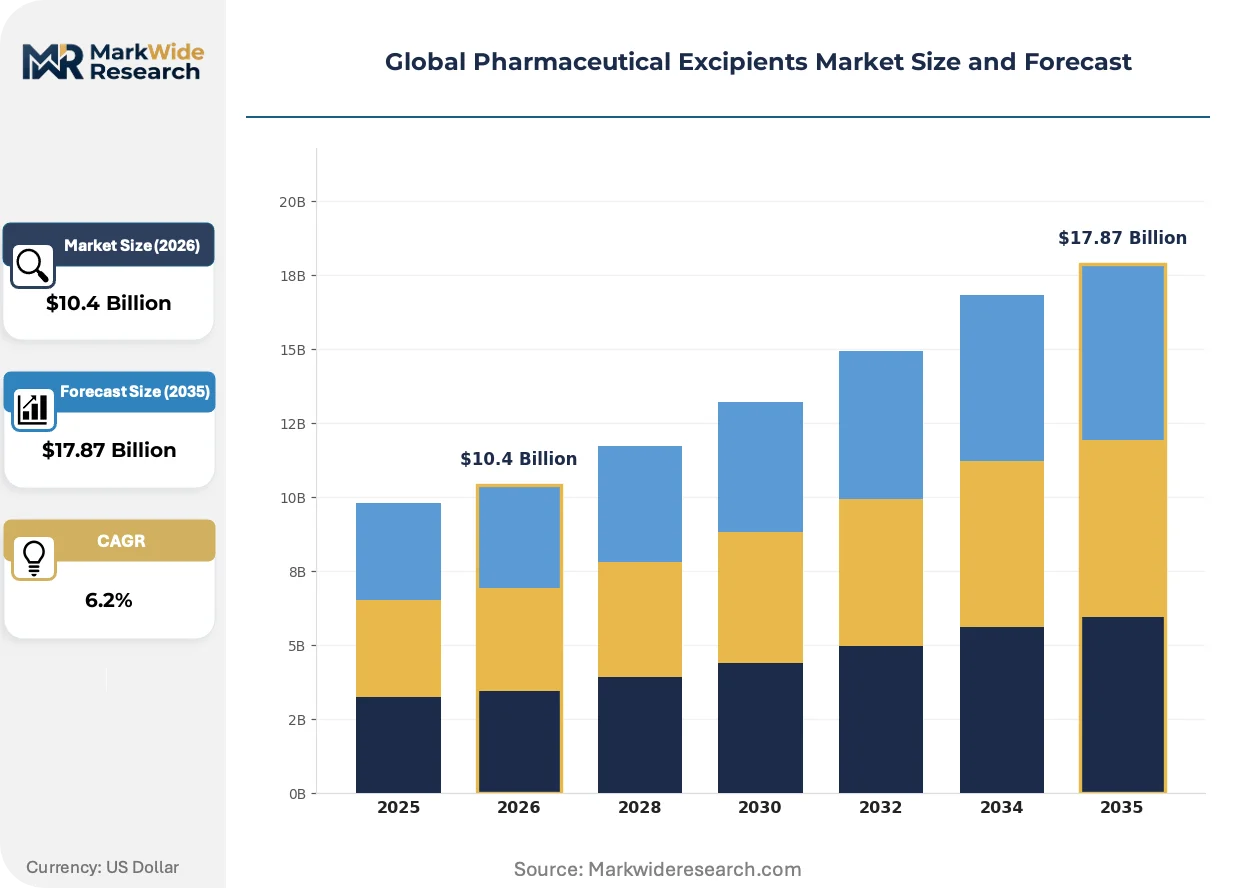
| Market Size in 2026 | $10.4 Billion |
| Market Size in 2035 | $17.87 Billion |
| CAGR (2026 – 2036) | 6.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Type: Binders, Fillers, Disintegrants, Lubricants Form: Granules, Powders, Solutions, Tablets Application: Oral, Parenteral, Topical, Transdermal End User: Pharmaceutical Companies, Contract Manufacturers, Research Institutes, Biopharmaceuticals |
| Companies Covered | BASF SE, International Flavors & Fragrances Inc., Archer Daniels Midland, Evonik Industries AG, Ashland Global Holdings, Roquette Frères, Dow Chemical Company, Kerry Group plc, Croda International plc, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Pharmaceutical Excipients Market Shifts & Advancements
Functional performance specifications are displacing commodity-grade purchasing across oral solid dosage categories, with formulation houses prioritizing excipient engineering over cost-per-kilogram metrics.
Co-processed multifunctional excipients are converging with continuous manufacturing platforms to enable real-time powder flow control and compression force optimization. Biopharmaceutical sponsors adopting these integrated systems are compressing batch release timelines from weeks to days. This convergence is compressing demand for standalone single-function materials while elevating technical service requirements.
REACH registration deadlines for low-tonnage substances are forcing European excipient suppliers to consolidate product portfolios or absorb registration costs that erode margin on specialty grades. The regulation is accelerating withdrawal of niche functional materials from the European market. Formulation scientists are responding by reformulating around available alternatives, often accepting performance trade-offs.
Buyer concentration among the top twenty global pharmaceutical companies is consolidating excipient procurement into centralized category management functions. These procurement organizations are unbundling technical qualification from commercial negotiations, compressing supplier margins while extending contract durations. The shift is most visible in North American and Western European markets where sponsor consolidation has proceeded furthest.
Global Pharmaceutical Excipients Market Segmentation
Excipient segmentation reveals how functional chemistry, physical form, and delivery route intersect to determine procurement priorities. Formulation houses segment their supplier base across these dimensions to match material specifications with dosage form engineering requirements.
Type:
Binders and fillers operate as embedded infrastructure within tablet matrices, while disintegrants and lubricants function as standalone performance modifiers dosed at lower inclusion rates.
- Binders:Polymeric adhesives such as povidone and hydroxypropyl cellulose confer mechanical integrity to granules and compacts. Demand concentrates in high-volume oral solid dosage manufacturing across India and the United States, where direct compression lines require consistent particle size distributions to maintain tablet hardness specifications.
- Fillers:Diluents including microcrystalline cellulose and lactose monohydrate constitute the bulk matrix of most tablets and capsules. Volume placements cluster in chronic disease categories—cardiovascular and metabolic therapies—where dose sizes exceed 200mg and API loading demands neutral carrier substrates.
- Disintegrants:Superdisintegrants like croscarmellose sodium accelerate tablet breakup for rapid API release. Orally disintegrating tablet formats for geriatric populations in Germany and Japan are pulling modified starch and crospovidone grades into specialized supply chains.
- Lubricants:Magnesium stearate and stearic acid reduce friction during compression and ejection. These materials face heightened elemental impurity scrutiny under ICH Q3D guidelines, favoring suppliers with validated heavy metal testing protocols.
Volume placements concentrate in fillers; the faster expansion belongs to disintegrants.
Form:
Physical state determines handling characteristics, stability profiles, and integration complexity with continuous manufacturing platforms.
- Granules:Agglomerated particles engineered for flowability and compressibility serve roller compaction and fluid bed granulation processes. German and Swiss formulation houses specify granule porosity to match real-time release testing parameters.
- Powders:Fine particulate excipients dominate direct compression workflows, with particle size distribution tightly controlled to prevent segregation during hopper discharge. Indian CMOs consume powder grades at scale for generic solid dosage exports.
- Solutions:Liquid excipients including solvents and co-solvents enable parenteral and topical formulation, requiring endotoxin-controlled manufacturing suites that concentrate supply among EMA-registered European producers.
- Tablets:Pre-compressed excipient compacts function as direct compression aids or placebo controls, simplifying inventory management for clinical trial supply operations.
Procurement volumes skew toward powders; engineered granules are climbing the fastest as continuous manufacturing adoption spreads.
Application:
Delivery route dictates purity grade, regulatory pathway, and functional performance specifications, with parenteral applications demanding the most stringent qualification protocols.
- Oral:Tablets, capsules, and suspensions represent the dominant consumption channel, with excipient selection driven by dissolution profile engineering and gastric stability requirements. Brazilian and Mexican formulation houses are expanding oral excipient qualification to meet ANVISA's ICH-aligned standards.
- Parenteral:Injectable and infusion formulations require sterile, endotoxin-free excipients with documented compatibility against biologic APIs. CDSCO-registered Indian facilities are scaling parenteral-grade consumption as global sponsors outsource sterile manufacturing.
- Topical:Creams, ointments, and gels utilize emollients and penetration enhancers, with texture and rheology specifications varying by dermatological indication.
- Transdermal:Patch formulations demand film-forming polymers and adhesive excipients with controlled release kinetics, a segment where Korean and Japanese specialty chemical suppliers maintain technical leadership.
Oral applications anchor volume demand; parenteral grades command the steepest expansion trajectory as biologics manufacturing scales.
End User:
Customer type shapes contract structures, technical service intensity, and qualification burden, with biopharmaceutical sponsors imposing the most demanding specification protocols.
- Pharmaceutical Companies:Integrated Big Pharma operations maintain captive excipient qualification teams and long-term supply agreements, centralizing procurement through category management functions.
- Contract Manufacturers:CDMOs and CMOs demand excipient flexibility across multiple sponsor programs, requiring suppliers to maintain broad pharmacopeial dossiers spanning USP-NF, EP, and JP standards.
- Research Institutes:Academic and government formulation labs consume small-batch, high-purity grades for preclinical and early-phase development, prioritizing technical documentation over unit economics.
- Biopharmaceuticals:Cell and gene therapy developers source specialized excipients for cryopreservation and lipid nanoparticle formulations, a customer segment where functional performance overrides cost-per-kilogram metrics.
Contract manufacturers represent the largest volume channel; biopharmaceuticals are expanding most quickly as novel modality pipelines mature.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Excipient production clusters concentrate in Germany and the Netherlands, while consumption gravity shifts toward India and the United States as contract manufacturing scales. This divergence creates supply chain tension between REACH-registered European specialty producers and volume-hungry Asian formulation houses.
Germany
Ludwigshafen and Marl host integrated chemical platforms producing high-purity binders and functional polymers for parenteral applications. The EU Green Deal is tightening renewable feedstock verification requirements for excipient exports. BASF SE leverages its Rhine-Ruhr manufacturing complex to secure bio-based pathways for tablet binders.
United States
Indianapolis and New Jersey formulation corridors drive demand for direct-compression fillers and superdisintegrants in generic solid dosage manufacturing. FDA enforces ICH Q3D elemental impurity thresholds through updated USP-NF monographs. CDMOs in Puerto Rico are expanding sterile-grade excipient consumption for biologics fill-finish operations.
India
Hyderabad and Ahmedabad CMO clusters are scaling sterile-grade excipient intake as global sponsors outsource parenteral production. CDSCO registration requirements for excipient suppliers are converging with ICH quality guidelines. The Telangana formulation belt is attracting multi-ton contracts for disintegrant-grade materials.
China
Zhejiang and Jiangsu provinces manufacture microcrystalline cellulose and polymeric excipients for domestic and export oral solid dosage markets. NMPA alignment with ICH Q3D is elevating analytical qualification burdens for elemental impurity testing. The Yangtze River Delta chemical parks are consolidating excipient production under stricter environmental compliance.
Brazil
São Paulo and Rio de Janeiro formulation houses are expanding excipient qualification to meet ANVISA's ICH-aligned standards for generic drug exports. Mercosur harmonization with international pharmacopeias is opening procurement pathways for imported specialty grades. The São Paulo state pharmaceutical corridor is driving regional demand for rapid-dissolve tablet excipients.
Global Pharmaceutical Excipients Market Competitive Landscape
The competitive structure tilts toward diversified chemical conglomerates with integrated feedstock access. Tier-one suppliers command parenteral-grade qualification dossiers spanning USP-NF, EP, and JP standards, while mid-tier players compete on oral solid dosage volume contracts. Three archetypes dominate: integrated chemical platforms, nutritional-bioactive crossovers, and polymer specialists. Capacity expansion in Indian CMO corridors and portfolio consolidation around co-processed multifunctional grades represent the dominant competitive vectors.
Within the integrated chemical platform tier, BASF SE and Evonik Industries AG exemplify the archetype of suppliers leveraging captive petrochemical and renewable feedstock pathways to secure high-purity binder and functional polymer supply. Kerry Group plc occupies a position bridging nutritional ingredients and controlled-release excipient formats. These three anchors demonstrate how technical qualification depth and regulatory dossier breadth determine competitive position in multi-regional supply contracts.
| Leading Market Players |
|---|
| BASF SE |
| International Flavors & Fragrances Inc. |
| Archer Daniels Midland |
| Evonik Industries AG |
| Ashland Global Holdings |
| Roquette Frères |
| Dow Chemical Company |
| Kerry Group plc |
| Croda International plc |
| Others |
Supply & Pricing Matrix
The EU Green Deal gates qualified supply and premium-tier pricing access for European formulation houses, forcing excipient buyers to verify renewable feedstock pathways or forfeit procurement eligibility. This sustainability mandate compresses margins for non-compliant suppliers while elevating pricing power for BASF SE and Evonik Industries AG with validated bio-based production.
Pricing Analysis
Yield-based pricing anchors parenteral-grade excipient contracts, with sterile processing throughput determining unit economics rather than raw material cost. Three-tier pricing structure across premium, standard, and economy levels separates endotoxin-controlled parenteral grades from oral solid dosage commodities. Pricing pressure stems from Indian CMO volume aggregation, which compresses margins on generic-grade fillers. Contract manufacturers exhibit highest price sensitivity; biopharmaceutical sponsors prioritize functional performance over unit cost.
Supply Chain Analysis
Dual-sourcing requirements from FDA and EMA force formulation houses to qualify multiple suppliers for parenteral-grade materials, fragmenting procurement across Germany, India, and the United States. Supply draws from petrochemical feedstocks for functional polymers, cellulose pulp for microcrystalline grades, and renewable starches for disintegrants. Single-source vulnerability concentrates in REACH-registered European specialty producers. Distribution runs through CDMO hubs in Hyderabad, Indianapolis, and Ludwigshafen with just-in-time inventory protocols.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
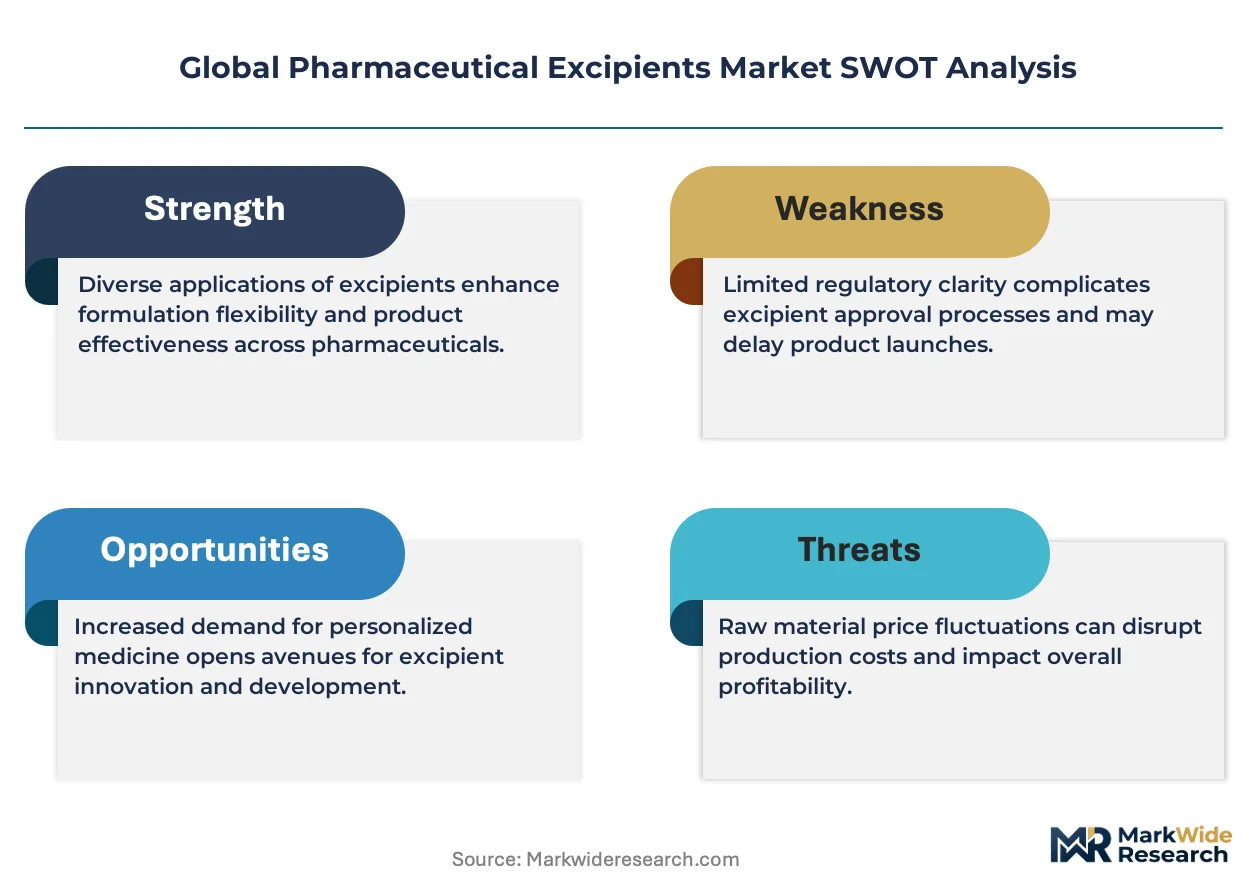
ICH Q3D compliance costs erect a barrier-to-entry moat that rewards incumbent excipient suppliers with validated analytical capabilities and multi-pharmacopeial dossiers. New entrants face qualification timelines that strain capital reserves before revenue generation begins.
For Market Incumbents: Deepen backward integration into renewable feedstock supply to secure EU Green Deal compliance advantages. Expand sterile-grade capacity in Indian CMO corridors before CDSCO registration requirements tighten. Defend against polymer specialists entering parenteral applications by accelerating co-processed multifunctional excipient development.
For New Entrants and Emerging Players: Begin with oral solid dosage disintegrants for Brazilian ANVISA-aligned formulation houses, where ICH harmonization creates qualification pathways without legacy dossier burdens. Target contract manufacturers in Mexico and Southeast Asia seeking alternatives to European supply concentration. Establish technical service partnerships with regional CMOs to bypass centralized Big Pharma procurement.
For Investors and Strategic Acquirers: CDSCO registration acceleration among Indian sterile manufacturers is the leading indicator that parenteral-grade excipient demand will outpace supply. Acquire mid-tier suppliers with validated USP-NF and EP dossiers but underutilized aseptic capacity. Watch for REACH registration withdrawals forcing formulation reformulation around available alternatives.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Renewable Feedstocks | BASF SE secures bio-based binder pathways that satisfy EU Green Deal verification requirements. |
| Sterile-Grade Capacity Expansion | Evonik Industries AG anchors parenteral polymer supply as Indian CMOs scale biologics manufacturing. |
| Co-Processed Multifunctional Excipient Development | Kerry Group plc converges nutritional and controlled-release expertise for continuous manufacturing platforms. |
| Multi-Pharmacopeial Dossier Investment | Suppliers avoid dual-qualification costs that erode margin on US-EU supply contracts. |
| CDSCO Registration Acceleration | Excipient makers capture sterile-grade demand from global sponsors outsourcing to Indian facilities. |
Research Methodology
Trade association data, regulatory filings, and customs records anchored secondary inputs for this analysis. Primary interviews with formulation scientists, regulatory affairs directors, CDMO procurement managers, and excipient supplier technical service heads validated demand assumptions. FDA 483 observations, EMA inspection reports, USP-NF monograph updates, and CDSCO registration databases provided compliance benchmarks. Bottom-up volume modeling across dosage form categories triangulated against top-down pharmaceutical production forecasts.
Granularity-level modeling operated at functional excipient type, physical form, delivery route, and end-user archetype dimensions. CAGRs derived from segment-level volume trajectories calibrated to pharmaceutical manufacturing expansion in India, United States, Germany, China, and Brazil. Treatment line evolution toward biologics and orally disintegrating formats informed parenteral-grade and disintegrant demand projections across the analysis window.
Underlying measurement precision varies by segment; parenteral-grade excipient forecasts carry tighter precision than commodity oral solid dosage categories due to concentrated supplier visibility. Forecasts reflect assumptions around ICH Q3D implementation timelines, REACH registration withdrawal patterns, and CDSCO inspection capacity expansion. Deviation in EU Green Deal enforcement stringency or Indian environmental compliance acceleration would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pharmaceutical Ingredients
Asia-Pacific Pharmaceutical Glycerine Market
Pharmaceutical Ingredients
Non-Steroidal Anti-Inflammatory Drugs (Nsaids) Market
Pharmaceutical Ingredients
Active Pharmaceutical Ingredient for Cancer Market
Pharmaceutical Ingredients
Pharmaceutical Grade Beta-Alanine Market
Pharmaceutical Ingredients
Pharmaceutical Thermal Analysis Market
Pharmaceutical Ingredients
Oral Doxycycline Hyclate Market
Pharmaceutical Ingredients
Tranexamic Acid API Market
Pharmaceutical Ingredients
Global Tacrolimus Market
Pharmaceutical Ingredients
Citicoline Market
Pharmaceutical Ingredients
Germany Active Pharmaceutical Ingredients (API) Market
Pharmaceutical Ingredients
Pharma Grade Ibuprofen API Market
Pharmaceutical Ingredients
Oxycodone Drugs Market
Pharmaceutical Ingredients
Topical Drugs Market
Pharmaceutical Ingredients
Zinc Bacitracin Market
Pharmaceutical Ingredients
Lipids Active Pharmaceutical Ingredient Market
Pharmaceutical Ingredients
Chlorzoxazone Market