
 Flurbiprofen Market | 2026-2036
Flurbiprofen Market Size, Share, and Industry Trends Forecast 2026-2036
Flurbiprofen Market Insights
Ophthalmic surgery is realigning toward multimodal analgesia protocols that incorporate topical NSAIDs. Sun Pharmaceutical Industries Ltd. leverages its generic manufacturing scale to supply cost-competitive flurbiprofen formulations across regulated markets. Pfizer Inc. anchors its position through sustained R&D investment in novel delivery mechanisms for established NSAID molecules.
Flurbiprofen is a propionic acid-derived nonsteroidal anti-inflammatory drug with a molecular formula of C15H13FO2, functioning primarily as a cyclooxygenase inhibitor for pain and inflammation management. The compound's lipophilic character enables effective transdermal and topical penetration, supporting its use in gel formulations for localized musculoskeletal conditions. Tablets dominate current prescription volumes due to established reimbursement pathways and clinician familiarity, while transdermal delivery represents the fastest-expanding segment as patients seek alternatives to systemic gastrointestinal exposure. Home care channels capture growing margin pools as post-acute pain management shifts away from institutional settings.
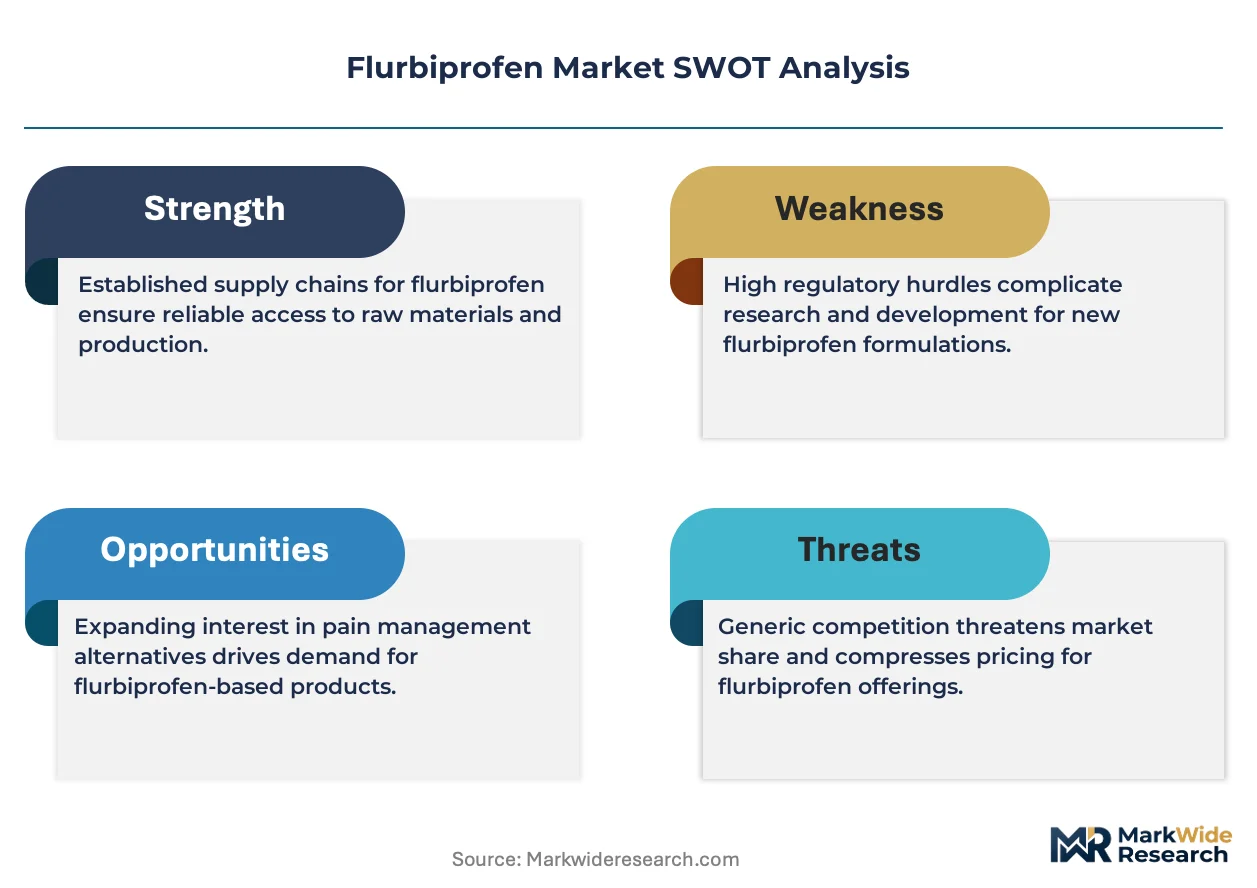
The FDA maintains stringent cardiovascular and gastrointestinal risk labeling requirements for all prescription NSAIDs including flurbiprofen, directly influencing prescriber education and patient selection criteria. The EMA's Pharmacovigilance Risk Assessment Committee periodically reviews systemic NSAID safety profiles, affecting market access conditions across European member states. Health Canada and the TGA enforce comparable vigilance standards that manufacturers must navigate for product registration. Stakeholders should monitor evolving opioid-sparing initiatives in perioperative care, as these protocols determine whether flurbiprofen gains or loses position within multimodal analgesia formularies.
Market Dynamics
The FDA's cardiovascular safety labeling requirements for prescription NSAIDs are compressing prescribing volumes while simultaneously redirecting demand toward topical and transdermal formulations that minimize systemic exposure.
Growth Catalysts
- Opioid-sparing perioperative protocols:Ambulatory surgical centers in the United States are embedding flurbiprofen into multimodal analgesia pathways to reduce post-operative opioid dependence.
- REACH authorization pathways:The European Chemicals Agency's streamlined substance registration process is accelerating market entry for generic flurbiprofen API manufacturers targeting EU member states.
- Lipophilic molecule engineering:Advanced transdermal penetration enhancers are expanding the addressable patient population seeking localized musculoskeletal pain relief without gastrointestinal complications.
Market Restraints
- API supply concentration:Bulk flurbiprofen active pharmaceutical ingredient production clusters in Indian and Chinese chemical manufacturing zones, creating single-source vulnerability.
- Cardiovascular black-box warnings:The FDA's mandatory labeling for thrombotic risk elevates prescriber liability and narrows the eligible patient pool for systemic formulations.
- COX-2 selective substitution:Celecoxib and other coxibs continue displacing traditional NSAIDs in chronic pain protocols where cardiovascular risk stratification favors selectivity.
Strategic Opportunities
- Ophthalmic surgery expansion:Cataract and refractive surgery volumes in Germany, France, and Spain are driving demand for topical NSAID drops as standard anti-inflammatory prophylaxis.
- Home care channel development:Post-acute pain management is migrating from hospital infusion centers to patient-administered transdermal patches, creating margin capture opportunities outside institutional procurement.
- Japan's geriatric pain management guidelines:PMDA-aligned clinical pathways for elderly patients emphasize topical NSAIDs over systemic alternatives, opening formulation-specific demand.
Industry Challenges
- Bioequivalence demonstration for transdermal generics:Proving pharmacokinetic equivalence to reference listed drugs requires specialized clinical trial infrastructure and extended FDA review timelines.
- Multinational pharmacovigilance coordination:Harmonizing adverse event reporting across FDA, EMA, and PMDA jurisdictions demands dedicated regulatory affairs capacity and real-time data integration systems.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Flurbiprofen Market |
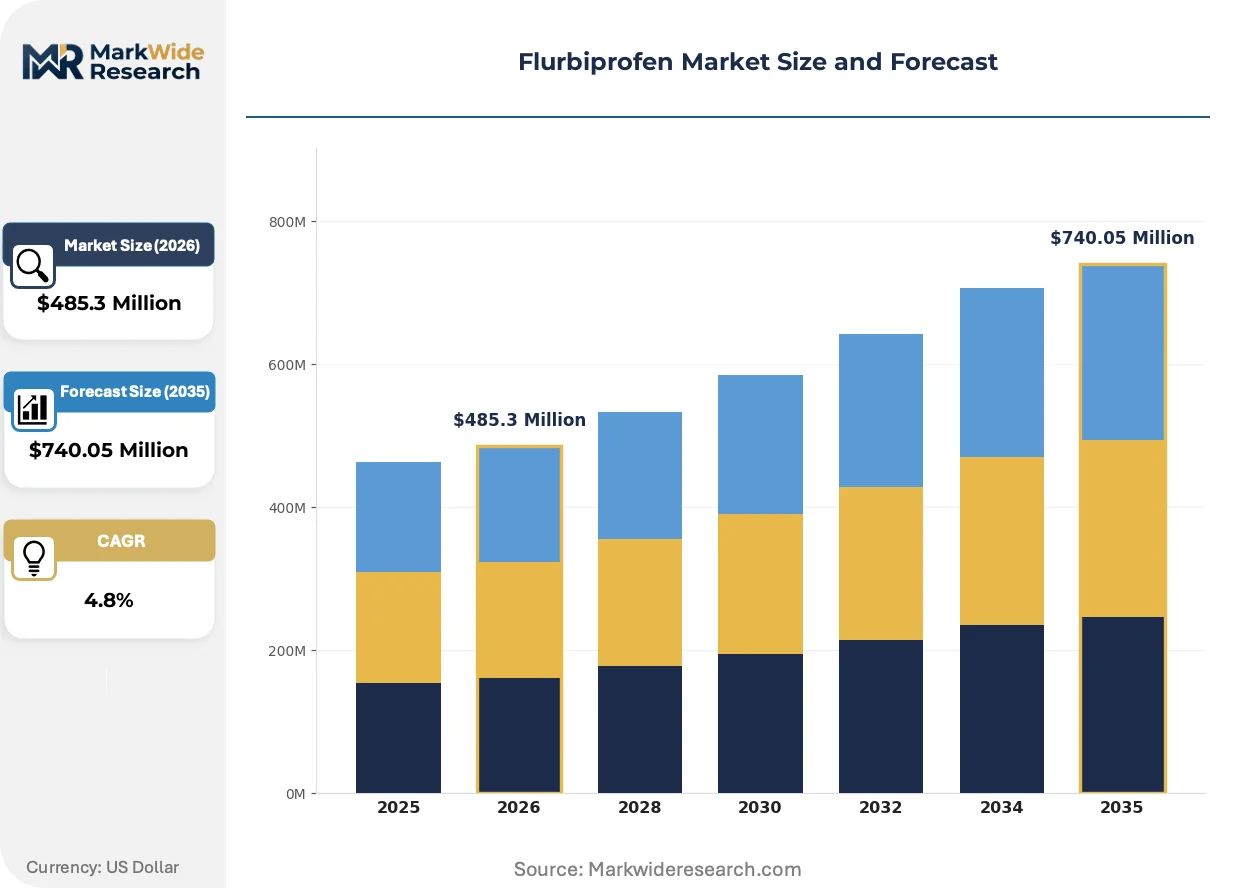
| Market Size in 2026 | $485.3 Million |
| Market Size in 2035 | $740.05 Million |
| CAGR (2026 – 2036) | 4.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Tablets, Injections, Gel, Oral Suspension Delivery Mode: Oral, Parenteral, Topical, Transdermal End User: Hospitals, Clinics, Home Care, Pharmacies Application: Pain Management, Inflammation Control, Arthritis Treatment, Migraine Relief |
| Companies Covered | Sun Pharmaceutical Industries Ltd., Sanofi S.A., Pfizer Inc., GlaxoSmithKline plc, Bayer AG, Novartis AG, Mylan N.V., Johnson & Johnson, Teva Pharmaceutical Industries Ltd., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Flurbiprofen Market Trends and Innovations
Formulation science and delivery mechanism innovation are fragmenting the traditional tablet-dominant market structure. Manufacturers are engineering differentiated products around tissue-specific penetration and controlled-release kinetics.
Nanostructured lipid carriers are converging with conventional flurbiprofen formulations to enhance dermal bioavailability and prolong local anti-inflammatory effect. Dermatology clinics and sports medicine practices in the United States are adopting these advanced carriers for tendinopathy and soft-tissue injury protocols. The technology is converging with patient preference for non-systemic pain management, compressing demand for oral dosage forms in musculoskeletal indications.
The EMA's Pharmacovigilance Risk Assessment Committee has intensified periodic safety review requirements for all systemic NSAID molecules, including flurbiprofen. This regulatory pressure is forcing manufacturers to invest in real-world evidence generation and risk minimization measures across European markets. Hospital formularies in France, Italy, and the Netherlands are responding by restricting systemic NSAID access and expanding topical alternatives.
Patient-administered pain management is displacing clinic-based injection protocols in post-surgical recovery. Home care channels and direct-to-patient pharmacy distribution are capturing volume previously routed through hospital outpatient departments. The United States exhibits the most pronounced channel shift, where ambulatory surgery center discharge protocols increasingly specify take-home transdermal NSAID regimens rather than scheduled follow-up injections.
Flurbiprofen Market Segmentation
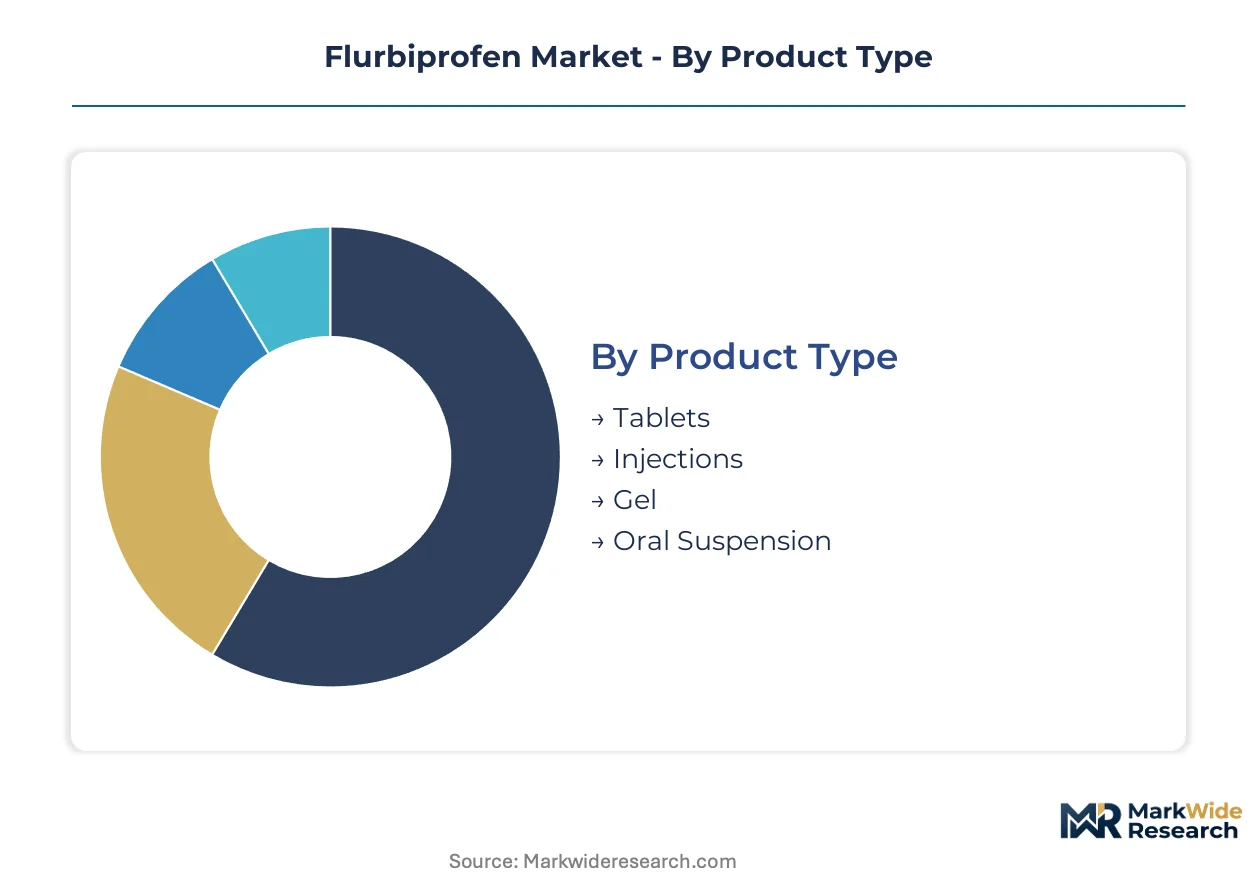
Flurbiprofen's formulation diversity creates distinct investment profiles across manufacturing modalities. Each segment carries unique regulatory burdens and margin structures that determine competitive positioning.
Product Type:
Capital intensity peaks with sterile injectable manufacturing, where aseptic filling lines and isolator technology demand substantial upfront outlays.
- Tablets:Conventional oral solid dosage forms utilizing standard compression and coating equipment. United States hospital formularies drive volume allocation through established reimbursement pathways and clinician familiarity with systemic NSAID protocols.
- Injections:Sterile parenteral solutions requiring isolator-based aseptic processing and terminal sterilization validation. Ambulatory surgical centers in Germany and France embed these into multimodal perioperative pathways where rapid onset and opioid-sparing profiles justify premium positioning.
- Gel:Semi-solid topical formulations with lower barrier-to-entry manufacturing requirements. Sports medicine practices favor these for localized musculoskeletal applications.
- Oral Suspension:Liquid dosage forms addressing pediatric and geriatric populations with swallowing difficulties. Pharmacy compounding channels capture niche demand.
Most installed capacity flows through Tablets. Expansion is steepest in Gel as patients seek alternatives to systemic gastrointestinal exposure.
Delivery Mode:
Volume concentration varies sharply by patient setting, with institutional procurement favoring parenteral routes and retail channels driving patient-administered alternatives.
- Oral:Systemic absorption through gastrointestinal tract with established bioequivalence frameworks. United States generic substitution rates compress pricing power while maintaining volume dominance through Medicare Part D coverage.
- Parenteral:Intravenous and intramuscular administration for acute perioperative settings. Japanese geriatric pain management guidelines under PMDA alignment emphasize this route for hospitalized populations.
- Topical:Direct application to affected tissue with minimal systemic uptake. EMA Pharmacovigilance Risk Assessment Committee pressures are accelerating hospital formulary expansion of this category across France, Italy, and the Netherlands.
- Transdermal:Patch-based controlled release through skin barrier penetration. Home care channels in the United States are capturing margin pools as post-acute pain management migrates from infusion centers to patient-administered regimens.
Oral delivery retains the largest installed base. Transdermal patches are climbing the fastest as channel economics favor take-home dispensing over institutional reimbursement.
End User:
Procurement sophistication divides segments, with consolidated hospital purchasing exerting price pressure against fragmented retail pharmacy margins.
- Hospitals:Integrated delivery networks with formulary committees and group purchasing organization contracts. FDA cardiovascular black-box warnings are narrowing eligible patient pools and intensifying risk stratification protocols.
- Clinics:Outpatient facilities including ambulatory surgical centers and specialty pain practices. Opioid-sparing initiatives in United States perioperative care are embedding flurbiprofen into multimodal analgesia pathways.
- Home Care:Patient-administered pain management outside institutional settings. Direct-to-patient pharmacy distribution is capturing volume previously routed through hospital outpatient departments.
- Pharmacies:Retail and mail-order dispensaries with generic substitution mandates. Reimbursement compression limits margin capture.
Hospital procurement channels dominate current volume. Home care is gaining share fastest as post-surgical discharge protocols specify take-home regimens.
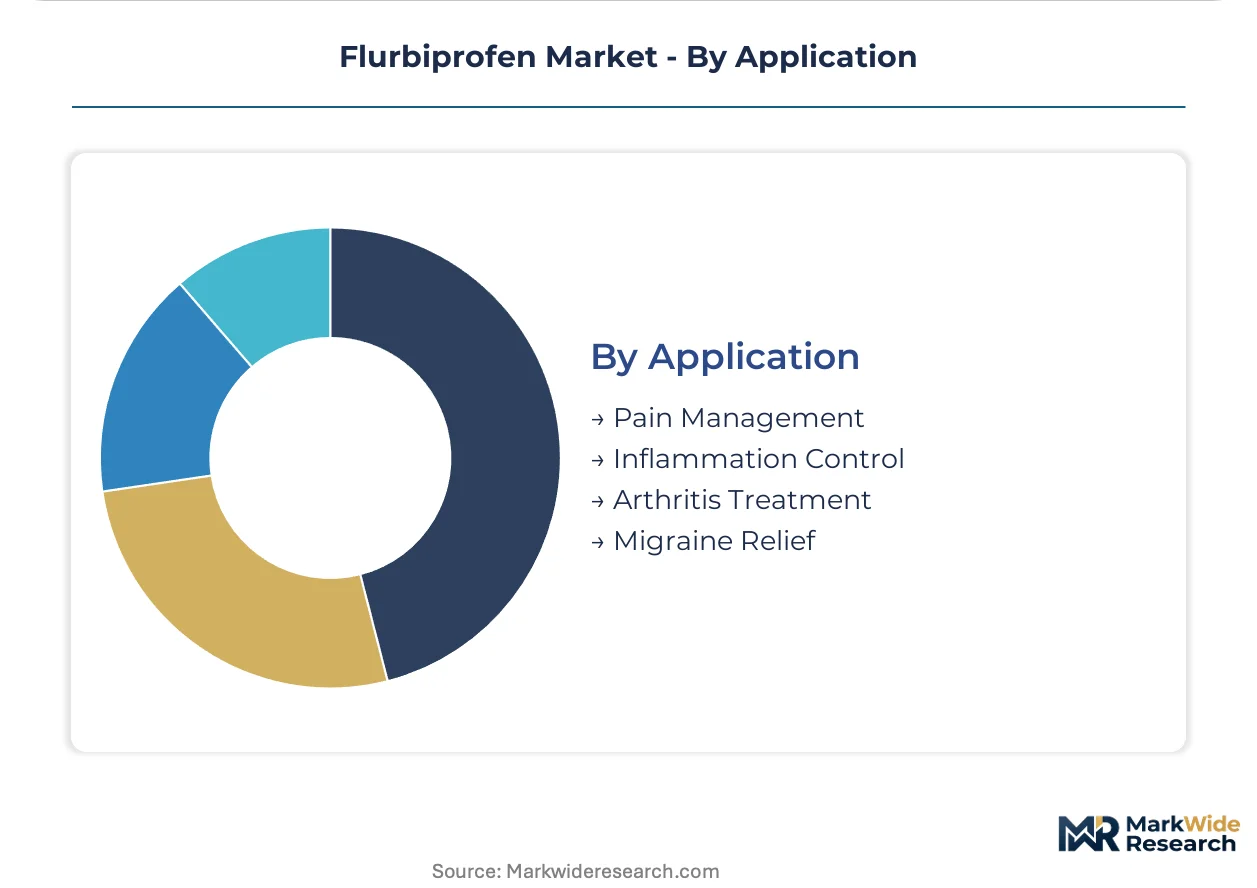
Application:
Clinical evidence requirements and competitive intensity vary by therapeutic indication, with chronic conditions demanding larger safety databases than acute episodic use.
- Pain Management:Acute and chronic pain states spanning post-surgical, traumatic, and neuropathic etiologies. REACH authorization pathways are accelerating generic API manufacturer entry into EU member states for this high-volume indication.
- Inflammation Control:Suppression of prostaglandin-mediated inflammatory responses in soft tissue and ophthalmic settings. Cataract and refractive surgery volumes in Germany, France, and Spain are driving demand for topical NSAID drops as standard anti-inflammatory prophylaxis.
- Arthritis Treatment:Chronic management of osteoarthritis and rheumatoid arthritis symptoms. COX-2 selective substitution by celecoxib is displacing traditional NSAIDs where cardiovascular risk stratification favors selectivity.
- Migraine Relief:Acute abortive therapy for headache disorders. Neurology specialists reserve this for specific phenotypes.
Pain Management absorbs the majority of installed capacity. Inflammation Control is expanding most quickly behind ophthalmic surgery protocol adoption.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory-arbitrage dynamics are reshaping flurbiprofen production geography as manufacturers migrate toward jurisdictions with streamlined API registration pathways and lower compliance costs. Cost-of-compliance gaps between established Western markets and emerging manufacturing hubs are accelerating facility relocation decisions.
United States
FDA cardiovascular black-box warnings are narrowing systemic NSAID prescribing pools while expanding topical formulary access. Medicare Part D reimbursement pathways sustain tablet volume dominance despite risk stratification pressures. New Jersey and Pennsylvania pharmaceutical corridors host concentrated generic manufacturing infrastructure serving domestic hospital procurement networks.
Germany
Cataract and refractive surgery volumes in Bavaria and North Rhine-Westphalia are driving ophthalmic NSAID demand through statutory health insurance reimbursement channels. EMA Pharmacovigilance Risk Assessment Committee periodic reviews are accelerating hospital formulary restrictions on systemic formulations. Frankfurt-Rhine-Main chemical manufacturing clusters supply API intermediates to European formulation facilities.
India
REACH authorization pathway expertise among Mumbai and Ahmedabad API manufacturers is accelerating European market entry for bulk flurbiprofen producers. CDSCO manufacturing facility inspections are tightening quality compliance standards for export-oriented production. Hyderabad and Visakhapatnam pharmaceutical zones concentrate sterile injectable formulation capacity serving contract manufacturing demand.
Japan
PMDA-aligned geriatric pain management guidelines are embedding topical NSAIDs into clinical pathways for elderly populations. Tokyo and Osaka metropolitan hospital networks are restricting systemic NSAID access through formulary committee decisions. Kanto region pharmaceutical R&D clusters are engineering next-generation transdermal penetration enhancers for localized musculoskeletal applications.
China
NMPA priority review pathways for generic injectable NSAIDs are compressing approval timelines for domestic manufacturers targeting perioperative segments. Yangtze River Delta chemical manufacturing zones dominate bulk API production for export markets. Shanghai and Suzhou pharmaceutical parks are expanding sterile filling capacity to capture contract manufacturing demand from Western brand-owners.
Flurbiprofen Market Competitive Landscape
Portfolio diversification dominates the current landscape as incumbents balance systemic formulation exposure against topical and transdermal growth vectors. The vendor base stratifies across three tiers: multinational pharmaceutical conglomerates with integrated NSAID portfolios, mid-scale generic specialists concentrating on cost-competitive API supply, and regional formulation players capturing niche indication markets. Two strategic archetypes predominate: scale-driven manufacturers leveraging vertical integration into API production, and innovation-focused developers engineering differentiated delivery mechanisms. Capacity expansion in sterile injectable infrastructure and technology licensing for transdermal penetration platforms represent the dominant competitive moves.
Among multinational pharmaceutical conglomerates, Sun Pharmaceutical Industries Ltd., Pfizer Inc., and Novartis AG occupy distinct positioning within the competitive structure. Sun Pharmaceutical exemplifies the scale-driven generic archetype with concentrated manufacturing infrastructure across regulated markets. Pfizer anchors the innovation-oriented tier through sustained investment in novel delivery mechanism development for established NSAID molecules. Novartis sits within the diversified pharmaceutical portfolio segment, balancing mature brand maintenance with pipeline transition strategies. These three entities collectively represent the competitive tension between cost leadership and formulation differentiation that defines current market dynamics.
| Leading Market Players |
|---|
| Sun Pharmaceutical Industries Ltd. |
| Sanofi S.A. |
| Pfizer Inc. |
| GlaxoSmithKline plc |
| Bayer AG |
| Novartis AG |
| Mylan N.V. |
| Johnson & Johnson |
| Teva Pharmaceutical Industries Ltd. |
| Others |
Pricing and Supply Chain Analysis
Para-fluorobenzaldehyde spot pricing on Indian commodity exchanges cascades through flurbiprofen API manufacturing into three distinct formulation tiers, with transdermal patch producers capturing premium positioning while oral generic tablets face reimbursement compression through Medicare Part D channel economics.
Pricing Analysis
Distributor margin layers in the United States hospital procurement channel absorb 12-18 percentage points before formulary placement, while direct-to-patient pharmacy distribution for home care transdermal regimens retains fuller value capture. Pricing stratifies across premium sterile injectables for ambulatory surgical centers, standard coated tablets for chronic pain management, and economy-tier API bulk supply to compounding pharmacies. Cost compression in oral solid dosage forms is intensifying because United States generic substitution rates approach 90 percent for systemic NSAIDs. Hospital group purchasing organizations exhibit the highest price sensitivity, whereas ophthalmology clinics purchasing topical drops for surgical prophylaxis prioritize supply security over unit cost.
Supply Chain Analysis
Dual-sourcing requirements from European REACH-authorized buyers now mandate qualified API supply from both Indian and Chinese chemical manufacturing zones, compressing single-source dependency risks that dominated procurement through 2020. Bulk flurbiprofen production concentrates in Gujarat and Jiangsu provinces, with Hyderabad and Shanghai formulation facilities adding sterile injectable finishing capacity. The supply chain rests on para-fluorobenzaldehyde, propionic acid derivatives, and specialized transdermal penetration enhancers as critical inputs. Tariff exposure on Chinese-origin API intermediates threatens margin stability for European generic manufacturers. Distribution runs through hospital procurement networks for parenteral formulations, direct-to-patient pharmacy channels for transdermal patches, and retail dispensaries for oral dosage forms.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Flurbiprofen manufacturing economics favor geographic arbitrage between Indian API production zones and European formulation finishing, where REACH compliance costs in Germany and France create 15-20 percent cost differentials against domestic European chemical synthesis.
For Market Incumbents: Anticipate COX-2 selective substitution pressure in chronic arthritis segments by accelerating transdermal patch capacity expansion in United States home care channels. Capture backward integration into para-fluorobenzaldehyde precursor manufacturing to defend margin position against Indian API price volatility. Secure FDA cardiovascular risk mitigation labeling updates before EMA Pharmacovigilance Risk Assessment Committee reviews tighten European hospital formulary access further. For New Entrants and Emerging Players: Begin with ophthalmic surgery topical drops in Spain and Italy, where statutory health insurance reimbursement pathways remain less consolidated than German or French procurement. Target compounding pharmacy channels for oral suspension formulations addressing pediatric and geriatric swallowing difficulties, a segment large manufacturers disfavor due to batch-size economics. Pursue technology licensing partnerships with Japanese transdermal penetration enhancer developers rather than independent R&D investment. For Investors and Strategic Acquirers: Consolidation pressure builds where sterile injectable manufacturing capacity scarcity intersects with opioid-sparing perioperative protocol expansion. Mid-scale generic specialists with captive API supply and existing FDA establishment registrations offer the strongest acquisition profile. Watch Japanese PMDA geriatric guideline revisions as the signal indicating whether topical NSAID demand acceleration justifies transdermal platform valuations.| Strategic Initiative | Industry Significance |
|---|---|
| Transdermal Patch Manufacturing Scale-Up | Captures home care channel margin pools as United States discharge protocols shift from infusion centers. |
| REACH Authorization Pathway Investment | Unlocks European Union member state market access for Indian API producers seeking formulation partnerships. |
| Ophthalmic Drop Formulation Development | Aligns with cataract surgery volume expansion in Germany, France, and Spain through statutory reimbursement. |
| Sterile Injectable Capacity Expansion | Addresses ambulatory surgical center demand for rapid-onset opioid-sparing perioperative analgesia protocols. |
| Real-World Evidence Generation Partnership | Satisfies EMA Pharmacovigilance Risk Assessment Committee intensified safety review requirements. |
Research Methodology
Direct dialogue with regulatory affairs directors at generic pharmaceutical manufacturers, hospital formulary committee pharmacists, and ambulatory surgical center procurement managers grounded the qualitative foundation, supplemented by FDA cardiovascular safety labeling archives, EMA periodic safety review reports, ClinicalTrials.gov NSAID protocol registrations, and United States Medicare Part D reimbursement databases. Bottom-up prescription volume modeling and top-down pharmaceutical market sizing triangulated demand estimates across the analysis window.
Bottom-up segmentation analysis tracked formulation-specific demand by delivery mode, end-user channel, and therapeutic application, while top-down cross-checks validated against national health expenditure data and pharmaceutical trade flows. CAGRs were derived from normalized prescription volume trajectories and pricing deflators across the projection horizon, with explicit modeling of FDA black-box warning impacts on systemic NSAID prescribing pools and EMA formulary restriction propagation timelines.
Several conditions sit outside the modeled scope, including unforeseen cardiovascular safety signal emergence requiring label expansion, abrupt API manufacturing facility shutdowns from regulatory enforcement actions, and geopolitical trade restrictions on Chinese-origin chemical intermediates. Deviation in opioid-sparing protocol adoption rates across United States ambulatory surgical networks would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pharmaceutical Ingredients
MEK Inhibitors Market
Pharmaceutical Ingredients
Pharma-Grade Magnesium Trisilicate Market
Pharmaceutical Ingredients
Pharma Grade Ibuprofen API Market
Pharmaceutical Ingredients
Antibiotics Active Pharmaceutical Ingredient (API) Market
Pharmaceutical Ingredients
Pharmaceutical Thermal Analysis Market
Pharmaceutical Ingredients
Prescription Hair Loss and Hair Removal Drugs Market
Pharmaceutical Ingredients
Global Antazoline Market
Pharmaceutical Ingredients
Oral Transmucosal Drugs Market
Pharmaceutical Ingredients
Small Molecule Drug Discovery Market
Pharmaceutical Ingredients
Alpha Lipoic Acid API Market
Pharmaceutical Ingredients
Furosemide Market
Pharmaceutical Ingredients
Glycylglycine Market
Pharmaceutical Ingredients
Kitasamycin Market
Pharmaceutical Ingredients
Pharmaceutical Grade Beta-Alanine Market
Pharmaceutical Ingredients
Pharmaceutical Suspension Market
Pharmaceutical Ingredients
Calcium Folinate for Injection Market