
 Pharma Grade Ibuprofen API Market | 2026-2036
Pharma Grade Ibuprofen API Market Size, Share, and Industry Trends Forecast 2026-2036
Pharma Grade Ibuprofen API Market Insights
The pricing spread between premium-grade and commodity-grade ibuprofen API is recalibrating as impurity-profile specifications tighten under pharmacopeial revisions. SI Group leverages its integrated phenol-to-ibuprofen pathway to sustain cost discipline across cyclical feedstock swings. Dr. Reddy's Laboratories Ltd. anchors volume supply to North American and European generic-drug customers through dedicated contract structures. IOL Chemicals and Pharmaceuticals differentiates by controlling captive isobutylbenzene supply, insulating margin pools from aromatic hydrocarbon volatility.
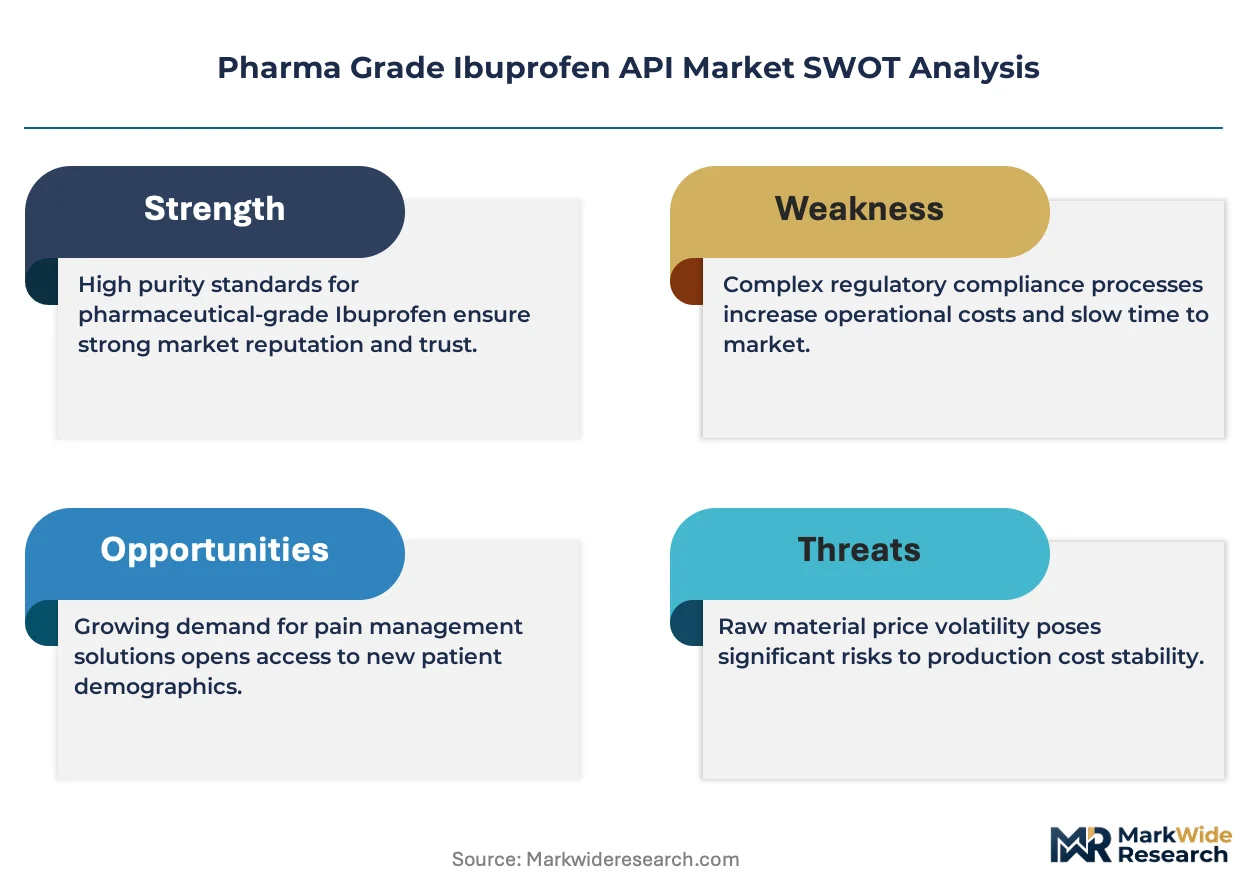
Pharma grade ibuprofen API denotes the active pharmaceutical ingredient meeting United States Pharmacopeia (USP) or European Pharmacopeia (EP) monograph standards, typically manufactured via the Boots-Hoechst-Celanese process with specified limits on individual and total impurities below 0.10% and 0.30% respectively, serving as the foundational raw material for oral analgesic and anti-inflammatory drug products. Powder formulations dominate current procurement volumes due to compatibility with downstream tablet compression and encapsulation lines, while extended-release formulations represent the fastest-expanding segment as patient-compliance formulations gain formulary placement. Pharmaceutical grade material captures the dominant margin pool, with laboratory grade occupying a narrow premium niche serving clinical-trial and reference-standard applications.
FDA enforces Current Good Manufacturing Practice (CGMP) requirements through facility inspections and Warning Letters that directly determine market access for API suppliers to the United States. EMA's active substance master file (ASMF) procedure and REACH chemical registration obligations shape European import pathways and environmental compliance burdens. India's CDSCO synchronizes with ICH Q3D elemental impurity guidelines, aligning domestic manufacturers with export-market specifications. Stakeholders must monitor evolving pharmacopeial harmonization between USP, EP, and Indian Pharmacopeia (IP) monographs, as divergence in residual-solvent limits could fragment qualification requirements and force redundant testing protocols across supply destinations.
Market Dynamics
Impurity-profile tightening under USP and EP monograph revisions is compressing the supplier base, forcing API manufacturers to recalibrate process chemistry or exit regulated markets entirely. This quality-bar elevation rewards producers with captive feedstock control and integrated analytical capabilities.
Growth Catalysts
- Extended-release formulation demand:Patient-compliance tablets are capturing formulary placement at the expense of immediate-release generics, pulling premium-grade API volumes into chronic pain management protocols.
- EMA ASMF pathway maturation:Streamlined European drug master file procedures are shortening qualification timelines for Indian and Chinese suppliers seeking regulated-market access.
- CDSCO-ICH Q3D alignment:India's synchronization with elemental impurity guidelines is collapsing dual-track testing burdens for export-oriented manufacturers.
Market Restraints
- Isobutylbenzene feedstock volatility:Aromatic hydrocarbon price swings transmit directly into ibuprofen API cost structures, eroding margin predictability for non-integrated producers.
- Indian supply concentration:Overreliance on Punjab and Gujarat manufacturing clusters exposes procurement continuity to localized environmental enforcement actions or monsoon-related logistics disruptions.
- Genotoxic impurity detection thresholds:USP <1469> nitrosamine testing requirements are forcing batch-rejection rates upward and extending release timelines.
Strategic Opportunities
- Brazilian ANVISA pre-qualification:Underpenetrated Latin American generics markets offer first-mover advantages for API suppliers completing local registration dossiers ahead of patent cliff waves.
- Continuous flow chemistry adoption:Microreactor process intensification promises solvent reduction and yield improvement, aligning with REACH environmental compliance trajectories.
- Direct-to-formulator e-procurement platforms:Digital marketplaces are collapsing traditional distributor markups for mid-tier generic manufacturers seeking spot API purchases.
Industry Challenges
- Analytical method transfer complexity:Pharmacopeial divergence between USP, EP, and IP residual-solvent specifications forces redundant validation studies and extends customer qualification cycles.
- Specialized process chemist scarcity:Boots-Hoechst-Celanese route expertise concentrates among aging technical workforces in legacy manufacturing regions, constraining capacity expansion velocity.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Pharma Grade Ibuprofen API Market |
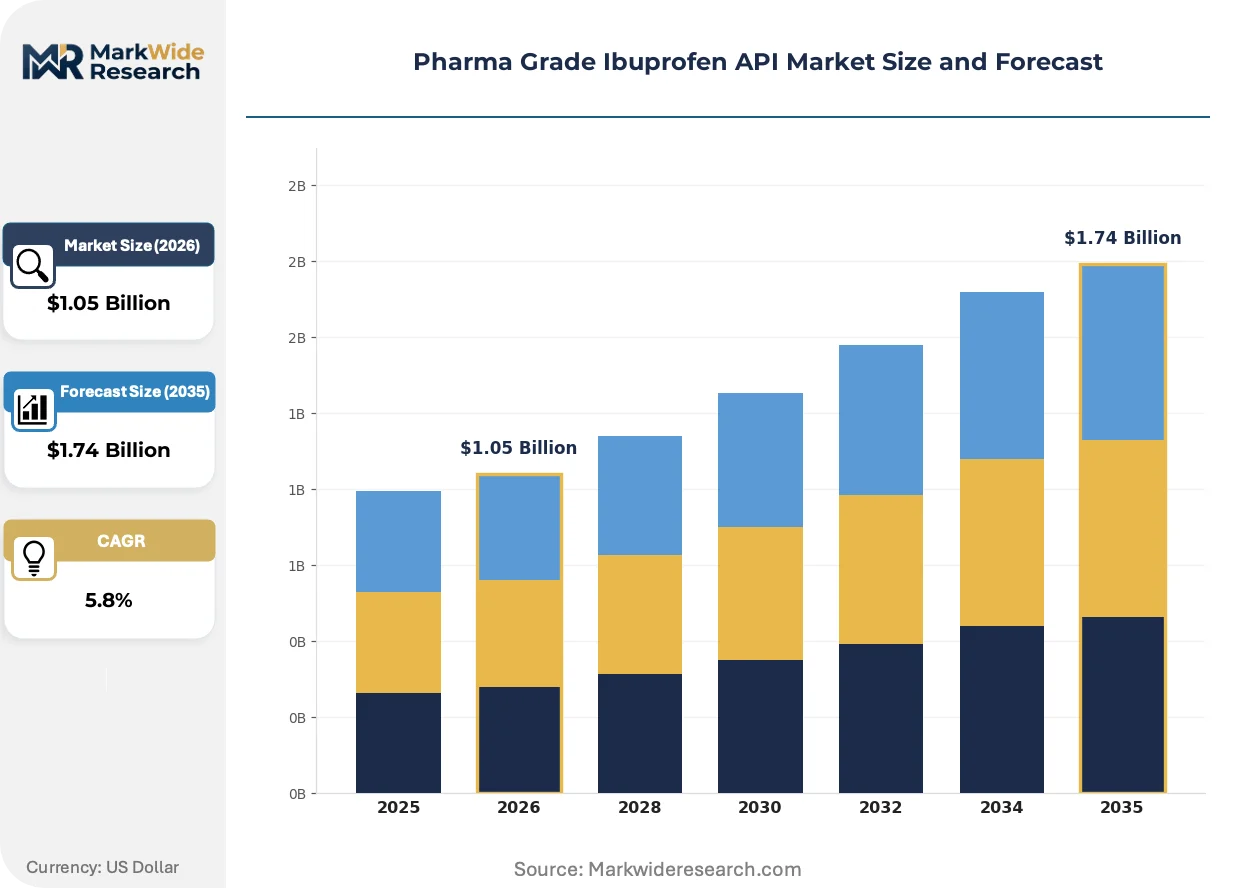
| Market Size in 2026 | $1.05 Billion |
| Market Size in 2035 | $1.74 Billion |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Powder, Solution, Granules, Tablets Grade: Pharmaceutical Grade, Food Grade, Industrial Grade, Laboratory Grade Formulation: Immediate Release, Extended Release, Delayed Release, Enteric Coated Application: Analgesic, Anti-inflammatory, Fever Reducer, Others |
| Companies Covered | SI Group, Dr. Reddy's Laboratories Ltd., IOL Chemicals and Pharmaceuticals, Hubei Biocause Pharmaceutical Co., Ltd., Arch Pharmalabs Ltd., Granules India Limited, Rochem International Inc., Strides Pharma Science Ltd., BASF SE, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Pharma Grade Ibuprofen API Market Trends and Innovations
Process analytical technology integration is displacing offline quality control, enabling real-time release decisions that compress batch cycle times. This shift rewards capital-intensive producers with embedded PAT infrastructure.
Continuous manufacturing platforms are decentralizing production economics for ibuprofen API, collapsing the minimum efficient scale threshold that historically favored commodity-volume players. Mid-sized Indian and European manufacturers are piloting modular microreactor installations to serve regional formulation customers with reduced logistics exposure. The technology is decentralizing procurement patterns toward shorter-contract, higher-frequency purchasing relationships.
REACH authorization requirements for residual-solvent handling are forcing capital redeployment into closed-loop recovery systems across European manufacturing sites. ECHA's sunset date pressures are accelerating process chemistry redesigns to eliminate Category 1 solvent dependence. Specialty API producers with established green-chemistry credentials are capturing preferential supply positions with ESG-mandated pharmaceutical customers.
Formulator consolidation among North American generic-drug customers is concentrating purchasing power and compressing supplier rosters toward dual-source or sole-source arrangements. Large-volume buyers are unbundling technical services from API pricing, forcing commodity producers into pure price competition while awarding integrated solution providers with multi-year contracts. This concentration is most visible in the United States, where three generic manufacturers account for the majority of over-the-counter ibuprofen tablet volumes.
Pharma Grade Ibuprofen API Market Segmentation
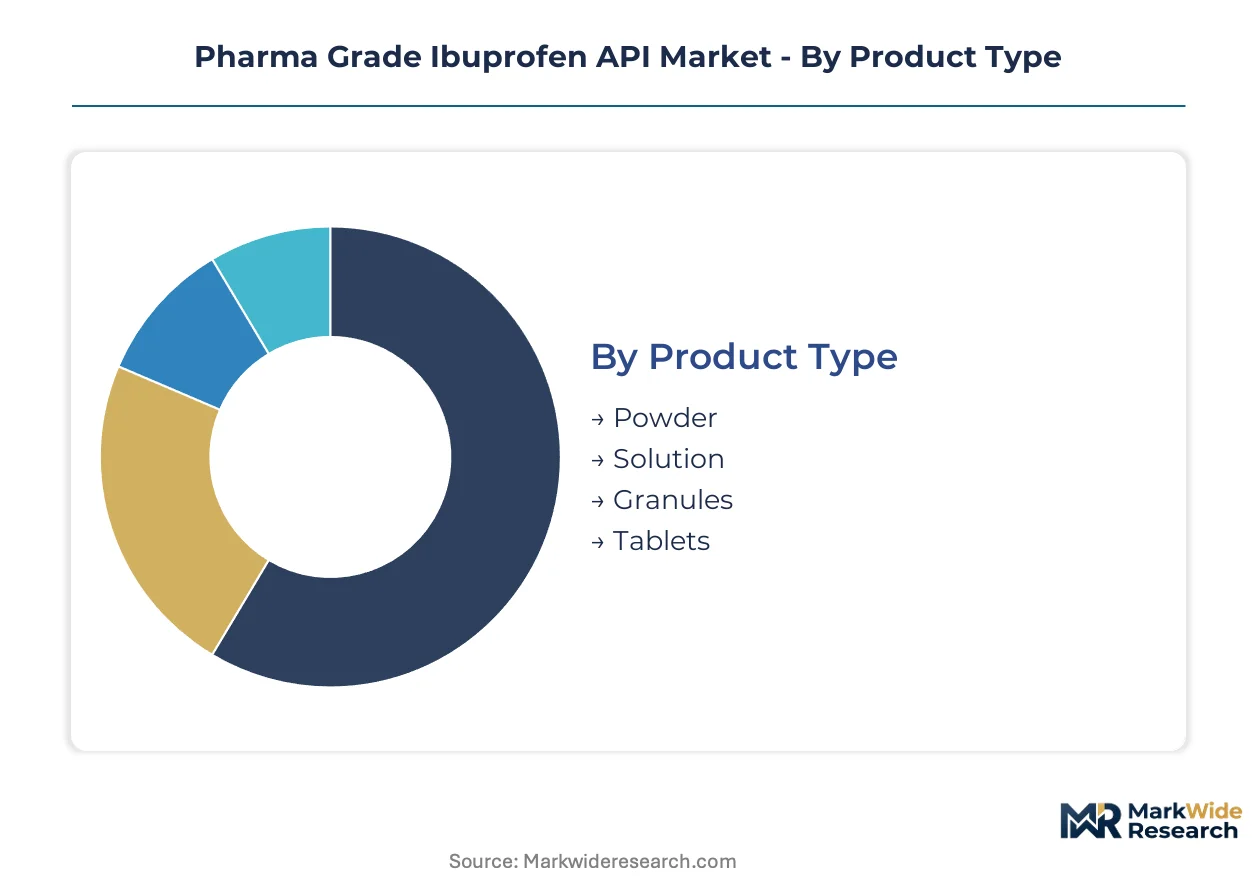
Ibuprofen API procurement patterns fragment sharply across physical form, purity tier, and release kinetics. Each segmentation axis carries distinct margin profiles and qualification burdens that reshape supplier-customer contracting structures.
Product Type:
Powder and solution formats serve fundamentally different integration depths—bulk powder demands downstream formulation infrastructure while solution grades embed directly into liquid-dose manufacturing lines.
- Powder:Crystalline bulk material dominates procurement volumes for tablet compression and encapsulation operations. North American generic manufacturers absorb the majority of powder shipments for immediate-release solid-dose production where feedstock flexibility outweighs handling convenience.
- Solution:Pre-dissolved API streamlines liquid formulation workflows for pediatric suspensions and parenteral preparations. European contract manufacturers favor solution procurement to bypass solvent-handling permits under REACH authorization requirements.
- Granules:Intermediate processed form enables direct-compression tableting without secondary milling stages.
- Tablets:Finished dosage units represent minimal API volume as most procurement concentrates at intermediate stages.
Powder leads volumes today; solution formats are gaining share fastest among specialized liquid-dose contract manufacturers.
Grade:
Certification tiers stratify around downstream regulatory exposure—pharmaceutical and laboratory grades command documentation intensity that industrial specifications escape entirely.
- Pharmaceutical Grade:USP and EP monograph-compliant material anchors all regulated-market drug applications. CDSCO-aligned Indian manufacturers supply the dominant share to export markets where FDA and EMA inspections determine facility eligibility.
- Laboratory Grade:Reference-standard purity serves analytical method development and clinical-trial comparator sourcing. This narrow segment concentrates among European and North American specialty chemical distributors with certified reference material accreditation.
- Food Grade:Lower-specification material for nutraceutical applications outside pharmaceutical regulatory pathways.
- Industrial Grade:Technical purity for non-pharmaceutical chemical synthesis and research applications.
Pharmaceutical grade commands absolute volume dominance; laboratory grade maintains the steepest premium pricing spread.
Formulation:
Release-kinetics engineering separates commodity immediate-release supply from value-added modified-dose technologies requiring specialized process chemistry.
- Immediate Release:Standard dissolution profile serves acute pain management where rapid onset overrides duration concerns. This mature segment concentrates procurement among high-volume Indian API exporters serving cost-sensitive generic tablet markets.
- Extended Release:Matrix-embedded or coated particles enable twice-daily or once-daily dosing for chronic pain protocols. North American formulary placement for osteoarthritis and rheumatoid arthritis maintenance therapy is pulling premium-grade API demand toward this category.
- Delayed Release:Time-lag coatings protect gastric mucosa for sensitive patient populations.
- Enteric Coated:pH-dependent dissolution for intestinal absorption bypassing stomach exposure.
Immediate release retains volume leadership; extended release exhibits the most rapid expansion trajectory as chronic pain management protocols displace acute dosing regimens.
Application:
Therapeutic indication shapes API specification stringency—anti-inflammatory applications demand tighter impurity profiling than simple analgesic formulations.
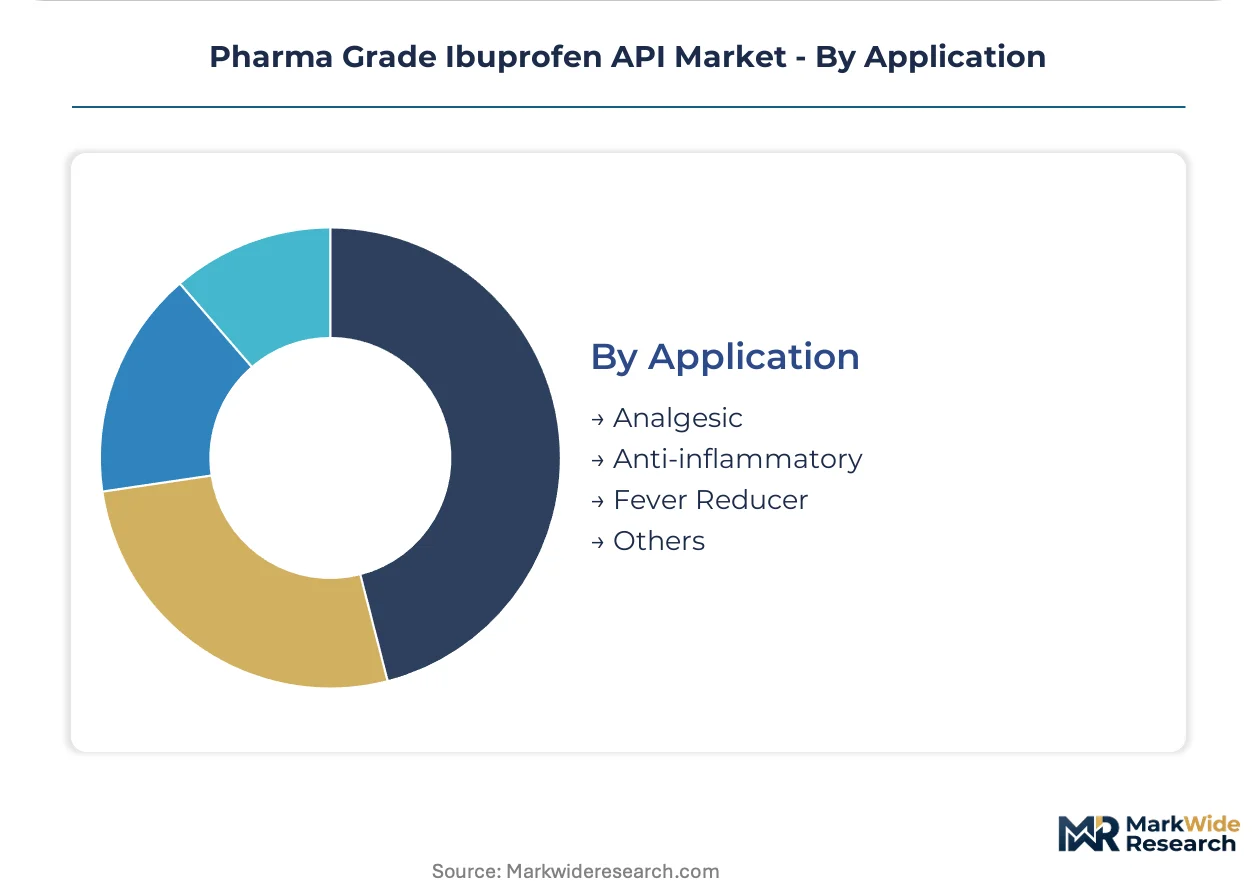
- Analgesic:Pain relief formulations across OTC and prescription channels absorb the majority of API throughput. This application tolerates broader specification ranges where cost minimization dominates procurement criteria.
- Anti-inflammatory:Rheumatoid arthritis and musculoskeletal disorder treatments require extended-release compatibility and tighter endotoxin limits. European and North American markets concentrate demand here as chronic disease protocols expand.
- Fever Reducer:Antipyretic applications in pediatric and infectious disease contexts.
- Others:Emerging investigational uses including potential neurological applications.
Analgesic applications anchor current procurement volumes; anti-inflammatory indications are climbing fastest as population aging extends chronic therapy durations.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
India's API export engine runs faster than China's domestic formulation absorption, creating divergent procurement rhythms across Asia. European regulatory tightening pulls supply toward Western-certified facilities. North American generic consolidation concentrates purchasing power among fewer buyers.
United States
FDA Warning Letters determine facility eligibility for API imports into the world's largest generic drug market. The agency's Current Good Manufacturing Practice enforcement through facility inspections creates binary market access outcomes. New Jersey and Pennsylvania host major formulation clusters where generic manufacturers consolidate procurement toward dual-source API arrangements.
Germany
EMA's active substance master file procedure shapes European import pathways for ibuprofen API suppliers. REACH chemical registration obligations impose environmental compliance burdens on residual-solvent handling. The Rhine-Ruhr industrial corridor anchors formulation manufacturing for export throughout the European Union.
India
CDSCO synchronization with ICH Q3D elemental impurity guidelines collapses dual-track testing for export-oriented manufacturers. Punjab and Gujarat manufacturing clusters serve both domestic formulation needs and regulated-market export contracts. Hyderabad's analytical services ecosystem supports impurity-profile validation for US and European submissions.
China
NMPA domestic approval pathways run parallel to export certification requirements, creating bifurcated quality systems. Hubei province concentration of API synthesis capacity exposes procurement continuity to localized environmental enforcement actions. The Yangtze River Delta formulation belt absorbs the majority of domestic API production.
Brazil
ANVISA pre-qualification offers first-mover positioning ahead of patent cliff waves in Latin America's largest generics market. São Paulo state concentration of pharmaceutical manufacturing creates regional procurement gravity. Local registration dossier completion remains underpenetrated relative to North American and European market entry.
Pharma Grade Ibuprofen API Market Competitive Landscape
Top-tier vendors anchor regulated-market supply, while mid-scale specialists serve regional formulation customers with spot purchasing arrangements. The supplier base compresses toward integrated producers with captive feedstock control and in-house analytical capabilities. Strategic archetypes include phenol-integrated manufacturers, isobutylbenzene-captive operators, and pure-play API exporters. Dominant competitive moves center on process analytical technology deployment and continuous flow chemistry piloting.
Among Indian API specialists, Dr. Reddy's Laboratories Ltd., IOL Chemicals and Pharmaceuticals, and Granules India Limited exemplify scale-driven positions serving North American and European generic-drug customers. SI Group represents the phenol-integrated archetype with upstream chemical pathway control. Hubei Biocause Pharmaceutical Co., Ltd. anchors Chinese supply capacity serving domestic formulation and selective export channels. These named entities occupy positions across the quality-tier spectrum without implying specific strategic actions or market share claims.
| Leading Market Players |
|---|
| SI Group |
| Dr. Reddy's Laboratories Ltd. |
| IOL Chemicals and Pharmaceuticals |
| Hubei Biocause Pharmaceutical Co., Ltd. |
| Arch Pharmalabs Ltd. |
| Granules India Limited |
| Rochem International Inc. |
| Strides Pharma Science Ltd. |
| BASF SE |
| Others |
Pricing and Supply Chain Analysis
Premium-to-commodity grade divergence in ibuprofen API separates USP/EP-certified pharmaceutical material from technical-grade industrial supply, with that bifurcation manifesting in both contract pricing structures and the geographic routing of procurement flows. Indian manufacturers with captive isobutylbenzene production command premium positioning against spot-market dependent competitors, while FDA Warning Letter status creates binary pricing tiers that reshape buyer sourcing decisions.
Pricing Analysis
Capacity additions in Gujarat and Punjab are reshaping price floors for immediate-release powder grades even as extended-release API maintains contract premiums. Three-tier pricing structure across pharmaceutical, laboratory, and industrial grades separates USP/EP-certified material from reference-standard purity and technical applications. Pricing pressure stems from generic-drug customer consolidation in North America, where three manufacturers dominate OTC tablet volumes. Spot purchasers among mid-tier European formulators exhibit highest price sensitivity; integrated producers with captive feedstock show lowest.
Supply Chain Analysis
Direct-to-formulator channels handle North American generic manufacturer demand, while distributor-mediated procurement serves smaller European contract manufacturers. Supply concentrates in India, China, and the United States, with Punjab and Gujarat clusters anchoring export capacity. Raw material flows draw from isobutylbenzene, phenol, and acetic anhydride feedstocks. Single-source vulnerability concentrates in Indian environmental enforcement exposure. Distribution runs through long-term offtake contracts for regulated-market supply and spot platforms for non-certified grades.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Margin expansion in pharma grade ibuprofen API rests on impurity-profile tightening that rewards producers with integrated analytical capabilities and captive feedstock control.
For Market Incumbents: Hedge against isobutylbenzene volatility through backward integration into aromatic hydrocarbon supply or long-term feedstock offtake structures. Defensive consolidation should prioritize acquiring ASMF-filed European facilities to compress qualification timelines for EMA-regulated customers. Process analytical technology deployment represents the critical lever for real-time release capabilities that differentiate against commodity competitors. For New Entrants and Emerging Players: Enter via Brazilian ANVISA pre-qualification ahead of patent cliff waves in Latin America's largest generics market. White-space targets include solution-format API for European liquid-dose contract manufacturers seeking REACH solvent-handling bypass, and extended-release grades for North American chronic pain protocols. Go-to-market positioning should emphasize green-chemistry credentials for ESG-mandated pharmaceutical customers. For Investors and Strategic Acquirers: Asymmetric upside sits with phenol-integrated manufacturers with Boots-Hoechst-Celanese route expertise and established FDA inspection histories. Long-term viability favors producers with dual USP/EP pharmacopeial alignment and embedded PAT infrastructure. Watch nitrosamine testing requirement expansion as inflection indicator for batch-rejection rate impacts on release timelines.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Isobutylbenzene | Captive aromatic hydrocarbon supply insulates margin pools from feedstock volatility. |
| Process Analytical Technology Deployment | Real-time release decisions compress batch cycle times for FDA-inspected facilities. |
| EMA ASMF Filing Acceleration | Streamlined European master file procedures shorten qualification timelines for Indian exporters. |
| Continuous Flow Chemistry Piloting | Microreactor intensification aligns with REACH solvent reduction trajectories. |
| Brazilian ANVISA Pre-qualification | First-mover registration completion captures Latin American generics expansion. |
Research Methodology
Direct dialogue with API manufacturing plant managers, generic drug procurement directors, regulatory affairs specialists, and CDSCO compliance officers grounded qualitative assessment, cross-referenced against FDA 483 observations, EMA ASMF filings, USP monograph revisions, and Indian customs export data. Bottom-up volume triangulation against top-down value estimation validated market sizing across the analysis window.
Bottom-up modeling disaggregated volume by grade tier, formulation kinetics, and regional regulatory cluster, while top-down analysis tracked value flows through pharmaceutical versus laboratory certification pathways. CAGRs derived from segment-level growth rate aggregation weighted by base-year contribution. Forecast inputs incorporated impurity-profile specification evolution and extended-release formulary placement trajectories.
The model holds under stable pharmacopeial harmonization; deviation in USP-EP-IP residual-solvent limit divergence would shift qualification burden estimates. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pharmaceutical Ingredients
China Active Pharmaceutical Ingredients (API) Market
Pharmaceutical Ingredients
Pharmaceutical Grade Amino Acid Market
Pharmaceutical Ingredients
Global Granisetron Market
Pharmaceutical Ingredients
Antibiotics Active Pharmaceutical Ingredient (API) Market
Pharmaceutical Ingredients
Non-Steroidal Anti-Inflammatory Drugs (Nsaids) Market
Pharmaceutical Ingredients
Global Barbiturate Drugs Market
Pharmaceutical Ingredients
Cox 2 Inhibitors Market
Pharmaceutical Ingredients
Fipronil Market
Pharmaceutical Ingredients
Sennosides Market
Pharmaceutical Ingredients
Pharmaceutical Fine Chemicals Market
Pharmaceutical Ingredients
Active Pharmaceutical Ingredient for Cancer Market
Pharmaceutical Ingredients
Nortriptyline Hydrochloride Market
Pharmaceutical Ingredients
Rizatriptan Market
Pharmaceutical Ingredients
Lidocaine Hydrochloride Market
Pharmaceutical Ingredients
Casein and Casein Derivatives Market
Pharmaceutical Ingredients
Global Tizanidine Market