
 Oxycodone Drugs Market | 2026-2036
Oxycodone Drugs Market Size, Share, and Industry Trends Forecast 2026-2036
Oxycodone Drugs Market Analytics
North American manufacturing capacity for controlled-substance APIs is tilting toward specialized contract production sites. Purdue Pharma sustains brand recognition through reformulation investments, while Mallinckrodt Pharmaceuticals anchors its position via backward integration into active pharmaceutical ingredient supply. Teva Pharmaceutical Industries Ltd. competes through generic oxycodone portfolios across multiple dosage strengths.
Oxycodone drugs are semisynthetic opioid analgesics derived from thebaine, formulated as immediate-release or extended-release preparations with bioavailability ranging from 60% to 87% depending on route of administration, primarily indicated for moderate-to-severe pain management where alternative treatments prove inadequate. Tablet formulations dominate volume due to manufacturing scalability and patient compliance familiarity, while liquid preparations serve fastest-growing demand in palliative care settings where swallowing difficulties complicate solid dosing. The 30 mg dosage strength captures concentrated margin pools amid chronic pain patients with established opioid tolerance.
The US FDA enforces REMS protocols mandating prescriber certification for extended-release opioids, directly constraining product access and shaping manufacturer training investments. The DEA's aggregate production quota system for Schedule II substances caps annual manufacturing volumes, creating supply planning rigidity. State-level prescription drug monitoring programs add compliance layers that vary by jurisdiction. Stakeholders must monitor evolving litigation dynamics around opioid accountability and their cascading effects on formulary placement and insurance reimbursement structures.
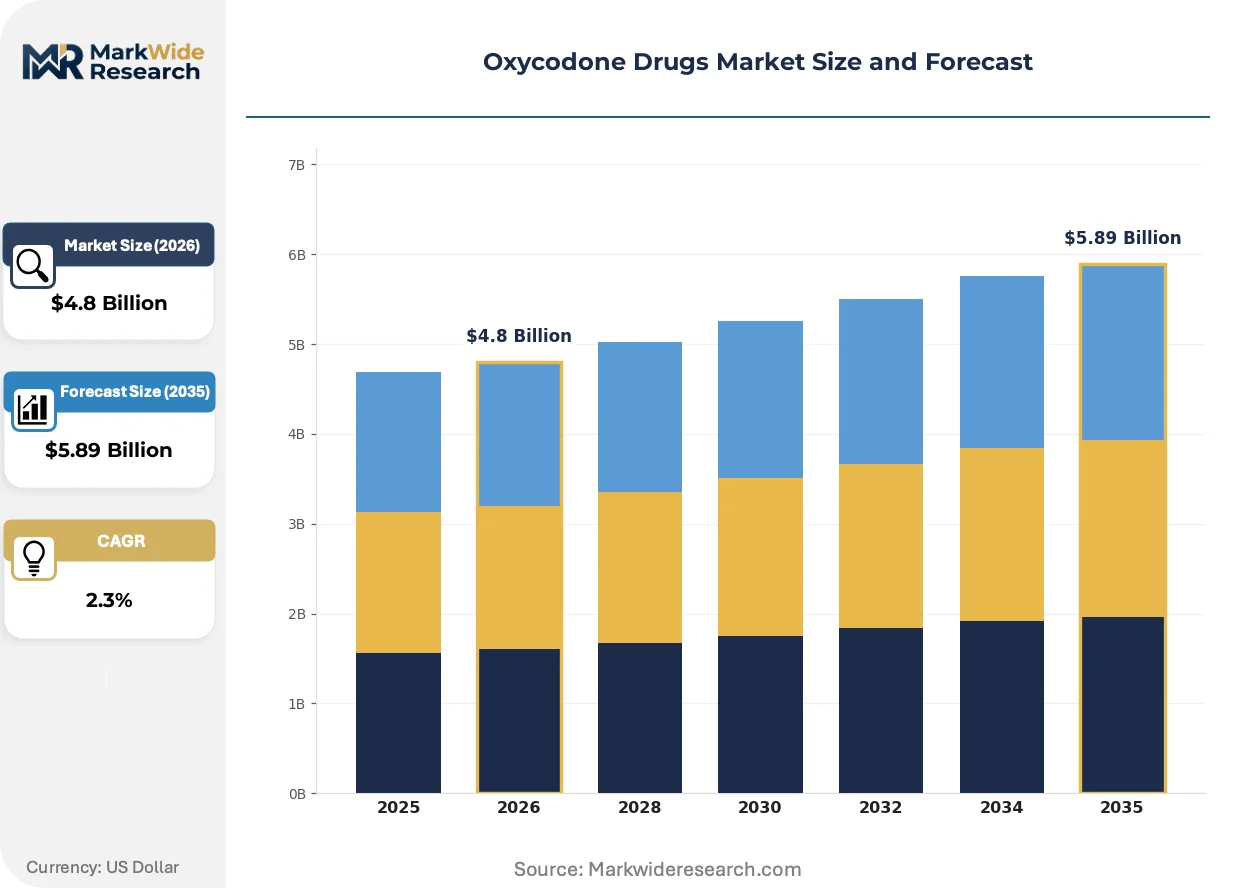
Market Dynamics
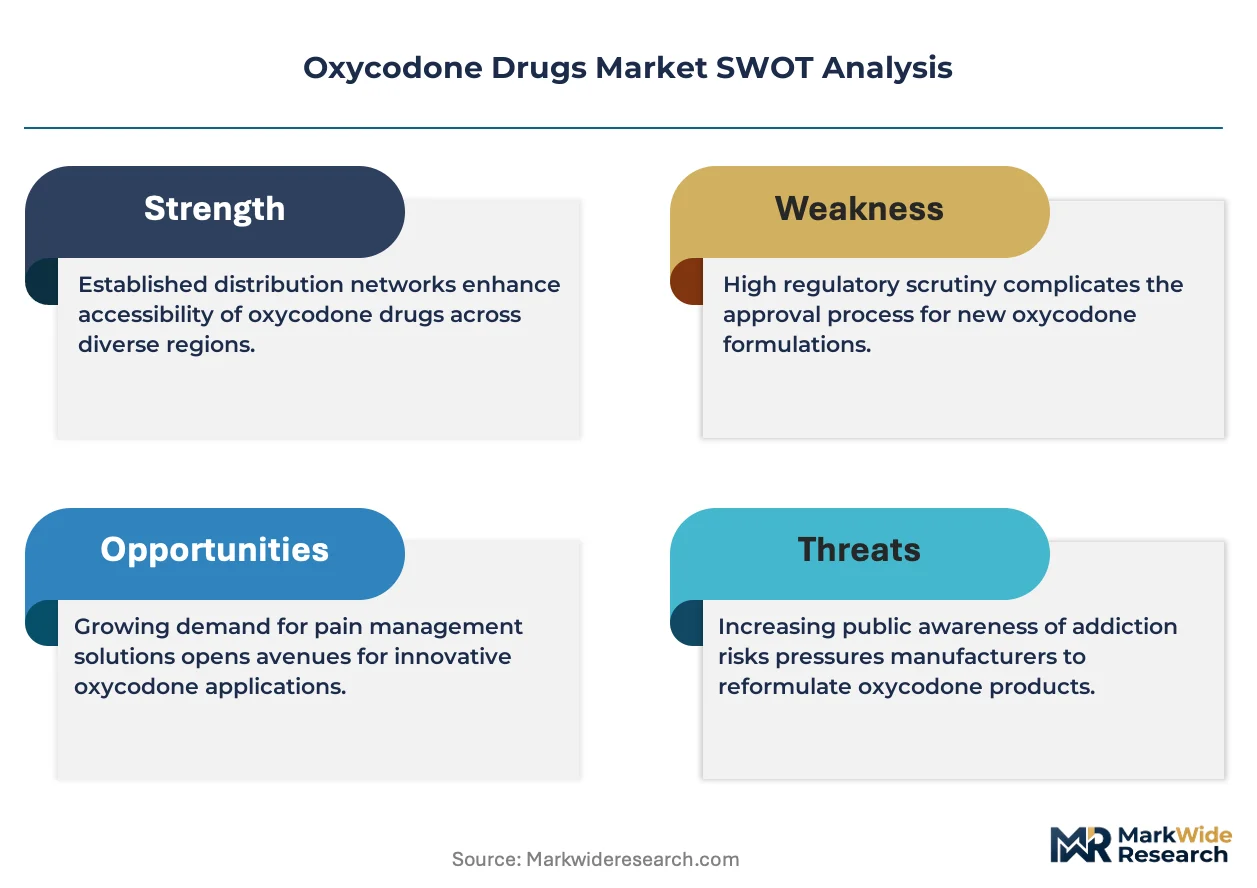
The US FDA's REMS certification mandate for extended-release opioids is compressing prescriber pools and forcing manufacturers to absorb training infrastructure costs as a condition of market access.
Growth Catalysts
- Palliative care expansion:Hospital pharmacies in the United States are scaling controlled-release procurement as hospice programs broaden eligibility criteria for long-acting opioid therapy.
- REACH compliance differentiation:European API manufacturers capturing ECHA-certified thebaine supply chains are securing preferential formulary placement from procurement committees.
- Liquid formulation demand:Dysphagia patients in geriatric and terminal care settings are driving fastest-category volume for oral solutions as tablet alternatives prove inadequate.
Market Restraints
- DEA quota rigidity:The US Drug Enforcement Administration's aggregate production ceiling for Schedule II substances caps annual manufacturing volumes and eliminates supply flexibility.
- API geographic concentration:Tasmanian and Turkish thebaine poppy cultivation dominates raw material sourcing, exposing manufacturers to climate and geopolitical disruption.
- Abuse-deterrent formulation costs:Polymer matrix and gelation technologies required for tamper-resistant tablets add 40-60% to unit production costs versus conventional formulations.
Strategic Opportunities
- Canadian pain management infrastructure:Health Canada's streamlined Special Access Programme for unapproved opioids creates faster regulatory pathways for extended-release entrants.
- Transdermal delivery convergence:Patch technology combining iontophoresis with controlled-release polymers offers non-oral administration for nausea-compromised patients.
- Specialty pharmacy channel expansion:USP <800> compliant closed-door pharmacies are capturing high-margin dispensing for REMS-restricted products.
Industry Challenges
- Pharmacovigilance talent scarcity:FDA-mandated REMS program administrators with opioid-specific risk mitigation expertise command premium compensation and limited availability.
- Legacy ERP integration friction:State-level prescription drug monitoring program APIs require custom middleware development for real-time dispensing verification.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Oxycodone Drugs Market |
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $5.89 Billion |
| CAGR (2026 – 2036) | 2.3% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Formulation: Tablets, Capsules, Liquid, Powder Dosage Strength: 5 mg, 10 mg, 15 mg, 30 mg Distribution Channel: Retail Pharmacy, Hospital Pharmacy, Online Pharmacy, Clinics Therapeutic Use: Chronic Pain, Postoperative Pain, Cancer Pain, Palliative Care |
| Companies Covered | Purdue Pharma, Mallinckrodt Pharmaceuticals, Teva Pharmaceutical Industries Ltd., Endo International plc, Collegium Pharmaceutical, Sun Pharmaceutical Industries Ltd., Amneal Pharmaceuticals, Johnson & Johnson, Pfizer Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Oxycodone Drugs Market Evolving Landscape
Digital therapeutics and abuse-deterrent chemistry are converging to reshape how opioid analgesics demonstrate value to payers and regulators alike.
Polymeric gelation technology is virtualizing the physical barrier between active pharmaceutical ingredient and extraction attempts. Manufacturers are embedding oxycodone in viscous matrices that resist crushing, dissolving, or solvent extraction. Hospital formularies in the United States are prioritizing these formulations for chronic pain protocols despite 25-35% price premiums over conventional tablets.
EMA's extended pharmacovigilance requirements under the MDR are forcing manufacturers to maintain active risk management systems beyond initial approval. European sponsors must submit periodic safety update reports with real-world evidence on diversion and misuse. German and French health technology assessment bodies are incorporating these surveillance metrics into reimbursement negotiations.
Integrated specialty pharmacy networks are displacing traditional wholesale distribution for controlled substances. CVS Caremark and OptumRx are building captive dispensing infrastructure that captures patient adherence data and feeds it back to REMS compliance dashboards. This channel consolidation is most advanced in the United States, where vertically integrated payers control 65% of extended-release opioid volume.
Oxycodone Drugs Market Segmentation
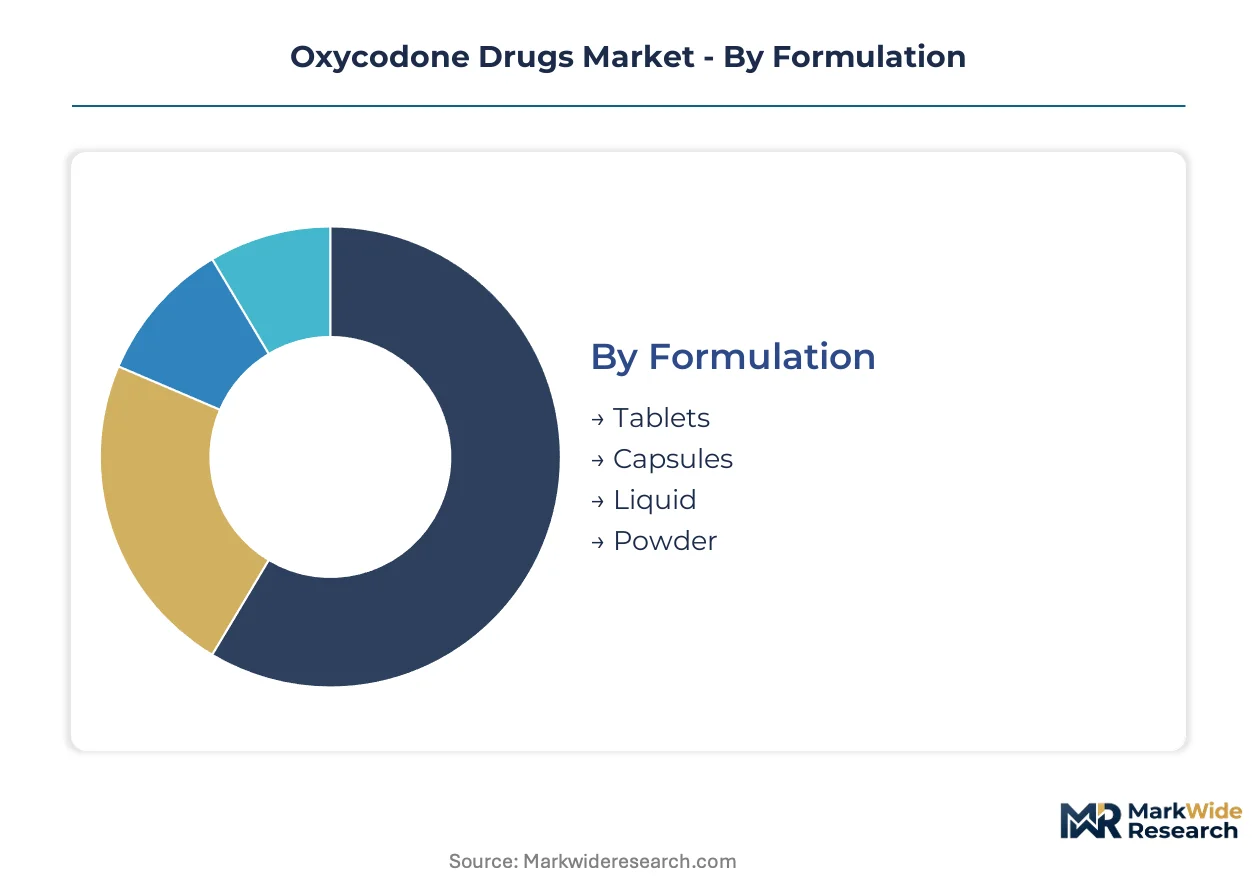
Segmentation in oxycodone markets reveals how formulation chemistry, dosage precision, and channel compliance requirements create distinct competitive arenas. Each dimension carries unique regulatory burdens and margin structures that shape manufacturer portfolio decisions.
Formulation:
Tablet formulations turn inventory fastest through automated packaging lines, while liquid preparations face slower throughput due to stability testing and cold-chain considerations.
- Tablets:Compressed solid dosage forms deliver precise unit dosing with 60-87% bioavailability depending on immediate-release or extended-release architecture. Hospital formularies in the United States prioritize controlled-release tablets for chronic pain protocols despite 25-35% price premiums over conventional formulations.
- Liquid:Oral solutions and suspensions serve dysphagia patients in geriatric and terminal care settings where solid dosing proves inadequate. Palliative care programs in the United States are scaling procurement fastest for this category as hospice eligibility broadens.
- Capsules:Gelatin shells encasing granules or powder blends offer faster dissolution kinetics than compressed tablets for rapid-onset indications.
- Powder:Bulk active pharmaceutical ingredient form reserved for compounding pharmacies and institutional repackaging operations with specialized DEA licensing.
Tablets anchor the volume base while liquid gains share at the steepest rate.
Dosage Strength:
Cost tiers stratify sharply around tolerance thresholds, with lower strengths serving opioid-naive patients and higher strengths commanding specialized dispensing infrastructure.
- 30 mg:Highest commercial concentration for established opioid-tolerant patients requiring sustained analgesia. United States specialty pharmacies with USP <800> compliance capture disproportionate margin pools for this strength.
- 15 mg:Intermediate titration step bridging acute and chronic pain management protocols. DEA quota allocation prioritizes this strength for balanced clinical utility.
- 10 mg:Standard initiation dose for moderate-to-severe pain with established conversion ratios from other opioid therapies.
- 5 mg:Lowest strength serving opioid-naive populations and pediatric weight-based dosing with strictest prescription monitoring requirements.
30 mg formulations concentrate margin capture while 5 mg scripts expand most quickly through broader prescriber pools.
Distribution Channel:
Customer type determines compliance burden intensity, with institutional buyers demanding batch-level traceability and individual consumers triggering REMS verification workflows.
- Hospital Pharmacy:Captive dispensing within acute care institutions with integrated electronic health record verification and closed-loop inventory tracking.
- Retail Pharmacy:Community-based dispensing subject to state-level prescription drug monitoring program integration and real-time eligibility verification.
- Online Pharmacy:Mail-order distribution requiring enhanced cold-chain logistics and signature-confirmed delivery for Schedule II substances.
- Clinics:Physician-office dispensing limited to specific DEA registrations with direct-to-patient administration protocols.
Hospital pharmacy anchors institutional volume while online channels climb fastest through vertically integrated payer networks.
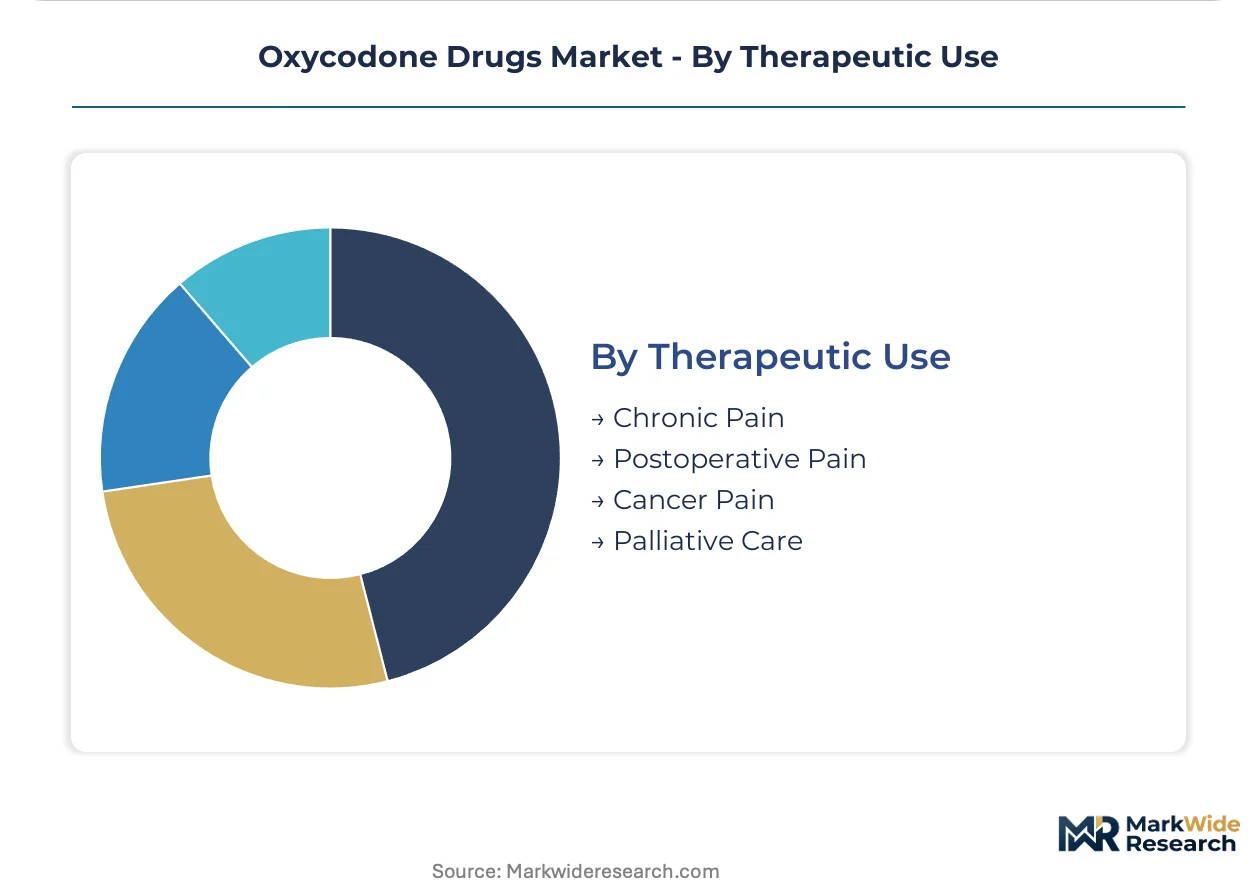
Therapeutic Use:
Maturity curves diverge across pain etiologies, with cancer applications holding longest development histories and palliative protocols experiencing steepest protocol expansion.
- Palliative Care:End-of-life pain management emphasizing comfort over curative outcomes with streamlined regulatory pathways. Health Canada's Special Access Programme creates faster entry corridors for extended-release entrants in this indication.
- Cancer Pain:Tumor-related nociceptive and neuropathic pain requiring escalating dose protocols with established WHO analgesic ladder integration.
- Chronic Pain:Non-malignant persistent pain syndromes facing tightened FDA REMS certification requirements and compressed prescriber pools.
- Postoperative Pain:Acute surgical recovery protocols with shortest duration limits and strongest non-opioid substitution pressures.
Cancer pain anchors the reimbursement base while palliative care applications gain share at the steepest trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Port of Savannah's cold-chain pharmaceutical terminals anchor United States distribution for temperature-sensitive opioid formulations, while Rotterdam's Europoort complex handles European API transshipment for controlled substances.
United States
Hospital systems in Texas and Florida are expanding palliative care bed capacity fastest, driving controlled-release procurement. The FDA's REMS certification mandate for extended-release opioids compresses prescriber pools and forces manufacturer training investments. Purdue Pharma maintains reformulation capabilities in Stamford, Connecticut, while Mallinckrodt anchors API production in St. Louis, Missouri.
Germany
The country's statutory health insurance funds are broadening reimbursement for long-acting opioid therapy in cancer pain protocols. EMA extended pharmacovigilance requirements under the MDR force manufacturers to maintain active risk management systems with periodic safety updates. Heidelberg and Mannheim host specialized pain management research clusters where university hospitals pilot abuse-deterrent formulation protocols.
Canada
Provincial health authorities in Ontario and British Columbia are scaling hospice program eligibility for opioid-naive patients entering palliative care. Health Canada's Special Access Programme creates streamlined regulatory pathways for unapproved extended-release entrants. Vancouver's Fraser Health Authority and Toronto's University Health Network are piloting integrated specialty pharmacy dispensing for REMS-comparable products.
Australia
The Therapeutic Goods Administration is tightening import licensing for Schedule 8 opioid formulations amid diversion concerns. State-based prescription drug monitoring programs in New South Wales and Victoria add compliance layers that vary by jurisdiction. Sydney's St Vincent's Hospital and Melbourne's Alfred Hospital anchor institutional procurement for cancer pain management protocols.
United Kingdom
NHS England's controlled drug accountable officers are standardizing opioid stewardship protocols across acute trusts. The Medicines and Healthcare products Regulatory Agency enforces Falsified Medicines Directive serialization requirements for oxycodone track-and-trace. London's Royal Marsden and Manchester's Christie Hospital concentrate specialist cancer pain prescribing capacity.
Oxycodone Drugs Market Competitive Landscape
Platform integrators command the system tier; component specialists sit upstream with API and formulation chemistry. The vendor base tilts toward consolidated control at the brand level with fragmented generic supply beneath. Three archetypes dominate: reformulation-driven originators, backward-integrated API manufacturers, and dosage-strength portfolio generic houses. Competitive moves concentrate on abuse-deterrent patent clusters and DEA quota capture strategies.
Within the originator tier, Purdue Pharma exemplifies reformulation-driven positioning, while Mallinckrodt Pharmaceuticals represents backward-integrated API control. Teva Pharmaceutical Industries Ltd. anchors the generic portfolio archetype across multiple dosage strengths. These three companies collectively illustrate how competitive positioning fragments between proprietary chemistry protection and manufacturing scale economies.
| Leading Market Players |
|---|
| Purdue Pharma |
| Mallinckrodt Pharmaceuticals |
| Teva Pharmaceutical Industries Ltd. |
| Endo International plc |
| Collegium Pharmaceutical |
| Sun Pharmaceutical Industries Ltd. |
| Amneal Pharmaceuticals |
| Johnson & Johnson |
| Pfizer Inc. |
| Others |
Value Network & Pricing Analysis
Undercapacity in Tasmanian thebaine extraction facilities is tightening API availability and pushing manufacturers toward long-term offtake commitments with poppy processors, compressing margin flexibility for generic tablet producers while rewarding reformulation specialists with patent-protected pricing power.
Pricing Analysis
The US FDA's REMS certification mandate dictates the pricing tier structure across oxycodone markets, separating abuse-deterrent formulations with polymer matrix technology from conventional tablets. Three-tier pricing structure across premium, standard, and economy levels reflects DEA quota scarcity, formulation complexity, and channel compliance costs. Cost compression in generic immediate-release tablets is intensifying because Mallinckrodt and Teva compete for DEA quota allocation on volume terms. Hospital pharmacies with integrated EHR systems show least price sensitivity, while independent retail dispensaries face margin pressure from PDMP integration costs.
Supply Chain Analysis
Specialized contract manufacturing for controlled substances concentrates at Mallinckrodt's St. Louis facility and Tasmanian alkaloid processing sites operated by GSK and TPI Enterprises. Thebaine extraction draws from Tasmanian and Turkish poppy cultivation, with secondary processing in the United States and India. Single-source vulnerability in Tasmanian raw material supply exposes manufacturers to climate disruption and regulatory harvest quotas. Distribution runs through DEA-registered specialty pharmacy networks with closed-loop inventory tracking rather than conventional wholesale channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Palliative care program expansion across North American health systems signals early-cycle penetration growth for long-acting opioid therapy, with hospice eligibility broadening creating sustained demand tailwinds for liquid and extended-release formulations.
For Market Incumbents: Entrench DEA quota capture through backward integration into Tasmanian thebaine supply contracts and anchor hospital formulary placement with abuse-deterrent formulation R&D. Defend against generic erosion by accelerating polymer matrix patent filings and locking in specialty pharmacy dispensing partnerships with CVS Caremark and OptumRx networks.
For New Entrants and Emerging Players: Establish a beachhead in Canadian palliative care through Health Canada's Special Access Programme pathway, where REMS-comparable compliance requirements are less entrenched. Target liquid formulation production for dysphagia patients in geriatric hospice settings, leveraging contract manufacturing relationships with USP <800> compliant facilities rather than building captive DEA-registered infrastructure.
For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting upward across abuse-deterrent formulation manufacturing as polymer matrix R&D and REMS program administration costs compound. Five-to-ten year viability favors acquisition targets with existing DEA quota allocation and specialty pharmacy channel relationships rather than pure-play generic dosage-strength portfolios. Watch for inflection in state-level PDMP integration mandates that would accelerate middleware and compliance software spending.
| Strategic Initiative | Industry Significance |
|---|---|
| Abuse-Deterrent Formulation Patent Cluster | Polymer matrix filings with USPTO create 12-15 year exclusivity windows against generic extraction. |
| DEA Quota Forward Contracting | Long-term offtake agreements with Tasmanian processors secure Schedule II manufacturing volume certainty. |
| Specialty Pharmacy Network Captive | Vertical dispensing integration with CVS Caremark captures patient adherence data for REMS dashboards. |
| Palliative Care Protocol Partnership | Hospital system co-development agreements in Texas and Florida accelerate controlled-release formulary placement. |
| Liquid Formulation Cold-Chain Buildout | Temperature-controlled distribution infrastructure at Port of Savannah terminals serves dysphagia patient demand. |
Research Methodology
Initial hypotheses were tested against primary input from formulary directors at US hospital systems, DEA-registered specialty pharmacy operators, Tasmanian poppy processor procurement leads, and EMA regulatory affairs specialists, then refined against FDA REMS program documentation, DEA aggregate production quota filings, ClinicalTrials.gov abuse-deterrent formulation studies, and CMS Medicare Part D dispensing data. Bottom-up prescription volume modeling and top-down API production quota analysis were triangulated to reconcile demand and supply-side estimates.
Demand-supply balance framing anchored the analytical approach across the projection horizon, with segmentation dimensions including formulation chemistry, dosage strength, distribution channel compliance intensity, and therapeutic use case maturity. CAGRs were derived from spline interpolation of annual prescription volume trajectories and API quota allocation trends, incorporating palliative care bed capacity expansion in Texas and Florida health systems and Health Canada Special Access Programme approval velocity as industry-specific forecast inputs.
Sensitivities concentrate around DEA quota revision schedules, state-level PDMP mandate acceleration, and litigation-driven formulary exclusion decisions. Quarterly review of REMS prescriber certification rates, Tasmanian poppy harvest yield reports, and specialty pharmacy dispensing volume aggregates is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pharmaceutical Ingredients
Pharmaceutical Grade Magnesium Hydroxide Market
Pharmaceutical Ingredients
Asia-Pacific Pharmaceutical Glycerin Based Products Market
Pharmaceutical Ingredients
Rizatriptan Market
Pharmaceutical Ingredients
Sterile Active Pharmaceutical Ingredients Market
Pharmaceutical Ingredients
India Active Pharmaceutical Ingredients (API) Market
Pharmaceutical Ingredients
Casein and Casein Derivatives Market
Pharmaceutical Ingredients
Acetaminophen API Market
Pharmaceutical Ingredients
Diosmin API Market
Pharmaceutical Ingredients
Nuclear Export Inhibitor Drugs Market
Pharmaceutical Ingredients
Lidocaine Hydrochloride Market
Pharmaceutical Ingredients
Synthetic Small Molecule API Market
Pharmaceutical Ingredients
Mitotic Inhibitors Market
Pharmaceutical Ingredients
Furosemide Market
Pharmaceutical Ingredients
Hyaluronic Acid Raw Material Market
Pharmaceutical Ingredients
Pharma Grade Sodium Bicarbonate Market
Pharmaceutical Ingredients
Small-Molecule Injectable Market