
 Injectable Benzodiazepine Market | 2026-2036
Injectable Benzodiazepine Market Size, Share, and Industry Trends Forecast 2026-2036
Injectable Benzodiazepine Market Outlook
Prefilled syringe bundling with automated dispensing cabinets is consolidating purchasing decisions for hospital formularies. Pfizer leverages its sterile injectable infrastructure to sustain supply security for institutional buyers across North America. Hikma Pharmaceuticals anchors its position through geographic dominance in Middle Eastern and European hospital tenders. Teva Pharmaceutical Industries Ltd. competes on manufacturing scale, offering multi-source lorazepam vials that reduce single-supplier risk for pharmacy directors.
Injectable benzodiazepines are aqueous or propylene glycol-based sterile solutions formulated for parenteral administration, typically containing 5 mg/mL diazepam, 2 mg/mL lorazepam, or 1 mg/mL midazolam with pH-adjusted buffers to ensure chemical stability and rapid CNS penetration. These formulations serve as first-line agents for acute seizure cessation, procedural sedation, and preoperative anxiolysis where oral bioavailability is contraindicated or insufficient. Midazepam injection dominates procedural sedation applications due to its rapid onset and short half-life, while lorazepam vials command margin pools in emergency seizure management where longer duration of action reduces redosing frequency. The intravenous delivery mode leads volume shipments, though intramuscular formulations retain niche demand in prehospital and battlefield medicine settings where vascular access is delayed.
FDA risk evaluation and mitigation strategies for benzodiazepine dependence shape product labeling, prescriber training requirements, and distribution controls that manufacturers must integrate into commercialization planning. EMA pharmacovigilance obligations and US Drug Enforcement Administration scheduling classifications further constrain formulation innovation and cross-border shipment logistics for controlled substance injectables. Stakeholders must monitor evolving FDA guidance on benzodiazepine-sparing anesthesia protocols and state-level prescription drug monitoring program expansions that could redirect demand toward alternative sedative agents.
Market Dynamics
FDA benzodiazepine labeling revisions and DEA scheduling enforcement are compressing formulation innovation timelines while hospital emergency departments intensify demand for rapid-onset parenteral sedatives. Manufacturers must now integrate risk evaluation protocols directly into commercialization planning.
Growth Catalysts
- Emergency medicine protocol expansion:Hospital emergency departments in the United States are standardizing intravenous midazolam for rapid seizure termination, creating institutional demand pull through anesthesia and critical care formularies.
- REMS integration:FDA risk evaluation and mitigation strategies for benzodiazepine dependence mandate prescriber training and distribution controls that favor established sterile injectable manufacturers with compliance infrastructure.
- Prehospital administration:Intramuscular lorazepam formulations retain demand in battlefield medicine and ambulance settings where vascular access is delayed, sustaining niche volume pools.
Market Restraints
- Propylene glycol supply concentration:Formulation dependence on this solvent creates input cost volatility and supplier lock-in for parenteral diazepam and lorazepam production.
- Controlled substance logistics:DEA scheduling classifications constrain cross-border shipment routes and warehousing requirements, elevating distribution complexity for institutional buyers.
- Non-benzodiazepine sedation alternatives:Ketamine and dexmedetomidine protocols in procedural sedation threaten to displace midazolam volume in anesthesia departments.
Strategic Opportunities
- Prefilled syringe automation:Bundling with automated dispensing cabinets consolidates hospital formulary decisions and locks in multi-year procurement contracts for pharmacy directors.
- EMA pharmacovigilance alignment:European manufacturers can leverage stricter adverse event reporting standards as competitive differentiation in tenders requiring documentation depth.
- Prehospital expansion:Battlefield medicine and rural ambulance services in underserved geographies present white-space demand for intramuscular formulations with extended stability profiles.
Industry Challenges
- Sterile manufacturing capacity:Aseptic fill-finish line qualification and isolator technology deployment require substantial capex outlays that constrain mid-tier manufacturer expansion.
- Controlled substance licensing:State-level prescription drug monitoring program integration demands specialized compliance personnel and IT infrastructure that fragment operational focus.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Injectable Benzodiazepine Market |
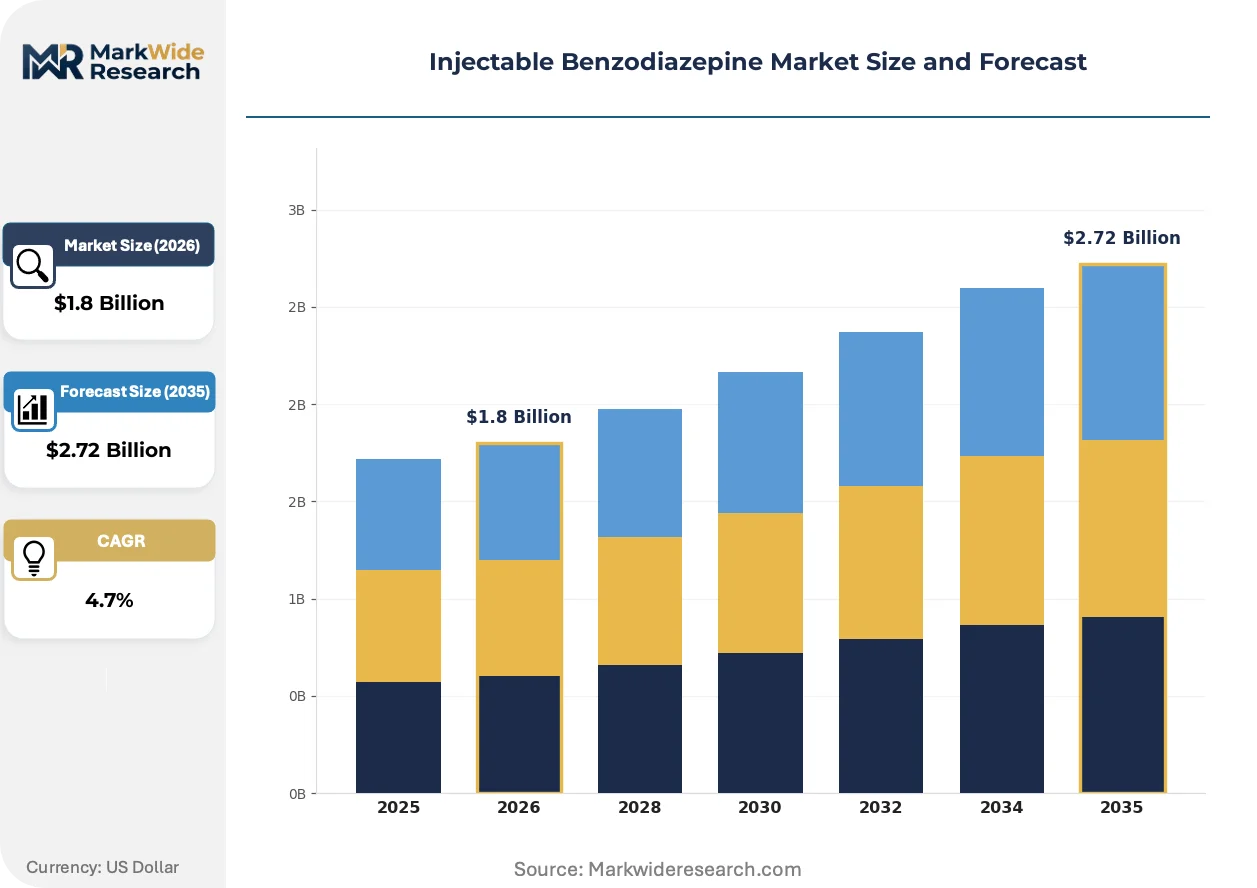
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $2.72 Billion |
| CAGR (2026 – 2036) | 4.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Diazepam, Lorazepam, Midazolam, Clonazepam Delivery Mode: Intravenous, Intramuscular, Subcutaneous, Epidural End User: Hospitals, Clinics, Emergency Rooms, Homecare Providers Application: General Anesthesia, Sedation, Seizure Control, Anxiety Management |
| Companies Covered | Pfizer, F. Hoffmann-La Roche AG, Teva Pharmaceutical Industries Ltd., Hikma Pharmaceuticals, Bausch Health Companies Inc., NATCO Pharma, AdvaCare Pharma, Hameln Pharma, Accord Healthcare, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Injectable Benzodiazepine Market Strategic Shifts
Formulation stability engineering and delivery device integration are compressing product development cycles while regulatory documentation requirements intensify. These shifts favor manufacturers with captive sterile infrastructure and automated packaging capabilities.
Lipid emulsion diazepam formulations are rewriting stability expectations for parenteral benzodiazepines. Hospital pharmacy directors are adopting these alternatives to reduce propylene glycol-related adverse events in high-dose sedation protocols. This reformulation wave is compressing legacy aqueous solution margins while enabling premium positioning for chemically stable alternatives.
EMA pharmacovigilance obligations under the Medical Device Regulation are tightening post-market surveillance requirements for combination products. Manufacturers must now integrate device-related adverse event tracking into their quality management systems. European hospital tenders increasingly weight documentation completeness, disadvantaging suppliers with fragmented regulatory affairs functions.
Consolidated purchasing through group purchasing organizations is compressing supplier rosters for institutional buyers. Pharmacy directors are reducing single-source risk by demanding multi-manufacturer lorazepam vial availability. This concentration is most visible in United States health system networks where formulary standardization across dozens of facilities locks in volume commitments.
Injectable Benzodiazepine Market Segmentation
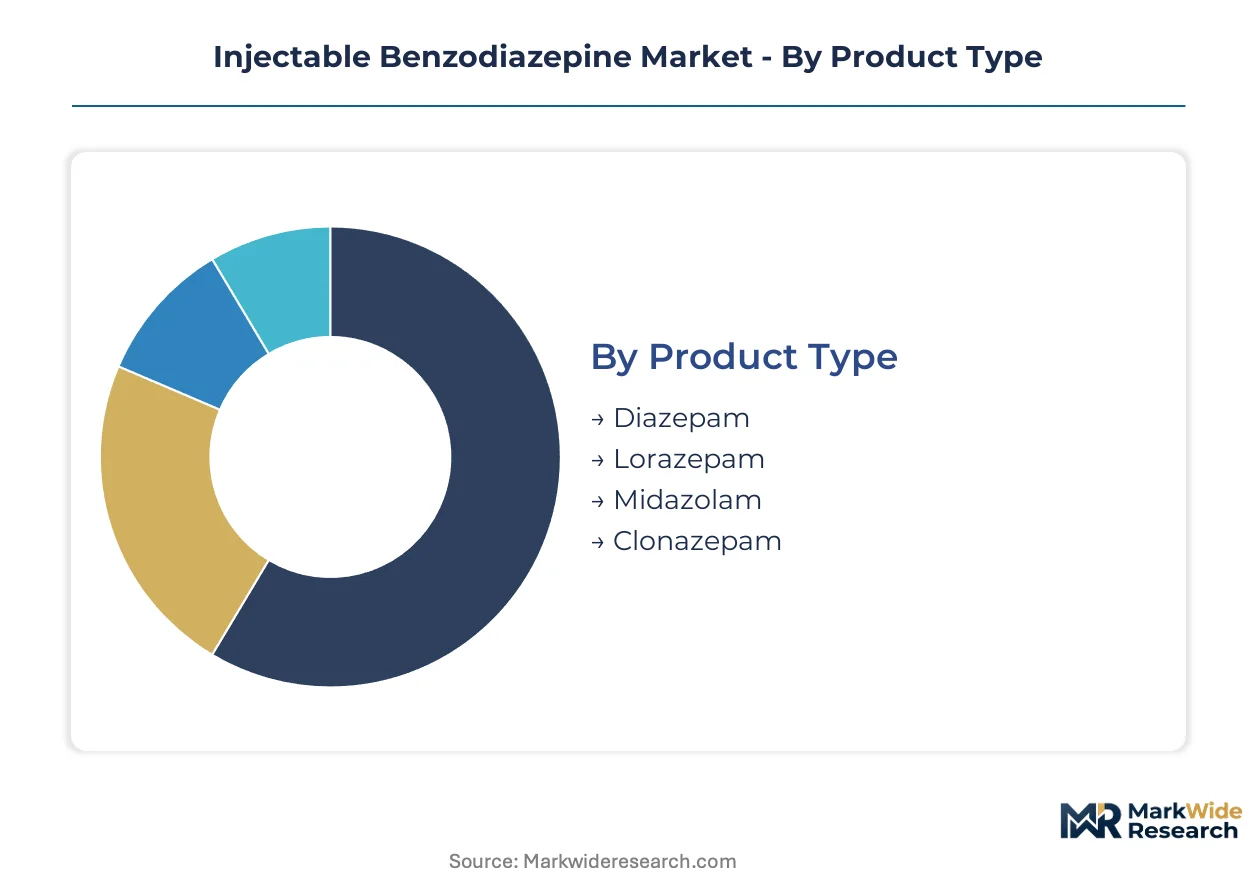
Injectable benzodiazepine procurement patterns diverge sharply across clinical settings and molecular specifications. Hospital formulary committees weight pharmacokinetic profiles against controlled substance handling costs when segmenting purchasing decisions.
Product Type:
Molecular stability and onset characteristics define competitive positioning across the four active pharmaceutical ingredients.
- Midazolam:Aqueous formulations with rapid CNS penetration and short half-life dominate procedural sedation protocols. United States anesthesia departments standardize this agent for preoperative anxiolysis, though FDA labeling revisions for respiratory depression constrain dosing flexibility.
- Lorazepam:Propylene glycol-based solutions deliver extended duration of action ideal for emergency seizure termination. Hospital emergency departments in the United States favor this agent for reduced redosing frequency, though solvent-related adverse events drive reformulation investments.
- Diazepam:Lipid emulsion variants address propylene glycol toxicity concerns in high-dose protocols.
- Clonazepam:Niche applications in refractory seizure management sustain limited volume procurement.
Midazolam leads on scale; lorazepam leads on momentum.
Delivery Mode:
Route selection hinges on vascular access availability and onset urgency requirements across care settings.
- Intravenous:Direct vascular administration achieves peak plasma concentrations within minutes, making this route mandatory for status epilepticus protocols. United States critical care units drive volume concentration through standardized infusion pump compatibility requirements.
- Intramuscular:Depot absorption sust therapeutic levels when IV placement fails, preserving demand in battlefield medicine and rural ambulance services where vascular access delays threaten patient outcomes.
- Subcutaneous:Alternative parenteral access for patients with compromised peripheral veins.
- Epidural:Regional anesthesia applications in obstetric and perioperative settings.
Intravenous delivery anchors procurement volumes; intramuscular formulations expand most quickly into prehospital settings.
End User:
Facility type determines compliance infrastructure requirements and formulary standardization scope.
- Hospitals:Automated dispensing cabinet integration and multi-year group purchasing contracts consolidate procurement decisions. United States health system networks standardize across dozens of facilities, locking in volume commitments for sterile injectable manufacturers.
- Emergency Rooms:Rapid turnover and high-acuity presentations demand immediate availability of multiple benzodiazepine options.
- Clinics:Outpatient procedural sedation drives midazolam preference for short-duration interventions.
- Homecare Providers:Extended stability intramuscular formulations enable seizure rescue in residential settings.
Hospitals dominate absolute demand; emergency rooms show steepest expansion trajectory.
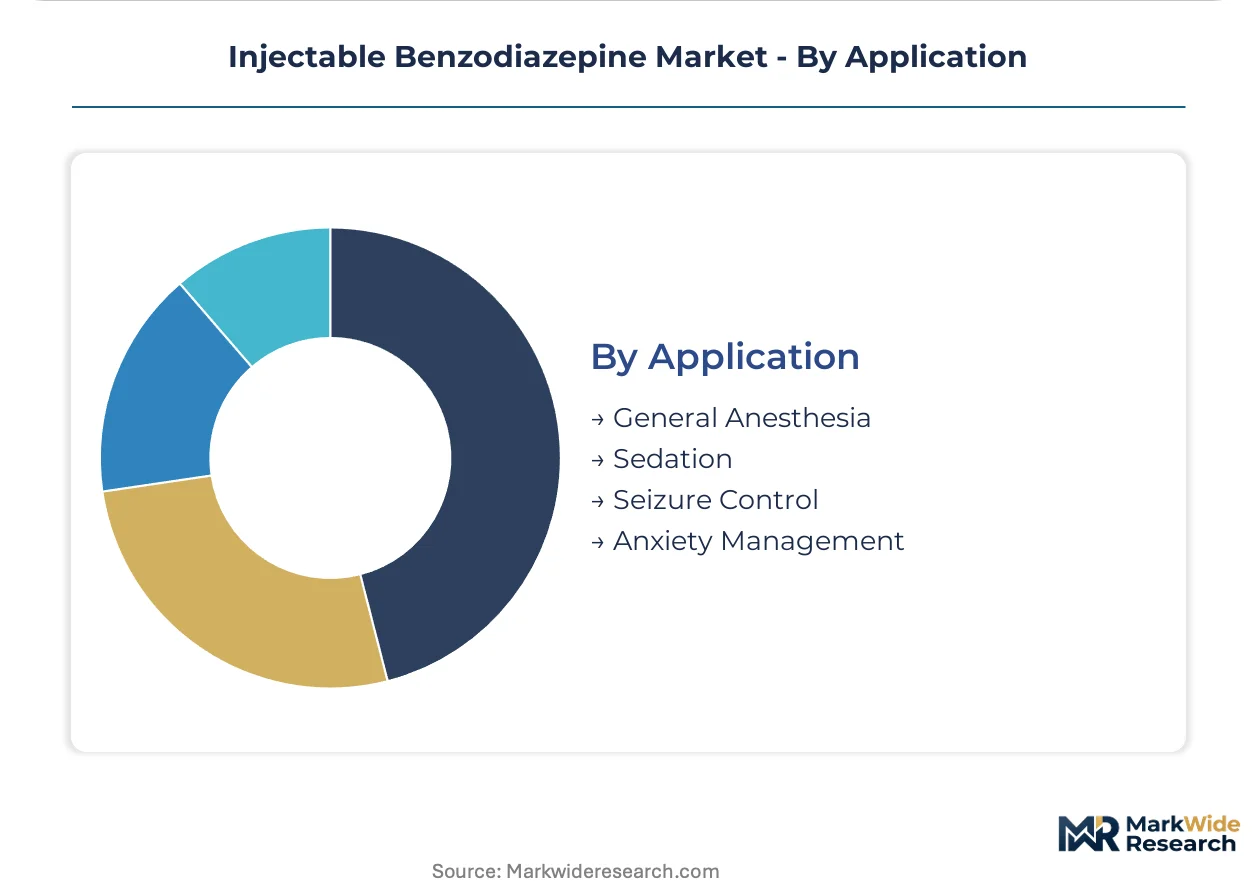
Application:
Clinical indication shapes dosing protocols and therapeutic index requirements.
- General Anesthesia:Adjunctive sedation alongside propofol or volatile agents requires precise titration capabilities. United States operating rooms prioritize midazolam for its predictable offset, though ketamine-sparing protocols threaten displacement.
- Seizure Control:First-line status epilepticus management demands agents with established IV efficacy and minimal respiratory compromise.
- Sedation:Procedural and ICU applications favor short-acting agents with rapid clearance.
- Anxiety Management:Preoperative and acute agitation protocols sustain lorazepam utilization.
General anesthesia commands premium positioning; seizure control applications gain share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The injectable benzodiazepine industry traces its commercial roots to mid-20th century European pharmaceutical innovation, with Swiss and German laboratories pioneering the first parenteral formulations for surgical sedation before scaling across North American hospital systems.
United States
FDA anesthesia protocol standardization and emergency department seizure management guidelines drive institutional procurement of intravenous midazolam and lorazepam. The DEA's Schedule IV controlled substance scheduling constrains distribution logistics while mandating specialized warehousing. The Philadelphia-Camden corridor hosts sterile injectable manufacturing clusters where Pfizer maintains fill-finish capacity for hospital network contracts.
Germany
EMA pharmacovigilance obligations under the Medical Device Regulation tighten post-market surveillance for combination products with automated delivery systems. The country's national pharmaceutical regulator enforces batch release testing that exceeds minimum EU requirements. The Rhine-Main region around Frankfurt concentrates contract manufacturing organizations serving Middle Eastern export markets with extended-stability formulations.
Switzerland
Swissmedic's stringent GMP inspections and therapeutic goods certification create competitive differentiation for manufacturers targeting premium hospital tenders. The country's central bank stability supports long-term procurement contracts denominated in Swiss francs. Basel's pharmaceutical cluster anchors formulation R&D for lipid emulsion diazepam variants addressing propylene glycol toxicity concerns.
United Kingdom
NHS England's national procurement frameworks consolidate purchasing decisions across hospital trusts, favoring suppliers with multi-source lorazepam availability. The Medicines and Healthcare products Regulatory Agency updated benzodiazepine labeling requirements following FDA risk evaluation templates. The M62 corridor between Manchester and Leeds hosts distribution hubs serving emergency medicine networks with rapid replenishment capabilities.
India
CDSCO manufacturing license requirements and export-oriented unit status attract contract development organizations serving regulated markets with cost-competitive API sourcing. The country's national pharmaceutical regulator harmonizes inspection protocols with WHO prequalification standards. Hyderabad's Genome Valley cluster specializes in sterile injectable capacity for lorazepam vials destined for African and Southeast Asian tenders.
Injectable Benzodiazepine Market Competitive Environment
The competitive structure tilts toward diversified pharmaceutical conglomerates with captive sterile infrastructure. Three manufacturer archetypes dominate: established injectable specialists with North American distribution networks, European contract manufacturers leveraging EMA documentation depth, and emerging market API-integrated suppliers competing on cost position. Consolidation through group purchasing organization contracts and automated dispensing cabinet bundling represents the primary competitive dynamic, while reformulation investments in lipid-based stability systems constitute the secondary vector.
Among diversified pharmaceutical conglomerates, Pfizer and Teva Pharmaceutical Industries Ltd. exemplify the scale-driven archetype with institutional formulary penetration across United States health systems. Hikma Pharmaceuticals occupies a position within the geographic-specialist tier, anchoring Middle Eastern and European hospital tender participation through regional regulatory alignment. These three entities represent contrasting strategic postures—North American volume concentration, multi-source generic manufacturing scale, and emerging market geographic dominance—without implying specific market share positions or operational priorities.
| Leading Market Players |
|---|
| Pfizer |
| F. Hoffmann-La Roche AG |
| Teva Pharmaceutical Industries Ltd. |
| Hikma Pharmaceuticals |
| Bausch Health Companies Inc. |
| NATCO Pharma |
| AdvaCare Pharma |
| Hameln Pharma |
| Accord Healthcare |
| Others |
Value Chain & Pricing Dynamics
Captive sterile manufacturing infrastructure anchors pricing power for established injectable specialists, creating a structural moat that insulates premium formulations from commodity erosion while forcing mid-tier competitors toward contract manufacturing arrangements. This integration choice concentrates margin capture in manufacturers with FDA-audited fill-finish lines and DEA-licensed warehousing, leaving price-sensitive procurement to group purchasing organization tenders for multi-source lorazepam vials.
Pricing Analysis
Contract-based long-term offtake agreements dominate hospital procurement, with pricing stratifying across lipid emulsion premium tiers, standard aqueous formulations, and economy-grade multi-source generics. Price differentiation hinges on FDA compliance tier and sterile certification grade, with propylene glycol-free formulations commanding substantial premiums. Cost compression in standard aqueous solutions is intensifying because of raw material volatility and GPO consolidation, while emergency departments show least price sensitivity due to protocol standardization imperatives.
Supply Chain Analysis
Propylene glycol supply rests on concentrated petrochemical producers in the United States and Western Europe, with benzodiazepine API synthesis anchored in India and China. Formulation dependence on DEA-controlled precursor chemicals and specialized parenteral solvents creates single-source vulnerability for institutional buyers. Distribution runs through cold-chain logistics networks serving hospital systems and emergency medicine networks, with automated dispensing cabinet integration consolidating downstream channel control.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The injectable benzodiazepine market compounds steadily through emergency medicine protocol standardization that locks in recurring institutional demand regardless of economic cycles.
For Market Incumbents: Cement formulary position through prefilled syringe bundling with automated dispensing cabinets, reducing pharmacy director switching costs while building multi-year procurement lock-in. Deepen backward integration into propylene glycol alternatives to defend margin position against solvent cost volatility and FDA reformulation pressures. For New Entrants and Emerging Players: FDA updated benzodiazepine labeling guidance in the United States opens a window for lipid emulsion specialists to capture premium positioning in high-dose sedation protocols. Target underserved rural ambulance services and battlefield medicine procurement channels with extended-stability intramuscular formulations, leveraging intramuscular delivery mode growth as the go-to-market angle. For Investors and Strategic Acquirers: Consolidation pressure builds where sterile manufacturing capacity scarcity meets escalating REMS compliance costs. The 5-10 year viability window favors acquisition targets with captive aseptic fill-finish infrastructure and established DEA controlled substance licensing. Watch FDA benzodiazepine-sparing anesthesia protocol guidance as the inflection indicator for demand displacement risk.| Strategic Initiative | Industry Significance |
|---|---|
| REMS Compliance Infrastructure Investment | Establishes barrier to entry against non-specialized competitors under FDA enforcement. |
| Lipid Emulsion Formulation Development | Captures premium hospital procurement addressing propylene glycol toxicity concerns. |
| Automated Dispensing Cabinet Partnership | Locks in multi-year formulary commitments through pharmacy director consolidation. |
| Prehospital Intramuscular Expansion | Accesses white-space demand in battlefield medicine and rural ambulance services. |
| EMA Pharmacovigilance Alignment | Differentiates documentation depth for European hospital tender participation. |
Study Parameters
Direct dialogue with hospital pharmacy directors, emergency medicine clinicians, sterile manufacturing executives, regulatory affairs specialists, and group purchasing organization contract managers grounded qualitative insights. Secondary validation drew from FDA Orange Book filings, DEA controlled substance manufacturing quotas, EMA pharmacovigilance databases, and hospital procurement contract registries. Bottom-up volume estimates triangulated against top-down market sizing across molecular type, delivery mode, and end-user facility tier.
Bottom-up modeling aggregated institutional procurement volumes by hospital system network and emergency department protocol standardization, while top-down analysis tracked sterile injectable industry shipments and controlled substance distribution reports. Segmentation dimensions spanned active pharmaceutical ingredient, parenteral delivery route, clinical application, and regional regulatory cluster. CAGRs derived from historical volume trajectories adjusted for protocol adoption curves and reformulation investment cycles.
Forecast precision tightens around the base case; tail outcomes carry wider variance under DEA scheduling reclassification or breakthrough non-benzodiazepine sedation agent approval. Forecasts reflect documented assumptions regarding emergency medicine protocol persistence and sterile manufacturing capacity expansion. A small set of named triggers—FDA benzodiazepine-sparing guidance, propylene glycol supply disruption, and state-level prescription drug monitoring program integration—warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pharmaceuticals
Ampicillin Drugs Market
Pharmaceuticals
Naproxen Market
Pharmaceuticals
Granulocyte Macrophage Colony Stimulating Factor Market
Pharmaceuticals
Global RFID in Pharmaceuticals Market
Pharmaceuticals
Europe Sodium-Dependent Glucose Cotransporter 2 Market
Pharmaceuticals
Hydroxyzine Market
Pharmaceuticals
Marburg Virus Disease Therapeutics Market
Pharmaceuticals
Trenbolone Acetate Market
Pharmaceuticals
Netherlands Pharmaceutical Market
Pharmaceuticals
Dipeptide Peptidase 4 Inhibitors Market
Pharmaceuticals
Pharmacy and Drug Store Franchises Market
Pharmaceuticals
Global Lyophilized Injectable Drugs Market
Pharmaceuticals
Drug Delivery Market
Pharmaceuticals
Europe Small Molecule Sterile Injectable Drugs Market
Pharmaceuticals
Global Antacids Market
Pharmaceuticals
Pancrelipase Market