
 Asia-Pacific Silica Sand Market | 2026-2036
Asia-Pacific Silica Sand Market Size, Share, and Industry Trends Forecast 2026-2036
Asia-Pacific Silica Sand Market Insights
Advanced beneficiation and precision grading technology is rewriting silica sand processing economics across the Asia-Pacific. Sibelco leverages its integrated logistics network to supply foundry-grade material to automotive casting operations in Thailand and Vietnam. JFE Mineral & Alloy Company Ltd anchors Japanese supply chains with high-purity output for semiconductor and optical glass applications. TOCHU Corporation dominates specialized frac sand distribution to Australian unconventional gas projects.
Silica sand consists primarily of silicon dioxide in granular form, typically requiring minimum SiO₂ content of 95% for industrial use and exceeding 99.5% for optical and solar glass manufacturing through washing, attrition scrubbing, and magnetic separation processes. Glass Sand commands the largest value share as photovoltaic panel and container glass manufacturers in China and India scale float and rolled glass capacity. Foundry Sand generates stable offtake from automotive and machinery casting clusters but faces margin pressure from synthetic substitute competition. Hydraulic Fracturing Sand remains concentrated in Australian shale basins where basin-specific proppant specifications determine supplier selection.
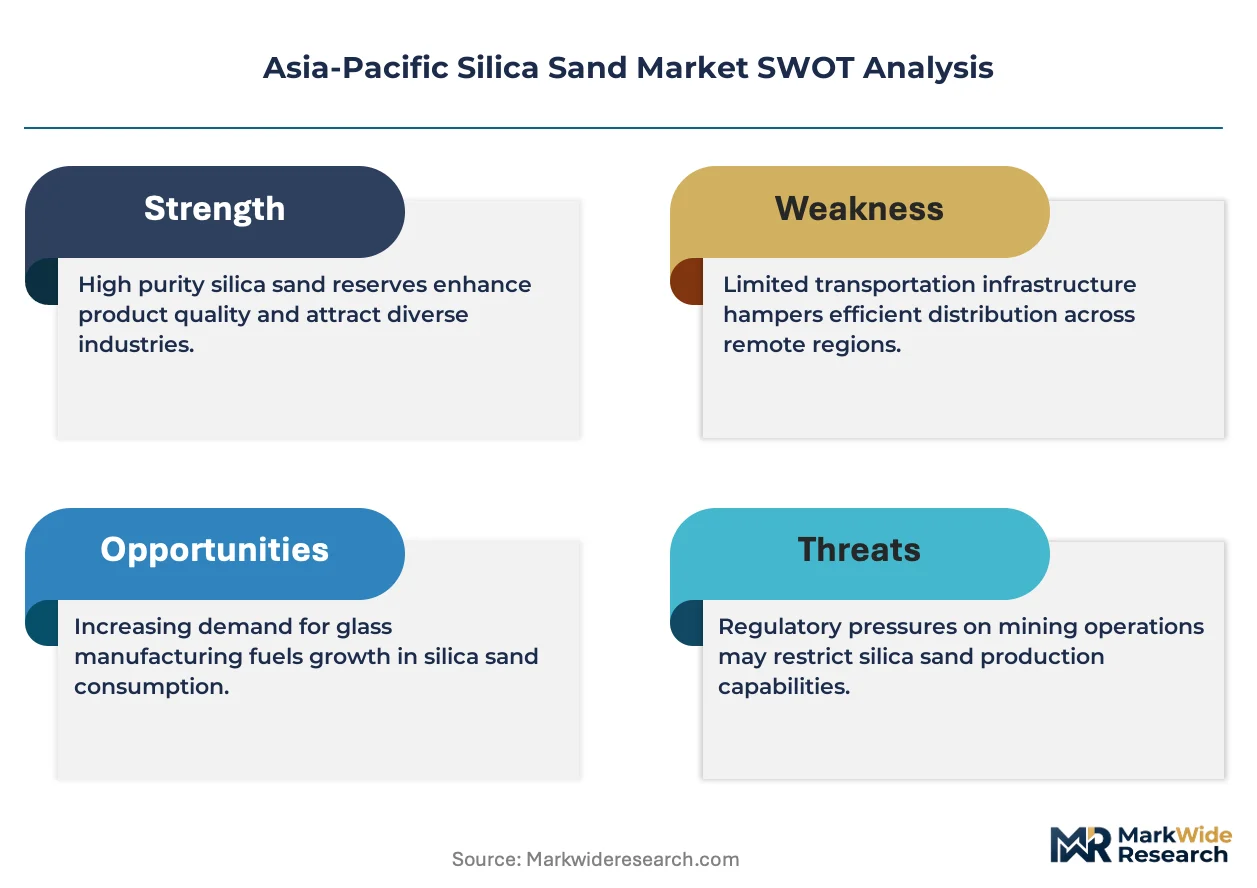
China's MEE enforces stricter quarry rehabilitation and water recycling mandates that raise compliance costs for domestic producers. India's BIS certification requirements for foundry and glass-grade silica sand create non-tariff barriers for unprocessed imports from Southeast Asia. Australia's state-level environmental regulators impose progressive rehabilitation bonds on Queensland and Western Australia extraction leases. Stakeholders must monitor evolving purity specifications from solar glass manufacturers and track permitting delays that could tighten regional supply ahead of capacity expansions.
Market Dynamics
China's MEE environmental permitting regime is compressing domestic supply capacity while solar glass manufacturers in Jiangsu and Shandong provinces demand ever-higher purity thresholds, creating a structural squeeze that rewards processors with advanced beneficiation capabilities.
Growth Catalysts
- Photovoltaic glass expansion:Float and rolled glass lines serving solar panel manufacturers in China and India are scaling capacity, pulling high-purity feedstock through dedicated offtake agreements.
- MEE water recycling mandates:Stricter quarry rehabilitation requirements under China's Ministry of Ecology and Environment are forcing consolidation toward operators with closed-loop processing systems.
- Foundry cluster concentration:Automotive casting operations in Thailand and Vietnam are absorbing foundry-grade material through integrated logistics networks serving just-in-time production schedules.
Market Restraints
- Energy cost volatility:Drying and thermal processing stages face margin pressure from natural gas and electricity price swings across Australian and Southeast Asian extraction sites.
- Synthetic substitute competition:Ceramic proppants and resin-coated sands are capturing share in hydraulic fracturing applications where crush resistance specifications permit alternative materials.
- BIS certification friction:India's Bureau of Indian Standards requirements for foundry and glass-grade material create non-tariff barriers blocking unprocessed imports from Indonesian and Malaysian sources.
Strategic Opportunities
- Semiconductor-grade purification:Ultra-high-purity processing for optical and solar glass applications commands premium pricing as Japanese and South Korean electronics manufacturers diversify supply sources.
- Western Australia shale basins:Basin-specific proppant specifications in Queensland and Western Australia create niche demand for precisely graded frac sand with documented crush-test performance.
- Backward integration by glassmakers:Container and solar glass producers are acquiring captive sand reserves to secure quality consistency and hedge against MEE-driven supply interruptions.
Industry Challenges
- Attrition scrubbing expertise shortage:Qualified technicians capable of optimizing particle surface cleaning and iron oxide reduction are concentrated among a handful of engineering consultancies.
- Magnetic separation capex intensity:High-gradient magnetic separators capable of achieving 99.5% SiO₂ purity require substantial capital deployment with extended commissioning timelines.
- Rehabilitation bond liquidity:Australian state regulators demand progressive financial assurance instruments that strain balance sheets for mid-scale Queensland and Western Australia leaseholders.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Asia-Pacific Silica Sand Market |
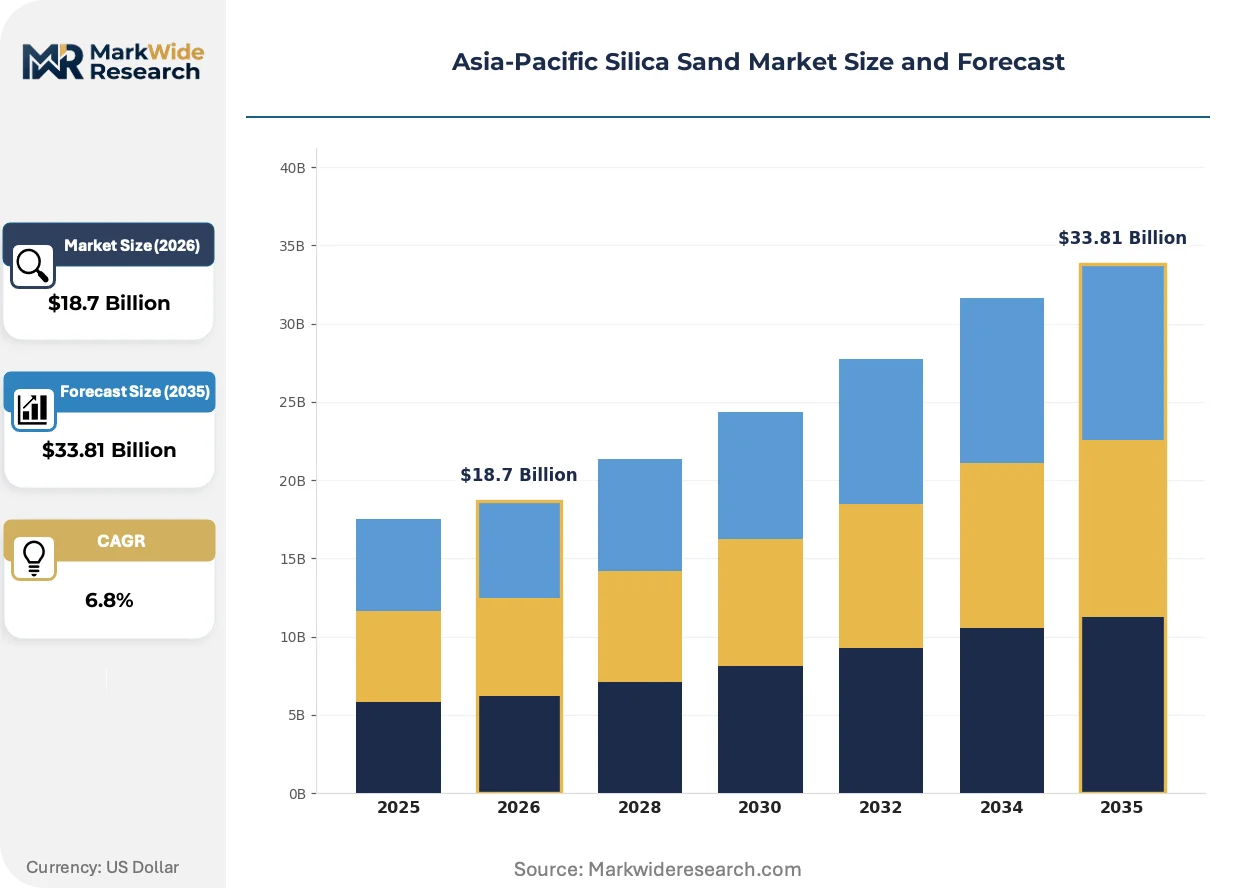
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $33.81 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Glass Sand, Foundry Sand, Hydraulic Fracturing Sand, Industrial Sand Application: Construction, Glass Manufacturing, Oil & Gas, Water Filtration End User: Construction Companies, Glass Manufacturers, Hydraulic Fracturing Firms, Water Treatment Facilities Distribution Channel: Direct Sales, Distributors, Online Retailers, Industrial Suppliers |
| Companies Covered | Sibelco, Chongqing Changjiang River Moulding Material Group Co. Ltd, JFE Mineral & Alloy Company Ltd, PUM Group, Mitsubishi Corporation, TOCHU Corporation, VRX Silica Ltd, Mangal Minerals, Raghav Productivity Enhancers Limited, Others |
| Regions Covered | Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Asia-Pacific Silica Sand Market Trends and Innovations
Processing technology convergence and regulatory stringency are compressing the viable supplier base while opening premium tiers for purity-certified material. Three developments are restructuring competitive economics.
Dry classification systems incorporating air separation and electrostatic beneficiation are collapsing the cost differential between wet and dry processing routes for foundry-grade material. Australian unconventional gas operators are adopting these systems to reduce water consumption in arid extraction regions. The technology is collapsing capital requirements for mid-scale entrants previously excluded by infrastructure-intensive wet plant investments.
China's GB standards for industrial minerals are tightening impurity thresholds for iron, chromium, and titanium oxides in glass-grade silica sand. The standards are forcing processors to retrofit magnetic separation and acid leaching circuits or exit the premium tier. Solar glass manufacturers in eastern China are responding by consolidating supplier panels toward integrated operators with certified quality management systems.
Long-term offtake contracting is displacing spot market transactions as solar glass producers seek supply security amid MEE permitting uncertainty. Glass manufacturers are locking in multi-year agreements with processors demonstrating compliant water recycling and rehabilitation performance. This pattern is most visible in Jiangsu province where photovoltaic panel foundries are vertically integrating into sand processing through equity stakes and dedicated supply arrangements.
Asia-Pacific Silica Sand Market Segmentation
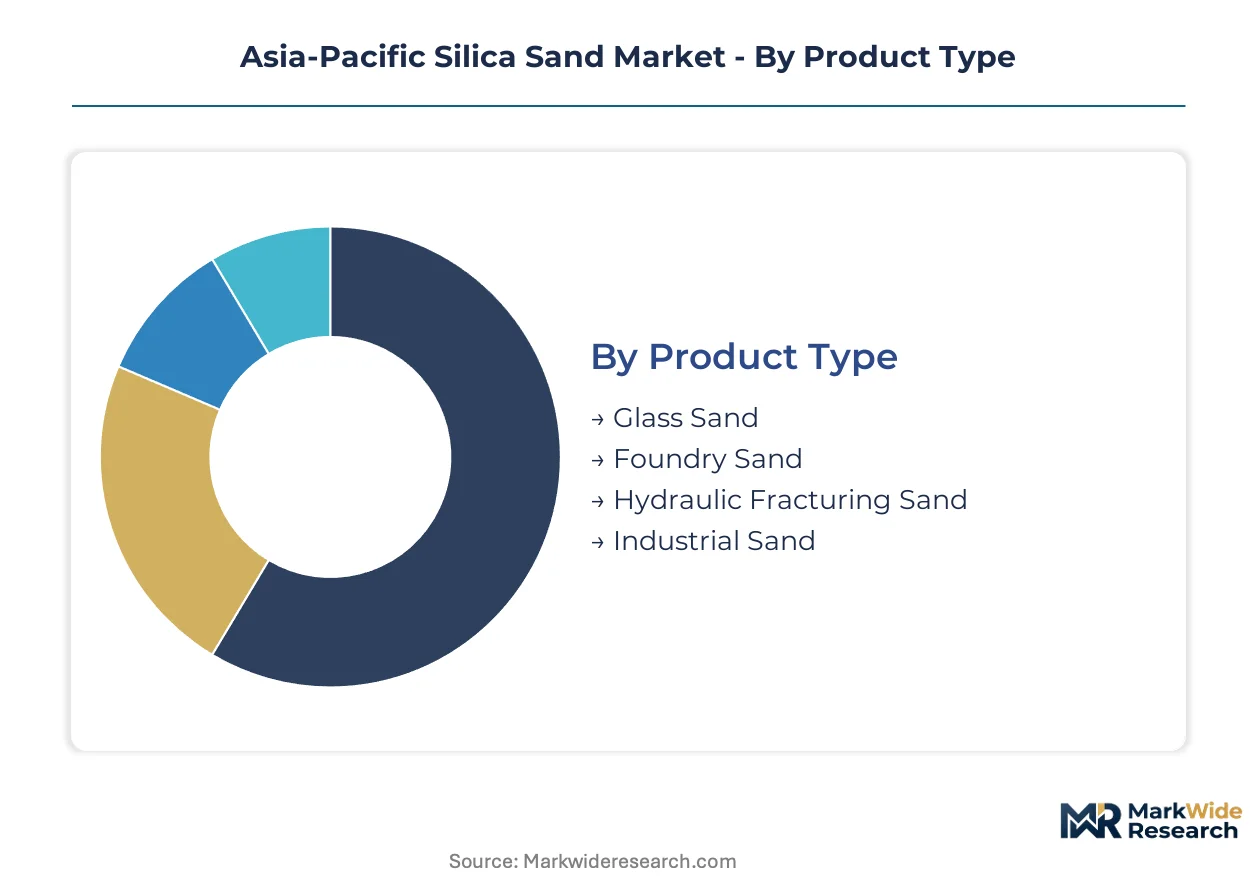
Silica sand grades vary dramatically in purity thresholds and processing intensity across the Asia-Pacific. End-use specifications dictate beneficiation investments, while distribution economics separate commodity flows from premium certified material.
Product Type:
Mature industrial grades coexist with emerging ultra-purity segments demanding specialized magnetic separation infrastructure.
- Glass Sand:Requires minimum 99.5% SiO₂ content achieved through acid leaching and high-gradient magnetic separation. Float glass manufacturers in Jiangsu province lock in multi-year offtake agreements to secure consistency against MEE permitting volatility.
- Foundry Sand:Grain shape and thermal stability determine suitability for automotive casting operations. Thai and Vietnamese foundry clusters absorb material through integrated logistics networks serving just-in-time production schedules.
- Hydraulic Fracturing Sand:Crush resistance and sphericity specifications dominate Australian shale basin procurement.
- Industrial Sand:Lower-purity grades serve construction and chemical applications with minimal processing.
Glass Sand retains volume leadership; Hydraulic Fracturing Sand holds the steepest expansion curve.
Application:
Cost tiers separate commodity construction material from precision-grade optical and solar applications commanding premium certification.
- Glass Manufacturing:Photovoltaic panel producers in eastern China drive specification tightening for iron oxide and chromium content. Rolled glass lines serving solar manufacturers scale capacity through dedicated feedstock agreements with processors demonstrating closed-loop water systems.
- Construction:Concrete and mortar applications absorb lower-grade material with minimal beneficiation. Urban infrastructure projects in India and Southeast Asia pull steady volume through distributor networks.
- Oil & Gas:Australian unconventional gas operators specify precisely graded proppant with documented crush-test performance.
- Water Filtration:Grain size uniformity and acid solubility standards govern municipal and industrial treatment facility procurement.
Glass Manufacturing commands the highest margin tier; Water Filtration is climbing fastest on infrastructure investment cycles.
End User:
Customer type determines contract structure, with captive integration favored by volume consumers and spot markets serving fragmented buyers.
- Glass Manufacturers:Container and solar glass producers are acquiring captive sand reserves to hedge against MEE-driven supply interruptions. Quality consistency requirements favor backward integration over merchant supply.
- Construction Companies:Price-sensitive procurement through industrial suppliers dominates residential and commercial building segments.
- Hydraulic Fracturing Firms:Basin-specific proppant specifications in Queensland and Western Australia create niche demand for documented performance material.
- Water Treatment Facilities:Municipal procurement cycles and certification requirements structure long-term supply relationships.
Glass Manufacturers anchor premium demand; Hydraulic Fracturing Firms are expanding offtake most rapidly.
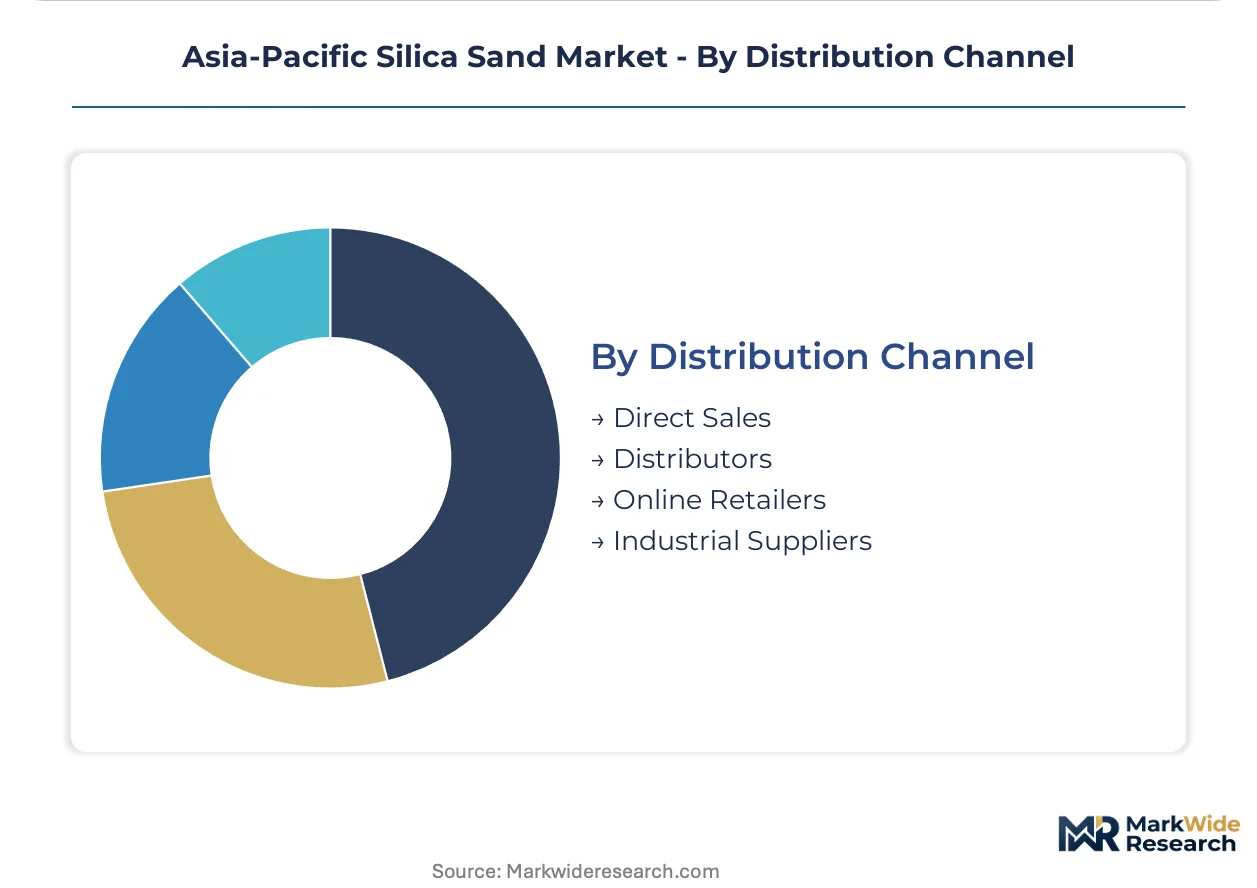
Distribution Channel:
Supply concentration in eastern China and Queensland shapes logistics economics across channel types.
- Direct Sales:Large-volume glass and foundry consumers negotiate dedicated supply agreements with processors. Contract terms increasingly incorporate water recycling compliance and rehabilitation performance guarantees.
- Distributors:Regional stocking points serve mid-scale construction and industrial customers with fragmented demand patterns.
- Industrial Suppliers:Integrated material merchants bundle silica sand with complementary construction and foundry inputs.
- Online Retailers:Emerging channel for standardized grades and small-lot procurement by specialty fabricators.
Direct Sales retains the dominant share; Online Retailers are gaining traction fastest among specialty buyers.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Glass manufacturers and foundry operators across the Asia-Pacific concentrate procurement power through dedicated offtake agreements, while environmental regulators in China and Australia reshape extraction economics.
China
Photovoltaic panel foundries in Jiangsu and Shandong provinces drive demand for 99.5% SiO₂ glass sand through multi-year supply contracts. MEE water recycling mandates and quarry rehabilitation requirements under GB standards are forcing consolidation toward processors with closed-loop systems. Eastern China's industrial clusters now favor integrated operators with certified quality management over merchant suppliers.
Australia
Unconventional gas operators in Queensland and Western Australia specify precisely graded frac sand with documented crush-test performance for shale basin applications. State-level environmental regulators impose progressive rehabilitation bonds on extraction leases, straining balance sheets for mid-scale leaseholders. Basin-specific proppant procurement patterns concentrate supply relationships around documented performance material.
India
Container glass and foundry casting operations absorb steady volumes of beneficiated sand through distributor networks serving fragmented industrial demand. BIS certification requirements for foundry and glass-grade material create non-tariff barriers blocking unprocessed imports from Southeast Asian sources. Western and southern industrial corridors concentrate procurement through regional stocking points.
Japan
Semiconductor and optical glass applications command ultra-high-purity processing premiums as electronics manufacturers diversify supply sources. METI industrial mineral policies support domestic beneficiation capacity for critical material security. Japanese supply chains anchor on processors capable of achieving sub-50ppm iron oxide content for specialty applications.
Vietnam and Thailand
Automotive casting clusters absorb foundry-grade material through integrated logistics networks serving just-in-time production schedules. Thai and Vietnamese foundry operators prioritize grain shape and thermal stability specifications for machinery and vehicle component manufacturing. Southeast Asian procurement patterns favor regional processors with dedicated distribution infrastructure over distant suppliers.
Asia-Pacific Silica Sand Market Competitive Landscape
Channel-controlling players compete with product-specialist players across tiered market segments. The supplier base concentrates around integrated mineral processors with captive logistics networks and specialized beneficiation operators serving purity-critical applications. Three archetypes dominate: diversified industrial mineral conglomerates with regional distribution infrastructure, precision beneficiation specialists serving semiconductor and optical glass tiers, and basin-focused frac sand processors with documented crush-test capabilities. Competitive moves center on backward integration into captive sand reserves and multi-year offtake contracting to secure volume commitments.
Within the diversified industrial mineral tier, Sibelco exemplifies channel control through integrated logistics networks spanning Southeast Asian foundry markets. JFE Mineral & Alloy Company Ltd occupies a position among precision beneficiation specialists serving Japanese semiconductor and optical glass supply chains. TOCHU Corporation represents basin-specific frac sand distribution expertise focused on Australian unconventional gas project requirements.
| Leading Market Players |
|---|
| Sibelco |
| Chongqing Changjiang River Moulding Material Group Co. Ltd |
| JFE Mineral & Alloy Company Ltd |
| PUM Group |
| Mitsubishi Corporation |
| TOCHU Corporation |
| VRX Silica Ltd |
| Mangal Minerals |
| Raghav Productivity Enhancers Limited |
| Others |
Pricing and Supply Chain Analysis
Overcapacity in lower-grade foundry sand across Vietnam and Thailand is compressing spot-market realizations while simultaneously pushing processors toward long-term offtake structures with glass manufacturers in eastern China. This utilization divergence rewards operators with closed-loop beneficiation systems capable of meeting MEE-mandated purity thresholds.
Pricing Analysis
Cost-plus contracts indexed to natural gas and electricity benchmarks dominate procurement between Jiangsu solar glass manufacturers and integrated sand processors. Three-tier pricing structure across premium, standard, and economy levels separates acid-leached 99.5% SiO₂ glass sand from attrition-scrubbed foundry grades and minimally processed construction material. Pricing pressure stems from energy cost volatility in Australian thermal processing operations. Construction sector buyers exhibit highest price sensitivity; semiconductor-grade purchasers accept substantial premiums for documented sub-50ppm iron oxide certification.
Supply Chain Analysis
Contract manufacturing concentration rests with Sibelco's integrated Southeast Asian logistics network, JFE Mineral's Japanese beneficiation facilities, and TOCHU Corporation's Australian frac sand distribution infrastructure. Geographic supply concentrates in China, Australia, and Vietnam. Raw material dependencies center on high-purity silica deposits, magnetic separation reagents, and acid leaching chemicals. Single-source vulnerability runs through Queensland and Western Australia extraction leases subject to progressive rehabilitation bond requirements. Distribution runs through direct sales agreements with volume glass and foundry consumers, supplemented by regional distributors serving fragmented construction demand.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Asia-Pacific silica sand markets are entering a high-growth disruption as MEE environmental mandates force consolidation toward processors with certified closed-loop systems. This regulatory inflection elevates capital requirements while opening premium tiers for purity-certified material.
For Market Incumbents: Entrench market position through backward integration into captive sand reserves in Jiangsu and Shandong provinces, securing feedstock consistency against MEE-driven supply interruptions. Invest in high-gradient magnetic separation infrastructure to meet tightening GB standards for iron oxide content. Synthetic substitute competition in hydraulic fracturing applications demands documented crush-test performance to defend frac sand margins. For New Entrants and Emerging Players: Mid-scale dry classification systems serving Australian unconventional gas operators represent the most penetrable entry point, collapsing capital barriers previously excluding wet plant investments. Target foundry-grade supply to Thai and Vietnamese automotive casting clusters through integrated logistics partnerships. Go-to-market leverage rests on air separation technology reducing water consumption in arid extraction regions. For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting upward across semiconductor-grade purification segments as Japanese and South Korean electronics manufacturers diversify supply sources. Long-term viability favors precision beneficiation specialists with demonstrated sub-50ppm iron oxide capability over commodity construction-grade processors. Monitor MEE permitting delays and rehabilitation bond liquidity stress among Queensland mid-scale leaseholders as inflection signals for consolidation timing.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Captive Reserves | Glass manufacturers in Jiangsu province secure supply consistency against MEE permitting volatility. |
| High-Gradient Magnetic Separation Deployment | Processors achieve 99.5% SiO₂ purity thresholds demanded by solar panel foundries. |
| Long-Term Offtake Contracting | Multi-year agreements displace spot transactions amid water recycling compliance requirements. |
| Dry Classification System Adoption | Australian gas operators reduce water consumption while collapsing capital requirements for mid-scale entrants. |
| Rehabilitation Bond Financial Structuring | Queensland leaseholders manage progressive assurance instruments straining balance sheets. |
Research Methodology
A standing panel of quarry operations managers, glass manufacturer procurement directors, foundry supply chain leads, and environmental compliance officers provided ongoing calibration against secondary validation. Primary interviews combined with customs trade data, MEE permitting disclosures, BIS certification records, and SEC filings from listed industrial mineral processors enabled bottom-up and top-down triangulation.
Scenario-bracketing framed volume and value outputs across the analysis window, with segmentation modeled by product grade tier, end-use application, purity certification level, and regional production hub. CAGRs derived from installed capacity trajectories, offtake contract visibility, and regulatory compliance cost curves. Forecast inputs incorporated MEE water recycling mandate implementation timelines and solar glass capacity expansion announcements.
Macroeconomic conditions sit as an overlay; deviation in Chinese construction activity, Australian natural gas drilling rates, or Indian infrastructure investment cycles would shift the trajectory. Forecasts reflect assumptions regarding MEE enforcement consistency, BIS certification friction persistence, and rehabilitation bond policy stability. Quarterly review of permitting approval velocities, energy cost indices, and synthetic proppant substitution rates is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Glass
Recycled Glass Market
Glass
China Flat Glass Market
Glass
India Flat Glass Market
Glass
Middle-East and Africa Flat Glass Market
Glass
Glass Like Carbon Market
Glass
East Africa Flat Glass Market
Glass
Global Laminated Glass Market
Glass
North America and Australia Silica Market
Glass
North America Industrial Silica Sand Market
Glass
Decorative Glass Market
Glass
Spherical Silica Market
Glass
Tinted Glass Market
Glass
Optical Materials Market
Glass
3D Glass Market
Glass
United States Flat Glass Market
Glass
Glass Recycling Market