
 Optical Glass Market | 2026-2036
Optical Glass Market Size, Share, and Industry Trends Forecast 2026-2036
Optical Glass Market Analysis
The premium optical glass tier is consolidating around melt-controlled low-homogeneity formulations for extreme ultraviolet lithography, while commodity soda-lime and crown glass fragments across regional job shops. Schott AG anchors European supply through its proprietary fine annealing processes for astronomical mirror substrates. HOYA leverages vertical integration from raw material refining to polished lens elements for medical endoscopes. Corning Incorporated dominates high-transmission fused silica for semiconductor stepper optics through captive synthetic quartz production.
Optical glass refers to engineered silicate or non-silicate compositions manufactured with precise refractive index control, typically within ±0.0001 deviation, through continuous melting or pot melting followed by fine annealing to eliminate internal stress birefringence. Its primary purpose is transmitting, focusing, or filtering light across ultraviolet through infrared wavelengths in instruments requiring sub-wavelength surface figure accuracy. Planoconvex lenses and biconvex lenses carry mature margin pools in industrial machine vision and smartphone camera modules where volume scale offsets price erosion. Concave lenses and filters represent faster-growing value segments as augmented reality waveguides and lidar rangefinders impose narrowband coating requirements. Coating technology increasingly determines competitive positioning as ion-beam sputtered anti-reflective stacks extend transmission bandwidth beyond what substrate composition alone achieves.
EMA's Medical Device Regulation and FDA's Quality System Regulation impose biocompatibility and traceability requirements on optical glass destined for surgical instruments and diagnostic imaging, elevating documentation costs for non-specialized suppliers. REACH restrictions on lead and cadmium in optical formulations force reformulation of traditional dense flint glasses toward lanthanum-substituted alternatives. China's SAMR enforces GB standards for optical uniformity that exclude uncertified foundries from defense and aerospace procurement. Stakeholders must monitor how EU Green Deal carbon border adjustments reshape cost structures for energy-intensive melting operations before committing to capacity expansion decisions.
Market Dynamics
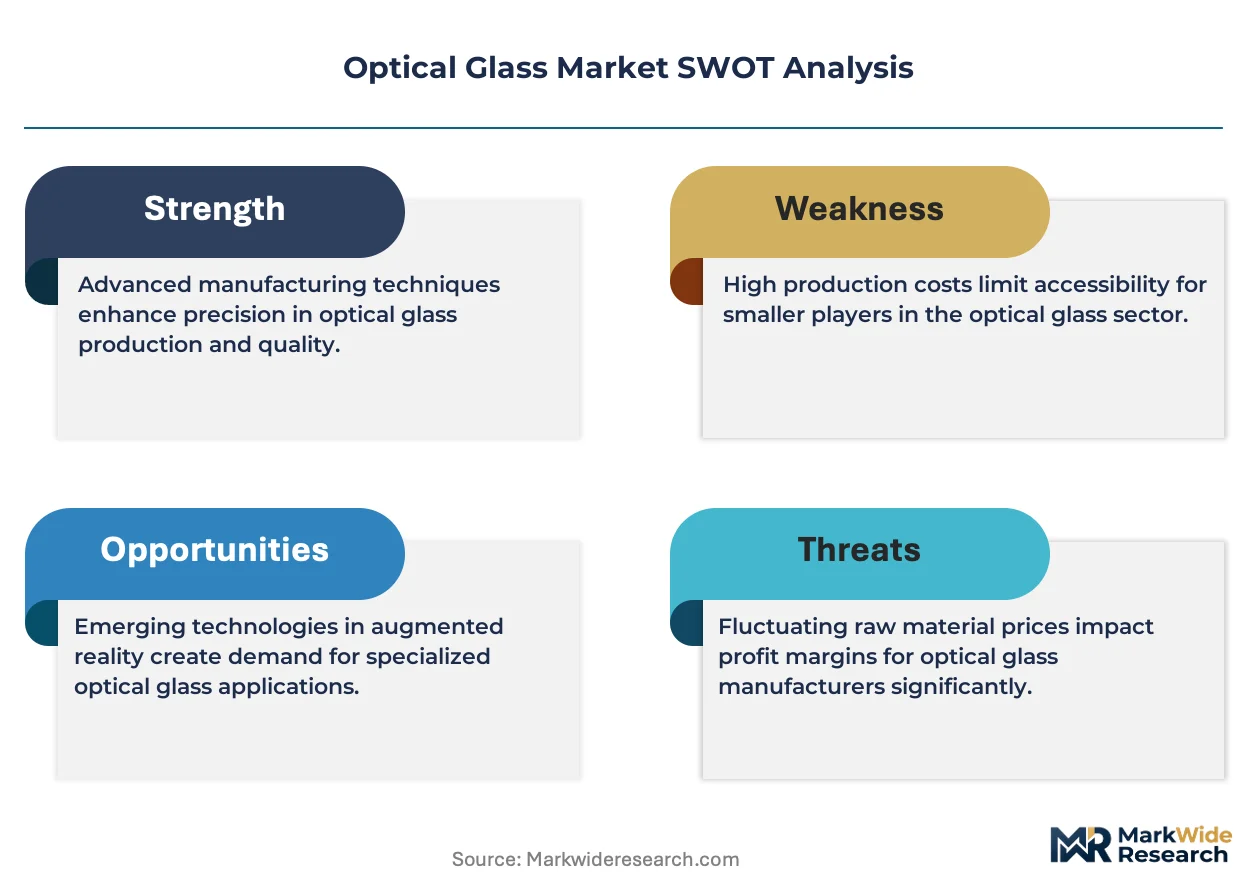
Extreme ultraviolet lithography systems from ASML and Nikon are forcing melt-controlled low-homogeneity formulations into the premium tier, while China's dual carbon goals tighten emissions standards on energy-intensive melting furnaces. This dual pressure is compressing margins for commodity producers while rewarding certified precision suppliers.
Growth Catalysts
- Semiconductor lithography expansion:Sub-wavelength patterning requirements in EUV systems pull demand for synthetic fused silica with sub-ppm impurity levels. Foundries in Taiwan and South Korea anchor this procurement.
- EU Green Deal carbon border adjustments:CBAM implementation is redirecting optical glass sourcing toward low-carbon melting operations. German and French suppliers with renewable-powered furnaces capture preferential placement.
- Medical endoscope miniaturization:Disposable flexible endoscopes require ultra-thin rod lenses with biocompatibility certification. FDA Quality System Regulation compliance opens procurement to qualified Asian manufacturers.
Market Restraints
- Energy cost volatility:Natural gas and electricity price spikes in Germany and Japan directly impact continuous melting furnace economics. Energy now represents 35-45% of production cost at Mainz and Osaka facilities.
- Raw material concentration:High-purity lanthanum oxide and tantalum pentoxide supply concentrates in Chinese refining operations. Non-Chinese formulators face input security risks.
- REACH substitution mandates:Lead and cadmium restrictions in traditional dense flint glasses force reformulation cycles. Lanthanum-substituted alternatives require 18-24 month qualification timelines.
Strategic Opportunities
- India defense procurement:India's BIS optical uniformity standards for thermal imaging and laser designation systems exclude uncertified foundries. Domestic qualification creates protected volume for early entrants.
- AR waveguide coating integration:Ion-beam sputtered narrowband filters on molded glass substrates enable lighter augmented reality headsets. Meta and Apple supply chains are qualifying dual-capability suppliers.
- Japan METI semiconductor materials initiative:Subsidies for domestic EUV-grade synthetic quartz production reduce import dependency. Local partners gain preferred access to Nikon lithography supply chains.
Industry Challenges
- Fine annealing specialist scarcity:Stress-birefringence elimination to sub-5 nm/cm levels requires decades of craft knowledge. Retirement waves at Schott AG and HOYA threaten process continuity.
- Multi-standard certification burden:Simultaneous EMA Medical Device Regulation, FDA 21 CFR Part 820, and China NMPA registration for surgical optics extends commercialization timelines to 36-48 months.
- Legacy furnace reconfiguration:Converting coal-fired pot melting to electric or hydrogen-powered continuous melting requires $15-25 million per line. Smaller Czech and Polish job shops lack balance sheet capacity.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Optical Glass Market |
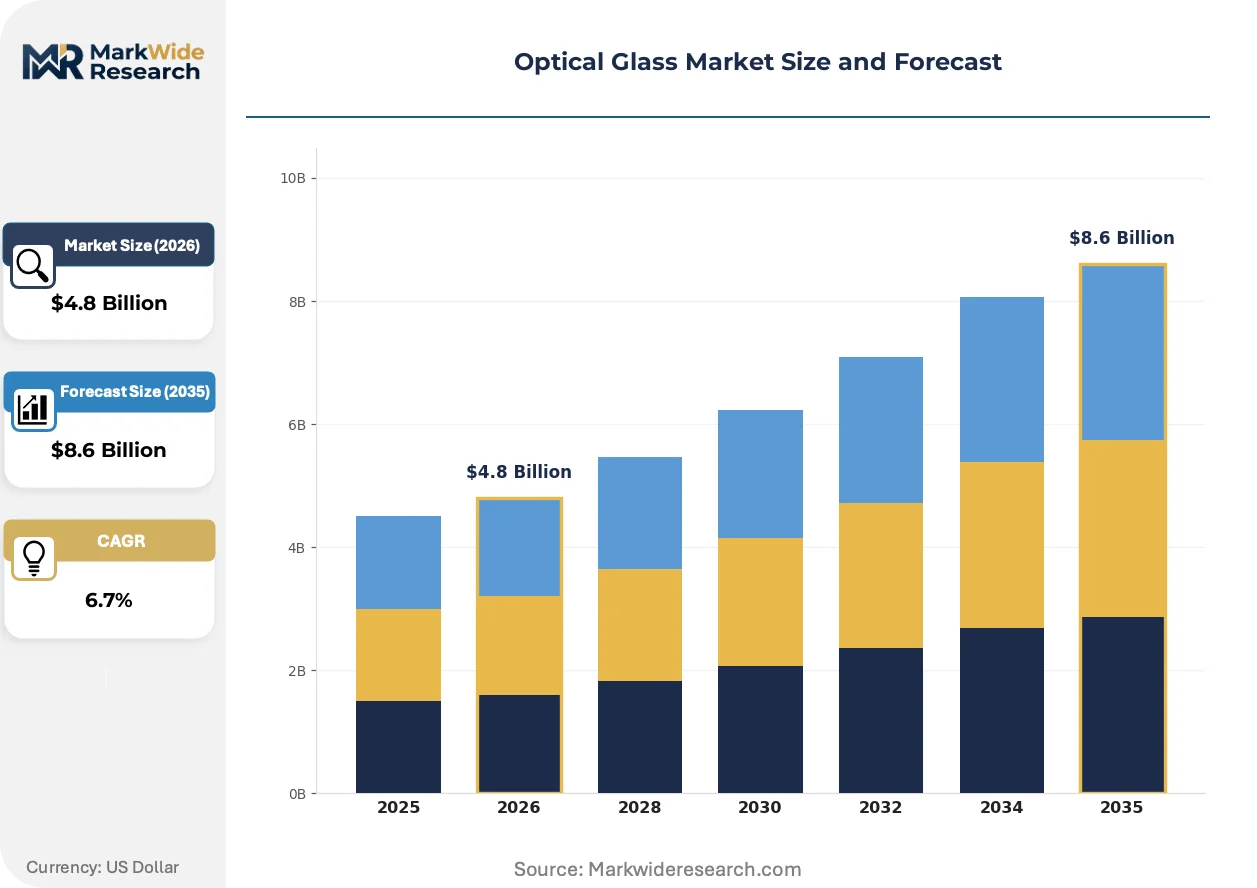
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $8.6 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Planoconvex Lenses, Biconvex Lenses, Concave Lenses, Filters End User: Healthcare, Industrial Processing, Consumer Electronics, Defense Application: Photography, Telescopes, Microscopes, Projection Systems Technology: Coating, Grinding, Molding, Polishing |
| Companies Covered | CDGM Glass, Ohara, HOYA, Sumita Optical Glass, Hubei New Huaguang, Schott AG, Nikon Corporation, AGC, Corning Incorporated, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Optical Glass Market Emerging Trajectories
Computational optics and additive manufacturing are compressing traditional grinding-polishing value chains while ion-beam deposition technologies extend substrate performance beyond material limits.
Helium ion beam figuring is rewriting surface accuracy standards for astronomical mirror substrates. European Southern Observatory and NASA procurement specifications now demand sub-nanometer surface figure on meter-class blanks. This technology is compressing delivery timelines from 24 months to 8 months for custom telescope primaries.
China's SAMR enforcement of GB standards for optical uniformity is excluding uncertified foundries from defense and aerospace procurement. Domestic certification bodies in Chengdu and Xi'an now control access to military thermal imaging contracts. Foreign suppliers without in-country testing partnerships face automatic disqualification.
Buyers in smartphone camera modules are consolidating lens element sourcing around vertically integrated module assemblers. Tier-one integrators in Vietnam and India now specify complete optical stacks rather than discrete substrates. This disintermediation is compressing margin pools for standalone glass processors in Taiwan and South Korea.
Optical Glass Market Segmentation
Optical glass segmentation maps directly onto value capture tiers, where refractive index precision and surface figure tolerance separate premium lithography substrates from commodity smartphone lenses. Each axis reveals distinct margin pools and certification barriers.
Product Type:
Refractive geometry determines thermal stability requirements and coating compatibility in downstream optical stacks.
- Planoconvex Lenses:Single flat and single curved surface geometry simplifies mounting alignment in machine vision systems. Volume procurement from Vietnam and India smartphone module assemblers compresses unit economics despite scale.
- Filters:Dichroic and narrowband interference coatings on polished substrates enable wavelength-selective transmission for lidar and AR waveguides. Ion-beam sputtering integration with molded glass creates the steepest value-add trajectory.
- Biconvex Lenses:Symmetrical curvature suits simple imaging applications in consumer cameras and projectors with minimal aberration correction.
- Concave Lenses:Diverging optical power expands beam profiles in laser systems and eyepiece assemblies for medical endoscopes.
Planoconvex lenses lead on scale; filters lead on momentum.
End User:
Regulatory burden and qualification timelines fragment procurement patterns across buyer categories.
- Healthcare:Biocompatibility certification under FDA 21 CFR Part 820 and EMA Medical Device Regulation gates surgical instrument and diagnostic imaging supply chains. HOYA and Schott AG dominate qualified rod lens supply for flexible endoscopes.
- Defense:Thermal imaging and laser designation systems require optical uniformity certification under China SAMR GB standards and India BIS specifications. Domestic testing partnerships in Chengdu and Bengaluru control contract access.
- Industrial Processing:Machine vision and semiconductor inspection systems prioritize transmission stability over medical-grade documentation.
- Consumer Electronics:Smartphone camera modules and AR headsets drive volume through vertically integrated module assemblers in Vietnam and South Korea.
Healthcare commands the highest certification premiums; defense procurement is expanding most quickly under import substitution mandates.
Application:
Optical path complexity and environmental exposure requirements shape substrate specifications.
- Microscopes:Numerical aperture demands and immersion oil compatibility require crown-flint achromatic doublets with sub-wavelength surface figure. Research instrument manufacturers in Germany and Japan specify proprietary fine-annealed substrates.
- Telescopes:Meter-class mirror blanks for astronomical observatories specify helium ion beam figuring to sub-nanometer accuracy. European Southern Observatory and NASA procurement compresses delivery timelines from 24 months to 8 months.
- Photography:Mobile camera modules and interchangeable lens systems prioritize weight reduction through molded aspheric elements.
- Projection Systems:High-lumen density tolerance drives fused silica adoption for cinema and laser phosphor displays.
Microscopes retain the deepest supplier relationships; telescopes show the steepest technology escalation.
Technology:
Process control at each fabrication stage determines final optical performance and yield economics.
- Coating:Ion-beam sputtered anti-reflective and filter stacks extend transmission bandwidth beyond substrate material limits. ASML EUV optics require synthetic fused silica with sub-ppm impurity levels paired with specialized coating chambers.
- Polishing:Sub-nanometer surface figure achievement for lithography and astronomy substrates relies on deterministic figuring with in-process metrology feedback.
- Grinding:CNC-controlled curve generation establishes initial geometry before fine polishing, with diamond wheel specifications varying by glass hardness.
- Molding:Precision glass molding of aspheric surfaces eliminates polishing steps for high-volume smartphone lenses, though tool wear limits material options.
Coating commands the highest value-add per process hour; molding scales fastest in consumer electronics supply chains.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Master glassblowers and fine annealing specialists cluster in Germany's Jena optical valley and Japan's Osaka-Kyoto corridor, anchoring precision substrate supply chains for lithography and medical endoscopy.
United States
EUV lithography tool deployment at Intel's Arizona and Ohio fabs pulls synthetic fused silica demand from Corning's New York state production base. EPA emissions standards for melting furnaces favor electric-powered operations over legacy natural gas configurations. Rochester, New York retains deep metrology expertise from Kodak's optical heritage, now serving defense thermal imaging contracts.
Germany
Schott AG's Mainz facility supplies fine-annealed mirror substrates for European Southern Observatory telescopes and semiconductor stepper optics. EU Green Deal carbon border adjustments redirect procurement toward renewable-powered melting operations. Jena's optical cluster concentrates ion-beam sputtering specialists serving Zeiss microscopy supply chains.
China
Domestic lithography tool development by SMEE and lens fabrication for smartphone modules drive optical glass consumption in Shanghai and Shenzhen. SAMR enforcement of GB standards for optical uniformity excludes uncertified foundries from defense procurement. Chengdu and Xi'an host certification bodies controlling access to military thermal imaging contracts.
Japan
Nikon's lithography systems and HOYA's medical endoscope rod lenses anchor precision glass demand in the Osaka-Kyoto corridor. METI subsidies for domestic EUV-grade synthetic quartz production reduce import dependency. Nagoya-area suppliers gain preferred access to Nikon supply chains under the semiconductor materials initiative.
India
Defense thermal imaging and laser designation programs under import substitution mandates create protected volume for qualified suppliers. BIS optical uniformity standards exclude uncertified foundries from military procurement. Bengaluru hosts emerging testing partnerships seeking early qualification for domestic defense contracts.
Optical Glass Market Vendor Landscape
Capital-heavy producers compete with asset-light designers across a tiered structure where continuous melting furnace ownership separates premium substrate suppliers from regional job shops. Three archetypes dominate: integrated silicate formulators controlling raw material refining, precision polishers specializing in sub-nanometer surface figure, and coating houses layering ion-beam sputtered optical stacks. Strategic moves center on captive synthetic quartz production and qualification partnerships with lithography tool OEMs.
Within the integrated formulator tier, Schott AG and HOYA occupy positions defined by decades of fine annealing process continuity, while Corning Incorporated anchors North American supply through captive fused silica production. CDGM Glass exemplifies the scale-driven Chinese model serving domestic smartphone module assemblers.
| Leading Market Players |
|---|
| CDGM Glass |
| Ohara |
| HOYA |
| Sumita Optical Glass |
| Hubei New Huaguang |
| Schott AG |
| Nikon Corporation |
| AGC |
| Corning Incorporated |
| Others |
Supply Flow & Price Mechanics
Helium ion beam figuring for sub-nanometer surface accuracy is compressing traditional grinding-polishing timelines from 24 months to 8 months, simultaneously elevating capital barriers for precision suppliers while concentrating procurement power around certified astronomical mirror and EUV lithography substrate producers. This technological inflection redraws cost structures across premium and commodity tiers, with melt-controlled low-homogeneity formulations commanding sustained premiums as energy-intensive continuous melting faces carbon border adjustment pressures.
Pricing Analysis
Coating-integrated versus substrate-only supply splits the market into bundled service premiums and commoditized volume plays. Pricing stratifies across premium melt-controlled formulations for semiconductor lithography, certified medical-grade rod lenses, and commodity molded aspherics for smartphone modules. Price differentiation hinges on optical uniformity certification tier and ion-beam sputtering capability integration. Cost compression in commodity smartphone lens supply chains intensifies as vertically integrated module assemblers in Vietnam and India consolidate procurement. Consumer electronics buyers exhibit highest price sensitivity; astronomical observatory and EUV tool OEMs show lowest sensitivity due to specification rigidity.
Supply Chain Analysis
Freight costs for meter-class mirror blanks and fragile polished substrates favor regional clustering over global dispersion, anchoring supply around Germany's Jena optical valley and Japan's Osaka-Kyoto corridor. Production concentrates in Germany, Japan, and China, with raw material refining for high-purity lanthanum oxide and tantalum pentoxide drawing from Chinese operations. Synthetic fused silica supply rests on captive production at Corning's New York base and emerging Japanese METI-subsidized domestic capacity. Single-source vulnerability concentrates in EUV-grade synthetic quartz and fine annealing specialist labor pools. Distribution runs through lithography tool OEMs, medical device contract manufacturers, and defense procurement channels with mandatory domestic testing partnerships.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The optical glass market represents a late-cycle quality story where extreme ultraviolet lithography expansion and astronomical mirror precision escalation filter procurement toward certified suppliers with proven fine annealing continuity. Demand is concentrating in sub-ppm impurity synthetic fused silica and sub-nanometer surface figure substrates that exclude uncertified foundries.
For Market Incumbents: Anticipate retirement-driven fine annealing specialist scarcity by embedding process knowledge in automated stress-birefringence metrology systems and securing apprenticeship pipelines with Jena and Mainz technical institutes. Defend margin position through captive synthetic quartz production and pre-qualification partnerships with ASML and Nikon lithography supply chains before carbon border adjustments reshape European furnace economics. For New Entrants and Emerging Players: Direct-to-device qualification platforms offer a lower-friction entry path than traditional OEM channel development, particularly for medical endoscope rod lenses where FDA 21 CFR Part 820 compliance can be demonstrated through digital documentation systems. Target India's BIS-certified defense thermal imaging segment under import substitution mandates, where domestic testing partnerships in Bengaluru create protected volume for early qualified entrants. For Investors and Strategic Acquirers: Valuations sit cheapest among regional job shops with legacy pot melting furnaces facing $15-25 million reconfiguration costs to meet EU Green Deal emissions standards. Long-term viability favors acquirers of fine annealing craft knowledge and ion-beam sputtering integration capabilities over pure commodity formulators. Watch for METI subsidy announcements on domestic EUV-grade synthetic quartz production as signal of Japanese supply chain preference shifts.| Strategic Initiative | Industry Significance |
|---|---|
| Captive Synthetic Quartz Production | ASML and Nikon procurement specifications exclude non-captive fused silica suppliers from EUV optics qualification. |
| Fine Annealing Process Automation | Schott AG and HOYA retirement waves threaten sub-5 nm/cm stress-birefringence capability continuity without knowledge codification. |
| Ion-Beam Sputtering Integration | Meta and Apple AR waveguide supply chains prioritize dual-capability suppliers coating molded glass substrates. |
| Domestic Defense Certification Partnerships | China SAMR and India BIS optical uniformity standards exclude foreign foundries without in-country testing infrastructure. |
| Renewable-Powered Furnace Reconfiguration | EU Green Deal carbon border adjustments redirect procurement toward German and French suppliers with electric or hydrogen melting operations. |
Methodological Framework
Coverage spans Germany, Japan, China, and the United States, with primary inputs from each market's precision glass production clusters. Primary interviews with fine annealing process engineers, ion-beam sputtering equipment specialists, medical device procurement managers, and defense thermal imaging program officers combined with secondary validation from customs trade data, SEC filings of listed optical component suppliers, EMA Medical Device Regulation submission databases, and China SAMR GB standard certification records. Bottom-up volume estimates from individual facility capacities triangulated against top-down demand projections from lithography tool OEM shipment disclosures and astronomical observatory procurement budgets.
Rate-of-change decomposition separated volume growth from value mix shifts across the projection horizon. Segmentation dimensions modeled include refractive geometry type, end-user regulatory burden tier, application optical path complexity, and fabrication technology stage. CAGRs derived from fitted growth curves applied to base-year market sizing, with cross-checks against semiconductor capital equipment spending cycles and medical endoscope unit shipment trajectories. EUV lithography tool deployment schedules and China dual carbon policy implementation timelines served as industry-specific demand anchors.
The model assumes a particular technology adoption path for helium ion beam figuring and precision glass molding; alternative pathways for additive manufacturing optics or computational lens design would alter the outlook for traditional grinding-polishing value chain participants. Forecasts reflect assumptions on fine annealing specialist labor availability, REACH substitution timeline compliance, and carbon border adjustment scope expansion. A model refresh is warranted upon material change in ASML or Nikon lithography tool shipment forecasts or China SAMR enforcement intensity for defense procurement certification.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Glass
Global Laminated Glass Market
Glass
Glazing Gel Market
Glass
Glass Product Market
Glass
Patterned Glass Market
Glass
Heat Resistant Glass Market
Glass
Double Glazing Glass Market
Glass
Silica Sand for Glass Making Market
Glass
Global Ultra-Thin Glass Market
Glass
Glass Reactors Market
Glass
Paper Glass Maker Market
Glass
Middle-East and Africa Flat Glass Market
Glass
Global Glassware Market
Glass
Glass Substrate Market
Glass
Silica Sand Market
Glass
Global Energy Efficient Glass Market
Glass
North America Architectural Flat Glass Market