
 Global Artificial Intelligence (AI) in Pharmaceutical Market | 2026-2036
Global Artificial Intelligence (AI) in Pharmaceutical Market Size, Share, and Industry Trends Forecast 2026-2036
Global Artificial Intelligence (AI) in Pharmaceutical Market Foresight
Mid-sized biotechnology firms is redrawing procurement patterns across the AI pharmaceutical landscape as these buyers displace large pharma's historical dominance in algorithmic platform licensing. NVIDIA Corporation leverages its specialized silicon architecture to dominate computational biology workloads, while Insilico Medicine sustains end-to-end chemistry generation pipelines from target identification to preclinical candidate nomination. Recursion Pharmaceuticals anchors its position through industrial-scale cellular imaging datasets that feed proprietary machine learning models.
Artificial Intelligence in Pharmaceutical denotes algorithmic systems that process molecular, clinical, and biological data to predict drug-target interactions, optimize compound properties, or stratify patient populations, typically operating on high-dimensional datasets exceeding ten thousand features per observation. Machine Learning applications currently capture the largest share of deployed value, though Deep Learning architectures for protein structure prediction represent the fastest-expanding capability layer. Drug Discovery commands the dominant application segment, while Clinical Trials generates disproportionate margin expansion through adaptive enrollment algorithms that reduce protocol amendment rates.
The FDA, EMA, and WHO collectively shape market access through divergent postures on algorithmic validation, with the FDA emphasizing predetermined change control plans and the EMA requiring explicit algorithmic transparency in marketing authorization dossiers. China's NMPA accelerates domestic adoption through streamlined review pathways for AI-diagnostic combinations, creating regulatory arbitrage opportunities for multinational platform developers. Stakeholders must decide whether to pursue jurisdiction-specific compliance architectures or unified global submission strategies as regulatory divergence deepens.
Market Dynamics
Biopharmaceutical contract research organizations are accelerating algorithmic platform procurement as NIH-funded consortia compress preclinical timelines through predictive modeling integration. This buyer-segment migration is restructuring vendor pricing power across molecular design and patient stratification workflows.
Growth Catalysts
- EMA Algorithmic Transparency Mandates:European marketing authorization dossiers now require explicit model interpretability documentation, creating compliance-driven demand for explainable AI toolkits among submission teams.
- Cellular Imaging Dataset Proliferation:Industrial-scale phenotypic screening infrastructure generates training data volumes that enable supervised learning applications in toxicity prediction previously constrained by sample scarcity.
- Boston-San Francisco Venture Clustering:Concentrated startup formation around these metropolitan hubs produces specialized talent pools and cross-pollination between academic computational biology labs and commercial platform developers.
Market Restraints
- GPU Compute Cost Volatility:Specialized silicon for deep learning protein structure prediction faces supply allocation constraints from competing artificial intelligence workloads outside pharmaceutical applications.
- FDA Predetermined Change Control Burden:Algorithmic validation requirements for drug development tools impose documentation overhead that extends platform deployment timelines for adaptive machine learning systems.
- Quantum Chemistry Simulation Substitution:Physics-based molecular dynamics methods retain preference for certain target classes where training data sparsity limits neural network generalization.
Strategic Opportunities
- China NMPA Streamlined Pathways:Accelerated review timelines for AI-diagnostic combinations create first-mover advantages for multinational developers establishing domestic regulatory capabilities.
- Adaptive Enrollment Algorithm Adoption:Clinical trial operators in the United States deploy real-time patient matching systems that compress recruitment duration and reduce protocol amendment frequency.
- Federated Learning Convergence:Distributed model training across institutional boundaries enables multi-site collaboration without centralizing proprietary patient datasets, addressing data sovereignty constraints.
Industry Challenges
- Computational Biology Talent Scarcity:Hybrid expertise spanning medicinal chemistry and machine learning architecture design remains concentrated among elite academic programs, constraining platform team scaling.
- Legacy Electronic Data Capture Integration:Established clinical trial management systems require custom API development for seamless AI-enabled decision support deployment, extending implementation cycles.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Artificial Intelligence (AI) in Pharmaceutical Market |
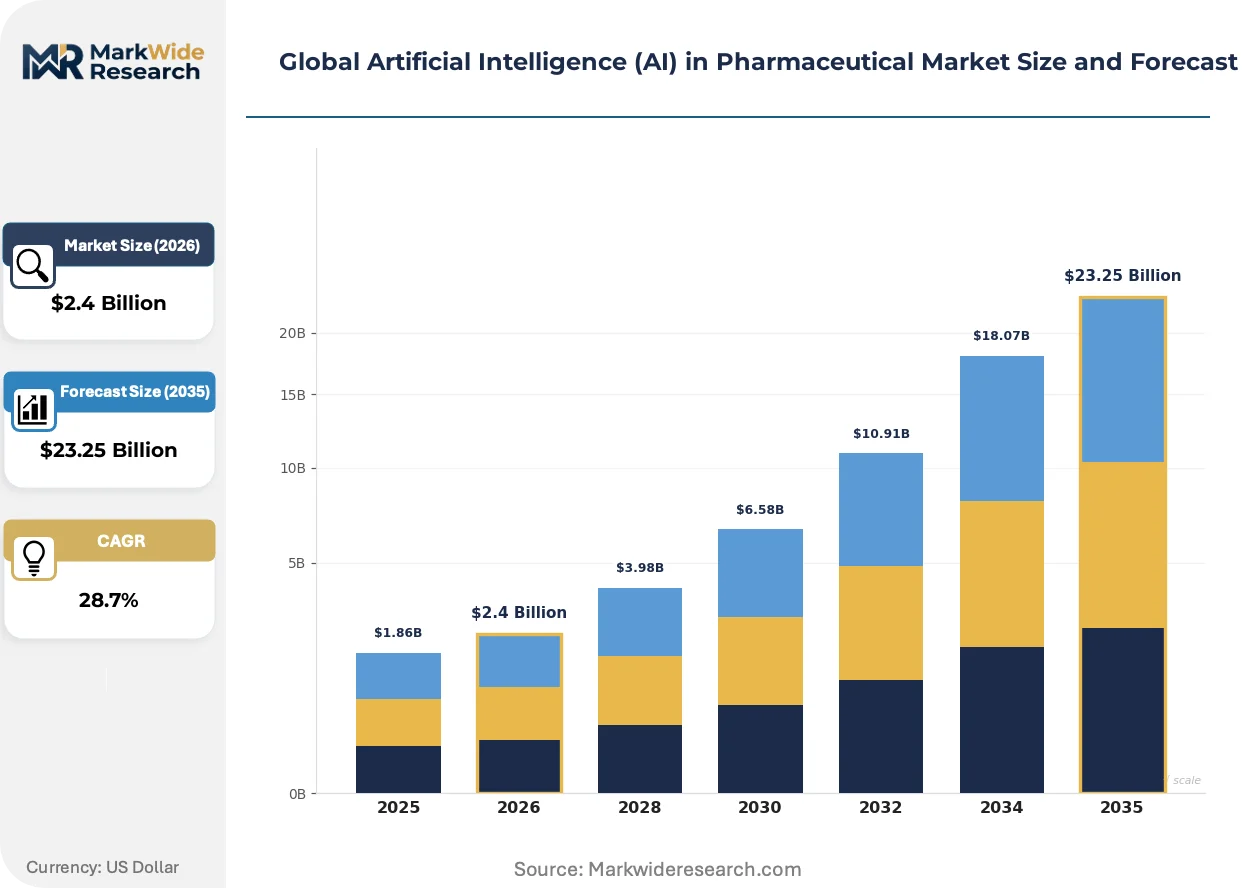
| Market Size in 2026 | $2.4 Billion |
| Market Size in 2035 | $23.25 Billion |
| CAGR (2026 – 2036) | 28.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Technology: Machine Learning, Natural Language Processing, Deep Learning, Computer Vision Application: Drug Discovery, Clinical Trials, Diagnostics, Patient Management End User: Pharmaceutical Companies, Research Institutions, Biotechnology Firms, Healthcare Providers Deployment: Cloud-Based, On-Premises, Hybrid, SaaS |
| Companies Covered | IBM Corporation, Microsoft, NVIDIA Corporation, Google, Insilico Medicine, Recursion Pharmaceuticals, Atomwise Inc, Exscientia, BenevolentAI, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Artificial Intelligence (AI) in Pharmaceutical Market Shifts & Advancements
Foundation models trained on protein sequence and structure databases are compressing discovery timelines while regulatory frameworks race to establish validation protocols for continuously learning systems. These parallel developments are restructuring competitive advantage around data moats and submission readiness.
Transformer architectures for protein structure prediction are fragmenting the traditional computational chemistry vendor landscape. Mid-sized biotechnology firms now license endpoint-specific models rather than comprehensive platform suites, compressing contract values while expanding addressable buyer counts. This unbundling enables point-solution procurement that matches discrete pipeline stage requirements.
The FDA's predetermined change control plan guidance for AI-enabled drug development tools is formalizing documentation standards for algorithmic modifications during clinical use. Sponsors must now prospectively define acceptable performance drift thresholds and retraining protocols, affecting how machine learning systems are architected for regulatory submission. Biopharmaceutical contract research organizations are responding by embedding compliance engineers within discovery teams.
Buyer concentration among mid-sized biotechnology firms is displacing large pharmaceutical historical dominance in algorithmic platform licensing. These emerging buyers prioritize modular, API-accessible tools over integrated suites, favoring vendors with flexible deployment architectures. The shift is most visible in United States coastal clusters where venture-backed formation rates exceed legacy hub concentrations.
Global Artificial Intelligence (AI) in Pharmaceutical Market Segmentation
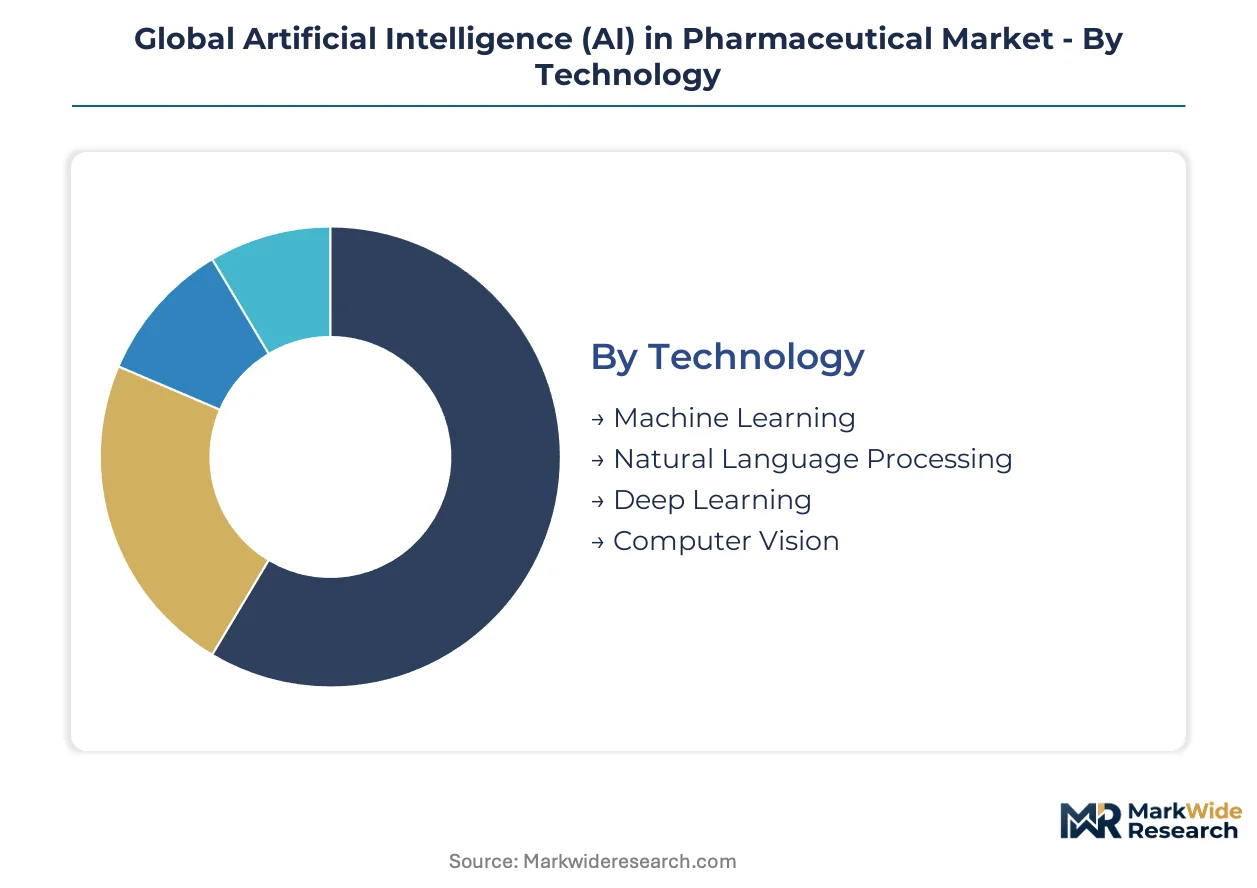
Segmentation in AI pharmaceutical markets reveals how algorithmic capabilities map to distinct value creation points across discovery, development, and commercialization workflows. Technology architecture choices determine computational cost structures, while deployment models shape data sovereignty compliance across multinational regulatory environments.
Technology:
Margin pools concentrate in deep learning architectures where specialized silicon requirements create vendor lock-in and premium pricing power for infrastructure providers.
- Deep Learning:Neural network architectures process high-dimensional molecular representations and protein structure predictions, demanding GPU clusters that concentrate demand among United States and China-based cloud providers. Training costs and specialized talent scarcity limit deployment to well-capitalized sponsors.
- Machine Learning:Traditional supervised learning methods dominate deployed value through established random forest and gradient boosting implementations in target identification and compound property optimization. Interpretability requirements from FDA and EMA submissions favor these transparent algorithmic approaches.
- Natural Language Processing:Extracts structured insights from unstructured biomedical literature and clinical trial protocols, accelerating target validation literature reviews.
- Computer Vision:Processes cellular imaging and histopathology datasets for phenotypic screening applications.
Deep Learning holds installed capacity. Machine Learning is rotating up the share rankings as regulatory interpretability mandates strengthen.
Application:
Volume concentration follows the pharmaceutical development pipeline, with early-stage discovery commanding platform licensing frequency while late-stage applications capture per-contract value premiums.
- Drug Discovery:Algorithmic target identification, hit generation, and lead optimization compress preclinical timelines through predictive modeling of drug-target interactions and ADMET properties. NIH-funded consortia and Boston-San Francisco venture clusters drive procurement concentration.
- Clinical Trials:Adaptive enrollment algorithms and patient stratification systems reduce protocol amendment rates and recruitment duration, generating disproportionate margin expansion through outcome-based contracting models.
- Diagnostics:AI-enabled imaging and biomarker interpretation tools face divergent regulatory pathways across FDA, EMA, and China's NMPA jurisdictions.
- Patient Management:Post-market surveillance and adherence monitoring applications extend pharmaceutical value capture beyond approval.
Drug Discovery anchors current deployment volume. Clinical Trials is climbing the fastest as adaptive trial designs gain sponsor acceptance.
End User:
Customer type determines procurement sophistication, with contract structures ranging from enterprise platform licenses to per-project API calls.
- Biotechnology Firms:Mid-sized entities now displace large pharmaceutical historical dominance in algorithmic platform licensing, prioritizing modular API-accessible tools over integrated suites. Venture-backed formation rates in United States coastal clusters exceed legacy hub concentrations.
- Pharmaceutical Companies:Legacy organizations maintain selective platform investments while increasingly outsourcing specialized computational biology workloads to contract research organizations.
- Research Institutions:Academic computational biology labs generate foundational datasets and talent pipelines that commercialize through startup formation.
- Healthcare Providers:Clinical deployment of AI-diagnostic combinations accelerates through China's NMPA streamlined review pathways.
Biotechnology Firms hold installed capacity. Pharmaceutical Companies is rotating up the share rankings as outsourcing patterns mature.
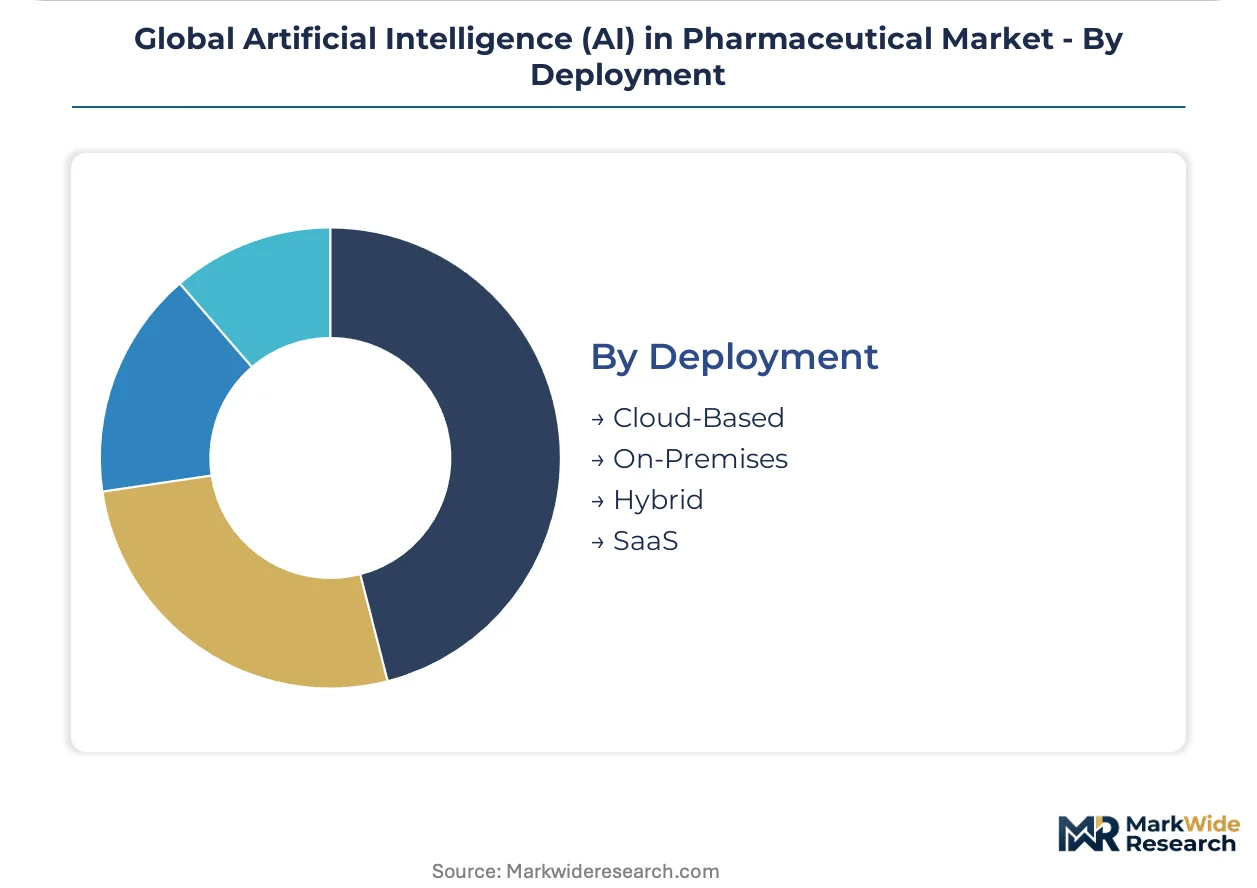
Deployment:
Architecture choices reflect data sovereignty constraints and regulatory validation burdens across multinational operational footprints.
- Cloud-Based:Scalable compute access enables burst capacity for deep learning training workloads without capital infrastructure commitment. United States and China hyperscalers dominate pharmaceutical workload hosting.
- Hybrid:Combines on-premises data residency for proprietary molecular libraries with cloud burst capacity for computational intensive model training, addressing EMA algorithmic transparency requirements and FDA predetermined change control documentation.
- On-Premises:Retained for highest-sensitivity proprietary datasets and regulatory air-gapped validation environments.
- SaaS:Subscription access to endpoint-specific models enables point-solution procurement matching discrete pipeline stage requirements.
Cloud-Based holds installed capacity. Hybrid is rotating up the share rankings as data sovereignty constraints deepen.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Specialized silicon fabrication for deep learning workloads concentrates in United States and China-based foundries, with cloud infrastructure providers in both countries capturing pharmaceutical computational demand. Algorithmic platform developers cluster around metropolitan innovation hubs where venture capital and academic computational biology programs intersect.
United States
NIH-funded consortia and Boston-San Francisco venture clusters drive procurement concentration for predictive modeling platforms. FDA predetermined change control plan guidance reshapes validation documentation requirements for algorithmic drug development tools. Greater Boston anchors startup formation rates that exceed legacy pharmaceutical hub concentrations.
China
NMPA streamlined review pathways for AI-diagnostic combinations accelerate domestic adoption and create regulatory arbitrage opportunities for multinational developers. Dual carbon goals and MIIT industrial policy direct state investment toward computational biology infrastructure. Yangtze River Delta and Pearl River Delta metropolitan clusters host hyperscaler facilities serving regional pharmaceutical workloads.
Germany
EMA algorithmic transparency mandates for marketing authorization dossiers generate compliance-driven demand for explainable AI toolkits among European submission teams. Federal Ministry of Education and Research funding supports academic computational biology programs that commercialize through startup formation. Baden-Württemberg and Bavaria host industrial-scale pharmaceutical R&D operations integrating machine learning into lead optimization workflows.
United Kingdom
BenevolentAI and Exscientia anchor a London-Oxford-Cambridge cluster where academic machine learning research transitions to commercial platform development. MHRA alignment with EMA interpretability requirements shapes submission preparation for UK-based sponsors. The Southeast England corridor concentrates venture-backed algorithmic drug discovery companies serving European and North American markets.
Switzerland
Swissmedic marketing authorization processes for AI-enabled devices attract developers seeking regulatory clarity alongside EMA pathways. ETH Zurich and University of Basel computational biology programs supply specialized talent to regional pharmaceutical headquarters. The Basel-Zurich corridor hosts large pharmaceutical algorithmic platform investments and specialized contract research operations.
Global Artificial Intelligence (AI) in Pharmaceutical Market Competitive Landscape
Concentration sits with diversified technology conglomerates and specialized biotechnology platform developers. The vendor landscape exhibits tiered structure with infrastructure providers commanding silicon-level pricing power while application-layer specialists compete on algorithmic performance. Three archetypes dominate: hyperscale cloud providers with pharmaceutical verticalization, end-to-end drug discovery platform developers, and point-solution specialists in protein structure prediction or clinical trial optimization. Competitive moves center on strategic partnerships between hardware and software layers and geographic expansion of regulatory submission capabilities.
Within the infrastructure-provider tier, NVIDIA Corporation exemplifies specialized silicon architecture dominance for computational biology workloads. Among end-to-end platform developers, Insilico Medicine and Recursion Pharmaceuticals occupy positions spanning target identification through preclinical candidate nomination. These three companies anchor distinct competitive vectors: hardware-enabled compute access, chemistry generation pipelines, and industrial-scale cellular imaging datasets respectively.
| Leading Market Players |
|---|
| IBM Corporation |
| Microsoft |
| NVIDIA Corporation |
| Insilico Medicine |
| Recursion Pharmaceuticals |
| Atomwise Inc |
| Exscientia |
| BenevolentAI |
| Others |
Supply & Pricing Matrix
GPU cluster utilization rates above eighty percent in United States and China hyperscaler facilities create scale economies that compress per-compute-hour costs for deep learning training workloads while establishing price floors that exclude smaller platform developers from protein structure prediction markets. This concentration of specialized silicon capacity simultaneously shapes vendor pricing power and buyer procurement thresholds across algorithmic drug discovery workflows.
Pricing Analysis
Volume-discount tiering structures separate enterprise platform licenses from per-project API calls and SaaS subscriptions for modular toolkits. Premium pricing attaches to FDA-validated algorithmic drug development tools with predetermined change control documentation, while standard tiers serve exploratory discovery workflows without submission readiness. Cost compression in cloud-based compute access intensifies as hyperscalers compete for pharmaceutical vertical workloads. Mid-sized biotechnology firms exhibit highest price sensitivity, prioritizing point-solution procurement over comprehensive platform suites, whereas large pharmaceutical companies accept premium tiers for regulatory-cleared end-to-end pipelines.
Supply Chain Analysis
TSMC advanced node fabrication in Taiwan underwrites global supply of GPUs deployed for protein structure prediction and molecular dynamics simulation. NVIDIA Corporation designs in the United States, while assembly and testing concentrates in China and Malaysia. Specialized memory components draw from South Korean suppliers. Single-source vulnerability in leading-edge semiconductor lithography equipment exposes downstream pharmaceutical AI developers to allocation constraints when competing artificial intelligence workloads surge. Distribution runs through direct hyperscaler partnerships and specialized life sciences cloud providers with HIPAA and FDA 21 CFR Part 11 compliance certifications.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
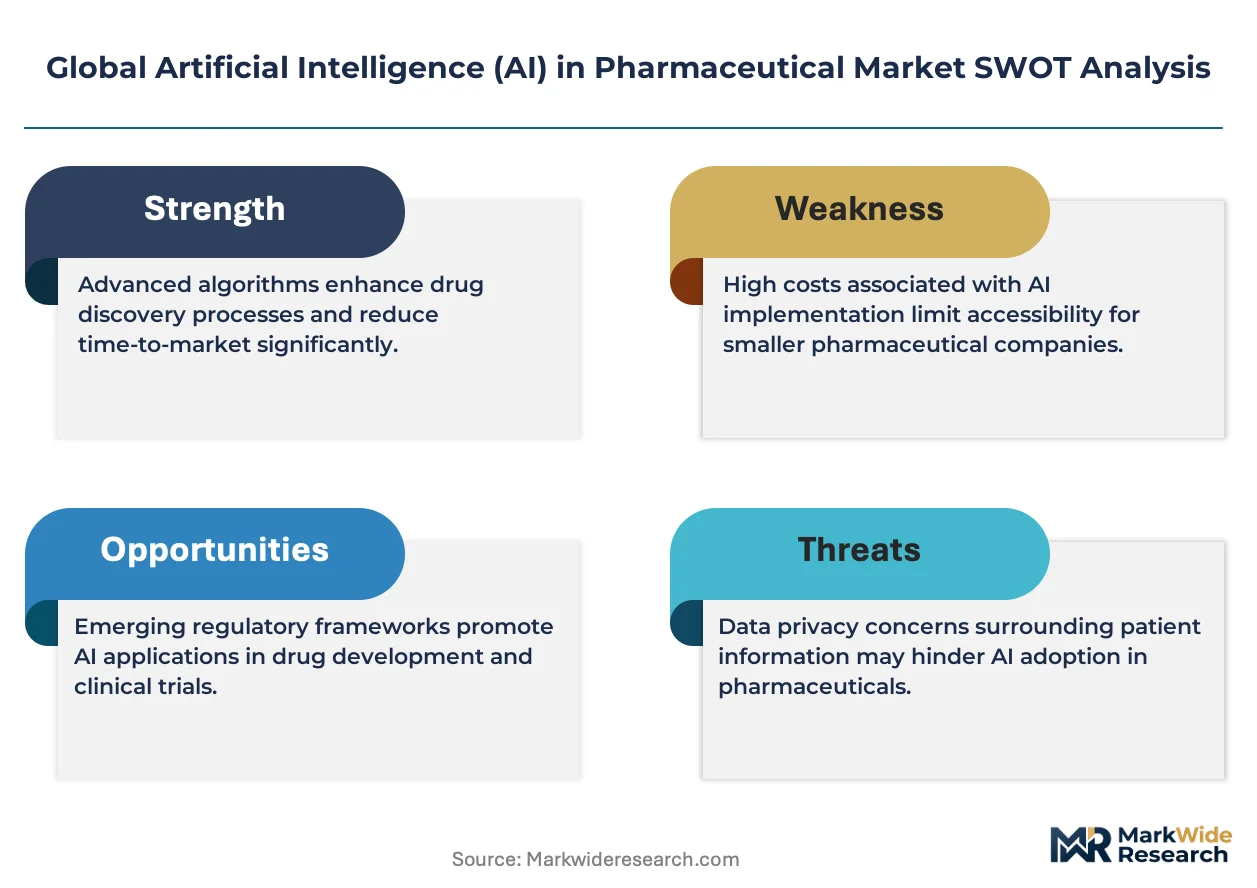
Early-cycle expansion dynamics in algorithmic drug discovery reflect penetration rates below fifteen percent for deep learning-enabled target identification across mid-sized biotechnology pipelines, creating runway for platform licensing growth as regulatory validation protocols mature.
For Market Incumbents: Consolidate data moat advantages through exclusive partnerships with NIH-funded consortia generating industrial-scale cellular imaging datasets. Lock in regulatory submission readiness by embedding compliance engineers within discovery teams to navigate FDA predetermined change control documentation. Acquire point-solution specialists in protein structure prediction before transformer architectures fragment traditional computational chemistry vendor positions.
For New Entrants and Emerging Players: FDA breakthrough device designation fast-tracks offer accelerated validation pathways for AI-enabled diagnostic combinations targeting oncology biomarker interpretation. White-space concentration sits in federated learning infrastructure enabling multi-site collaboration without centralizing proprietary patient datasets. China's NMPA streamlined review pathways present the most penetrable regulatory geography for multinational developers establishing domestic capabilities. Go-to-market positioning should emphasize API-accessible modular tools over integrated platform suites to match mid-sized biotechnology procurement preferences.
For Investors and Strategic Acquirers: Specialized contract research organizations with embedded computational biology teams represent prime acquisition targets as pharmaceutical companies accelerate outsourcing of algorithmic workloads. Long-term viability over the next decade hinges on regulatory submission capabilities spanning FDA, EMA, and NMPA jurisdictions rather than algorithmic performance metrics alone. Watch for inflection signals in adaptive enrollment algorithm adoption rates across United States clinical trial operators, as this application segment generates disproportionate margin expansion through outcome-based contracting models.
| Strategic Initiative | Industry Significance |
|---|---|
| Regulatory Submission Capability Expansion | EMA algorithmic transparency mandates and FDA predetermined change control plans require multi-jurisdiction documentation expertise. |
| Federated Learning Infrastructure Deployment | Distributed model training addresses data sovereignty constraints across European and Asian institutional boundaries. |
| Cellular Imaging Dataset Acquisition | Industrial-scale phenotypic screening infrastructure feeds proprietary machine learning models with training data moats. |
| API-First Platform Architecture | Modular tool access matches mid-sized biotechnology procurement patterns displacing large pharma historical dominance. |
| China NMPA Regulatory Establishment | Streamlined review pathways for AI-diagnostic combinations create first-mover advantages in accelerated domestic adoption. |
Research Methodology
A spread of perspectives from drug development executives, regulatory affairs leads, computational biology platform engineers, and biopharmaceutical contract research organization procurement managers converged on the working assumptions shaping this analysis. Primary interview insights combined with secondary validation from FDA filings, EMA marketing authorization dossiers, ClinicalTrials.gov protocol registries, and NIH grant portfolio databases. Bottom-up triangulation across technology deployment counts, platform licensing contract values, and end-user procurement patterns intersected with top-down market sizing from hyperscaler pharmaceutical vertical revenue disclosures and venture capital investment flows.
Segmentation dimensions modeled span technology architecture, application workflow, end-user organization type, and deployment model across the projection horizon. Treatment line positioning, regional regulatory cluster alignment, and pipeline stage-specific algorithmic requirements provided additional pharmaceutical industry granularity. CAGRs derived from fitted growth curves incorporating adoption S-cycles, regulatory validation timeline compression, and compute cost elasticity parameters. Forecast inputs included GPU cluster capacity expansion schedules, NIH consortium funding allocations, and biopharmaceutical R&D outsourcing ratio trajectories.
Decision-makers should treat outputs as directional under assumptions of continued regulatory divergence between FDA, EMA, and NMPA jurisdictions; material deviation in algorithmic validation standard harmonization would warrant model refresh. Specific risk factors include GPU supply allocation shocks from competing artificial intelligence workloads, quantum chemistry simulation substitution for target classes with training data sparsity, and legacy electronic data capture system integration failures extending implementation cycles. Practitioners should keep alternative scenarios live as federated learning regulatory frameworks and adaptive trial design reimbursement policies evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Artificial Intelligence (AI)
Artificial Intelligence Platform Market
Artificial Intelligence (AI)
AI Platform Market
Artificial Intelligence (AI)
Global Federated Learning Solutions Market
Artificial Intelligence (AI)
Model Validation and Automation Market
Artificial Intelligence (AI)
Explainable AI Market
Artificial Intelligence (AI)
Human-Computer Interaction (HCI) Market
Artificial Intelligence (AI)
Machine Learning As a Service (Mlaas) Market
Artificial Intelligence (AI)
Global Call Center AI Market
Artificial Intelligence (AI)
Artificial Intelligence Oven Market
Artificial Intelligence (AI)
Smart Home Digital Assistant [Voice] Market
Artificial Intelligence (AI)
Artificial Intelligence (AI) in Supply Chain Market
Artificial Intelligence (AI)
Automotive Predictive Diagnostic System Market
Artificial Intelligence (AI)
Artificial Intelligence in Trading Market
Artificial Intelligence (AI)
North America Conversational AI Market
Artificial Intelligence (AI)
Natural Language Processing in BFSI Market
Artificial Intelligence (AI)
Home AI Oven Market