
 Firefighting Robots Market | 2026-2036
Firefighting Robots Market Size, Share, and Industry Trends Forecast 2026-2036
Firefighting Robots Market Analysis
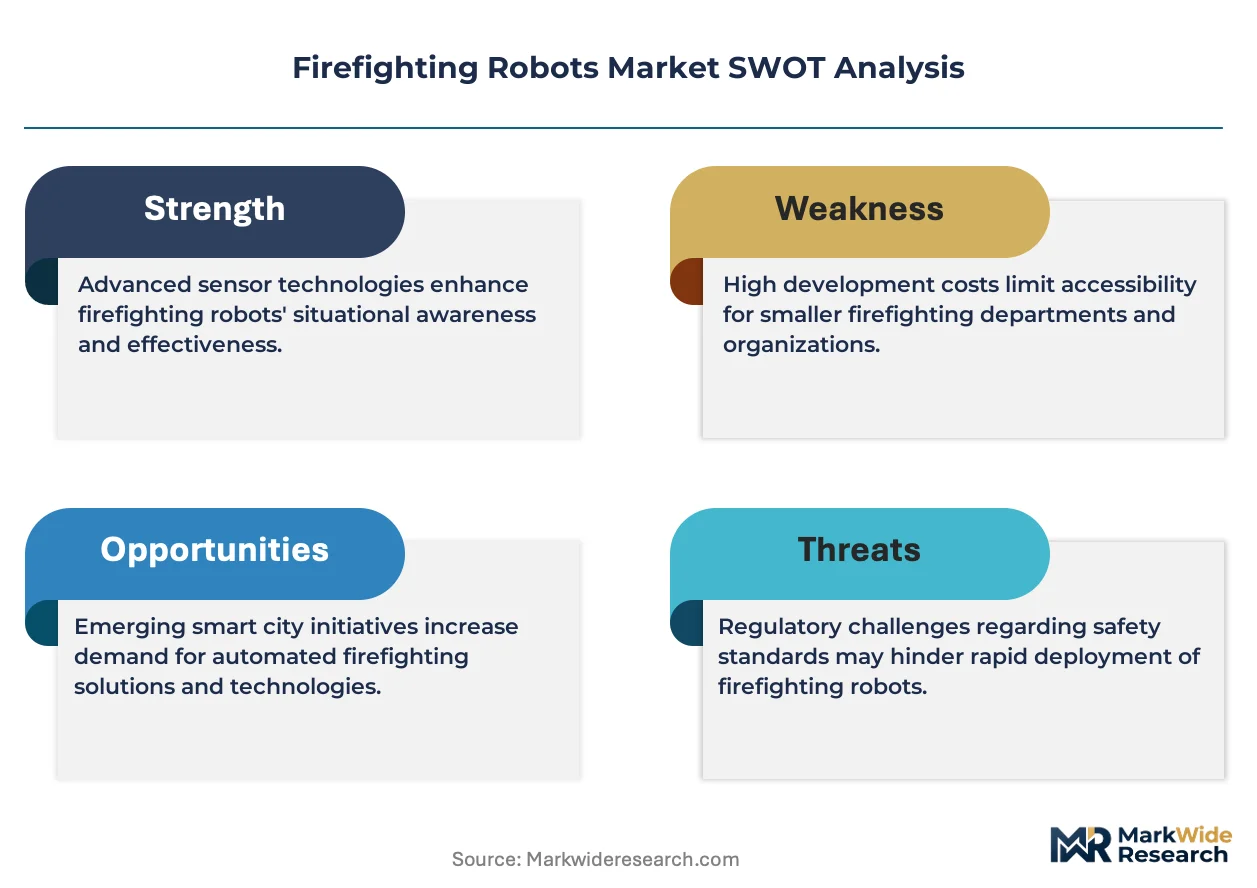
Autonomous navigation fused with thermal imaging is reconfiguring how firefighting robots map hazardous environments and execute suppression protocols without human entry. Mitsubishi Heavy Industries leverages its aerospace sensor heritage to anchor high-precision positioning systems for ground robots. QinetiQ Group competes through defense-grade ruggedization standards that sustain operational performance in extreme thermal conditions. Shark Robotics specializes in compact form factors that navigate collapsed urban structures where larger units cannot operate.
Firefighting robots are mobile robotic platforms engineered to withstand temperatures exceeding 800°C while deploying water, foam, or chemical suppressants via remotely operated or autonomous control systems; their primary purpose is to replace human firefighters in structurally compromised, toxic, or explosively volatile environments. Ground robots dominate current procurement volumes across European fire departments due to proven payload capacity and stair-climbing mechanics. AI Integration represents the fastest-expanding technology segment as sensor fusion and real-time decision algorithms reduce operator cognitive load during multi-unit deployments. Surveillance robots carry thinner margin pools but extend addressable demand into perimeter monitoring and post-extinguishment thermal scanning.
EU MDR and CE marking frameworks govern autonomous emergency equipment sold across European member states, while Japan's METI sets performance benchmarks for AI-integrated industrial safety systems. The US FAA coordinates with NHTSA on unmanned aerial firefighting platforms that transit between jurisdictions, creating fragmented certification pathways that shape vendor market access strategies. Stakeholders must monitor how divergent national safety standards for autonomous emergency response equipment reshape product development roadmaps and partnership requirements.
Market Dynamics
Autonomous navigation architectures are compressing operator-to-robot ratios from three personnel per unit toward single-operator multi-robot control, fundamentally restructuring fire department capital allocation and training curricula across industrial and municipal buyers.
Growth Catalysts
- EU MDR Certification Pathways:CE marking requirements for autonomous emergency equipment create procurement clarity for German, French, and Italian fire departments, accelerating replacement cycles for legacy remotely operated vehicles.
- Thermal Sensor Fusion:Real-time integration of infrared imaging with LiDAR mapping enables ground robots to locate hotspots through smoke opacity that defeats human visibility, expanding addressable incident types.
- Industrial Facility Mandates:Japan's METI funding directives for AI-integrated suppression systems at petrochemical and semiconductor fabrication sites generate concentrated demand for autonomous extinguishing platforms.
Market Restraints
- Lithium-Ion Battery Supply Concentration:Dependence on East Asian cell manufacturers exposes robot OEMs to raw material volatility and export control friction for high-density power systems rated above 800°C operational thresholds.
- EU AI Act Compliance Burden:Risk classification of autonomous decision-making systems in emergency response creates documentation and conformity assessment costs that disproportionately burden mid-tier European vendors.
- Human Firefighter Substitution Limits:Structural collapse scenarios requiring tactile judgment and improvised tool deployment remain technically inaccessible to current manipulator architectures, capping penetration in urban search-and-rescue.
Strategic Opportunities
- Perimeter Surveillance Extension:Surveillance-class robots with thinner suppressant payloads but extended thermal scanning duration open demand from forestry services and wildland-urban interface districts in Australia and California.
- Convergence of Exoskeleton and Robot Control:Haptic feedback interfaces originally developed for surgical robotics are migrating into firefighting teleoperation, enabling precision nozzle manipulation at extended ranges.
- Indian Industrial Safety Mandates:State-level factory inspectorates under the CEA are drafting compulsory automated response requirements for chemical cluster zones, creating first-mover positioning for certified suppliers.
Industry Challenges
- Multi-Jurisdiction Certification Timelines:Divergent testing protocols between FAA aerial standards, NHTSA ground vehicle rules, and EU MDR autonomous equipment frameworks extend product launch cycles and fragment engineering resources.
- Thermal Protection Material Obsolescence:Ceramic composite shielding rated for 800°C sustained exposure requires replacement after single incident deployment, creating consumables cost uncertainty in municipal procurement budgeting.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Firefighting Robots Market |
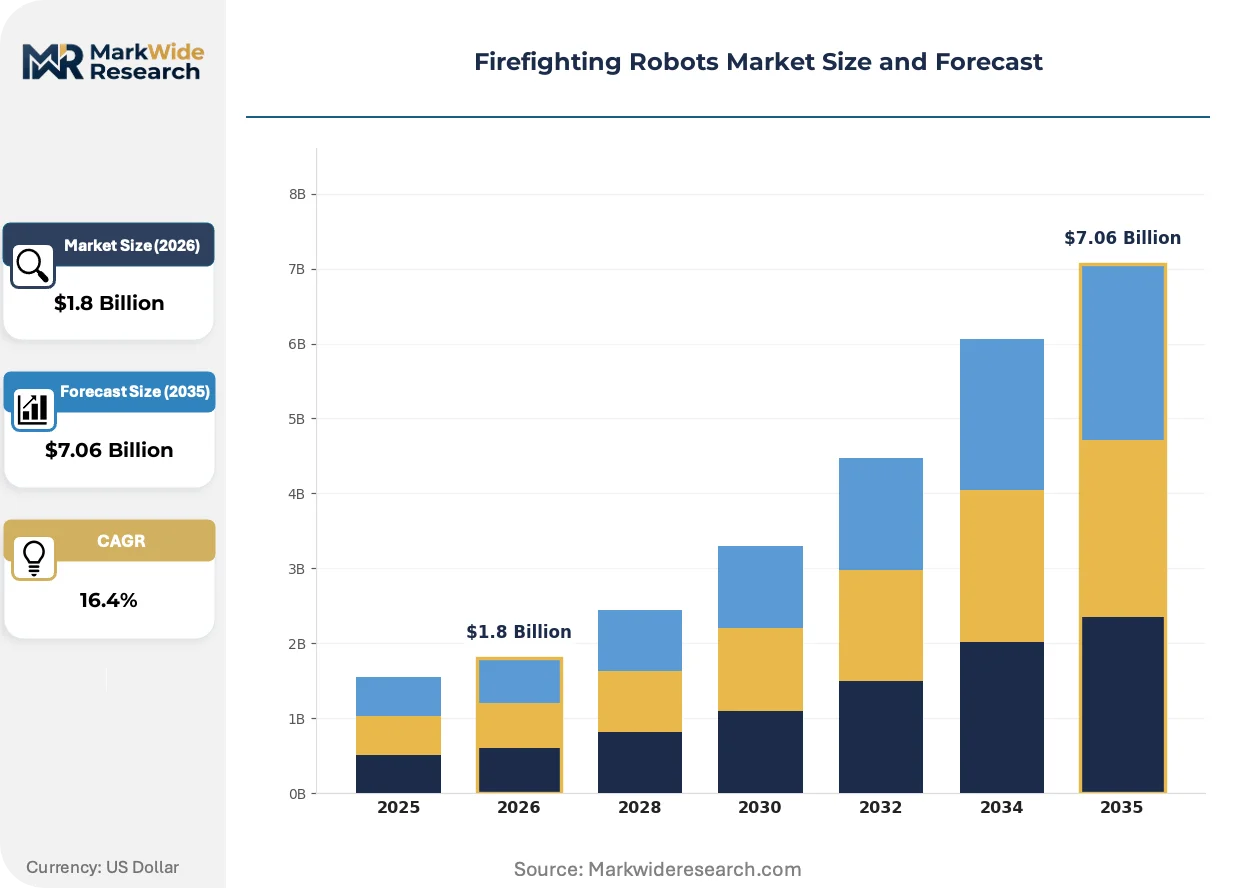
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $7.06 Billion |
| CAGR (2026 – 2036) | 16.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Autonomous Drones, Ground Robots, Water-Throwing Robots, Surveillance Robots Technology: AI Integration, Remote Control, Sensor Technology, Fire Suppression Systems End User: Fire Departments, Industrial Facilities, Military, Training Organizations Application: Wildfire Management, Structural Fire Response, Hazardous Material Handling, Urban Rescue |
| Companies Covered | Mitsubishi Heavy Industries, EmiControls, Howe & Howe Technologies, QinetiQ Group, Vimal Fire Controls, Shark Robotics, Angatec, LeoTronics Robotics, DOK-ING d.o.o., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Firefighting Robots Market Emerging Trajectories
Digital twin architectures are compressing development cycles for firefighting robot platforms by enabling thermal and navigation stress testing in simulated structural collapse scenarios before physical prototyping.
Sensor fusion middleware is virtualizing the boundary between operator supervision and autonomous execution, allowing Japanese industrial buyers to deploy mixed fleets where ground robots handle suppression while human teams manage evacuation coordination.
EU AI Act risk-tier classifications are forcing vendors to rearchitect decision algorithms for high-risk autonomous emergency systems, with German certification bodies now requiring documented human override latency specifications for municipal procurement eligibility.
Service contract unbundling is fragmenting traditional equipment sales into separate hardware, software maintenance, and incident-response subscription tiers, with Japanese METI-funded facilities pioneering per-deployment pricing models that shift capital expenditure to operational budgets.
Firefighting Robots Market Segmentation
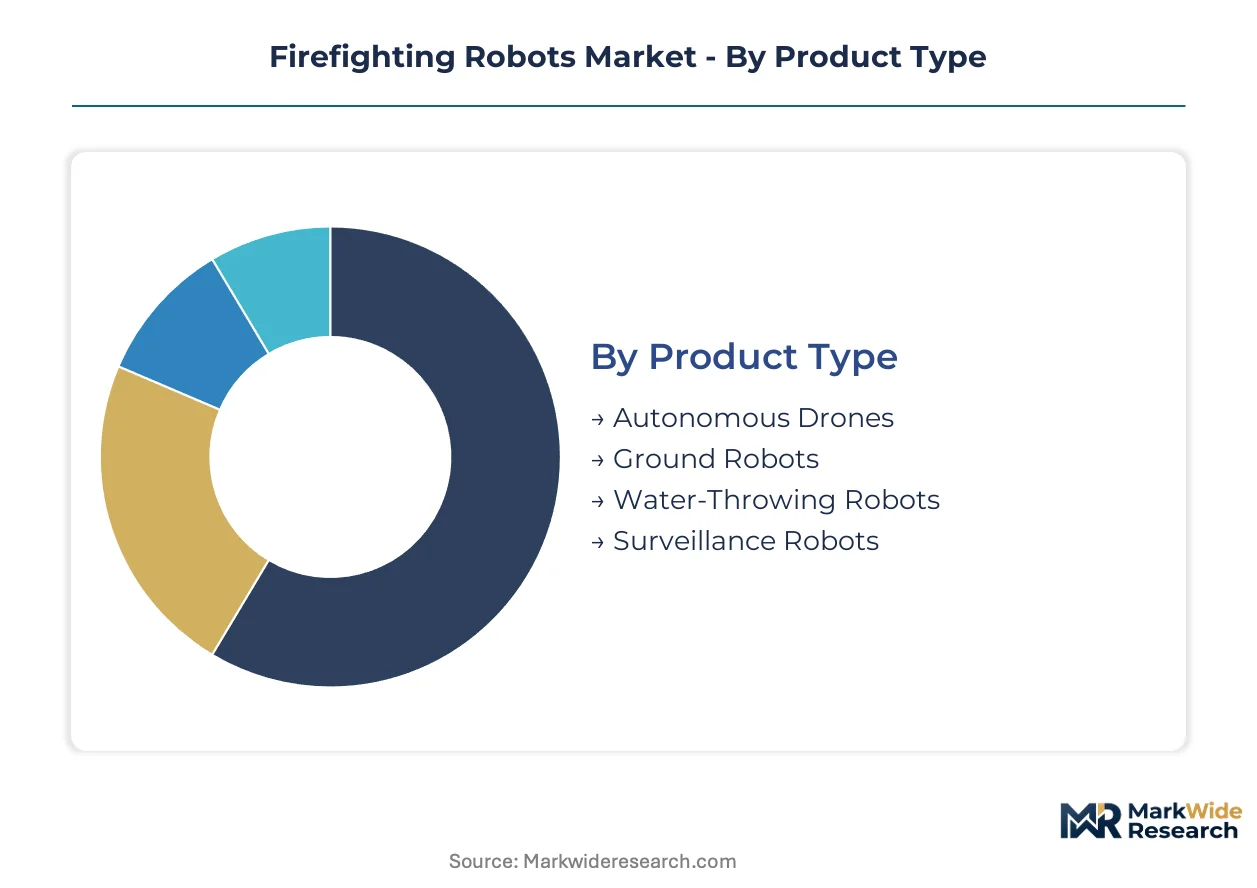
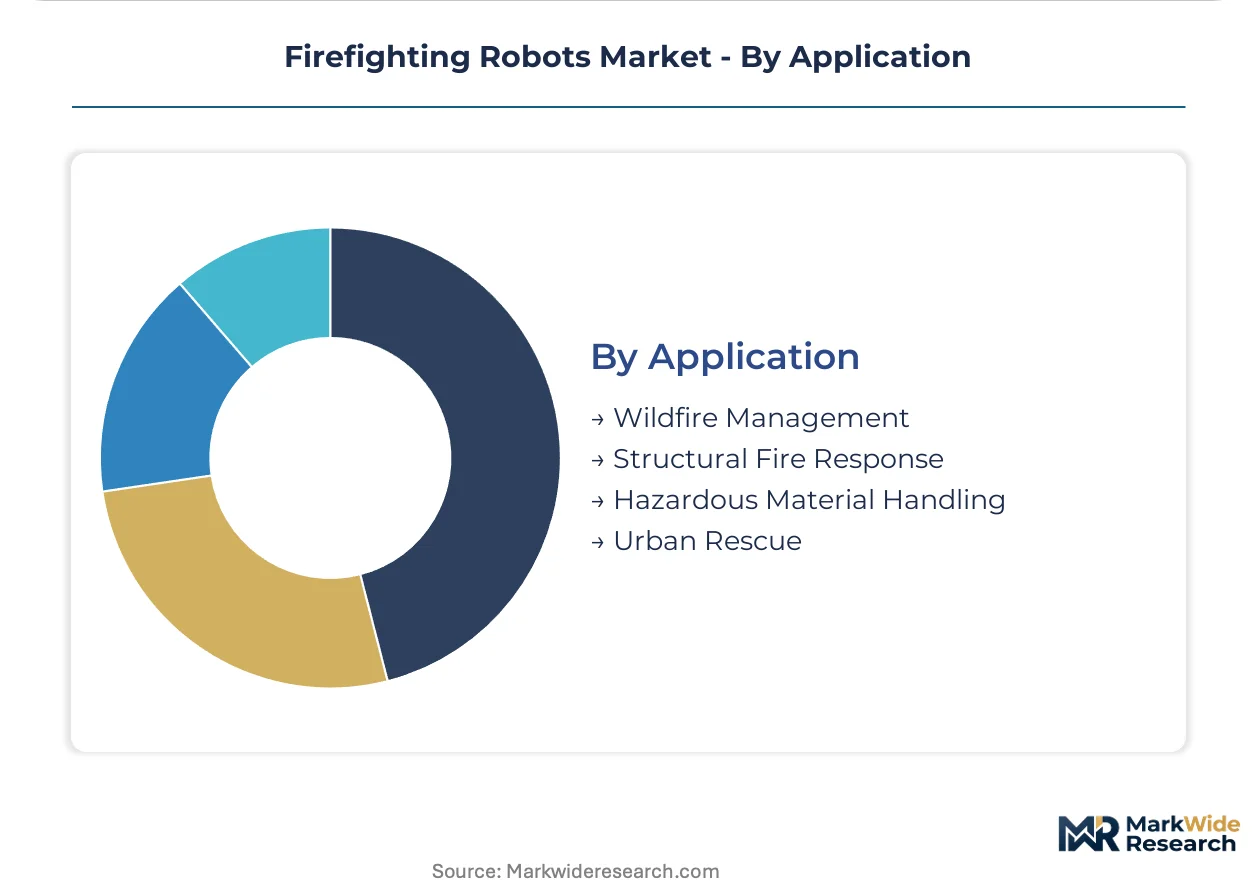
Firefighting robot procurement splits across four structural dimensions that determine payload specifications, thermal tolerance ratings, and operator training requirements. Each segmentation axis carries distinct margin profiles and certification pathways that reshape vendor product roadmaps.
Product Type:
Physical form factor determines mobility constraints, suppressant capacity, and deployment logistics across municipal and industrial buyers.
- Ground Robots:Tracked or wheeled platforms engineered for stair climbing and debris traversal while carrying 500+ liter suppressant payloads. German fire departments under EU MDR certification drive concentrated procurement for structural response scenarios.
- Autonomous Drones:Aerial platforms equipped with thermal cameras and limited water-drop capacity for reconnaissance and perimeter mapping. Demand clusters in Australian forestry services for wildland-urban interface monitoring where ground access fails.
- Water-Throwing Robots:Stationary or slow-moving units with high-pressure nozzle arrays for fixed-installation industrial protection. Japanese petrochemical facilities under METI directives anchor adoption for tank farm cooling operations.
- Surveillance Robots:Lightweight platforms prioritizing thermal scanning duration over suppression capability. California fire districts purchase for post-extinguishment hotspot detection with thinner municipal budgets.
Ground robots hold installed capacity. Autonomous drones are rotating up the share rankings.
Technology:
Control architecture sophistication separates premium autonomous systems from cost-optimized remote-operated units.
- AI Integration:Sensor fusion algorithms enabling real-time hotspot classification and nozzle positioning without continuous operator input. Japanese semiconductor fabrication sites under METI funding represent the steepest expansion trajectory for unsupervised industrial deployment.
- Sensor Technology:Infrared-LiDAR fusion systems that map thermal gradients through smoke opacity exceeding human visibility limits. EU MDR certification requirements for autonomous emergency equipment mandate specific accuracy thresholds for municipal procurement eligibility.
- Remote Control:Tethered or radio-linked operation maintaining human-in-the-loop decision authority for liability-sensitive deployments. Training organizations in Germany favor this architecture for certification curricula.
- Fire Suppression Systems:Modular payload architectures accommodating water, foam, or chemical agents with quick-swap mechanisms. Industrial facilities specify these for multi-hazard chemical cluster zones.
Remote control retains volume leadership. AI integration is climbing the fastest.
End User:
Buyer category determines procurement authority, budget cycle timing, and regulatory compliance scope.
- Industrial Facilities:Petrochemical, semiconductor, and chemical manufacturing sites with captive emergency response teams. Japan's METI funding accelerates AI-integrated suppression procurement for automated facility protection.
- Fire Departments:Municipal and regional authorities with standardized equipment replacement cycles. EU MDR CE marking creates procurement clarity for German, French, and Italian departments.
- Military:Defense agencies requiring defense-grade ruggedization for explosive ordnance disposal and aircraft hangar protection. QinetiQ Group competes through extreme thermal condition specifications.
- Training Organizations:Academies and certification bodies developing operator curricula for emerging autonomous platforms. German vocational institutes anchor demand for remote-control training units.
Fire departments hold installed capacity. Industrial facilities are gaining share fastest.
Application:
Incident type dictates robot mobility requirements, thermal shielding specifications, and suppressant delivery methods.
- Structural Fire Response:Interior navigation through compromised buildings with falling debris and flashover risk. Ground robots with ceramic composite shielding rated for 800°C sustained exposure dominate German municipal procurement.
- Wildfire Management:Extended perimeter operations across uneven terrain with limited water access. Surveillance-class robots with extended thermal scanning duration open demand from Australian forestry services.
- Hazardous Material Handling:Chemical spill containment and vapor suppression without human exposure to toxic atmospheres. Industrial facilities specify these for regulatory compliance with national safety standards.
- Urban Rescue:Collapsed structure penetration requiring compact form factors and tactile sensor feedback. Current manipulator architectures remain technically limited for improvised tool deployment scenarios.
Structural fire response holds installed capacity. Wildfire management is rotating up the share rankings.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Municipal fire departments and industrial facility operators concentrate procurement across five national markets where regulatory frameworks and hazard profiles create distinct equipment specifications. Each geography shapes vendor access through divergent certification requirements and funding mechanisms.
United States
Wildland-urban interface districts in California and Colorado drive surveillance-robot procurement for extended thermal scanning after major wildfire events. The FAA coordinates with NHTSA on certification pathways for aerial platforms that transit between state jurisdictions, creating fragmented compliance timelines. Los Angeles County Fire Department operates mixed fleets combining ground units for structural response with drones for canyon perimeter monitoring.
Germany
North Rhine-Westphalia's chemical cluster zones anchor demand for AI-integrated suppression systems with documented human-override latency specifications. EU MDR CE marking requirements for autonomous emergency equipment accelerate replacement cycles for legacy remotely operated vehicles in municipal departments. Berlin and Hamburg fire authorities specify ceramic composite shielding rated for 800°C sustained exposure in their procurement tenders.
Japan
Semiconductor fabrication sites in Kyushu and petrochemical complexes in Chiba prefecture generate concentrated demand under METI funding directives for automated facility protection. The country's national industrial safety regulator mandates performance benchmarks for AI-integrated industrial safety systems that exceed municipal fire department specifications. Osaka-based training organizations develop curricula for single-operator multi-robot control architectures.
Australia
Forestry services in New South Wales and Victoria purchase surveillance-class robots with extended thermal scanning duration for post-extinguishment hotspot detection in eucalyptus forest zones. The country's national safety standards for autonomous emergency response equipment emphasize perimeter monitoring capabilities over suppressant payload capacity. Queensland fire districts experiment with mixed fleet deployments during extended dry seasons.
India
State-level factory inspectorates under the CEA draft compulsory automated response requirements for chemical cluster zones in Gujarat and Maharashtra. The Bureau of Indian Standards develops performance benchmarks for high-temperature operational thresholds that align with EU MDR specifications. Reliance-operated Jamnagar refinery complex pilots autonomous extinguishing platforms for tank farm cooling operations.
Firefighting Robots Market Vendor Landscape
Channel-controlling players compete with product-specialist players across procurement tiers defined by certification complexity and thermal performance specifications. The vendor base stratifies between defense-grade ruggedization specialists and compact-form-factor innovators. Three archetypes dominate: aerospace heritage conglomerates leveraging sensor integration capabilities, defense contractors applying extreme-environment specifications, and urban-mobility specialists optimizing for collapsed-structure penetration. Competitive moves center on strategic partnerships for multi-jurisdiction certification acceleration and portfolio diversification into surveillance-class platforms with thinner suppressant payloads.
Among defense-grade specialists, QinetiQ Group and Howe & Howe Technologies occupy positions where extreme thermal condition specifications anchor municipal and military procurement eligibility. Shark Robotics exemplifies the compact-form-factor archetype, while Mitsubishi Heavy Industries represents aerospace heritage players applying high-precision positioning systems to ground robot navigation. These three companies illustrate how vendor origin—British defense contracting, American rugged-terrain engineering, French urban-mobility optimization, and Japanese aerospace conglomerate structure—shapes accessible procurement channels without requiring identical certification pathways.
| Leading Market Players |
|---|
| Mitsubishi Heavy Industries |
| EmiControls |
| Howe & Howe Technologies |
| QinetiQ Group |
| Vimal Fire Controls |
| Shark Robotics |
| Angatec |
| LeoTronics Robotics |
| DOK-ING d.o.o. |
| Others |
Supply Flow & Price Mechanics
The Shanghai-Rotterdam maritime corridor shapes cost dynamics for ceramic composite shielding and high-density battery cells, concentrating supply-side leverage among East Asian manufacturers while forcing European OEMs to absorb freight volatility into tiered equipment pricing.
Pricing Analysis
Cost-plus contracts with lithium carbonate indexation dominate procurement for thermal protection systems, separating premium autonomous units with EU MDR certification from standard remote-operated platforms. Price differentiation hinges on CE marking tier and suppressant payload capacity, with municipal fire departments in Germany exhibiting highest sensitivity to consumables replacement costs. Cost compression in the surveillance-robot tier intensifies because California forestry services prioritize thermal scanning duration over suppression capability. Industrial facilities under Japan METI funding show least price sensitivity due to per-deployment subscription models shifting capital expenditure to operational budgets.
Supply Chain Analysis
Upstream ceramic fiber feedstock concentrates in Japan, Germany, and the United States, while lithium-ion cell manufacturing anchors in South Korea, China, and Japan. Robot OEMs draw from aerospace-grade sensor suppliers and defense-tier ruggedization specialists, creating multi-tier component sourcing. Single-source vulnerability for 800°C-rated battery management systems exposes vendors to export control friction. Distribution runs through municipal procurement frameworks in Europe, direct industrial sales in Asia-Pacific, and mixed fleet integrators in North American wildland districts.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Firefighting robots represent high-growth equipment disruption as EU AI Act risk classifications force algorithm rearchitecture for municipal eligibility, compressing vendor development cycles and reshaping competitive positioning.
For Market Incumbents: Insulate core positioning through backward integration into ceramic composite shielding production and captive certification consulting capabilities. Defense-grade ruggedization specialists face margin pressure from compact-form-factor entrants penetrating urban search-and-rescue gaps. Priority lever rests on accelerating multi-jurisdiction certification timelines through strategic partnerships with German notified bodies and Japanese industrial safety regulators. For New Entrants and Emerging Players: Build out surveillance-class platform portfolios targeting Australian forestry services and California wildland-urban interface districts where suppressant payload requirements are thinnest. White-space concentrates in perimeter monitoring applications with extended thermal scanning duration. Go-to-market angle emphasizes per-deployment pricing models that shift municipal capital expenditure to operational budgets. For Investors and Strategic Acquirers: Mid-cycle technology positioning favors sensor fusion middleware developers over hardware-locked OEMs, as virtualization between operator supervision and autonomous execution captures recurring software revenue. Long-term viability across the projection horizon hinges on regulatory compliance automation capabilities. Acquisition target archetype includes AI-integrated suppression algorithm developers with documented human-override latency specifications. Signal to watch is EU AI Act conformity assessment backlog duration as inflection indicator for certification-constrained supply.| Strategic Initiative | Industry Significance |
|---|---|
| EU MDR Certification Acceleration | CE marking pathways for autonomous emergency equipment compress German municipal procurement cycles. |
| AI-Integrated Suppression Development | Sensor fusion algorithms reduce operator cognitive load during multi-unit deployments. |
| Perimeter Surveillance Extension | Thin-payload thermal scanning opens Australian forestry and California wildland demand. |
| Ceramic Composite Backward Integration | In-house shielding production mitigates single-incident replacement cost uncertainty. |
| Service Contract Unbundling | Separate hardware, software maintenance, and incident-response tiers shift municipal budgeting. |
Methodological Framework
Demand-side practitioners and supply-side operators were both consulted through structured primary interviews with municipal fire chiefs, industrial safety officers, robot OEM product managers, and certification body technical assessors. Secondary validation drew from EU MDR technical documentation, METI funding directive filings, FAA-NHTSA coordination protocols, and customs trade data for thermal protection material flows. Bottom-up unit economics triangulated against top-down addressable market sizing across product type, technology, end user, and application dimensions.
Calibration against historical procurement volumes in Germany, Japan, and California anchored growth trajectory assumptions across the analysis window. Segmentation modeling incorporated physical form factor, control architecture sophistication, buyer category procurement authority, and incident type mobility requirements. CAGRs derived from regression analysis of replacement cycle compression and regulatory mandate acceleration. Industry-specific inputs included EU AI Act risk-tier classification timelines and lithium-ion battery supply concentration indices.
The forecast holds incumbent behavior within observed patterns; aggressive capacity expansion by South Korean battery manufacturers or accelerated EU MDR mutual recognition agreements would shift outcomes beyond modeled ranges. Cross-checking against municipal fire department capital expenditure surveys and industrial facility automation investment benchmarks is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Robotics and Automation
SCARA Robots Market
Robotics and Automation
Non-Medical Biomimetic Robots Market
Robotics and Automation
Europe Data Center Robotics Market
Robotics and Automation
Telepresence Robot Market
Robotics and Automation
Global Automotive Gesture Recognition System Market
Robotics and Automation
Harvesting Robot Market
Robotics and Automation
Gimbal Stabilizers Market
Robotics and Automation
Robotic Flexible Washer Market
Robotics and Automation
North America Automated Liquid Handling Market
Robotics and Automation
Global Machine Vision and Vision Guided Robotics Market
Robotics and Automation
Disinfectant Robot Market
Robotics and Automation
Commercial Service Robotics Market
Robotics and Automation
Asia-Pacific AUV and ROV Market
Robotics and Automation
Rotary Gripper Module Market
Robotics and Automation
Africa Agricultural Robots and Mechatronics Market
Robotics and Automation
Mobile Robot Charging Station Market