
 AGV & AMR in Logistics Market | 2026-2036
AGV & AMR in Logistics Market Size, Share, and Industry Trends Forecast 2026-2036
AGV & AMR in Logistics Market Insights
Robot-as-a-service subscription models is restructuring capital deployment across warehouse automation, shifting customers from equipment ownership to per-pick pricing. Geek+ leverages its Beijing manufacturing base to sustain cost advantages in high-volume AMR production. Locus Robotics anchors its position through cloud-based fleet management software that integrates with existing warehouse management systems. Mobile Industrial Robots competes by specializing in collaborative AMR platforms designed for mid-size facilities without infrastructure modification.
AGV and AMR systems in logistics encompass autonomous material-handling vehicles that navigate facilities using lidar, computer vision, or magnetic guidance without human drivers, typically operating at speeds up to 2 meters per second with payload capacities ranging from 50 kilograms to several tons for industrial towing applications. These systems execute put-away, picking, and transport functions to reduce labor dependency and increase throughput consistency in distribution environments. Autonomous Mobile Robots lead technology investment as lidar and AI-based navigation displace fixed-guidepath AGV installations in greenfield warehouses. E-commerce end users represent the fastest-growing demand pool as same-day delivery commitments force fulfillment centers to maximize pick rates per labor hour. On-premises deployment dominates current installations, though cloud-based fleet orchestration is gaining traction among multi-site operators seeking centralized traffic management across distributed warehouses.
The EU Machinery Directive and CE marking requirements govern safety validation for mobile robots operating in European logistics facilities, while OSHA workplace safety standards shape American deployment protocols around human-robot collaboration zones. China's MIIT issues GB standards for industrial autonomous vehicles that affect import qualification and local certification timelines for foreign suppliers. Japan's METI promotes next-generation logistics through JIS standards and demonstration projects that accelerate AMR adoption in aging warehouse workforces. Stakeholders must monitor regulatory divergence between jurisdictions as compliance fragmentation threatens to complicate platform standardization and cross-border fleet deployment strategies.
Market Dynamics
The transition from fixed magnetic tape guidance to lidar-based simultaneous localization and mapping is compressing infrastructure requirements and reshaping competitive differentiation among warehouse automation providers.
Growth Catalysts
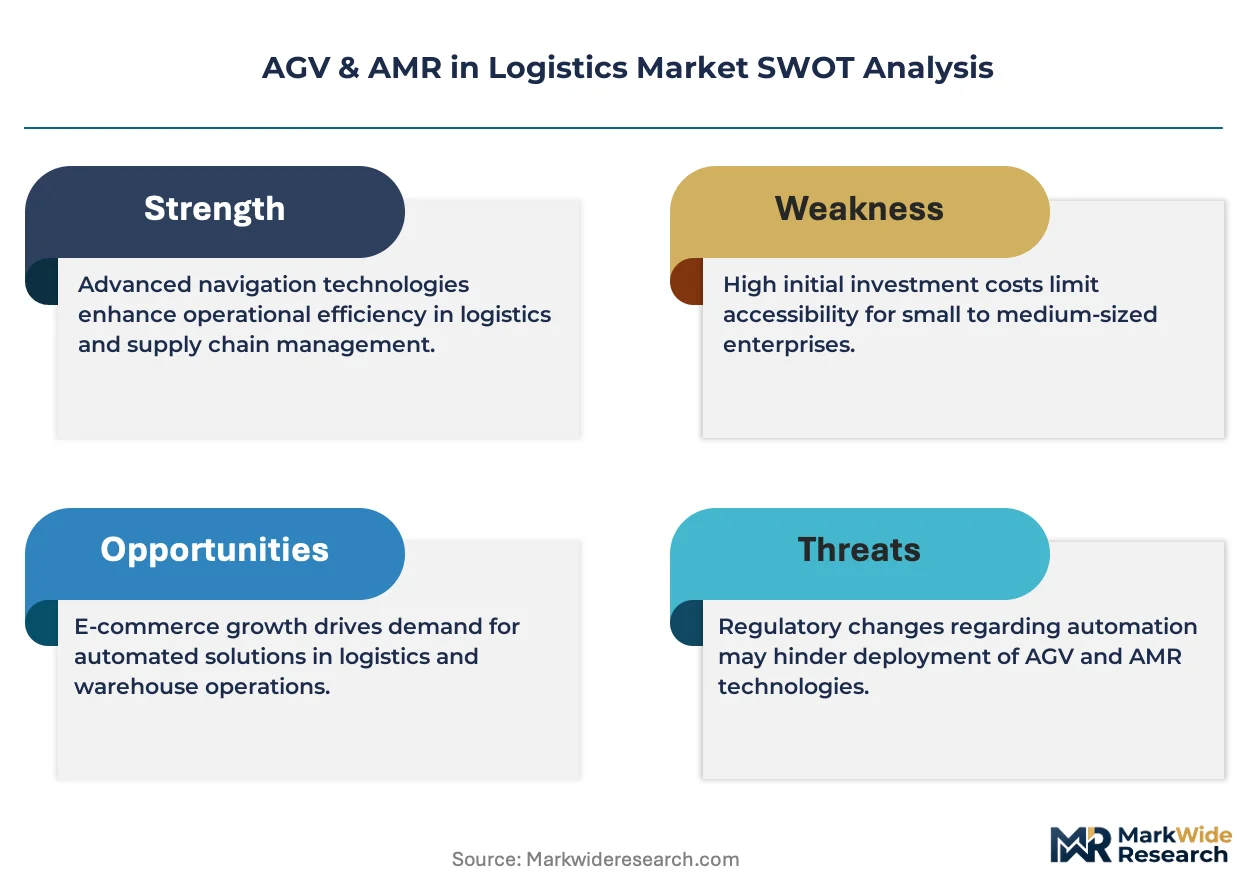
- EU AI Act compliance mandates:European logistics operators face accelerated replacement timelines for legacy AGV fleets to satisfy algorithmic transparency and risk classification requirements.
- Same-day fulfillment velocity:E-commerce distribution centers deploy AMR swarms to compress pick-to-pack cycle times below two-hour windows for metropolitan delivery commitments.
- Lidar cost deflation:Solid-state sensor manufacturing scale from automotive ADAS programs is reducing per-unit navigation hardware costs for mid-size warehouse operators.
Market Restraints
- Lithium-ion cell supply concentration:Battery pack procurement depends on Chinese cathode material refining capacity, exposing fleet operators to export control volatility.
- CE marking timeline friction:Machinery Directive conformity assessment for collaborative speed and separation monitoring extends European deployment schedules by four to six months.
- Fixed infrastructure AGV installed base:Sunk capital in magnetic tape and QR-code navigation systems creates substitution resistance among brownfield facilities.
Strategic Opportunities
- India warehouse automation:Third-party logistics providers in Mumbai and Delhi NCR face labor availability constraints that favor AMR pilot programs over conventional mechanization.
- Pharmaceutical cold chain validation:Temperature-controlled AMR platforms with continuous data logging address GDP compliance for vaccine distribution hubs.
- Cloud-native fleet orchestration:Multi-site operators centralize traffic management and predictive maintenance across distributed warehouses through API-first software architectures.
Industry Challenges
- Mechatronics technician scarcity:Maintenance organizations struggle to recruit personnel proficient in both mechanical drive systems and ROS-based software diagnostics.
- WMS integration complexity:Proprietary communication protocols between AMR middleware and legacy warehouse management systems require custom engineering for each deployment.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | AGV & AMR in Logistics Market |
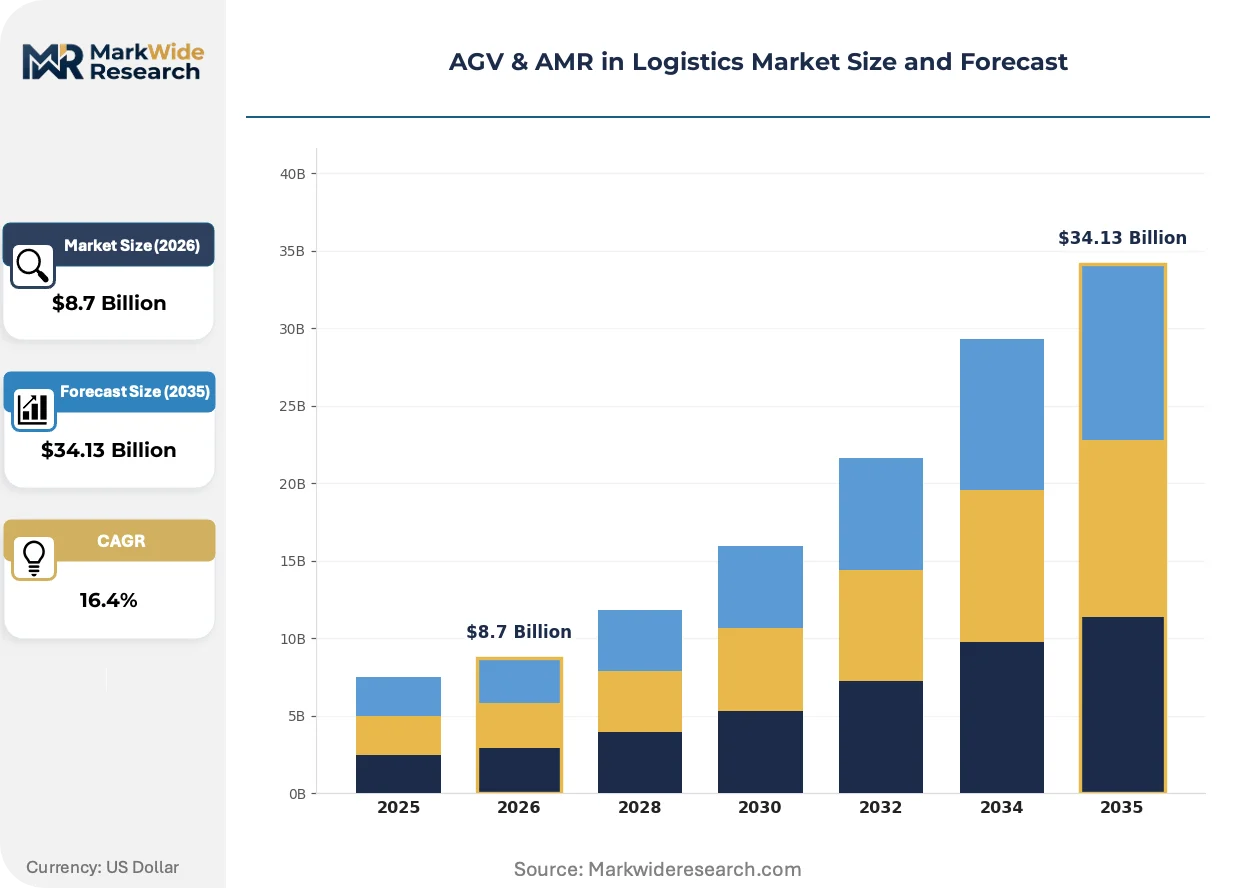
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $34.13 Billion |
| CAGR (2026 – 2036) | 16.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Automated Guided Vehicles, Autonomous Mobile Robots, Tow Tractors, Delivery Robots End User: E-commerce, Warehousing, Manufacturing, Retail Technology: Lidar, Computer Vision, RFID, AI Deployment: On-premises, Cloud-based, Hybrid, Edge Computing |
| Companies Covered | Amazon Robotics, Geek+, Locus Robotics, Fetch Robotics, Mobile Industrial Robots, KUKA, Omron, Dematic, Quicktron, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
AGV & AMR in Logistics Market Trends and Innovations
Navigation autonomy, energy density, and fleet coordination software are converging to enable human-robot collaboration zones that were technically infeasible five years ago.
Lidar-vision fusion perception stacks are integrating depth sensing with semantic segmentation to identify transient obstacles like pallet jacks and human pedestrians without facility modifications. Grocery distribution centers in the Netherlands and apparel fulfillment operations in South Korea deploy these systems at fleet scales exceeding 500 units per site. The technology is integrating predictive path planning that anticipates congestion 30 seconds ahead, compressing inter-aisle transit time variability.
The EU Machinery Directive's 2023 amendment on collaborative robot speed and separation monitoring is forcing redesigns of safety-rated monitored stop functions. Manufacturers must demonstrate fault-tolerant braking systems through third-party notified body assessment. German automotive parts distributors and French pharmaceutical wholesalers face the steepest compliance costs due to high-density human-robot interaction environments.
Robot-as-a-service contracting is displacing capital purchase models for mid-size facilities with annual throughput below 10 million picks. Third-party logistics providers in the United Kingdom and contract packaging operations in the United States favor per-pick pricing that transfers fleet utilization risk to vendors. This shift concentrates bargaining power with multi-site operators capable of standardizing equipment specifications across 10 or more warehouses.
AGV & AMR in Logistics Market Segmentation
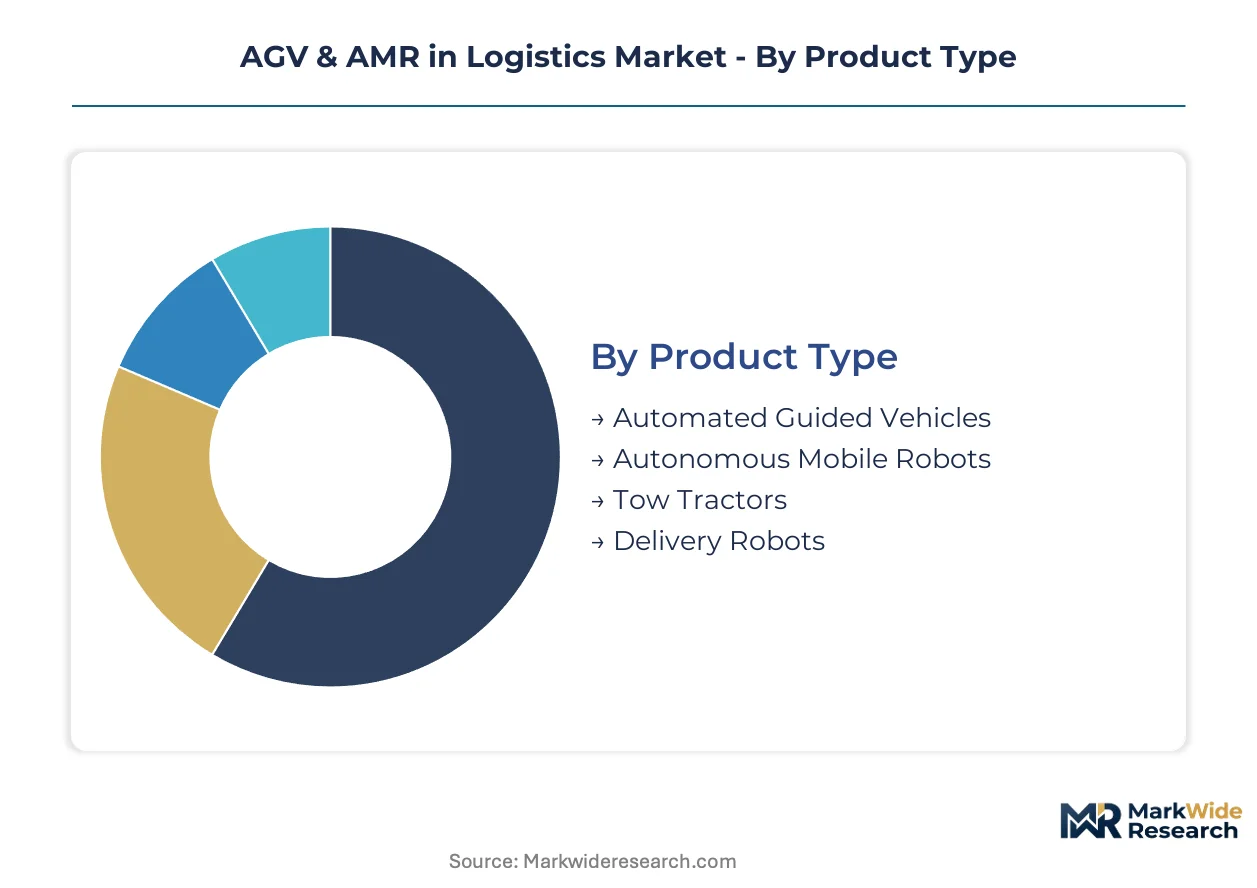
Segmentation reveals how navigation autonomy, payload scale, and fleet orchestration architecture drive purchasing decisions across logistics environments. Each dimension exposes distinct integration pathways from standalone equipment to deeply embedded warehouse systems.
Product Type:
Standalone platforms dominate brownfield retrofit budgets, while embedded AMR swarms reshape greenfield facility design from the ground up.
- Automated Guided Vehicles:Magnetic tape or QR-code guidance systems execute repetitive point-to-point transport along fixed routes. German automotive parts distributors and Japanese electronics manufacturers maintain these installations for predictable high-volume lanes where infrastructure modification costs are already sunk.
- Autonomous Mobile Robots:Lidar-based SLAM navigation enables dynamic path planning without facility modifications. E-commerce fulfillment centers in the Netherlands and South Korea deploy fleet scales exceeding 500 units per site to compress pick-to-pack cycle times below two-hour windows.
- Tow Tractors:Industrial-grade platforms pull cart trains up to several tons across manufacturing campuses and distribution yards. Food and beverage distributors in France leverage these for inter-building material flow where outdoor traversal meets indoor precision docking.
- Delivery Robots:Compact last-mile units navigate sidewalks and building lobbies for parcel handoff. Pilot programs in Dubai and Singapore test regulatory frameworks for autonomous vehicle operation in public pedestrian spaces.
Automated Guided Vehicles lead volumes today; Autonomous Mobile Robots are gaining share fastest.
End User:
Cost tier separation runs from capital-intensive manufacturing integration to variable-cost-per-pick logistics services.
- E-commerce:Same-day delivery commitments force fulfillment centers to maximize pick rates per labor hour through AMR swarm coordination. Amazon, Alibaba, and regional platforms drive fleet-scale procurement with per-pick pricing models.
- Warehousing:Third-party logistics providers face labor availability constraints that favor flexible automation over fixed mechanization. Mumbai and Delhi NCR operators pilot AMR programs to avoid conventional conveyor investments.
- Manufacturing:Just-in-time assembly lines require synchronized material delivery to production cells. Automotive plants in Germany and electronics factories in China embed AGVs into synchronized production scheduling systems.
- Retail:Back-of-store inventory movement and click-and-collect order consolidation demand compact platforms. Grocery chains in the United Kingdom deploy these for overnight shelf replenishment and online order assembly.
E-commerce commands the steepest expansion trajectory; Warehousing offers the broadest addressable facility base.
Technology:
Maturity gradients separate proven navigation hardware from emerging perception stacks still undergoing safety validation.
- Lidar:Solid-state sensor manufacturing scale from automotive ADAS programs reduces per-unit costs for mid-size warehouse operators. Dutch grocery distribution centers deploy these for centimeter-precision localization in narrow aisles.
- Computer Vision:Semantic segmentation identifies transient obstacles like pallet jacks and human pedestrians without facility modifications. South Korean apparel fulfillment operations integrate predictive path planning that anticipates congestion 30 seconds ahead.
- RFID:Tag-based localization supplements navigation in high-density storage zones where line-of-sight sensors face occlusion. Pharmaceutical cold chain facilities combine RFID with continuous temperature logging for GDP compliance.
- AI:Fleet learning algorithms optimize traffic patterns across distributed warehouses through cloud-native orchestration. Multi-site operators centralize predictive maintenance and dynamic task allocation through API-first software architectures.
Lidar anchors current installations; AI is climbing the fastest as fleet intelligence becomes the primary vendor differentiator.
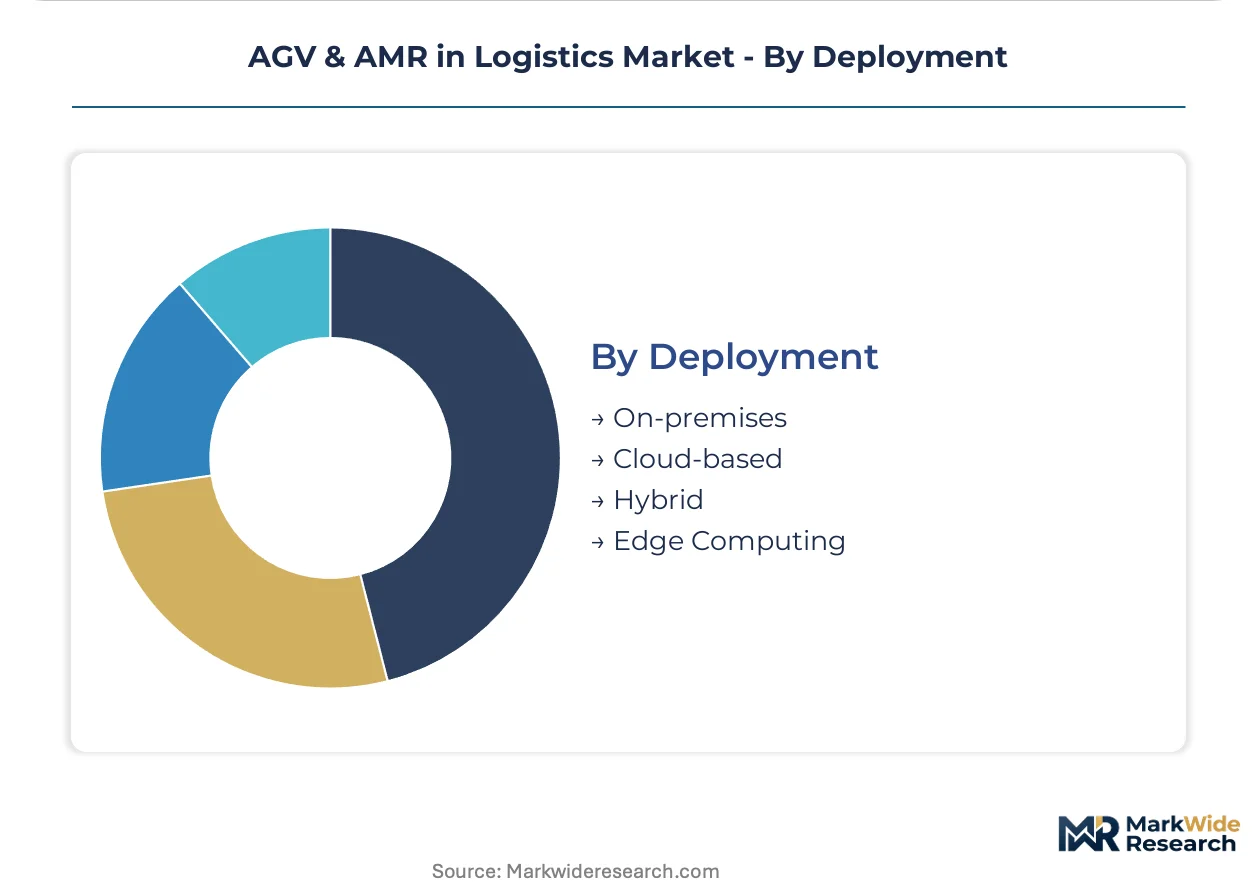
Deployment:
Customer type splits between security-conscious single-site operators and agility-seeking multi-site networks.
- On-premises:Local server infrastructure maintains data sovereignty and minimizes latency for safety-critical stop functions. German automotive parts distributors favor this model for CE marking compliance with Machinery Directive requirements.
- Cloud-based:Centralized fleet orchestration enables traffic management across 10 or more warehouses with standardized equipment specifications. United Kingdom third-party logistics providers transfer utilization risk to vendors through per-pick contracting.
- Hybrid:Edge processing handles real-time navigation while cloud layers manage analytics and optimization. French pharmaceutical wholesalers balance latency-sensitive safety systems with centralized operational visibility.
- Edge Computing:On-vehicle processing eliminates network dependency for autonomous decision-making. Japanese aging warehouse workforces benefit from reduced IT infrastructure complexity in METI-promoted demonstration projects.
On-premises deployment leads volumes today; Cloud-based architectures are expanding most quickly among multi-site standardization programs.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany deploys fleet-scale AMR installations at automotive parts distributors, while the United States concentrates demand among e-commerce fulfillment operators seeking per-pick pricing models. China leverages manufacturing scale advantages for high-volume production. Japan addresses aging warehouse workforces through METI-promoted demonstration projects.
Germany
Automotive parts distributors and third-party logistics providers drive fleet-scale autonomous vehicle procurement. The EU Machinery Directive and CE marking requirements govern safety validation for collaborative speed and separation monitoring. Stuttgart and Munich clusters host high-density human-robot interaction environments where fault-tolerant braking systems undergo third-party notified body assessment.
United States
E-commerce fulfillment centers deploy AMR swarms to compress pick-to-pack cycle times below two-hour windows for metropolitan delivery commitments. OSHA workplace safety standards shape deployment protocols around human-robot collaboration zones. California and Texas distribution hubs lead cloud-based fleet orchestration adoption among multi-site operators seeking centralized traffic management.
China
Beijing manufacturing bases sustain cost advantages in high-volume AMR production for domestic and export markets. MIIT issues GB standards for industrial autonomous vehicles affecting import qualification and local certification timelines. Yangtze River Delta electronics factories embed AGVs into synchronized production scheduling systems for just-in-time assembly lines.
Japan
Aging warehouse workforces accelerate AMR adoption in logistics networks facing labor availability constraints. METI promotes next-generation logistics through JIS standards and demonstration projects reducing IT infrastructure complexity. Kanto and Kansai regions deploy edge computing platforms eliminating network dependency for autonomous decision-making in METI-sponsored pilots.
Netherlands
Grocery distribution centers deploy lidar-vision fusion perception stacks at fleet scales exceeding 500 units per site. The EU AI Act mandates algorithmic transparency and risk classification requirements accelerating replacement timelines for legacy AGV fleets. Rotterdam and Amsterdam logistics corridors integrate predictive path planning that anticipates congestion 30 seconds ahead.
AGV & AMR in Logistics Market Competitive Landscape
Branded specialists and contract manufacturers split share differently across segments, with robotics-as-a-service providers capturing mid-size facilities while integrated automation vendors retain automotive and heavy manufacturing accounts. The vendor landscape organizes around three archetypes: cloud-native fleet orchestration platforms, hardware-focused AMR fabricators with captive manufacturing, and traditional AGV incumbents defending magnetic tape installed bases. Consolidation pressure concentrates among mid-tier players lacking either software differentiation or manufacturing scale. Dominant competitive moves include strategic partnerships between navigation software developers and battery pack suppliers, plus geographic expansion into India and Southeast Asia warehouse automation markets.
Among China-based fabricators, Geek+ and Quicktron occupy positions exemplifying manufacturing-scale archetypes serving high-volume export markets. Locus Robotics represents the cloud-native tier with API-first architectures enabling per-pick contracting models. These three anchors illustrate how competitive positioning diverges between hardware-centric cost leadership and software-defined fleet intelligence.
| Leading Market Players |
|---|
| Amazon Robotics |
| Geek+ |
| Locus Robotics |
| Fetch Robotics |
| Mobile Industrial Robots |
| KUKA |
| Omron |
| Dematic |
| Quicktron |
| Others |
Pricing and Supply Chain Analysis
Mechatronics technician scarcity in Germany and Japan widens pricing-tier spreads between premium CE-marked platforms and economy-grade alternatives lacking certified safety-rated monitored stop functions. Labor-cost differentials between Stuttgart engineering clusters and lower-wage assembly regions in Eastern Europe compress margins for mid-tier hardware fabricators unable to command software-defined fleet intelligence premiums.
Pricing Analysis
Capacity additions in China's Yangtze River Delta are reshaping price floors for lidar-based navigation hardware as solid-state sensor manufacturing scale from automotive ADAS programs reduces per-unit costs. Three-tier pricing structure across premium, standard, and economy levels separates CE-marked collaborative platforms from basic magnetic-tape AGVs and uncertified import alternatives. Cost compression in the economy tier is intensifying because Chinese fabricators leverage Beijing manufacturing bases for high-volume export production. Third-party logistics providers in the United Kingdom and contract packaging operations in the United States exhibit highest price sensitivity through per-pick contracting models, while German automotive parts distributors show lowest sensitivity due to Machinery Directive compliance mandates.
Supply Chain Analysis
Single-source vulnerability sits with Chinese cathode material refining capacity for lithium-ion battery packs, exposing fleet operators to export control volatility and procurement disruption. Component manufacturing draws from China, South Korea, and Japan for solid-state lidar sensors, drive motors, and battery management systems. Raw material dependencies include lithium carbonate, rare-earth permanent magnets, and semiconductor-grade silicon for navigation processors. Tariff exposure runs through cross-border component flows between Chinese fabrication facilities and European assembly operations. Distribution runs through direct OEM sales for large fleet deployments and robotics-as-a-service intermediaries for mid-size facilities.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market reads as a late-cycle quality story as e-commerce fulfillment operators shift procurement criteria from upfront capital cost toward algorithmic transparency and EU AI Act compliance certification.
For Market Incumbents: Extend cloud-native fleet orchestration capabilities through API-first architectures that embed predictive maintenance and dynamic task allocation as sticky switching costs. Deepen backward integration into solid-state lidar sensor supply through partnerships with automotive ADAS programs to defend against Chinese cost leaders. Prioritize CE marking investment and third-party notified body assessment for collaborative speed and separation monitoring to maintain access to German and French high-density human-robot interaction environments. For New Entrants and Emerging Players: Launch via robot-as-a-service subscription models targeting mid-size facilities with annual throughput below 10 million picks in India's Mumbai and Delhi NCR logistics corridors. White-space opportunities sit in pharmaceutical cold chain validation for temperature-controlled AMR platforms with continuous GDP-compliant data logging. Underpenetrated segments include edge computing deployments for Japanese aging warehouse workforces in METI-promoted demonstration projects. For Investors and Strategic Acquirers: Valuations sit cheapest among hardware-focused AMR fabricators lacking software differentiation or captive manufacturing scale relative to cloud-native fleet orchestration platforms. Long-term viability over the next decade hinges on consolidation among mid-tier players unable to bridge either robotics software or battery pack supply capabilities. Acquisition target archetypes include navigation software developers with ROS-based diagnostics expertise and regional system integrators with established WMS middleware relationships. Watch for inflection signals in India warehouse automation pilot program conversion rates from proof-of-concept to fleet-scale deployment.| Strategic Initiative | Industry Significance |
|---|---|
| Cloud-Native Fleet Orchestration | Enables per-pick contracting models that transfer utilization risk from operators to vendors across multi-site networks. |
| Backward Integration into Lidar Supply | Captures cost deflation from automotive ADAS manufacturing scale while reducing dependency on Chinese sensor imports. |
| CE Marking and Notified Body Assessment | Unlocks German and French high-density collaborative environments where Machinery Directive compliance gates market access. |
| Robot-as-a-Service Platform Launch | Addresses capital constraints among mid-size third-party logistics providers through subscription-based equipment access. |
| Pharmaceutical Cold Chain Validation | Captures GDP-compliant vaccine distribution hub demand with temperature logging and continuous data integrity assurance. |
Research Methodology
Coverage spans Germany, the United States, China, Japan, and the Netherlands, with primary inputs from each market's logistics operator ecosystem. The research combines structured interviews with warehouse operations directors, AMR fleet managers, WMS integration specialists, and mechatronics maintenance technicians with secondary validation through customs trade data, SEC filings from publicly traded automation vendors, EU Machinery Directive implementation guidance, and MIIT GB standards documentation. Bottom-up unit deployment estimates triangulate against top-down addressable facility calculations across e-commerce fulfillment, third-party logistics, and manufacturing verticals.
Rate-of-change decomposition separates volume growth from value-per-unit evolution across the projection horizon. Segmentation dimensions modeled include navigation technology autonomy level, payload capacity tier, deployment architecture, and end-use industry concentration. CAGRs derive from logistic curve fitting of technology substitution patterns between fixed-guidepath AGV and lidar-based AMR platforms. Industry-specific forecast inputs incorporate EU AI Act compliance timeline assumptions and lithium-ion cell supply concentration risk factors.
Forecast precision tightens around the base case; tail outcomes carry wider variance under export control disruptions affecting Chinese battery material flows or accelerated Machinery Directive amendments tightening collaborative robot speed thresholds. Forecasts reflect documented assumptions regarding e-commerce same-day delivery commitment penetration rates and automotive just-in-time assembly line reshoring patterns. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Robotics and Automation
Agriculture Robotics Market
Robotics and Automation
Robotic Flexible Washer Market
Robotics and Automation
Latin America Cloud Robotics Market
Robotics and Automation
North America Service Robotics Market
Robotics and Automation
Canada Cloud Robotics Market
Robotics and Automation
Global Entertainment Robots Market
Robotics and Automation
Japan Agricultural Robot Market
Robotics and Automation
Robot Fleet Management Software Market
Robotics and Automation
Consumer Robotics Market
Robotics and Automation
Non-Medical Biomimetic Robots Market
Robotics and Automation
Nanorobots in Healthcare Market
Robotics and Automation
Global Agriculture Robots Market
Robotics and Automation
Europe Articulated Robot Market
Robotics and Automation
GCC AUV Market
Robotics and Automation
Pipetting Robots Market
Robotics and Automation
Asia-Pacific Medical Robots Market