
 North America Robotics and Automation Actuators Market | 2026-2036
North America Robotics and Automation Actuators Market Size, Share, and Industry Trends Forecast 2026-2036
North America Robotics and Automation Actuators Market Analytics
Software-defined maintenance subscriptions is consolidating recurring revenue streams alongside hardware sales in the North America Robotics and Automation Actuators Market. Rockwell Automation leverages its FactoryTalk platform to anchor long-term service contracts across automotive and food-processing installations. Moog specializes in high-performance servo actuation for aerospace and defense applications, sustaining premium positioning through proprietary valve technology. Festo competes in pneumatic and electric actuator systems, extending its reach through distributed automation architectures in packaging and electronics assembly.
Robotics and automation actuators are electromechanical, hydraulic, or pneumatic devices that convert energy into controlled mechanical motion, typically delivering positional accuracy within micrometers and force outputs ranging from newtons to kilonewtons depending on actuator class. These components serve as the primary motion-execution layer in industrial robots, CNC systems, and automated guided vehicles, enabling programmable positioning, force control, and synchronized multi-axis operation. Electric actuators now lead product-type demand as plant electrification targets and energy-efficiency mandates displace hydraulic systems in cleanroom and precision-assembly environments. Smart actuators represent the fastest-growing technology segment, embedding sensors and edge-computing capability that reduces wiring complexity and enables predictive maintenance protocols. Material handling applications anchor volume demand across distribution centers and automotive plants, while robotics applications capture expanding margin pools as collaborative robot deployments accelerate in small and mid-sized manufacturing operations.
NHTSA, OSHA, and the FAA collectively shape product standards and market access for actuators deployed in automotive manufacturing, general industry, and commercial aerospace respectively. NHTSA crashworthiness and functional-safety requirements propagate into robotic welding and assembly systems, while OSHA machine-guarding standards mandate force-limiting and emergency-stop capabilities on collaborative robot actuators. Stakeholders must monitor evolving cybersecurity frameworks for connected smart actuators as operational technology networks converge with enterprise IT infrastructure across North American production facilities.
Market Dynamics
Electrification mandates across automotive and general manufacturing are compressing hydraulic system lifecycles while accelerating servo-electric actuator procurement timelines. Tier-1 suppliers in Michigan and Ontario now specify all-electric motion platforms for new greenfield installations.
Growth Catalysts
- OSHA Machine-Guarding Standards:Force-limiting actuator requirements for collaborative robots are mandating hardware upgrades across automotive and electronics assembly floors.
- Electric Vehicle Assembly Expansion:Battery pack handling and precision cell placement are driving multi-axis linear actuator demand in Detroit and Cleveland manufacturing corridors.
- Smart Actuator Technology:Embedded sensor arrays with edge-computing capability are reducing field wiring costs and enabling condition-based maintenance protocols.
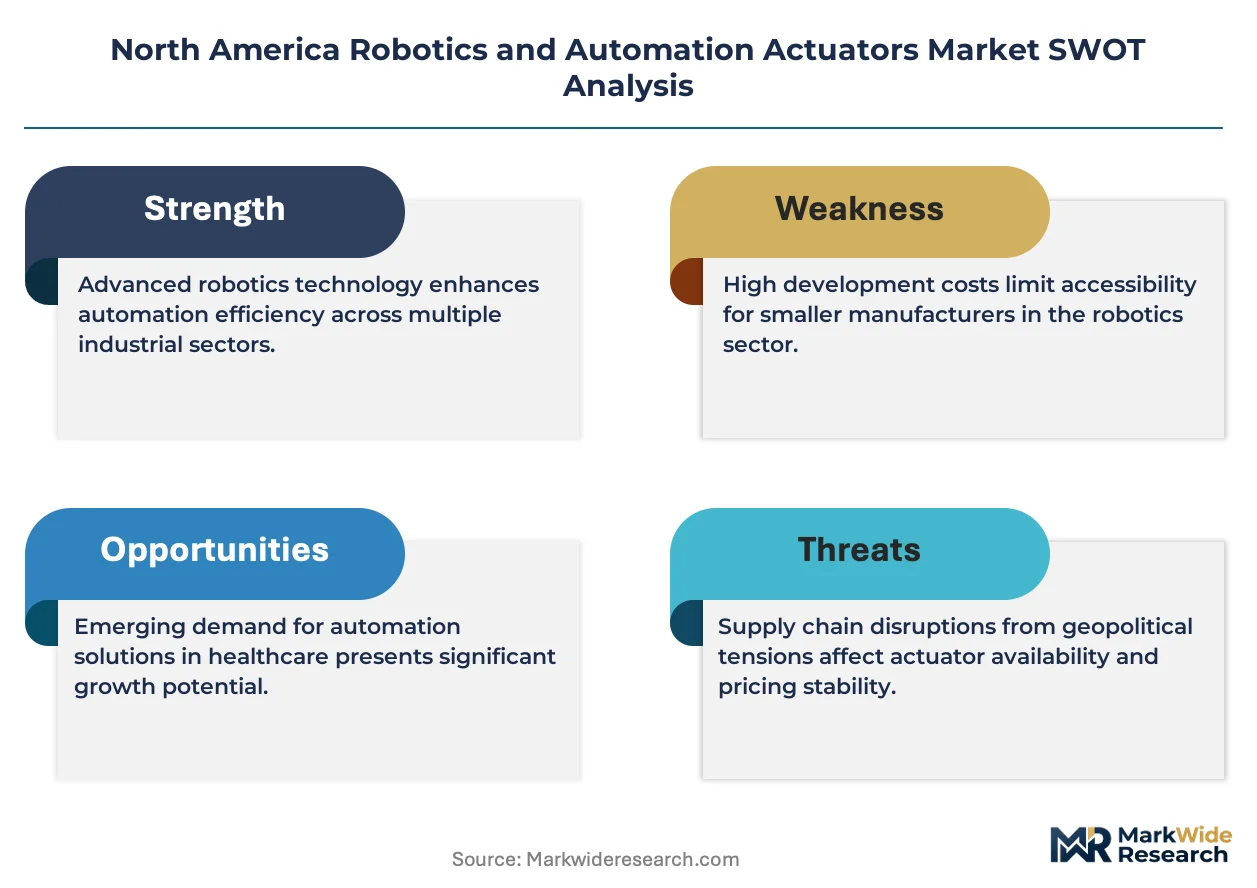
Market Restraints
- Rare Earth Magnet Supply Concentration:Neodymium and dysprosium sourcing dependence on Asian refining capacity creates input cost volatility for high-torque servo motors.
- NHTSA Functional-Safety Certification:Extended validation timelines for automotive welding and assembly actuators delay product commercialization by 8-14 months.
- Pneumatic System Inertia:Existing compressed air infrastructure in legacy plants slows electric actuator conversion despite efficiency advantages.
Strategic Opportunities
- Mexico Manufacturing Corridor:Nearshoring momentum in Querétaro and Nuevo León is creating demand for mid-range electric actuators in automotive supplier parks.
- US Inflation Reduction Act:Clean energy manufacturing tax credits are accelerating actuator procurement for solar panel and battery production equipment.
- Digital Twin Convergence:Physics-based simulation platforms paired with smart actuators are enabling virtual commissioning that reduces installation downtime.
Industry Challenges
- Motion Control Engineering Talent:Shortage of specialists fluent in servo tuning, harmonic drive selection, and safety-rated torque monitoring constrains system integrator capacity.
- Legacy PLC Integration:Retrofitting smart actuators into 1990s-era Rockwell and Siemens control architectures requires custom gateway development and extended commissioning.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | North America Robotics and Automation Actuators Market |
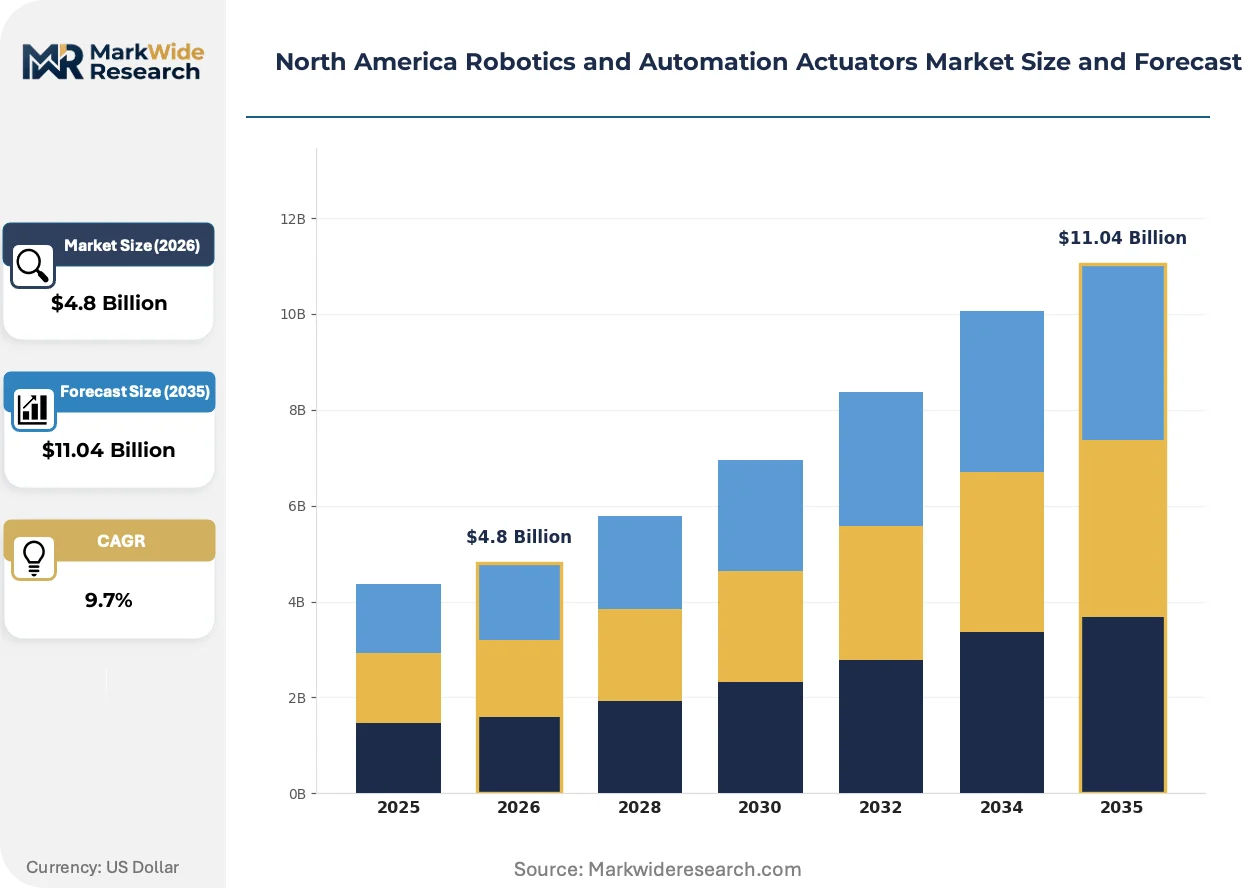
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $11.04 Billion |
| CAGR (2026 – 2036) | 9.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Electric Actuators, Hydraulic Actuators, Pneumatic Actuators, Mechanical Actuators End User: Manufacturing, Healthcare, Automotive, Aerospace Technology: Linear Motion, Rotary Motion, Servo Technology, Smart Actuators Application: Material Handling, Assembly Line, Robotics, Packaging |
| Companies Covered | Rockwell Automation, ABB, Moog, Altra Industrial Motion, Curtiss-Wright Corporation, SMC Corporation, MISUMI Group Inc., Flowserve Corporation, Festo, Others |
| Regions Covered | North America: US, Canada, Mexico |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
North America Robotics and Automation Actuators Market Evolving Landscape
Software-defined motion control is dissolving the boundary between mechanical hardware and digital service layers. Actuator vendors now compete on firmware update cadence and predictive analytics capability rather than torque density alone.
Integrated servo-actuator modules with built-in safety-rated encoders are expanding into collaborative robot joints and precision positioning stages. Medical device manufacturers in Minnesota and Massachusetts are adopting these compact units for diagnostic equipment motion platforms. The consolidation of motor, drive, and controller into sealed IP67 housings is compressing supply chain complexity and reducing cabinet space requirements.
NHTSA functional-safety mandates for automotive manufacturing equipment are propagating ISO 13849 and IEC 62061 compliance requirements into robotic welding actuator specifications. Tier-1 automotive suppliers in Ohio and Michigan now require SIL 2 or PL d certification as a baseline qualification. This regulatory pressure is filtering down to packaging and material handling actuator selections in adjacent industries.
Buyer preference for outcome-based service agreements is displacing traditional hardware-only procurement in high-availability applications. Automotive OEMs in Ontario and Tennessee now specify uptime guarantees and predictive maintenance inclusion rather than capital purchase with separate service contracts. This shift is most visible in continuous welding and paint-shop installations where unplanned downtime costs exceed hardware depreciation.
North America Robotics and Automation Actuators Market Segmentation
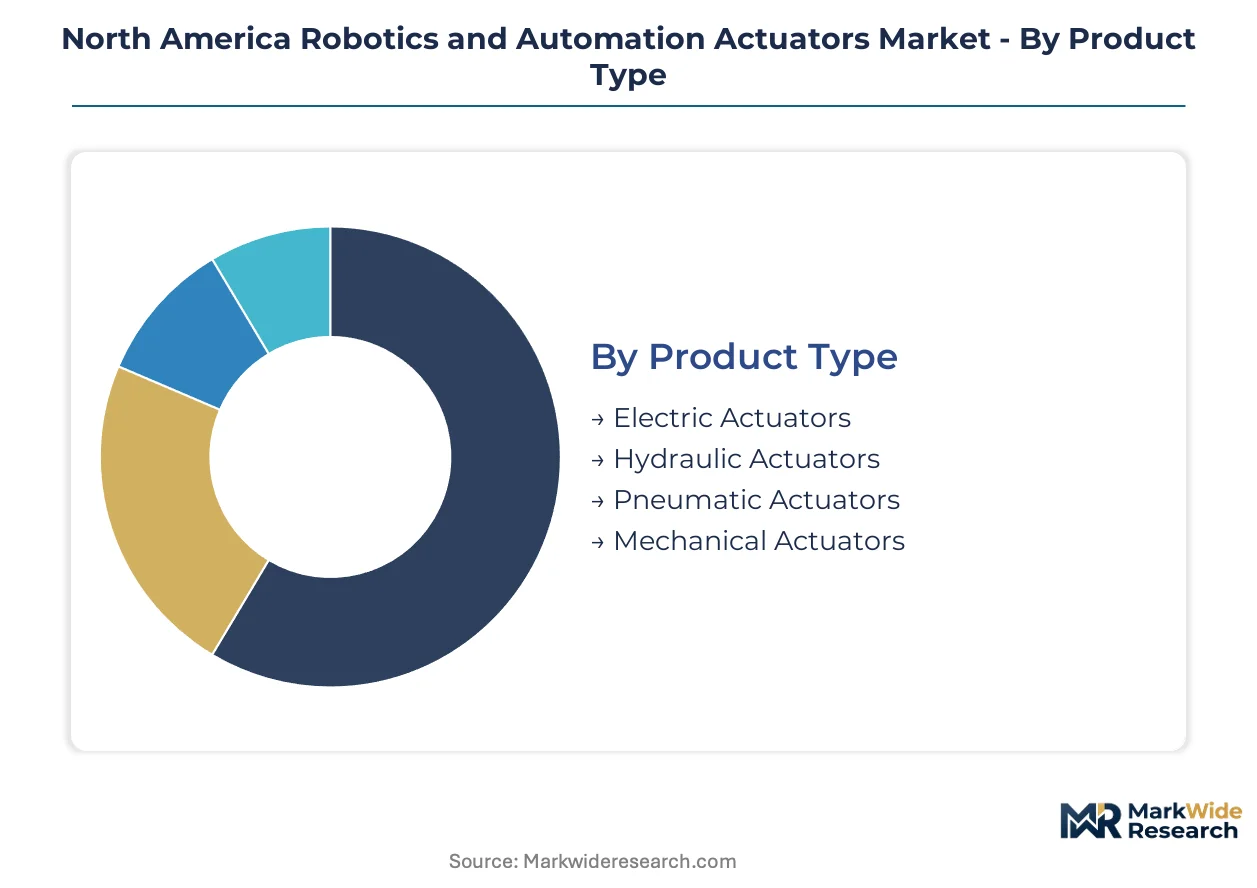
Actuator procurement patterns diverge sharply across product types, end-use sectors, and technology tiers. Capital allocation decisions in the Great Lakes manufacturing corridor reflect these structural divisions, with electrification mandates and NHTSA safety protocols reshaping specification requirements.
Product Type:
Capital intensity varies dramatically across actuator categories, with electric and hydraulic systems demanding the highest upfront engineering investment while pneumatic solutions leverage existing plant infrastructure.
- Electric Actuators:Brushless DC and AC servo motors with integrated drives deliver positional accuracy within micrometers and eliminate hydraulic fluid contamination risks. Battery pack assembly lines in Detroit and Cleveland specify these for cleanroom-compatible motion platforms, though rare earth magnet costs create input price volatility.
- Hydraulic Actuators:High-force fluid-power systems utilizing piston-cylinder architectures generate kilonewton-level outputs for heavy-press and stamping operations. Die-casting facilities in Ontario retain these for force-intensive applications despite electrification pressures, constrained by replacement capital requirements and retraining costs.
- Pneumatic Actuators:Compressed-air cylinders dominate legacy packaging and material handling installations across the Midwest.
- Mechanical Actuators:Screw-jack and cam-based systems persist in low-speed, high-load positioning stages.
Electric actuators absorb the bulk of installed capacity in new greenfield projects; smart electric variants are expanding most quickly as edge-computing integration reduces field wiring complexity.
End User:
Application complexity and regulatory burden shape customer-tier profitability, with aerospace and automotive commanding premium pricing while manufacturing volumes anchor scale economies.
- Manufacturing:General industrial automation spans food processing, electronics assembly, and metal fabrication across Ohio, Michigan, and Tennessee. OSHA machine-guarding compliance for collaborative robot deployments drives actuator replacement cycles in small and mid-sized operations.
- Automotive:Electric vehicle assembly expansion in Detroit, Cleveland, and Toronto concentrates multi-axis linear actuator demand for battery handling and precision cell placement. NHTSA functional-safety certification requirements extend validation timelines and elevate specification standards.
- Healthcare:Surgical robotics and diagnostic imaging platforms in Minnesota and Massachusetts demand compact servo modules with safety-rated encoders.
- Aerospace:Defense and commercial aviation applications in California and Texas require MIL-spec qualification and extended environmental testing.
Manufacturing absorbs the bulk of installed capacity; automotive applications are gaining share fastest as EV production capacity expands across the Great Lakes corridor.
Technology:
Control architecture sophistication determines system integration complexity and maintenance protocol requirements across the technology spectrum.
- Smart Actuators:Embedded sensor arrays with edge-computing capability enable condition-based maintenance and reduce control cabinet footprint. These units are penetrating collaborative robot joints and precision positioning stages as firmware-update cadence becomes a competitive differentiator.
- Servo Technology:Closed-loop motor-drive systems with harmonic drive reduction deliver precise torque and velocity control for CNC and robotic applications. Tier-1 automotive suppliers in Michigan require SIL 2 or PL d certification as baseline qualification.
- Linear Motion:Ball-screw and belt-drive actuators dominate Cartesian coordinate positioning in packaging and material handling.
- Rotary Motion:Direct-drive and geared rotary stages serve indexing and orientation applications across general industry.
Linear motion systems absorb the bulk of installed capacity; smart actuators are climbing the fastest as predictive maintenance protocols displace scheduled replacement.
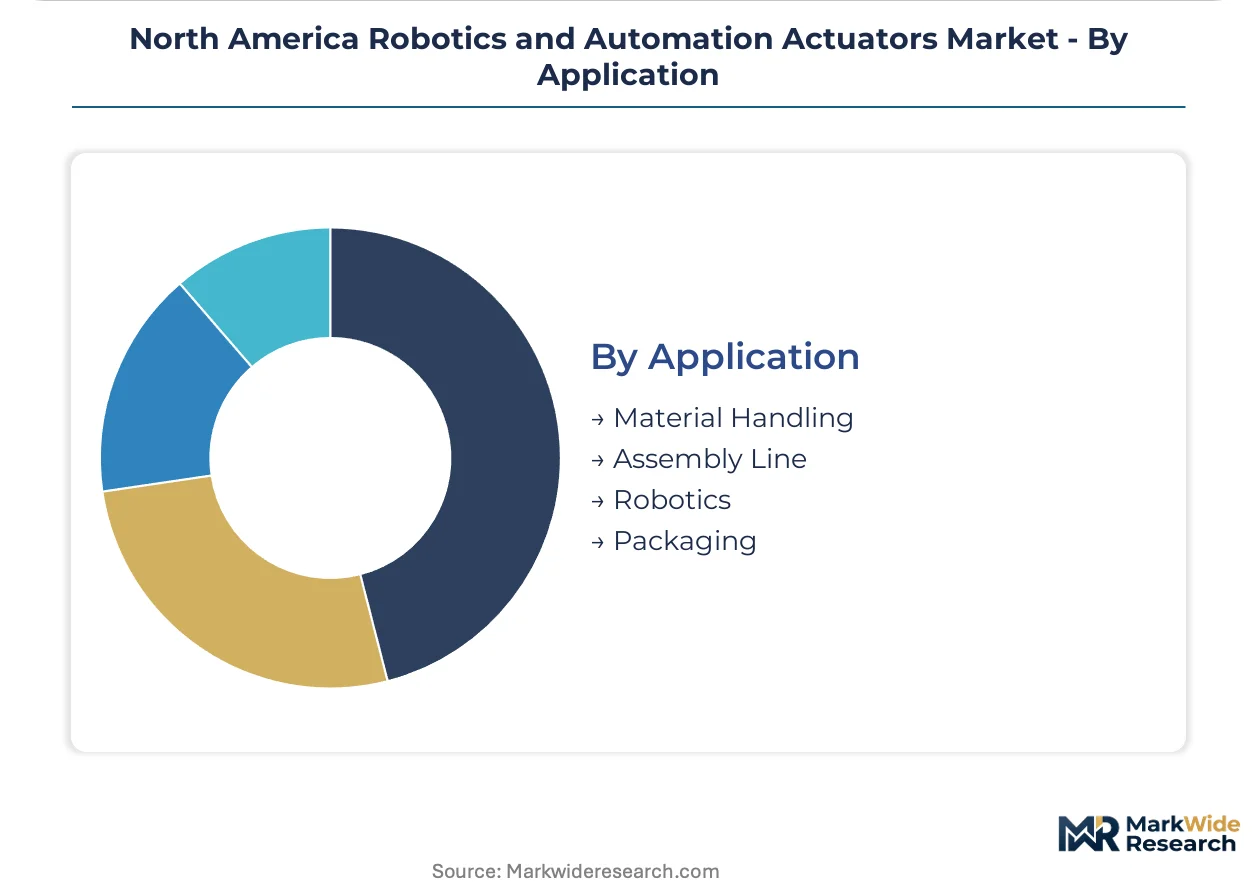
Application:
Throughput requirements and downtime cost exposure create distinct specification tiers across application categories.
- Material Handling:Conveyor transfer, palletizing, and automated storage/retrieval systems in distribution centers and automotive plants constitute the highest-volume application segment. Electric belt-drive actuators are displacing pneumatic cylinders in Amazon and Walmart fulfillment networks.
- Robotics:Articulated arm, SCARA, and collaborative robot joints demand compact, high-torque servo actuators with safety-rated torque monitoring. Small and mid-sized manufacturers in the Midwest are accelerating cobot deployments for machine-tending and assembly tasks.
- Assembly Line:Precision press-fit, welding, and fastening operations require force-controlled motion platforms.
- Packaging:High-speed carton forming, filling, and sealing equipment utilizes pneumatic and electric actuators in food and beverage facilities.
Material handling absorbs the bulk of installed capacity; robotics applications are expanding most quickly as collaborative systems penetrate small-lot manufacturing.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Production concentrates in the Great Lakes industrial corridor while consumption spreads across automotive clusters and emerging nearshoring zones. The United States dominates installed actuator capacity. Canada and Mexico absorb cross-border supply chain spillover.
United States
Electric vehicle battery assembly and NHTSA safety mandates drive actuator procurement across Michigan, Ohio, and Tennessee. OSHA machine-guarding standards for collaborative robots force hardware upgrades in automotive and electronics plants. Detroit and Cleveland manufacturing corridors anchor multi-axis linear actuator demand for precision cell placement.
Canada
Ontario's automotive supplier parks and aerospace testing facilities sustain servo-actuator demand for electric vehicle subassembly. Health Canada equipment certification requirements propagate into medical device actuator specifications. Toronto and Hamilton industrial zones concentrate smart actuator deployments for packaging and material handling.
Mexico
Nearshoring momentum in Querétaro and Nuevo León generates mid-range electric actuator demand for automotive supplier operations. Mexican federal manufacturing incentives under the IMMEX program accelerate greenfield automation investment. The Bajío region and northern border states absorb spillover from US Tier-1 supplier relocation.
North America Robotics and Automation Actuators Market Competitive Landscape
Top-tier vendors anchor premium servo-electric and smart actuator segments, while mid-tier specialists compete on pneumatic legacy compatibility and regional service density. The vendor base stratifies across integrated motion control platforms, component specialists, and distributed automation architects. Three archetypes dominate: safety-certified automotive suppliers, aerospace-grade precision manufacturers, and software-anchored platform vendors. Competitive moves concentrate on predictive maintenance service bundling and Mexico corridor distribution partnerships.
Among US-based industrial automation incumbents, Rockwell Automation and Moog occupy distinct positioning archetypes. Rockwell Automation exemplifies the software-anchored platform model through its FactoryTalk service architecture. Moog represents the aerospace-precision specialist tier with proprietary servo valve heritage. Festo, a German-origin pneumatic and electric systems provider, anchors the distributed automation architect segment in North American packaging and electronics assembly.
| Leading Market Players |
|---|
| Rockwell Automation |
| ABB |
| Moog |
| Altra Industrial Motion |
| Curtiss-Wright Corporation |
| SMC Corporation |
| MISUMI Group Inc. |
| Flowserve Corporation |
| Festo |
| Others |
Value Network & Pricing Analysis
Neodymium oxide price volatility cascades through rare earth magnet supply chains into three-tier pricing structure across premium, standard, and economy actuator tiers. Tier-1 automotive suppliers in Michigan absorb elevated input costs for SIL-certified servo modules, while mid-range pneumatic conversions in legacy plants face margin compression from magnet sourcing premiums.
Pricing Analysis
Margin tightening in standard-tier electric actuators reflects rare earth magnet cost pass-through and certification overhead from NHTSA functional-safety mandates. Three-tier pricing structure across premium, standard, and economy levels separates aerospace-grade servo valves from automotive-certified modules and uncertified pneumatic retrofits. Price differentiation hinges on ISO 13849 safety integrity level and after-sales predictive maintenance bundling. Small and mid-sized manufacturers in Ohio and Tennessee exhibit highest price sensitivity, deferring smart actuator upgrades despite efficiency gains.
Supply Chain Analysis
Rare earth magnet supply rests on Chinese refining concentration for neodymium and dysprosium, with secondary sourcing from Malaysian and Australian separation facilities. Precision bearings and harmonic drives draw from Japanese and German specialty manufacturers, while power electronics feed from Taiwanese semiconductor foundries. Single-source vulnerability in magnet refining creates tariff exposure and input cost spikes. Distribution runs through Tier-1 automotive supplier parks in Detroit, Cleveland, and Toronto, with aftermarket service parts flowing through Rockwell Automation's FactoryTalk-anchored channel network.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a vertical-integration race where servo motor and drive manufacturers pursue backward integration into rare earth magnet sourcing and safety-certified firmware development to escape commodity pricing traps.
For Market Incumbents: To counter rare earth cost volatility and emerging smart actuator entrants, Rockwell Automation and Moog should deepen backward integration into magnet alloy sourcing partnerships with Australian and North American mining ventures. Certification investment in SIL 3 and PL e tiers for collaborative robot joints creates defensible pricing power against mid-tier pneumatic specialists. Channel control through FactoryTalk service contracts locks in automotive OEM replacement cycles.
For New Entrants and Emerging Players: Edge-computing firmware with predictive maintenance algorithms offers a technology-first wedge into mid-range electric actuator segments underserved by incumbent software platforms. White-space targets concentrate in Mexico's Querétaro automotive supplier corridor and Tennessee battery assembly equipment retrofits. Go-to-market execution through regional system integrator partnerships bypasses incumbent direct sales density in Michigan and Ontario.
For Investors and Strategic Acquirers: Distressed-cycle entries favor aerospace-precision servo specialists with MIL-spec qualification and medical device actuator manufacturers in Minnesota and Massachusetts. Long-term viability over a multi-year horizon hinges on software-defined service revenue attachment rates exceeding hardware depreciation curves. Watch NHTSA cybersecurity rulemaking for connected industrial actuators as inflection signal for compliance-driven replacement demand.
| Strategic Initiative | Industry Significance |
|---|---|
| Rare Earth Magnet Supply Agreement | Long-term offtake contracts with Australian and North American miners reduce neodymium cost volatility exposure. |
| SIL 3 Certification Investment | Functional-safety tier advancement captures automotive welding actuator specifications from Tier-1 suppliers in Ohio. |
| Software-Defined Maintenance Platform | Predictive analytics bundling shifts revenue mix toward recurring service contracts anchored by FactoryTalk architecture. |
| Mexico Corridor Distribution Partnership | Regional service density in Querétaro and Nuevo León captures nearshoring spillover from US supplier relocation. |
| Digital Twin Integration | Physics-based simulation pairing with smart actuators reduces commissioning downtime for EV battery assembly lines. |
Research Methodology
Multi-period observation of NHTSA regulatory filings, OSHA machine-guarding enforcement patterns, and rare earth magnet price indices anchored the trend analysis, supplemented by interviews with plant engineers at Detroit and Cleveland automotive facilities, procurement leads at Tier-1 suppliers, motion control system integrators, and aftermarket service directors. Secondary validation drew from SEC 10-K disclosures of Rockwell Automation and Moog, USGS mineral commodity summaries for rare earth elements, and IHS Markit automotive production databases. Bottom-up actuator shipment estimates triangulated against top-down manufacturing capital expenditure projections across the Great Lakes corridor.
The input-output matrix framed demand modeling across product type, end-use sector, technology tier, and application category throughout the forecast period. CAGRs derived from segment-level volume trajectories weighted by electrification mandate timing and NHTSA certification pipeline delays. Industry-specific forecast inputs incorporated EV battery assembly line buildout schedules in Michigan, Ohio, and Tennessee, plus OSHA collaborative robot deployment compliance deadlines.
Several conditions sit outside the modeled scope, including unannounced tariff changes on rare earth imports, abrupt NHTSA cybersecurity rulemaking for connected actuators, and force-majeure disruptions to Asian magnet refining capacity. Forecasts reflect documented assumptions regarding electrification adoption curves and functional-safety certification timelines. A small set of named triggers warrants ongoing watch: neodymium price spikes above historical bands, SIL 3 mandate acceleration, and Mexico IMMEX program modifications.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Robotics and Automation
Global Robotic Process Automation in Healthcare Market
Robotics and Automation
Global Adaptive Robot Market
Robotics and Automation
Indonesia Robotics Market
Robotics and Automation
Wearable Robots and Exoskeletons Market
Robotics and Automation
Underwater Drone Market
Robotics and Automation
Europe Robotics and Automation Actuators Market
Robotics and Automation
Underwater Jetpack Market
Robotics and Automation
Vision Guided Robotics Market
Robotics and Automation
SCARA Robots Market
Robotics and Automation
China Industrial Robots Market
Robotics and Automation
France Cloud Robotics Market
Robotics and Automation
Asia-Pacific Service Robotics Market
Robotics and Automation
United States Agricultural Robots Market
Robotics and Automation
Bot Services Market
Robotics and Automation
China Autonomous Mobile Robot Market
Robotics and Automation
Telepresence Robotics Market