
 Global K-12 Robotic Toolkits Market | 2026-2036
Global K-12 Robotic Toolkits Market Size, Share, and Industry Trends Forecast 2026-2036
Global K-12 Robotic Toolkits Market Outlook
China's manufacturing corridor for educational electronics is reconfiguring supply availability for K-12 robotic components worldwide. LEGO Education leverages its brick-system interoperability to sustain curriculum loyalty across national standards. VEX Robotics anchors competitive robotics leagues in North American secondary schools. Makeblock competes on price-accessible modular architectures for emerging education budgets.
K-12 robotic toolkits integrate programmable mechanical assemblies, sensor interfaces, and coding environments designed to teach computational thinking through physical manipulation. Typical systems operate on rechargeable lithium-polymer cells with Bluetooth or USB-C connectivity to tablets and laptops, enabling drag-to-drop or text-based command sequencing for students aged five to eighteen. Educational robots and programming tools command the broadest classroom penetration, while sensor modules represent the fastest-attached margin pool as schools upgrade base kits rather than replace full systems. Building kits retain stable demand in elementary grades where tactile assembly precedes code literacy.
The U.S. Consumer Product Safety Commission and the FCC govern hardware safety and wireless emissions for classroom robotics, while the EU AI Act imposes transparency requirements on adaptive learning algorithms embedded in intelligent tutoring modules. China's SAMR oversees educational hardware quality certification under national GB standards. Stakeholders must track how divergent safety and algorithmic accountability regimes fragment product development roadmaps across target jurisdictions.
Market Dynamics
Curriculum standardization across OECD education systems is compressing vendor design cycles, forcing hardware-software bundles to align with national computational thinking frameworks rather than proprietary pedagogical methods.
Growth Catalysts
- EU AI Act transparency mandates:Algorithmic accountability requirements for adaptive tutoring modules are accelerating procurement of certified intelligent robotics kits in European secondary schools.
- Lithium-polymer cost curves:Battery chemistry improvements are reducing per-unit power costs for classroom robot fleets, expanding district-level deployment scale.
- East Asian STEM funding pipelines:Metropolitan school districts in China, South Korea, and Japan are anchoring concentrated demand for sensor-upgradeable base systems.
Market Restraints
- GB standards compliance costs:China's SAMR certification requirements for educational hardware create fixed cost barriers for non-domestic vendors entering Chinese procurement channels.
- Semiconductor supply concentration:Microcontroller fabrication concentration in Taiwan creates input volatility for programmable kit manufacturers.
- Tablet substitution pressure:Pure software coding platforms on existing school devices compete for limited STEM budget allocation against physical robotics purchases.
Strategic Opportunities
- India's BIS certification pathway:Emerging national standards for educational electronics create first-mover positioning for compliant modular architectures.
- Competitive robotics league expansion:Tournament-based adoption models in North American secondary schools are creating recurring sensor module attachment demand.
- Cloud-based coding environment convergence:Browser-native programming interfaces are eliminating local software installation friction for elementary-grade deployment.
Industry Challenges
- Computational thinking pedagogy gaps:Teacher certification programs lag hardware deployment, creating utilization rate compression in deployed classrooms.
- FCC emissions recertification timelines:Wireless protocol updates require hardware revision cycles that misalign with school district procurement calendars.
- Interoperability standard fragmentation:Competing physical connector formats between brick-system vendors increase total cost of ownership for mixed-fleet districts.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global K-12 Robotic Toolkits Market |
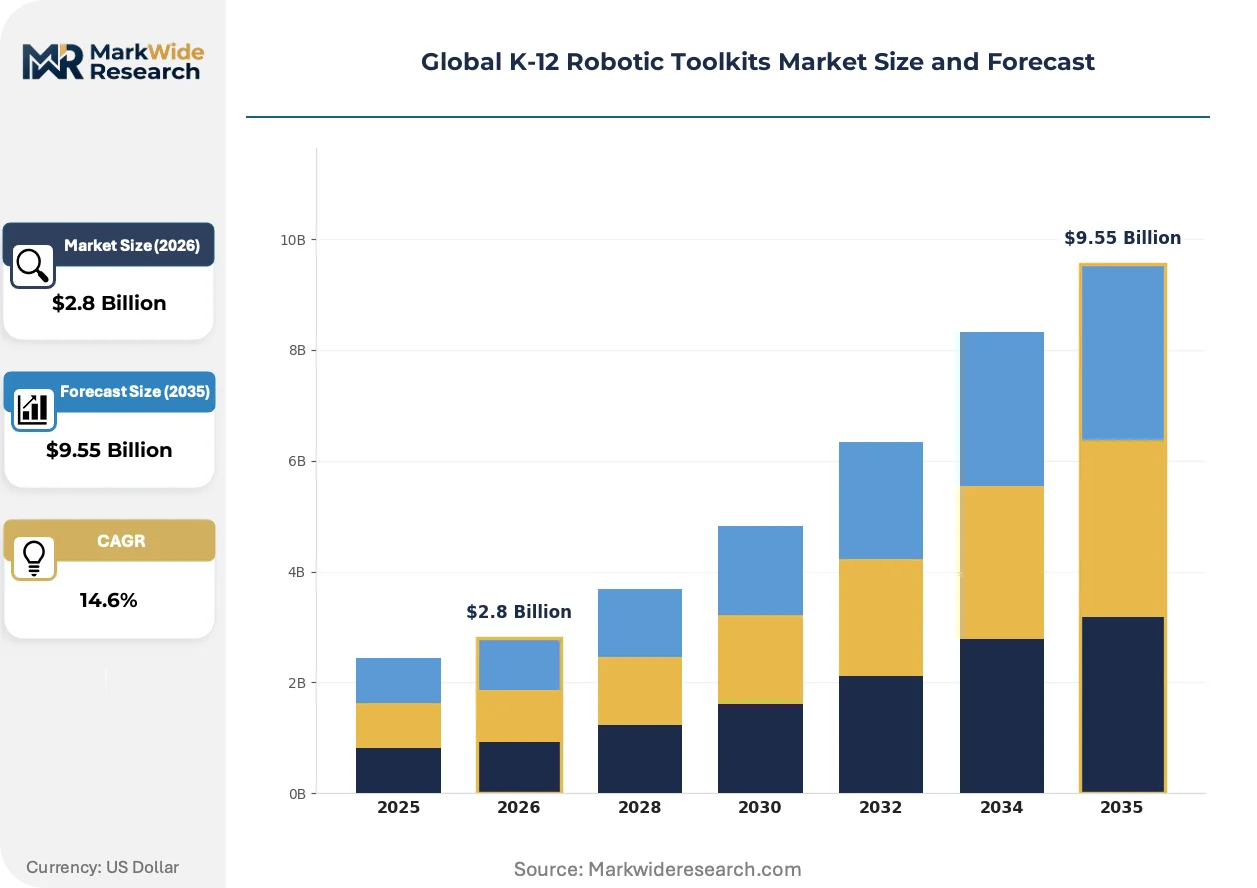
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $9.55 Billion |
| CAGR (2026 – 2036) | 14.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Building Kits, Programming Tools, Educational Robots, Sensor Modules End User: Schools, Home Educators, After-School Programs, Educational Institutions Technology: Robotics Software, Artificial Intelligence, Machine Learning, IoT Age Group: Elementary, Middle School, High School, Pre-Kindergarten |
| Companies Covered | LEGO Education, VEX Robotics, Sphero, Makeblock, Wonder Workshop, EZ-Robot, Modular Robotics, Valiant Technology, Raspberry Pi Foundation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global K-12 Robotic Toolkits Market Strategic Shifts
Physical-digital learning modality fusion is restructuring how robotics vendors architect curriculum-integrated hardware, with software abstraction layers now determining hardware attach rates more than mechanical durability.
Microcontroller platforms with integrated machine-learning accelerators are hybridizing edge inference capabilities into classroom robots previously limited to pre-programmed behavioral scripts. South Korean and Japanese middle schools are piloting these systems for real-time sensor feedback loops in science curricula. The technology is hybridizing lesson plan design around adaptive physical experiments rather than static coding exercises.
The EU AI Act's risk-classification framework for educational algorithms is mandating explainability documentation for intelligent tutoring modules embedded in robotics software. Vendors serving European markets must now maintain algorithmic audit trails alongside hardware safety certifications. Secondary schools in Germany and France are prioritizing compliant systems in competitive tenders, filtering non-compliant suppliers from shortlists.
District-level bulk purchasing consortia are consolidating procurement authority previously dispersed across individual schools. United States regional education service agencies now coordinate multi-district robotics kit acquisitions, compressing vendor sales cycles and standardizing sensor module specifications. This concentration is most visible in Texas and California, where state-level cooperative purchasing agreements cover over half of public school robotics spending.
Global K-12 Robotic Toolkits Market Segmentation
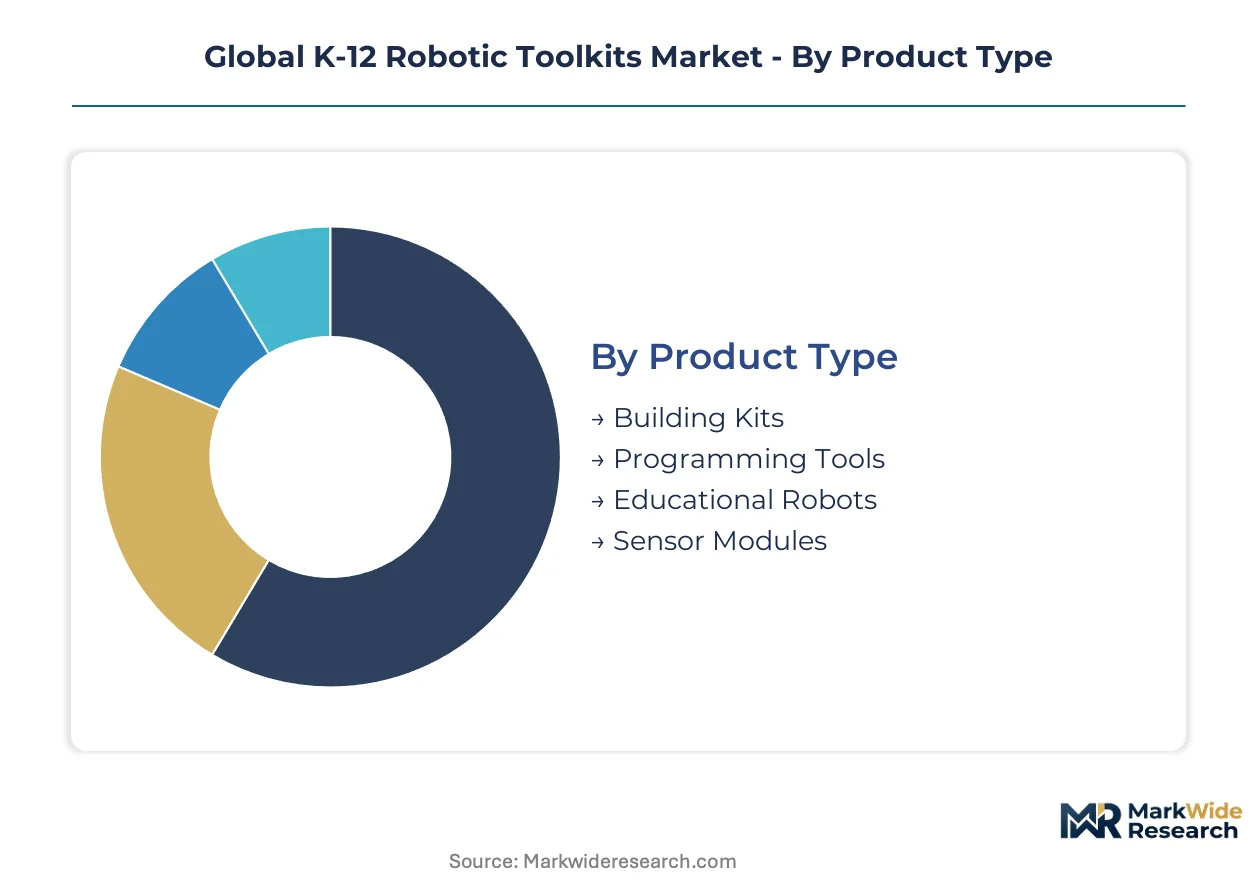
K-12 robotic toolkits fragment across four intersecting dimensions that determine procurement patterns and replacement cycles. Product architecture, end-user operational models, embedded technology layers, and age-appropriate pedagogical design each create distinct margin profiles and service requirements for vendors.
Product Type:
After-sales-service intensity varies sharply across product categories, with sensor modules requiring firmware calibration support while building kits demand minimal ongoing vendor interaction.
- Educational Robots:Self-contained programmable units with integrated motors, controllers, and rechargeable power systems. Demand concentrates in East Asian metropolitan districts where STEM funding pipelines support fleet deployments of 30-50 units per school. SAMR certification requirements in China filter non-compliant vendors from provincial procurement channels.
- Sensor Modules:Attachable peripherals enabling environmental data collection and real-time feedback loops. Middle schools across Germany and France prioritize EU AI Act-compliant intelligent tutoring modules with explainability documentation. Attachment rates climb as districts upgrade base kits rather than replace full systems.
- Building Kits:Modular mechanical components for tactile assembly preceding code literacy. Elementary grades in Texas and California regional consortia anchor stable replacement demand.
- Programming Tools:Software environments for drag-to-drop or text-based command sequencing. Browser-native interfaces are eliminating local installation friction for home educator segments.
Educational robots hold the largest share; momentum sits with sensor modules.
End User:
Procurement authority concentrates differently across customer types, with district-level bulk purchasing reshaping vendor sales cycles for school segments while home educators remain fragmented.
- Schools:Public and private K-12 institutions with formal curriculum integration. United States regional education service agencies in Texas and California now coordinate multi-district acquisitions covering over half of public robotics spending.
- After-School Programs:Supplementary learning providers operating outside standard school hours. Competitive robotics leagues in North American secondary schools generate recurring sensor module demand through tournament-based adoption models.
- Home Educators:Individual families purchasing direct-to-consumer. Price-accessible modular architectures from Chinese manufacturing corridors penetrate this budget-constrained segment.
- Educational Institutions:Museums, libraries, and STEM centers with informal learning mandates. Cloud-based coding environment convergence reduces IT support burdens for these resource-limited operators.
Schools dominate volume; after-school programs are expanding most quickly.
Technology:
Margin structure stratifies by technology layer, with hardware-software bundles capturing premium positioning against standalone programming platforms.
- Artificial Intelligence:Adaptive tutoring algorithms with explainability requirements under EU AI Act risk-classification frameworks. German and French secondary schools filter non-compliant suppliers from competitive tenders.
- Machine Learning:Edge inference capabilities enabling real-time sensor feedback loops. South Korean and Japanese middle schools pilot these systems for adaptive physical experiments.
- Robotics Software:Abstraction layers determining hardware attach rates more than mechanical durability. Physical-digital learning modality fusion restructures curriculum integration architectures.
- IoT:Wireless connectivity protocols requiring FCC emissions recertification for hardware revision cycles. Bluetooth and USB-C standards dominate tablet and laptop pairing.
Robotics software holds the largest share; artificial intelligence is gaining share fastest.
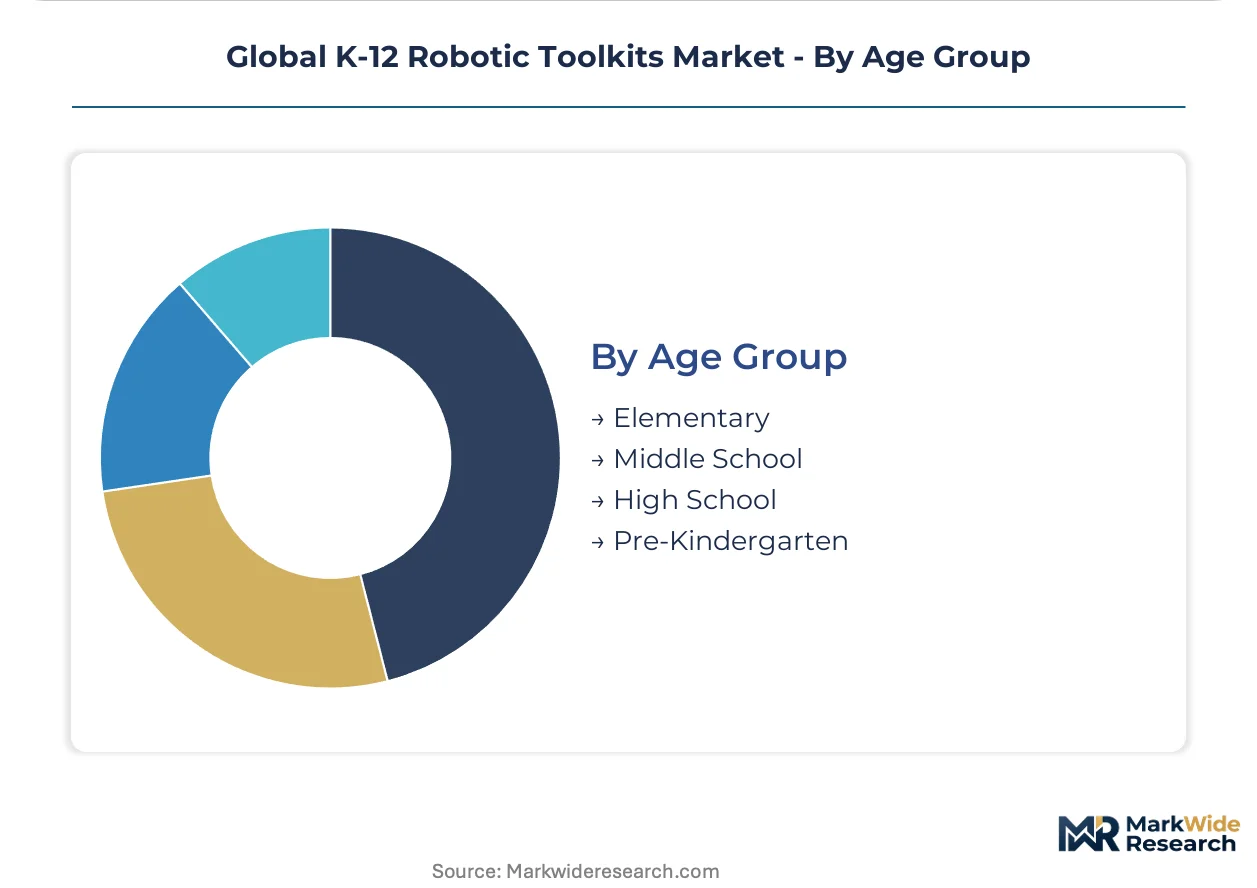
Age Group:
Curriculum standardization across OECD systems compresses vendor design cycles to align with national computational thinking frameworks rather than proprietary pedagogical methods.
- Middle School:Transitional grades where competitive robotics leagues anchor adoption. United States districts expand hands-on curricula with programmable mechanical assemblies and sensor interfaces.
- Elementary:Early grades where tactile assembly precedes code literacy. Building kits retain stable demand with lithium-polymer power systems enabling rechargeable classroom fleets.
- High School:Advanced grades requiring text-based programming and complex mechanical design. Teacher certification programs lag hardware deployment, creating utilization rate compression.
- Pre-Kindergarten:Early childhood introduction to computational thinking through physical manipulation. Drag-to-drop interfaces dominate with minimal text requirements.
Middle school holds the largest share; elementary is climbing the fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
SAMR certification requirements under China's GB standards anchor procurement dynamics for educational hardware across East Asian metropolitan districts. The EU AI Act's algorithmic transparency mandates filter vendor participation in German and French competitive tenders. Divergent regulatory regimes fragment product development roadmaps across target jurisdictions.
United States
Regional education service agencies in Texas and California coordinate multi-district acquisitions covering over half of public school robotics spending. The FCC governs hardware safety and wireless emissions for classroom robotics equipment. Competitive robotics leagues in North American secondary schools generate recurring sensor module demand through tournament-based adoption models.
China
Metropolitan school districts in the Yangtze River Delta and Pearl River Delta anchor concentrated demand for sensor-upgradeable base systems. SAMR oversees educational hardware quality certification under national GB standards, creating fixed cost barriers for non-domestic vendors. Shenzhen's manufacturing corridor reconfigures supply availability for K-12 robotic components worldwide.
Germany
Secondary schools prioritize EU AI Act-compliant intelligent tutoring modules with explainability documentation in competitive tenders. The EU AI Act's risk-classification framework for educational algorithms mandates algorithmic audit trails alongside hardware safety certifications. Bavaria's technical universities collaborate with secondary schools on adaptive physical experiment pilots.
Japan
Middle schools pilot microcontroller platforms with integrated machine-learning accelerators for real-time sensor feedback loops in science curricula. METI guidelines influence educational technology procurement standards for public institutions. Tokyo and Osaka metropolitan districts concentrate STEM funding pipelines for fleet deployments of programmable mechanical assemblies.
South Korea
Metropolitan school districts in Seoul and Busan-Ulsan drive demand for edge inference capabilities enabling adaptive physical experiments. The MFDS and national standards bodies oversee educational electronics quality frameworks. Gyeonggi Province's education technology clusters coordinate provincial procurement for rechargeable lithium-polymer classroom fleets.
Global K-12 Robotic Toolkits Market Competitive Environment
Capability concentration sits with specialized robotics software developers; scale advantage sits with brick-system incumbents with established curriculum loyalty. The vendor base stratifies across three tiers: premium-tier integrated hardware-software bundles, mid-tier modular architectures competing on price-accessibility, and open-source programmable platforms serving technical educators. Strategic moves center on backward integration into sensor module manufacturing and cloud-based coding environment convergence to eliminate local installation friction.
Within the premium-tier integrated bundle segment, LEGO Education and VEX Robotics occupy positions sustained by brick-system interoperability and competitive league anchoring respectively. Makeblock exemplifies the price-accessible modular architecture archetype competing for emerging education budgets. Sphero represents the self-contained programmable unit specialist targeting fleet deployment scalability in metropolitan districts.
| Leading Market Players |
|---|
| LEGO Education |
| VEX Robotics |
| Sphero |
| Makeblock |
| Wonder Workshop |
| EZ-Robot |
| Modular Robotics |
| Valiant Technology |
| Raspberry Pi Foundation |
| Others |
Value Chain & Pricing Dynamics
Shenzhen's manufacturing corridor for educational electronics concentrates upstream component supply, anchoring margin pools in sensor module firmware and cloud-based coding environments rather than base hardware assembly. Lithium-polymer cell costs and microcontroller availability directly determine where vendors capture value across kit tiers.
Pricing Analysis
East Asian metropolitan districts command 15-25% price premiums over North American rural districts for identical hardware-software bundles due to bundled after-sales calibration support. Pricing stratifies across premium certified tiers (EU AI Act-compliant intelligent tutoring modules), standard interoperable tiers (brick-system compatible base kits), and economy modular tiers (price-accessible architectures from Chinese manufacturing corridors). Cost compression in economy tiers intensifies because tablet substitution pressure forces vendors to absorb battery chemistry improvements rather than pass through savings. Home educators exhibit highest price sensitivity; German secondary schools with EU-mandated explainability documentation show lowest sensitivity.
Supply Chain Analysis
Foxconn, BYD Electronics, and select Shenzhen-based EMS providers hold contract-manufacturing capacity for programmable mechanical assemblies and sensor module integration. Component sourcing draws from Taiwan for microcontroller fabrication, South Korea for lithium-polymer cells, and China for plastic injection molding and PCB assembly. Single-source vulnerability concentrates in Taiwan semiconductor foundries serving edge inference accelerator demand. Distribution runs through regional education service agency consortia in Texas and California, provincial procurement channels in China, and competitive robotics league tournament organizers in North America.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Curriculum standardization across OECD systems fragments vendor positioning, creating niches for specialized robotics software developers and modular architecture specialists as brick-system incumbents face interoperability pressure.
For Market Incumbents: Harden algorithmic audit trail capabilities to maintain EU AI Act compliance eligibility in German and French competitive tenders. Deepen backward integration into sensor module manufacturing to capture attachment rate value as districts upgrade base kits rather than replace full systems. Lock in regional education service agency consortia through multi-year cloud-based coding environment contracts before browser-native interfaces commoditize software differentiation. For New Entrants and Emerging Players: Build out BIS-compliant modular architectures for India's emerging educational electronics standards pathway, securing first-mover positioning before certification requirements mature. Target home educator segments with price-accessible programmable units leveraging Shenzhen manufacturing cost structures. Penetrate through direct-to-consumer channels with drag-to-drop interfaces that eliminate IT support burdens for resource-limited operators. For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed robotics software developers holding cloud-based coding environment revenue streams and established curriculum integration partnerships. Long-term viability hinges on adaptive tutoring algorithm differentiation as physical kit commoditization accelerates. Watch for inflection in teacher certification program deployment rates, which signal utilization rate compression risk in installed hardware bases.| Strategic Initiative | Industry Significance |
|---|---|
| EU AI Act Certification Investment | Explainability documentation mandates filter non-compliant vendors from German and French tenders. |
| Backward Integration into Sensor Manufacturing | Captures fastest-growing margin pool as districts upgrade base kits rather than replace systems. |
| Cloud-Based Coding Environment Launch | Browser-native interfaces eliminate local installation friction for elementary-grade deployment. |
| Regional Education Service Agency Partnership | Texas and California consortia coordinate over half of United States public robotics spending. |
| India BIS Certification Pathway Entry | Emerging national standards create first-mover positioning for compliant modular architectures. |
Study Parameters
Demand-side practitioners and supply-side operators were both consulted through structured primary interviews with curriculum directors at East Asian metropolitan school districts, procurement officers at United States regional education service agencies, competitive robotics league tournament organizers, and firmware engineers at educational electronics manufacturers. Secondary validation drew from SAMR GB standards documentation, EU AI Act regulatory filings, FCC equipment authorization databases, and OECD computational thinking framework publications. Bottom-up triangulation across district-level fleet deployment data and top-down reconciliation against national STEM budget allocations anchored volume estimates.
Calibration against historical procurement cycles and lithium-polymer cost curve trajectories shaped the analytical framework across the projection horizon. Segmentation dimensions modeled include product architecture (educational robots, sensor modules, building kits, programming tools), end-user operational model (schools, after-school programs, home educators, educational institutions), embedded technology layer (artificial intelligence, machine learning, robotics software, IoT), and age-appropriate pedagogical design (pre-kindergarten, elementary, middle school, high school). CAGRs were derived from regression analysis of replacement cycle compression and attachment rate expansion, with specific inputs from teacher certification program deployment lag and wireless protocol recertification timeline misalignment.
Stress conditions across semiconductor supply volatility, EU AI Act enforcement intensity, and tablet substitution pressure were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions regarding curriculum standardization pace and regional funding pipeline stability. Quarterly review of district-level bulk purchasing consortium formation rates and teacher utilization survey data is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Robotics and Automation
Robotic Desktop Automation (RDA) Market
Robotics and Automation
North America Service Robotics Market
Robotics and Automation
Asia-Pacific Medical Robots Market
Robotics and Automation
Latin America Automated Guided Vehicle (AGV) Market
Robotics and Automation
Africa Cloud Robotics Market
Robotics and Automation
Lab Robotics Market
Robotics and Automation
Pharmaceutical Collaborative Robots Market
Robotics and Automation
Cloud Robotics Market
Robotics and Automation
Search and Rescue Robots Market
Robotics and Automation
Logistics Robotics Market
Robotics and Automation
Robotic Process Automation (RPA) Market
Robotics and Automation
Malaysia Robotics Market
Robotics and Automation
Claytronics Market
Robotics and Automation
Electric Power Intelligent Inspection Robot Market
Robotics and Automation
Smart Worker Market
Robotics and Automation
Japan Agricultural Robot Market