
 Cryogenic Capsules Market | 2026-2036
Cryogenic Capsules Market Size, Share, and Industry Trends Forecast 2026-2036
Cryogenic Capsules Market Outlook
Aftermarket service revenue is reconfiguring how cryogenic capsule suppliers capture lifetime value from installed bases. Worthington Industries leverages its metals fabrication heritage to dominate bulk tank refurbishment and field service networks. Thermo Fisher Scientific anchors its position through integrated consumable and instrumentation contracts with biobank operators. Cryoport specializes in logistics-enabled capsule leasing, differentiating through temperature-verified chain-of-custody protocols.
Cryogenic capsules are vacuum-insulated vessels engineered to maintain temperatures below minus 150 degrees Celsius for biological specimen preservation, typically employing multi-layer insulation and pressure-relief systems to prevent cryogenic liquid boil-off. Their primary purpose is to eliminate thermal degradation of cells, tissues, and pharmaceutical intermediates across extended storage or transport intervals. Stainless steel storage capsules command the largest material share due to structural durability under thermal cycling stress, while composite transfer vessels represent the fastest-growing category as pharmaceutical logistics operators seek weight reduction for air freight. Biobank end users concentrate procurement of high-capacity units, whereas pharmaceutical companies drive demand for validated sample holders aligned with clinical trial material traceability standards.
The FDA enforces current good tissue practice requirements that mandate container qualification for human cell and tissue products, directly elevating documentation burdens for capsule suppliers seeking biologics market access. The EPA regulates venting of cryogenic gases through Clean Air Act permitting, constraining facility-based storage system designs. ISO 20387 biobanking standards and the EU AI Act's data-integrity provisions for automated cold-chain monitoring together reshape product development priorities. Stakeholders must weigh capital deployment between standardized high-volume capsule platforms and configurable systems serving regulated cell-therapy workflows.
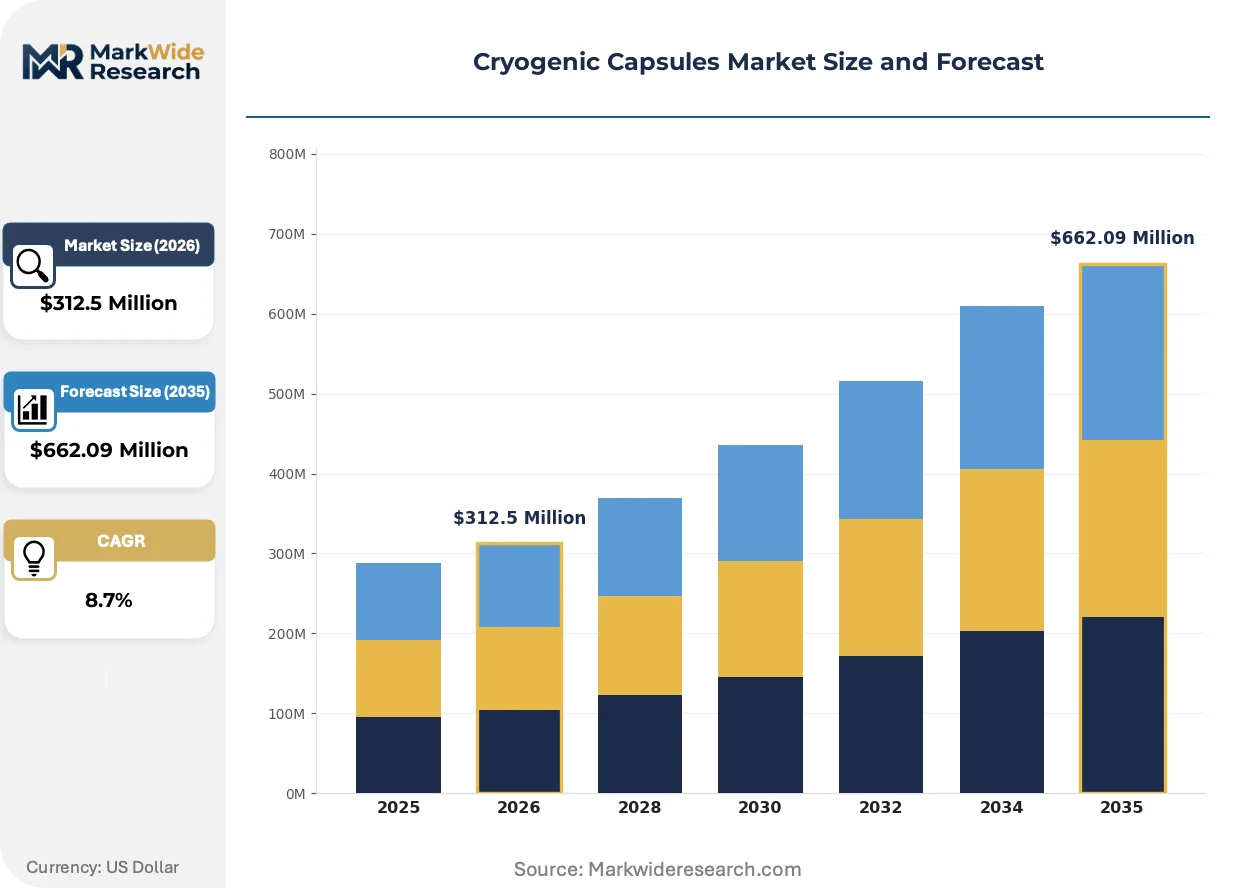
Market Dynamics
The FDA's updated good tissue practice rules are compressing supplier qualification timelines while biobank specimen volumes multiply, creating a structural squeeze between compliance burden and capacity scaling that favors integrated service providers over standalone hardware vendors.
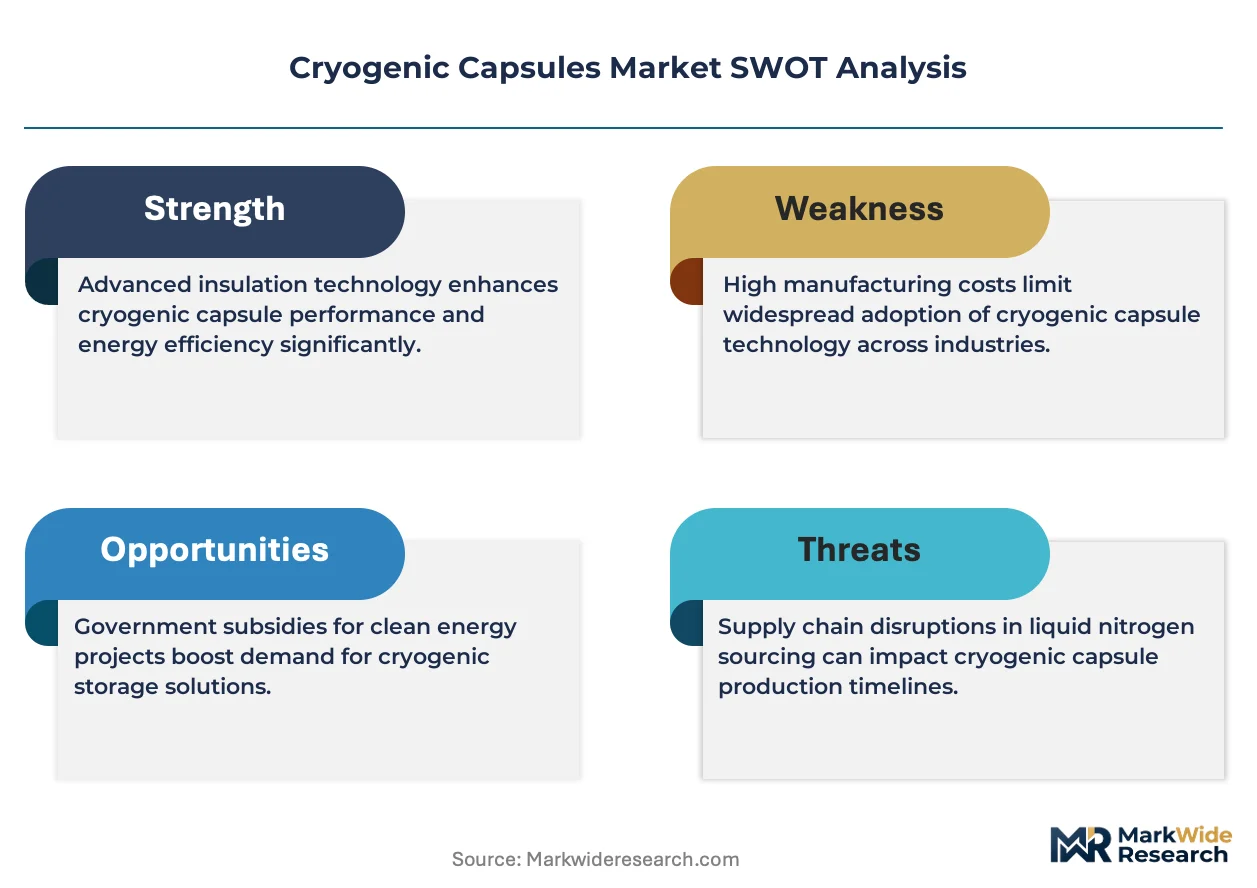
Growth Catalysts
- Cell therapy pipeline expansion:Autologous CAR-T manufacturing workflows require validated cryogenic storage at multiple clinical sites, pulling demand for traceable capsule systems through CDMO networks.
- ISO 20387 biobanking standards:Accreditation mandates for quality management systems are forcing repository upgrades toward automated liquid nitrogen monitoring and redundant backup vessels.
- Boston-Research Triangle cold-chain clustering:Pharmaceutical manufacturing investments in these hubs concentrate procurement power and accelerate specification harmonization across contract manufacturers.
Market Restraints
- Liquid nitrogen supply volatility:Regional production bottlenecks and energy cost spikes constrain facility-based storage economics for mid-sized biobanks.
- Specialized welding fabrication concentration:Vacuum-insulated vessel manufacturing depends on a narrow base of certified pressure-vessel shops in Germany and the United States.
- EPA Clean Air Act venting permits:Cryogenic gas discharge regulations add facility design constraints and timeline risk for greenfield biorepository construction.
Strategic Opportunities
- India biobank infrastructure buildout:The country's PLI scheme for medical devices creates tariff and investment incentives for localized capsule assembly and service depots.
- Drone-enabled last-mile delivery:Lightweight composite transfer vessels open air-logistics channels for time-critical cell therapy shipments between hospital networks.
- EU AI Act cold-chain monitoring:Automated temperature logging and chain-of-custody verification requirements create pull for sensor-integrated capsule platforms.
Industry Challenges
- Cryogenic systems engineering talent scarcity:Vacuum insulation design and pressure-relief system validation expertise concentrates among retiring specialists at legacy industrial gas suppliers.
- FDA container qualification timelines:Biologics license application support documentation for novel capsule designs extends validation cycles beyond typical product development schedules.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Cryogenic Capsules Market |
| Market Size in 2026 | $312.5 Million |
| Market Size in 2035 | $662.09 Million |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Storage Capsules, Transfer Vessels, Sample Holders, Cryogenic Tanks Material: Stainless Steel, Aluminum, Composites, Glass End User: Research Institutions, Biobanks, Pharmaceutical Companies, Hospitals Application: Laboratory Research, Clinical Trials, Drug Development, Tissue Preservation |
| Companies Covered | Worthington Industries, Panasonic Biomedical, Chart Industries, Air Products and Chemicals, Linde, Cryoport, Cryofab, Nikkiso, Thermo Fisher Scientific, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Cryogenic Capsules Market Strategic Shifts
Digital traceability architectures are displacing paper-based chain-of-custody systems across pharmaceutical cold chains, compressing audit preparation timelines while elevating sensor integration from optional feature to procurement prerequisite.
Smart capsule telemetry is digitizing specimen custody records through embedded temperature loggers and blockchain-anchored handoff confirmations. Biobank operators and cell therapy CDMOs are mandating these capabilities in new equipment tenders. The technology is digitizing compliance documentation workflows that previously consumed weeks of manual record reconciliation.
REACH and F-Gas Regulation amendments are tightening containment requirements for cryogenic fluids in transport vessels, pushing European manufacturers toward improved valve sealing technologies and secondary containment designs. Pharmaceutical logistics operators serving EU markets are accelerating fleet replacement cycles to preempt certification gaps. The regulatory pressure is reshaping R&D allocation toward materials compatibility testing.
Leasing models are unbundling capital expenditure from operational service relationships, allowing biobanks to convert fixed equipment costs into per-sample storage fees. Third-party cold-chain logistics providers are capturing this demand through temperature-verified capsule rental programs. The shift is most visible in United States clinical trial material networks where sponsor companies prioritize balance sheet flexibility over asset ownership.
Cryogenic Capsules Market Segmentation
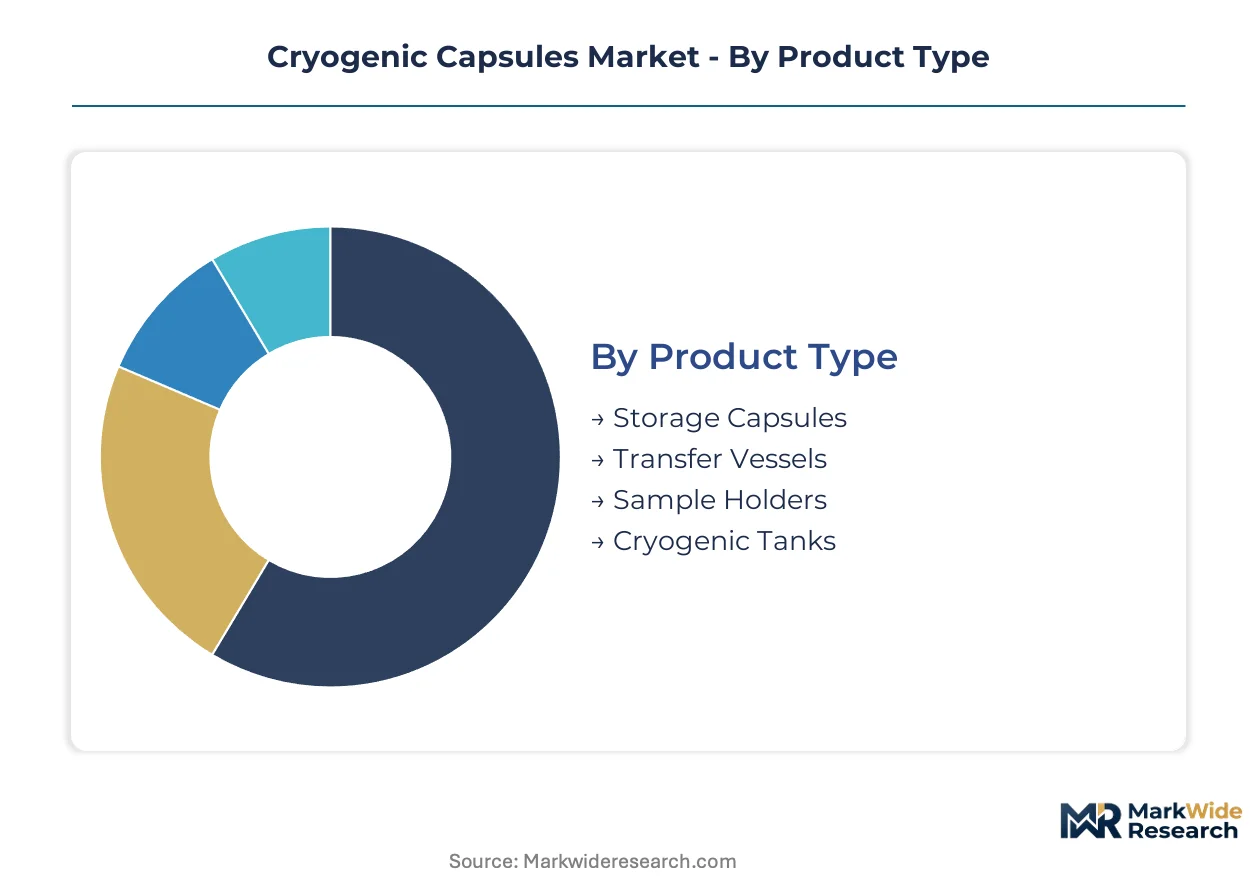
Cryogenic capsule procurement patterns diverge sharply across product architectures, material specifications, and end-use workflows. Understanding these fault lines reveals where specification power concentrates and where margin compression threatens hardware-only suppliers.
Product Type:
Application intensity and transport frequency determine which vessel architecture biobank operators and pharmaceutical logistics providers specify.
- Storage Capsules:Stationary vacuum-insulated vessels engineered for high-capacity liquid nitrogen containment over extended preservation intervals. Biobank operators in the United States cluster procurement around Boston and Research Triangle Park, driven by specimen volume multiplication and ISO 20387 accreditation mandates for redundant backup systems.
- Transfer Vessels:Lightweight portable units designed for specimen movement between clinical sites and processing facilities. Pharmaceutical logistics operators specify composite transfer vessels for air freight weight reduction, with demand accelerating through CDMO networks supporting autologous cell therapy manufacturing.
- Sample Holders:Validated containment systems for clinical trial material traceability.
- Cryogenic Tanks:Bulk stationary storage systems for facility-scale liquid nitrogen reserves.
Storage capsules command the established base. The steepest expansion runs through transfer vessels.
Material:
Thermal cycling durability and weight constraints pull material selection in opposing directions across static versus mobile applications.
- Stainless Steel:Austenitic grades dominate structural storage vessel fabrication due to fatigue resistance under repeated thermal shock. Biobank infrastructure investments in the United States specify stainless steel for high-capacity units, constrained by specialized welding fabrication concentration among certified pressure-vessel shops.
- Composites:Fiber-reinforced polymer systems enable mass reduction for logistics-intensive workflows. Pharmaceutical cold-chain operators serving EU markets accelerate fleet replacement cycles as REACH and F-Gas Regulation amendments tighten containment requirements for cryogenic fluids in transport.
- Aluminum:Intermediate weight and thermal conductivity for mid-range transport applications.
- Glass:Limited to laboratory-scale specimen visualization and research protocols.
Stainless steel anchors the installed base. Composite vessels are climbing the fastest.
End User:
Capital deployment scale and regulatory scrutiny intensity segment procurement behavior across institutional categories.
- Biobanks:Repository operators concentrate procurement of high-capacity storage capsules and automated liquid nitrogen monitoring systems. FDA updated good tissue practice rules compress supplier qualification timelines while specimen volumes multiply, creating structural squeeze between compliance burden and capacity scaling.
- Pharmaceutical Companies:Sponsor firms drive demand for validated sample holders aligned with clinical trial material traceability standards. Leasing models convert fixed equipment costs into per-sample storage fees across United States clinical trial material networks.
- Research Institutions:Academic laboratories with fragmented procurement authority and budget constraints.
- Hospitals:Clinical sites requiring point-of-care cryogenic preservation for cell therapy administration.
Biobanks represent the fastest-growing trajectory. Pharmaceutical companies retain specification authority for traceability-critical applications.
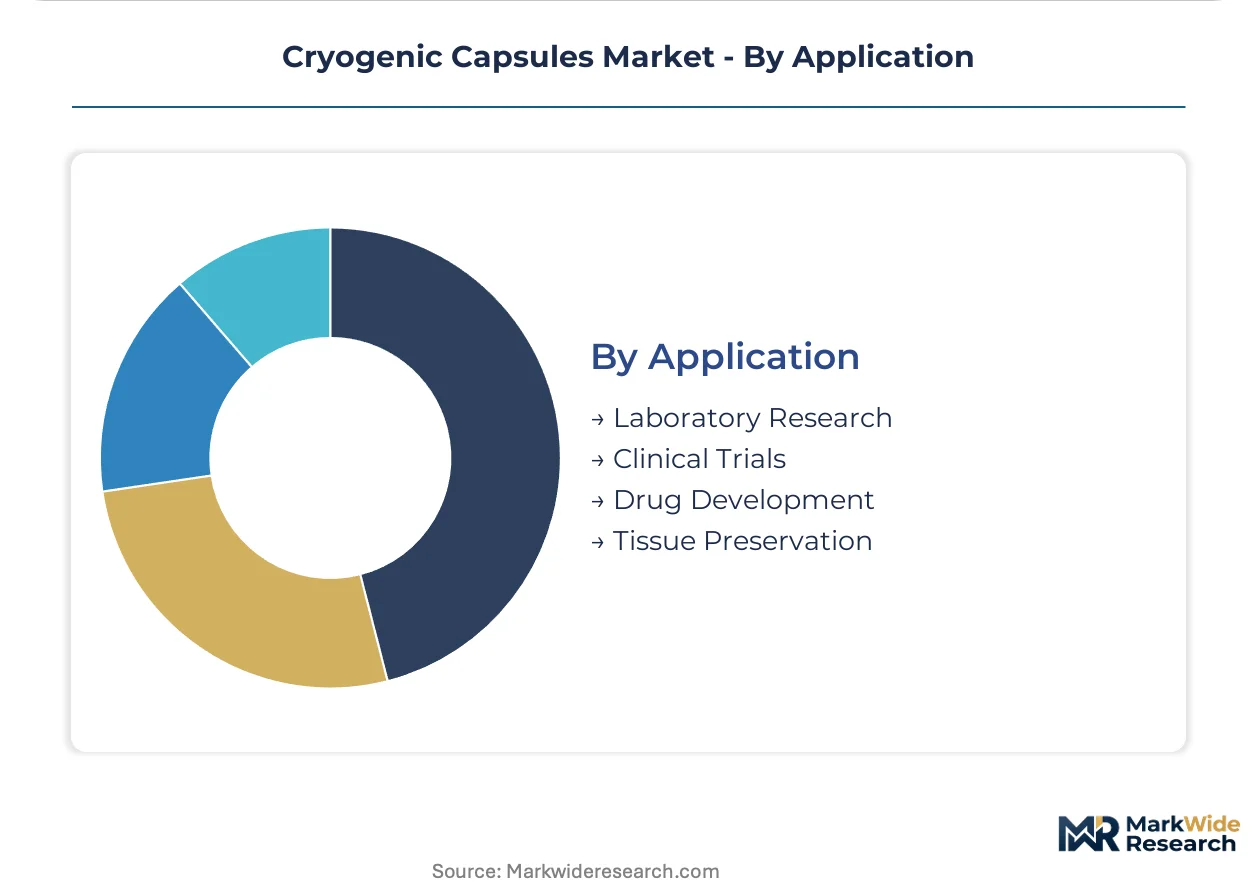
Application:
Workflow duration and custody chain complexity determine sensor integration and documentation requirements.
- Clinical Trials:Multi-site investigational product storage demands blockchain-anchored chain-of-custody verification. Biobank operators and cell therapy CDMOs mandate smart capsule telemetry in new equipment tenders, digitizing compliance documentation that previously consumed weeks of manual reconciliation.
- Tissue Preservation:Long-duration human cell and tissue product storage triggers FDA container qualification requirements. EPA Clean Air Act venting permits add facility design constraints for greenfield biorepository construction.
- Laboratory Research:Protocol-driven specimen storage with standardized temperature monitoring.
- Drug Development:Intermediate-duration pharmaceutical intermediate preservation.
Clinical trials dominate value capture. Tissue preservation applications are expanding most quickly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Price elasticity diverges sharply across geographies. United States biobanks absorb premium pricing for validated systems, while Indian operators prioritize localized assembly to circumvent import duties and service delays.
United States
FDA container qualification mandates for human cell and tissue products compress supplier approval timelines. The EPA's Clean Air Act venting permit requirements constrain greenfield biorepository construction timelines. Cold-chain investments concentrate around Boston and Research Triangle Park, where pharmaceutical manufacturing clusters drive specification harmonization across contract manufacturers.
Germany
Specialized welding fabrication for vacuum-insulated vessels depends on certified pressure-vessel shops concentrated in industrial regions. REACH and F-Gas Regulation amendments tighten containment requirements for cryogenic fluids in transport vessels. Bavaria and Baden-Württemberg host precision engineering suppliers serving pharmaceutical logistics operators accelerating fleet replacement cycles.
India
The PLI scheme for medical devices creates tariff and investment incentives for localized capsule assembly and service depots. CDSCO alignment with international quality standards elevates documentation requirements for imported equipment. Maharashtra and Karnataka biobank infrastructure buildouts concentrate procurement of high-capacity storage units as specimen volumes multiply.
Japan
METI industrial policy supports domestic production of advanced cold-chain equipment for cell therapy manufacturing workflows. PMDA guidance on regenerative medicine products mandates validated cryogenic storage at multiple clinical sites. The Kanto region around Tokyo anchors demand from pharmaceutical companies and CDMO networks.
United Kingdom
Post-Brexit regulatory divergence from EU frameworks creates dual compliance burdens for capsule suppliers serving both markets. The Medicines and Healthcare products Regulatory Agency maintains alignment with FDA good tissue practice standards. London and Southeast England biobank operators concentrate procurement of automated liquid nitrogen monitoring systems.
Cryogenic Capsules Market Competitive Environment
Capability concentration sits with specialized vacuum-insulation engineering shops; scale advantage sits with diversified industrial gas and laboratory equipment conglomerates. The market structures around three tiers: integrated service providers bundling hardware with logistics and monitoring, metals fabricators leveraging pressure-vessel certification heritage, and precision instrumentation specialists embedding sensor platforms. Dominant competitive moves include backward integration into cryogenic gas supply chains and geographic expansion through localized assembly partnerships.
Among diversified laboratory equipment conglomerates, Thermo Fisher Scientific exemplifies the integrated service archetype through consumable and instrumentation contracts. Cryoport occupies a position within the logistics-enabled leasing tier, differentiating through temperature-verified chain-of-custody protocols. Worthington Industries anchors the metals fabrication heritage segment, dominating bulk tank refurbishment and field service networks.
| Leading Market Players |
|---|
| Worthington Industries |
| Panasonic Biomedical |
| Chart Industries |
| Air Products and Chemicals |
| Linde |
| Cryoport |
| Cryofab |
| Nikkiso |
| Thermo Fisher Scientific |
| Others |
Value Chain & Pricing Dynamics
Overcapacity in German vacuum-insulated vessel fabrication is compressing lead times for certified pressure-vessel shops while elevating buyer negotiating leverage across North American procurement. This utilization dynamic simultaneously strains margins for metals fabricators and accelerates specification standardization among biobank operators seeking cost predictability.
Pricing Analysis
Long-term consumable and instrumentation contracts dominate biobank procurement, with spot purchasing limited to emergency replacement scenarios. Price differentiation rests on FDA container qualification tier and ISO 20387 accreditation status, with validated systems commanding substantial premiums over unqualified hardware. Pricing pressure intensifies in composite transfer vessels as REACH amendments force accelerated fleet replacement cycles. Pharmaceutical logistics operators exhibit lowest price sensitivity due to chain-of-custody liability exposure, while mid-sized research institutions drive hardest bargain terms.
Supply Chain Analysis
Upstream austenitic stainless steel feedstock draws from mills concentrated in Germany, Japan, and the United States, with specialized welding fabrication tethered to certified pressure-vessel shops in Bavaria and Baden-Württemberg. Multi-layer insulation materials and cryogenic valve assemblies hinge on precision engineering suppliers in the same industrial regions. Single-source vulnerability concentrates in vacuum-insulation design expertise held by retiring specialists at legacy industrial gas suppliers. Distribution runs through CDMO networks and third-party cold-chain logistics providers with temperature-verified leasing capabilities.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market is recovering from a cyclical trough driven by biobank infrastructure buildouts lagging cell therapy pipeline expansion. Capital deployment is accelerating as specimen volumes multiply and FDA qualification timelines compress.
For Market Incumbents: Build switching-cost moats through integrated consumable and instrumentation contracts that embed automated liquid nitrogen monitoring systems. Deepen backward integration into cryogenic gas supply chains to capture margin from liquid nitrogen volatility. Defend against composite vessel specialists by accelerating R&D allocation toward sensor-integrated platforms that satisfy EU AI Act cold-chain monitoring mandates. For New Entrants and Emerging Players: Establish a beachhead in India's PLI scheme for medical devices by partnering with Maharashtra and Karnataka biobank operators for localized capsule assembly. Target drone-enabled last-mile delivery applications for lightweight composite transfer vessels serving time-critical cell therapy shipments. Pursue logistics-enabled leasing models that convert biobank capital expenditure into per-sample storage fees. For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting upward across sensor-integrated capsule platforms as digital traceability architectures displace paper-based systems. Long-term viability favors integrated service providers bundling hardware with monitoring and logistics over standalone hardware vendors. Acquisition target archetype: precision instrumentation specialists with embedded sensor platforms and existing FDA qualification documentation. Monitor CDSCO alignment with international quality standards as inflection signal for Indian market access timing.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Cryogenic Gas Supply | Captures margin from liquid nitrogen production bottlenecks constraining mid-sized biobank storage economics. |
| Sensor-Integrated Platform Development | Addresses EU AI Act automated temperature logging mandates elevating procurement prerequisites for pharmaceutical logistics. |
| Localized Assembly Partnership | Exploits India's PLI scheme tariffs and investment incentives while circumventing import duty burdens. |
| Logistics-Enabled Leasing Program | Converts biobank fixed equipment costs into per-sample fees across Boston and Research Triangle Park clusters. |
| FDA Container Qualification Investment | Accelerates biologics license application support timelines that currently extend beyond product development cycles. |
Study Parameters
Initial hypotheses were tested against primary input from biobank operations directors, pharmaceutical cold-chain logistics managers, vacuum-insulation design engineers, and regulatory affairs specialists at cell therapy CDMOs and refined through secondary validation. Sources included FDA good tissue practice guidance documents, EPA Clean Air Act permitting records, ISO 20387 biobanking standards filings, and EU REACH amendment regulatory texts. Bottom-up procurement volume estimates from biobank operators were triangulated against top-down pharmaceutical manufacturing investment disclosures.
Demand-supply balance modeling anchored projections across the analysis window, with segmentation by product architecture, material specification, end-user category, and application workflow duration. CAGRs were derived from specimen volume multiplication rates, accreditation mandate timelines, and fleet replacement cycle acceleration. Industry-specific inputs incorporated autologous CAR-T manufacturing site expansion plans and automated liquid nitrogen monitoring adoption curves.
Sensitivities concentrate around liquid nitrogen supply volatility, FDA container qualification timeline extensions, and cryogenic systems engineering talent scarcity. Forecasts reflect assumptions regarding biobank infrastructure buildout pacing and regulatory harmonization between CDSCO and international quality standards. Cross-checking against pharmaceutical cold-chain capital expenditure disclosures and biobank accreditation database growth is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Cold Chain Packaging
Food Cold Chain Market
Cold Chain Packaging
Pharmaceutical Cold Chain Packaging Market
Cold Chain Packaging
Fish Boxes Market
Cold Chain Packaging
Cold Chain Packaging Pooling and Reverse Logistics Services Market
Cold Chain Packaging
Reusable Cold Chain Packaging Market
Cold Chain Packaging
North America Food Cold Chain Logistics Market
Cold Chain Packaging
Insulated Food Delivery Bags Market
Cold Chain Packaging
Refrigeration Packaging Market
Cold Chain Packaging
Global Cold Chain Tracking and Monitoring Market
Cold Chain Packaging
North America Cold Chain Market
Cold Chain Packaging
Cold Chain Market
Cold Chain Packaging
Biopharma Cold Chain Packaging Market
Cold Chain Packaging
Europe Cold Chain Tracking and Monitoring Market
Cold Chain Packaging
Temperature Controlled Packaging Boxes Market
Cold Chain Packaging
Cold Chain Temperature Monitoring Market
Cold Chain Packaging
Freezer Liner Market