
 North America Passive Temperature Controlled Packaging Market | 2026-2036
North America Passive Temperature Controlled Packaging Market Size, Share, and Industry Trends Forecast 2026-2036
North America Passive Temperature Controlled Packaging Market Analytics
Cold chain logistics talent scarcity is reorganizing how packaging vendors allocate engineering resources across North America. Sonoco Products Company leverages its corrugated manufacturing footprint to dominate insulated shipper production in the Southeast. ThermoSafe Solutions anchors its position through specialized qualification testing services that reduce pharmaceutical client validation cycles. Cold Chain Technologies competes aggressively on thermal pallet platforms for high-volume vaccine distribution networks.
Passive temperature controlled packaging employs phase-change materials, vacuum-insulated panels, and engineered foam barriers to maintain specified thermal ranges without active refrigeration during transit. Thermal duration performance typically spans 48-120 hours depending on payload configuration and ambient exposure profiles, with qualification testing under ISTA 7E and ASTM D3103 protocols verifying performance claims. Insulated shippers lead product type revenue due to their ubiquity in parcel-scale pharmaceutical distribution, while gel packs command the fastest material growth as reusable formats displace single-use alternatives. The 2-8°C temperature range occupies the largest margin pool because cardiovascular and oncology biologics overwhelmingly require controlled room temperature conditions.
FDA guidance on risk-based approaches to temperature excursion management shapes product qualification requirements, while the EPA's evolving framework for refrigerant phase-downs indirectly pressures alternatives to active cold chain systems. Health Canada and the Canadian Food Inspection Agency maintain aligned but distinct validation standards that create cross-border compliance complexity for unified North American distribution strategies. Stakeholders must monitor how USP <1079> revisions and emerging state-level pharmaceutical waste regulations will reshape material selection and end-of-life recovery obligations.
Market Dynamics
The FDA's risk-based temperature excursion framework is compressing qualification timelines while forcing pharmaceutical shippers to revalidate entire packaging portfolios against stricter performance thresholds.
Growth Catalysts
- mRNA therapy expansion:Cell-based and nucleic acid treatments require stringent 2-8°C and ultra-cold chain integrity, pulling specialized insulated shippers into oncology and infectious disease distribution networks.
- Health Canada alignment pressures:Cross-border harmonization initiatives between FDA and Canadian regulators are standardizing validation protocols, reducing redundant qualification costs for unified North American supply chains.
- Vacuum-insulated panel adoption:VIP technology extends thermal duration beyond 120 hours, enabling intercontinental passive distribution without active refrigeration handoffs.
Market Restraints
- Phase-change material cost volatility:Paraffin and salt-hydrate feedstock prices fluctuate with petrochemical indices, compressing margins for gel pack manufacturers serving high-volume vaccine distributors.
- Regional supply concentration:Engineered foam barrier production clusters in the US Southeast, creating freight cost penalties for biopharma clients operating in the Northeast corridor.
- Active cold chain substitution:Refrigerated trucking and containerized active systems threaten passive formats in routes exceeding 96-hour transit windows.
Strategic Opportunities
- Canadian underpenetration:Ontario and Quebec biotech clusters lack localized passive packaging manufacturing, creating first-mover advantages for US-qualified suppliers with Health Canada validation capabilities.
- Reusable format mandates:Emerging state-level pharmaceutical waste regulations in California and Massachusetts are accelerating demand for returnable gel pack and shipper systems.
- IoT-PCM convergence:Integration of temperature loggers with phase-change materials enables real-time excursion alerting without compromising passive thermal mass performance.
Industry Challenges
- Thermal engineer scarcity:Packaging vendors struggle to hire ISTA 7E-qualified test engineers, extending client validation cycles and creating project backlogs.
- Legacy ERP integration:Pharmaceutical distributors face friction connecting passive packaging qualification databases to existing track-and-trace systems.
- Multi-agency compliance timelines:Simultaneous FDA, EPA refrigerant, and state waste regulation updates force redundant documentation rework.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | North America Passive Temperature Controlled Packaging Market |
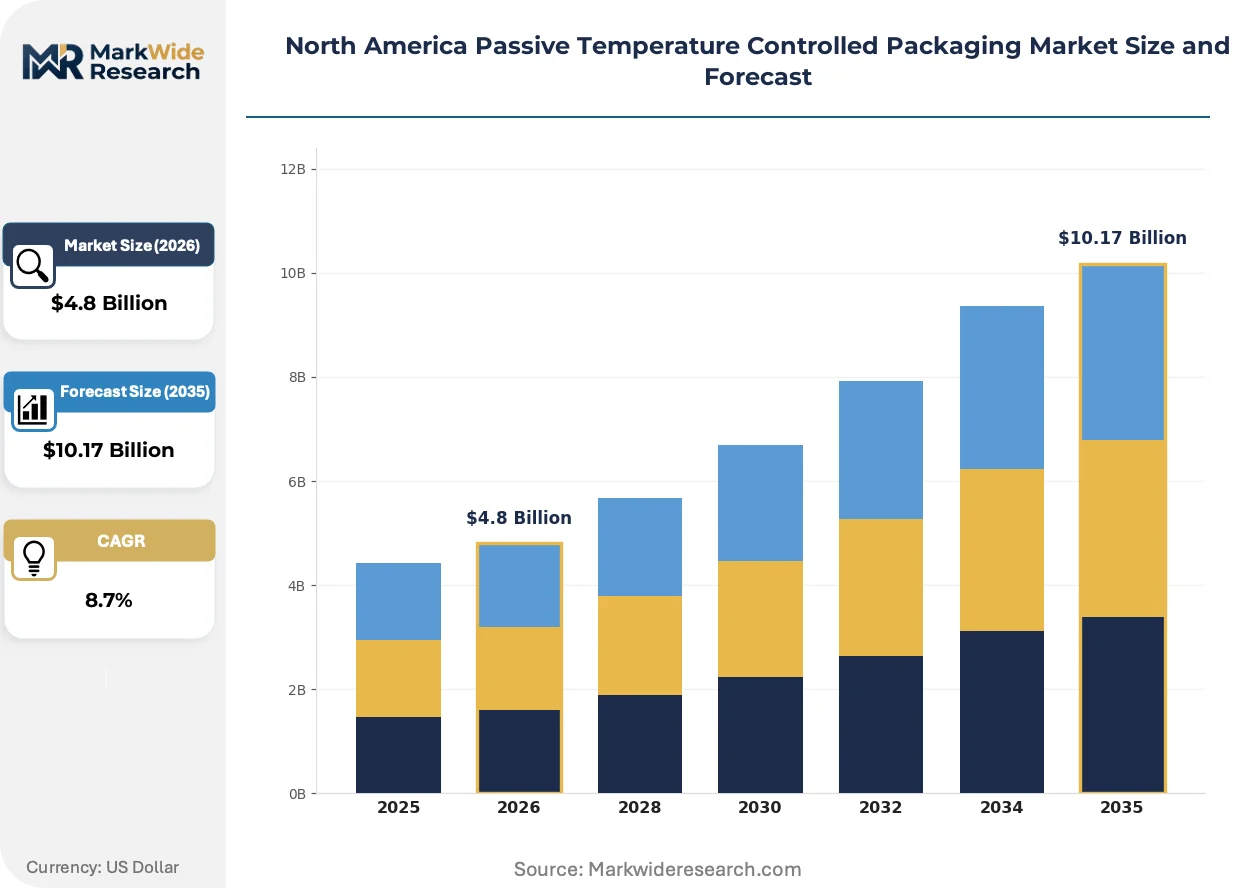
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $10.17 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Insulated Shippers, Thermal Pallets, Wraps, Containers End User: Pharmaceuticals, Food & Beverage, Biotechnology, Health Care Material: Foam, Cardboard, Gel Packs, Insulating Materials Temperature Range: 0-5°C, 2-8°C, -20°C, Ambient |
| Companies Covered | Sonoco Products Company, ThermoSafe Solutions, Cold Chain Technologies, Pelican Products, Inc., Cryopak Industries, Insulated Products Corporation, Packaging Corporation of America, Pelican BioThermal, Va-Q-Tec AG, Others |
| Regions Covered | North America: US, Canada, Mexico |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
North America Passive Temperature Controlled Packaging Market Evolving Landscape
Material science advances and regulatory digitization are fragmenting traditional thermal packaging categories while compressing the gap between laboratory performance and field reliability.
Vacuum-insulated panel technology is bifurcating the premium shipper segment. Cardiovascular biologics manufacturers with high-value payloads are adopting VIP-based formats at triple the rate of generic pharmaceutical distributors. This adoption pattern is compressing R&D investment into conventional expanded polystyrene barriers while expanding qualification laboratory capacity for advanced thermal modeling.
EPA refrigerant phase-down rules under the AIM Act are indirectly accelerating passive system adoption. Active refrigeration alternatives face hydrofluorocarbon supply constraints and servicing cost inflation, pushing vaccine distribution networks toward engineered foam and PCM solutions. The 2-8°C controlled room temperature segment is responding fastest, with distributors re-specifying pallet shippers to eliminate compressor dependency.
Performance-based procurement contracts are displacing unit-price purchasing in large biopharma accounts. Merck and Pfizer-scale buyers now specify thermal duration guarantees with penalty clauses rather than accepting manufacturer qualification reports at face value. This contractual evolution is most visible in Massachusetts and New Jersey cluster operations, where packaging vendors maintain dedicated field engineering staff for post-shipment performance verification.
North America Passive Temperature Controlled Packaging Market Segmentation
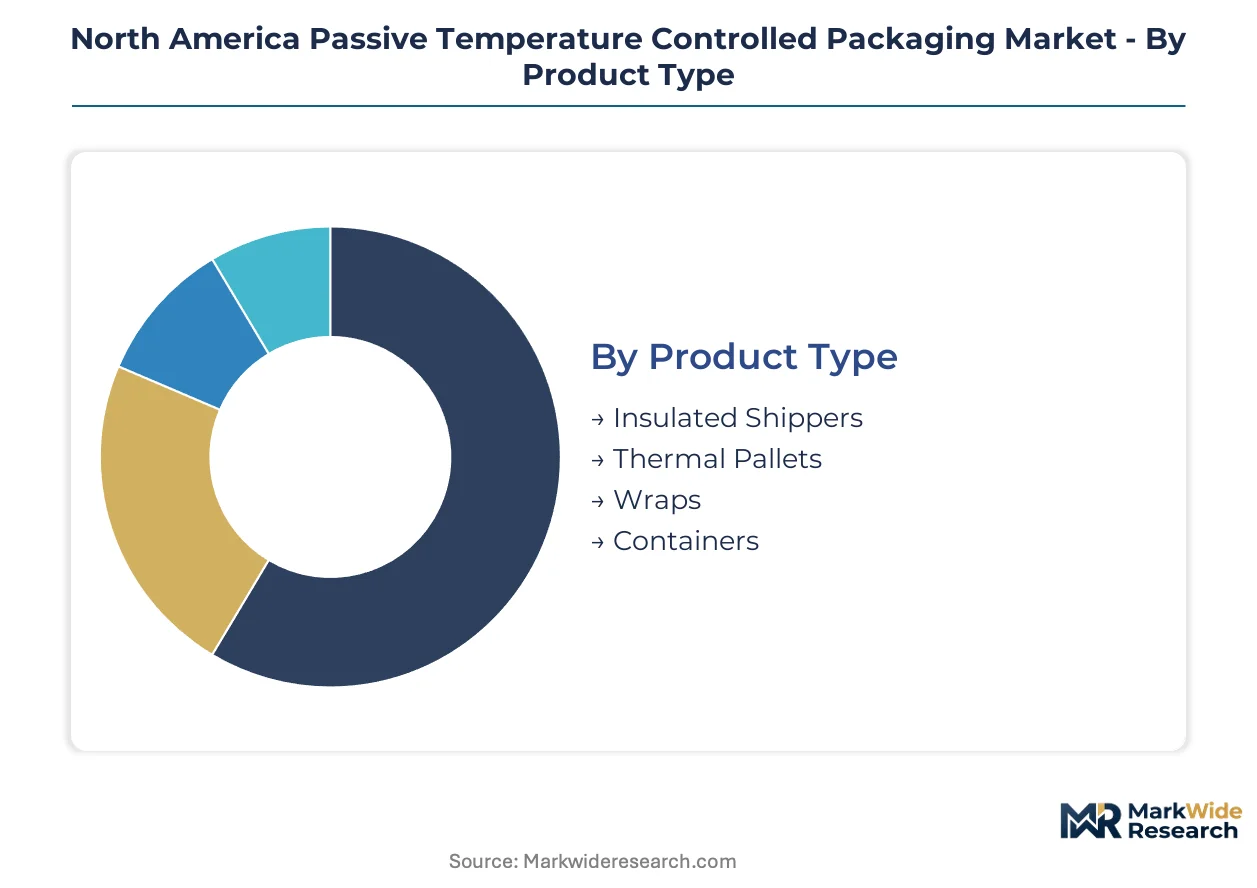
Passive temperature controlled packaging segments diverge sharply in qualification requirements and margin structure. FDA validation protocols for pharmaceutical applications impose testing burdens that reshape competitive positioning across product categories.
Product Type:
FDA's risk-based excursion framework differentiates qualification intensity by payload scale, compressing timelines for parcel formats while extending validation cycles for pallet-scale systems.
- Insulated Shippers:Corrugated shells with engineered foam or vacuum-insulated panel cores dominate parcel-scale pharmaceutical distribution. Massachusetts and New Jersey biotech clusters consume the majority of qualified shipper volume as mRNA therapy networks expand controlled room temperature distribution.
- Thermal Pallets:Large-format passive systems with phase-change material thermal mass replace active refrigeration in high-volume vaccine lanes. Pallet platforms face substitution pressure from refrigerated trucking on routes exceeding 96-hour transit windows.
- Wraps:Flexible insulating blankets with reflective barriers protect palletized payloads during last-mile handoffs. Food and beverage distributors favor wraps for seasonal produce protection where duration requirements remain under 48 hours.
- Containers:Reusable rigid formats with modular PCM cartridges serve intercontinental lanes requiring 120-plus hour thermal duration. Container adoption concentrates among cardiovascular biologics manufacturers with ultra-high-value payloads.
Insulated shippers handle the majority of throughput; gel pack-integrated containers are climbing the fastest on share.
End User:
Customer procurement maturity varies dramatically, with pharmaceutical buyers demanding performance guarantees while food and beverage purchasers prioritize unit economics.
- Pharmaceuticals:Cardiovascular and oncology biologics manufacturers specify ISTA 7E-qualified formats with thermal duration guarantees. Merck-scale and Pfizer-scale accounts now embed penalty clauses for excursion events, forcing vendors to maintain dedicated field engineering staff.
- Biotechnology:Cell-based therapy developers and nucleic acid treatment platforms require stringent 2-8°C and ultra-cold integrity. Massachusetts cluster operations pull specialized insulated shippers into infectious disease and personalized medicine distribution networks.
- Health Care:Hospital systems and specialty distributors balance qualification requirements against inventory turnover constraints. Health Care procurement favors reusable gel pack systems to comply with emerging state-level pharmaceutical waste regulations.
- Food & Beverage:Seasonal produce and premium protein distributors accept shorter thermal duration specifications in exchange for cost efficiency. Food and beverage demand concentrates in California and Florida agricultural export corridors.
Pharmaceuticals anchors revenue concentration; biotechnology is expanding most quickly on validation intensity.
Material:
Feedstock cost volatility and end-of-life recovery obligations are fragmenting supplier strategies across material categories.
- Gel Packs:Phase-change materials in paraffin or salt-hydrate formulations store and release latent heat at specified temperature setpoints. Reusable gel pack formats displace single-use alternatives as California and Massachusetts waste regulations tighten.
- Foam:Expanded polystyrene and polyurethane barriers provide cost-effective insulation for standard-duration lanes. Paraffin price fluctuations compress margins for foam-PCM composite manufacturers serving high-volume vaccine distributors.
- Insulating Materials:Vacuum-insulated panels and aerogel blankets deliver premium thermal performance for intercontinental distribution. VIP technology extends duration beyond 120 hours, enabling passive lanes without active refrigeration handoffs.
- Cardboard:Corrugated structural elements provide crush resistance and stackability for parcel-scale formats. Cardboard integration with engineered foam cores dominates Southeast manufacturing clusters supplying Northeast corridor demand.
Foam retains volume leadership; gel packs are gaining share fastest on reuse mandates.
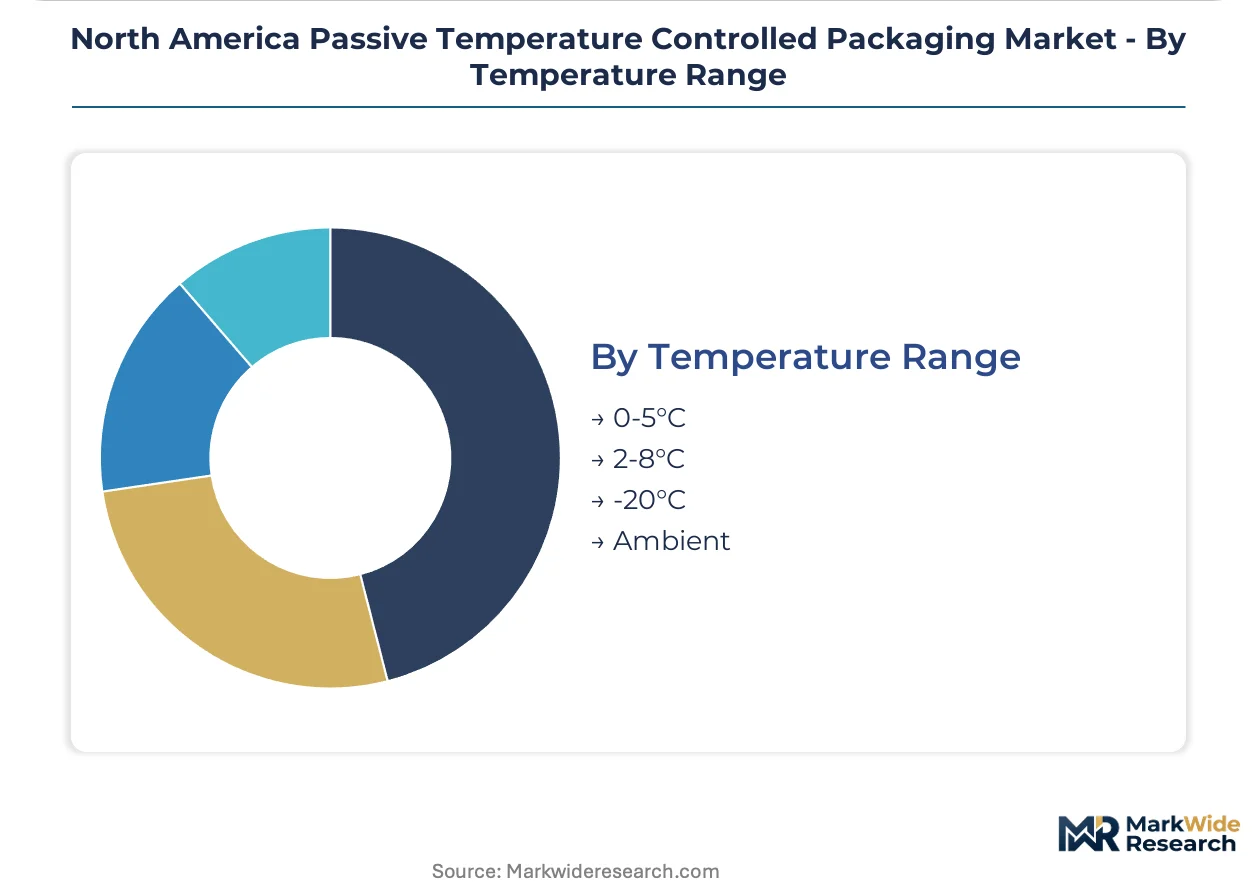
Temperature Range:
Payload thermal requirements dictate material selection, with controlled room temperature specifications commanding the broadest format availability.
- 2-8°C:Controlled room temperature range serves cardiovascular biologics, oncology therapeutics, and standard vaccine distribution. The 2-8°C segment occupies the largest margin pool as qualification protocols mature and format competition intensifies.
- -20°C:Frozen distribution for certain biologics and diagnostic reagents requires salt-hydrate PCM formulations with precise phase-change calibration. Ultra-cold demand concentrates in cell-based therapy networks with stringent stability requirements.
- 0-5°C:Narrow-band controlled temperature serves specialty vaccines and temperature-sensitive intermediates. 0-5°C specifications face format scarcity as manufacturers prioritize broader 2-8°C qualification coverage.
- Ambient:Protection against extreme heat or cold exposure for products stable at room temperature. Ambient-controlled formats expand in generic pharmaceutical distribution where excursion risk management supplements stability data.
2-8°C handles the majority of qualified volume; -20°C is the fastest mover on therapy complexity.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
FDA's risk-based excursion framework anchors the United States as the dominant geography, with Health Canada alignment pressures and Mexican pharmaceutical manufacturing expansion creating cross-border integration opportunities across North America.
United States
mRNA therapy networks and cell-based treatment platforms in Massachusetts and New Jersey pull specialized insulated shippers into high-volume distribution lanes. The FDA's updated temperature excursion management guidance compresses qualification timelines while forcing revalidation of entire packaging portfolios. The Northeast corridor from Boston to Princeton concentrates biopharma cold chain demand, with packaging vendors maintaining dedicated field engineering staff for post-shipment verification.
Canada
Ontario and Quebec biotech clusters lack localized passive packaging manufacturing, creating first-mover advantages for US-qualified suppliers. Health Canada and the Canadian Food Inspection Agency maintain aligned but distinct validation standards that generate cross-border compliance complexity. Toronto and Montreal pharmaceutical distribution hubs increasingly demand Health Canada-validated formats from suppliers with dual FDA-Health Canada qualification capabilities.
Mexico
Nearshoring of pharmaceutical manufacturing to Baja California and Mexico City metro areas expands demand for temperature-controlled export packaging. Mexican pharmaceutical regulators enforce stability testing requirements that mirror FDA protocols for products destined for US markets. The Tijuana medical device cluster and Mexico City pharmaceutical production zones drive adoption of 2-8°C qualified shippers for cross-border distribution.
Southeast United States
Engineered foam barrier production concentrates in Georgia and the Carolinas, creating freight cost penalties for Northeast biopharma clients. Sonoco Products Company leverages corrugated manufacturing footprints to dominate insulated shipper production in this region. Atlanta and Charlotte distribution hubs serve as consolidation points for passive packaging materials flowing to pharmaceutical clusters in the Northeast corridor.
California
State-level pharmaceutical waste regulations in California accelerate demand for reusable gel pack and shipper systems. San Diego and San Francisco biotech clusters require stringent 2-8°C integrity for cell therapy and nucleic acid distribution. The state's evolving extended producer responsibility frameworks reshape material selection and end-of-life recovery obligations for packaging vendors serving West Coast pharmaceutical accounts.
North America Passive Temperature Controlled Packaging Market Competitive Landscape
A small set of integrated leaders sits above a broader specialist tier in North American passive temperature controlled packaging. The upper tier combines corrugated manufacturing with qualification testing services, while mid-cap specialists focus on thermal pallet platforms or phase-change material formulations. Three archetypes dominate: integrated packaging conglomerates with multi-material capabilities, thermal engineering specialists with ISTA 7E laboratory accreditation, and European VIP technology licensors seeking North American manufacturing partnerships. Capacity expansion in Canadian validation capabilities and strategic partnerships for IoT-logger integration represent the dominant competitive moves.
Among US-based integrated packaging suppliers, Sonoco Products Company and Packaging Corporation of America exemplify the conglomerate archetype with corrugated manufacturing footprints serving pharmaceutical distribution networks. ThermoSafe Solutions occupies a position within the specialist tier, anchoring competitive positioning through qualification testing services that reduce client validation cycles. Cold Chain Technologies represents the thermal platform specialist archetype, with its naming convention suggesting focused expertise in cold chain infrastructure.
| Leading Market Players |
|---|
| Sonoco Products Company |
| ThermoSafe Solutions |
| Cold Chain Technologies |
| Pelican Products, Inc. |
| Cryopak Industries |
| Insulated Products Corporation |
| Packaging Corporation of America |
| Pelican BioThermal |
| Va-Q-Tec AG |
| Others |
Value Network & Pricing Analysis
ISTA 7E qualification protocols gate both supplier entry and price tiering simultaneously, compressing margins for uncertified foam converters while extending premium capture for accredited testing laboratories. Pharmaceutical buyers embed thermal duration guarantees with penalty clauses, forcing price stratification around validation depth rather than material cost alone.
Pricing Analysis
Massachusetts corridor pricing runs fifteen to twenty percent above Southeast manufacturing origins on identical shipper specifications. Three-tier pricing structure across premium VIP-based, standard EPS-foam, and economy cardboard-wrap levels separates cardiovascular biologics manufacturers from generic pharmaceutical distributors from seasonal produce exporters. Cost compression in standard-duration lanes is intensifying because paraffin feedstock volatility feeds through PCM composite pricing. Food and beverage distributors exhibit highest price sensitivity; cell-based therapy developers accept premium positioning for excursion liability transfer.
Supply Chain Analysis
Container availability constraints on Asia-North America trade lanes inflate inbound logistics costs for VIP core materials and aerogel blanket substrates. Engineered foam barrier production draws from Georgia, South Carolina, and North Carolina manufacturing clusters; phase-change material formulations rest on Texas and Louisiana petrochemical feedstock access. Single-source vulnerability concentrates in salt-hydrate PCM precursors sourced from Chinese chemical processors. Distribution runs through Atlanta and Charlotte consolidation hubs before final-mile deployment to Northeast corridor biotech clusters.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Early-cycle expansion characterizes this market as mRNA therapy networks penetrate infectious disease and oncology distribution lanes previously served by active refrigeration. Penetration depth remains shallow outside Massachusetts-New Jersey corridor concentration.
For Market Incumbents: Secure Health Canada validation capabilities before Ontario and Quebec biotech clusters mature, insulating against cross-border harmonization tailwinds. Deepen backward integration into paraffin and salt-hydrate feedstock channels to buffer PCM cost volatility. Active cold chain substitution on 96-plus hour routes threatens pallet-platform margins; respond with VIP duration extension to 120-hour thresholds.
For New Entrants and Emerging Players: Anchor in Canadian underpenetration, where localized manufacturing absence creates first-mover advantages for US-qualified suppliers with dual FDA-Health Canada protocols. Target reusable gel pack systems as California and Massachusetts pharmaceutical waste regulations tighten. Go-to-market angle should emphasize IoT-logger integration for real-time excursion alerting without passive thermal mass compromise.
For Investors and Strategic Acquirers: Carve-out targets emerge from corrugated conglomerates with dormant cold chain capabilities and stranded thermal engineering talent. Long-term viability frames around biopharma cold chain talent scarcity and regulatory digitization tailwinds sustaining qualification service premiums. Acquisition archetype: mid-cap ISTA 7E-accredited testing laboratories with pharmaceutical client relationships. Signal to watch: EPA refrigerant phase-down acceleration pushing vaccine distributors toward passive system re-specification.
| Strategic Initiative | Industry Significance |
|---|---|
| Health Canada Validation Investment | Dual FDA-Health Canada protocols capture Ontario-Quebec biotech expansion before local manufacturing emerges. |
| VIP Technology Licensing Partnership | European aerogel and vacuum-panel licensors seek North American manufacturing footholds for 120-hour duration formats. |
| Reusable Gel Pack System Development | California and Massachusetts extended producer responsibility frameworks mandate returnable PCM alternatives. |
| IoT-Logger Integration Program | Temperature logger convergence with phase-change materials enables real-time excursion alerting without thermal mass degradation. |
| Thermal Engineer Talent Acquisition | ISTA 7E-qualified test engineer scarcity extends client validation cycles, creating captive laboratory value. |
Research Methodology
Cross-validation between primary interviews with cold chain logistics directors and secondary validation through FDA guidance documents anchors the qualitative findings. Thermal packaging engineering leads, pharmaceutical distribution procurement managers, biotech supply chain directors, and ISTA laboratory accreditation officers provided structured input. Secondary sources include EPA refrigerant phase-down rulemakings, Health Canada validation standards, USP <1079> revision drafts, and customs trade data on PCM feedstock flows. Bottom-up shipper volume estimates and top-down biopharma cold chain expenditure analysis triangulate market sizing.
Sensitivity analysis around mRNA therapy adoption curves and EPA refrigerant phase-down acceleration brackets projection uncertainty. Segmentation dimensions span product type, end user, material composition, temperature range, and regional regulatory cluster. CAGRs derive from segment-level volume trajectories weighted by qualification intensity and margin structure. Industry-specific inputs include ISTA 7E testing capacity expansion rates and Health Canada-FDA harmonization timeline assumptions.
Decision-makers should treat outputs as directional under sustained biopharma cold chain investment and passive system preference stability; material deviation would warrant model refresh. Forecasts embed assumptions around regulatory digitization pace and reusable format mandate diffusion. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Cold Chain Packaging
Cooling Boxes Market
Cold Chain Packaging
Freezer Liner Market
Cold Chain Packaging
Cold Chain Micro-Fulfillment Hub Networks Market
Cold Chain Packaging
Cold Chain Equipment Market
Cold Chain Packaging
Fish Boxes Market
Cold Chain Packaging
Pharmaceutical Cold Chain Packaging Market
Cold Chain Packaging
Cold Chain Temperature Monitoring Market
Cold Chain Packaging
Food Cold Chain Market
Cold Chain Packaging
Global Cold Chain Tracking and Monitoring Market
Cold Chain Packaging
Europe Healthcare Cold Chain Logistics Market
Cold Chain Packaging
Foam Cooler Box Market
Cold Chain Packaging
Refrigeration Packaging Market
Cold Chain Packaging
Cold Chain Integrity and Shock Monitoring Test Devices Market
Cold Chain Packaging
Cold Chain Packaging Pooling and Reverse Logistics Services Market
Cold Chain Packaging
Ice Boxes Market
Cold Chain Packaging
Biopharma Cold Chain Packaging Market