
 Europe Cold Chain Tracking and Monitoring Market | 2026-2036
Europe Cold Chain Tracking and Monitoring Market Size, Share, and Industry Trends Forecast 2026-2036
Europe Cold Chain Tracking and Monitoring Market Analytics
Equipment leasing and sensor-as-a-service models are fragmenting capital requirements across the European cold chain tracking landscape. Sensitech leverages its refrigerated transport heritage to anchor premium pharmaceutical contracts across Benelux corridors. Zebra Technologies competes through ruggedized hardware ecosystems that dominate warehouse and last-mile environments. ELPRO-Buchs AG specializes in validated thermal packaging solutions that sustain compliance margins in clinical trial logistics.
Europe Cold Chain Tracking and Monitoring encompasses integrated hardware-software systems that measure, record, and transmit temperature, humidity, location, and shock data across temperature-sensitive supply chains, typically operating within calibrated ranges from minus 80 degrees Celsius to plus 25 degrees Celsius with audit-grade traceability. These systems serve primarily to prevent product degradation, ensure regulatory compliance, and enable root-cause analysis during temperature excursions. IoT platforms now lead technology adoption by enabling continuous cloud telemetry that displaces intermittent manual readings, while RFID retains structural importance in pharmaceutical serialization mandates where item-level pedigree verification remains compulsory. The food and beverage application segment generates the broadest installed base though pharmaceutical deployments command the deepest per-unit margins due to validation requirements.
The EU Good Distribution Practice enforced by EMA national competent authorities mandates qualified equipment and documented temperature control for medicinal products, directly elevating demand for validated monitoring systems. REACH and RoHS frameworks from ECHA constrain sensor material composition, shaping hardware design cycles and supplier qualification protocols across the continent. France's ANSM and Germany's regional pharmacy chambers conduct unannounced inspections that enforce calibration traceability standards. Stakeholders must monitor how the EU AI Act and forthcoming CSRD reporting obligations will expand algorithmic transparency requirements for predictive cold chain analytics platforms.
Market Dynamics
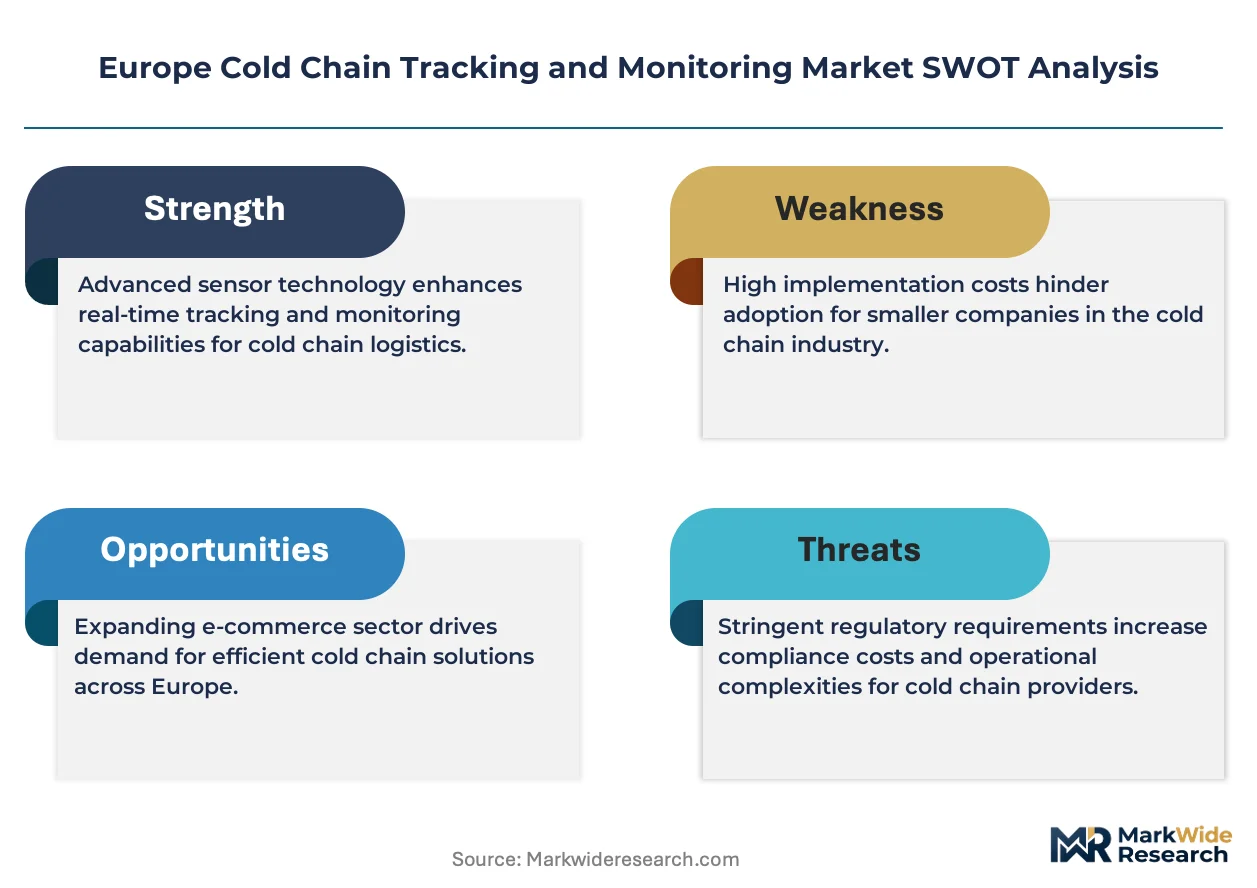
IoT-enabled sensor platforms are compressing equipment replacement cycles across European pharmaceutical corridors, forcing logistics operators to abandon legacy data logger architectures before full depreciation.
Growth Catalysts
- EU Good Distribution Practice mandates:EMA national competent authorities enforce qualified equipment and documented temperature control, compelling medicinal product distributors to deploy validated monitoring systems.
- Cell and gene therapy cold chains:Ultra-low temperature requirements from minus 150 to minus 80 degrees Celsius for mRNA vaccines and CAR-T treatments are expanding demand for cryogenic-capable telemetry platforms.
- Spain's fresh produce export corridors:Perishable agricultural shipments to Middle Eastern and Asian markets require continuous humidity and shock monitoring to reduce spoilage claims.
Market Restraints
- Lithium battery supply concentration:Dependence on East Asian cell manufacturers for IoT sensor power systems creates input volatility and extended lead times for hardware procurement.
- REACH substance restrictions:ECHA frameworks constrain sensor material composition, forcing redesign cycles that delay product certification and market entry.
- Calibration infrastructure gaps:Limited accredited laboratories in Eastern Europe extend equipment qualification timelines and raise total cost of ownership for cross-border operators.
Strategic Opportunities
- Sensor-as-a-service models:Subscription-based hardware provisioning reduces capital barriers for mid-tier logistics providers in Poland and Romania.
- EU AI Act compliance tools:Algorithmic transparency requirements for predictive analytics platforms create demand for explainable machine learning in cold chain risk scoring.
- Nordic biologics manufacturing:Sweden and Denmark's expanding pharmaceutical production clusters require integrated monitoring from manufacturing through last-mile distribution.
Industry Challenges
- Validation engineering talent scarcity:Qualified personnel for IQ/OQ/PQ documentation and thermal mapping studies are concentrated in Germany and Switzerland, creating recruitment bottlenecks.
- Legacy warehouse management system integration:SOAP-based ERP architectures in established European logistics networks resist API connectivity with modern cloud telemetry platforms.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe Cold Chain Tracking and Monitoring Market |
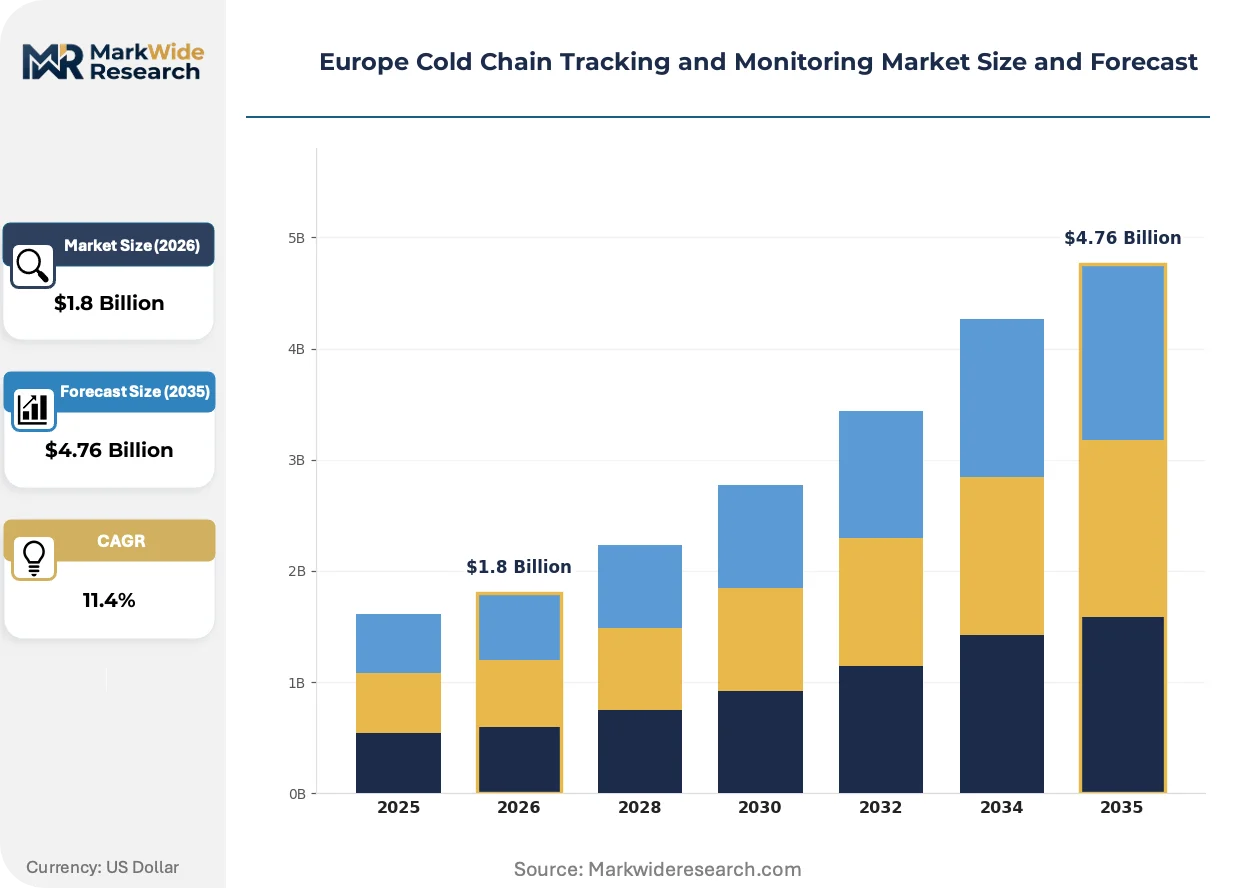
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $4.76 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Technology: RFID, GPS, Sensors, IoT Application: Pharmaceutical, Food & Beverage, Chemicals, Perishables End User: Retailers, Logistics Providers, Manufacturers, Distributors Delivery Mode: Cloud-based, On-premise, Hybrid, Mobile Solutions |
| Companies Covered | Sensitech, Honeywell International, Berlinger & Co. AG, Digi International, Zebra Technologies, ELPRO-Buchs AG, Emerson Electric, ORBCOMM, Controlant, Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe Cold Chain Tracking and Monitoring Market Evolving Landscape
Digital twin architectures and edge computing are restructuring how temperature-sensitive cargo is monitored, shifting from reactive exception reporting toward predictive intervention systems.
Bluetooth Low Energy mesh networks combined with cloud-native telemetry stacks are rendering obsolete standalone USB data loggers that require manual download and retrospective analysis. Pharmaceutical distributors in the Netherlands and Belgium are deploying these systems fleet-wide within eighteen-month refresh cycles. The structural compression of exception response time from hours to seconds is eliminating temperature excursion blind spots during multimodal handoffs.
France's ANSM and Germany's regional pharmacy chambers are intensifying unannounced inspection protocols for calibration traceability, compelling operators to adopt blockchain-anchored audit trails. This regulatory pressure is fragmenting supplier qualification processes and raising documentation burdens. Cold storage facilities in Lyon and Frankfurt are responding by consolidating monitoring vendors to reduce compliance audit complexity.
Leasing structures now dominate hardware acquisition in Southern Europe, with Italian and Spanish logistics providers preferring operational expenditure models over capital purchases. Equipment financiers are capturing margin pools previously held by sensor manufacturers. This shift is most pronounced in temperature-controlled last-mile fleets serving restaurant and pharmacy networks.
Europe Cold Chain Tracking and Monitoring Market Segmentation
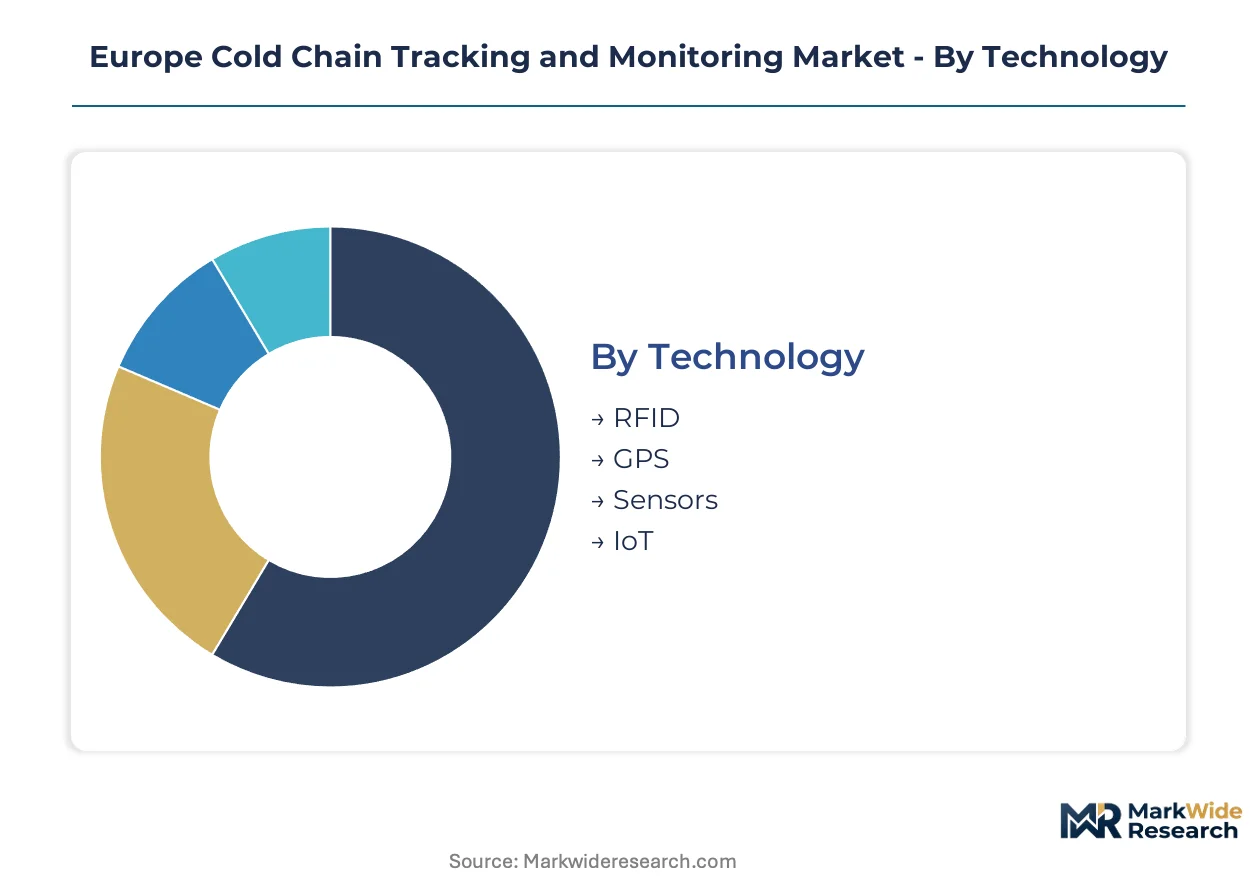
Segmentation in the European cold chain tracking and monitoring market reveals divergent equipment refresh cycles and margin structures. Pharmaceutical applications demand validated systems with extended replacement timelines, while food logistics operators cycle hardware faster to capture IoT efficiency gains.
Technology:
Sensor platforms turn over fastest where cloud connectivity obsoletes manual data retrieval, while RFID architectures persist longest in serialized pharmaceutical environments.
- Sensors:Temperature, humidity, and shock transducers with calibrated measurement ranges from minus 80 to plus 25 degrees Celsius. Demand clusters in Germany's vaccine distribution hubs where EMA Good Distribution Practice mandates continuous telemetry and automated excursion alerts.
- IoT:Cloud-native platforms enabling real-time data transmission via cellular or satellite networks. Nordic logistics corridors in Sweden and Denmark are displacing legacy data loggers fastest as biologics manufacturing expands and requires uninterrupted visibility.
- RFID:Passive and active radio-frequency identification for item-level tracking without battery dependence. Pharmaceutical serialization mandates across France and Benelux sustain structural demand despite slower growth.
- GPS:Location-tracking modules integrated with temperature monitoring for multimodal shipment visibility. Fresh produce exporters in Spain deploy these for Middle Eastern and Asian corridor transparency.
IoT platforms dominate installed base growth. Sensors represent the fastest-growing trajectory as hardware refresh accelerates.
Application:
Cost tier separation is pronounced: pharmaceutical deployments absorb premium validation expenses, while food and beverage operators prioritize unit economics at scale.
- Pharmaceutical:Validated monitoring for vaccines, biologics, and clinical trial materials with full IQ/OQ/PQ documentation. CAR-T and mRNA cold chains in Germany and Switzerland drive cryogenic-capable telemetry demand.
- Food & Beverage:Broadest installed base spanning dairy, meat, and prepared meals with HACCP-aligned monitoring. Spain's agricultural export corridors to Asia concentrate humidity and shock sensing requirements.
- Perishables:Temperature-sensitive flowers, fresh produce, and specialty foods with shorter transit windows. Italian last-mile fleets serving restaurant networks favor leased sensor-as-a-service models.
- Chemicals:Industrial and specialty chemical transport with hazardous material compliance overlays. REACH substance restrictions from ECHA constrain sensor material selection and extend certification timelines.
Food and beverage commands volume leadership. Pharmaceutical applications capture the steepest margin expansion.
End User:
Customer type determines procurement structure: capital-constrained operators lease, while integrated manufacturers captive-source monitoring infrastructure.
- Logistics Providers:Third-party cold chain operators managing multi-client pharmaceutical and food networks. Benelux corridors anchor premium contracts as Sensitech and Zebra Technologies compete for fleet-wide deployments.
- Manufacturers:Pharmaceutical and food producers integrating monitoring from production through distribution. Nordic biologics clusters in Sweden and Denmark require seamless manufacturing-to-last-mile telemetry.
- Distributors:Wholesale medicinal product and perishable goods distributors subject to unannounced inspections. France's ANSM and Germany's regional pharmacy chambers enforce calibration traceability standards.
- Retailers:Supermarket chains and pharmacy networks with temperature-controlled last-mile requirements. Southern European operators in Italy and Spain prefer operational expenditure models over hardware purchases.
Logistics providers anchor contract value. Manufacturers are where technology integration concentrates deepest.
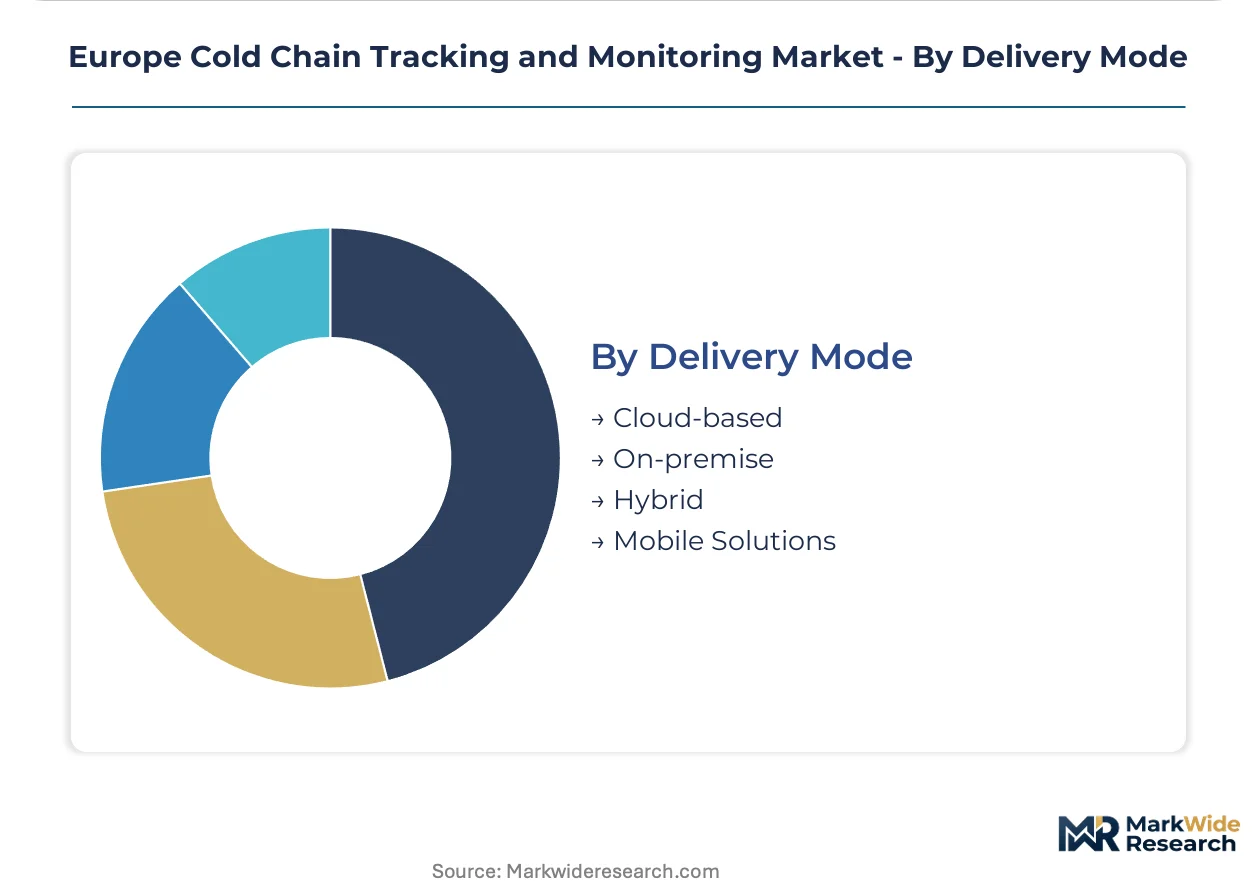
Delivery Mode:
Maturity gradient separates established on-premise architectures from cloud-native deployments capturing new capacity.
- Cloud-based:SaaS telemetry platforms with continuous data ingestion and predictive analytics. Netherlands and Belgium pharmaceutical distributors are deploying these fleet-wide within compressed refresh cycles.
- Hybrid:Edge computing with local data buffering and periodic cloud synchronization. Eastern European operators facing calibration infrastructure gaps favor these for offline resilience.
- Mobile Solutions:Smartphone-integrated Bluetooth Low Energy readers for last-mile and small-scale operations. Italian restaurant supply fleets leverage these for cost-effective route monitoring.
- On-premise:Legacy server-based systems with manual data management. Established logistics networks with SOAP-based ERP architectures resist API connectivity with modern platforms.
Cloud-based systems dominate new deployment share. Hybrid architectures are expanding most quickly in infrastructure-constrained geographies.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
EU Good Distribution Practice enforcement by EMA national competent authorities is accelerating sensor deployment across pharmaceutical corridors. REACH substance restrictions from ECHA reshape hardware design cycles continent-wide. Nordic biologics manufacturing clusters and Mediterranean fresh produce export hubs concentrate demand.
Germany
Vaccine distribution hubs in Frankfurt and Munich anchor pharmaceutical cold chain investment. Regional pharmacy chambers conduct unannounced inspections enforcing calibration traceability standards. Bavaria's biologics manufacturing corridor demands cryogenic-capable telemetry from minus 80 degrees Celsius for mRNA and CAR-T therapies.
Netherlands
Rotterdam and Schiphol logistics corridors serve as European pharmaceutical import gateways requiring continuous cloud telemetry. Benelux distributors deploy Bluetooth Low Energy mesh networks fleet-wide within compressed eighteen-month refresh cycles. Amsterdam-based operators consolidate monitoring vendors to reduce compliance audit complexity.
Spain
Fresh produce exporters to Middle Eastern and Asian markets drive humidity and shock sensing requirements. Valencia and Almería agricultural corridors favor leased sensor-as-a-service models over capital purchases. ANSM-aligned calibration protocols govern pharmaceutical shipments through Barcelona distribution nodes.
Sweden
Stockholm-Uppsala biologics manufacturing clusters require integrated monitoring from production through last-mile distribution. Nordic logistics operators displace legacy data loggers fastest as IoT platforms enable uninterrupted visibility. REACH-compliant sensor material selection constrains hardware procurement timelines.
France
ANSM intensifies unannounced inspection protocols for calibration traceability across Lyon and Paris pharmaceutical storage facilities. Clinical trial logistics in the Île-de-France region sustain demand for validated thermal packaging solutions. Blockchain-anchored audit trails emerge as response to regulatory documentation burdens.
Europe Cold Chain Tracking and Monitoring Market Competitive Landscape
On the supply side, the industry is consolidating around three strategic tiers. Equipment manufacturers with refrigerated transport heritage anchor premium pharmaceutical contracts. Ruggedized hardware specialists dominate warehouse and last-mile environments. Validated packaging engineers capture compliance-margin opportunities in clinical trial logistics. Dominant competitive moves include sensor-as-a-service leasing structures and API integration partnerships with cloud telemetry platforms.
Within the heritage transport-monitoring tier, Sensitech occupies a position exemplifying pharmaceutical corridor anchoring. Zebra Technologies and ELPRO-Buchs AG represent divergent specialization vectors—ruggedized warehouse ecosystems versus validated thermal packaging documentation—illustrating how hardware durability requirements and compliance validation burdens create distinct competitive positioning.
| Leading Market Players |
|---|
| Sensitech |
| Honeywell International |
| Berlinger & Co. AG |
| Digi International |
| Zebra Technologies |
| ELPRO-Buchs AG |
| Emerson Electric |
| ORBCOMM |
| Controlant |
| Others |
Value Network & Pricing Analysis
Frankfurt's vaccine distribution corridor anchors continental capacity for validated cold chain telemetry, with EMA Good Distribution Practice enforcement concentrating procurement power among qualified equipment vendors serving pharmaceutical distributors. This geographic supply concentration translates into pricing leverage for certified sensor manufacturers, while REACH-compliant hardware redesign cycles compress margins for second-tier suppliers.
Pricing Analysis
Certification level creates the primary spread between premium and economy tiers, with CE-marked and EMA-validated systems commanding substantial premiums over uncertified alternatives. Three-tier pricing structure across premium, standard, and economy levels reflects validation depth, after-sales calibration support, and software integration complexity. Cost compression in the standard tier is intensifying because IoT platform commoditization erodes hardware differentiation. Small logistics providers in Southern Europe exhibit highest price sensitivity, while German pharmaceutical distributors absorb premium pricing for audit-grade traceability.
Supply Chain Analysis
Lithium cell feedstock draws predominantly from East Asian manufacturers, with sensor assembly concentrated in Germany, Switzerland, and select Eastern European facilities. Hardware production rests on semiconductor components, battery systems, and calibrated transducer elements. Single-source vulnerability in cryogenic sensor substrates creates exposure to extended qualification timelines. Distribution runs through specialized pharmaceutical logistics integrators and food export corridor operators with fleet-wide deployment mandates.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Validation engineering talent scarcity constrains market expansion, with IQ/OQ/PQ documentation specialists and thermal mapping experts concentrated in German and Swiss clusters. This capability gap creates competitive moats for incumbents while raising entry barriers for new hardware platforms.
For Market Incumbents: Harden compliance documentation capabilities through captive calibration laboratory investments in Benelux corridors, where ANSM and EMA inspection intensity is accelerating. Consolidate vendor relationships to reduce audit complexity for pharmaceutical distributors facing unannounced regulatory scrutiny. Defensive positioning against sensor-as-a-service entrants requires embedding software analytics deeper into hardware lease structures. For New Entrants and Emerging Players: Establish a beachhead in Poland and Romania's mid-tier logistics segments, where capital constraints favor subscription-based hardware provisioning over capital purchases. Target fresh produce export corridors in Spain's Valencia agricultural cluster, where humidity and shock monitoring demand outpaces qualified supplier presence. A channel partnership strategy with Italian equipment financiers captures operational expenditure preference among restaurant supply fleets. For Investors and Strategic Acquirers: Mid-cycle technology positioning favors vertically integrated platforms combining sensor hardware with cloud-native telemetry stacks over point-solution data logger vendors. Long-term viability hinges on AI Act compliance capabilities for predictive analytics transparency. Acquisition targets should demonstrate explainable machine learning architectures and established EMA qualification pathways. The signal to watch is consolidation momentum among Southern European leasing providers seeking technology differentiation.| Strategic Initiative | Industry Significance |
|---|---|
| Calibration Infrastructure Expansion | Accredited laboratory capacity in Eastern Europe reduces equipment qualification timelines for cross-border operators. |
| Sensor-as-a-Service Platform Launch | Subscription hardware provisioning lowers capital barriers for mid-tier logistics providers in Poland and Romania. |
| EU AI Act Compliance Tool Development | Explainable machine learning architectures satisfy algorithmic transparency mandates for predictive cold chain risk scoring. |
| Blockchain-Anchored Audit Trail Integration | Immutable documentation streams address ANSM and German pharmacy chamber intensified inspection protocols. |
| API Integration Partnership Program | Cloud telemetry connectivity overcomes legacy SOAP-based ERP resistance in established European logistics networks. |
Research Methodology
Initial hypotheses were tested against primary input from cold chain logistics directors, pharmaceutical quality assurance managers, sensor platform engineers, and equipment financing specialists and refined through secondary validation. Regulatory filings from EMA and national competent authorities, REACH substance restriction databases, customs equipment import records, and IoT platform deployment disclosures anchored quantitative estimates. Bottom-up sensor shipment analysis and top-down cold chain infrastructure spending triangulation converged on market sizing.
Demand-supply balance framing structured the analytical approach across the analysis window, with segmentation modeled across technology platform, application vertical, end-user archetype, and delivery mode dimensions. CAGRs were derived from equipment refresh cycle compression rates and regulatory mandate implementation timelines. Cryogenic-capable telemetry adoption curves and cloud-native platform displacement rates informed trajectory assumptions.
Stress conditions across lithium battery supply volatility, REACH redesign cycle extensions, and calibration infrastructure development gaps were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions regarding EMA enforcement intensity and IoT platform commoditization pace. Cross-checking against ECHA regulatory impact assessments and national pharmacy chamber inspection frequency data is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Cold Chain Packaging
Cold Storage Insulated Market
Cold Chain Packaging
China Cold Chain Market
Cold Chain Packaging
Insulated Food Delivery Bags Market
Cold Chain Packaging
Cold Chain Packaging Pooling and Reverse Logistics Services Market
Cold Chain Packaging
Cryo Box Market
Cold Chain Packaging
Reusable Cold Chain Packaging Market
Cold Chain Packaging
Freezer Liner Market
Cold Chain Packaging
Ice Boxes Market
Cold Chain Packaging
North America Passive Temperature Controlled Packaging Market
Cold Chain Packaging
Cold Chain Packaging Market
Cold Chain Packaging
Cold Chain Micro-Fulfillment Hub Networks Market
Cold Chain Packaging
Cold Box Module Market
Cold Chain Packaging
Cryogenic Capsules Market
Cold Chain Packaging
Cold Chain Market
Cold Chain Packaging
Pharmaceutical Cold Chain Packaging Market
Cold Chain Packaging
North America Cold Chain Market