
 Middle East and Africa Pharmaceutical Vials Market | 2026-2036
Middle East and Africa Pharmaceutical Vials Market Size, Share, and Industry Trends Forecast 2026-2036
Middle East and Africa Pharmaceutical Vials Market Foresight
Direct procurement channels between Saudi and Emirati biomanufacturers and European glass converters is narrowing as regional converters expand borosilicate melting capacity. Schott AG leverages its tubular glass technology leadership to supply GCC vaccine fill-finish lines. Gerresheimer AG anchors North African distribution through its Egyptian secondary processing facility. RAK Ghani Glass LLC competes on proximity, cutting sea-freight lead times for UAE-based sterile injectables producers.
Pharmaceutical vials are rigid primary containers, typically fabricated from Type I borosilicate glass or cyclic olefin polymer, designed to maintain sterility, chemical stability, and seal integrity for parenteral drug products. These vessels must comply with pharmacopeial standards for hydrolytic resistance, particulate limits, and dimensional tolerance to ensure patient safety across liquid, lyophilized, and powder drug presentations. Glass vials still dominate the Middle East and Africa landscape, though pre-filled syringe formats are capturing share in biologics as healthcare systems prioritize dose accuracy and reduced medication errors. Single-dose ampoules and vials sustain stronger margin pools than multi-dose alternatives because regulatory pressure on antimicrobial preservatives forces formulation shifts toward preservative-free, unit-of-use packaging.
Saudi Food and Drug Authority and South African Health Products Regulatory Authority enforce pharmacopeial compliance that bars substandard packaging from government tender programs. The UAE's Ministry of Health and Prevention aligns with GCC Central Drug Registration requirements, creating a harmonized but stringent barrier to non-conforming imports. Stakeholders must monitor how Egypt's drug authority implements traceability mandates for serialized vial labels, as this will reshape supplier qualification criteria and capital allocation for coding and aggregation equipment.
Market Dynamics
Cold-chain biologics expansion across Gulf Cooperation Council states is reconfiguring pharmaceutical vial specifications, as temperature-sensitive vaccines and monoclonal antibodies demand borosilicate glass with enhanced thermal shock resistance and validated container closure integrity.
Growth Catalysts
- SFDA Localization Mandates:Saudi Food and Drug Authority procurement rules favor domestic vaccine fill-finish capacity, compelling international glass converters to establish regional melting and conversion operations.
- Biotech Industrial City Investments:Saudi Arabia's dedicated biomanufacturing zones attract sterile injectables producers requiring immediate proximity to qualified vial suppliers.
- Lyophilization-Compatible Formats:Freeze-dried biologics penetration drives demand for tubing vials with optimized heel geometry and controlled wall thickness distribution.
Market Restraints
- High-Purity Sand Concentration:Pharmaceutical-grade silica sourcing concentrates in limited geographies outside the Middle East and Africa, exposing converters to maritime freight volatility and customs clearance delays.
- SFDA and SAHPRA Compliance Barriers:Divergent pharmacovigilance documentation requirements between Saudi and South African regulators force redundant qualification testing and extended approval timelines.
- Pre-Filled Syringe Substitution:Unit-dose syringe formats capture share in biologics administration, compressing addressable vial volume in high-value therapeutic categories.
Strategic Opportunities
- Egyptian Traceability Mandates:Serialized vial label requirements under Egypt's drug authority create demand for integrated coding and aggregation equipment partnerships.
- UAE Sterile Injectables Cluster:Dubai Science Park and KIZAD free zone concentrations enable just-in-time vial supply models with sub-48-hour lead times.
- Cyclic Olefin Polymer Convergence:Breakage-resistant polymer vials combined with barrier film technologies open parenteral packaging applications in field-deployed vaccination programs.
Industry Challenges
- Pharmacopeial Testing Bottlenecks:Hydrolytic resistance and particulate validation capacity shortages at regional laboratories extend batch release cycles.
- Formulation-Package Interaction Expertise:Delamination risk assessment and extractables-leachables profiling require specialized analytical chemistry talent scarce across GCC and North African markets.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Middle East and Africa Pharmaceutical Vials Market |
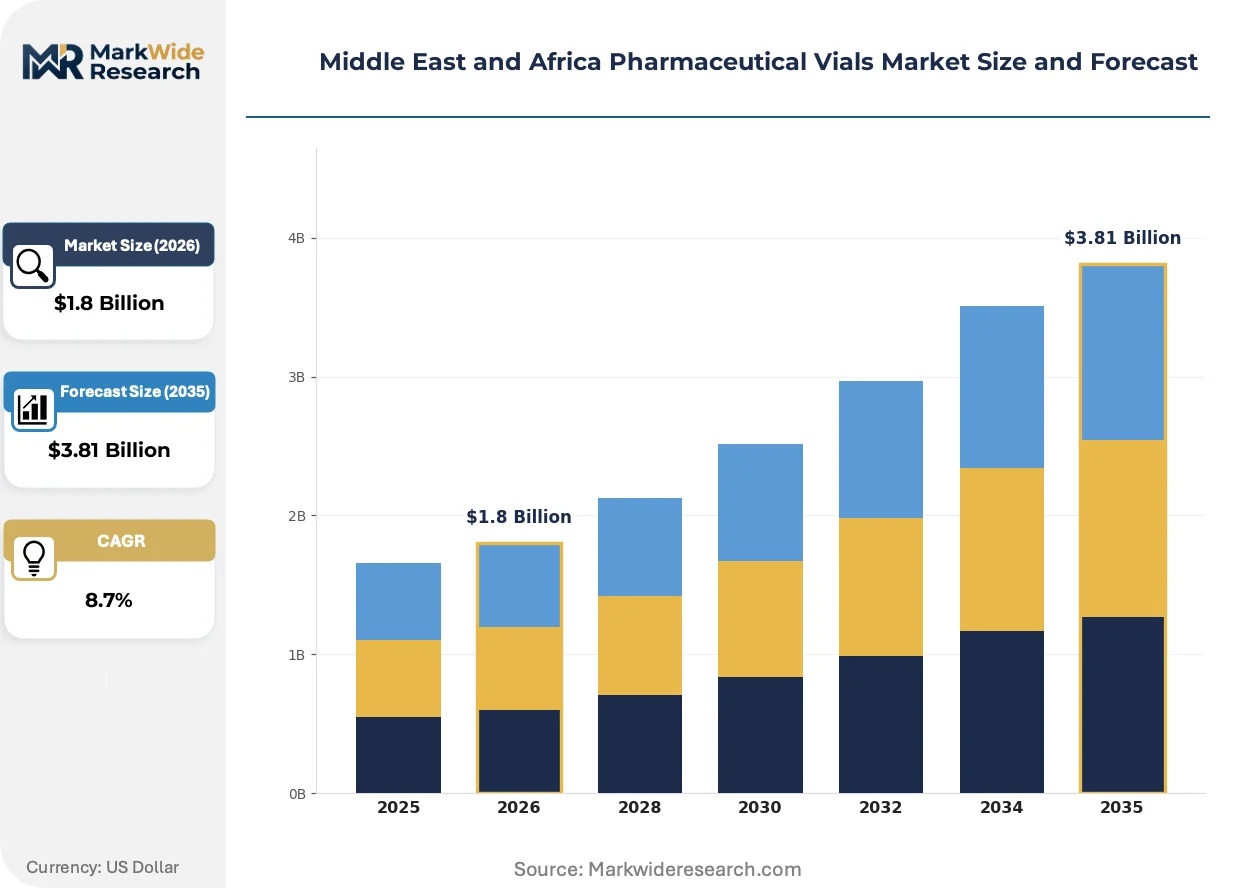
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.81 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Type: Glass, Plastic, Disposable, Reusable Product Type: Single-Dose, Multi-Dose, Pre-Filled, Auto-Injectors End User: Hospitals, Pharmacies, Research Laboratories, Biotech Companies Closure Type: Rubber Stoppers, Aluminum Caps, Flip-Off Seals, Luer Locks |
| Companies Covered | Schott AG, Gerresheimer AG, Stevanato Group S.P.A, DWK Life Sciences, Borosil Limited, RAK Ghani Glass LLC, Arab Pharmaceutical Glass Co., Bormioli Pharma, Vetter Pharma-Fertigung GmbH & Co. KG, Others |
| Regions Covered | Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Middle East and Africa Pharmaceutical Vials Market Shifts & Advancements
Container closure integrity verification and serialization technologies are transforming how pharmaceutical vials are specified, qualified, and tracked through distribution networks in the Middle East and Africa.
Machine vision inspection systems is digitizing defect detection in tubular glass conversion lines, replacing manual sampling protocols with 100% automated dimensional and cosmetic verification. Saudi vaccine fill-finish operations are adopting these systems fastest, driven by SFDA batch release documentation requirements. This compression of quality assurance cycles is narrowing acceptable supplier qualification windows and favoring converters with captive analytical capabilities.
SAHPRA tightened pharmacovigilance rules for parenteral packaging now require documented container closure integrity across temperature excursion scenarios. South African sterile injectables producers must validate seal performance from -40°C through +40°C storage conditions. Lyophilized biologics presentations face the most stringent testing protocols, with regulators demanding real-time data on stopper compression set and aluminum crimp torque retention.
Hospital procurement consortia across the UAE are consolidating vial purchasing through centralized tender platforms, displacing fragmented distributor networks with direct manufacturer agreements. Dubai Health Authority and Abu Dhabi Health Services Company now specify annual volume commitments with penalty clauses for supply interruptions. This concentration is visible most acutely in oncology and anesthesia therapeutic categories, where unit-of-use packaging specifications are being harmonized across emirate-level health systems.
Middle East and Africa Pharmaceutical Vials Market Segmentation
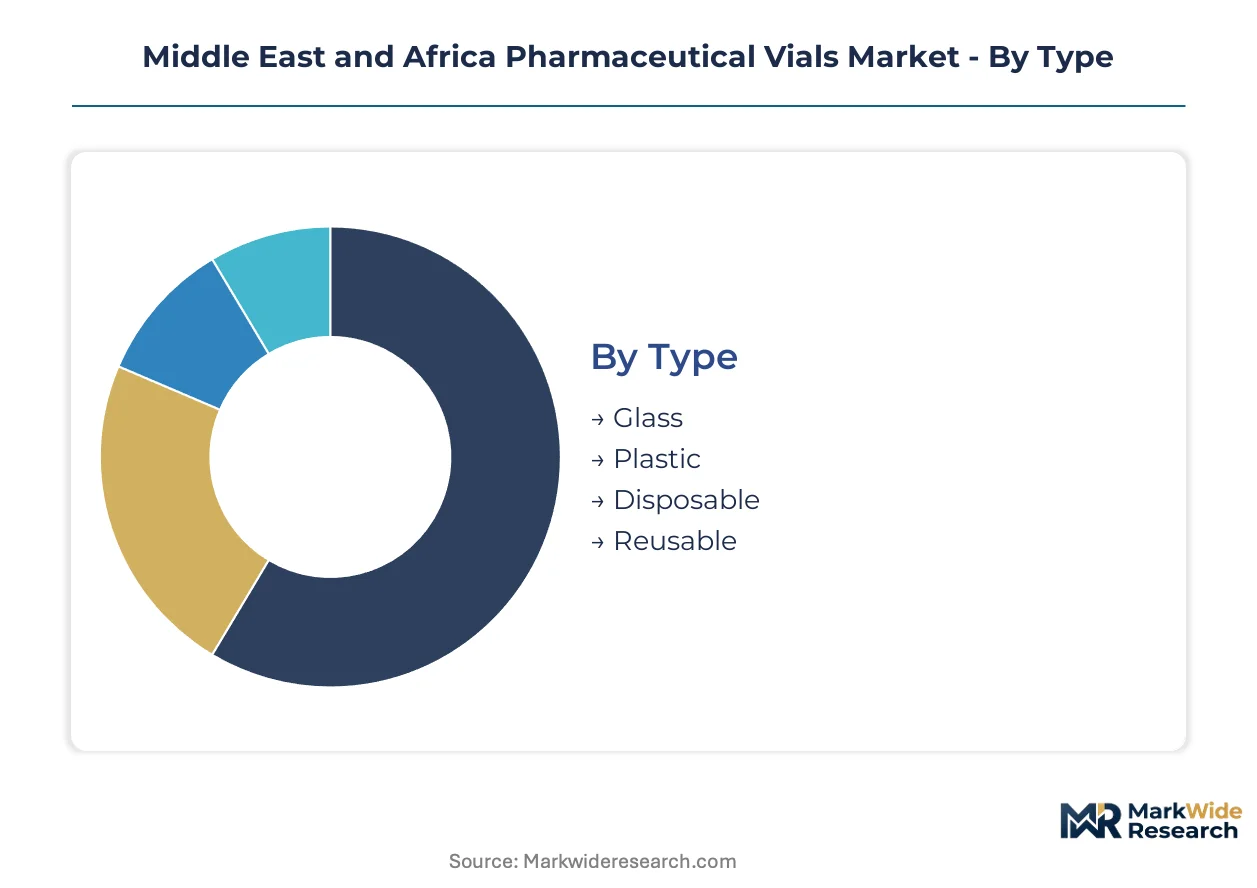
Pharmaceutical vial segmentation in the Middle East and Africa reflects divergent supply chain capabilities across glass melting, polymer conversion, and sterile fill-finish infrastructure. Each category maps directly to regulatory pathways enforced by SFDA, SAHPRA, and MOHAP, shaping procurement qualification requirements and capital deployment priorities for converters and drug manufacturers alike.
Type:
Glass dominates hospital procurement tenders across Saudi Arabia and the UAE, while polymer alternatives penetrate field vaccination programs where breakage resistance outweighs barrier performance requirements.
- Glass:Type I borosilicate tubing and molded formats supply lyophilized biologics and parenteral vaccines requiring hydrolytic resistance per USP <660>. Saudi vaccine fill-finish lines at King Abdullah Economic City specify Schott FIOLAX clear and amber tubing for thermal shock resilience across cold-chain distribution.
- Plastic:Cyclic olefin polymer and polypropylene vials serve temperature-stressed distribution networks in Sub-Saharan Africa where glass fracture rates compromise dose delivery. UAE-based humanitarian logistics operators specify polymer for last-mile vaccine campaigns.
- Disposable:Single-use polymer systems eliminate cleaning validation burdens for CMOs running multi-product fill-finish suites.
- Reusable:Glass vial return programs survive only in South African hospital consortia with centralized sterilization infrastructure.
Established volume favors Glass; emerging adoption favors Plastic.
Product Type:
Unit-of-use formats command premium positioning as preservative-free formulations displace multi-dose alternatives across GCC regulatory submissions.
- Single-Dose:Preservative-free presentations in borosilicate tubing vials with optimized heel geometry dominate Saudi oncology and biologics portfolios. SFDA pharmacovigilance rules now require documented container closure integrity for unit-of-use packaging across temperature excursion scenarios.
- Multi-Dose:Rubber-stoppered vials with antimicrobial preservatives retain share in anesthesia and emergency medicine where dose flexibility outweighs contamination risk. South African public sector tenders still specify multi-dose formats for cost-sensitive therapeutic categories.
- Pre-Filled:Syringe-format alternatives capture biologics administration share, compressing addressable vial volume in high-value monoclonal antibody categories.
- Auto-Injectors:Integrated drug-device combinations bypass traditional vial-stake supply chains entirely, reshaping competitive boundaries for sterile packaging converters.
Single-Dose formats expand most quickly in Saudi and Emirati biomanufacturing; Multi-Dose contracts anchor South African public procurement.
End User:
Hospital consolidation across Dubai and Abu Dhabi is concentrating purchasing power, while biotech greenfield investments in Saudi Arabia create demand for qualified vial supply at scale.
- Hospitals:Centralized tender platforms at Dubai Health Authority and Abu Dhabi Health Services Company specify annual volume commitments with penalty clauses for supply interruptions in oncology and anesthesia categories.
- Pharmacies:Retail distribution networks in Egypt and Morocco handle lower-volume parenteral products where serialization mandates are reshaping supplier qualification criteria.
- Research Laboratories:Clinical trial material supply requires small-batch borosilicate vials with documented extractables-leachables profiles.
- Biotech Companies:Saudi Arabia's Biotech Industrial City investments attract sterile injectables producers requiring immediate proximity to qualified glass converters.
Biotech Companies represent the steepest expansion trajectory; Hospitals retain the largest committed volumes.
Closure Type:
Seal performance validation requirements diverge sharply between lyophilized biologics needing compression set documentation and liquid formulations prioritizing ease of reconstitution.
- Rubber Stoppers:Bromobutyl and chlorobutyl formulations with documented silicone oil content supply freeze-dried and liquid parenteral presentations. SAHPRA now mandates real-time data on stopper compression set across -40°C through +40°C storage conditions.
- Aluminum Caps:Crimp torque retention validation determines seal integrity for Saudi vaccine exports requiring extended shelf-life stability.
- Flip-Off Seals:Color-coded aluminum-plastic combinations enable rapid product identification in high-throughput hospital pharmacy operations.
- Luer Locks:Threaded closure systems support syringe-compatible vial designs for emergency medicine and anesthesia applications.
Rubber Stoppers dominate lyophilized biologics specifications; Flip-Off Seals gain share in high-throughput hospital environments.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pricing power concentrates in Saudi Arabia and the UAE where localization mandates and biotech industrial investments command premium vial specifications, while Egyptian and South African markets operate under cost-sensitive procurement regimes with tighter margin structures.
Saudi Arabia
King Abdullah Economic City and Jeddah biotech zones drive specialized borosilicate demand for vaccine fill-finish lines. SFDA procurement rules now require documented domestic melting capacity for government tender eligibility. Schott AG supplies tubular glass technology to Saudi vaccine manufacturers under long-term supply agreements.
United Arab Emirates
Dubai Science Park and KIZAD free zone clusters enable just-in-time sterile injectables production with sub-48-hour vial lead times. MOHAP harmonization with GCC Central Drug Registration creates unified but stringent import barriers. RAK Ghani Glass LLC cuts sea-freight exposure for UAE-based producers through proximity conversion.
South Africa
SAHPRA tightened pharmacovigilance rules now mandate container closure integrity validation across -40°C to +40°C temperature excursions. Public sector tenders retain multi-dose format preference for cost-sensitive anesthesia and emergency medicine categories. Hospital consortia in Gauteng and Western Cape centralize purchasing through annual volume commitment contracts.
Egypt
Serialized vial label traceability mandates under Egypt's drug authority reshape supplier qualification criteria for coding equipment. Gerresheimer AG anchors North African distribution through secondary processing operations in Cairo. Retail pharmacy networks in Alexandria and Nile Delta handle lower-volume parenteral products facing new aggregation capital requirements.
Middle East and Africa Pharmaceutical Vials Market Competitive Landscape
Platform integrators command the system tier; component specialists sit upstream. The Middle East and Africa pharmaceutical vials market structures around three distinct competitive tiers: European glass converters with captive melting technology, regional proximity fabricators leveraging logistics arbitrage, and polymer specialists serving breakage-sensitive distribution networks. Consolidation pressure runs through qualification bottlenecks as SFDA and SAHPRA documentation requirements favor converters with integrated analytical capabilities. Dominant competitive moves include backward integration into borosilicate melting capacity and strategic partnerships with fill-finish operators for co-located supply.
Among European-based converters, Schott AG and Gerresheimer AG exemplify the technology-anchored tier, occupying positions built on tubular glass process leadership and regional distribution infrastructure respectively. RAK Ghani Glass LLC represents the proximity-specialist archetype, with UAE-based operations structured around shortened supply chains for Gulf Cooperation Council sterile injectables producers.
| Leading Market Players |
|---|
| Schott AG |
| Gerresheimer AG |
| Stevanato Group S.P.A |
| DWK Life Sciences |
| Borosil Limited |
| RAK Ghani Glass LLC |
| Arab Pharmaceutical Glass Co. |
| Bormioli Pharma |
| Vetter Pharma-Fertigung GmbH & Co. KG |
| Others |
Supply & Pricing Matrix
Red Sea maritime corridors linking European glass converters to Gulf Cooperation Council ports impose freight cost volatility that concentrates pricing power among regional borosilicate melters while forcing downstream buyers into long-term offtake contracts. This logistics tension rewards proximity fabricators with captive melting capacity, compressing margins for importers and creating three distinct price tiers across premium certified, standard pharmacopeial, and economy polymer alternatives.
Pricing Analysis
Configured-to-order pricing for lyophilization-compatible tubing vials with documented heel geometry commands substantial premiums over standard USP <660> catalog formats. Price differentiation rests on SFDA batch release documentation and validated container closure integrity testing, with Saudi vaccine fill-finish operations absorbing the highest premiums for thermal shock-resistant specifications. Cost compression in standard multi-dose formats is intensifying as Egyptian and South African public tenders consolidate volumes, while biotech companies in King Abdullah Economic City show least price sensitivity for single-dose preservative-free presentations.
Supply Chain Analysis
Contract manufacturing concentration for sterile fill-finish operations clusters in Saudi Arabia's Biotech Industrial City, the UAE's Dubai Science Park and KIZAD free zones, and South Africa's Gauteng hospital consortia. High-purity silica sand feeds from limited geographies outside the region, bromobutyl rubber stoppers draw from Southeast Asian polymer specialists, and aluminum crimp components source from European metalworks. Single-source vulnerability in pharmaceutical-grade glass tubing exposes converters to maritime chokepoint delays. Distribution runs through direct procurement channels between biomanufacturers and qualified converters, displacing fragmented distributor networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Fragmentation across regulatory compliance tiers creates entry niches as SFDA and SAHPRA documentation requirements diverge, splitting procurement qualification pathways and enabling specialized service providers to capture margin pools between standardized and custom validation protocols.
For Market Incumbents: Entrench market position through backward integration into borosilicate melting capacity within Saudi Arabia's localization zones, neutralizing freight cost volatility that threatens importers. Secure captive analytical capabilities for hydrolytic resistance and extractables-leachables profiling to compress batch release cycles, defending against polymer substitution in field vaccination programs. For New Entrants and Emerging Players: Polymer vial supply for Sub-Saharan African temperature-stressed distribution networks represents the most penetrable entry point, where breakage resistance outweighs barrier performance requirements and incumbent glass converters hold weak positioning. Egyptian serialization mandates for retail pharmacy networks create a secondary white-space for integrated coding and aggregation equipment partnerships. Go-to-market execution should anchor on humanitarian logistics operators with established last-mile vaccine campaign infrastructure. For Investors and Strategic Acquirers: Regional proximity fabricators with UAE-based conversion operations and sub-48-hour lead time capabilities to Gulf sterile injectables producers offer the strongest acquisition profile for medium-term holding periods. Long-term viability hinges on SFDA localization mandate enforcement depth and the pace of cyclic olefin polymer convergence in parenteral packaging. Watch SAHPRA container closure integrity rule harmonization with GCC Central Drug Registration as the inflection signal for consolidation timing.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Borosilicate Melting | SFDA procurement rules now require documented domestic melting capacity for government tender eligibility. |
| Serialization Equipment Partnership | Egypt's drug authority traceability mandates reshape supplier qualification criteria for coding and aggregation capital allocation. |
| Lyophilization-Compatible Format Development | Freeze-dried biologics penetration drives demand for tubing vials with optimized heel geometry and controlled wall thickness. |
| Polymer Vial Breakage Resistance Programs | Field-deployed vaccination programs in Sub-Saharan Africa prioritize dose delivery integrity over glass barrier performance. |
| Machine Vision Inspection Deployment | Saudi vaccine fill-finish operations adopt 100% automated dimensional verification to meet SFDA batch release documentation requirements. |
Research Methodology
Desk research of pharmacopeial standards documentation, customs trade records for pharmaceutical-grade silica and borosilicate glass, and SFDA regulatory filings preceded structured interviews with sterile injectables plant managers, regulatory affairs leads at glass converters, hospital procurement directors at Dubai Health Authority and Abu Dhabi Health Services Company, and pharmaceutical supply chain specialists across GCC and North African markets. Secondary validation drew from USP <660> hydrolytic resistance protocols, SAHPRA pharmacovigilance guidance documents, and GCC Central Drug Registration harmonization frameworks. Bottom-up volume estimates from fill-finish line capacity installations were triangulated against top-down pharmaceutical packaging spend allocations.
Assumptions around SFDA localization mandate enforcement timelines, SAHPRA container closure integrity rule adoption rates, and cyclic olefin polymer penetration in field vaccination programs were held fixed across baseline scenarios while temperature excursion validation stringency and polymer barrier film technology maturation were varied in sensitivity testing. Segmentation modeling incorporated material type, product format, end-user category, closure system, and regional regulatory cluster dimensions. CAGRs were derived from installed base growth in biotech industrial zones and tender volume commitments at centralized hospital procurement platforms. Forecast inputs included Saudi vaccine manufacturing localization targets and Egyptian serialization implementation schedules.
Practitioners should monitor SFDA domestic melting capacity verification protocols, SAHPRA temperature excursion documentation requirements, and polymer vial barrier performance certifications for early signals of forecast revision. Quarterly review of government tender program specifications, maritime freight rate indices for Red Sea corridors, and regional laboratory hydrolytic resistance validation capacity is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pharmaceutical Packaging
Global Pharmaceutical Processing Seals Market
Pharmaceutical Packaging
United States Ampoules Packaging Market
Pharmaceutical Packaging
Pharmaceutical Container Market
Pharmaceutical Packaging
North America Pharmaceutical Contract Packaging Market
Pharmaceutical Packaging
Vial Box Market
Pharmaceutical Packaging
Laboratory Consumables Primary Packaging Market
Pharmaceutical Packaging
North America Pharmaceutical Packaging Market
Pharmaceutical Packaging
Active and Intelligent Packaging in Pharmaceutical Market
Pharmaceutical Packaging
Saudi Arabia Pharmaceutical Packaging Market
Pharmaceutical Packaging
Latin America Pharmaceutical Plastic Packaging Market
Pharmaceutical Packaging
Vaccine Shippers Market
Pharmaceutical Packaging
North America Pharmaceutical Vials Market
Pharmaceutical Packaging
Middle East and Africa Pharmaceutical Packaging Market
Pharmaceutical Packaging
Pharmaceutical Vials Market
Pharmaceutical Packaging
Pharmaceutical Packaging Equipment Market
Pharmaceutical Packaging
Europe Pharmaceutical Packaging Market