
 Global Healthcare Revenue Cycle Management Market | 2026-2036
Global Healthcare Revenue Cycle Management Market Size, Share, and Industry Trends Forecast 2026-2036
Global Healthcare Revenue Cycle Management Market Foresight
Independent physician practices is collapsing as the dominant buyer archetype for standalone RCM software, while integrated delivery networks and hospital systems capture larger procurement volumes. Epic Systems Corporation anchors the hospital-centric segment through its deeply embedded EHR-RCM integration. R1 RCM sustains momentum via its scaled partnerships with large health systems. Optum leverages its payer-provider convergence model to control end-to-end revenue workflows.
Healthcare Revenue Cycle Management denotes the financial process that healthcare facilities use to track patient care episodes from registration and appointment scheduling through final payment, incorporating electronic data interchange standards such as HIPAA 837 claim formats and ANSI X12 transaction sets to ensure interoperability. The primary purpose is to optimize reimbursement velocity, reduce denials, and maintain regulatory compliance across complex payer environments. Cloud-Based deployment leads the solution architecture, with SaaS delivery models capturing the fastest expansion as health systems prioritize capital efficiency. Claims Management occupies the largest solution offering share, though Denial Management represents the highest-margin growth pocket as denial rates climb across commercial and government payers.
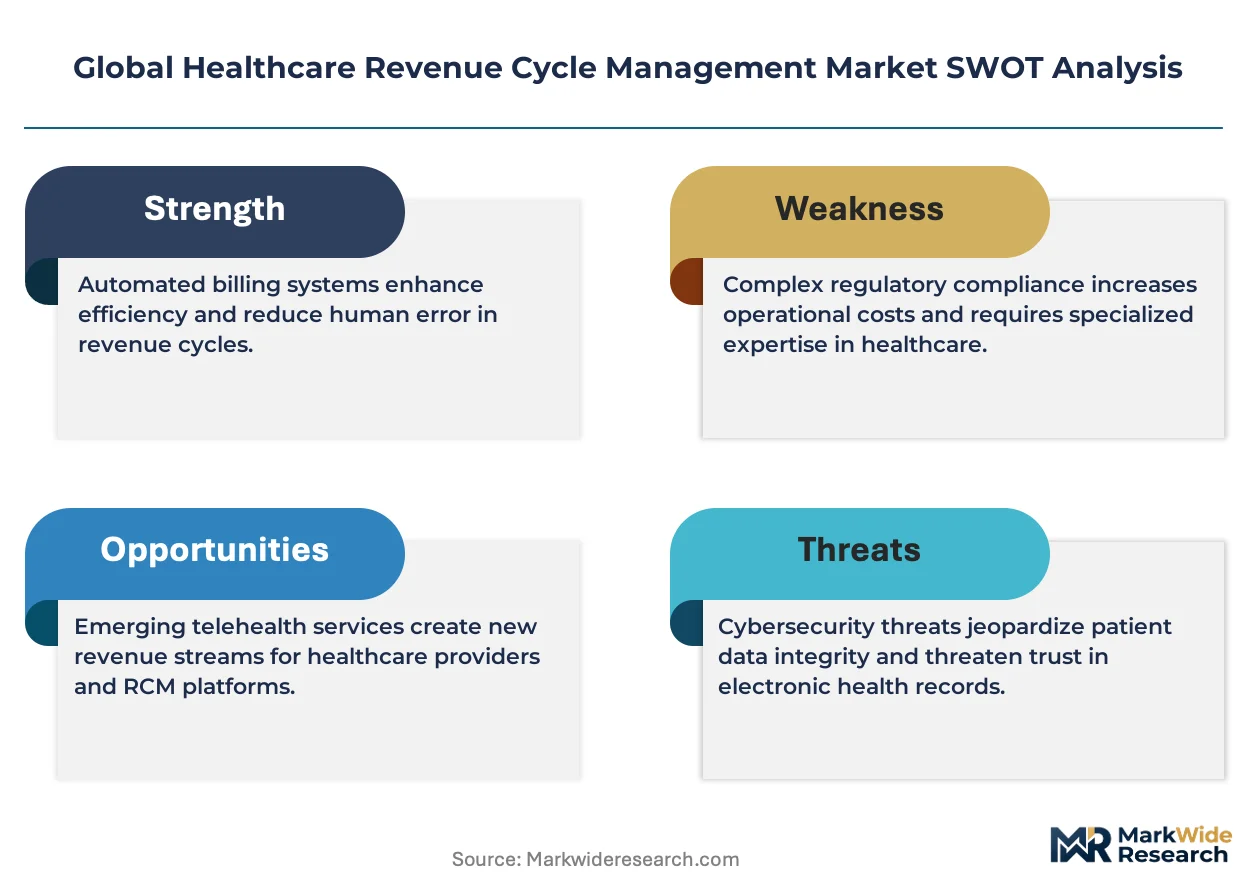
FDA oversight of clinical decision support tools embedded within RCM platforms, combined with CMS reimbursement rulemaking and HIPAA transaction standards, shapes product development roadmaps and market access requirements for vendors. The EU AI Act introduces compliance obligations for European health systems deploying automated prior authorization and claims adjudication algorithms. Stakeholders must monitor how interoperability mandates from ONC and evolving state-level surprise billing regulations alter data exchange architectures and vendor competitive positioning.
Market Dynamics
The transition from fee-for-service to value-based reimbursement under CMS rules is compressing RCM procurement cycles and forcing health systems to prioritize platforms that integrate clinical and financial workflows.
Growth Catalysts
- CMS Alternative Payment Models:Mandatory bundled payment programs for cardiac and orthopedic episodes drive hospital systems toward integrated RCM platforms that track quality metrics alongside reimbursement.
- Cloud SaaS architectures:Capital-constrained health systems in the United States accelerate migration from on-premise installations to subscription-based delivery, reducing IT infrastructure burdens.
- Denial rate inflation:Commercial and government payers tighten prior authorization requirements, expanding the addressable market for automated denial management modules.
Market Restraints
- Interoperability fragmentation:Inconsistent implementation of HL7 FHIR standards across EHR vendors creates data silos that impede seamless revenue cycle handoffs.
- Legacy system entrenchment:Epic Systems Corporation's dominant hospital footprint locks competitors out of enterprise accounts through deeply embedded clinical-financial integration.
- Workforce compression:Certified medical coders and revenue cycle analysts face acute shortages, inflating implementation costs for new platform deployments.
Strategic Opportunities
- India's hospital digitization:The country's PLI scheme for medical devices and expanding private hospital chains create first-mover openings for cloud-native RCM entrants.
- Prior authorization automation:Machine learning algorithms that predict payer-specific documentation requirements reduce manual rework and accelerate cash conversion.
- Surprise billing compliance:State-level transparency mandates in Texas, Florida, and New York require price estimation tools that integrate with patient access workflows.
Industry Challenges
- EHR-RCM integration complexity:Health systems running Cerner or MEDITECH alongside standalone RCM modules face protracted API configuration timelines that delay go-live dates.
- Cybersecurity certification burden:HITRUST and SOC 2 Type II audits demand 12-18 month compliance cycles that strain vendor engineering resources.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Healthcare Revenue Cycle Management Market |
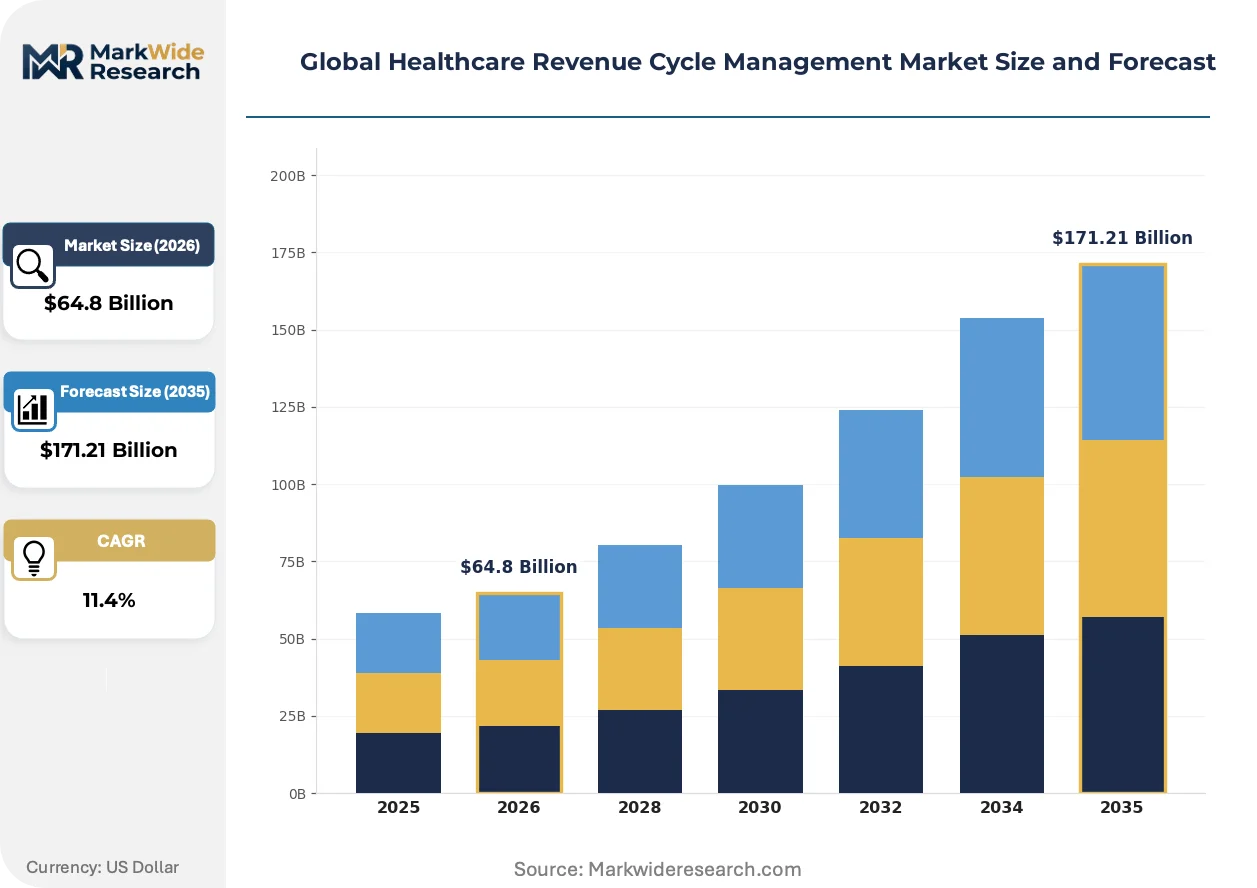
| Market Size in 2026 | $64.8 Billion |
| Market Size in 2035 | $171.21 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Solution Offering: Claims Management, Patient Scheduling, Payment Posting, Eligibility Verification, Denial Management, Reporting & Analytics Deployment Mode: Cloud-Based, On-Premises, Hybrid, SaaS, Hosted, Managed Services End User: Hospitals, Ambulatory Surgical Centers, Imaging Centers, Physician Practices, Diagnostic Laboratories, Long-Term Care Facilities Application: Billing & Invoicing, Patient Registration, Revenue Integrity, Payment Processing, Coding & Documentation, Insurance Verification |
| Companies Covered | Optum, R1 RCM, Epic Systems Corporation, Conifer Health Solutions, GeBBS Healthcare Solutions, Access Healthcare, Ensemble Health Partners, Omega Healthcare, AGS Health, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Healthcare Revenue Cycle Management Market Shifts & Advancements
Artificial intelligence is penetrating claims scrubbing and prior authorization workflows, compressing the traditional RCM vendor competitive set and elevating platform differentiation around predictive accuracy.
Machine learning algorithms trained on historical denial patterns are displacing rules-based claim scrubbing engines in large health system deployments. Hospital revenue cycle directors at systems exceeding 500 beds now mandate AI-enabled denial prediction as a procurement requirement. This capability is displacing incumbent clearinghouse relationships as health systems bring adjudication intelligence in-house.
The EU AI Act's risk classification framework for healthcare algorithms imposes conformity assessment obligations on automated prior authorization tools deployed in European health systems. Vendors must document training data provenance and algorithmic explainability to achieve CE marking for high-risk applications. German and French hospital procurement committees now require AI Act compliance documentation alongside traditional GDPR assessments.
Consolidation among United States health systems is concentrating purchasing power into fewer integrated delivery networks with enterprise-scale RCM requirements. Independent physician practices that once drove standalone software sales are dissolving into hospital employment models or selling to private equity platforms. This buyer concentration is most visible in Texas and Florida, where hospital system mergers have reduced the number of independent RCM decision-makers by half over the past five years.
Global Healthcare Revenue Cycle Management Market Segmentation
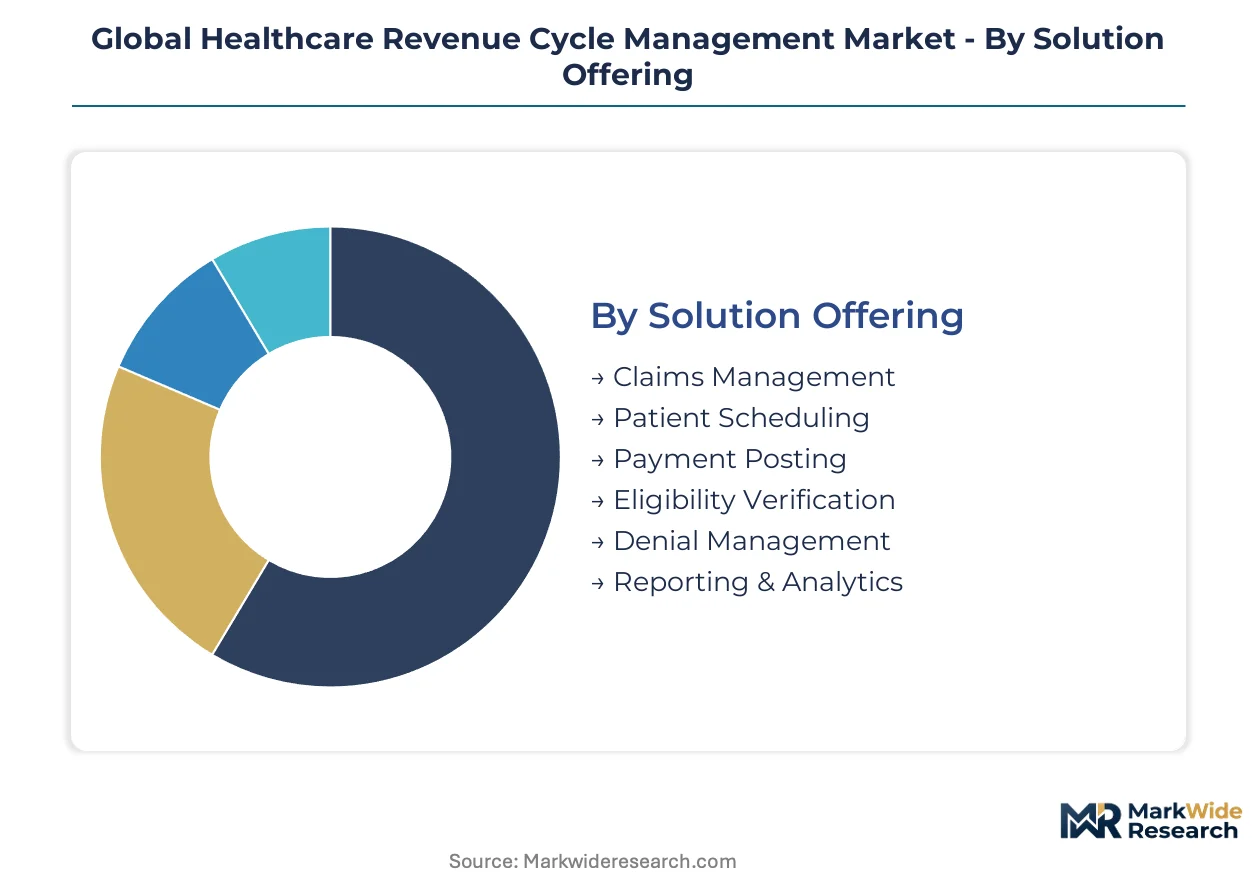
Segmentation in healthcare RCM reveals how procurement authority concentrates among large health systems while deployment preferences shift toward capital-efficient models. Understanding these divides exposes where vendors face displacement risk from adjacent software categories and where integration moats protect incumbents.
Solution Offering:
Substitution pressure runs highest in commoditized workflow modules where standalone vendors compete against EHR-native alternatives.
- Claims Management:Core transaction processing layer handling HIPAA 837 claim generation, scrubbing, and electronic submission to commercial and government payers. Demand concentrates in United States hospital systems consolidating clearinghouse relationships into single-vendor contracts. CMS mandate for electronic claims submission under HIPAA Transaction Rule locks in baseline demand.
- Denial Management:Predictive analytics engines that flag documentation gaps before payer submission and automate appeal workflows. United States revenue cycle directors at systems exceeding 500 beds now mandate AI-enabled denial prediction as procurement requirement. Commercial payer prior authorization tightening expands addressable market.
- Patient Scheduling:Appointment orchestration tools integrated with registration and insurance verification workflows.
- Payment Posting:Automated reconciliation of remittance advice against patient accounts and general ledger entries.
- Eligibility Verification:Real-time payer connectivity confirming coverage status and benefit limits at point of service.
- Reporting & Analytics:Dashboards tracking days in accounts receivable, denial rates, and payer mix performance.
Claims Management retains volume leadership; Denial Management holds the steepest expansion curve.
Deployment Mode:
Cost tier stratification separates capital-constrained buyers seeking operational expenditure models from security-sensitive organizations retaining on-site control.
- Cloud-Based:Multi-tenant architectures delivering RCM functionality via internet connectivity without client-side infrastructure. United States community hospitals and rural health systems accelerate migration to reduce IT staffing burdens. Epic Systems Corporation and Oracle Health extend cloud-native RCM modules to capture this shift.
- SaaS:Subscription-licensed software with automatic updates and usage-based pricing tiers. Large United States integrated delivery networks favor SaaS for enterprise standardization across acquired facilities. Capital efficiency mandates from hospital boards drive procurement preference.
- On-Premises:Client-managed installations within health system data centers.
- Hybrid:Split architectures keeping sensitive patient data on-site while leveraging cloud for analytics.
- Hosted:Single-tenant cloud deployments with dedicated infrastructure managed by vendor.
- Managed Services:Outsourced revenue cycle operations including staffing and technology.
Cloud-Based deployments capture the majority of new contract value; SaaS licensing expands most quickly among multi-facility networks.
End User:
Customer type concentration reflects structural consolidation of United States healthcare delivery, with independent practice collapse redirecting purchasing authority toward employed-physician networks.
- Hospitals:Acute care facilities and integrated delivery networks with enterprise-scale RCM requirements. United States health system mergers in Texas and Florida concentrate procurement into fewer decision-makers with expanded contract values. Epic-embedded RCM dominates this segment through clinical-financial integration.
- Physician Practices:Outpatient clinics and specialty groups managing independent revenue cycles. United States independent practices face dissolution into hospital employment or private equity platforms. Standalone RCM software demand collapses as these entities lose procurement autonomy.
- Ambulatory Surgical Centers:Freestanding outpatient surgery facilities with focused billing workflows.
- Imaging Centers:Diagnostic radiology and imaging service providers.
- Diagnostic Laboratories:Clinical and anatomic pathology testing facilities.
- Long-Term Care Facilities:Skilled nursing and post-acute care providers with distinct payer mixes.
Hospitals dominate absolute spending; Ambulatory Surgical Centers gain share fastest as outpatient migration accelerates.
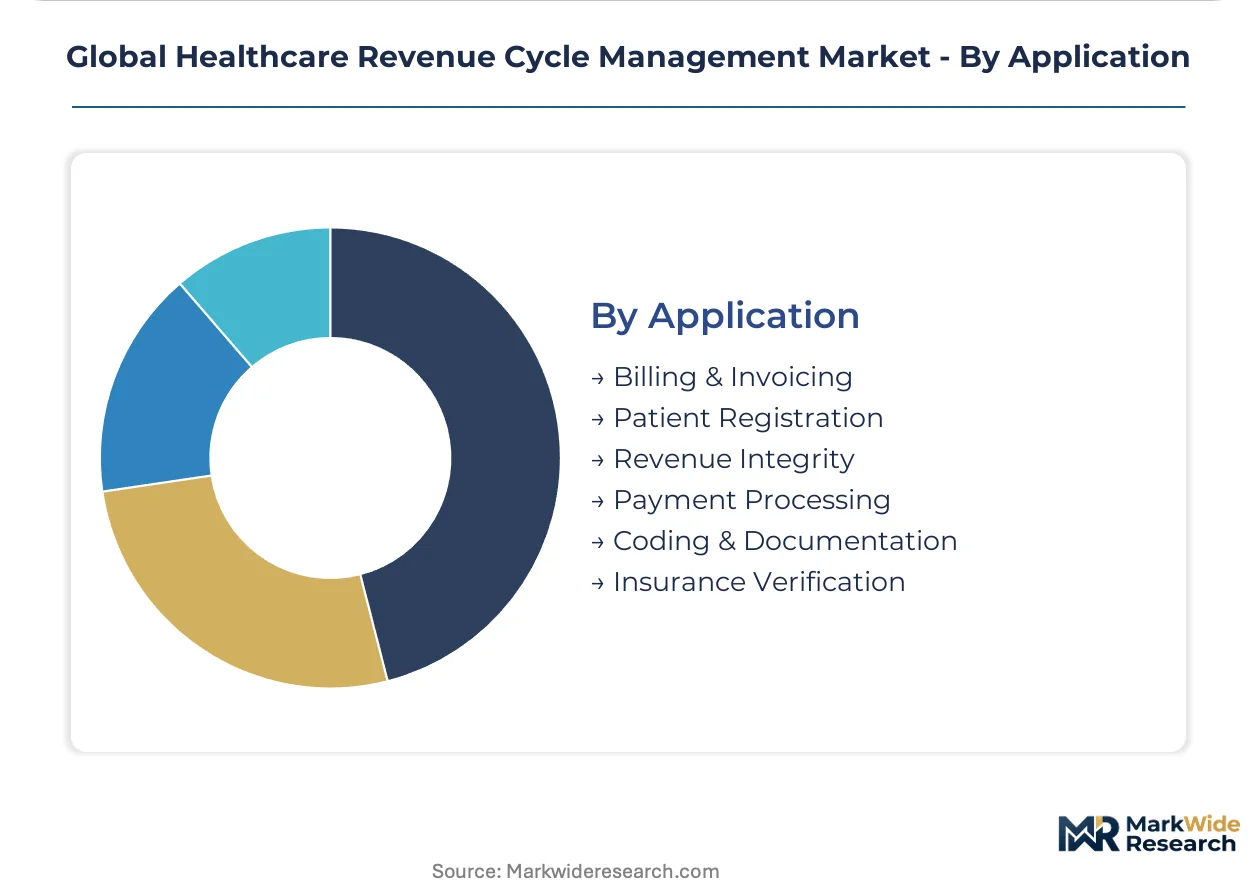
Application:
Maturity differentiation separates established billing functions from emerging revenue integrity disciplines addressing value-based reimbursement complexity.
- Billing & Invoicing:Patient statement generation, payment plan administration, and collections workflow management. United States hospital business offices centralize billing operations to reduce cost-to-collect metrics. Patient financial responsibility expansion drives self-pay module investment.
- Revenue Integrity:Clinical documentation improvement, charge capture validation, and compliance auditing. United States academic medical centers staff revenue integrity departments to defend reimbursement under CMS quality programs. Clinical-financial workflow convergence elevates this function.
- Patient Registration:Demographic capture, insurance intake, and consent management.
- Payment Processing:Credit card, ACH, and digital wallet transaction handling.
- Coding & Documentation:ICD-10-CM/PCS assignment and clinical documentation integrity.
- Insurance Verification:Eligibility confirmation and prior authorization initiation.
Billing & Invoicing anchors current deployment value; Revenue Integrity climbs the fastest as value-based models mature.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
United States-based RCM vendors export cloud-native platforms to English-speaking hospital systems in Canada and Australia, while Indian service providers supply back-office revenue cycle operations to American health networks seeking labor arbitrage.
United States
Hospital consolidation in Texas and Florida concentrates procurement authority into fewer integrated delivery networks with enterprise-scale contracts. CMS Alternative Payment Models for cardiac and orthopedic episodes mandate quality metric tracking alongside reimbursement. The Dallas-Fort Worth metroplex anchors a cluster of revenue cycle outsourcing firms serving national health systems.
Germany
University hospitals in Baden-Württemberg and Bavaria deploy automated prior authorization tools to manage statutory health insurance complexity. The EU AI Act imposes conformity assessment obligations on algorithmic claims adjudication systems. Berlin hosts a concentration of health IT consultancies bridging EHR-RCM integration gaps.
India
Private hospital chains in Maharashtra and Karnataka accelerate digitization under the PLI scheme for medical devices. CDSCO oversight of clinical decision support tools shapes product localization requirements. Hyderabad's HealthTech corridor attracts cloud-native RCM entrants targeting domestic and export markets.
United Kingdom
NHS Trusts in London and the Midlands pilot integrated revenue integrity platforms to defend reimbursement under payment-by-results frameworks. NHS England's interoperability mandates alter data exchange architectures for vendor market access. The Cambridge-Oxford-London golden triangle concentrates health analytics startups.
Australia
State hospital networks in New South Wales and Victoria migrate from on-premise installations to subscription-based RCM delivery. The Therapeutic Goods Administration regulates clinical decision support modules embedded within revenue platforms. Sydney's digital health cluster hosts Asia-Pacific headquarters for multinational RCM vendors.
Global Healthcare Revenue Cycle Management Market Competitive Landscape
Player mix skews toward health system partnerships and payer-provider convergence models rather than standalone software licensing. Three archetypes dominate: EHR-embedded platforms, outsourced revenue cycle operators, and payer-affiliated end-to-end workflow managers. Consolidation concentrates through health system mergers reducing independent decision-makers, while cloud-native entrants target mid-market displacement. Strategic partnerships and M&A activity represent the primary competitive moves as vendors seek scale and clinical-financial integration depth.
Within the EHR-embedded tier, Epic Systems Corporation anchors hospital-centric deployments through deeply embedded clinical-financial integration. Optum occupies a position exemplifying payer-provider convergence control over end-to-end revenue workflows. R1 RCM sits within the scaled partnership archetype, representing outsourced revenue cycle management for large health systems.
| Leading Market Players |
|---|
| Optum |
| R1 RCM |
| Epic Systems Corporation |
| Conifer Health Solutions |
| GeBBS Healthcare Solutions |
| Access Healthcare |
| Ensemble Health Partners |
| Omega Healthcare |
| AGS Health |
| Others |
Supply & Pricing Matrix
Enterprise-scale health system deployments in the United States generate procurement volumes that compress per-seat licensing costs for cloud-native RCM platforms while elevating price floors for specialized denial management modules. Scale economies among integrated delivery networks with 500-plus beds reshape vendor pricing power across both subscription tiers and transactional fee structures.
Pricing Analysis
Next-generation AI-enabled denial prediction commands premium positioning against rules-based claim scrubbing engines and legacy clearinghouse relationships. Three-tier pricing structure across premium, standard, and economy levels separates AI-native platforms with predictive accuracy guarantees from workflow automation tools and basic claims processing modules. Pricing pressure stems from Epic Systems Corporation's embedded RCM bundling with EHR contracts, which forces standalone vendors toward aggressive discounting. Community hospitals and rural health systems exhibit highest price sensitivity, while academic medical centers prioritize clinical-financial integration over cost minimization.
Supply Chain Analysis
Just-in-time deployment preferences dominate as health systems prioritize SaaS delivery over capital-intensive on-premise infrastructure builds. Engineering talent concentrates in the United States, India, and Germany, with Hyderabad's HealthTech corridor and Berlin's health IT cluster feeding cloud-native development pipelines. Raw material dependencies center on GPU compute capacity for machine learning training, HL7 FHIR interoperability middleware, and HITRUST-certified data center infrastructure. Single-source vulnerability runs through NVIDIA's dominance in AI training hardware. Distribution runs through direct enterprise sales teams targeting hospital procurement committees and GPO contract vehicles.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Healthcare RCM sits in early-cycle expansion as value-based reimbursement mandates from CMS force clinical-financial workflow convergence that legacy platforms cannot address.
For Market Incumbents: Secure EHR-RCM integration depth through API standardization investments that lock out standalone competitors from enterprise accounts. Defend against cloud-native entrants by accelerating HITRUST and SOC 2 Type II certification cycles that strain mid-cap engineering resources. Prioritize denial management module stickiness through AI training data moats built on historical payer-specific patterns. For New Entrants and Emerging Players: CDSCO fast-track pathways for clinical decision support modules in India open first-mover positioning before domestic hospital chains consolidate vendor relationships. Target Maharashtra and Karnataka private hospital networks with cloud-native deployments that bypass legacy on-premise entrenchment. Lead with prior authorization automation as the wedge capability that demonstrates immediate cash-conversion impact to CFO audiences. For Investors and Strategic Acquirers: AI-native denial prediction specialists with proven health system deployments represent the highest-conviction acquisition archetype for platform consolidation plays. Long-term viability hinges on regulatory compliance breadth spanning FDA oversight, EU AI Act conformity assessments, and HIPAA transaction rule adherence. Watch for CMS bundled payment program expansion into oncology and maternity episodes as the inflection signal that accelerates integrated RCM procurement cycles.| Strategic Initiative | Industry Significance |
|---|---|
| Platform Integration | Epic-embedded RCM consolidation locks competitors out of 500-plus bed hospital systems. |
| AI Certification Pathway | EU AI Act conformity assessments enable CE marking for automated prior authorization tools in German university hospitals. |
| Hospital System Partnership | Scaled IDN contracts in Texas and Florida concentrate procurement authority into fewer decision-makers. |
| Geographic Expansion | India's PLI scheme for medical devices attracts cloud-native entrants targeting Maharashtra digitization. |
| Strategic Partnership | Payer-provider convergence models mirror Optum's end-to-end revenue workflow control architecture. |
Research Methodology
Two parallel data streams informed the analysis: structured primary interviews with revenue cycle directors, hospital CFOs, health system procurement officers, and GPO contracts managers; and secondary validation against CMS Medicare cost reports, hospital procurement databases, HIPAA transaction rule filings, and SEC 10-K disclosures from publicly traded RCM vendors. Bottom-up facility-level deployment estimates triangulated against top-down health system IT budget allocations.
Across the projection horizon, the analytical framework modeled segmentation dimensions spanning deployment architecture, solution module maturity, end-user scale tier, and regional regulatory cluster. CAGRs derived from facility adoption curves weighted by bed count and payer mix complexity. Forecast inputs incorporated denial rate inflation trajectories and CMS Alternative Payment Model expansion timelines.
Underlying assumptions cover interoperability standard implementation pace and health system consolidation velocity, with deviation risk concentrated in HL7 FHIR adoption delays and workforce compression for certified medical coders. Revision becomes warranted when AI Act enforcement thresholds or state-level surprise billing mandates cross implementation thresholds that alter vendor competitive positioning.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Healthcare IT
Patient Registry Software Market
Healthcare IT
Integrated Operating Room Management Systems Market
Healthcare IT
Hospital Capacity Management Solutions Market
Healthcare IT
Global Back-End Revenue Cycle Management Market
Healthcare IT
Healthcare Business Collaboration Tools Market
Healthcare IT
Americas Healthcare Human Resources (HR) Software Market
Healthcare IT
Healthcare Claims Management Software Market
Healthcare IT
Veterinary Practice Management Software Market
Healthcare IT
Chiropractic Software Market
Healthcare IT
Global Patient Intake Software Market
Healthcare IT
IT-Enabled Healthcare Market
Healthcare IT
Anatomic Pathology Track and Trace Solutions Market
Healthcare IT
Medical Specimen Tracking System Market
Healthcare IT
Digital Mhealth Solution Market
Healthcare IT
Neurosurgery Software Market
Healthcare IT
Revenue Cycle Management (RCM) Market