
 Hospital Workforce Management Software Market | 2026-2036
Hospital Workforce Management Software Market Size, Share, and Industry Trends Forecast 2026-2036
Hospital Workforce Management Software Market Analysis
North American health system IT budgets are rebalancing toward workforce optimization after years of dominant EHR spending. Oracle Corporation leverages its Cerner integration pipeline to anchor cloud-based scheduling within existing hospital data architectures. UKG Inc. competes through specialized nurse float pool management, while SAP SE extends its position via payroll compliance modules that address multi-state labor regulations.
Hospital workforce management software encompasses integrated platforms that automate staff scheduling, time and attendance tracking, credential verification, and labor cost analytics across clinical and non-clinical personnel. These systems typically interface with EHR and HRIS databases through HL7 FHIR APIs to ensure real-time staffing alignment with patient census data. Scheduling software leads product type revenue by addressing the largest operational pain point in acute care settings, while cloud-based deployment is expanding fastest as hospitals retire legacy on-premises systems. Talent acquisition modules command premium pricing due to specialized clinical credential parsing and automated background check orchestration.
FDA oversight of clinical decision support intersects with workforce platforms when scheduling algorithms incorporate patient acuity scoring, while HIPAA mandates govern workforce data interoperability. OSHA workplace safety reporting requirements and state nurse staffing ratio laws in California and Massachusetts directly shape feature roadmaps for compliance dashboards. Stakeholders must monitor whether emerging AI scheduling tools trigger additional FDA software-as-medical-device classification before committing to platform architectures.
Market Dynamics
Large health systems in the United States are consolidating vendor relationships around cloud-native scheduling platforms that interoperate with existing Cerner and Epic deployments, compressing procurement cycles and raising switching costs for incumbent providers.
Growth Catalysts
- California nurse-to-patient ratio mandates:State staffing laws require real-time compliance documentation, forcing hospitals to automate scheduling audits and credential verification workflows.
- HL7 FHIR API standardization:Interoperability protocols enable workforce platforms to pull live patient census data, aligning staffing levels with acuity scores without manual reconciliation.
- German hospital federation consolidation:Regional network standardization across Bavaria and North Rhine-Westphalia is creating pooled procurement demand for unified workforce analytics.
Market Restraints
- Legacy system integration costs:On-premises Kronos and API Healthcare installations require expensive middleware development to connect with modern cloud scheduling layers.
- Clinical credential verification bottlenecks:Multi-state nursing license reciprocity gaps create compliance delays that software alone cannot resolve without manual oversight.
- IT talent scarcity in acute care:Hospital IT departments lack sufficient HL7 integration specialists to deploy workforce platforms at vendor-projected timelines.
Strategic Opportunities
- AI-driven predictive scheduling:Machine learning models analyzing historical admission patterns can reduce premium labor spend on float pool nurses.
- OSHA workplace safety reporting automation:Integrated incident tracking modules address rising regulatory pressure for nurse injury documentation.
- Perioperative services specialization:Surgical scheduling optimization remains underserved relative to medical-surgical units, offering white space for modular solutions.
Industry Challenges
- HIPAA Security Rule compliance complexity:Workforce data containing nurse performance metrics and disciplinary records requires enhanced encryption and access controls beyond standard HRIS configurations.
- Multi-state payroll tax calculation accuracy:Travel nurses working across jurisdictions create withholding errors that expose hospitals to state revenue department penalties.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Hospital Workforce Management Software Market |
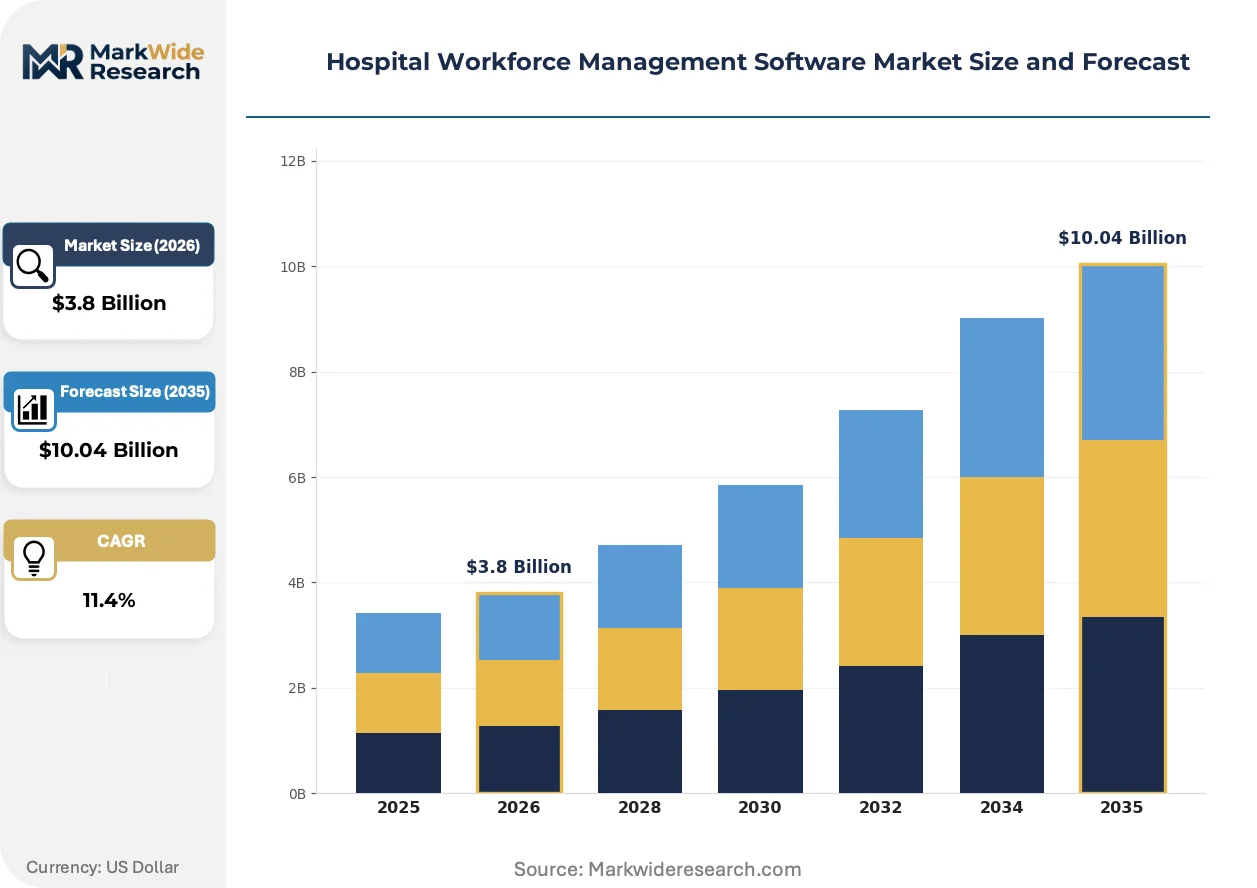
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $10.04 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Scheduling Software, Payroll Management, Talent Acquisition, Staff Training End User: Hospitals, Clinics, Long-Term Care Facilities, Emergency Services Deployment: Cloud-Based, On-Premises, Hybrid, Mobile Service Type: Consulting, Implementation, Support, Maintenance |
| Companies Covered | UKG Inc., Oracle Corporation, Workday Inc., ADP Inc., SAP SE, ATOSS Software AG, Infor, McKesson Corporation, Cornerstone Ondemand Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Hospital Workforce Management Software Market Emerging Trajectories
Workforce management platforms are converging with clinical systems through API-first architectures, eroding the traditional boundary between HR technology and patient care infrastructure.
Real-time location systems using Bluetooth Low Energy badges are unifying nurse tracking with automated census-based staffing adjustments. Academic medical centers in Massachusetts and Pennsylvania are deploying these sensors at scale. The technology is unifying physical workflow data with scheduling algorithms, compressing the gap between planned and actual staffing ratios.
The FDA's evolving software-as-medical-device guidance is reshaping how vendors develop scheduling tools that incorporate patient acuity scoring. Algorithms influencing clinical staffing decisions now face potential premarket review requirements. Scheduling platforms with embedded acuity modules are most affected, with vendors in California and Texas restructuring development roadmaps to segregate decision-support features.
Subscription-based pricing for talent acquisition modules is displacing perpetual license models in community hospital segments. Smaller facilities in Ohio and Florida prefer monthly fees tied to hire volume rather than upfront capital expenditure. This shift is most visible among critical access hospitals with constrained IT budgets and high nurse turnover rates.
Hospital Workforce Management Software Market Segmentation
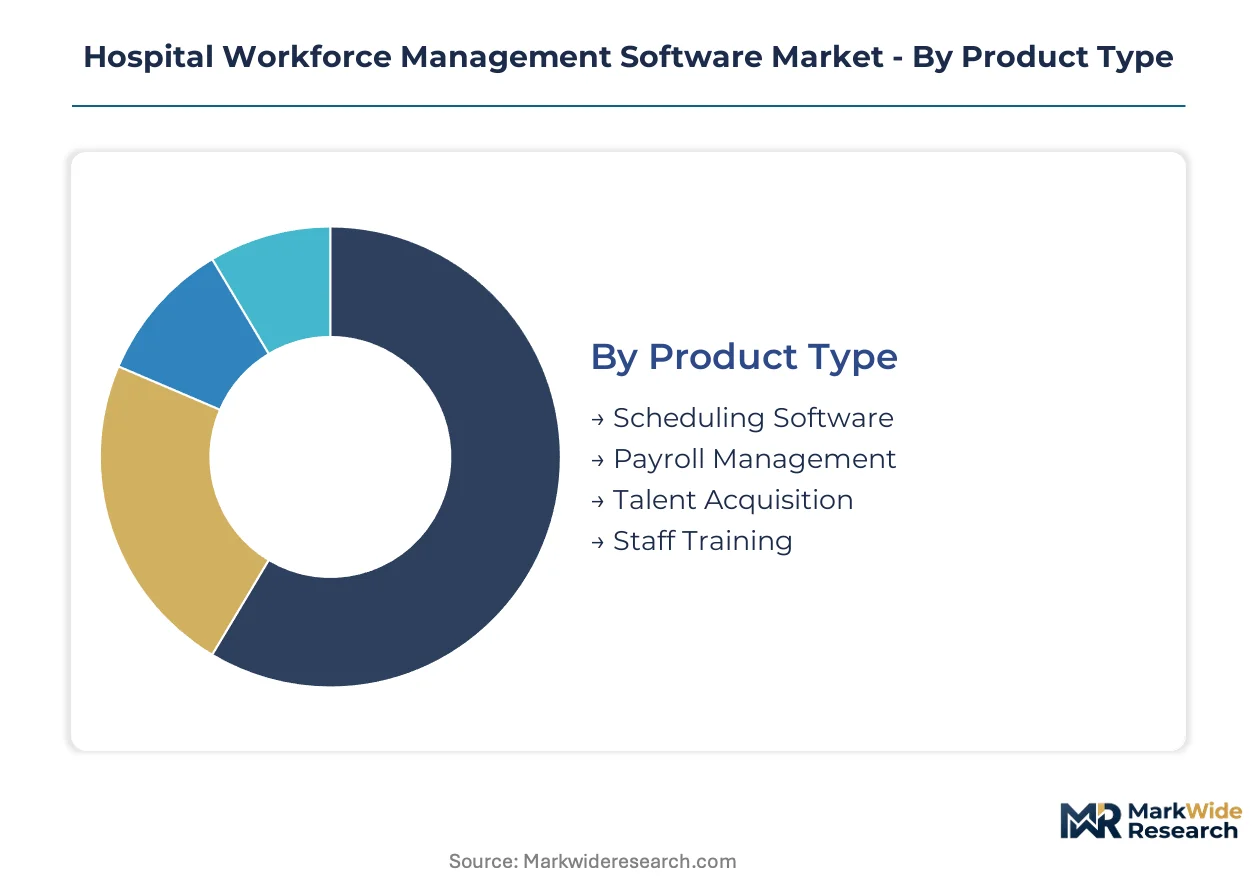
Hospital workforce management software segments reflect distinct technology maturity curves and procurement priorities across acute care settings. Understanding these divisions clarifies where vendors concentrate R&D investment versus where system integrators capture service revenue.
Product Type:
Technical sophistication varies sharply across functional modules, with algorithmic complexity driving price premiums and implementation timelines.
- Scheduling Software:Automated shift optimization engines process nurse availability, credential status, and patient census through constraint-based algorithms. Large health systems in the United States deploy these platforms to maintain compliance with California and Massachusetts nurse ratio mandates while reducing premium labor spend.
- Payroll Management:Multi-jurisdictional tax engines calculate withholdings for travel nurses working across state lines, addressing compliance exposure that manual processes cannot scale. Demand concentrates in Texas and Florida where seasonal staffing fluctuations create complex payment scenarios.
- Talent Acquisition:Clinical credential parsing automates license verification against state nursing board databases.
- Staff Training:Competency tracking modules align continuing education with regulatory renewal cycles.
Scheduling software leads on scale; talent acquisition leads on momentum.
End User:
Facility type dictates feature requirements, with acuity levels and regulatory exposure shaping procurement specifications.
- Hospitals:Enterprise platforms integrate with Cerner and Epic EHR deployments through HL7 FHIR APIs, enabling real-time staffing adjustments against live patient census. Academic medical centers in Pennsylvania and Massachusetts drive demand for predictive analytics modules.
- Clinics:Lightweight cloud solutions prioritize rapid deployment over deep EHR integration, serving ambulatory networks with limited IT staff.
- Long-Term Care Facilities:Shift bidding tools address high turnover among certified nursing assistants.
- Emergency Services:Mobile-first scheduling supports paramedic rotation management across dispersed coverage zones.
Hospitals dominate current procurement volume; long-term care facilities are expanding most quickly.
Deployment:
Infrastructure choices reflect IT modernization cycles and cybersecurity posture assessments across health system portfolios.
- Cloud-Based:SaaS architectures eliminate capital expenditure for server infrastructure while enabling automatic security patch deployment. German hospital federations in Bavaria and North Rhine-Westphalia are standardizing on cloud-native platforms to enable regional workforce analytics pooling.
- On-Premises:Legacy Kronos and API Healthcare installations persist where data residency requirements or air-gapped security protocols prevail.
- Hybrid:Split architectures keep sensitive payroll data local while pushing scheduling optimization to cloud compute.
- Mobile:Native applications enable shift swapping and time clocking without workstation dependency.
Cloud-based deployment captures the largest share of new contracts; mobile deployment shows the steepest expansion trajectory.
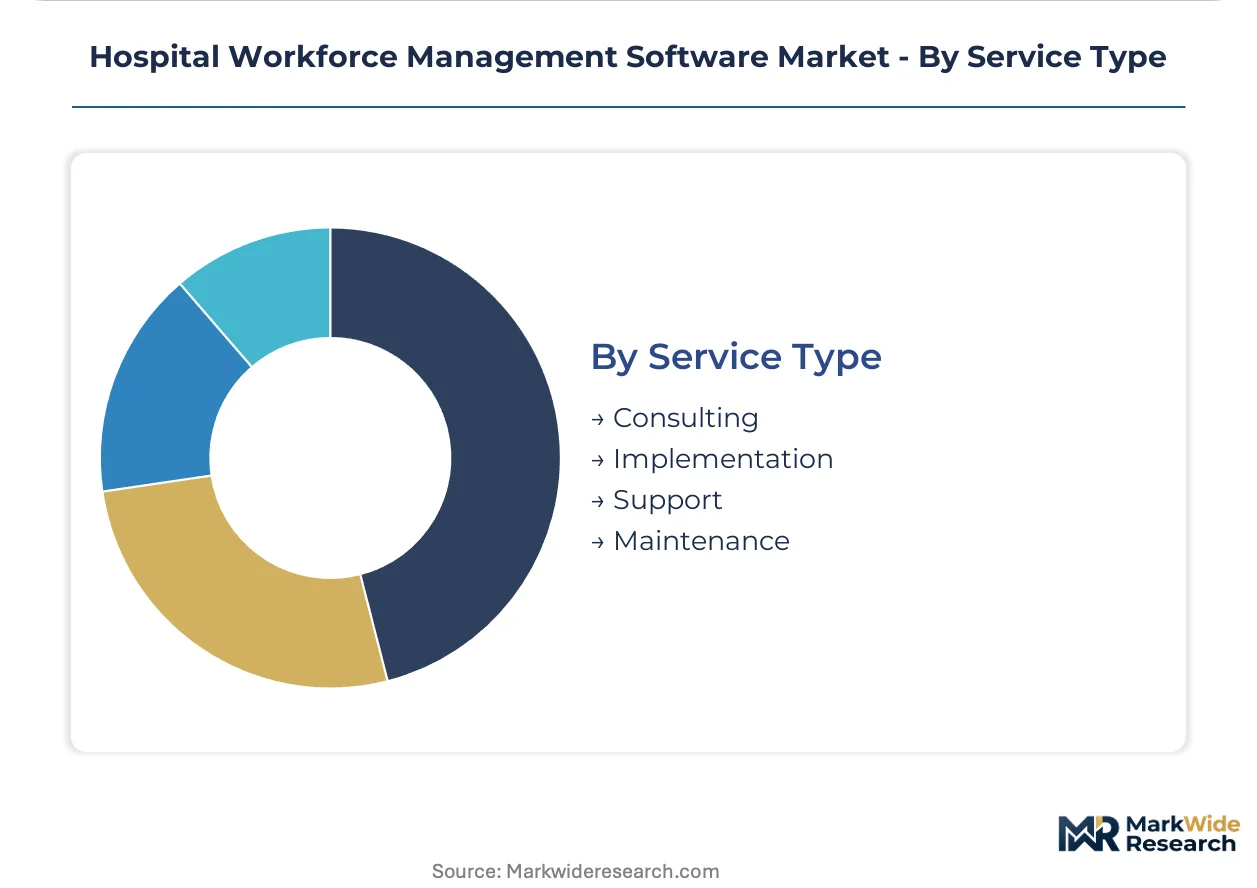
Service Type:
Professional services revenue scales with platform complexity and health system IT resource constraints.
- Consulting:Workforce optimization assessments identify staffing model inefficiencies before technology deployment. Engagement volume correlates with health system consolidation activity.
- Implementation:HL7 integration specialists configure EHR connectivity and validate data flows against HIPAA Security Rule requirements.
- Support:Tiered help desk operations address end-user training gaps and system troubleshooting.
- Maintenance:Subscription renewals cover regulatory update patches and feature version migrations.
Implementation services generate the highest per-contract value; support contracts provide the most predictable recurring revenue.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany's hospital federation consolidation contrasts with the United States' state-level regulatory fragmentation, creating divergent procurement patterns across the two largest national markets for workforce management platforms.
United States
California and Massachusetts nurse-to-patient ratio mandates drive real-time compliance documentation demand. OSHA workplace safety reporting requirements shape feature roadmaps for incident tracking modules. Large health systems in Pennsylvania and Texas are consolidating vendor relationships around cloud-native scheduling platforms.
Germany
Hospital federations in Bavaria and North Rhine-Westphalia are standardizing workforce analytics across regional networks. The country's national healthcare regulator supports interoperability frameworks for pooled procurement. Academic medical centers in Berlin and Munich anchor demand for predictive scheduling modules.
United Kingdom
NHS trust consolidation creates enterprise-scale procurement opportunities for integrated scheduling and payroll systems. The country's data protection authority enforces strict workforce data handling requirements. London and Manchester health systems lead adoption of real-time location systems for nurse tracking.
Canada
Provincial health authority consolidation in Ontario and British Columbia drives demand for unified workforce platforms. Health Canada oversees software safety classifications affecting scheduling algorithms with clinical decision support. Toronto and Vancouver academic hospitals anchor cloud migration projects.
Japan
Metropolitan hospital networks in Tokyo and Osaka address nursing shortages through automated shift optimization. The country's Ministry of Economy, Trade and Industry promotes healthcare IT standardization. Aging demographics in rural prefectures accelerate mobile-first scheduling adoption.
Hospital Workforce Management Software Market Vendor Landscape
United States vendors anchor the cloud-native tier; German specialists hold positions in compliance-heavy European procurement cycles. The market structure concentrates around three to five dominant platforms with deep EHR integration capabilities, while mid-tier providers compete on modular pricing for community hospitals. Two strategic archetypes prevail: enterprise suite providers extending from HRIS roots, and clinical workflow specialists originating in nurse scheduling. Competitive moves center on API-first architecture investments and regional partnership networks for implementation services.
Among enterprise suite providers, Oracle Corporation and UKG Inc. occupy positions exemplifying divergent integration strategies. SAP SE anchors the payroll compliance archetype for multi-jurisdictional health systems. These three companies represent the primary competitive anchors around which mid-tier specialists and regional providers position modular offerings.
| Leading Market Players |
|---|
| UKG Inc. |
| Oracle Corporation |
| Workday Inc. |
| ADP Inc. |
| SAP SE |
| ATOSS Software AG |
| Infor |
| McKesson Corporation |
| Cornerstone Ondemand Inc. |
| Others |
Supply Flow & Price Mechanics
HL7 FHIR integration specialists in Massachusetts and California command wage premiums that compress SaaS pricing spreads between enterprise and mid-market tiers. Labor-cost differentials between health system IT departments and vendor implementation teams directly widen the gap between premium cloud-native deployments and economy-tier on-premises alternatives.
Pricing Analysis
Capacity additions in Germany's Bavarian hospital federation networks are reshaping price floors for regional workforce analytics pooling. Three-tier pricing structure across premium, standard, and economy levels segments by EHR integration depth and predictive module inclusion. Pricing pressure stems from subscription fatigue among critical access hospitals in Ohio and Florida. Community hospitals exhibit highest price sensitivity; academic medical centers in Pennsylvania show least.
Supply Chain Analysis
FDA software-as-medical-device qualification gating constrains vendor development roadmaps for acuity-embedded scheduling tools. Software engineering talent concentrates in the United States, Germany, and India. Cloud infrastructure and clinical credential databases constitute critical input dependencies. Single-source vulnerability runs through hyperscaler compute concentration. Distribution runs through direct enterprise sales with regional implementation partner networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Hospital workforce management software functions as a stable compounder anchored by nurse staffing ratio mandates that perpetuate compliance-driven procurement cycles.
For Market Incumbents: To counter modular specialists attacking the perioperative scheduling white space, Oracle Corporation and UKG Inc. must deepen API-first architecture investments and anchor cloud scheduling within Cerner and Epic data architectures. Capacity addition in German hospital federations offers a consolidation lever for regional analytics dominance. For New Entrants and Emerging Players: Regional implementation partners in long-term care facilities represent the most penetrable channel for white-space entry. Perioperative services specialization and mobile-first shift bidding for certified nursing assistants offer undefended segments. Go-to-market through Ohio and Florida critical access hospital GPO contracts accelerates footprint. For Investors and Strategic Acquirers: Health system IT departments are the most active acquirer in this space through captive innovation arms and strategic venture units. Five-to-ten year viability rests on AI scheduling module differentiation. Signal to monitor: FDA premarket review triggers for acuity-scoring algorithms that would reclassify vendor platforms as medical devices.| Strategic Initiative | Industry Significance |
|---|---|
| Platform Integration | HL7 FHIR API connectivity with Cerner and Epic EHR deployments anchors switching costs. |
| Acquisition of Specialist Firm | Perioperative scheduling modules address surgical unit white space faster than organic development. |
| Strategic Partnership | German hospital federation alliances enable pooled procurement leverage across Bavaria and North Rhine-Westphalia. |
| Product Launch | AI-driven predictive scheduling reduces premium labor spend on float pool nurses in Massachusetts academic centers. |
| Geographic Expansion | Cloud-native deployment in Ontario and British Columbia captures Canadian provincial health authority consolidation. |
Methodological Framework
Quantitative tracking and qualitative interviews ran in parallel throughout the study window. Primary engagement captured hospital CIOs, nurse managers, health system procurement committees, HL7 integration specialists, and GPO contracts managers. Secondary validation drew from CMS Medicare cost reports, hospital procurement databases, FDA software guidance documents, and state nursing board regulatory filings. Bottom-up deployment counts and top-down health system IT spending estimates were triangulated.
Segment-weighting applied deployment model, facility size tier, EHR integration complexity, and regional regulatory cluster dimensions across the modeling period. CAGRs derived from historical procurement velocity and mandated compliance upgrade cycles. Forecast inputs incorporated California and Massachusetts nurse ratio enforcement timelines and German hospital federation standardization roadmaps.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to FDA software-as-medical-device reclassification and AI scheduling algorithm liability frameworks. A model refresh is warranted upon material change in federal nurse staffing mandate expansion or hyperscaler cloud pricing volatility.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Healthcare IT
United States Pharmacy Management System Market
Healthcare IT
ECG Management Systems Market
Healthcare IT
Global Pharma Knowledge Management Software Market
Healthcare IT
Prior Authorization Software Market
Healthcare IT
Global Accountable Care Solutions Market
Healthcare IT
Revenue Cycle Management (RCM) Market
Healthcare IT
Medical IoT Software Market
Healthcare IT
Patient Registry Software Market
Healthcare IT
Aged Care Software Market
Healthcare IT
Prior Authorization Workflow Orchestration Market
Healthcare IT
US Practice Management Systems Market
Healthcare IT
Cancer Patient Registry Software Market
Healthcare IT
Pharmaceutical Quality Management Systems Market
Healthcare IT
Pharmaceutical Software Market
Healthcare IT
Wearable Biosensors Market
Healthcare IT
Assisted Living Software Market