
 Chiropractic Software Market | 2026-2036
Chiropractic Software Market Size, Share, and Industry Trends Forecast 2026-2036
Chiropractic Software Market Analysis
North American health IT infrastructure spending is restructuring how chiropractic practices source operational technology. ChiroTouch leverages deep EHR specialization to anchor its position among multi-location clinics. Genesis Chiropractic Software sustains competitive density through billing-centric workflow design. Jane App differentiates via broad allied-health platform extension that captures adjacent provider segments.
Chiropractic software denotes clinical and administrative applications engineered for spinal manipulation therapy practices, typically incorporating SOAP note documentation, appointment scheduling, insurance claims processing, and outcome measurement dashboards with interoperability standards such as HL7 FHIR. The primary commercial purpose centers on reducing documentation burden while ensuring compliant revenue cycle management for cash-based and insurance-reimbursed care models. Cloud-Based deployment now leads new installations as practices prioritize remote accessibility and reduced server maintenance overhead. EHR Software commands the deepest margin pools due to integration complexity and regulatory validation requirements. Patient Engagement Tools represent the fastest-expanding category as outcome transparency becomes central to patient retention strategies.
FDA oversight of software-as-medical-device classifications intersects with HIPAA security rule enforcement to elevate compliance costs for entrants lacking established audit frameworks. State chiropractic boards in California, Texas, and New York impose supplementary documentation standards that fragment vendor certification requirements. Stakeholders must monitor evolving interoperability mandates and payer integration demands as practice consolidation accelerates platform standardization decisions.
Market Dynamics
Cloud migration is compressing procurement cycles for chiropractic practices, as HIPAA security rule enforcement and interoperability mandates force legacy system replacements ahead of planned refresh timelines.
Growth Catalysts
- HL7 FHIR Interoperability:Federal mandates for seamless health data exchange are compelling practice management system upgrades. Multi-location clinics prioritize platforms with native FHIR connectivity.
- United States Urban Healthcare Corridors:Solo and group practices in metropolitan clusters are consolidating vendor relationships around integrated EHR-billing platforms to streamline credentialing across payer networks.
- Patient Outcome Measurement:Transparent reporting dashboards are displacing paper-based satisfaction surveys. Cash-based practices deploy these tools to differentiate against insurance-reimbursed competitors.
Market Restraints
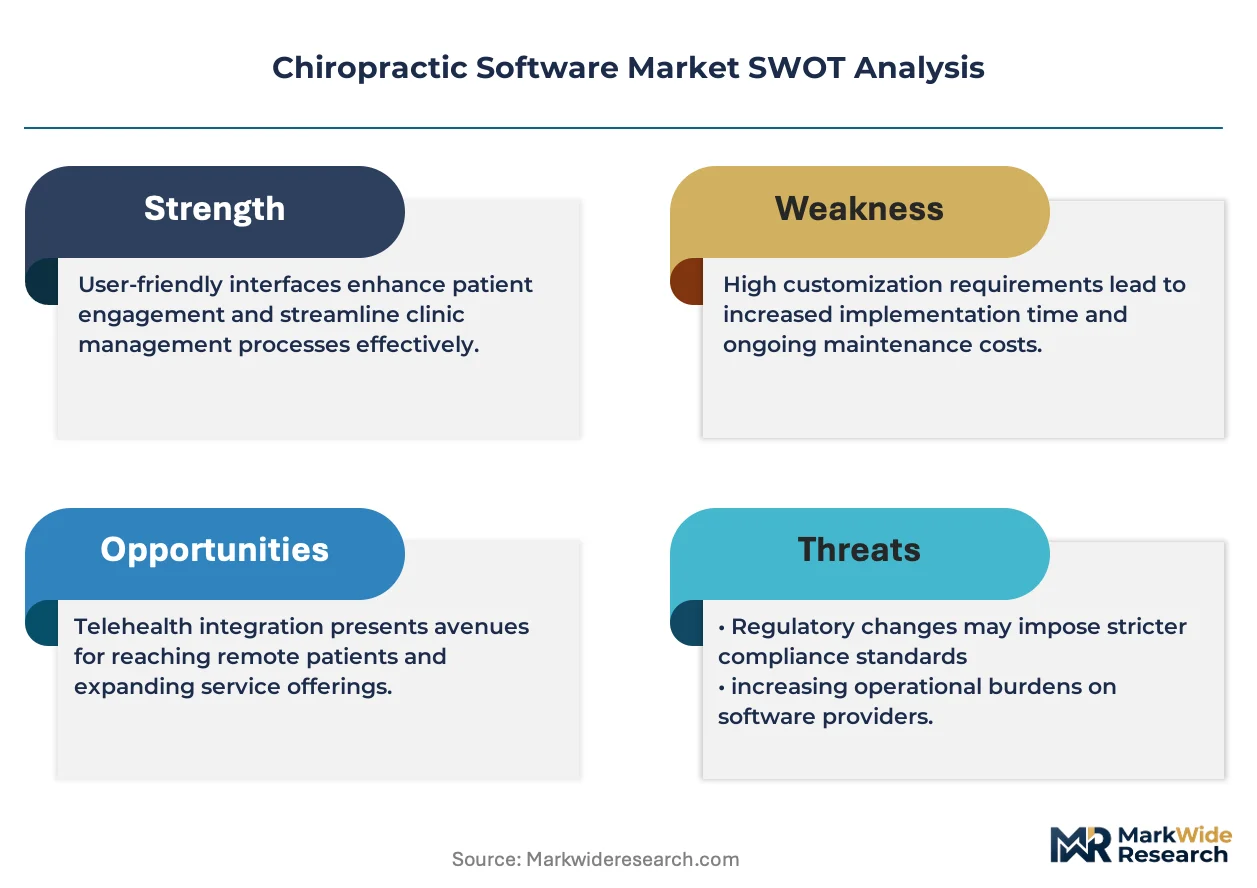
- HIPAA Compliance Cost Burden:Security rule audit frameworks elevate fixed costs for entrants lacking established breach response protocols. Small vendors face disproportionate compliance overhead.
- State Board Documentation Fragmentation:California, Texas, and New York impose non-uniform SOAP note standards. Vendors must maintain separate certification tracks for multi-state practice groups.
- Server Maintenance Substitution:On-premise legacy systems face displacement by cloud-native alternatives. Practices with sunk infrastructure investment delay migration despite long-term TCO advantages.
Strategic Opportunities
- Allied-Health Platform Extension:Physical therapy and acupuncture segments remain underpenetrated by chiropractic-specialized vendors. Workflow adaptation for adjacent provider types captures cross-referral networks.
- Remote Patient Monitoring Integration:Wearable spinal alignment sensors and home exercise compliance trackers converge with practice management platforms. Post-treatment engagement protocols reduce patient attrition.
- Outcome-Based Reimbursement Tailwinds:Commercial payers in select United States markets pilot value-based contracts for musculoskeletal care. Documentation platforms with embedded functional outcome scoring qualify practices for performance bonuses.
Industry Challenges
- Revenue Cycle Certification Complexity:Staff proficient in both clinical documentation and insurance claims adjudication command premium compensation. Training pipelines for hybrid roles remain underdeveloped.
- Legacy System Integration Friction:Data migration from discontinued platforms to cloud-native environments risks patient record corruption. Practices demand parallel operation periods that extend implementation timelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Chiropractic Software Market |
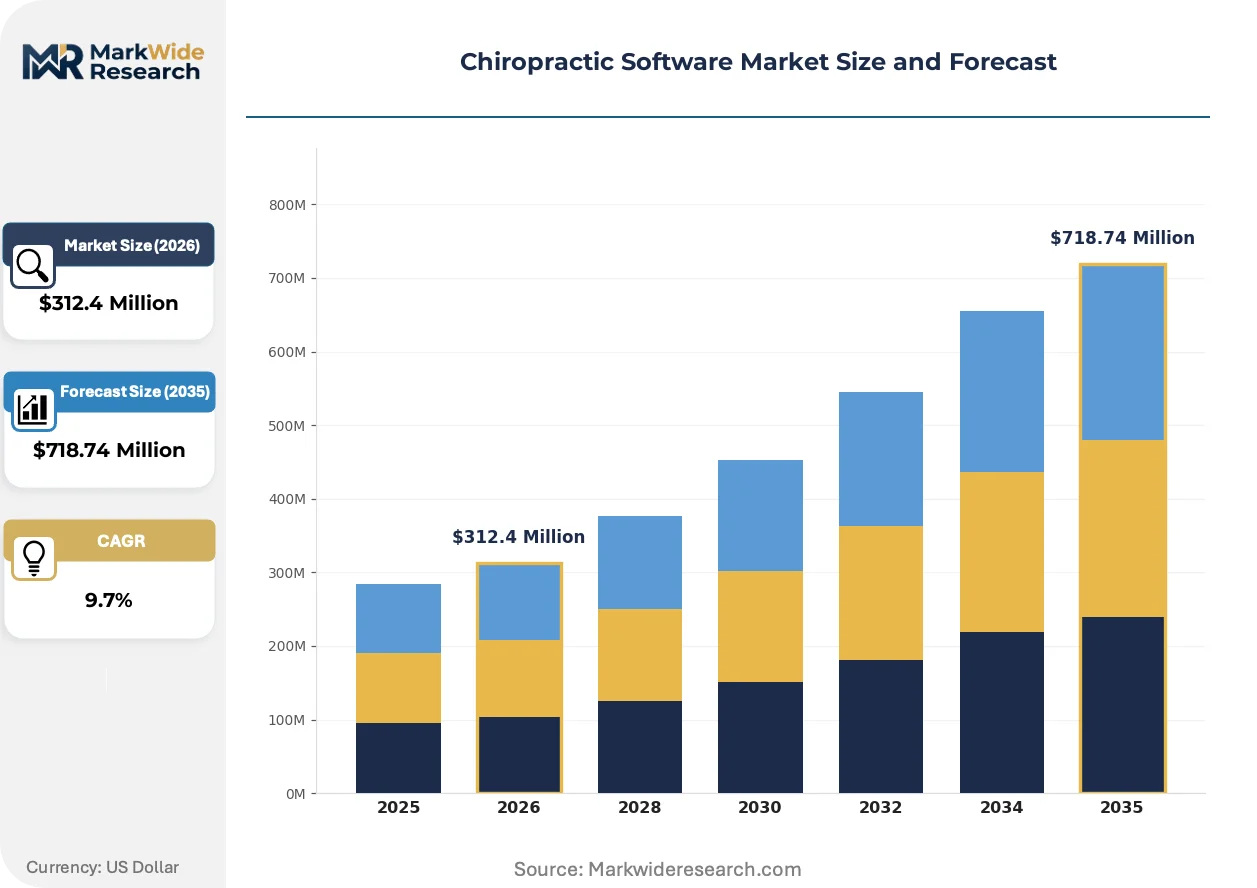
| Market Size in 2026 | $312.4 Million |
| Market Size in 2035 | $718.74 Million |
| CAGR (2026 – 2036) | 9.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Practice Management, Billing Solutions, EHR Software, Patient Engagement Tools End User: Chiropractors, Clinics, Hospitals, Rehabilitation Centers Deployment: On-Premise, Cloud-Based, Hybrid, Mobile Applications Integration Level: Standalone, API-Based, Fully Integrated, Partial Integration |
| Companies Covered | ChiroSpring, Jane App, ChiroTouch, ChiroUp, Genesis Chiropractic Software, SpryPT, Chiro8000, Atlas, ChiroFusion, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Chiropractic Software Market Emerging Trajectories
Artificial intelligence documentation tools and remote accessibility architectures are restructuring how chiropractic practices allocate technology budgets, compressing the traditional seven-year system replacement cycle.
AI-powered SOAP note generation is expanding into high-volume practices, transcribing provider-patient dialogue into structured clinical documentation. Solo practitioners and small group clinics adopt these tools fastest, reducing documentation burden by reallocating staff hours from transcription to patient-facing activities. This compression of administrative labor is expanding into competitive differentiation for cash-based models competing on appointment throughput.
FDA software-as-medical-device classification guidance intersects with HIPAA security rule enforcement to elevate validation requirements for diagnostic support modules. Chiropractic platforms incorporating range-of-motion analysis algorithms face heightened scrutiny. Vendors targeting multi-state practice groups are responding by segregating clinical decision support from core documentation functions to limit regulatory exposure.
Subscription-based pricing models are displacing perpetual license structures among United States chiropractic practices, particularly in urban healthcare corridors with high staff turnover. Cloud-native vendors capture recurring revenue while practices reduce upfront capital deployment. This shift is most visible in North American metropolitan markets where practice consolidation creates centralized procurement authority favoring operational expenditure treatment.
Chiropractic Software Market Segmentation
Chiropractic software procurement decisions cluster around deployment economics and clinical workflow depth. Vendors compete by matching capital requirements to practice scale and regulatory exposure.
Product Type:
Capital intensity varies sharply across clinical versus administrative modules, with regulatory validation costs driving tiered investment thresholds.
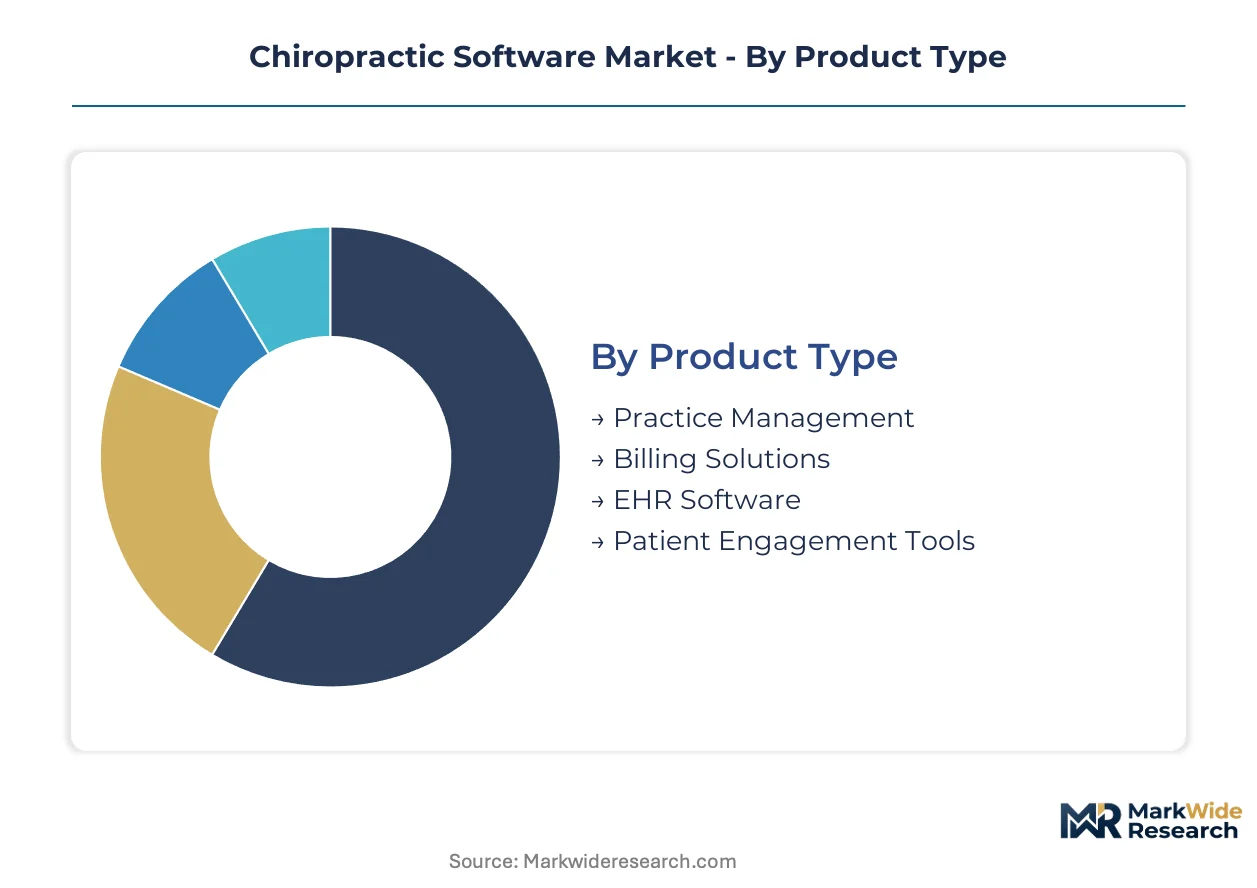
- EHR Software:Clinical documentation platforms with SOAP note structuring, interoperability protocols, and HIPAA audit trails require substantial upfront development and certification expenditure. Multi-location clinic networks in Texas and Florida concentrate demand here, driven by state board documentation mandates and payer credentialing requirements.
- Patient Engagement Tools:Outcome measurement dashboards and automated communication systems deploy lighter infrastructure but demand continuous content development. Cash-based practices in California urban corridors adopt these fastest to differentiate on transparency metrics against insurance-reimbursed competitors.
- Practice Management:Scheduling and workflow orchestration platforms with lower regulatory overhead.
- Billing Solutions:Revenue cycle management modules focused on claims adjudication and denial management.
EHR Software absorbs the bulk of installed capacity; Patient Engagement Tools are expanding most quickly.
End User:
Customer scale determines implementation complexity and customization depth, with hospital systems demanding enterprise-grade integration.
- Clinics:Multi-provider group practices with 5-50 practitioners require scalable platforms balancing standardization with specialty-specific workflows. Metropolitan healthcare clusters in New York and Illinois drive procurement volume, compelled by consolidation trends and centralized IT governance.
- Chiropractors:Solo and small group practitioners under five providers prioritize cost-efficient cloud solutions with minimal IT overhead. These operators across Arizona and Colorado adopt subscription models fastest, reducing capital deployment amid staff turnover pressures.
- Hospitals:Integrated health systems with chiropractic departments demanding full EHR interoperability.
- Rehabilitation Centers:Multi-disciplinary facilities requiring cross-provider documentation standards.
Clinics command the deepest vendor engagement; Chiropractors show the steepest adoption climb.
Deployment:
Operating expenditure versus capital expenditure treatment shapes procurement authority and refresh timelines across practice types.
- Cloud-Based:Browser-accessible platforms with vendor-managed infrastructure eliminate server maintenance burdens. Urban practices in California and Washington State migrate fastest, prioritizing remote accessibility for providers splitting time across locations.
- Mobile Applications:Smartphone-native documentation and scheduling tools target providers with high patient throughput requirements. Younger practitioner cohorts in Texas and North Carolina deploy these for point-of-care SOAP capture, reducing evening administrative hours.
- On-Premise:Locally hosted systems retaining data sovereignty for risk-averse operators.
- Hybrid:Mixed architectures preserving legacy infrastructure while adding cloud connectivity.
Cloud-Based deployment holds dominant share; Mobile Applications gain share fastest.
Integration Level:
Technical architecture determines interoperability scope and regulatory exposure for multi-system environments.
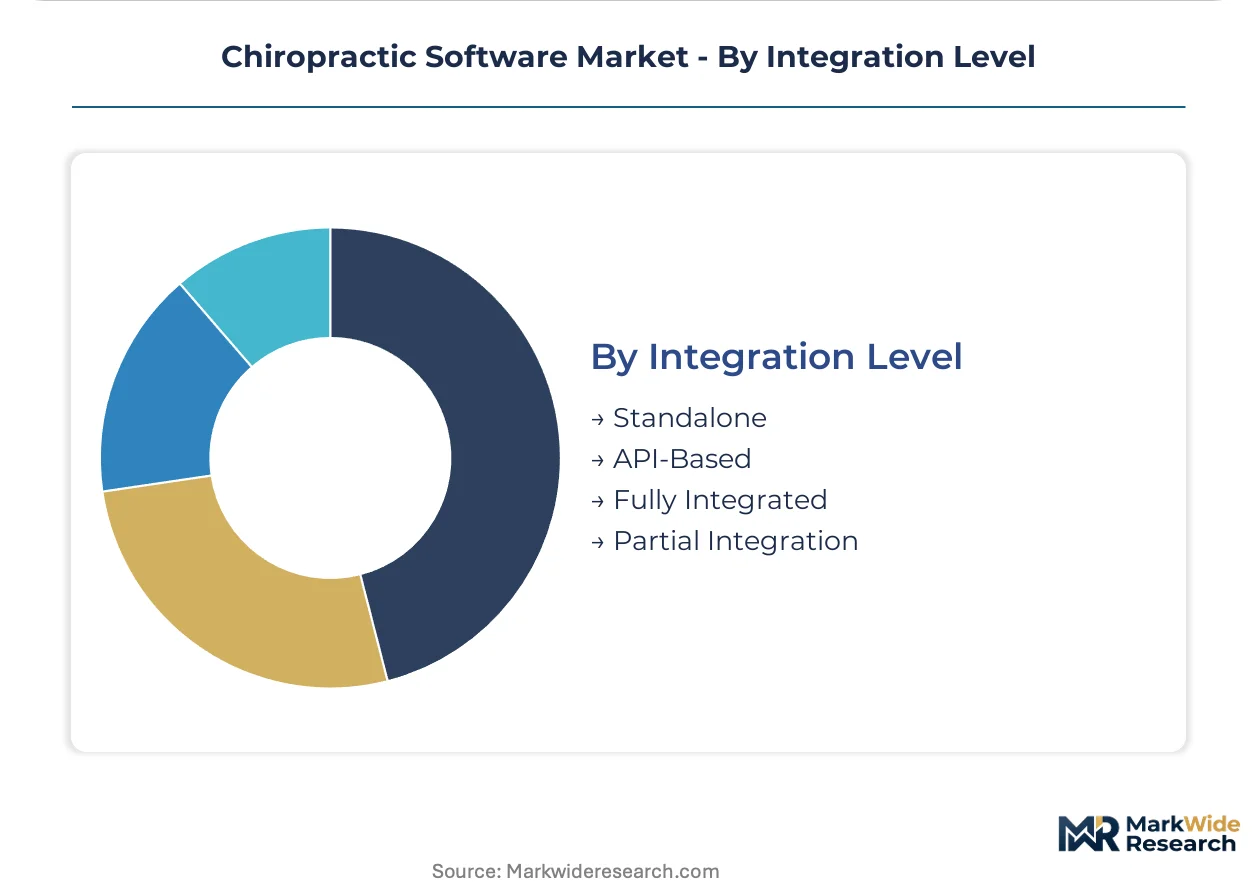
- Fully Integrated:Unified platforms spanning clinical, administrative, and financial functions with native HL7 FHIR connectivity. Multi-state practice groups concentrate demand here, compelled by federal interoperability mandates and payer network standardization requirements.
- API-Based:Modular systems connecting via standardized interfaces to best-of-breed components. Technology-forward clinics in Massachusetts and Washington favor this approach, preserving vendor flexibility while achieving workflow continuity.
- Standalone:Single-function applications operating without external system connectivity.
- Partial Integration:Limited connectivity between select modules, often legacy-dependent.
Fully Integrated platforms anchor enterprise procurement; API-Based architectures climb fastest among mid-market adopters.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Data center infrastructure in Northern Virginia anchors cloud-native software deployment capacity for chiropractic platforms across the United States. Metropolitan healthcare corridors leverage this compute density to deliver low-latency EHR access to multi-location clinic networks.
United States
Urban healthcare corridors in Texas, California, and New York concentrate demand for integrated EHR-billing platforms. HIPAA security rule enforcement compels legacy system replacements ahead of planned refresh timelines. Dallas-Fort Worth and Houston metro areas drive procurement volume as practice consolidation accelerates platform standardization decisions.
Canada
Provincial health data sovereignty requirements shape cloud procurement patterns for chiropractic practices in Ontario and British Columbia. PIPEDA compliance frameworks intersect with provincial privacy statutes to elevate vendor certification requirements. Toronto and Vancouver metropolitan clusters prioritize platforms with domestic data residency guarantees.
United Kingdom
NHS interoperability mandates and GDPR data protection standards reshape software selection criteria for chiropractic clinics in Greater London and Manchester. The Care Quality Commission's digital record-keeping expectations elevate documentation platform requirements. London's private healthcare corridor concentrates demand for premium-tier patient engagement modules.
Germany
BSI cybersecurity certification and GDPR strict liability provisions elevate compliance costs for chiropractic software entrants. Bavaria and North Rhine-Westphalia host the deepest concentration of multi-provider group practices. Munich's healthcare technology cluster drives demand for API-based modular architectures preserving vendor flexibility.
Australia
My Health Record integration requirements and the Privacy Act's notifiable data breach scheme compel platform upgrades for chiropractic practices in New South Wales and Victoria. TGA software-as-medical-device guidance intersects with clinical decision support modules. Sydney and Melbourne metropolitan areas lead cloud migration adoption among solo practitioners.
Chiropractic Software Market Vendor Landscape
Global majors compete with regional champions across EHR specialization depth and billing workflow integration. The vendor base stratifies into three tiers: established healthcare IT conglomerates with broad platform portfolios, chiropractic-specialized pure-plays with deep SOAP note functionality, and allied-health generalists capturing cross-referral networks. Dominant competitive moves include API-based ecosystem partnerships and vertical capability acquisitions targeting revenue cycle expertise.
Within the specialization tier, ChiroTouch and Genesis Chiropractic Software exemplify divergent positioning strategies, with the former anchoring multi-location clinic networks and the latter sustaining density through billing-centric design. Jane App occupies a position bridging chiropractic and adjacent allied-health segments. These three entities represent the spectrum from narrow EHR depth to broad platform extension.
| Leading Market Players |
|---|
| ChiroSpring |
| Jane App |
| ChiroTouch |
| ChiroUp |
| Genesis Chiropractic Software |
| SpryPT |
| Chiro8000 |
| Atlas |
| ChiroFusion |
| Others |
Supply Flow & Price Mechanics
Cloud infrastructure pricing indices cascading from Northern Virginia data centers compress margin structures for chiropractic software vendors, forcing tiered service bundling that separates HIPAA-compliant hosting from premium interoperability modules.
Pricing Analysis
Warranty and service bundling separates basic uptime guarantees from comprehensive breach-response coverage across vendor tiers. Subscription SaaS models dominate new installations, with price differentiation anchored in HL7 FHIR certification depth and state-board documentation compliance breadth. Cost compression in the mid-market intensifies as multi-location clinic networks consolidate procurement authority. Solo practitioners exhibit highest price sensitivity, while hospital-integrated chiropractic departments absorb premium pricing for enterprise-grade integration.
Supply Chain Analysis
Dual-sourcing requirements for cloud infrastructure compel vendors to qualify multiple hyperscale providers, typically AWS and Azure, alongside domestic alternatives for Canadian and European data residency mandates. Software development draws from engineering talent pools concentrated in the United States, India, and Eastern Europe. Raw material dependencies center on semiconductor components for server hardware and specialized encryption modules for HIPAA compliance. Single-source vulnerability in AI training data pipelines poses structural risk. Distribution runs through direct vendor sales teams for enterprise accounts and value-added resellers serving independent practices.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Certified compliance engineering capacity acts as the binding constraint propping pricing power for established vendors, as HIPAA audit frameworks and state-board documentation standards outpace qualified talent supply.
For Market Incumbents: Anticipate margin compression from API-first challengers by deepening vertical integration into revenue cycle management services and accelerating FHIR certification investment ahead of federal mandate expansion. Channel control through exclusive partnerships with chiropractic purchasing cooperatives in Texas and California preserves installed-base migration risk. For New Entrants and Emerging Players: Enter via allied-health platform extension targeting physical therapy and acupuncture workflows, where chiropractic-specialized incumbents maintain shallow penetration. Cash-based practices in Arizona and Colorado represent the most penetrable segment, with subscription pricing and mobile-first documentation as the primary go-to-market angle. For Investors and Strategic Acquirers: Distressed-cycle entries favor billing-centric workflow specialists with established payer network credentialing in the United States Southeast, where practice consolidation creates rollup opportunities. Long-term viability hinges on interoperability mandate compliance breadth rather than single-state certification depth. Watch for CMS value-based contracting pilots in musculoskeletal care as the inflection signal for outcome-measurement platform premiums.| Strategic Initiative | Industry Significance |
|---|---|
| FHIR Certification Acceleration | Native interoperability compliance qualifies vendors for federal health information exchange mandates ahead of enforcement deadlines. |
| Revenue Cycle Service Integration | Embedded billing expertise reduces customer churn by capturing claims adjudication workflows adjacent to clinical documentation. |
| Allied-Health Platform Extension | Physical therapy and acupuncture workflow adaptation captures cross-referral networks and expands addressable provider base. |
| Domestic Data Residency Guarantees | Canadian and European cloud hosting satisfies PIPEDA and GDPR sovereignty requirements for multi-national practice groups. |
| AI Documentation Module Development | FDA software-as-medical-device segregation limits regulatory exposure while preserving competitive differentiation in high-volume practices. |
Methodological Framework
Multi-period observation of vendor pricing disclosures, certification timelines, and practice consolidation patterns anchored the trend analysis, supplemented by interviews with chiropractic practice owners, health IT procurement officers, EHR integration specialists, and revenue cycle management consultants. Secondary validation drew from CMS Medicare reimbursement data, state chiropractic board regulatory filings, hospital GPO contract databases, and hyperscaler infrastructure capex reports. Bottom-up practice-level demand estimates and top-down healthcare IT spending allocations were triangulated for consistency.
Input-output matrices mapped deployment model adoption curves against end-user scale segments and integration complexity tiers across the projection horizon. Segmentation dimensions modeled encompassed product type, practice size, deployment architecture, and regional regulatory cluster. CAGRs were derived from fitted growth curves calibrated to historical adoption rates and policy mandate timelines. Forecast inputs included HIPAA enforcement intensity indices and commercial payer value-based contracting pilot expansion.
Forecast precision tightens around the base case; tail outcomes carry wider variance under accelerated FDA software-as-medical-device reclassification or state-board documentation standard harmonization scenarios. Deviation in federal interoperability mandate enforcement schedules would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Healthcare IT
Healthcare Enterprise Software Market
Healthcare IT
Healthcare Business Collaboration Tools Market
Healthcare IT
US Urgent Care Center Software Market
Healthcare IT
Operating Room Software Market
Healthcare IT
Healthcare Contact Center Solution Market
Healthcare IT
North American Dental Software Market
Healthcare IT
Europe Healthcare Information Technology (IT) Market
Healthcare IT
Pharma Management Software Market
Healthcare IT
Global Computerized Physician Order Entry (CPOE) Systems Market
Healthcare IT
Global Emergency Department Information System Market
Healthcare IT
Operating Room Management Software Market
Healthcare IT
Healthcare Claims Management Software Market
Healthcare IT
Europe Outpatient Software Market
Healthcare IT
Healthcare Revenue Cycle Management (RCM) Software Market
Healthcare IT
Patient Access Solutions Market
Healthcare IT
Radiation Dose Optimisation Software Market