
 Healthcare IT Market | 2026-2036
Healthcare IT Market Size, Share, and Industry Trends Forecast 2026-2036
Healthcare IT Market Analysis
Hospital end-user demand is broadening as health systems merge and centralize technology procurement. Epic Systems dominates inpatient EHR installations across large academic medical centers. Oracle Health leverages its cloud infrastructure to compete for clients seeking modular, interoperable platforms. Philips Healthcare anchors its position through deep clinical informatics integration with imaging workflows.
Healthcare IT encompasses software systems, data infrastructure, and digital platforms that manage clinical, financial, and operational processes across care delivery organizations. Core functional parameters include HL7 FHIR interoperability standards, sub-second query response times for clinical decision support, and 99.99% uptime requirements for cloud-hosted patient records. EMR and EHR product types command the largest installed base, though margin pools are shifting toward cloud-based delivery models where recurring revenue structures reduce customer churn. Telehealth solutions represent the fastest-growing application segment as reimbursement parity policies stabilize and remote monitoring protocols expand beyond acute episodes.
FDA oversight of software-as-medical-device algorithms, ONC certification requirements for interoperability, and HIPAA security rule enforcement collectively shape product development roadmaps and go-to-market timelines. The EU AI Act and GDPR cross-border data transfer provisions add compliance layers for vendors serving multinational health systems. Stakeholders must monitor how FDA's predetermined change control plans for adaptive AI will alter validation costs and competitive positioning in clinical decision support.
Market Dynamics
Hospital consolidation is compressing vendor negotiation cycles as merged health systems centralize procurement under single enterprise architecture mandates. This structural concentration forces IT vendors to restructure pricing and implementation timelines around multi-year framework agreements rather than individual facility sales.
Growth Catalysts
- ONC Interoperability Mandates:Federal certification requirements under the 21st Century Cures Act compel EHR replacement cycles. Health systems must upgrade to HL7 FHIR-compliant platforms to maintain Medicaid and Medicare reimbursement eligibility.
- Cloud Infrastructure Migration:Hospital IT departments are retiring on-premise data centers in favor of elastic compute environments. This shift reduces capital expenditure burdens while enabling real-time analytics across distributed care networks.
- Telehealth Reimbursement Parity:State-level policy alignment with federal Medicare telehealth expansions sustains demand for integrated virtual care platforms. Rural hospitals leverage these tools to extend specialist access without physical infrastructure investment.
Market Restraints
- Implementation Cost Concentration:Large-scale EHR deployments require 18-36 month capital commitments that strain mid-sized community hospital balance sheets. These institutions lack the IT staffing depth to manage parallel legacy and modern system operations.
- Cybersecurity Insurance Volatility:Ransomware attacks against healthcare targets have compressed carrier appetite and expanded premium obligations. Underwriters now mandate specific endpoint detection protocols as coverage prerequisites.
- Technical Debt Accumulation:Decades of proprietary system layering creates integration friction that slows modular platform adoption. Custom code dependencies resist standard API connectivity without expensive remediation.
Strategic Opportunities
- AI-Enabled Clinical Decision Support:FDA predetermined change control plans for adaptive algorithms create regulatory clarity. Vendors can now design continuous learning diagnostic tools without repeated 510(k) submissions for each model update.
- Remote Patient Monitoring Expansion:Chronic disease management protocols are extending beyond acute episodes into longitudinal home-based surveillance. Device-agnostic platforms that aggregate multiple biometric streams command premium positioning.
- European Market Entry:EU AI Act risk classification frameworks and MDR software-as-medical-device pathways create structured compliance roadmaps. US vendors with ISO 13485 quality systems can leverage existing documentation for CE marking acceleration.
Industry Challenges
- Interoperability Engineer Scarcity:Health systems compete for talent capable of mapping proprietary data schemas to FHIR resources. Academic training programs have not scaled to meet implementation demand.
- Legacy System Decommissioning:Data archival requirements and user retraining burdens extend parallel system operation timelines. Hospitals face dual maintenance costs during migration windows.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Healthcare IT Market |
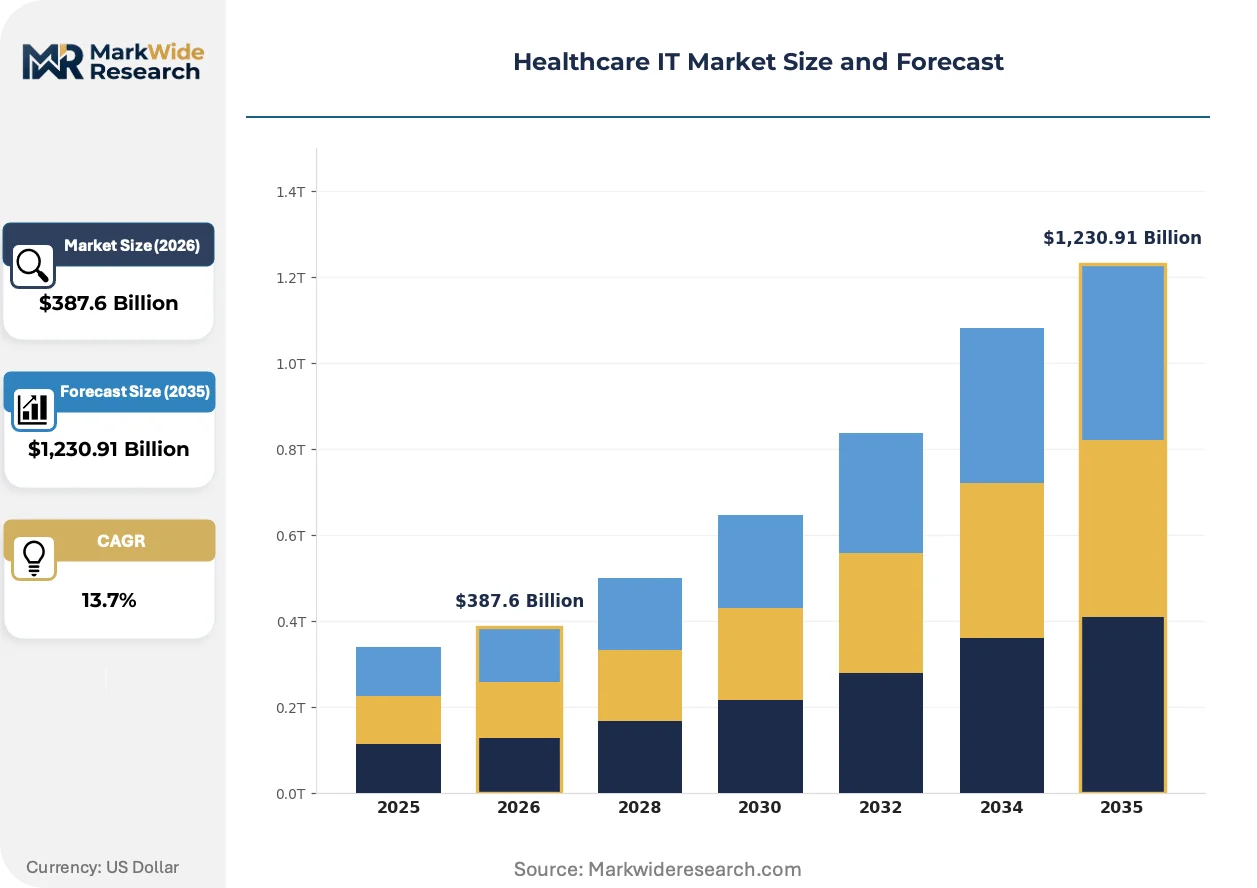
| Market Size in 2026 | $387.6 Billion |
| Market Size in 2035 | $1,230.91 Billion |
| CAGR (2026 – 2036) | 13.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: EMR, EHR, Telehealth Solutions, Healthcare Analytics End User: Hospitals, Clinics, Diagnostic Labs, Long-term Care Facilities Application: Patient Management, Revenue Cycle Management, Population Health, Clinical Decision Support Delivery Model: On-premise, Cloud-based, Hybrid, SaaS |
| Companies Covered | Epic Systems, Oracle Health, GE Healthcare, Philips Healthcare, McKesson Corporation, Optum, Allscripts, athenahealth, Meditech, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Healthcare IT Market Emerging Trajectories
Healthcare IT architecture is pivoting from record-keeping systems toward predictive platforms that anticipate clinical deterioration and resource constraints. This transformation redefines vendor competitive advantage around data science capabilities rather than workflow automation depth.
Generative AI documentation tools are absorbing physician administrative burden across emergency and primary care settings. Large health systems in Texas and California have deployed ambient clinical intelligence for real-time encounter summarization. This technology is absorbing transcription service contracts and medical scribe staffing budgets into platform licensing fees.
The EU AI Act high-risk system classification for clinical decision support imposes conformity assessment obligations on vendors serving European health networks. CE marking timelines have extended as notified bodies develop evaluation protocols for machine learning-based diagnostics. German university hospitals are delaying procurement decisions until regulatory clarity stabilizes, compressing near-term revenue recognition for affected product categories.
Subscription-based platform economics are displacing perpetual license arrangements in health system procurement. Chief information officers now prioritize total cost-of-ownership metrics over upfront capital expenditure comparisons. This preference shift is most visible in the southeastern United States, where hospital operating margins remain under pressure from labor cost inflation and payer mix deterioration.
Healthcare IT Market Segmentation
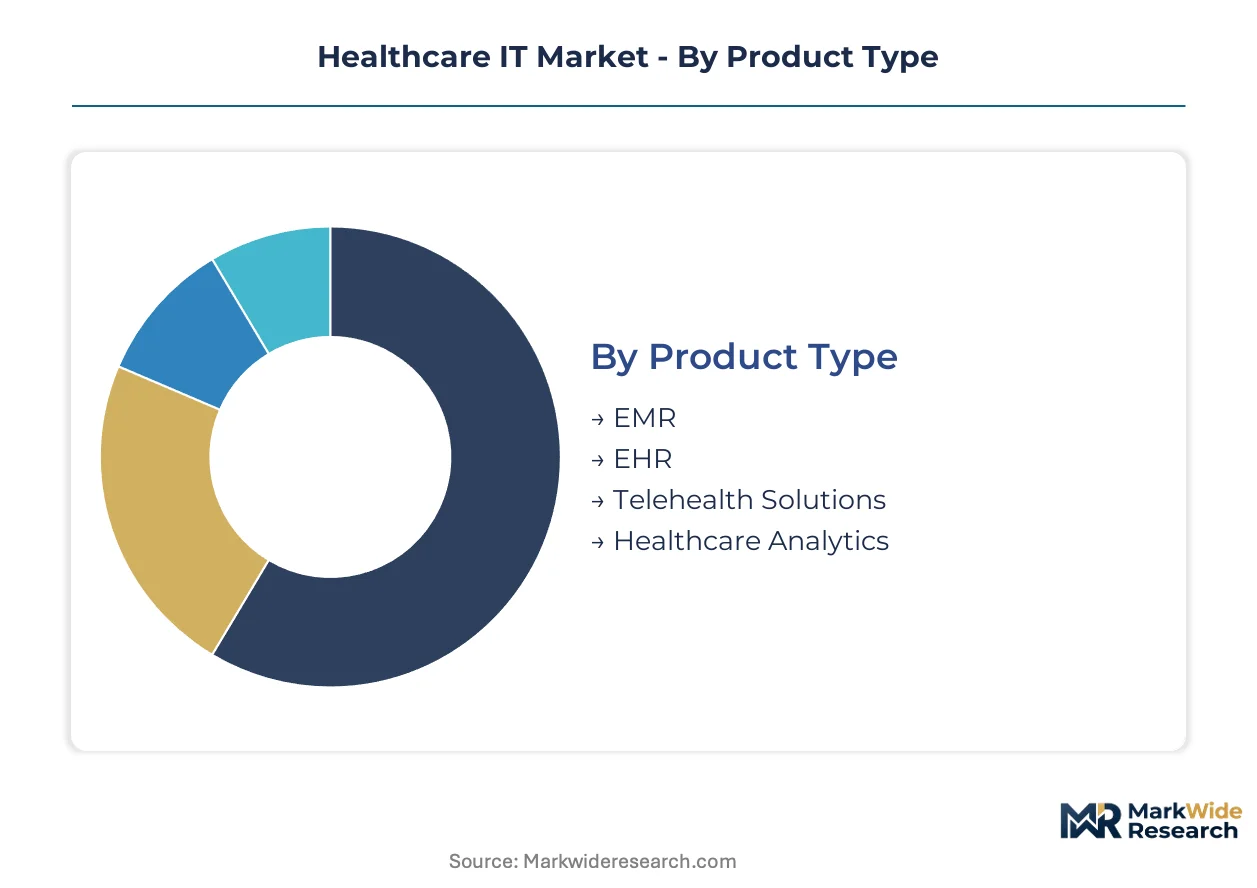
Healthcare IT procurement decisions hinge on interoperability mandates, cloud migration timelines, and reimbursement eligibility requirements. Segmentation reveals where capital concentrates versus where subscription economics are displacing perpetual licenses.
Product Type:
Hospital capital committees prioritize systems that secure federal certification and enable value-based care reporting.
- EMR:Electronic medical record systems manage patient encounters within single organizational boundaries. Demand concentrates in mid-sized community hospitals replacing decade-old installations to meet ONC certification deadlines.
- EHR:Comprehensive health record platforms aggregate longitudinal data across care settings. Academic medical centers in the United States drive replacement cycles as they consolidate acquired facilities under unified architectures.
- Telehealth Solutions:Virtual care platforms integrate video consultation with remote monitoring workflows. Rural health networks leverage these tools to extend specialist access without facility expansion.
- Healthcare Analytics:Predictive platforms process clinical and operational data for resource optimization. Health systems deploy these tools to reduce readmission penalties and optimize OR block scheduling.
Volume sits with EHR installations; growth tilts toward telehealth solutions.
End User:
Procurement scale and implementation complexity vary dramatically across care delivery settings.
- Hospitals:Large health systems negotiate multi-year enterprise agreements covering dozens of facilities. These buyers demand 99.99% uptime SLAs and sub-second clinical decision support response times.
- Clinics:Outpatient practices prioritize rapid deployment and minimal IT staffing requirements. Federally qualified health centers represent a concentrated demand pool as they modernize under HRSA infrastructure grants.
- Diagnostic Labs:Laboratory information systems require deep integration with imaging modalities and billing platforms. Reference labs invest in interoperability infrastructure to exchange results directly with ordering provider EHRs.
- Long-term Care Facilities:Skilled nursing and assisted living operators adopt point-of-care documentation tools. Medicaid reimbursement complexity drives demand for integrated revenue cycle capabilities.
Revenue concentrates in hospital contracts; expansion accelerates fastest among long-term care facilities.
Application:
Functional priorities shift based on organizational maturity and payment model exposure.
- Patient Management:Scheduling, registration, and care coordination workflows form the operational backbone. Health systems consolidate these functions across merged entities to eliminate redundant administrative layers.
- Revenue Cycle Management:Claims processing and denial management tools protect operating margins. Denial rates exceeding industry benchmarks trigger urgent procurement decisions.
- Population Health:Risk stratification and care gap analytics support value-based contract performance. Medicare ACOs represent the primary demand concentration as they assume downside risk.
- Clinical Decision Support:Evidence-based order sets and diagnostic algorithms reduce variation. FDA predetermined change control plans enable adaptive AI deployment without repeated 510(k) submissions.
Deployment volume favors patient management; clinical decision support climbs the fastest as AI validation pathways mature.
Delivery Model:
Total cost-of-ownership calculations now dominate vendor selection over upfront capital comparisons.
- On-premise:Self-hosted infrastructure retains relevance for organizations with specialized security requirements. Defense health facilities and certain research institutions maintain these deployments for data sovereignty.
- Cloud-based:Elastic compute environments eliminate data center capital burdens and enable disaster recovery automation. Hospital networks in the southeastern United States accelerate migration as operating margins compress.
- Hybrid:Mixed architectures preserve sensitive workloads on-premise while bursting analytics to cloud. This configuration appeals to organizations navigating legacy system decommissioning timelines.
- SaaS:Subscription licensing transfers implementation risk to vendors and accelerates time-to-value. Chief information officers increasingly mandate SaaS for non-core administrative applications.
Installed base remains with on-premise systems; new procurement tilts decisively toward SaaS structures.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Research Triangle Park in North Carolina and Boston's Longwood Medical Area concentrate health IT development through tax-advantaged zones and NIH proximity. Federal interoperability mandates and cloud migration incentives reshape procurement geography across mature health economies.
United States
Hospital consolidation drives enterprise EHR replacement cycles across merged health systems. ONC certification requirements under the 21st Century Cures Act compel Medicaid and Medicare reimbursement-linked upgrades. Epic Systems dominates installations across academic medical centers clustered in Wisconsin and the Upper Midwest.
Germany
University hospitals delay AI-enabled diagnostic procurement pending EU AI Act conformity assessment clarity. BfArM and notified bodies develop evaluation protocols for machine learning-based clinical decision support. Berlin and Munich health networks pilot FHIR-compliant data exchange infrastructure under national digitization mandates.
United Kingdom
NHS England's Federated Data Platform procurement concentrates cloud analytics demand among integrated care systems. NHS Digital interoperability standards accelerate legacy system decommissioning timelines. London's King's Health Partners and Manchester's health innovation campus anchor vendor pilot programs for predictive analytics deployment.
India
Hospital chains in Maharashtra and Karnataka modernize revenue cycle infrastructure to capture medical tourism flows. CDSCO software-as-medical-device pathways and Ayushman Bharat digital health mission create structured procurement frameworks. Hyderabad's Genome Valley and Bangalore's health tech corridor attract SaaS vendors targeting diagnostic lab digitization.
Japan
Metropolitan hospital networks retire decade-old on-premise systems for cloud-hosted patient records. PMDA guidance on adaptive AI algorithms enables continuous learning diagnostic tools without repeated regulatory submissions. Tokyo and Osaka medical centers prioritize clinical decision support integration with existing imaging workflows.
Healthcare IT Market Vendor Landscape
Branded specialists and contract manufacturers split share differently across segments, with integrated platform vendors commanding hospital enterprise contracts while modular specialists capture clinic and ambulatory settings. Market structure tilts toward consolidation as merged health systems centralize procurement under single-vendor architectures. Three archetypes dominate: legacy EHR incumbents with deep workflow integration, cloud-native challengers with API-first interoperability, and imaging-informatics hybrids leveraging diagnostic device relationships. M&A activity concentrates on analytics capabilities and telehealth infrastructure, while strategic partnerships between EHR vendors and cloud hyperscalers reshape hosting economics.
Among US-based platform vendors, Epic Systems, Oracle Health, and athenahealth occupy distinct positioning tiers. Epic exemplifies the integrated incumbent archetype through its dominance in large academic medical center installations. Oracle Health represents cloud infrastructure leverage as a competitive vector for modular platform delivery. athenahealth sits within the SaaS-native challenger tier targeting outpatient and ambulatory network consolidation.
| Leading Market Players |
|---|
| Epic Systems |
| Oracle Health |
| GE Healthcare |
| Philips Healthcare |
| McKesson Corporation |
| Optum |
| Allscripts |
| athenahealth |
| Meditech |
| Others |
Supply Flow & Price Mechanics
Consolidated hospital networks in the United States now command 60-70% of annual EHR procurement volume, forcing vendors toward multi-year enterprise subscription frameworks rather than perpetual license arrangements. This buyer concentration compresses negotiation cycles and transfers implementation risk to suppliers through outcome-based pricing clauses.
Pricing Analysis
Short lead-time deployments command 15-25% premiums over standard 18-36 month implementation schedules as health systems face ONC certification deadlines. Three-tier pricing structure across premium, standard, and economy levels segments by deployment complexity and interoperability maturity. Cost compression in mid-sized community hospital tiers is intensifying because these buyers lack IT staffing depth for parallel system operations. Federally qualified health centers represent the most price-sensitive segment, while academic medical centers prioritize uptime SLAs over capital efficiency.
Supply Chain Analysis
Cloud infrastructure supply rests on hyperscaler data center concentration in the United States, Ireland, and Singapore, with specialized healthcare compliance regions expanding in Germany and Japan. Compute instances, API middleware, and FHIR translation engines constitute the critical input stack. Single-source vulnerability concentrates in Epic Systems' proprietary interoperability protocols, which resist standard API connectivity. Distribution runs through direct enterprise sales teams for hospital networks and channel partners for ambulatory clinic segments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Healthcare IT is becoming a vertical-integration race as vendors pursue captive control over cloud infrastructure to escape hyperscaler margin extraction. This upstream lever determines whether platform economics or hosting costs dominate profitability.
For Market Incumbents: Cement dominance in large academic medical centers by accelerating FHIR-native module development ahead of 21st Century Cures Act enforcement windows. Defend against Oracle Health's cloud infrastructure leverage through deeper clinical workflow integration that raises switching costs. Prioritize backward integration into remote patient monitoring device ecosystems to capture longitudinal data streams. For New Entrants and Emerging Players: Begin with AI-enabled clinical documentation tools for emergency departments, where physician burnout creates urgent demand and incumbent workflow entrenchment remains shallow. Skilled nursing facilities offer the most penetrable segment given their lagging digitization and Medicaid reimbursement complexity. Pursue SaaS-native positioning with rapid deployment guarantees to differentiate from legacy EHR implementation timelines. For Investors and Strategic Acquirers: The window for entry favors analytics specialists with FDA-predetermined change control plans already filed. Long-term viability hinges on platforms that aggregate multiple biometric streams for device-agnostic remote monitoring. Watch for EU AI Act conformity assessment clarity as the inflection signal for European health network procurement resumption.| Strategic Initiative | Industry Significance |
|---|---|
| FHIR-Native Platform Development | ONC certification requirements under the 21st Century Cures Act compel compliant architectures for reimbursement eligibility. |
| Cloud Infrastructure Partnership | Hyperscaler alliances reduce capital expenditure burdens while enabling elastic compute for real-time analytics. |
| AI Clinical Decision Support Submission | FDA predetermined change control plans enable continuous learning without repeated 510(k) submissions. |
| Remote Monitoring Device Integration | Device-agnostic platforms that aggregate biometric streams command premium positioning in chronic disease management. |
| EU Market CE Marking Pathway | MDR software-as-medical-device compliance creates structured entry for US vendors with ISO 13485 systems. |
Methodological Framework
Document review covered hospital procurement databases, GPO contracts, CMS Medicare reimbursement filings, and ONC certification records, complemented by interviews with hospital CIOs, EHR implementation specialists, and interoperability engineers. Primary fieldwork included discussions with FDA regulatory affairs consultants and EU notified body representatives. Secondary validation drew from SEC filings of publicly traded health IT vendors and hyperscaler healthcare vertical disclosures. Bottom-up facility-level demand estimates were triangulated against top-down health system IT budget aggregates.
Segment-level revenue outputs were generated through multi-dimensional modeling across deployment model, organization size, application function, and regional regulatory cluster. CAGRs were derived from fitted growth curves calibrated to historical EHR replacement cycles and telehealth reimbursement policy trajectories. Cloud migration velocity and AI clinical decision support adoption curves served as key forecast inputs.
Underlying measurement precision varies by segment; cloud-based delivery models carry tighter precision than on-premise legacy systems given disclosed vendor subscription metrics. Forecasts reflect assumptions around ONC enforcement timelines and EU AI Act implementation clarity. Cybersecurity insurance market volatility and interoperability engineer scarcity represent specific risk factors that could revise projections. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Healthcare IT
US Long Term Care Software Market
Healthcare IT
Dental Implantology Software Market
Healthcare IT
Patient Access Solutions Market
Healthcare IT
Epharmacy Market
Healthcare IT
Global Technology Spending on Core Administration in Healthcare Market
Healthcare IT
Hand Hygiene Monitoring System Market
Healthcare IT
Healthcare IT Consulting Services Market
Healthcare IT
US Dental Clearing Houses Market
Healthcare IT
Digital Mhealth Solution Market
Healthcare IT
Europe Hospital Capacity Management Solutions Market
Healthcare IT
Europe Outpatient Software Market
Healthcare IT
Radiation Dose Optimisation Software Market
Healthcare IT
Chiropractic Software Market
Healthcare IT
Anatomic Pathology Track and Trace Solutions Market
Healthcare IT
Healthcare Mobility Solutions Market
Healthcare IT
Global Pharmacy Inventory Management Software Solutions and Cabinets Market