

Encapsulated Salicylic Acid Market Size, Share, and Industry Trends Forecast 2026-2036
Encapsulated Salicylic Acid Market Insights
Asset-light contract manufacturing and toll-processing arrangements are narrowing the capital barrier for mid-tier competitors in encapsulated salicylic acid supply. Thermo Fisher Scientific leverages its analytical and formulation services footprint to sustain high-margin custom encapsulation programs for pharmaceutical clients. BASF SE anchors European supply through polymer-coated particle expertise, while Seqens Group competes via specialized active-ingredient finishing capabilities across multiple geographies.
Encapsulated salicylic acid consists of beta-hydroxy acid cores shielded within lipid, polymer, or polysaccharide shells, typically ranging from 50 nanometers to 5 micrometers in diameter, designed to enable timed release and reduce dermal irritation in topical delivery. Microcapsules occupy the largest volume share among product types due to established manufacturing scalability and broader compatibility with cream and lotion bases, while nanocapsules are gaining traction in serum formulations where deeper epidermal penetration drives premium positioning. Anti-dandruff solutions and keratolytic agents represent mature application segments with stable offtake, whereas hyperpigmentation control is emerging as a faster-growing category as brands seek alternatives to hydroquinone-restricted formulations.
FDA oversight of over-the-counter topical acne therapies and EPA reporting requirements for salicylic acid manufacturing emissions shape compliance costs and facility location decisions for suppliers. EMA's MDR and REACH substance evaluation protocols in Europe impose additional toxicological documentation burdens that favor larger players with dedicated regulatory affairs infrastructure. Stakeholders must monitor evolving state-level cosmetic ingredient disclosure laws and biocompatibility testing standards as these frameworks increasingly determine market access velocity and reformulation timelines.
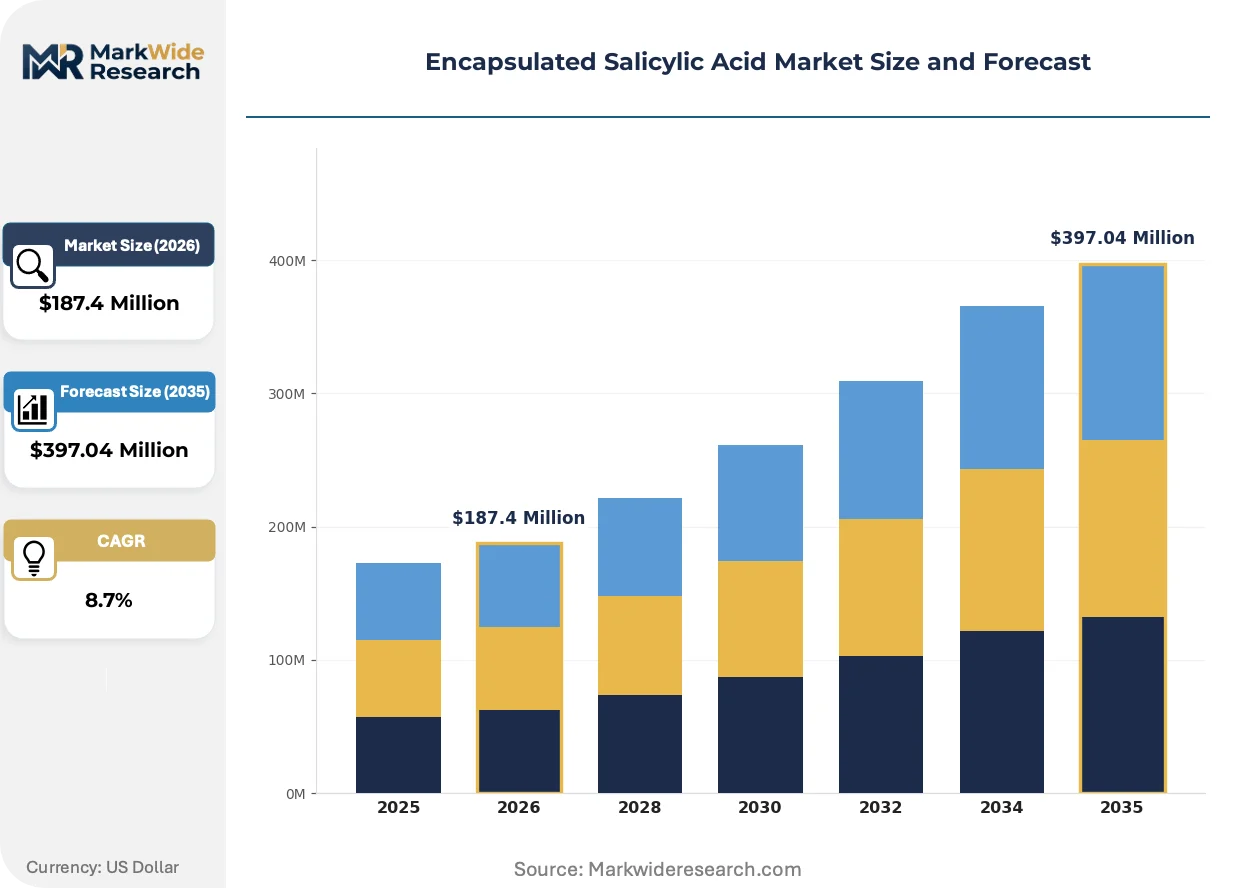
Market Dynamics
Encapsulation technology providers face mounting pressure from REACH substance evaluation protocols and EPA reporting mandates that demand validated toxicological documentation for every batch release, forcing capital reallocation toward analytical infrastructure.
Growth Catalysts
- REACH compliance deadlines:European manufacturers must submit enhanced safety dossiers for salicylic acid derivatives, accelerating substitution toward pre-validated encapsulated formats with existing registration packages.
- China's domestic pharmaceutical capacity:Local producers in Jiangsu and Zhejiang provinces are scaling lipid-based encapsulation lines to serve NMPA-registered topical drug applications.
- Keratolytic agent reformulation:Dermatology brands are replacing conventional salicylic acid with polymer-coated microcapsules to reduce irritation claims and expand OTC labeling flexibility.
Market Restraints
- Ethanol feedstock volatility:Salicylic acid synthesis depends on petrochemical-derived phenol and sodium hydroxide, exposing margin structures to energy price swings.
- Specialized equipment concentration:Fluidized bed coating systems and spray-dryer assemblies for sub-micron encapsulation concentrate among German and Swiss machinery suppliers.
- Hydroquinone substitution ceiling:Regulatory restrictions on skin-lightening actives create demand pull, but encapsulated salicylic acid exhibits inferior melanin suppression versus kojic acid alternatives in head-to-head trials.
Strategic Opportunities
- Southeast Asian personal care manufacturing:Indonesia and Vietnam lack domestic encapsulation capabilities, creating import substitution potential for toll-processing partnerships with regional contract manufacturers.
- Biodegradable polymer shells:Convergence of polylactic acid coating technology with fermentation-derived salicylic acid enables carbon-neutral positioning for premium skincare lines.
- Direct-to-clinic distribution:Medical aesthetic chains in Brazil and Mexico are bypassing traditional wholesale channels to procure bulk encapsulated actives for in-house compounding.
Industry Challenges
- Formulation chemist scarcity:The intersection of colloid science, pharmaceutical stability testing, and cosmetic regulatory affairs requires hybrid expertise that training programs have failed to produce at scale.
- Batch-to-batch release variability:Microcapsule size distribution and shell thickness tolerances complicate tech transfer between toll manufacturers and brand owners, extending qualification timelines.
- Legacy ERP integration:Encapsulation specialists adopting automated process analytical technology face friction connecting real-time coating monitors to incumbent manufacturing execution systems.
Report Scope
MarkWide ResearchGet the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Encapsulated Salicylic Acid Market Trends and Innovations
Digital formulation platforms and closed-loop process control are compressing development cycles for encapsulated actives, while regulatory pre-certification programs reshape competitive access.
Multilayer polymer-lipid hybrid shells are virtualizing the performance gap between conventional salicylic acid and next-generation beta-hydroxy acid derivatives. Korean skincare brands are adopting these structures for overnight repair serums at triple the pace of North American counterparts. The technology is virtualizing R&D expenditure patterns, allowing mid-tier competitors to bypass decade-long stability studies through licensed platform access.
EMA's Medical Device Regulation extension to borderline cosmetic-pharmaceutical products is forcing encapsulation houses to maintain dual quality management systems. Manufacturers serving both OTC drug and cosmetic markets face redundant audit burdens that favor larger players with dedicated regulatory infrastructure. Serum and ampoule categories in France and Italy are experiencing the steepest compliance cost inflation as ANSM intensifies post-market surveillance.
Medical spa chains and dermatology clinics are consolidating procurement of encapsulated actives through group purchasing organizations, displacing traditional distributor relationships. This concentration is compressing price negotiation cycles and demanding just-in-time inventory commitments from toll manufacturers. The shift is most visible in California and Florida, where vertically integrated aesthetic chains now represent the dominant volume channel for professional-grade keratolytic formulations.
Encapsulated Salicylic Acid Market Segmentation
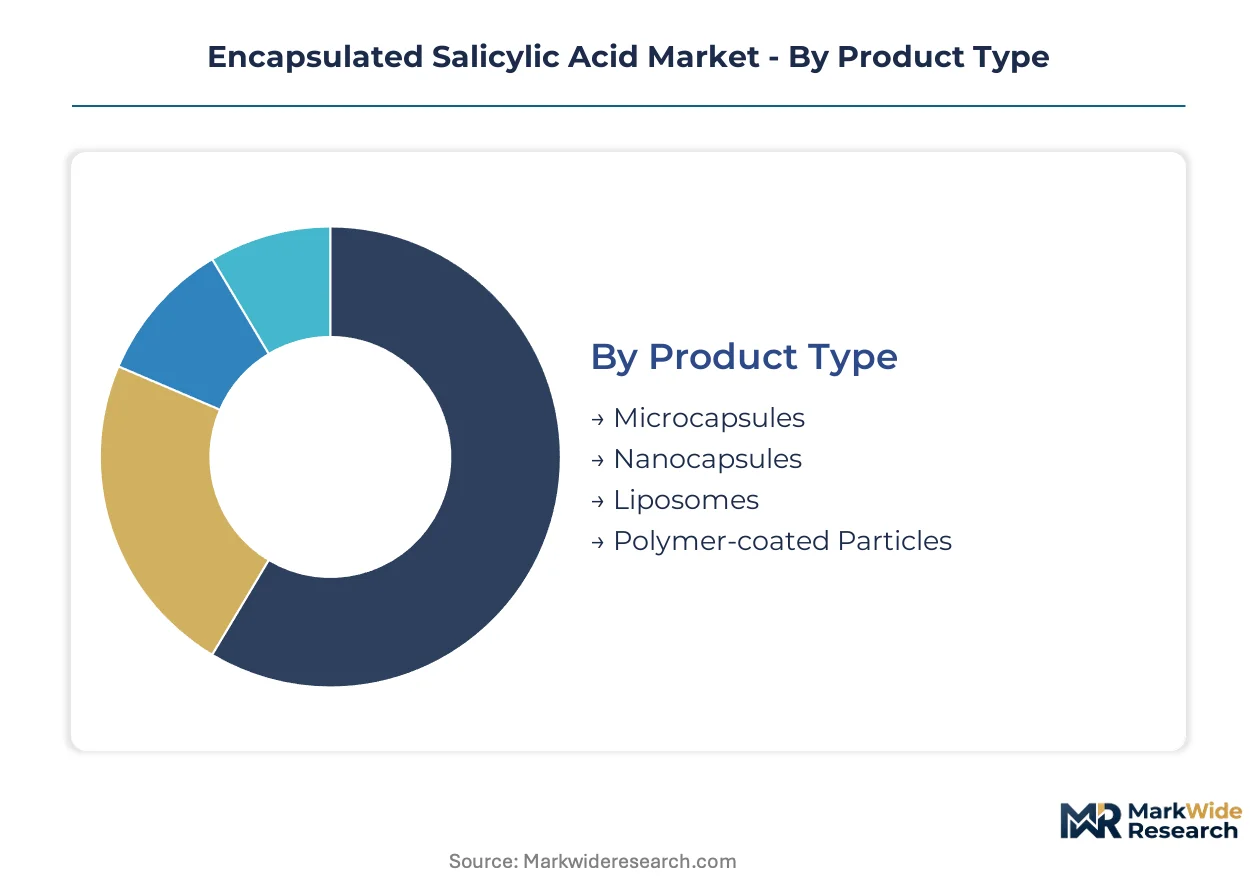
Encapsulated salicylic acid formulations diverge sharply across delivery platforms, therapeutic targets, and end-user procurement patterns. Each segmentation axis carries distinct technical specifications, regulatory pathways, and margin structures that determine competitive positioning.
Product Type:
Delivery platform selection governs release kinetics, stability profiles, and manufacturing capital intensity across the use-case spectrum.
- Microcapsules:Shell structures ranging 1-5 micrometers composed of ethylcellulose or gelatin matrices enable sustained release over 8-12 hours. Demand concentrates in mass-market anti-dandruff shampoos where cost-per-unit constraints dominate procurement decisions at Unilever and P&G scale.
- Nanocapsules:Sub-micron lipid or polymer shells below 200 nanometers penetrate stratum corneum barriers for transdermal delivery. Korean serum manufacturers in Seoul and Busan are scaling capacity fastest, driven by medical aesthetic clinic demand for minimal-irritation keratolytic treatments.
- Liposomes:Phospholipid bilayer vesicles enhance bioavailability in dermatological preparations.
- Polymer-coated Particles:Multi-layer synthetic shells provide tunable release profiles for prescription-grade psoriasis therapies.
Established volume favors microcapsules; emerging adoption favors nanocapsules.
Application:
Clinical indication determines regulatory classification, reimbursement access, and formulation complexity tiers.
- Acne Treatment:OTC monograph compliance under FDA 21 CFR 333.310 specifies 0.5-2% salicylic acid concentration limits. North American private-label manufacturers dominate volume, though EU-based brands face stricter ANSM post-market surveillance requirements in France.
- Psoriasis Therapy:Prescription-grade encapsulation requires validated bioequivalence studies for generic substitution. German dermatology clinics are expanding compounded topical prescriptions, bypassing traditional pharmaceutical distribution channels.
- Anti-Dandruff Solutions:Mature segment with stable offtake in mass-market hair care.
- Hyperpigmentation Control:Positioned as hydroquinone alternative with regulatory tailwinds.
- Keratolytic Agents:Professional peel formulations command premium pricing in medical spa channels.
Prescription psoriasis applications command margin premiums; hyperpigmentation control is climbing the fastest.
End User:
Procurement sophistication varies from validated pharmaceutical supply chains to brand-marketing-driven cosmetic sourcing.
- Pharmaceutical Manufacturers:Require ICH Q7-compliant active pharmaceutical ingredient documentation, batch release certificates, and stability data per USP <905>. Indian CDSCO-registered facilities in Hyderabad and Ahmedabad are qualifying encapsulation toll processors for export to regulated markets.
- Cosmeceutical Companies:Prioritize cosmetic claim substantiation over pharmaceutical validation. Chinese domestic brands in Shanghai and Guangzhou are accelerating lipid-nanocapsule adoption for Tmall-premium positioning.
- Dermatology Clinics:Compounding pharmacies serving direct clinic procurement.
- Personal Care Brands:Mass-market volume buyers with price-sensitive formulation specifications.
Pharmaceutical manufacturers anchor quality standards; cosmeceutical companies are gaining share fastest.
Formulation Type:
Vehicle selection determines encapsulation compatibility, sensory attributes, and shelf-life stability.
- Serums:Water-light vehicles with minimal emulsifier content demand sub-micron encapsulation to prevent aggregation. Brazilian medical aesthetic chains in São Paulo are consolidating group purchasing organization procurement for professional-grade keratolytic serums.
- Creams:Oil-in-water emulsions accommodate broader microcapsule size distributions. Italian pharmacy brands leverage established manufacturing infrastructure for OTC acne therapies under EMA borderline product guidance.
- Lotions:Lower viscosity vehicles for body-care applications.
- Gels:Alcohol-based or hydroalcoholic systems with specific polymer compatibility requirements.
- Powders:Anhydrous formats for DIY mixing and travel-positioned products.
Creams retain volume leadership; serums show steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pharmaceutical manufacturers in the United States, Germany, China, South Korea, and Brazil concentrate procurement of encapsulated salicylic acid, with each market exhibiting distinct regulatory pathways and formulation preferences that shape supplier selection criteria.
United States
FDA's 21 CFR 333.310 monograph governs OTC acne therapies containing 0.5-2% salicylic acid, pushing brands toward encapsulated formats that reduce irritation claims and expand labeling flexibility. EPA reporting requirements for manufacturing emissions shape facility location decisions for domestic suppliers. New Jersey and Pennsylvania host the densest clusters of toll encapsulation processors serving pharmaceutical and cosmeceutical clients.
Germany
EMA's Medical Device Regulation extension to borderline cosmetic-pharmaceutical products forces encapsulation houses to maintain dual quality management systems. REACH substance evaluation protocols demand validated toxicological documentation for every batch release. Bavaria and Baden-Württemberg concentrate polymer-coating expertise for prescription-grade psoriasis therapies.
China
NMPA registration requirements for topical drug applications accelerate domestic capacity scaling in Jiangsu and Zhejiang provinces. Local producers are expanding lipid-based encapsulation lines to serve both pharmaceutical and premium skincare segments. Shanghai and Guangzhou anchor demand from Tmall-premium cosmeceutical brands seeking nanocapsule differentiation.
South Korea
MFDS oversight of functional cosmetics creates a regulatory pathway for encapsulated actives claiming specific skin benefits. Medical aesthetic clinics in Seoul and Busan drive serum formulation demand for minimal-irritation keratolytic treatments. Korean skincare brands adopt multilayer polymer-lipid hybrid shells at triple the pace of North American counterparts.
Brazil
ANVISA's pharmaceutical registration framework supports compounded topical prescriptions bypassing traditional distribution channels. Medical spa chains in São Paulo consolidate procurement through group purchasing organizations, demanding just-in-time inventory commitments. Vertically integrated aesthetic chains now represent the dominant volume channel for professional-grade keratolytic formulations.
Encapsulated Salicylic Acid Market Competitive Landscape
Channel-controlling players compete with product-specialist players across three discernible tiers. Thermo Fisher Scientific and BASF SE anchor the premium tier through integrated analytical and polymer-coating capabilities, while mid-scale toll processors compete on registration-package speed and regional proximity. Strategic moves concentrate on asset-light contract manufacturing arrangements and toll-processing partnerships that narrow capital barriers for emerging competitors.
Among science-driven conglomerates, Thermo Fisher Scientific and Merck KGaA occupy positions emphasizing analytical validation and custom formulation services for pharmaceutical clients. BASF SE and Seqens Group represent European supply anchors through polymer expertise and active-ingredient finishing capabilities respectively. Chinese specialists including Alta Laboratories and Siddharth Carbochem Products exemplify the cost-optimized manufacturing tier serving domestic and export markets with scaled salicylic acid production.
| Leading Market Players |
|---|
| Thermo Fisher Scientific |
| Merck KGaA |
| BASF SE |
| Seqens Group |
| Alta Laboratories |
| Siddharth Carbochem Products |
| Novocap SA |
| Hebei Jingye Medical Technology |
| Zhenjiang Gaopeng Pharmaceutical |
| Others |
Pricing and Supply Chain Analysis
German and Swiss machinery suppliers for fluidized bed coating systems and spray-dryer assemblies capture upstream margin pools, leaving downstream formulation houses to compete on registration-package speed and regional proximity rather than equipment ownership.
Pricing Analysis
Certification level (ICH Q7/FDA-grade versus cosmetic-grade) creates the primary spread between pharmaceutical and cosmeceutical procurement tiers. Three-tier pricing structure across premium, standard, and economy levels reflects batch validation depth, with toll processors commanding premiums for pre-submitted REACH dossiers. Cost compression in standard-grade microcapsules is intensifying because Chinese domestic producers are scaling lipid-based lines for Tmall-premium brands. Mass-market personal care manufacturers exhibit highest price sensitivity, while dermatology clinics purchasing through group purchasing organizations prioritize just-in-time reliability over unit cost.
Supply Chain Analysis
Tariff exposure between China and the United States dominates supply chain risk calculations for North American pharmaceutical clients sourcing lipid-nanocapsule intermediates. Manufacturing concentrates in China, Germany, and India, with Jiangsu and Zhejiang provinces anchoring lipid-based encapsulation capacity. Salicylic acid synthesis draws from petrochemical-derived phenol and sodium hydroxide feedstocks, exposing margin structures to energy price volatility. Distribution runs through toll-processing partnerships and asset-light contract manufacturing arrangements that narrow capital barriers for mid-tier competitors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Encapsulated salicylic acid sits in early-cycle expansion as medical aesthetic chains in Brazil and Mexico bypass traditional wholesale channels, creating direct procurement velocity that did not exist three years ago.
For Market Incumbents: Build regulatory affairs infrastructure as a moat against EMA's Medical Device Regulation extension to borderline cosmetic-pharmaceutical products. BASF SE and Seqens Group should deepen polymer-coating expertise in Bavaria and Baden-Württemberg to serve prescription-grade psoriasis therapies. Thermo Fisher Scientific can leverage analytical validation capabilities to capture high-margin custom encapsulation programs threatened by emerging Chinese toll processors. For New Entrants and Emerging Players: Build out toll-processing partnerships in Indonesia and Vietnam where domestic encapsulation capabilities remain absent. Southeast Asian personal care manufacturing represents the most penetrable geography, with regional contract manufacturers seeking import substitution for lipid-nanocapsule inputs. A direct-to-clinic distribution angle targeting Brazilian medical spa chains bypasses entrenched distributor relationships. For Investors and Strategic Acquirers: Secondary-cycle assets sit with private-equity-backed contract manufacturing organizations that consolidated during the last decade but now face redundant audit burdens from dual quality management systems. Long-term viability hinges on regulatory pre-certification program access and licensed platform technology for multilayer polymer-lipid hybrid shells. The signal to watch is ANSM post-market surveillance intensity in France and Italy, which determines compliance cost inflation and margin compression timelines for serum and ampoule categories.| Strategic Initiative | Industry Significance |
|---|---|
| Regulatory Pre-Certification Investment | EMA's MDR extension forces encapsulation houses to maintain dual quality management systems for market access. |
| Biodegradable Polymer Shell Development | Polylactic acid coating convergence with fermentation-derived salicylic acid enables carbon-neutral premium positioning. |
| Direct-to-Clinic Distribution Buildout | Vertically integrated aesthetic chains in São Paulo now represent the dominant volume channel for professional-grade keratolytic formulations. |
| Toll-Processing Partnership Expansion | Asset-light arrangements in Indonesia and Vietnam narrow capital barriers for mid-tier competitors seeking regional proximity. |
| Multilayer Hybrid Shell Licensing | Korean skincare brands adopt polymer-lipid structures at triple the pace of North American counterparts for overnight repair serums. |
Research Methodology
A standing panel of encapsulation technology directors, dermatology clinic procurement managers, pharmaceutical regulatory affairs leads, and cosmeceutical brand formulators provided ongoing calibration throughout the study period. Primary interviews combined with secondary validation from FDA 21 CFR filings, EMA MDR guidance documents, NMPA registration databases, and REACH substance evaluation protocols. Bottom-up capacity assessments across Jiangsu and Zhejiang provinces triangulated against top-down demand modeling from Tmall-premium skincare sales data.
Scenario-bracketing around regulatory timeline acceleration and feedstock price volatility shaped the analytical framework across the projection horizon. Segmentation dimensions modeled include delivery platform (microcapsule versus nanocapsule versus liposome), therapeutic application (acne versus psoriasis versus hyperpigmentation), end-user procurement sophistication (pharmaceutical versus cosmeceutical), and formulation vehicle (serum versus cream versus gel). CAGRs derived from installed capacity expansion announcements, toll-processor qualification timelines, and brand-owner reformulation cycle frequencies. Industry-specific inputs encompassed fluidized bed coating equipment lead times and REACH dossier preparation durations.
Stress conditions across phenol feedstock price bands, NMPA registration timeline delays, and ANSM post-market surveillance intensity were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions regarding lipid-nanocapsule penetration rates in medical aesthetic channels and polymer-coated microcapsule substitution in OTC acne therapies. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.