
 India Active Pharmaceutical Ingredients (API) Market | 2026-2036
India Active Pharmaceutical Ingredients (API) Market Size, Share, and Industry Trends Forecast 2026-2036
India Active Pharmaceutical Ingredients (API) Market Foresight
Contract manufacturing networks between domestic formulators and bulk drug producers is reshaping procurement patterns across India's pharmaceutical value chain. Sun Pharmaceutical Industries leverages backward integration into active ingredient production to secure cost advantages for its generic portfolio. Divis Laboratories sustains dominant positions in specialty API chemistry through dedicated manufacturing infrastructure. Dr. Reddy's Laboratories anchors export competitiveness by controlling critical intermediate supplies for regulated markets.
Active pharmaceutical ingredients constitute the biologically active components in drug formulations, typically synthesized through multi-step chemical processes involving fermentation, extraction, or recombinant DNA technology depending on molecular complexity. These compounds deliver therapeutic effects in finished dosage forms ranging from oral tablets to sterile injectables. Generic APIs command the largest production volumes as patent expirations continue expanding the addressable market for cost-competitive alternatives. Specialty APIs capture disproportionate margin pools due to complex synthesis requirements and limited qualified supplier bases. Contract Manufacturing APIs represent the fastest-expanding channel as global innovators outsource production to India's cost-optimized facilities.
CDSCO mandates stringent quality documentation for API registration while BIS standards govern manufacturing facility certifications, creating compliance barriers that favor established producers with dedicated regulatory affairs capabilities. The PLI scheme for bulk drugs directly subsidizes domestic fermentation and chemical synthesis capacity, redirecting procurement away from Chinese imports toward Indian manufacturing. Stakeholders must monitor evolving environmental clearances from MEE-aligned state pollution control boards as effluent discharge regulations tighten around solvent-intensive API production clusters.
Market Dynamics
CDSCO's tightened API quality guidelines and the PLI scheme's production-linked incentives are accelerating import substitution, redirecting procurement from Chinese suppliers toward Gujarat's chemical belt and Hyderabad's bulk drug cluster.
Growth Catalysts
- PLI Scheme Incentives:Production-linked subsidies for fermentation and chemical synthesis capacity are attracting greenfield investments into domestic bulk drug manufacturing.
- Oncology Procurement Surge:Domestic pharmaceutical companies are expanding bulk procurement of oncology APIs as cancer therapy portfolios multiply.
- Hyderabad Cluster Expansion:Concentrated technical talent and dedicated effluent treatment infrastructure are drawing specialty API producers to Telangana's bulk drug parks.
Market Restraints
- Chinese Import Dependency:Key Starting Materials and advanced intermediates for antibiotics and vitamins remain concentrated among Hubei and Zhejiang suppliers.
- Solvent Cost Volatility:Petrochemical-derived solvents constitute 25-35% of API production costs, exposing margins to crude oil price swings.
- Environmental Clearance Friction:MEE-aligned state pollution control boards are tightening effluent discharge norms around Vapi and Ankleshwar manufacturing zones.
Strategic Opportunities
- Biologics API Transition:Recombinant protein and monoclonal antibody manufacturing represents underdeveloped capacity as chronic disease portfolios expand.
- CDMO Channel Growth:Global innovators are outsourcing complex synthesis steps to Indian contract manufacturers with dedicated regulatory affairs capabilities.
- Penicillin G Revival:Fermentation-based antibiotic APIs are reshoring as PLI subsidies offset Chinese cost advantages in Punjab and Gujarat.
Industry Challenges
- Analytical Chemistry Talent Gap:ICH Q3D elemental impurity testing and nitrosamine risk assessment require specialized skill sets in short supply.
- US FDA Inspection Backlog:Pre-approval inspection delays are stretching ANDA filing timelines for export-oriented API producers.
- Multi-Product Facility Validation:Campaign-style manufacturing across different APIs complicates cleaning validation and cross-contamination risk management.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | India Active Pharmaceutical Ingredients (API) Market |
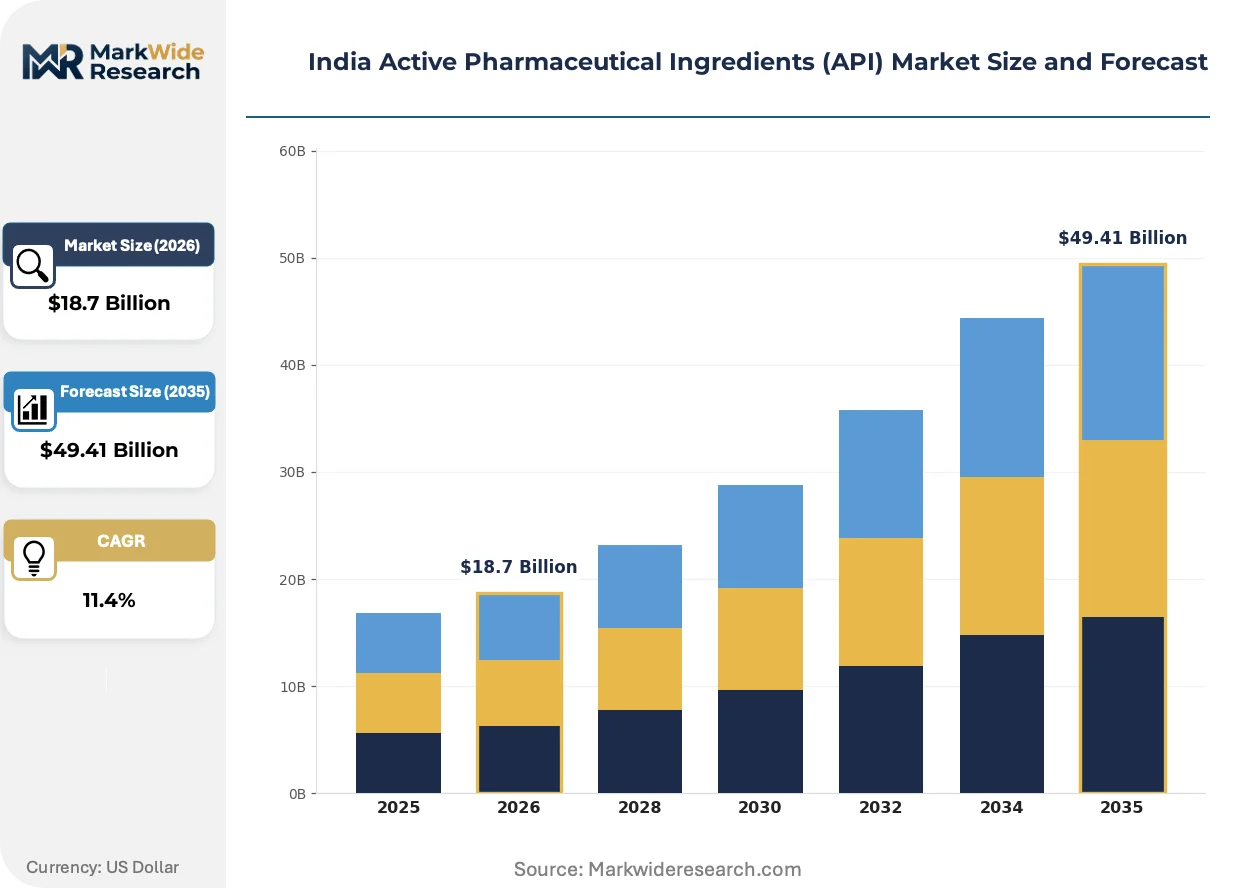
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $49.41 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Generic APIs, Specialty APIs, Biologics, Contract Manufacturing APIs End User: Pharmaceutical Companies, Contract Research Organizations, Academic Institutions, Biotechnology Firms Grading: Pharmaceutical Grade, Industrial Grade, Food Grade, Technical Grade Formulation Type: Oral Dosage Forms, Injectable Forms, Topical Forms, Inhalable Forms |
| Companies Covered | Sun Pharmaceutical Industries, Divis Laboratories, Aurobindo Pharma, Cadila Pharmaceuticals, Glenmark Pharmaceuticals, Dr. Reddy's Laboratories, Lupin, Torrent Pharmaceuticals, Cipla, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
India Active Pharmaceutical Ingredients (API) Market Shifts & Advancements
Continuous processing technologies and single-use bioreactor systems are displacing traditional batch fermentation, compressing cycle times and reducing solvent waste in API synthesis.
Continuous flow chemistry is migrating from pilot-scale demonstration to commercial manufacturing for high-volume generic APIs. Sun Pharmaceutical Industries and Divis Laboratories are retrofitting Hyderabad and Visakhapatnam facilities with modular microreactor systems. This technology is enabling 40-60% reduction in solvent volumes while improving yield consistency for nitration and hydrogenation steps.
CDSCO's revised Schedule M guidelines for Good Manufacturing Practices now mandate quality risk management documentation and computerized system validation for all API registrations. Domestic formulators are demanding enhanced supplier qualification protocols, forcing bulk drug producers to upgrade quality management systems. Small and mid-scale manufacturers in Indore and Baddi are consolidating to share regulatory affairs capabilities.
Long-term offtake agreements are replacing spot-market purchasing for critical oncology and diabetes APIs. Dr. Reddy's Laboratories and Cipla are negotiating three-to-five-year supply contracts with dedicated fermentation capacity, displacing transactional procurement through Mumbai trading houses. This shift concentrates volume with qualified suppliers possessing dedicated regulatory dossiers for regulated markets.
India Active Pharmaceutical Ingredients (API) Market Segmentation
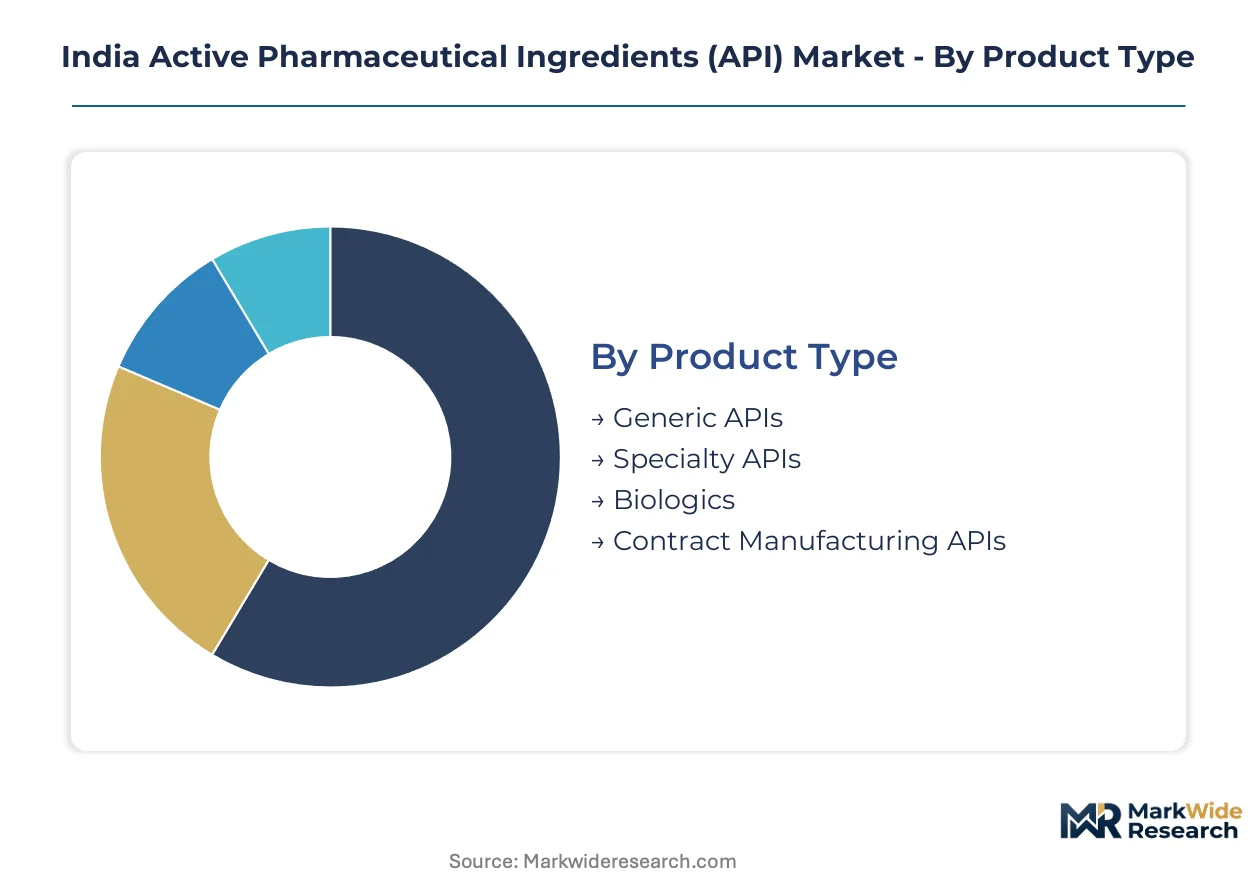
Segmentation in India's API market reveals distinct procurement rhythms and margin structures across molecular categories. Product type and end-user dimensions drive fundamentally different manufacturing investments and regulatory compliance requirements.
Product Type:
Generic APIs turn inventory fastest through high-volume fermentation campaigns, while biologics and specialty APIs operate on extended batch cycles with dedicated facility lock-in.
- Generic APIs:High-volume fermentation and chemical synthesis outputs serve cost-competitive oral solid dosage markets. Procurement concentrates among Mumbai-based formulators supplying domestic retail pharmacies and export markets, with CDSCO's tightened GMP documentation compressing supplier qualification timelines.
- Specialty APIs:Complex multi-step synthesis requiring dedicated hydrogenation and cryogenic infrastructure commands premium positioning. Demand clusters in Hyderabad's bulk drug parks where Divis Laboratories and similar operators control limited qualified supplier pools for regulated markets.
- Biologics:Recombinant protein and monoclonal antibody production demands single-use bioreactor systems and specialized cold chain logistics.
- Contract Manufacturing APIs:Toll manufacturing arrangements for global innovators leverage India's cost-optimized facilities with dedicated regulatory affairs capabilities.
Generic APIs anchor the volume base while contract manufacturing APIs gain share at the steepest rate.
End User:
Cost tier separation distinguishes research-scale procurement from commercial bulk purchasing, with pharmaceutical companies operating on fundamentally different margin expectations than academic buyers.
- Pharmaceutical Companies:Domestic formulators in Gujarat and Telangana drive bulk procurement of oncology and chronic disease APIs under long-term offtake agreements. PLI scheme subsidies are redirecting their sourcing from Chinese imports toward Punjab and Gujarat fermentation capacity.
- Biotechnology Firms:Emerging cell therapy and gene therapy developers require GMP-compliant biologics APIs with specialized analytical documentation. Procurement concentrates in Bangalore's biotech corridor where CDSCO's accelerated approval pathways support clinical trial material supply.
- Contract Research Organizations:Phase-appropriate API supply for clinical development programs demands flexible batch sizing and rapid regulatory response.
- Academic Institutions:Research-grade material procurement operates on limited budgets with minimal regulatory documentation requirements.
Pharmaceutical companies dominate absolute procurement value while biotechnology firms are expanding most quickly as chronic disease portfolios multiply.
Grading:
Application-driven purity specifications create four distinct compliance tiers, with pharmaceutical grade commanding dedicated facility validation and technical grade permitting multi-product campaign manufacturing.
- Pharmaceutical Grade:GMP-compliant APIs with complete ICH Q3D elemental impurity documentation and nitrosamine risk assessments. Manufacturing concentrates in Vapi and Ankleshwar zones where MEE-aligned state pollution control boards enforce stringent effluent discharge norms.
- Industrial Grade:Non-pharmaceutical chemical synthesis intermediates with reduced analytical burden serve agrochemical and dye intermediate markets.
- Food Grade:Nutraceutical and dietary supplement APIs require FSSAI compliance alongside basic pharmacopeial standards.
- Technical Grade:Bulk chemical precursors for further processing operate with minimal regulatory oversight and fastest batch release.
Pharmaceutical grade anchors compliance investment while industrial grade captures volume in solvent-intensive chemical synthesis.
Formulation Type:
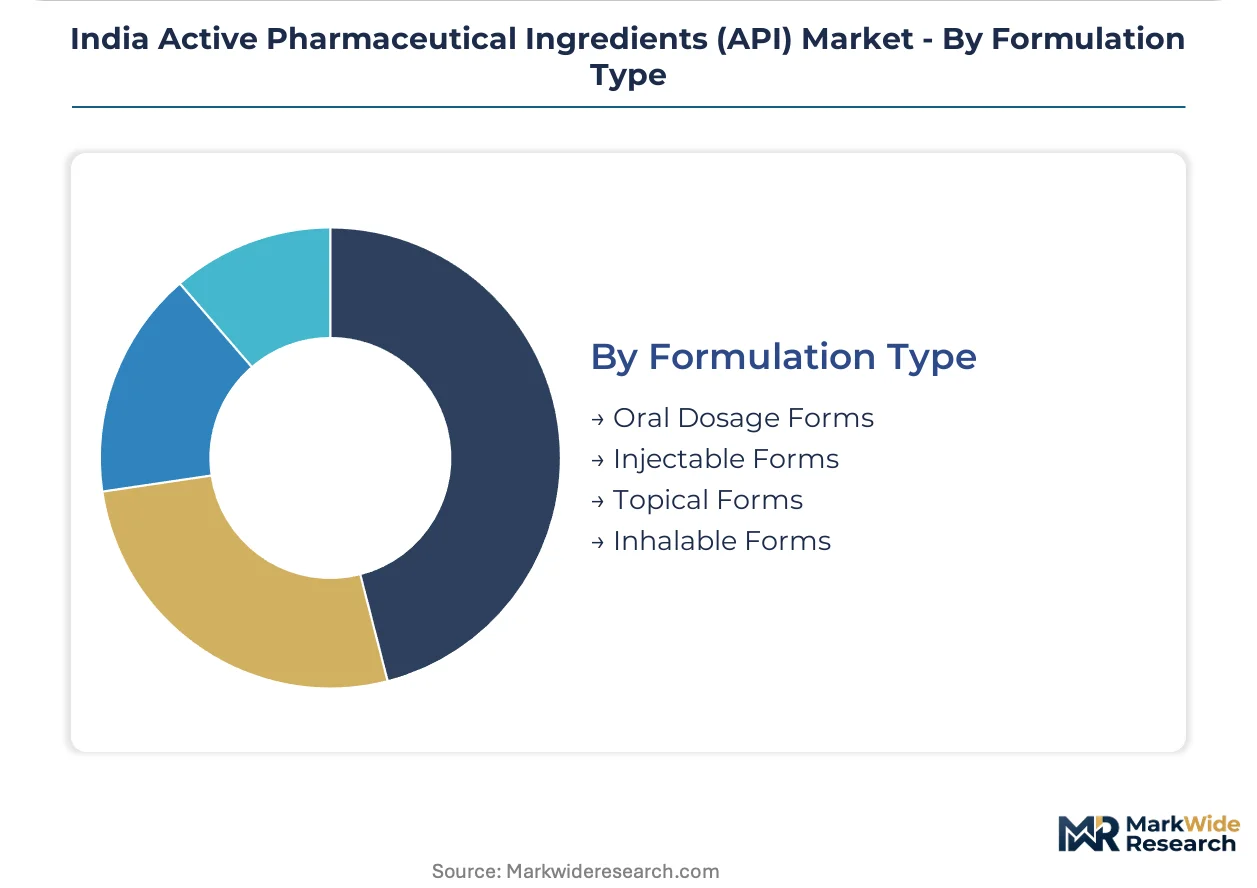
Supply concentration maps directly to India's manufacturing infrastructure, with oral dosage forms leveraging existing fermentation capacity and injectable forms requiring sterile facility investments concentrated in specific clusters.
- Oral Dosage Forms:Tablet and capsule APIs constitute the largest production volumes, with generic statins and diabetes medications driving procurement from Gujarat's chemical belt. Sun Pharmaceutical Industries and Dr. Reddy's Laboratories anchor backward integration into captive API supply.
- Injectable Forms:Sterile API manufacturing with endotoxin and particulate control demands dedicated fill-finish infrastructure. Production concentrates in Hyderabad and Visakhapatnam where specialized facilities serve regulated export markets.
- Topical Forms:Cream and ointment APIs require specialized particle size control and dermatological safety testing.
- Inhalable Forms:Pulmonary delivery APIs with precise particle engineering for dry powder and metered-dose applications represent emerging capacity requirements.
Oral dosage forms anchor the volume base while injectable forms command the steepest expansion trajectory as biologics portfolios multiply.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Gujarat commands premium pricing power over Maharashtra due to concentrated chemical infrastructure, while Telangana's bulk drug parks erode Karnataka's historical biologics advantage through dedicated effluent treatment investments.
Gujarat
Ankleshwar and Vapi industrial zones anchor fermentation-based antibiotic production under CDSCO's tightened GMP documentation. The state's MEE-aligned pollution control board enforces stringent effluent norms that favor capital-intensive producers with dedicated treatment infrastructure. Dahej and Vadodara clusters attract PLI scheme investments for penicillin G revival projects.
Telangana
Hyderabad's Genome Valley and Pashamylaram bulk drug parks concentrate oncology API synthesis for regulated export markets. CDSCO's accelerated approval pathways support clinical trial material supply to biotechnology firms expanding chronic disease portfolios. The Telangana State Industrial Infrastructure Corporation channels dedicated technical talent into fermentation and chemical synthesis operations.
Maharashtra
Mumbai trading houses historically dominated spot-market API procurement, though long-term offtake agreements now displace transactional purchasing. BIS facility certification requirements compress supplier qualification timelines for domestic formulators. Tarapur and Mahad chemical zones face margin pressure from solvent cost volatility tied to petrochemical feedstock fluctuations.
Karnataka
Bangalore's biotech corridor specializes in recombinant protein and monoclonal antibody manufacturing for emerging cell therapy developers. FSSAI compliance overlays basic pharmacopeial standards for nutraceutical API production in Peenya industrial estate. The state's pollution control board applies graduated enforcement that permits campaign-style manufacturing across multiple biologics.
Andhra Pradesh
Visakhapatnam's pharmaceutical zone hosts sterile API manufacturing with endotoxin control for injectable dosage forms. The state's industrial promotion policy targets backward integration into captive intermediate supply for export-oriented formulators. Vizag and Srikakulam clusters leverage port connectivity for time-sensitive biologics cold chain logistics.
India Active Pharmaceutical Ingredients (API) Market Competitive Landscape
Integrated formulators and dedicated bulk drug producers split the market between captive supply security and merchant sales flexibility. The vendor base concentrates around three strategic archetypes: backward-integrated pharmaceutical conglomerates controlling critical intermediate supplies, standalone API specialists with dedicated hydrogenation infrastructure, and toll manufacturers serving global innovators through contract research arrangements. Dominant competitive moves include fermentation capacity expansion under PLI scheme subsidies and long-term offtake agreements replacing spot-market purchasing.
Within the integrated formulator tier, Sun Pharmaceutical Industries and Dr. Reddy's Laboratories exemplify backward integration strategies that secure cost advantages for generic portfolios. Divis Laboratories occupies a specialist position in complex multi-step synthesis for regulated markets. These three entities anchor competitive dynamics across Gujarat's chemical belt and Hyderabad's bulk drug cluster.
| Leading Market Players |
|---|
| Sun Pharmaceutical Industries |
| Divis Laboratories |
| Aurobindo Pharma |
| Cadila Pharmaceuticals |
| Glenmark Pharmaceuticals |
| Dr. Reddy's Laboratories |
| Lupin |
| Torrent Pharmaceuticals |
| Cipla |
| Others |
Supply & Pricing Matrix
Chinese import dependency for Key Starting Materials determines both the premium spread between captive and merchant API supply and the geographic concentration of India's fermentation capacity investments. CDSCO's tightened GMP documentation and PLI scheme subsidies are compressing spot-market pricing while elevating long-term contract premiums for qualified suppliers.
Pricing Analysis
Configured-to-order pricing for specialty APIs with dedicated hydrogenation infrastructure commands substantial premiums over standard fermentation-based generic outputs. Three-tier pricing structure across pharmaceutical grade, industrial grade, and technical grade levels separates CDSCO-registered suppliers from non-compliant merchant producers. Pricing pressure stems from solvent cost volatility tied to petrochemical feedstock fluctuations, particularly affecting Vapi and Ankleshwar manufacturing zones. Domestic formulators in Gujarat and Telangana exhibit highest price sensitivity for high-volume antibiotic APIs, while biotechnology firms in Bangalore tolerate premium positioning for GMP-compliant biologics.
Supply Chain Analysis
Contract manufacturing concentration among Divis Laboratories, Sun Pharmaceutical Industries, and Dr. Reddy's Laboratories controls specialty API capacity for regulated export markets. Raw material dependencies on Hubei and Zhejiang suppliers for advanced intermediates, Punjab fermentation units for penicillin G precursors, and Gujarat chemical processors for solvent recovery create multi-node vulnerability. Single-source vulnerability concentrates in oncology API starting materials where qualified supplier pools remain limited. Distribution runs through long-term offtake agreements directly linking bulk drug parks to domestic formulators, displacing Mumbai trading house intermediation.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Consolidation among domestic pharmaceutical formulators into four-to-five integrated conglomerates is shifting procurement leverage toward buyers with dedicated fermentation capacity requirements.
For Market Incumbents: Build regulatory dossier moats through CDSCO Schedule M compliance investments and dedicated ICH Q3D elemental impurity testing infrastructure. Anchor backward integration into captive intermediate supply for oncology and diabetes APIs to offset Chinese import substitution pressure. Expand hydrogenation and cryogenic capacity in Hyderabad's bulk drug parks to defend margin position against emerging toll manufacturers. For New Entrants and Emerging Players: Biologics API manufacturing in Bangalore's biotech corridor offers white-space penetration with limited incumbent lock-in. Target recombinant protein and monoclonal antibody production where CDSCO's accelerated approval pathways reduce time-to-market barriers. Pursue toll manufacturing arrangements with global innovators seeking cost-optimized facilities with dedicated regulatory affairs capabilities. For Investors and Strategic Acquirers: Standalone API specialists with dedicated fermentation infrastructure and established US FDA inspection histories represent priority acquisition archetypes. Long-term viability hinges on PLI scheme subsidy capture and environmental clearance navigation across MEE-aligned state pollution control boards. Watch CDSCO pre-approval inspection backlog resolution as inflection signal for export-oriented capacity valuation.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Captive Intermediate Supply | Dr. Reddy's Laboratories and Sun Pharmaceutical Industries secure cost advantages for generic portfolios through controlled critical input sourcing. |
| Continuous Flow Chemistry Retrofit | Divis Laboratories and Hyderabad-based operators achieve 40-60% solvent volume reduction through modular microreactor system deployment. |
| Long-term Offtake Agreement Negotiation | Cipla and domestic formulators displace Mumbai trading house procurement through three-to-five-year supply contracts with dedicated fermentation capacity. |
| CDSCO Schedule M Compliance Investment | Small and mid-scale manufacturers in Indore and Baddi consolidate to share regulatory affairs capabilities under tightened GMP documentation mandates. |
| Biologics API Capacity Buildout | Bangalore biotech corridor developers leverage single-use bioreactor systems for emerging cell therapy and gene therapy clinical trial material supply. |
Research Methodology
Desk research of CDSCO registration filings, PLI scheme beneficiary disclosures, and state pollution control board clearance records preceded structured interviews with regulatory affairs directors at bulk drug manufacturers, procurement leads at domestic formulators, and technical talent specialists in Hyderabad's bulk drug parks. Secondary validation drew from BIS facility certification databases, MEE-aligned environmental compliance reports, and customs import data for Key Starting Materials. Bottom-up capacity assessments across Gujarat's chemical belt and Telangana's bulk drug parks were triangulated against top-down pharmaceutical production value estimates.
Assumptions held fixed include PLI scheme subsidy continuity, CDSCO's current GMP documentation stringency, and existing environmental clearance timelines across Vapi and Ankleshwar zones. Variables tested across the analysis window encompass Chinese import substitution velocity, solvent cost volatility sensitivity, and biotechnology firm penetration into biologics API demand. Segmentation dimensions modeled include product type, end user archetype, grading tier, and formulation type. CAGRs were derived from volume trajectory analysis weighted by regulatory compliance tier and facility certification status.
The forecast holds incumbent behavior within observed patterns; aggressive capacity expansion by Punjab and Gujarat fermentation operators or sudden CDSCO documentation requirement shifts would shift outcomes. Quarterly review of CDSCO pre-approval inspection clearance rates, MEE-aligned state pollution control board enforcement intensity, and PLI scheme disbursement velocity is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pharmaceutical Ingredients
Topical Drugs Market
Pharmaceutical Ingredients
Global Granisetron Market
Pharmaceutical Ingredients
Diclofenac Sodium API Market
Pharmaceutical Ingredients
Global Tacrolimus Market
Pharmaceutical Ingredients
Europe Active Pharmaceutical Ingredients (API) Market
Pharmaceutical Ingredients
Cyclooxygenase 2 Inhibitor Market
Pharmaceutical Ingredients
Fosfomycin Trometamol Powder Market
Pharmaceutical Ingredients
Oxycodone Drugs Market
Pharmaceutical Ingredients
Quinoline Market
Pharmaceutical Ingredients
North America Active Pharmaceutical Ingredients Market
Pharmaceutical Ingredients
Cox 2 Inhibitors Market
Pharmaceutical Ingredients
Pharma Grade Synthetic Camphor Market
Pharmaceutical Ingredients
Global Dexamethasone Market
Pharmaceutical Ingredients
Synthetic Lethality-Based Drugs and Targets Market
Pharmaceutical Ingredients
Cetrorelix Acetate API Market
Pharmaceutical Ingredients
Pharmaceutical Grade Magnesium Hydroxide Market