
 Pharmaceutical Grade Hyaluronic Acid Market | 2026-2036
Pharmaceutical Grade Hyaluronic Acid Market Size, Share, and Industry Trends Forecast 2026-2036
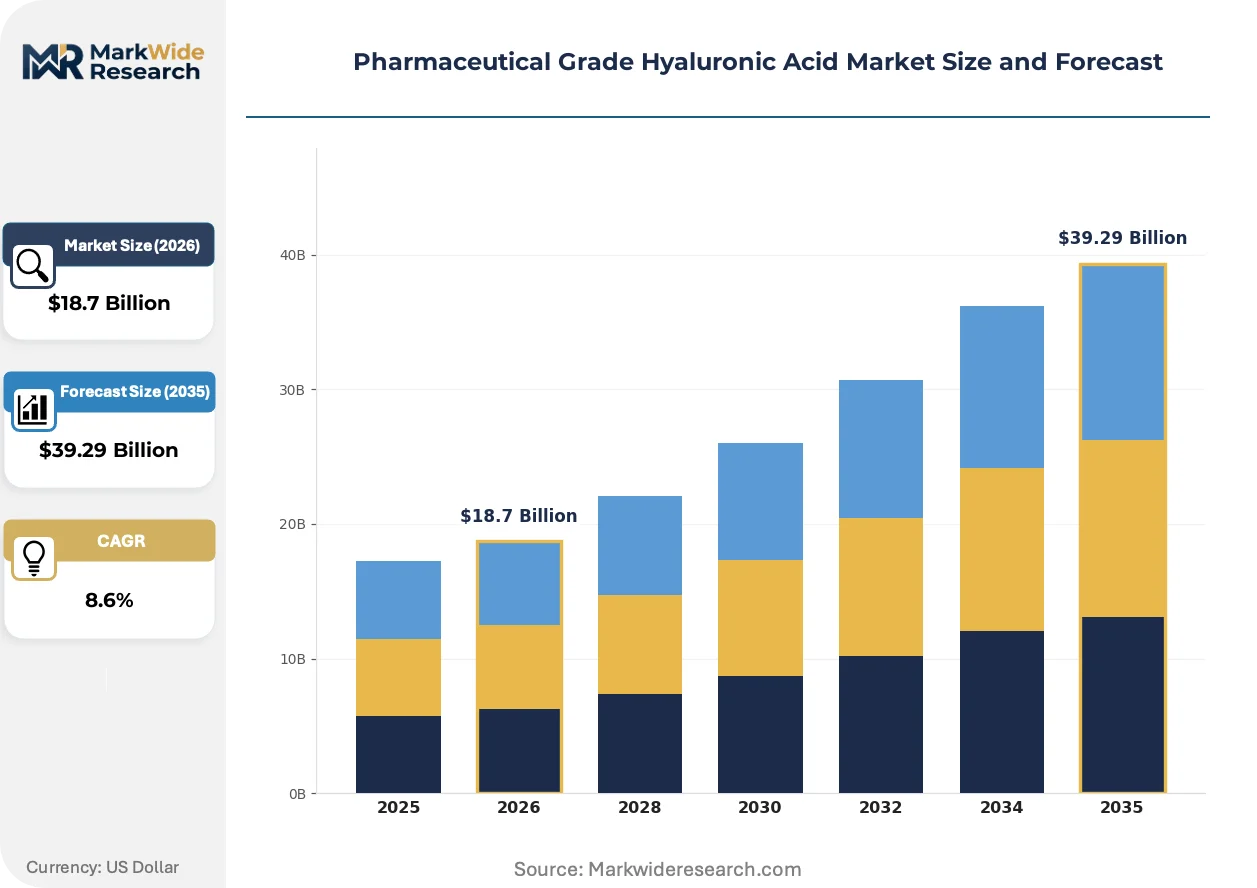
Pharmaceutical Grade Hyaluronic Acid Market Outlook
China is narrowing its historical supply deficit through aggressive fermentation capacity expansion. Bloomage Biotechnology leverages vertical integration from microbial fermentation to finished active pharmaceutical ingredient, sustaining cost advantages across the value chain. Seikagaku anchors high-purity ophthalmology-grade supply through proprietary Streptococcus zooepidemicus strains. HTL Biotechnology specializes in pharmaceutical-grade extraction from rooster comb, occupying a defensible niche in European markets.
Pharmaceutical grade hyaluronic acid denotes sodium hyaluronate meeting injectable purity thresholds, typically exceeding 95% purity with endotoxin levels below 0.5 EU/mg and molecular weight ranges from 50 kDa to 3 MDa depending on therapeutic indication. Manufacturers employ either microbial fermentation or animal tissue extraction, with fermentation routes dominating ophthalmic viscoelastic and intra-articular injection applications due to superior batch consistency. The injectable product type commands premium positioning owing to sterility validation burdens and clinical trial requirements, while dermal fillers concentrate margin pools through direct-to-practitioner channel control. Orthopedics applications are accelerating fastest as viscosupplementation protocols expand beyond knee osteoarthritis into hip and shoulder joints.
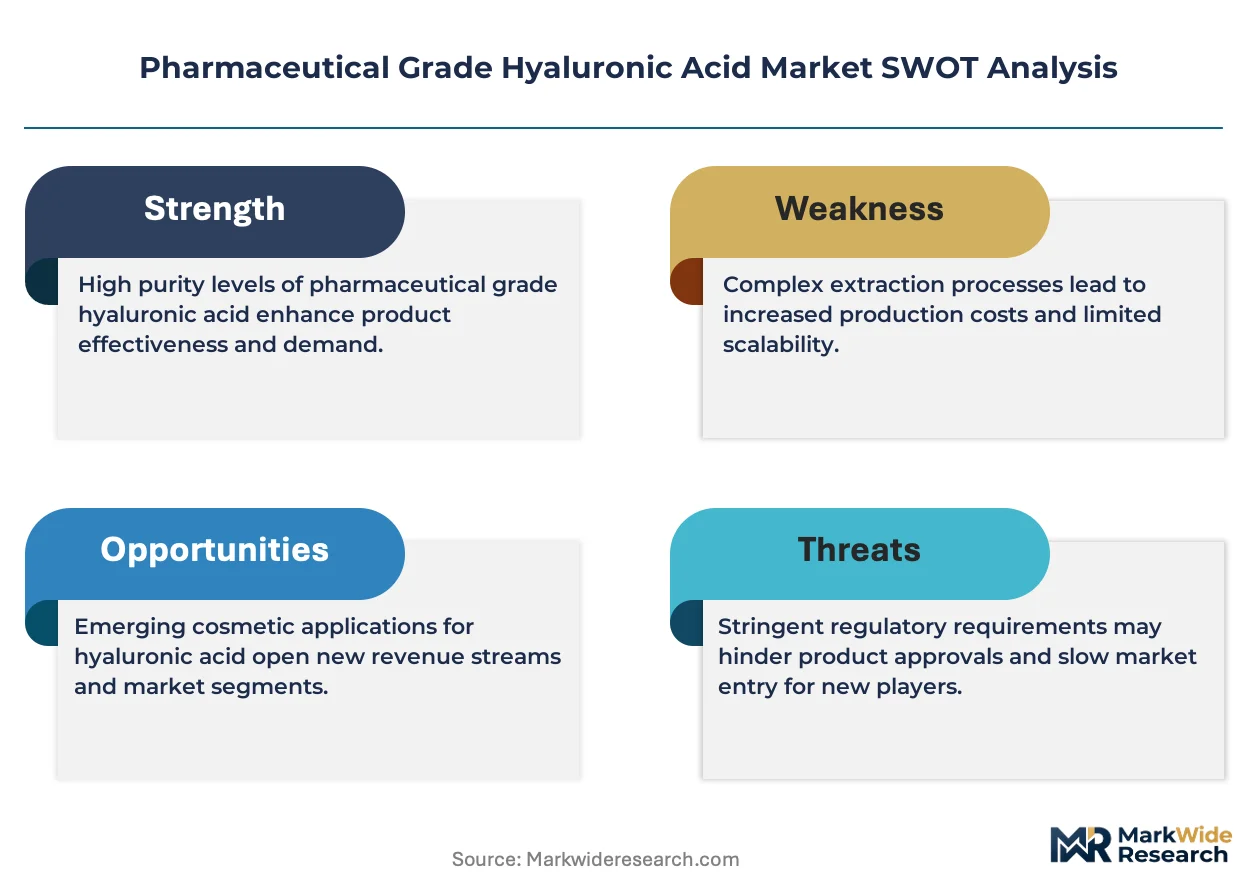
The FDA enforces Current Good Manufacturing Practice for active pharmaceutical ingredients through its Center for Drug Evaluation and Research, while the EMA's Committee for Medicinal Products for Human Use mandates European Pharmacopoeia monograph compliance for sodium hyaluronate destined for intra-articular or intraocular use. China's NMPA has tightened registration requirements for imported hyaluronic acid raw materials, forcing multinationals to establish local testing partnerships or dedicated Chinese pharmacopoeia certification programs. Stakeholders must monitor evolving endotoxin testing methodologies and shifting pharmacopoeial harmonization timelines between USP, EP, and ChP standards to preempt supply disruptions.
Market Dynamics
Fermentation technology maturation in China and South Korea is compressing historical supply deficits while FDA purity mandates for injectable biologics force manufacturing upgrades across incumbent suppliers.
Growth Catalysts
- EMA MDR Compliance:European Medicines Agency Medical Device Regulation harmonization is accelerating pharmaceutical-grade certification adoption among dermal filler manufacturers seeking unified market access.
- Viscosupplementation Protocol Expansion:Orthopedic applications beyond knee osteoarthritis into hip and shoulder joints are widening addressable patient populations for intra-articular sodium hyaluronate injections.
- Ophthalmic Viscoelastic Demand:Cataract surgery volume concentration in aging demographics across Japan, Germany, and the United States sustains high-purity hyaluronic acid consumption for anterior segment procedures.
Market Restraints
- Rooster Comb Raw Material Volatility:Animal tissue extraction routes face input cost instability from avian supply chain disruptions and European animal welfare regulatory tightening.
- Fermentation Capacity Concentration:Microbial production infrastructure clusters disproportionately in Shandong and Jiangsu provinces, creating geographic supply vulnerability to regional energy or environmental policy shifts.
- Endotoxin Testing Standard Divergence:USP, EP, and ChP pharmacopoeial harmonization delays force manufacturers to maintain parallel validation protocols, elevating quality assurance overhead.
Strategic Opportunities
- Indian Domestic Biotech Cluster Formation:CDSCO regulatory pathway streamlining and PLI scheme incentives are attracting fermentation capacity investment for export-oriented pharmaceutical-grade production.
- Crosslinked Gel Formulation Innovation:Advanced chemical modification technologies enabling extended residence time dermal fillers are opening premium positioning above standard sodium hyaluronate injections.
- Direct-to-Clinic Distribution Models:Aesthetic medicine practitioners in Brazil and Mexico are bypassing traditional distributor tiers through manufacturer-negotiated volume contracts, capturing margin pool redistribution.
Industry Challenges
- Streptococcus zooepidemicus Strain Stewardship:Proprietary microbial genetics management demands specialized fermentation biology expertise scarce outside established Japanese and Chinese production centers.
- Multi-Pharmacopoeia Certification Timelines:Simultaneous USP, EP, and ChP compliance documentation extends raw material qualification cycles, compressing working capital efficiency for contract manufacturers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Pharmaceutical Grade Hyaluronic Acid Market |
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $39.29 Billion |
| CAGR (2026 – 2036) | 8.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Injectable, Topical, Eye Drops, Dermal Fillers Application: Ophthalmology, Dermatology, Orthopedics, Aesthetics End User: Hospitals, Clinics, Research Laboratories, Homecare Distribution Channel: Online, Offline, Pharmacies, Wholesalers |
| Companies Covered | Seikagaku, Fidia Farmaceutici, Bloomage Biotechnology, LG Chem, Anika Therapeutics, Merck KGaA, Kewpie Corporation, HTL Biotechnology, Contipro, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Pharmaceutical Grade Hyaluronic Acid Market Strategic Shifts
Manufacturing process convergence and regulatory harmonization pressures are restructuring competitive differentiation from purity attainment toward molecular weight precision and application-specific functionalization.
Continuous fermentation systems paired with real-time analytical process control are hybridizing batch manufacturing economics with pharmaceutical-grade consistency requirements. Mid-scale producers in South Korea and Italy are adopting these hybrid configurations to bridge the gap between laboratory-scale optimization and commercial-volume GMP compliance. The technology is hybridizing capital intensity structures, enabling modular capacity expansion without the full-scale facility investments historically required for endotoxin-controlled environments.
China's NMPA has tightened registration requirements for imported hyaluronic acid raw materials, forcing multinationals to establish local testing partnerships or dedicated Chinese pharmacopoeia certification programs. This regulatory friction is accelerating joint venture formation between European API suppliers and domestic Chinese testing laboratories. Ophthalmic viscoelastic applications face the steepest compliance burden given intraocular sterility thresholds, prompting some manufacturers to segregate China-dedicated production lines.
Practitioner procurement in aesthetic medicine is consolidating through group purchasing organizations and multi-clinic chains, displacing fragmented individual practice ordering patterns. Dermal filler distributors in the United States and United Kingdom are responding with tiered volume pricing and consignment inventory arrangements. Brazil's consolidated dermatology clinic networks exhibit the most pronounced procurement concentration, with top ten chains commanding substantial manufacturer attention in contract negotiations.
Pharmaceutical Grade Hyaluronic Acid Market Segmentation
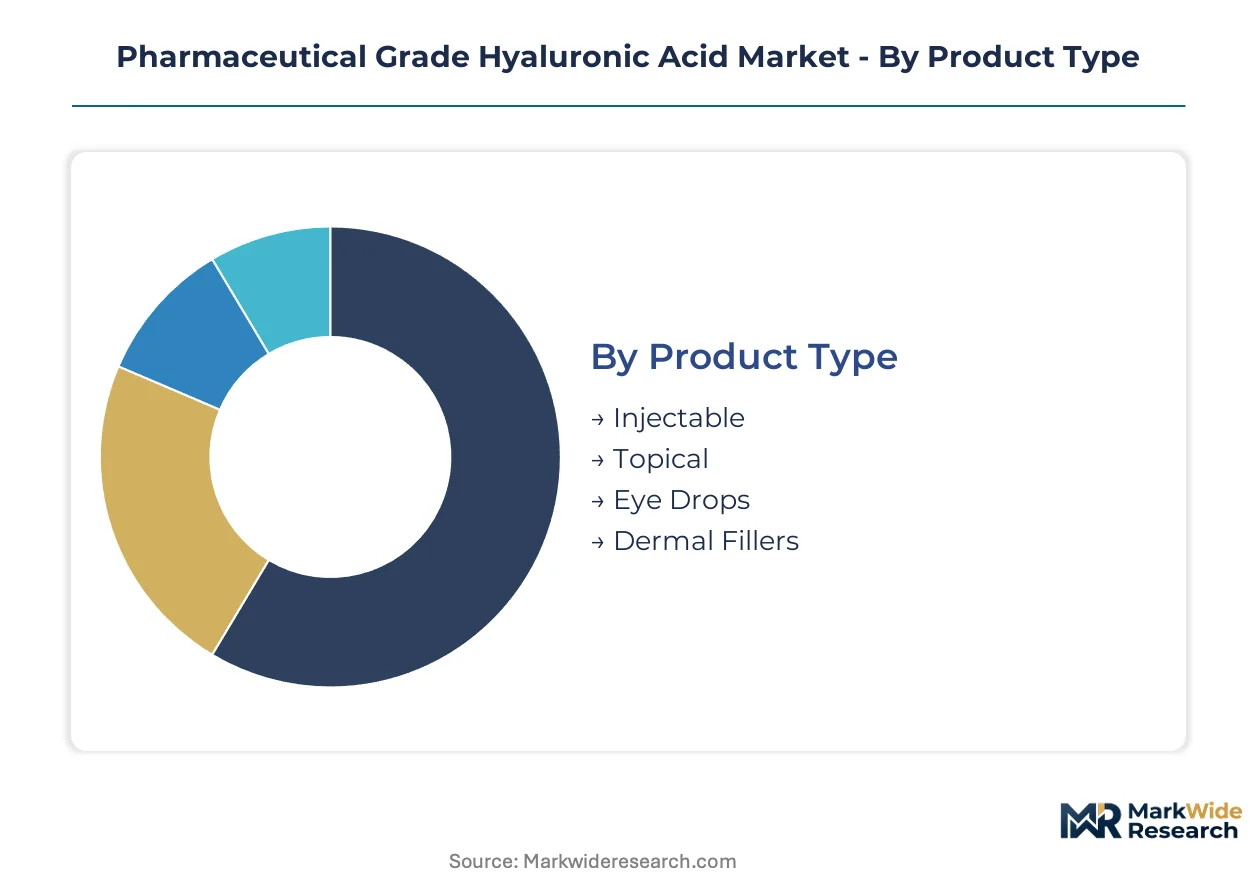
Pharmaceutical grade hyaluronic acid markets segment across therapeutic delivery routes, clinical specialties, and procurement channels. Each dimension carries distinct regulatory burdens, purity thresholds, and margin structures that reshape competitive positioning.
Product Type:
The use-case spectrum spans sterile injectables demanding endotoxin-controlled manufacturing through consumer-facing topical formulations with relaxed purity requirements.
- Injectable:Sodium hyaluronate solutions meeting USP sterility and endotoxin specifications below 0.5 EU/mg. Demand concentrates in intra-articular osteoarthritis protocols across German and Japanese hospital systems, where reimbursement codes favor pharmacy-compounded over pre-filled presentations.
- Dermal Fillers:Crosslinked hyaluronic acid gels with tunable rheological properties for subdermal implantation. Aesthetic medicine practitioners in Brazil and Mexico drive volume through direct manufacturer contracting, bypassing traditional distributor markups.
- Topical:Lower molecular weight fractions for wound healing and dermatological carriers. European wound care formulators in Milan and Barcelona source pharmaceutical-grade material despite cosmetic-grade sufficiency.
- Eye Drops:Preservative-free ophthalmic solutions requiring iso-osmotic formulation. Japanese dry eye specialists specify ultra-pure sodium hyaluronate from Streptococcus zooepidemicus fermentation routes.
The dominant share belongs to Injectable, while Dermal Fillers is closing the gap fastest.
Application:
Clinical adoption intensity varies by specialty reimbursement economics and procedure volume trajectories.
- Ophthalmology:Viscoelastic devices for cataract surgery and anterior segment procedures. Aging demographics in Japan, Germany, and the United States sustain consumption despite phacoemulsification technique refinements reducing per-procedure volume.
- Orthopedics:Intra-articular injections for viscosupplementation in knee, hip, and shoulder osteoarthritis. US orthopedic groups are expanding hip and shoulder protocols beyond traditional knee indications, widening addressable patient populations.
- Dermatology:Medical-grade topical and injectable applications for wound healing and scar revision. Hospital outpatient departments in France and Italy specify pharmaceutical-grade material for reimbursable procedures.
- Aesthetics:Cosmetic dermal fillers and skin boosters operating outside reimbursement frameworks. Direct-to-clinic procurement consolidation in Brazil and UK clinic chains is compressing distributor margins.
Ophthalmology commands the largest installed base, though Orthopedics shows the steepest expansion trajectory as joint indication protocols multiply.
End User:
Procurement authority concentrates differently across institutional, clinical, and consumer access points.
- Hospitals:Centralized pharmacy and surgical supply chains with group purchasing organization leverage. US health systems negotiate multi-year sodium hyaluronate contracts covering ophthalmic, orthopedic, and wound care applications.
- Clinics:Independent dermatology, ophthalmology, and orthopedic practices with fragmented purchasing. Aesthetic medicine consolidation into multi-clinic chains in Brazil and Mexico is shifting negotiation power toward volume-based manufacturer relationships.
- Research Laboratories:Preclinical and clinical trial material sourcing with exacting documentation requirements. Contract research organizations in South Korea and Singapore specify pharmaceutical-grade for regulatory submission packages.
- Homecare:Patient-administered eye drops and topical preparations with pharmacy dispensing. European homecare nursing services are expanding viscosupplementation administration outside hospital settings where regulations permit.
Hospitals retain volume leadership, while Clinics are gaining procurement sophistication fastest through consolidation.
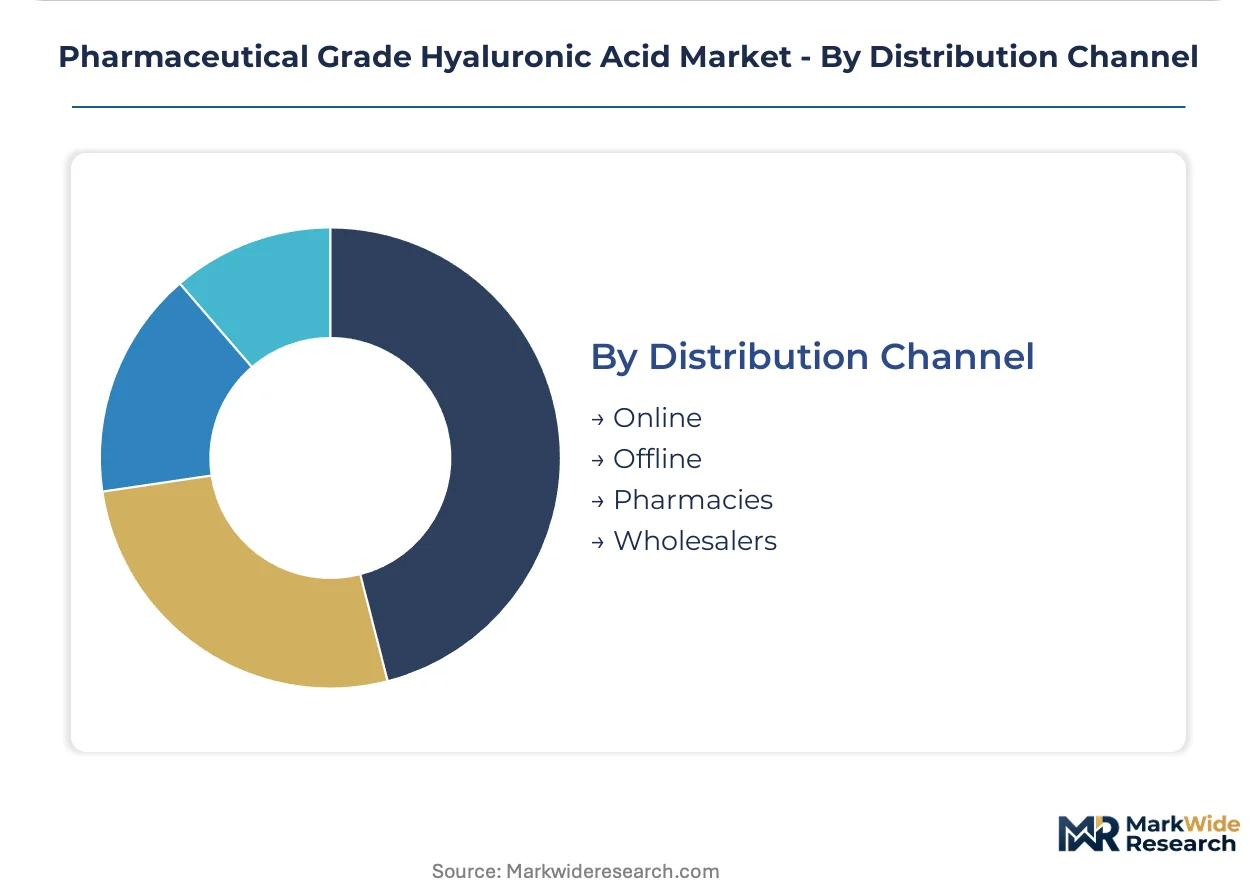
Distribution Channel:
Channel economics reflect regulatory custody requirements and customer access preferences.
- Offline:Traditional medical-surgical distributors with cold chain and documentation capabilities. German and Japanese hospital supply chains maintain dominant share through established GMP logistics relationships.
- Pharmacies:Community and hospital pharmacy dispensing for reimbursable prescriptions. French and Italian pharmacy networks control patient access to intra-articular and ophthalmic preparations.
- Wholesalers:Regional pharmaceutical distributors handling bulk API and finished formulation. Chinese domestic wholesalers are expanding pharmaceutical-grade hyaluronic acid portfolios as local fermentation capacity matures.
- Online:Direct manufacturer portals and B2B procurement platforms. Aesthetic medicine practitioners in Brazil and Mexico increasingly source dermal fillers through manufacturer-negotiated digital contracts.
Offline channels dominate transaction value, while Online is penetrating fastest in aesthetic medicine segments with lighter regulatory custody requirements.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Port of Rotterdam's cold-chain pharmaceutical terminals anchor European sodium hyaluronate distribution, while Shanghai Yangshan Deep Water Port handles the bulk of intra-Asian API transshipment for fermentation-derived material.
United States
Cataract surgery volume in Florida and Arizona retirement corridors sustains ophthalmic viscoelastic consumption. The FDA's Center for Drug Evaluation and Research enforces Current Good Manufacturing Practice for all injectable biologics, tightening endotoxin documentation burdens. Boston's Route 128 biotech corridor hosts contract manufacturers qualifying pharmaceutical-grade material for clinical trial supply.
Germany
Hospital pharmacy compounding of intra-articular sodium hyaluronate dominates viscosupplementation protocols in Bavarian orthopedic networks. The EMA's Medical Device Regulation harmonization accelerates pharmaceutical-grade certification for dermal filler manufacturers seeking unified European market access. Mannheim and Heidelberg anchor Rhine-Neckar pharmaceutical logistics clusters handling finished formulation distribution.
China
Domestic fermentation capacity expansion in Shandong and Jiangsu provinces narrows historical supply deficits for ophthalmic and orthopedic applications. The NMPA's tightened registration requirements for imported raw materials force multinationals to establish local testing partnerships or dedicated Chinese pharmacopoeia certification programs. Qingdao's biotech industrial park concentrates Streptococcus zooepidemicus strain development facilities.
Japan
Aging demographics concentrate cataract procedure volume in Tokyo and Osaka metropolitan areas, sustaining high-purity hyaluronic acid demand for anterior segment surgery. The PMDA maintains stringent sterility thresholds for intraocular devices, privileging established fermentation routes with documented batch consistency. Tsukuba's biomedical research cluster anchors preclinical material sourcing for regenerative medicine applications.
Brazil
Consolidated dermatology clinic networks in São Paulo and Rio de Janeiro command substantial manufacturer attention in dermal filler contract negotiations. ANVISA's pharmaceutical-grade import licensing creates documentation hurdles for raw material suppliers lacking local registration partnerships. The São Paulo state health secretariat's procurement centralization is displacing fragmented individual practice ordering patterns.
Pharmaceutical Grade Hyaluronic Acid Market Competitive Environment
Platform integrators command the system tier; component specialists sit upstream in the value chain. The market structures around a consolidated fermentation technology tier and a fragmented downstream formulation segment. Three archetypes dominate: vertically integrated biotech conglomerates with captive strain libraries, specialized API suppliers with pharmacopoeia certification depth, and regional distributors with cold-chain logistics lock-in. Capacity expansion and strategic partnerships represent the dominant competitive moves, with fermentation infrastructure investments clustering in East Asian biotech corridors.
Within the fermentation-technology tier, Seikagaku and Bloomage Biotechnology exemplify divergent geographic anchoring strategies. Seikagaku occupies a position within Japanese precision-fermentation specialists leveraging proprietary microbial genetics. Bloomage Biotechnology represents Chinese vertical integration from microbial fermentation through finished active pharmaceutical ingredient production. HTL Biotechnology anchors European animal-extraction routes, occupying a defensible niche in markets prioritizing rooster-comb sourcing credentials.
| Leading Market Players |
|---|
| Seikagaku |
| Fidia Farmaceutici |
| Bloomage Biotechnology |
| LG Chem |
| Anika Therapeutics |
| Merck KGaA |
| Kewpie Corporation |
| HTL Biotechnology |
| Contipro |
| Others |
Value Chain & Pricing Dynamics
Fermentation capacity clustering in Shandong and Jiangsu provinces concentrates upstream supply control, directing margin pools toward endotoxin-certified finished formulations and direct-to-clinic dermal filler channels.
Pricing Analysis
Current Good Manufacturing Practice enforcement through the FDA's Center for Drug Evaluation and Research dictates the pricing tier structure across injectable-grade sodium hyaluronate. Three-tier pricing structure across premium, standard, and economy levels separates ophthalmic viscoelastic applications from intra-articular injections and topical formulations. Price differentiation hinges on endotoxin certification depth and molecular weight precision. Cost compression in standard-grade material is intensifying because Chinese fermentation capacity expansion erodes historical scarcity premiums. Hospital procurement groups exhibit highest price sensitivity through multi-year contract leverage, while aesthetic clinic chains in Brazil accept premium positioning for crosslinked gel exclusivity.
Supply Chain Analysis
Export-control scrutiny on microbial strain genetics and fermentation bioreactor technology limits technology transfer from established Japanese and Chinese production centers. Raw material flows draw from Streptococcus zooepidemicus culture banks, pharmaceutical-grade glucose feedstocks, and rooster comb tissue for extraction routes. Supply chain risk centers on single-source vulnerability for proprietary microbial genetics held by Seikagaku and select Chinese strain libraries. Distribution runs through cold-chain pharmaceutical terminals at Rotterdam and Shanghai Yangshan, with finished formulation logistics anchored in Mannheim and Boston biotech corridors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Pharmaceutical-grade hyaluronic acid markets reward service-attach revenue streams, with compounding pharmacy partnerships and clinic staff training programs expanding faster than commodity API supply.
For Market Incumbents: Insulate fermentation strain stewardship advantages through captive microbiology expertise and dedicated pharmacopoeia certification programs for NMPA, EMA, and FDA parallel compliance. Lock in multi-year sodium hyaluronate contracts with US health systems covering ophthalmic, orthopedic, and wound care applications to defend against Chinese capacity-led price erosion. For New Entrants and Emerging Players: Establish a beachhead in Indian domestic biotech clusters where CDSCO regulatory pathway streamlining and PLI scheme incentives attract fermentation capacity investment for export-oriented pharmaceutical-grade production. Target crosslinked gel formulation innovation for extended residence time dermal fillers, bypassing entrenched sodium hyaluronate injection competition through direct-to-clinic digital contracts in Mexico. For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed European API suppliers lacking Chinese pharmacopoeia certification programs. Long-term viability over a five-to-ten year window favors targets with demonstrated batch consistency in Streptococcus zooepidemicus fermentation and established relationships with Tsukuba or Boston regenerative medicine research clusters. Watch for NMPA registration requirement tightening as the inflection signal forcing distressed divestitures from multinationals without local testing partnerships.| Strategic Initiative | Industry Significance |
|---|---|
| Manufacturing Scale-Up | Fermentation capacity expansion in Shandong and Jiangsu narrows supply deficits for ophthalmic applications. |
| Regulatory Approval Pathway | EMA Medical Device Regulation harmonization accelerates pharmaceutical-grade certification for dermal filler manufacturers. |
| Backward Integration | Bloomage Biotechnology's microbial fermentation-to-API control sustains cost advantages across value chain tiers. |
| Joint Venture | European API suppliers form China-dedicated testing partnerships to satisfy NMPA registration requirements. |
| Pipeline Diversification | Orthopedic viscosupplementation protocols expand beyond knee into hip and shoulder joint indications. |
Study Parameters
A spread of perspectives from regulatory affairs leads at fermentation technology suppliers, hospital procurement managers in German and Japanese health systems, formulary directors at US orthopedic groups, and aesthetic clinic chain operators in Brazil converged on the working assumptions. Primary interview insights combined with secondary validation from FDA 510(k) filings, EMA CHMP assessment reports, NMPA registration databases, and Chinese Pharmacopoeia monograph updates. Bottom-up sodium hyaluronate volume estimates triangulated against top-down therapeutic category expenditure analysis.
Demand-supply balance modeling across the projection horizon segmented by product type, application specialty, molecular weight tier, and regional regulatory cluster. CAGRs derived from procedure volume trajectories in cataract surgery, osteoarthritis injection protocols, and aesthetic medicine adoption curves. Forecast inputs incorporated reimbursement code stability for intra-articular injections, phacoemulsification technique refinements affecting per-procedure viscoelastic volume, and dermal filler direct-to-clinic procurement consolidation patterns.
Macroeconomic conditions sit as an overlay; deviation in healthcare reimbursement policy, biologics manufacturing energy costs, or avian supply chain stability for extraction routes would shift the trajectory. Forecasts reflect assumptions on pharmacopoeial harmonization timelines and fermentation capacity commissioning schedules. Material shifts in FDA endotoxin testing methodology or NMPA import registration enforcement would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pharmaceutical Ingredients
Penciclovir API Market
Pharmaceutical Ingredients
Pharmaceutical Desiccants Market
Pharmaceutical Ingredients
Global Small Molecule API Market
Pharmaceutical Ingredients
Synthetic Small Molecule API Market
Pharmaceutical Ingredients
Mrna Synthesis Raw Materials Market
Pharmaceutical Ingredients
Cetrorelix Acetate API Market
Pharmaceutical Ingredients
Pharma Grade Ibuprofen API Market
Pharmaceutical Ingredients
Piperacillin Sodium API Market
Pharmaceutical Ingredients
France Active Pharmaceutical Ingredients (API) Market
Pharmaceutical Ingredients
Silver Sulfadiazine Market
Pharmaceutical Ingredients
Originator Small Molecule Drug Market
Pharmaceutical Ingredients
Calcium Gluconate Market
Pharmaceutical Ingredients
Diclofenac Sodium API Market
Pharmaceutical Ingredients
Tranexamic Acid API Market
Pharmaceutical Ingredients
United Kingdom Active Pharmaceutical Ingredients (API) Market
Pharmaceutical Ingredients
Montelukast API Market