
 Pemetrexed Market | 2026-2036
Pemetrexed Market Size, Share, and Industry Trends Forecast 2026-2036
Pemetrexed Market Analysis
Aftermarket service revenue around infusion protocol training and patient monitoring programs is fragmenting across competing hospital networks and specialty pharmacy channels. Eli Lilly and Company anchors the originator segment through sustained investment in clinical evidence generation for expanded indications. Fresenius Kabi competes aggressively in the injectable formulation space with vertically integrated manufacturing capabilities. Sun Pharmaceutical Industries leverages its biosimilar pipeline to occupy price-sensitive segments in emerging markets.
Pemetrexed is a folate antimetabolite chemotherapy agent containing a pyrrolopyrimidine-based core structure that inhibits multiple enzymes in purine and pyrimidine biosynthesis, including thymidylate synthase, dihydrofolate reductase, and glycinamide ribonucleotide formyltransferase. It is administered intravenously in combination with cisplatin for malignant pleural mesothelioma and as a single agent or combination therapy for non-small cell lung cancer, with dosing calibrated to creatinine clearance and folic acid supplementation status. The indication dimension shows non-small cell lung cancer maintenance therapy generating the dominant revenue pool, while the biosimilar product type category records the fastest volume growth as patent cliffs mature. Oncology clinics within the end-user dimension capture expanding margin pools as administration shifts away from inpatient settings toward ambulatory infusion centers.
The FDA, EMA, and WHO prequalification standards govern pemetrexed approval pathways, with the FDA's oncology center of excellence accelerating biosimilar reviews and EMA's MDR framework tightening batch-release documentation for lyophilized formulations. These regulatory structures elevate compliance costs for powder formulation manufacturers while creating differentiated access tiers across pre-mixed and lyophilized presentation formats. Stakeholders must monitor evolving pharmacovigilance requirements for combination therapy regimens and calibrate portfolio bets between originator defense and biosimilar acceleration.
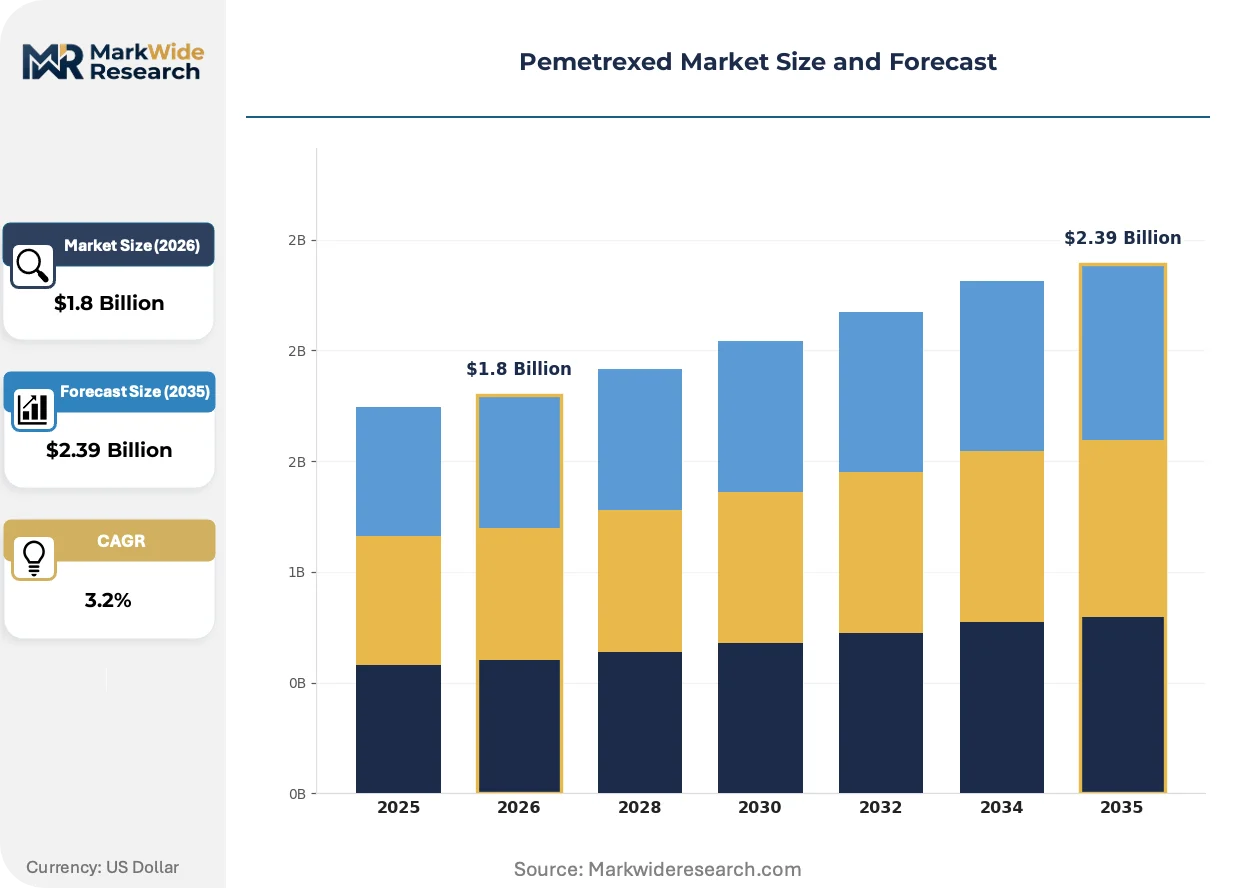
Market Dynamics
The FDA's oncology center of excellence is compressing biosimilar review timelines from 10 months toward 6 months, accelerating competitive entry against originator formulations and fragmenting margin pools across injectable presentation formats.
Growth Catalysts
- Accelerated Approval Pathways:The FDA's oncology center of excellence fast-tracks biosimilar reviews, compressing time-to-market for lyophilized formulations and expanding patient access to maintenance regimens.
- Outpatient Migration:Oncology clinics are capturing administration volume as payers mandate site-of-care shifts away from higher-cost inpatient infusion centers toward ambulatory settings.
- Folic Acid Co-Supplementation Protocols:Standardized pre-treatment regimens reduce hematologic toxicity rates, enabling broader eligibility for elderly and renal-impaired patient populations.
Market Restraints
- API Supply Concentration:Active pharmaceutical ingredient production clusters in China and India, creating single-source vulnerability for pemetrexed diacid and L-glutamic acid derivatives.
- Lyophilization Capacity Bottlenecks:Sterile powder formulation requires validated freeze-drying infrastructure that few contract manufacturers possess, constraining batch release velocity.
- Platinum-Based Combination Limits:Cisplatin nephrotoxicity and carboplatin hypersensitivity reactions cap combination therapy penetration in comorbid patient segments.
Strategic Opportunities
- Pre-Mixed Infusion Bags:Ready-to-administer presentations reduce pharmacy compounding labor and enable point-of-care administration in community oncology practices lacking sterile hood capacity.
- Maintenance Therapy Label Expansion:EMA's MDR framework rewards post-marketing evidence generation, creating regulatory pathways for prolonged dosing intervals in responder populations.
- Specialty Pharmacy Integration:Limited distribution networks capture patient monitoring revenue through oral folic acid co-dispensing and adherence tracking programs.
Industry Challenges
- Biosimilar Interchangeability Designation:FDA's heightened immunogenicity data requirements for automatic substitution create documentation burdens that extend development timelines.
- Cold Chain Integrity:Multi-stop distribution of temperature-sensitive lyophilized vials demands validated thermal packaging that increases logistics cost per unit.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Pemetrexed Market |
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $2.39 Billion |
| CAGR (2026 – 2036) | 3.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Injectable, Oral, Combination Therapy, Biosimilar End User: Oncology Clinics, Hospitals, Homecare, Research Institutions Formulation: Solution, Powder, Lyophilized, Pre-mixed Indication: Mesothelioma, Non-Small Cell Lung Cancer, Other Solid Tumors, Maintenance Therapy |
| Companies Covered | Abbott Laboratories, Fresenius Kabi, Eli Lilly and Company, Apotex Inc., Sun Pharmaceutical Industries, Eagle Pharmaceuticals, Cadila Healthcare, Accord Healthcare, Stada Arzneimittel AG, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Pemetrexed Market Emerging Trajectories
Formulation science and site-of-care economics are converging to reshape how pemetrexed reaches patients, with presentation formats and administration settings evolving faster than clinical protocols.
Ready-to-use premixed infusion bags are migrating from academic medical centers toward community oncology practices. These presentations eliminate pharmacy reconstitution steps and reduce occupational exposure risks. The technology is compressing the role of hospital-based sterile compounding facilities while expanding administration capacity in physician-owned infusion suites.
EMA's Medical Device Regulation tightened batch-release documentation requirements for lyophilized oncology injectables in 2021. Manufacturers now face elevated quality system costs for powder presentations. The regulation is pushing portfolio rationalization toward liquid-stable alternatives in European markets while preserving lyophilized formats for tropical distribution where cold chain reliability remains variable.
Site-of-care economics now govern payer reimbursement tiering for infusion administration. United States commercial insurers and Medicare Advantage plans route patients toward lower-cost ambulatory settings through differential copay structures. This behavioral shift concentrates volume in oncology clinics and hospital outpatient departments, compressing traditional inpatient pharmacy revenue pools.
Pemetrexed Market Segmentation
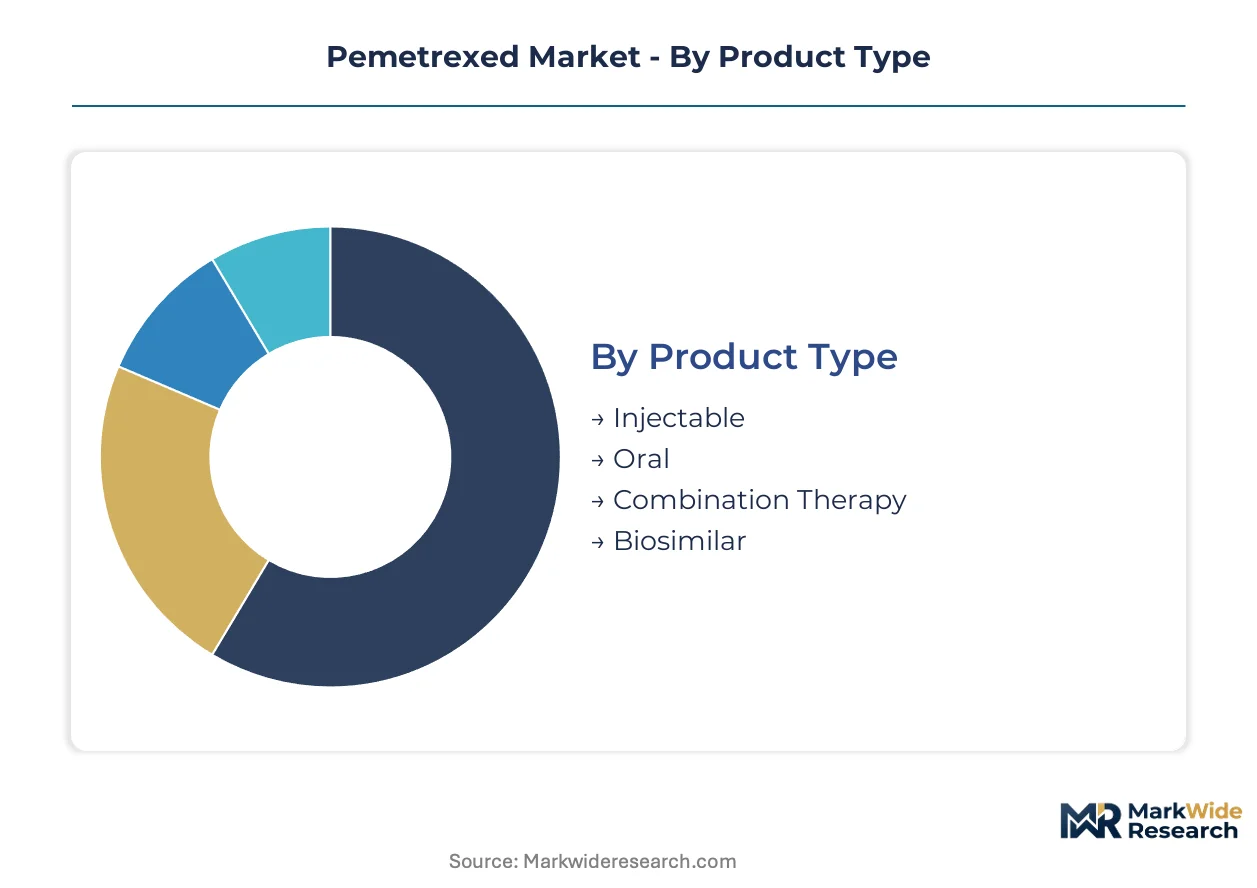
Pemetrexed's market structure fragments across four distinct dimensions that govern pricing power, distribution complexity, and competitive entry velocity. Each segmentation axis carries different margin profiles and regulatory burdens, forcing portfolio managers to prioritize resource allocation across incompatible manufacturing requirements.
Product Type:
Cycle times vary dramatically across this category, with biosimilars compressing development timelines through abbreviated pathways while combination therapies face extended clinical validation periods.
- Injectable:Intravenous infusion dominates current administration protocols, with demand concentrating in United States oncology clinics where outpatient reimbursement favors infusion-based regimens. Cold chain requirements and sterile compounding infrastructure limit manufacturer participation.
- Biosimilar:Abbreviated approval pathways accelerate competitive entry against originator formulations, with volume expanding most quickly in European markets where EMA's scientific advice programs reduce regulatory uncertainty. FDA's oncology center of excellence further compresses review timelines.
- Oral:Bioavailability challenges constrain development pipelines, with few candidates advancing past Phase I due to pemetrexed's poor gastrointestinal absorption.
- Combination Therapy:Platinum-based regimens with cisplatin or carboplatin require coordinated toxicity management, extending protocol development cycles.
Injectable formulations anchor the volume base while biosimilars gain share at the steepest rate.
End User:
Cost tier stratification separates high-acuity inpatient settings from lower-cost ambulatory alternatives, with reimbursement differentials driving patient migration patterns.
- Oncology Clinics:Ambulatory infusion centers capture expanding administration volume as United States payers mandate site-of-care optimization. Lower overhead structures enable competitive pricing against hospital outpatient departments.
- Hospitals:Inpatient oncology units retain complex cases requiring concurrent supportive care, with 340B drug pricing programs creating margin compression for contract pharmacies.
- Homecare:Subcutaneous formulation advances could enable domestic administration, though current intravenous requirements limit penetration.
- Research Institutions:Academic medical centers drive protocol innovation through investigator-sponsored trials, with limited commercial volume but outsized influence on treatment guidelines.
Hospitals retain the highest acuity cases while oncology clinics capture volume at the fastest clip.
Formulation:
Supply concentration in sterile manufacturing creates bottlenecks, with lyophilized capacity scarcity elevating batch release timelines relative to liquid-stable alternatives.
- Lyophilized:Freeze-dried powder presentations extend shelf stability but require validated aseptic processing infrastructure that few contract manufacturers possess. EMA's MDR framework tightened documentation requirements.
- Pre-mixed:Ready-to-administer infusion bags reduce pharmacy labor and occupational exposure, with adoption climbing fastest in community oncology practices lacking sterile hood capacity.
- Solution:Liquid formulations demand cold chain integrity throughout distribution, limiting reach to tropical markets with unreliable refrigeration infrastructure.
- Powder:Reconstitution-dependent presentations retain cost advantages in price-sensitive segments but require compounding expertise at point of care.
Lyophilized formats dominate current production while pre-mixed alternatives expand most rapidly.
Indication:
Maturity gradients separate established maintenance protocols from emerging solid tumor applications, with label expansion timelines determining competitive positioning.
- Non-Small Cell Lung Cancer:Maintenance therapy following platinum-based induction anchors commercial revenue, with United States incidence rates and favorable reimbursement sustaining volume concentration.
- Maintenance Therapy:Prolonged dosing intervals in responder populations represent the steepest expansion trajectory, with EMA's post-marketing evidence frameworks rewarding survival data generation.
- Mesothelioma:Orphan indication status with cisplatin combination maintains niche demand, constrained by limited patient prevalence relative to lung cancer.
- Other Solid Tumors:Investigational applications in bladder and cervical malignancies remain pre-commercial, with Phase II data pending.
Non-Small Cell Lung Cancer maintenance anchors revenue while maintenance therapy protocols broaden fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Demand elasticity for pemetrexed varies sharply across geographies, with United States payers showing low price sensitivity for maintenance regimens while Indian and Chinese procurement channels prioritize cost-minimized biosimilar alternatives.
United States
Medicare reimbursement rates for outpatient oncology clinics sustain premium pricing for originator formulations. FDA's oncology center of excellence accelerates biosimilar reviews through the 351(k) pathway. The Texas Medical Center in Houston anchors clinical trial activity for expanded maintenance indications.
Germany
G-BA benefit assessment procedures create pricing pressure on new entrants while stabilizing volume for established therapies. EMA's centralized marketing authorization streamlines access across member states. The Rhine-Main biopharma cluster near Frankfurt houses sterile injectable manufacturing for European distribution.
India
CDSCO's abbreviated approval pathways for oncology generics compress time-to-market for domestic manufacturers. Government procurement through the Central Government Health Scheme concentrates volume in public hospital networks. The Baddi-Barotiwala-Nalagarh pharmaceutical belt in Himachal Pradesh specializes in oncology API production.
Japan
PMDA's sakigake designation system prioritizes review for therapies addressing unmet needs in thoracic malignancies. National Health Insurance price listing occurs within 60 days of approval, enabling rapid access. The Kansai region around Osaka hosts contract manufacturing organizations serving Asia-Pacific markets.
China
NMPA's priority review channel for oncology drugs reduces approval timelines for locally manufactured alternatives. National reimbursement drug list negotiations drive aggressive price concessions for volume commitments. The Yangtze River Delta around Shanghai concentrates sterile formulation capacity for domestic and export supply.
Pemetrexed Market Vendor Landscape
Originator defense specialists and biosimilar acceleration players split the market into asymmetric competitive zones with divergent margin profiles. The structure tilts toward consolidation at the originator tier while fragmenting across mid-tier injectable manufacturers. Two dominant archetypes emerge: vertically integrated pharmaceutical conglomerates with captive API supply, and specialty generic houses reliant on contract manufacturing. Capacity expansion in lyophilized sterile processing and strategic partnerships for pre-mixed bag distribution constitute the primary competitive moves reshaping positioning.
Among originator-anchored conglomerates, Eli Lilly and Company exemplifies clinical evidence generation strategies for label expansion, while Fresenius Kabi occupies a position emphasizing integrated manufacturing control over injectable supply chains. Sun Pharmaceutical Industries represents the biosimilar-focused archetype targeting price-sensitive segments through abbreviated regulatory pathways.
| Leading Market Players |
|---|
| Abbott Laboratories |
| Fresenius Kabi |
| Eli Lilly and Company |
| Apotex Inc. |
| Sun Pharmaceutical Industries |
| Eagle Pharmaceuticals |
| Cadila Healthcare |
| Accord Healthcare |
| Stada Arzneimittel AG |
| Others |
Supply Flow & Price Mechanics
Single-source dependency on Chinese and Indian API manufacturers determines both the three-tier pricing structure across premium originator, mid-tier injectable, and economy biosimilar levels and the elongated supply chain shape with dual-sourcing redundancy gaps. This concentration risk elevates procurement costs for European and Japanese manufacturers while compressing margins for price-sensitive emerging market entrants.
Pricing Analysis
Aftermarket service revenue from infusion protocol training and patient monitoring programs drives lifetime value for originator manufacturers defending premium positioning. Three-tier pricing structure across premium originator, mid-tier injectable, and economy biosimilar levels separates Eli Lilly's evidence-based premium from Fresenius Kabi's integrated manufacturing tier and Sun Pharmaceutical's price-sensitive biosimilar segment. Cost compression in the biosimilar tier is intensifying because abbreviated FDA approval pathways accelerate competitive entry. Oncology clinics in the United States show lowest price sensitivity due to favorable Medicare reimbursement, while Indian government procurement channels exhibit highest sensitivity with centralized tender mechanisms.
Supply Chain Analysis
Supplier-financing through extended payment terms for API procurement characterizes relationships between Western formulation manufacturers and Asian raw material suppliers. Active pharmaceutical ingredient production draws from China, India, and limited Italian specialty chemical houses, with pemetrexed diacid and L-glutamic acid derivatives as critical inputs. Single-source vulnerability in lyophilization capacity creates bottlenecks for sterile powder batch release. Distribution runs through cold-chain logistics networks serving oncology clinics and hospital outpatient departments, with specialty pharmacy channels capturing adherence monitoring revenue.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The pemetrexed market sits at a post-patent-cliff cyclical recovery driven by biosimilar volume expansion and site-of-care economics favoring outpatient administration. Recovery momentum depends on regulatory acceleration maintaining competitive entry velocity against originator defense strategies.
For Market Incumbents: Insulate premium positioning through captive lyophilization capacity expansion and EMA post-marketing evidence generation for maintenance therapy label extensions. Eli Lilly should deepen clinical trial investment in responder population survival data while locking oncology clinic formulary access through integrated patient monitoring programs. Threat from FDA-accelerated biosimilar reviews demands faster protocol innovation cycles. For New Entrants and Emerging Players: Southeast Asian oncology clinic networks represent underpenetrated white space with rising non-small cell lung cancer incidence and limited biosimilar competition. Target community oncology practices lacking sterile compounding infrastructure with pre-mixed infusion bag partnerships. Go-to-market angle should emphasize pharmacy labor reduction and occupational safety compliance. For Investors and Strategic Acquirers: The market sits at a volume-expansion phase that favors vertically integrated injectable manufacturers with captive API supply. Long-term viability through the next decade hinges on lyophilization capacity scarcity and pre-mixed formulation technology access. Acquisition target archetype: mid-tier sterile injectable specialists with EMA MDR compliance infrastructure. Signal to watch is FDA interchangeability designation granting automatic substitution rights.| Strategic Initiative | Industry Significance |
|---|---|
| Lyophilization Capacity Expansion | Validated freeze-drying infrastructure scarcity elevates batch release velocity for sterile powder presentations. |
| Pre-Mixed Infusion Bag Launch | Ready-to-administer formats capture community oncology practices lacking sterile hood compounding capacity. |
| FDA Interchangeability Pathway | Automatic substitution designation fragments originator defense strategies across Medicare Part B reimbursement. |
| EMA Post-Marketing Evidence Generation | Survival data in responder populations unlocks prolonged maintenance therapy dosing interval expansion. |
| Specialty Pharmacy Network Integration | Limited distribution partnerships capture oral folic acid co-dispensing and adherence tracking revenue pools. |
Methodological Framework
A spread of perspectives from oncology clinic administrators, hospital pharmacy directors, regulatory affairs specialists at sterile injectable manufacturers, and payer formulary managers converged on the working assumptions driving this analysis. Primary interviews combined with secondary validation from FDA 351(k) biosimilar filings, EMA centralized marketing authorization procedures, ClinicalTrials.gov maintenance therapy protocols, and CMS Medicare reimbursement schedules. Bottom-up patient volume modeling and top-down pharmaceutical expenditure triangulation anchored value estimates.
Demand-supply-balance framing structured the analytical approach across the projection horizon, with segmentation dimensions covering product type, end-user channel, formulation presentation, and indication maturity. Treatment line positioning and regional regulatory cluster differentiation shaped patient access assumptions. CAGRs derived from patent cliff timing, biosimilar approval velocity, and site-of-care reimbursement tier evolution. Forecast inputs included lyophilization capacity utilization rates and pre-mixed bag adoption curves in community oncology settings.
Practitioners should monitor FDA interchangeability designation grants, EMA MDR batch documentation enforcement, and API supply disruption events for early signals of forecast deviation. Macroeconomic, regulatory, or technological deviation would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pharmaceutical Ingredients
Flurbiprofen Market
Pharmaceutical Ingredients
Pharmaceutical Grade Beta-Alanine Market
Pharmaceutical Ingredients
Mitotic Inhibitors Market
Pharmaceutical Ingredients
Global Small Molecule API Market
Pharmaceutical Ingredients
Active Pharmaceutical Ingredient for Cancer Market
Pharmaceutical Ingredients
Global Pharmaceutical Grade Sodium Chloride Market
Pharmaceutical Ingredients
Global Chlorpheniramine Maleate Market
Pharmaceutical Ingredients
Piperacillin Sodium API Market
Pharmaceutical Ingredients
Calcium Folinate for Injection Market
Pharmaceutical Ingredients
Heparin Sodium API Market
Pharmaceutical Ingredients
Fixed-Dose Combination Drugs Market
Pharmaceutical Ingredients
Pharmaceutical Grade Magnesium Hydroxide Market
Pharmaceutical Ingredients
Cox 2 Inhibitors Market
Pharmaceutical Ingredients
Small-Molecule Injectable Drugs Market
Pharmaceutical Ingredients
Small Molecule Drug Discovery Market
Pharmaceutical Ingredients
Antibiotics API Market