
 Sterile Active Pharmaceutical Ingredients Market | 2026-2036
Sterile Active Pharmaceutical Ingredients Market Size, Share, and Industry Trends Forecast 2026-2036
Sterile Active Pharmaceutical Ingredients Market Analysis
Contract manufacturing organizations are rotating toward high-containment sterile capabilities as pharmaceutical companies outsource aseptic API production. Lonza Group dominates microbial fermentation for sterile biologics across Swiss and US facilities. Pfizer CentreOne leverages its captive sterile network to supply internal pipelines and external partners. Fresenius Kabi anchors European hospital demand through integrated sterile manufacturing and finished-dose packaging.
Sterile active pharmaceutical ingredients are biologically or chemically synthesized compounds manufactured under aseptic conditions to eliminate microbial contamination, meeting endotoxin limits below specified thresholds and sterility assurance levels required for parenteral administration. Biologics command the largest value pool due to complex aseptic cell-culture requirements and temperature-sensitive processing, while peptides represent the fastest-expanding segment driven by GLP-1 receptor agonist demand. Intravenous delivery sustains the highest volume share across hospital and acute-care settings, though subcutaneous formats are gaining share with pre-filled syringe and autoinjector adoption.
The FDA enforces sterility testing and environmental monitoring under current Good Manufacturing Practice guidelines, while the European Medicines Agency applies EU GMP Annex 1 standards that mandate barrier technology and continuous viable particle monitoring. India's Central Drugs Standard Control Organization aligns with WHO prequalification norms for export-oriented sterile API facilities. Stakeholders must monitor regulatory divergence between US and European aseptic processing expectations as they evaluate capital allocation across sterile manufacturing footprints.
Market Dynamics
The sterile API sector is being restructured by the migration of biologics manufacturing toward outsourced aseptic processing, as pharmaceutical sponsors shed fixed-asset burdens and contract manufacturing organizations absorb capacity risk.
Growth Catalysts
- EU GMP Annex 1 Revisions:The 2022 update mandates barrier technology and continuous viable particle monitoring, forcing facility upgrades that favor specialist contract manufacturers with capital reserves.
- GLP-1 Receptor Agonist Surge:Peptide-based diabetes and obesity therapies require sterile parenteral APIs, pulling fermentation and synthesis capacity toward high-potency, low-volume production.
- India's CDSCO Export Alignment:WHO prequalification norms for sterile API facilities are concentrating investment in Hyderabad and Ahmedabad clusters serving regulated markets.
Market Restraints
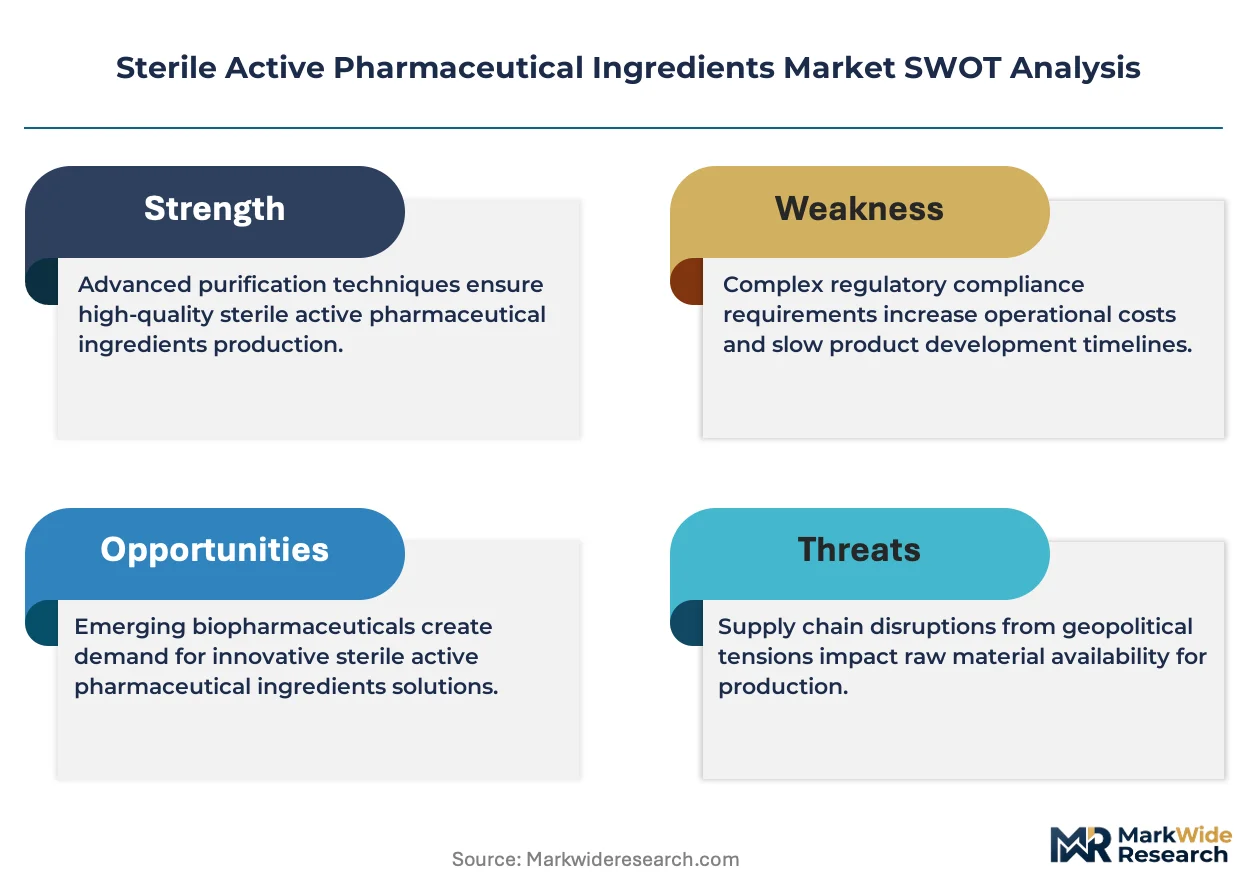
- Specialized Input Scarcity:Pharmaceutical-grade stainless steel and single-use bioreactor bags face allocation constraints from semiconductor and food-grade competitors.
- Swiss-US Supply Concentration:Lonza and Catalent anchor microbial fermentation capacity, creating bottleneck risk for biologics sponsors without captive facilities.
- Terminal Sterilization Limitations:Heat-labile biologics cannot undergo final sterilization, forcing reliance on aseptic processing with higher contamination failure rates.
Strategic Opportunities
- Brazil's ANVISA Accelerated Pathway:Local sterile API production for Latin American biologics markets remains underdeveloped, creating first-mover openings for GMP-certified entrants.
- Continuous Manufacturing Convergence:Integration of process analytical technology with single-use systems enables real-time release testing, compressing batch cycle times.
- Pre-Filled Syringe Format Expansion:Subcutaneous administration shifts are demanding sterile API supply chains configured for combination product assembly.
Industry Challenges
- Aseptic Processing Specialist Shortage:Cleanroom operators and contamination control engineers command premium wages as training pipelines lag facility expansion.
- Isolator Technology Capex Burden:Restricted access barrier systems require 18-24 month installation timelines, freezing capital during regulatory review periods.
- Legacy Facility Retrofit Complexity:Older fill-finish sites face structural constraints integrating continuous monitoring systems without complete rebuilds.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Sterile Active Pharmaceutical Ingredients Market |
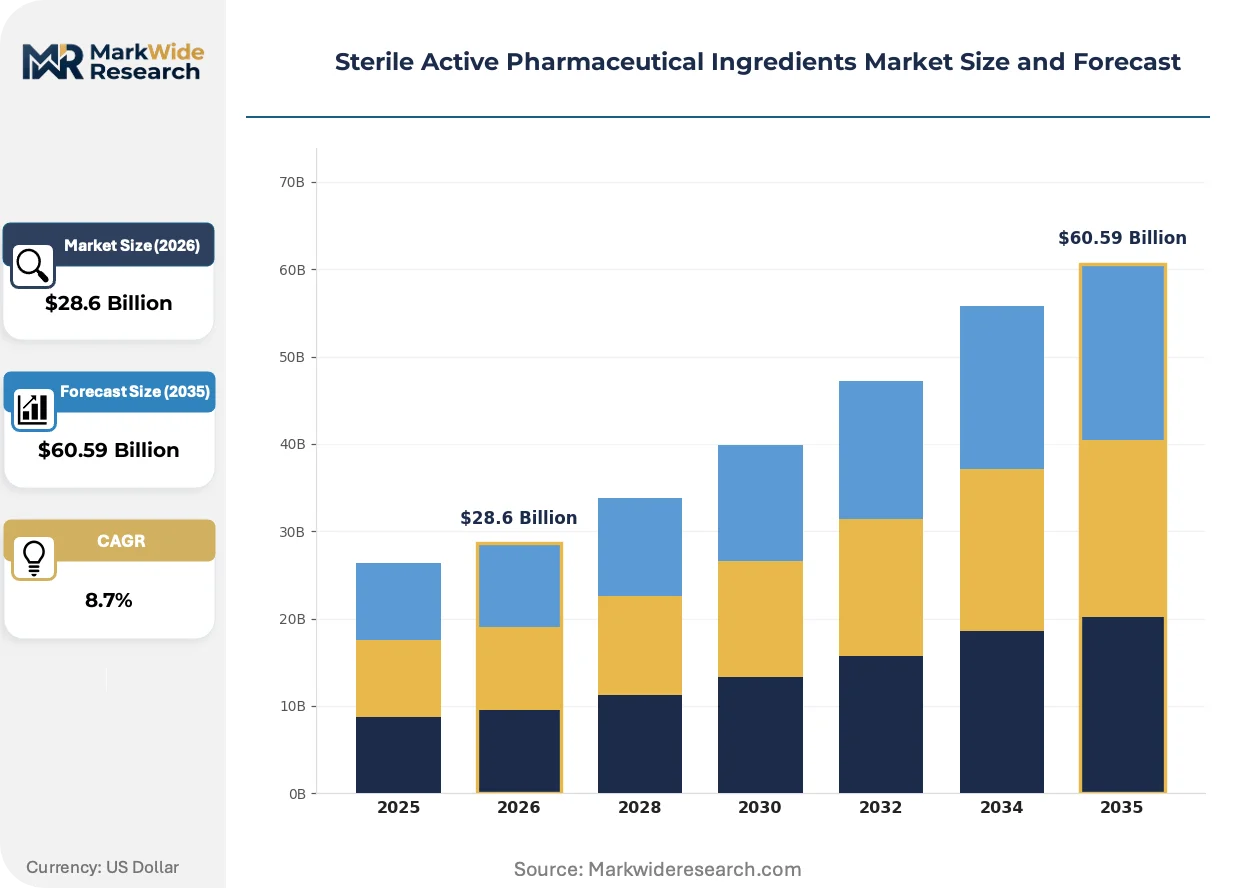
| Market Size in 2026 | $28.6 Billion |
| Market Size in 2035 | $60.59 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Biologics, Small Molecules, Peptides, Vaccines Delivery Mode: Intravenous, Intramuscular, Subcutaneous, Inhalation End User: Pharmaceutical Companies, Contract Manufacturing Organizations, Research Institutions, Hospitals Packaging Type: Ampoules, Vials, Pre-filled Syringes, Blister Packs |
| Companies Covered | Pfizer CentreOne, Fresenius Kabi, Lonza Group, Siegfried Holding, Hikma Pharmaceuticals, Baxter International, CordenPharma International, Dr. Reddy’s Laboratories, Teva Pharmaceutical Industries, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Sterile Active Pharmaceutical Ingredients Market Emerging Trajectories
Single-use technologies and modular facility designs are compressing the traditional sterile manufacturing model, enabling faster product changeovers and reducing cross-contamination risks in multi-product sites.
Modular cleanroom pods equipped with pre-validated isolator systems are decomposing the conventional stick-built facility paradigm. Mid-sized biotech sponsors are adopting these units to enter clinical manufacturing within 12 months rather than 36. The shift is compressing the addressable market for traditional engineering-procurement-construction contractors.
The FDA's 2023 revision to its sterile drug guidance document imposes stricter environmental monitoring and contamination control strategy requirements. Manufacturers must now document holistic risk assessments spanning facility design through personnel behavior. Parenteral biologics producers with legacy open-filling operations face the steepest compliance cliffs.
Hospital and infusion center buyers are consolidating sterile API procurement through integrated delivery networks and group purchasing organizations. This concentration is squeezing spot-market spot purchases and favoring contract manufacturers with multi-year supply agreements. The pattern is most pronounced in United States acute-care systems absorbing physician practice networks.
Sterile Active Pharmaceutical Ingredients Market Segmentation
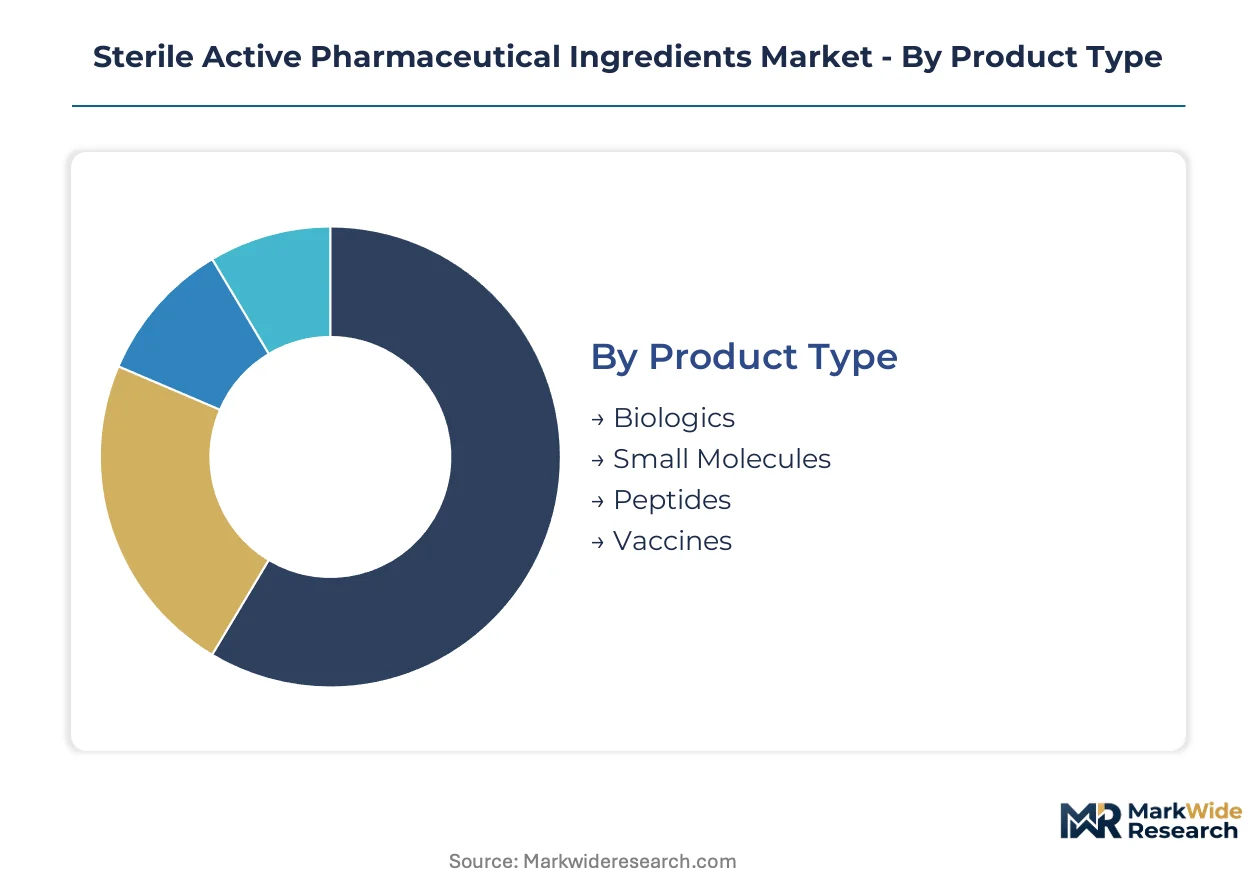
Sterile API procurement patterns diverge sharply across product categories and delivery formats. Biologics sponsors demand aseptic cell-culture capabilities while generic injectable manufacturers prioritize cost-efficient small-molecule sterilization. Understanding these segment boundaries clarifies where capital deployment yields differentiated returns.
Product Type:
Domestic production clusters in the United States, Switzerland, and India anchor biologics and peptide supply, while small-molecule sterile APIs flow more heavily through export-oriented manufacturing in China and Eastern Europe.
- Biologics:Large-molecule therapeutics derived from living cells require aseptic cell-culture processing under strict endotoxin controls. Demand concentrates in Massachusetts and Basel-region facilities serving oncology and immunology pipelines, with FDA and Swissmedic inspections driving barrier technology investments.
- Peptides:Synthetic amino acid chains, particularly GLP-1 receptor agonists, demand sterile parenteral formulation with precise impurity profiling. Hyderabad and Ahmedabad clusters in India are absorbing fermentation and solid-phase synthesis capacity for export to regulated markets under CDSCO-WHO alignment.
- Small Molecules:Chemically synthesized compounds undergo terminal sterilization or aseptic filtration for generic injectable markets.
- Vaccines:Antigen-based biologics require dedicated fill-finish lines with formaldehyde-free preservation systems.
Biologics holds the largest share; momentum sits with peptides.
Delivery Mode:
Hospital procurement patterns favor intravenous formats for acute administration, while self-injection trends are redistributing volume toward subcutaneous delivery systems with distinct API stability requirements.
- Intravenous:Direct bloodstream administration via infusion or bolus injection dominates oncology and critical-care settings. United States integrated delivery networks specify endotoxin limits below EU GMP Annex 1 thresholds, forcing suppliers into redundant testing protocols.
- Subcutaneous:Tissue-layer injection via pre-filled syringes or autoinjectors enables outpatient administration for chronic therapies. Germany's hospital procurement consortia are standardizing viscosity specifications for high-concentration biologics, compressing formulation flexibility.
- Intramuscular:Depot-formulation injections sustain vaccine and long-acting antipsychotic delivery.
- Inhalation:Nebulized or dry-powder sterile APIs target respiratory indications with particle size distribution constraints.
Intravenous formats dominate current volume; subcutaneous systems are expanding most quickly.
End User:
Contract manufacturing organizations are capturing share from captive pharmaceutical facilities as sponsors shed fixed-asset exposure, while research institutions remain fragmented procurement targets.
- Contract Manufacturing Organizations:Specialist aseptic processors absorb capacity risk and regulatory compliance burdens from pharmaceutical sponsors. Lonza's microbial fermentation network across Swiss and US facilities illustrates the capital concentration required for biologics-scale sterile production.
- Pharmaceutical Companies:Vertically integrated manufacturers retain sterile API production for pipeline assets and supply security. Pfizer CentreOne leverages captive sterile capacity to serve internal development programs alongside selective external partnerships.
- Research Institutions:Academic and government laboratories procure small-batch sterile APIs for clinical trial material.
- Hospitals:Compounding pharmacies and health systems source sterile APIs for 503B outsourcing facilities.
Contract manufacturing organizations command the steepest expansion trajectory; pharmaceutical companies retain the largest existing share.
Packaging Type:
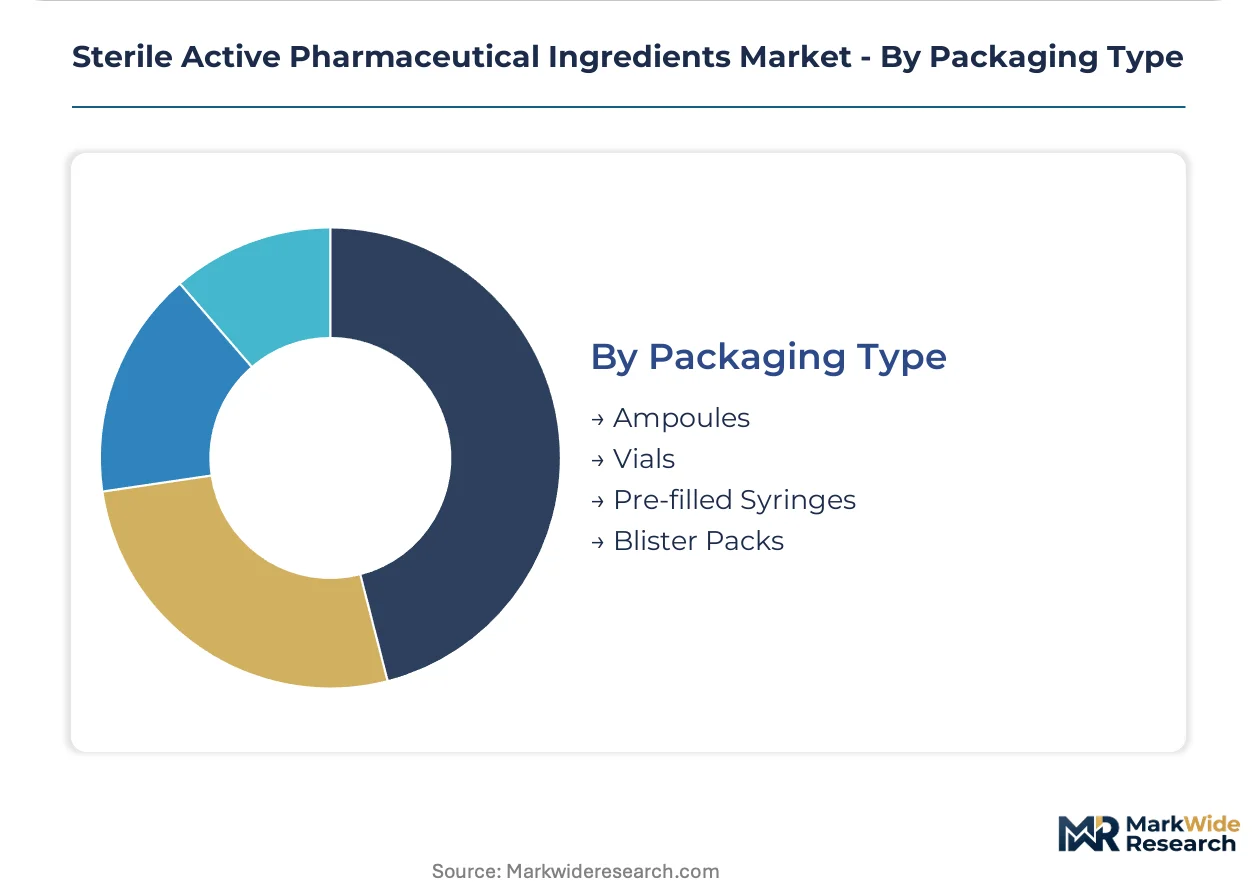
Pre-filled syringe adoption is forcing API suppliers into combination-product regulatory pathways, while vial formats maintain cost advantages for high-volume generic injectables.
- Pre-filled Syringes:Ready-to-use delivery systems integrate sterile API with container-closure systems under device regulations. Fresenius Kabi's European hospital supply contracts specify siliconization and tungsten-residue limits that propagate upstream to API specification sheets.
- Vials:Multi-dose glass or polymer containers remain the default for lyophilized and liquid sterile APIs. India's export-oriented sterile facilities in Hyderabad cluster around vial-format production for regulated-market generic injectables.
- Ampoules:Single-use glass containers serve emergency and field-medicine applications with break-open administration.
- Blister Packs:Sterile powder or lyophilized cake presentation for reconstitution prior to injection.
Vials retain the largest installed base; pre-filled syringes are gaining share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Sterile API manufacturing capacity clusters in jurisdictions with mature regulatory frameworks and established biologics ecosystems. The United States, Germany, India, Switzerland, and Japan host the dominant production footprints, each shaped by distinct compliance architectures and end-market access strategies.
United States
Massachusetts and North Carolina biomanufacturing corridors absorb the majority of domestic sterile API investment, driven by oncology and immunology pipeline demand. FDA's 2023 sterile drug guidance revision imposes stricter environmental monitoring and contamination control documentation requirements. Boston-Cambridge cluster facilities are retrofitting legacy open-filling lines with restricted access barrier systems to meet compliance deadlines.
Germany
Rhineland-Palatinate and Bavaria sterile manufacturing sites anchor European hospital procurement through integrated supply contracts. EMA's EU GMP Annex 1 mandates continuous viable particle monitoring and barrier technology deployment across aseptic processing suites. Frankfurt-Rhine-Main region contract manufacturers are consolidating multi-product capacity to serve pan-European integrated delivery networks.
India
Hyderabad and Ahmedabad fermentation clusters are scaling peptide synthesis capacity for GLP-1 receptor agonist export markets. CDSCO alignment with WHO prequalification norms is concentrating investment in Telangana and Gujarat facilities serving regulated-market sponsors. Hyderabad's Genome Valley ecosystem is attracting specialist aseptic processors seeking cost-competitive, inspection-ready manufacturing.
Switzerland
Basel-region biologics infrastructure supports microbial fermentation at industrial scale for global biopharma sponsors. Swissmedic inspection standards drive barrier technology adoption and real-time release testing capabilities. Lonza's Visp facility anchors the country's sterile biologics production concentration.
Japan
Kansai and Kanto pharmaceutical manufacturing belts maintain captive sterile API capacity for domestic biologics pipelines. PMDA's ICH Q5A viral safety guidelines shape contamination control strategies for cell-culture derived products. Osaka-based facilities are integrating process analytical technology to compress batch release timelines.
Sterile Active Pharmaceutical Ingredients Market Vendor Landscape
Concentration sits with integrated biologics specialists and contract manufacturing organizations possessing aseptic processing scale. The vendor base stratifies across three tiers: global CDMOs with multi-continental sterile networks, regional specialists serving specific therapeutic categories, and captive pharmaceutical manufacturing divisions. Competitive positioning hinges on regulatory inspection history, barrier technology deployment, and multi-year supply agreement penetration. M&A activity targets aseptic processing capability gaps, while capacity expansion concentrates in India and Switzerland to balance cost and compliance profiles.
Among the integrated pharmaceutical manufacturing divisions, Pfizer CentreOne and Fresenius Kabi exemplify divergent strategic archetypes. Pfizer CentreOne occupies a position bridging captive sterile supply for internal pipelines with selective external partnership access. Fresenius Kabi represents the hospital-centric integration model, combining sterile API production with finished-dose packaging and direct acute-care distribution. Lonza Group anchors the specialist CDMO tier, with its Swiss and US microbial fermentation footprint serving biologics sponsors without captive aseptic infrastructure.
| Leading Market Players |
|---|
| Pfizer CentreOne |
| Fresenius Kabi |
| Lonza Group |
| Siegfried Holding |
| Hikma Pharmaceuticals |
| Baxter International |
| CordenPharma International |
| Dr. Reddy's Laboratories |
| Teva Pharmaceutical Industries |
| Others |
Supply Flow & Price Mechanics
Single-use bioreactor bags displacing stainless steel infrastructure simultaneously redistributes sterile API production toward modular facilities in India and Switzerland while compressing capital recovery timelines that anchor pricing premiums for barrier technology-equipped lines.
Pricing Analysis
EU GMP Annex 1 dictates the pricing tier structure across sterile API manufacturing, separating barrier technology-certified facilities from open-filling operations and terminal sterilization lines. Three-tier pricing structure across premium barrier-isolator, standard restricted-access, and economy terminal-sterilization levels reflects contamination control investment differentials. Cost compression in standard-tier peptide synthesis is intensifying because GLP-1 receptor agonist demand is absorbing available fermentation capacity. Generic injectable manufacturers exhibit highest price sensitivity, while oncology biologics sponsors accept premium tiers for FDA-inspected aseptic cell-culture supply security.
Supply Chain Analysis
Switzerland and India anchor microbial fermentation and peptide synthesis capacity for regulated-market sterile API supply. Pharmaceutical-grade stainless steel and single-use bioreactor bags draw from semiconductor and food-grade competitors, creating allocation bottlenecks. Single-source vulnerability concentrates in Swiss-US fermentation networks controlled by specialist contract manufacturers. Distribution runs through integrated delivery networks and group purchasing organizations that consolidate hospital procurement and squeeze spot-market transactions.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Sterile API manufacturing sits in early-cycle expansion as GLP-1 receptor agonist demand penetrates obesity and diabetes treatment protocols, pulling greenfield investment toward peptide synthesis infrastructure.
For Market Incumbents: Consolidate barrier technology advantages through captive certification investments in EU GMP Annex 1-compliant isolator suites, while absorbing mid-tier competitors facing legacy facility retrofit cliffs. Defend against modular cleanroom pod disruptors by locking multi-year supply agreements with integrated delivery networks that specify endotoxin thresholds below regulatory minimums.
For New Entrants and Emerging Players: Lead with Brazil's ANVISA accelerated pathway for Latin American biologics markets, where local sterile API production remains underdeveloped and first-mover GMP certification yields procurement preference. Target Hyderabad and Ahmedabad manufacturing clusters serving WHO prequalification-aligned export demand, positioning through CDSCO inspection-ready facility designs that compress regulatory approval timelines.
For Investors and Strategic Acquirers: Secondary-cycle assets sit with private equity-backed contract manufacturing organizations that acquired regional sterile processors during prior consolidation waves. Five-to-ten year viability hinges on barrier technology deployment completion and FDA inspection history depth. Monitor EU GMP Annex 1 compliance deadline progression as inflection indicator for distressed facility availability.
| Strategic Initiative | Industry Significance |
|---|---|
| Barrier Technology Deployment | Isolator system installation satisfies EU GMP Annex 1 continuous monitoring mandates for aseptic processing. |
| Modular Cleanroom Pod Adoption | Pre-validated units compress clinical manufacturing timelines from thirty-six to twelve months for biotech sponsors. |
| GLP-1 Peptide Capacity Expansion | Fermentation and solid-phase synthesis investments capture diabetes and obesity therapy demand acceleration. |
| Pre-filled Syringe Format Integration | Combination product regulatory pathways align sterile API supply with autoinjector and self-injection device assembly. |
| Continuous Manufacturing Convergence | Process analytical technology integration enables real-time release testing and batch cycle compression. |
Methodological Framework
Demand-side practitioners and supply-side operators were both consulted through structured primary interviews with sterile manufacturing executives, regulatory affairs leads at FDA-inspected facilities, hospital procurement managers within integrated delivery networks, and contamination control engineering specialists. Secondary validation drew from FDA sterile drug guidance documents, EMA EU GMP Annex 1 revision texts, CDSCO facility inspection reports, and WHO prequalification assessment records. Bottom-up capacity modeling triangulated against top-down therapeutic demand projections across biologics, peptides, and generic injectable segments.
Across the analysis window, volume and value outputs reflect analytical frameworks segmented by product type, delivery mode, end-user category, and regional regulatory cluster. CAGRs were derived from installed capacity expansion trajectories, pipeline asset progression through clinical stages, and substitution elasticities between captive and outsourced manufacturing. Forecast inputs incorporated GLP-1 receptor agonist demand curves, barrier technology adoption rates, and modular facility deployment timelines.
The analysis sits within stated boundaries; outcomes outside sustained biologics pipeline investment, regulatory inspection capacity expansion, or single-use technology supply stabilization would require recalibration. Forecasts reflect documented assumptions regarding sponsor outsourcing propensity and contract manufacturer capital availability. Recalibration cycles align with material shifts in FDA guidance enforcement, EU GMP Annex 1 implementation deadlines, and WHO prequalification norm revisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pharmaceutical Ingredients
Pharma Grade Ibuprofen API Market
Pharmaceutical Ingredients
Sennosides Market
Pharmaceutical Ingredients
MEK Inhibitors Market
Pharmaceutical Ingredients
Mitotic Inhibitors Market
Pharmaceutical Ingredients
US Pharmaceutical Glycerin Based Products Market
Pharmaceutical Ingredients
Transdermal Drugs Market
Pharmaceutical Ingredients
Pharmaceutical Glycerine Market
Pharmaceutical Ingredients
Co-Crystal Ingredient Market
Pharmaceutical Ingredients
Pharmaceutical Grade Magnesium Hydroxide Market
Pharmaceutical Ingredients
Global Pharmaceutical Excipients Market
Pharmaceutical Ingredients
Global Barbiturate Drugs Market
Pharmaceutical Ingredients
Immunosuppressants Market
Pharmaceutical Ingredients
Nuclear Export Inhibitor Drugs Market
Pharmaceutical Ingredients
Pharmaceuticals Grade Sodium Bicarbonate Market
Pharmaceutical Ingredients
Piperacillin Sodium API Market
Pharmaceutical Ingredients
Fosfomycin Trometamol Powder Market