
 Fugitive Emissions Detection and Quantification Test Systems Market | 2026-2036
Fugitive Emissions Detection and Quantification Test Systems Market Size, Share, and Industry Trends Forecast 2026-2036
Fugitive Emissions Detection and Quantification Test Systems Market Insights
The EPA's methane emissions standards under the Inflation Reduction Act is shifting procurement priorities across North American energy infrastructure. Teledyne FLIR leverages its thermal imaging heritage to dominate optical gas imaging deployments at upstream facilities. Baker Hughes anchors its position through integrated digital platforms that combine hardware sensors with cloud-based analytics for continuous monitoring. Honeywell competes by extending its distributed control system architecture into emissions management software layers.
Fugitive emissions detection and quantification test systems comprise calibrated instrumentation that measures hydrocarbon and volatile organic compound leakage rates at concentrations down to parts per million, employing optical absorption spectroscopy or electrochemical cell principles to identify emission points across pressurized equipment. These systems serve the primary industrial purpose of enabling regulatory compliance while reducing product loss and safety hazards at oil and gas production, processing, and transmission sites. Thermal cameras command the largest revenue share among product types due to their non-contact detection capability and rapid area coverage, though electrochemical technology segments are gaining traction in fixed-installation applications where cost sensitivity dominates specification criteria. Environmental consultants represent the fastest-growing end user category as third-party verification services expand under tightening EPA audit protocols.
The EPA, the EU Green Deal's methane strategy framework, and ISO 14064 standards collectively shape equipment certification requirements, detection frequency mandates, and reporting granularity across operating jurisdictions. Compliance timelines under the Inflation Reduction Act's waste emissions charge are accelerating capital allocation toward automated quantification systems that reduce manual survey dependence. Stakeholders must monitor evolving interoperability standards between sensor hardware and emissions accounting platforms to avoid stranded technology investments as regulatory reporting migrates toward real-time data submission protocols.
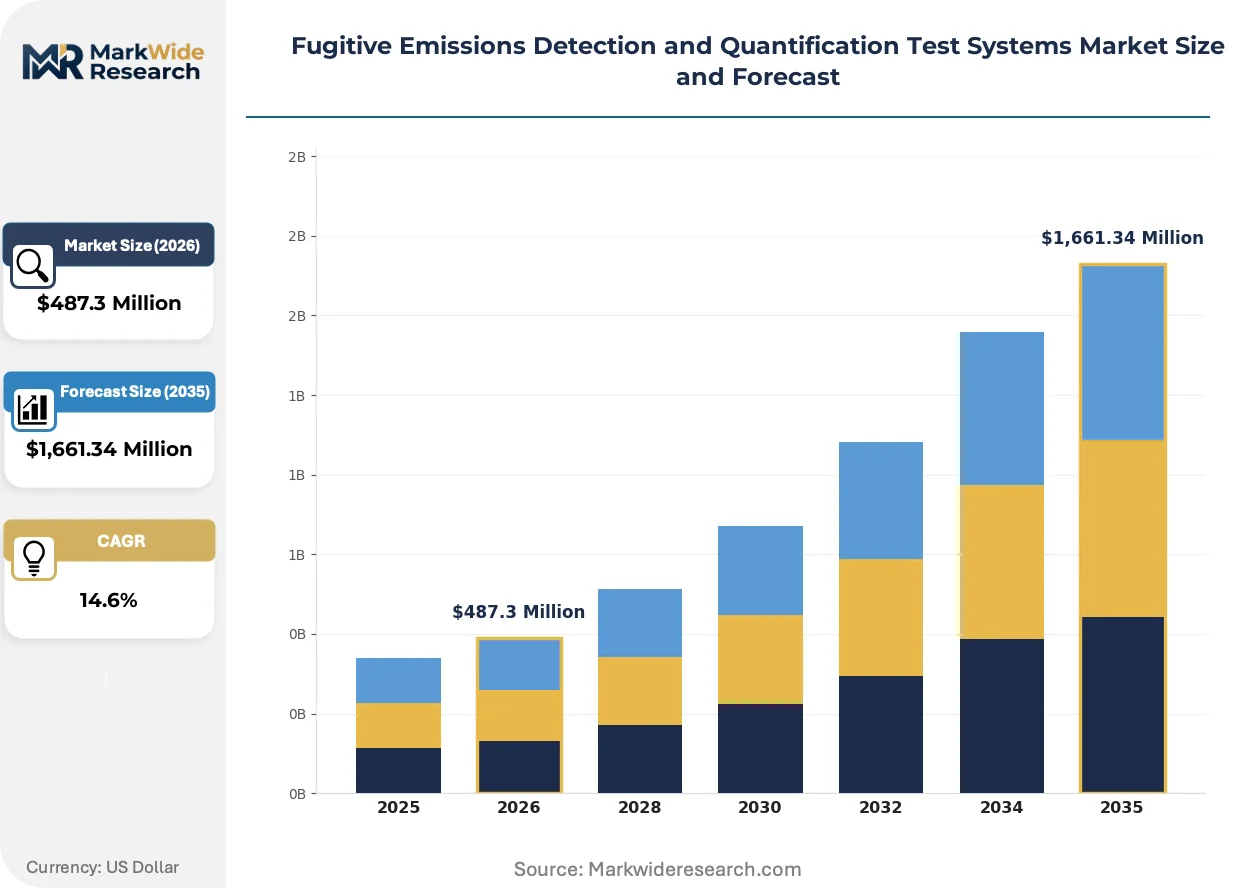
Market Dynamics
EPA methane waste emissions charges under the Inflation Reduction Act are compressing compliance timelines and forcing oilfield operators toward continuous monitoring architectures that eliminate manual survey dependence.
Growth Catalysts
- Inflation Reduction Act mandates:The EPA's escalating waste emissions charges create immediate financial pressure for automated quantification systems at upstream facilities.
- Permian Basin infrastructure density:Concentrated drilling activity across West Texas and New Mexico generates concentrated procurement volume for pipeline monitoring networks.
- Optical gas imaging maturation:Thermal camera sensitivity improvements enable detection at parts-per-million thresholds previously requiring laboratory analysis.
Market Restraints
- Sensor hardware cost structure:Infrared detector arrays and precision optics maintain elevated unit economics that constrain fixed-installation deployment at marginal wells.
- Calibration gas supply concentration:Certified reference material production clusters in Germany and the United States, exposing buyers to transatlantic logistics friction.
- Electrochemical cell temperature sensitivity:Performance degradation below minus twenty degrees Celsius limits deployment latitude in North Dakota and Alberta winter conditions.
Strategic Opportunities
- EU Green Deal methane strategy:The European Commission's import standard proposals create compliance service demand for verification systems at LNG terminals.
- Drone-mounted sensor convergence:Unmanned aerial platforms combining thermal cameras with methane spectrometers enable survey automation across inaccessible terrain.
- Environmental consultant channel expansion:Third-party verification services under tightening audit protocols represent underpenetrated recurring revenue streams.
Industry Challenges
- Spectroscopy technician scarcity:Specialized calibration and data interpretation skills concentrate at legacy oilfield service firms, constraining vendor scaling.
- Legacy SCADA integration complexity:Emissions data streams must interface with decades-old distributed control architectures without disrupting operational continuity.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Fugitive Emissions Detection and Quantification Test Systems Market |
| Market Size in 2026 | $487.3 Million |
| Market Size in 2035 | $1,661.34 Million |
| CAGR (2026 – 2036) | 14.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Gas Analyzers, Optical Sensors, Thermal Cameras, Acoustic Detectors, PID Sensors Technology: Infrared, Ultraviolet, Laser, Ultrasonic, Electrochemical Application: Petrochemical Operations, Gas Processing, Waste Management, Chemical Manufacturing, Refrigeration Monitoring End User: Oilfield Operators, Refining Facilities, Wastewater Treatment Plants, HVAC Contractors, Environmental Consultants |
| Companies Covered | Teledyne FLIR, Thermo Fisher Scientific, ABB, Honeywell, Sensirion Connected Solutions, Baker Hughes, SeekOps, Alliance Technical Group, Southwest Research Institute, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Fugitive Emissions Detection and Quantification Test Systems Market Trends and Innovations
Continuous monitoring architectures are displacing periodic manual surveys as the default compliance posture, reshaping equipment specifications toward networked sensor arrays and real-time data transmission.
Quantum cascade laser spectroscopy is unifying detection and quantification functions within single hardware units. Midstream operators at compressor stations are adopting these integrated systems to reduce instrument count and maintenance overhead. The technology is unifying what were previously separate capital allocations into consolidated procurement decisions.
EPA's November 2023 supplemental proposal to the New Source Performance Standards tightens leak detection frequency requirements at well sites and tank batteries. Oilfield operators face accelerated capital deployment timelines to achieve compliance before 2026 enforcement dates. Equipment procurement is concentrating on systems with automated quantification capabilities that satisfy waste emissions charge documentation requirements.
Service contracting is fragmenting equipment ownership from data delivery. Environmental consulting firms are assuming capital responsibility for sensor networks while charging operators per-quantified-emission fees. This model is displacing traditional capital purchase arrangements most visibly in the Permian Basin, where drilling economics favor operational expenditure structures.
Fugitive Emissions Detection and Quantification Test Systems Market Segmentation
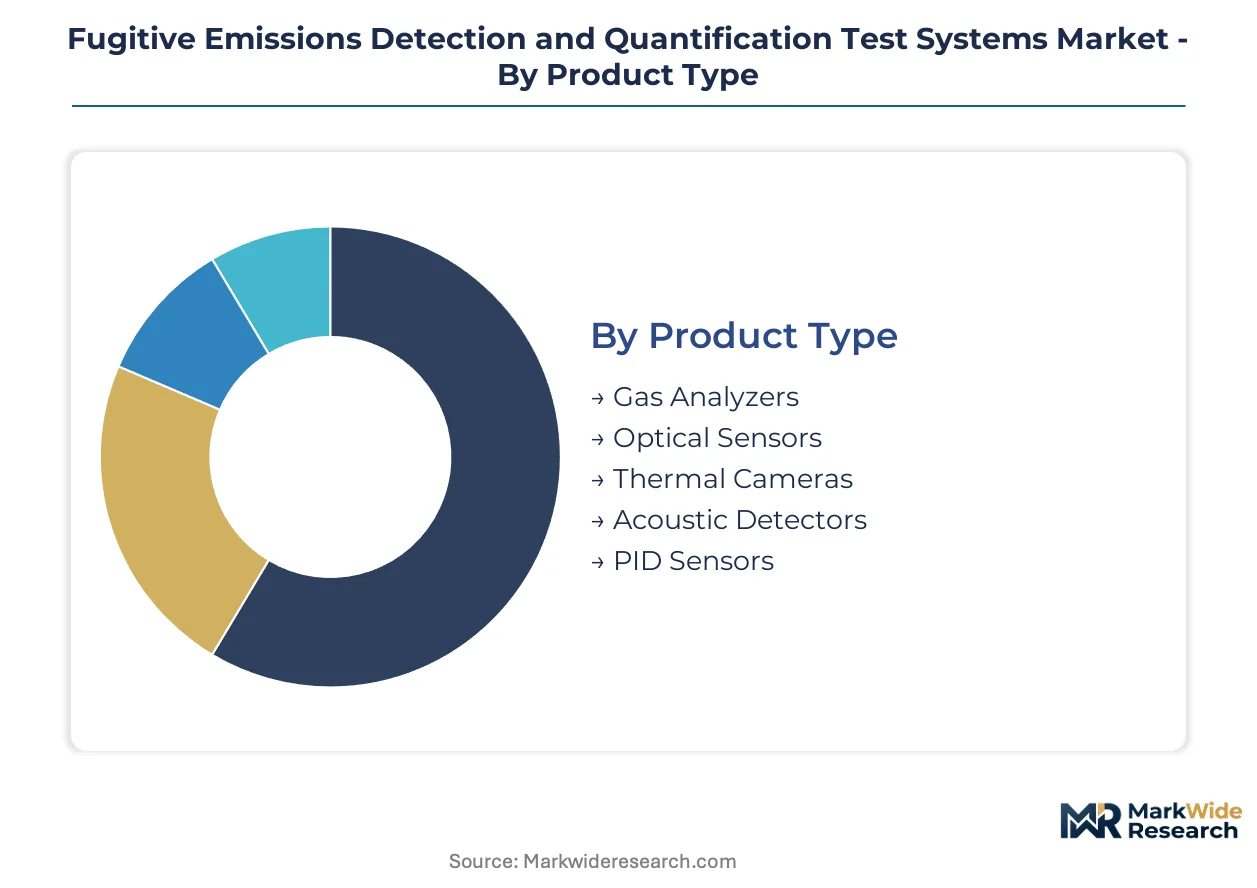
Segmentation in fugitive emissions detection reveals how procurement priorities diverge across facility types and regulatory exposure. Buyers select hardware configurations based on detection threshold requirements, survey frequency mandates, and integration complexity with existing control systems.
Product Type:
Capital allocation decisions hinge on the trade-off between detection sensitivity and deployment flexibility across fixed versus mobile applications.
- Thermal Cameras:Non-contact optical gas imaging systems detect hydrocarbon leaks through differential infrared absorption at parts-per-million thresholds. Demand concentrates at upstream well pads and compressor stations across the Permian Basin, where EPA leak detection frequency mandates drive rapid area coverage requirements.
- Optical Sensors:Tunable diode laser and quantum cascade laser instruments provide continuous point monitoring with quantification capabilities integrated into single hardware units. Midstream operators at Gulf Coast refining corridors specify these for automated waste emissions charge documentation under Inflation Reduction Act timelines.
- Gas Analyzers:Calibrated benchtop and portable units employing flame ionization or photoionization detection for laboratory-grade concentration measurement.
- Acoustic Detectors:Ultrasonic leak detection systems identify pressure-driven emissions through sound signature analysis without gas-specific calibration.
- PID Sensors:Photoionization detectors target volatile organic compound detection at parts-per-billion sensitivity for chemical manufacturing fence-line monitoring.
Thermal cameras lead on scale; optical sensors lead on momentum.
Technology:
Detection modality selection determines maintenance overhead, calibration intervals, and interoperability with emissions accounting platforms.
- Infrared:Absorption spectroscopy across near-infrared and mid-infrared bands dominates continuous monitoring architectures through proven reliability in hydrocarbon-specific detection.
- Laser:Tunable and quantum cascade laser systems unify detection with quantification, reducing instrument count at compressor stations where maintenance access is constrained.
- Electrochemical:Cell-based sensors offer cost-effective fixed-installation monitoring where parts-per-million sensitivity satisfies regulatory thresholds without optical complexity.
- Ultraviolet:UV fluorescence and absorption methods target sulfur compound and specific VOC species in refinery flare monitoring applications.
- Ultrasonic:Pressure-wave detection operates independently of gas composition, serving as a complementary trigger for optical confirmation systems.
Infrared technology holds installed base dominance; laser-based systems are climbing the fastest.
Application:
Facility type dictates detection frequency, emission source geometry, and integration requirements with process safety systems.
- Petrochemical Operations:Complex process unit networks with high valve and flange density demand multi-technology deployments combining thermal imaging for surveys with fixed optical sensors for continuous coverage.
- Gas Processing:Cryogenic separation and dehydration units generate concentrated methane leakage points where automated quantification systems satisfy EPA waste emissions charge documentation.
- Chemical Manufacturing:Batch reactor and storage tank operations require fence-line monitoring for VOC perimeter compliance under state-level air quality regulations.
- Waste Management:Landfill gas collection and anaerobic digester systems employ portable analyzers for surface emission monitoring and wellhead tuning.
- Refrigeration Monitoring:Industrial ammonia and fluorinated gas systems utilize electrochemical and infrared detectors for leak detection in enclosed machinery spaces.
Petrochemical operations anchor procurement volume; gas processing applications show the steepest expansion trajectory.
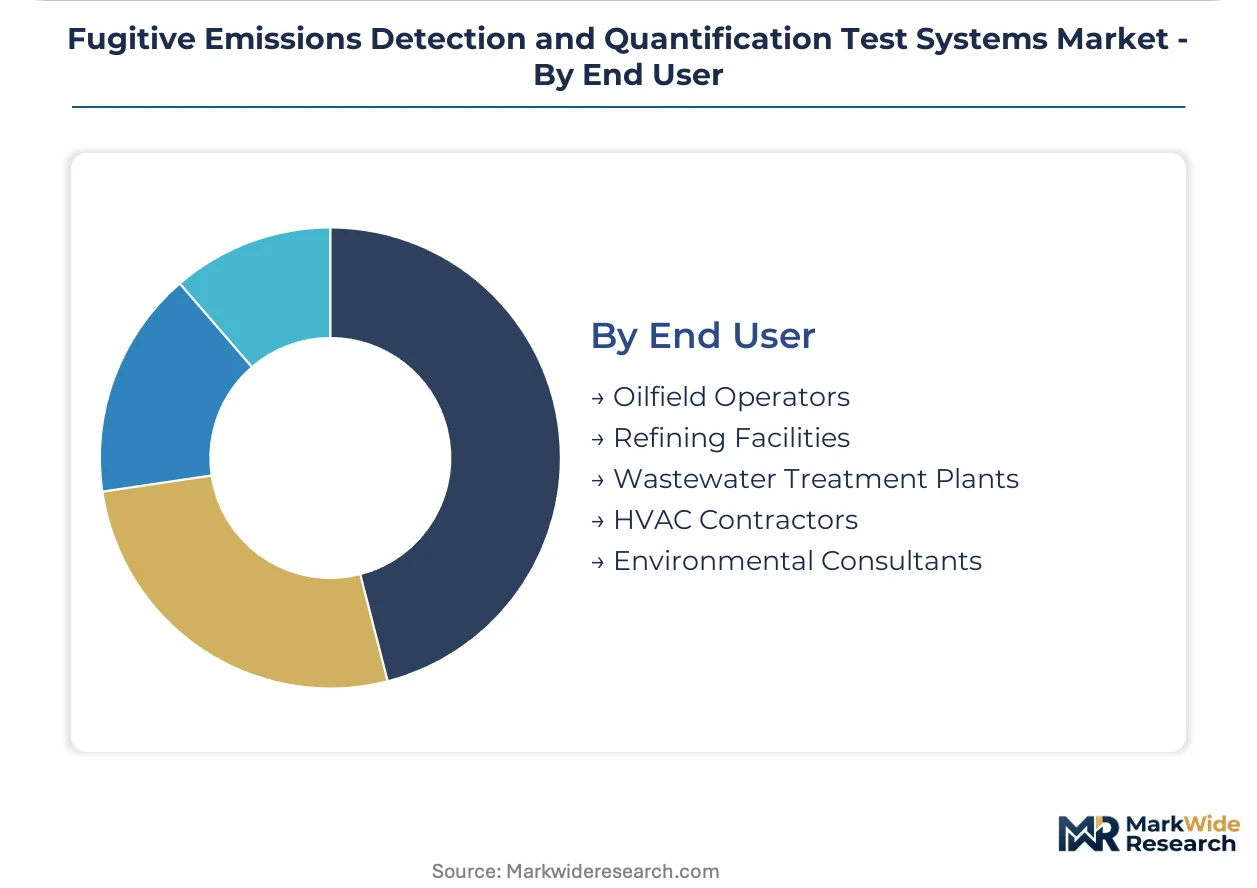
End User:
Organizational capability and regulatory exposure determine whether buyers favor capital ownership or outsourced verification services.
- Environmental Consultants:Third-party verification firms are assuming capital responsibility for sensor networks while charging per-quantified-emission fees, displacing traditional purchase arrangements most visibly in the Permian Basin.
- Oilfield Operators:Upstream producers face compressed compliance timelines under EPA supplemental proposals, accelerating deployment of automated systems that eliminate manual survey dependence.
- Refining Facilities:Integrated downstream complexes specify distributed sensor arrays that interface with legacy SCADA architectures without operational disruption.
- Wastewater Treatment Plants:Biogas recovery and odor control operations employ portable detection for digester integrity and collection system leak identification.
- HVAC Contractors:Commercial and industrial refrigeration service providers utilize handheld detectors for leak pinpointing during maintenance calls.
Oilfield operators represent the largest installed base; environmental consultants are gaining share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Specialized spectroscopy technicians and calibration engineers concentrate in Houston, Calgary, and Aberdeen, anchoring regional service capabilities for complex emissions quantification deployments.
United States
Permian Basin drilling density and Gulf Coast refining corridors generate concentrated procurement for continuous monitoring networks. EPA methane waste emissions charges under the Inflation Reduction Act compress compliance timelines toward automated quantification systems. West Texas and New Mexico well pads deploy networked sensor arrays to eliminate manual survey dependence.
Canada
Alberta oil sands operations and Saskatchewan conventional production drive demand for cold-weather-rated detection systems. Environment and Climate Change Canada methane regulations mandate quarterly leak surveys at upstream facilities. Calgary-based service firms anchor third-party verification capacity for cross-border operator compliance.
Germany
Certified reference material production clusters in industrial chemical corridors supply calibration gases across European markets. EU Green Deal methane strategy import standards create verification demand at LNG terminals and pipeline interconnections. Ruhr Valley industrial zones deploy fence-line monitoring for petrochemical complex perimeter compliance.
China
State-owned pipeline operators expand methane detection procurement under national dual carbon goals and MEE emissions inventory requirements. Sichuan-Chongqing shale gas development concentrates demand for portable quantification systems. Yangtze River Delta refining hubs integrate continuous monitoring with legacy distributed control architectures.
Saudi Arabia
Aramco infrastructure expansion and gas processing capacity additions drive procurement for compressor station monitoring systems. The national regulator's emissions intensity targets accelerate deployment of automated quantification at upstream facilities. Eastern Province gas processing complexes anchor regional adoption of integrated laser spectroscopy systems.
Fugitive Emissions Detection and Quantification Test Systems Market Competitive Landscape
Capital-heavy producers compete with asset-light designers across the technology stack, with integrated industrial conglomerates maintaining sensor fabrication capabilities while specialized software vendors supply analytics layers. The vendor base stratifies into three tiers: diversified industrial technology groups with distributed control heritage, pure-play emissions detection specialists, and environmental service firms assuming equipment ownership. Consolidation pressure intensifies as operators seek single-source accountability for hardware, calibration, and regulatory reporting. Dominant competitive moves include vertical integration into cloud-based emissions accounting platforms and geographic expansion through environmental consultant channel partnerships.
Among diversified industrial technology groups, Teledyne FLIR, Honeywell, and Baker Hughes exemplify contrasting strategic postures. Teledyne FLIR occupies a position within thermal imaging heritage, anchoring optical gas imaging deployments through detector array capabilities. Honeywell sits within distributed control system architecture extension, representing emissions management software layer integration. Baker Hughes exemplifies integrated digital platform convergence, combining hardware sensor production with cloud analytics for continuous monitoring applications.
| Leading Market Players |
|---|
| Teledyne FLIR |
| Thermo Fisher Scientific |
| ABB |
| Honeywell |
| Sensirion Connected Solutions |
| Baker Hughes |
| SeekOps |
| Alliance Technical Group |
| Southwest Research Institute |
| Others |
Pricing and Supply Chain Analysis
Specialized spectroscopy technicians clustering in Houston, Calgary, and Aberdeen create labor-cost differentials that widen pricing-tier spreads between premium optical systems and economy-grade electrochemical installations. Calibration engineer scarcity in North American energy corridors elevates service-bundled pricing for continuous monitoring architectures while compressing margins on standalone hardware sales.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels dominates procurement patterns, with ISO 14064 certification grade and after-sales calibration service depth as primary differentiation drivers. Cost compression in economy-tier electrochemical sensors is intensifying because Chinese manufacturing scale is flooding fixed-installation markets. Environmental consultants exhibit highest price sensitivity due to per-quantified-emission fee structures, while integrated oilfield operators absorb premium pricing for automated quantification capabilities.
Supply Chain Analysis
Transatlantic freight costs for certified reference gases expose buyers to logistics friction that amplifies total cost of ownership for European calibration material imports. Infrared detector array fabrication concentrates in the United States, Germany, and Japan, while precision optics sourcing rests on Taiwanese lens grinding and German coating expertise. Single-source vulnerability in quantum cascade laser chip production threatens midstream operator deployment timelines. Distribution runs through environmental consulting channel partnerships that assume capital responsibility for sensor networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a geographic-arbitrage play: EPA methane waste emissions charges impose compliance cost structures in the United States that exceed European baseline requirements, creating margin expansion opportunities for vendors with cross-regional certification capabilities.
For Market Incumbents: Hedge against electrochemical commoditization by deepening in-house production of quantum cascade laser spectroscopy units, locking in chip supply from German specialty foundries. Defend installed base positions through backward integration into cloud-based emissions accounting platforms that reduce customer switching costs. Prioritize certification investment for EU Green Deal methane strategy import standards at LNG terminals. For New Entrants and Emerging Players: The $800-to-$2,400 per-unit price-point gap between premium thermal camera systems and economy electrochemical sensors opens white-space targeting for drone-mounted sensor convergence products. Environmental consultant channel partnerships in the Permian Basin represent the most penetrable entry vector. Pursue go-to-market positioning around per-quantified-emission fee structures that displace traditional capital purchase arrangements. For Investors and Strategic Acquirers: Industrial technology conglomerates with distributed control heritage are the most active acquirer in this space, consolidating pure-play emissions detection specialists to fill software layer gaps. Long-term viability hinges on interoperability with real-time emissions accounting platforms migrating toward automated regulatory submission. Target acquisition archetypes: environmental service firms with captive sensor network ownership and calibration infrastructure. Watch for EPA supplemental proposal enforcement dates as inflection indicators for capital deployment velocity.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Detector Fabrication | Captive supply of infrared arrays insulates margins from German and Japanese component pricing volatility. |
| Cloud Analytics Platform Development | Honeywell and Baker Hughes architectures demonstrate emissions data monetization beyond hardware sale. |
| Environmental Consultant Channel Partnerships | Permian Basin drilling economics favor operational expenditure structures over capital ownership. |
| EU Green Deal Certification Investment | LNG terminal verification demand at Rotterdam and Hamburg creates service revenue expansion. |
| Drone-Mounted Sensor Convergence | SeekOps and Alliance Technical Group deployments prove inaccessible terrain survey automation viability. |
Research Methodology
Multiple input streams — primary interviews with plant engineers and environmental compliance officers, secondary validation through EPA regulatory filings and SEC 10-K equipment procurement disclosures, customs data on infrared detector array trade flows — were reconciled through bottom-up and top-down triangulation. Conversations with maintenance directors at Permian Basin well pads, calibration service technicians in Calgary, and midstream operator procurement teams informed sensitivity threshold and deployment frequency assumptions. Trade publications from the American Petroleum Institute and European Commission methane strategy documentation provided secondary anchor points.
Historical capital expenditure patterns were cross-referenced against panel input from oilfield service executives to model adoption curves across the projection horizon. Segmentation dimensions included product type, detection technology, facility application, and end-user organizational structure. CAGRs were derived from equipment shipment volumes reconciled against regulatory mandate enforcement timelines. Industry-specific forecast inputs incorporated EPA waste emissions charge escalation schedules and EU import standard proposal progression.
The model assumes a particular technology adoption path; alternative pathways for quantum cascade laser spectroscopy cost reduction would alter the outlook for electrochemical sensor displacement. Forecasts reflect assumptions about regulatory enforcement consistency and calibration gas supply chain stability. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Testing Equipment
Supercritical Fluid Chromatography Market
Testing Equipment
Paint Tester Market
Testing Equipment
Laboratory Centrifuge and Accessories Market
Testing Equipment
High Performance Liquid Chromatography-Tandem Mass Spectrometry System Market
Testing Equipment
Glass Testing Equipment Market
Testing Equipment
Chemical Testing Services Market
Testing Equipment
HPLC Market
Testing Equipment
Flammability Test Chamber Market
Testing Equipment
Chromatography Data Systems Market
Testing Equipment
Mud Sediment Tester Market
Testing Equipment
Melting Point Apparatus Market
Testing Equipment
Global Circular Dichroism (CD) Spectrometers Market
Testing Equipment
High-Temperature Corrosion and Creep Testing Equipment for Process Industries Market
Testing Equipment
Chromatography Accessories and Consumables Market
Testing Equipment
PFAS Ultra-Trace Water Analysis Test Instruments Market
Testing Equipment
Stack Emissions Real-Time Speciation and Compliance Test Systems Market