
 Analytical Gel Permeation Chromatography Market | 2026-2036
Analytical Gel Permeation Chromatography Market Size, Share, and Industry Trends Forecast 2026-2036
Analytical Gel Permeation Chromatography Market Analytics
Software-defined data analytics and subscription-based chromatography informatics is rebalancing how laboratories procure GPC capabilities. Agilent Technologies leverages its OpenLab platform to sustain recurring revenue from pharmaceutical clients. Waters Corporation anchors its position through proprietary column chemistries and controlled informatics ecosystems. Shimadzu Corporation competes by extending modular instrument architectures that reduce capital barriers for mid-sized labs.
Analytical gel permeation chromatography separates dissolved macromolecules by hydrodynamic volume using porous stationary-phase columns with defined pore-size distributions, typically operating with organic or aqueous mobile phases at controlled flow rates and temperatures. The technique determines molecular weight distributions, polydispersity indices, and branching structures for synthetic polymers and biologics. Instruments dominate hardware revenue due to detector complexity and precision engineering requirements, while polymer characterization commands the largest application share from materials science and pharmaceutical excipient development. Quality control applications in biotech manufacturing represent the fastest-expanding segment as regulators mandate batch-to-batch molecular consistency.
FDA enforces ICH Q6B guidelines that require molecular weight verification for biologic license applications, directly expanding GPC demand for protein aggregate detection. EPA methods for polymer microplastic identification in environmental matrices are proliferating across state laboratories, while REACH in Europe mandates polymer registration data that depends on molecular weight distribution analytics. Stakeholders must monitor evolving pharmacopeial harmonization between USP, EP, and JP monographs for size-exclusion chromatography, as divergence in acceptance criteria will fragment instrument validation protocols and reshape service contract structures.
Market Dynamics
Software-defined analytics platforms are restructuring how pharmaceutical laboratories procure GPC capabilities, shifting capital-heavy instrument purchases toward recurring subscription models that embed compliance validation and remote diagnostics.
Growth Catalysts
- ICH Q6B harmonization:FDA and EMA alignment on molecular weight verification for biologic license applications mandates GPC deployment for protein aggregate detection across contract manufacturing organizations.
- Polymer microplastic identification:EPA method proliferation across US state laboratories creates sustained replacement demand for high-resolution columns and multi-detector configurations.
- Germany's chemical corridor concentration:BASF, Covestro, and Lanxess facilities in Ludwigshafen and Leverkusen anchor European demand for continuous polymer characterization in materials science.
Market Restraints
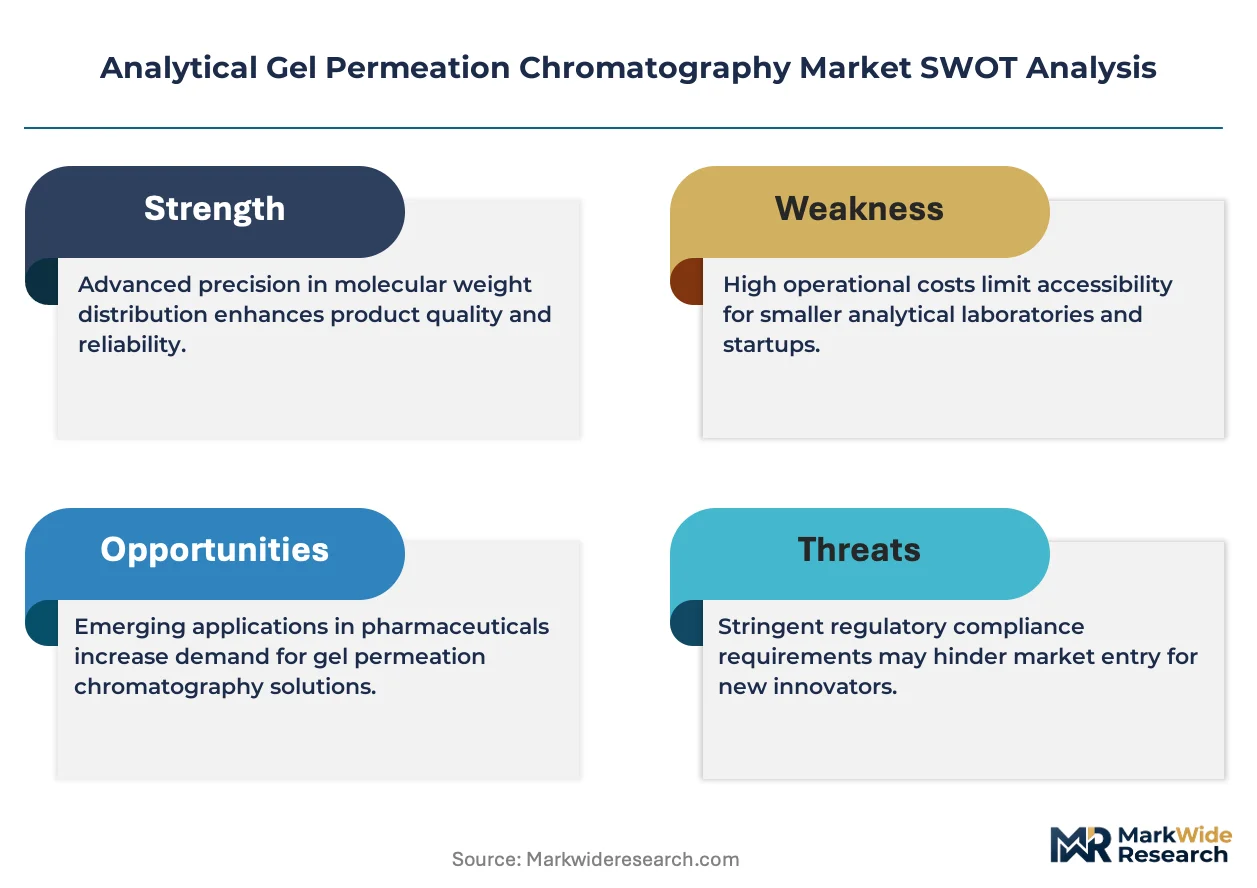
- Helium supply volatility:GPC-IR and light scattering detectors depend on helium carrier gas, with US Bureau of Land Management auction disruptions causing 40-60% price spikes that compress service contract margins.
- Column chemistry concentration:Proprietary styrene-divinylbenzene particle synthesis capabilities concentrate among three Japanese and US suppliers, creating single-source vulnerability for sub-5-micron high-pore-volume media.
- Mass spectrometry substitution:Native mass spec and charge detection mass spec are displacing GPC for some protein oligomerization studies in early-stage biologic development.
Strategic Opportunities
- India's biologics manufacturing expansion:CDSCO's 2023 biosimilar guidance tightening molecular comparability requirements creates first-mover advantage for GPC vendors establishing local service infrastructure in Hyderabad and Bengaluru.
- Continuous manufacturing integration:Real-time GPC PAT (Process Analytical Technology) deployment for polymerization reactor control enables per-kilogram pricing models that decouple revenue from capital equipment cycles.
- EU Green Deal polymer circularity:REACH registration data requirements for recycled polymer feedstocks mandate molecular weight distribution analytics for chemical recycling qualification protocols.
Industry Challenges
- Chromatography data system integration:Pharmaceutical quality control laboratories struggle to embed GPC workflows within centralized LIMS architectures due to vendor-specific file formats and audit trail incompatibilities.
- Metrology technician scarcity:Multi-detector calibration and Mark-Houwink parameter validation require specialized expertise that concentrates among aging cohorts in Germany, Switzerland, and Massachusetts.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Analytical Gel Permeation Chromatography Market |
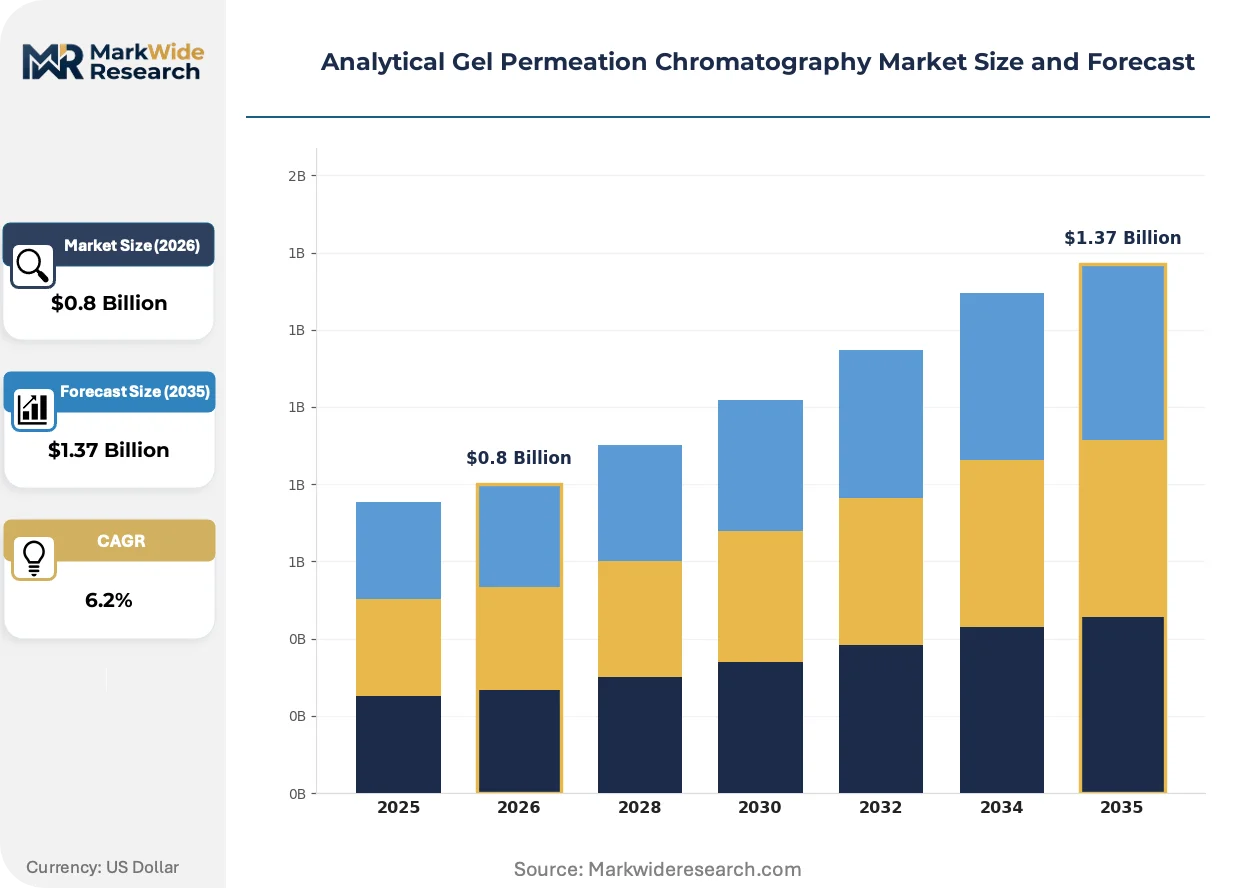
| Market Size in 2026 | $0.8 Billion |
| Market Size in 2035 | $1.37 Billion |
| CAGR (2026 – 2036) | 6.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Column Chromatography, Instruments, Reagents, Software End User: Pharmaceuticals, Biotech, Academia, Environmental Testing Application: Polymer Characterization, Quality Control, Research & Development, Formulation Technology: High-Performance Liquid Chromatography, Ultra-Performance Liquid Chromatography, Pulsed Field Gradient, Others |
| Companies Covered | Agilent Technologies, Waters Corporation, Shimadzu Corporation, Thermo Fisher Scientific, Tosoh Corporation, Bio-Rad Laboratories, Gilson Inc., Malvern Panalytical, Polymer Char, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analytical Gel Permeation Chromatography Market Evolving Landscape
Multi-angle light scattering detectors paired with micro-volume flow cells are compressing sample requirements and analysis times, enabling at-line deployment in continuous bioprocessing environments previously reserved for offline quality control.
Micro-volume multi-angle light scattering (MALS) detectors with integrated viscometry are overtaking conventional concentration detectors for absolute molecular weight determination in biopharmaceutical quality control. Contract development and manufacturing organizations in the Boston-Cambridge corridor are adopting these configurations within 18-month replacement cycles. The technology is overtaking refractive index detection for high-value biologics where aggregate quantification accuracy directly impacts batch release decisions.
REACH polymer registration requirements under ECHA's 2023 updated guidance are mandating molecular weight distribution data for all imported synthetic polymers above one ton annual volume. European compounders and distributors must now maintain GPC analytics capabilities or outsource to certified laboratories. Materials science divisions at polymer producers in Germany and the Netherlands are responding by embedding automated GPC systems within technical service laboratories.
Subscription-based chromatography informatics is displacing perpetual license models among mid-sized pharmaceutical quality control departments. Waters' Empower and Agilent's OpenLab platforms now structure pricing around sample throughput tiers rather than seat counts. This shift is most visible among generic drug manufacturers in India and Eastern Europe seeking to align analytical costs with fluctuating batch volumes.
Analytical Gel Permeation Chromatography Market Segmentation
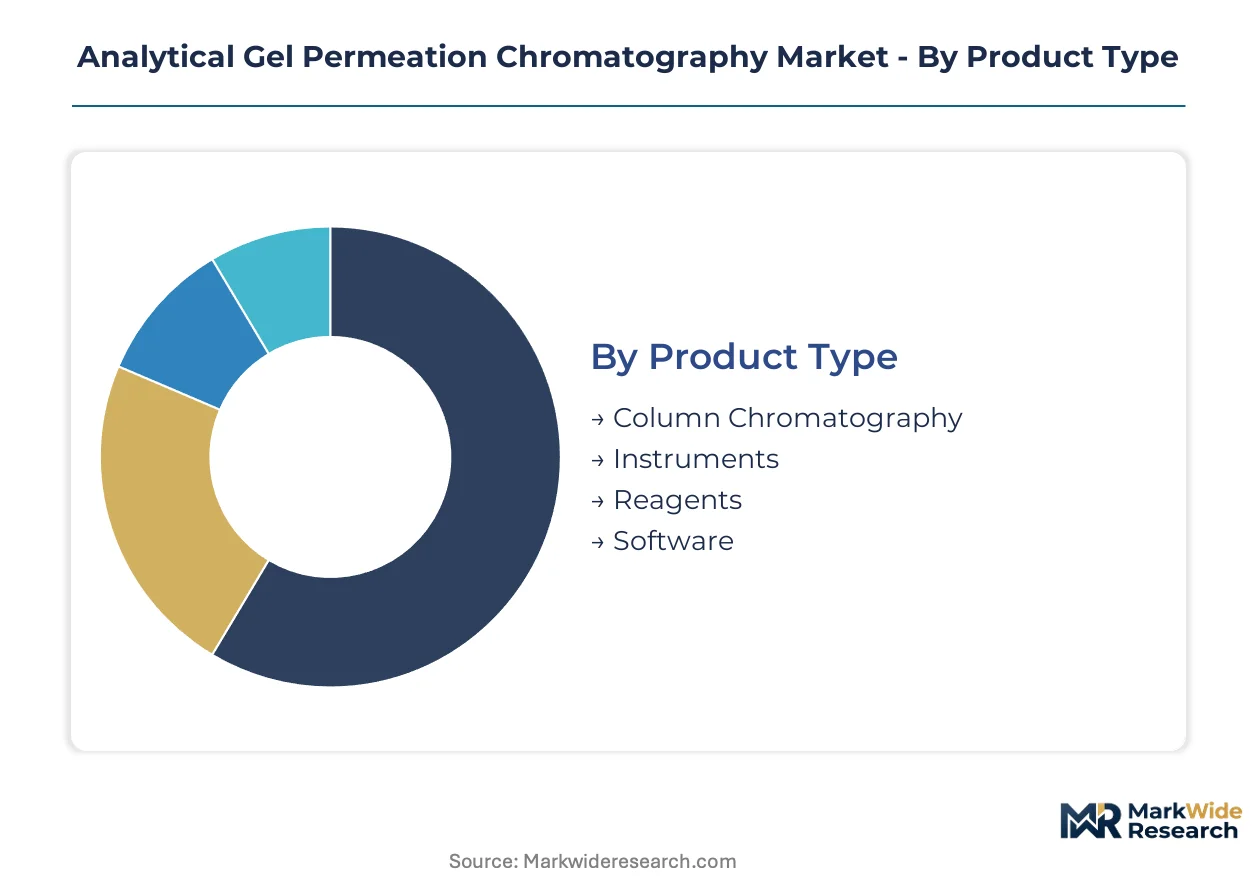
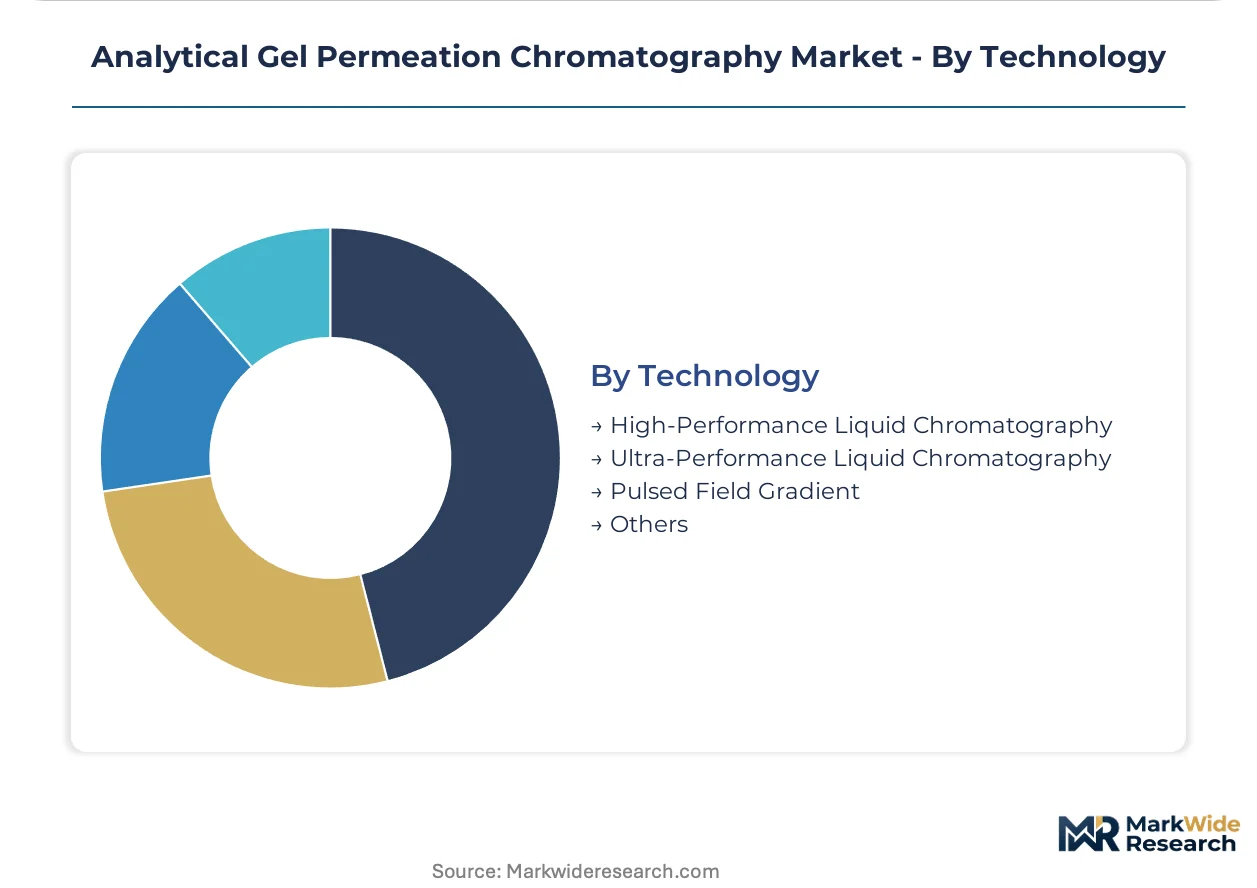
GPC market segmentation reflects divergent procurement patterns between regulated pharmaceutical quality control and flexible research environments. Product architecture and end-use compliance requirements create distinct margin profiles across each category.
Product Type:
Customization intensity spans from commoditized consumables to engineered systems requiring extensive validation protocols.
- Instruments:Multi-detector configurations integrating refractive index, light scattering, and viscometry dominate capital expenditure. Pharmaceutical manufacturers in Germany and Massachusetts prioritize systems with embedded 21 CFR Part 11 compliance for biologic batch release.
- Column Chromatography:Styrene-divinylbenzene particle synthesis with sub-5-micron pore-size distributions determines resolution performance. Proprietary surface chemistries from Japanese suppliers command premium positioning in high-throughput polymer laboratories.
- Reagents:Certified reference standards for molecular weight calibration face tightening pharmacopeial harmonization requirements across USP, EP, and JP monographs.
- Software:Subscription-based chromatography informatics with audit trail integration displaces perpetual licenses in mid-sized quality control departments.
Leading the category by volume: Column Chromatography. Expanding most quickly: Software.
End User:
Regulatory burden intensity separates price-insensitive compliance-driven buyers from cost-conscious research segments.
- Pharmaceuticals:ICH Q6B guidelines mandate molecular weight verification for biologic license applications, forcing GPC deployment for protein aggregate detection. FDA enforcement actions against data integrity violations accelerate instrument replacement cycles.
- Biotech:CDMOs in the Boston-Cambridge corridor adopt micro-volume MALS configurations within compressed 18-month replacement timelines for high-value biologics.
- Environmental Testing:EPA method proliferation for polymer microplastic identification across state laboratories generates sustained column and detector demand.
- Academia:Grant-funded polymer chemistry programs concentrate procurement in Germany's chemical corridor and Netherlands materials science institutes.
Dominating revenue contribution: Pharmaceuticals. Gaining share fastest: Biotech.
Application:
Volume scale and margin structure diverge between routine quality control and exploratory research workflows.
- Quality Control:Batch-to-batch molecular consistency requirements in biotech manufacturing enforce standardized SOPs with minimal method flexibility. Regulatory audit frequency drives service contract attachment rates above hardware margins.
- Polymer Characterization:REACH registration mandates for molecular weight distribution data compel European compounders to maintain internal GPC capabilities or outsource to certified laboratories.
- Research & Development:Early-stage biologic development faces displacement pressure from native mass spectrometry for protein oligomerization studies.
- Formulation:Excipient molecular weight verification supports complex generic approvals under tightened FDA ANDA requirements.
Highest volume segment: Polymer Characterization. Steepest expansion trajectory: Quality Control.
Technology:
Performance tiering separates resolution capabilities and corresponding capital intensity across laboratory scales.
- Ultra-Performance Liquid Chromatography:Sub-2-micron particle columns deliver accelerated analysis times for at-line PAT deployment in continuous polymerization reactor control.
- High-Performance Liquid Chromatography:Conventional 3-5 micron configurations retain dominance in routine quality control where method transfer stability outweighs speed requirements.
- Pulsed Field Gradient:Specialized diffusion coefficient measurements address advanced polymer branching structure analysis in materials science research.
- Others:Emerging microfluidic and chip-based separations target sample-limited biopharmaceutical applications.
Technology leader by installed base: High-Performance Liquid Chromatography. Climbing the fastest: Ultra-Performance Liquid Chromatography.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Instrument manufacturing concentrates in Japan, the United States, and Germany, while consumption spreads across pharmaceutical clusters in Switzerland, India, and the Netherlands. This production-consumption divide shapes regional service infrastructure investments and calibration expertise distribution.
United States
FDA ICH Q6B enforcement drives GPC deployment for protein aggregate detection in biologic license applications. The Boston-Cambridge corridor anchors North American demand as CDMOs compress replacement cycles for micro-volume MALS configurations. Massachusetts and California laboratories prioritize 21 CFR Part 11 compliant systems for batch release workflows.
Germany
BASF, Covestro, and Lanxess facilities in Ludwigshafen and Leverkusen sustain European polymer characterization demand. REACH registration requirements under ECHA guidance mandate molecular weight distribution analytics for imported synthetic polymers. The chemical corridor between North Rhine-Westphalia and Baden-Württemberg embeds automated GPC within technical service laboratories.
Japan
PMDA harmonization with FDA biologic guidelines accelerates GPC adoption for biosimilar molecular comparability studies. METI-supported materials science programs concentrate procurement in Osaka and Nagoya polymer research institutes. Domestic column chemistry suppliers control proprietary styrene-divinylbenzene particle synthesis for sub-5-micron high-pore-volume media.
India
CDSCO's 2023 biosimilar guidance tightening molecular comparability requirements creates first-mover opportunities for vendors establishing local service infrastructure. Hyderabad and Bengaluru biologics manufacturing clusters drive demand for quality control GPC systems. Generic drug manufacturers in Gujarat and Maharashtra adopt subscription-based chromatography informatics to align analytical costs with batch volumes.
Switzerland
Swissmedic enforcement of molecular weight verification standards supports GPC deployment for biologic purity testing. Basel's pharmaceutical manufacturing concentration requires continuous polymer characterization for excipient development. Materials science divisions at specialty chemical producers embed multi-detector configurations within quality control workflows.
Analytical Gel Permeation Chromatography Market Competitive Landscape
Capital-heavy instrument manufacturers compete with asset-light informatics specialists across the GPC value chain. The market structures around three tiers: integrated analytical platform vendors controlling detector-column-software ecosystems; specialized column chemistry suppliers with proprietary particle synthesis capabilities; and regional service providers embedding compliance validation expertise. Consolidation pressure concentrates among mid-scale laboratories seeking subscription-based procurement models. Strategic moves center on informatics platform expansion and geographic service infrastructure buildout.
Within the integrated platform tier, Agilent Technologies, Waters Corporation, and Shimadzu Corporation occupy positions defined by their control over detector architectures and chromatography informatics ecosystems. Agilent leverages recurring revenue through subscription-based OpenLab deployments. Waters anchors positioning through proprietary column chemistries and controlled Empower ecosystems. Shimadzu extends modular instrument architectures that reduce capital barriers for mid-sized laboratories in India and Eastern Europe.
| Leading Market Players |
|---|
| Agilent Technologies |
| Waters Corporation |
| Shimadzu Corporation |
| Thermo Fisher Scientific |
| Tosoh Corporation |
| Bio-Rad Laboratories |
| Gilson Inc. |
| Malvern Panalytical |
| Polymer Char |
| Others |
Value Network & Pricing Analysis
REACH polymer registration requirements under ECHA guidance gate qualified supply of certified GPC columns and reagents, restricting premium-tier pricing access to vendors with validated molecular weight standard traceability and pharmacopeial compliance documentation.
Pricing Analysis
Margin tightening in instrument tiers reflects helium supply volatility and detector complexity premiums. Three-tier pricing structure across premium, standard, and economy levels separates 21 CFR Part 11 compliant multi-detector systems from modular configurations and entry-grade academic units. Certification grade and after-sales service bundling drive price differentiation. Cost compression accelerates in mid-sized laboratory segments as subscription-based chromatography informatics displaces perpetual licenses. Generic drug manufacturers in India and Eastern Europe exhibit highest price sensitivity; biotech CDMOs in Massachusetts and Switzerland demonstrate lowest.
Supply Chain Analysis
Single-source vulnerability sits with Japanese and US suppliers controlling proprietary styrene-divinylbenzene particle synthesis for sub-5-micron high-pore-volume media. Manufacturing concentrates in Japan, the United States, and Germany for instruments; column chemistry production draws from Japan and the United States. Raw material dependencies include high-purity helium carrier gas, specialized fused silica capillaries, and certified polystyrene molecular weight standards. Supply chain risk centers on Bureau of Land Management auction disruptions causing helium price spikes. Distribution runs through direct sales forces for pharmaceutical manufacturers and authorized distributors for academic and environmental testing segments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Control over proprietary column chemistries and captive informatics ecosystems is accelerating vertical-integration races among platform vendors seeking to lock in recurring revenue streams.
For Market Incumbents: To counter native mass spectrometry substitution in early-stage biologic development, Agilent Technologies and Waters Corporation should deepen backward integration into styrene-divinylbenzene particle synthesis and expand OpenLab and Empower subscription penetration among mid-sized quality control departments in India and Eastern Europe. Certification investment in 21 CFR Part 11 compliance modules remains essential for biotech batch release workflows. For New Entrants and Emerging Players: Mid-sized contract manufacturing organizations in Hyderabad and Bengaluru represent underserved buyer archetypes with tightening CDSCO biosimilar guidance requirements. First-mover advantage awaits vendors establishing local service infrastructure with rapid calibration response capabilities. White-space targets include continuous manufacturing PAT integration for polymerization reactor control and chemical recycling qualification protocols under EU Green Deal mandates. A per-kilogram pricing model decouples revenue from capital equipment cycles. For Investors and Strategic Acquirers: CDSCO's 2023 biosimilar guidance tightening molecular comparability requirements is the leading indicator that Indian biologics manufacturing expansion will sustain GPC demand acceleration. Long-term viability over the next decade hinges on informatics platform recurring revenue attachment rates rather than instrument hardware margins. Acquisition targets should prioritize regional service providers with embedded compliance validation expertise in Switzerland and Massachusetts. Monitor helium supply auction outcomes as the critical inflection signal for detector cost structure pressure.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Column Chemistry | Captive supply of sub-5-micron styrene-divinylbenzene media reduces single-source vulnerability for Japanese and US suppliers. |
| Subscription-Based Informatics Expansion | OpenLab and Empower platform penetration aligns analytical costs with fluctuating batch volumes at Indian generic manufacturers. |
| Local Service Infrastructure Buildout | Hyderabad and Bengaluru facilities capture CDSCO biosimilar guidance compliance demand from biologics manufacturing clusters. |
| Continuous Manufacturing PAT Integration | Real-time GPC deployment for polymerization reactor control enables per-kilogram pricing models beyond capital equipment cycles. |
| Green Certification Program Alignment | REACH registration data capabilities for recycled polymer feedstocks qualify vendors for EU Green Deal chemical recycling protocols. |
Research Methodology
SEC 10-K filings, ECHA guidance documents, and FDA ICH Q6B enforcement records formed the secondary backbone of this analysis. Primary interviews with chromatography informatics product managers, pharmaceutical quality control laboratory directors, polymer characterization scientists at BASF and Covestro facilities, and regulatory affairs specialists at CDSCO and PMDA validated demand assumptions. Bottom-up and top-down triangulation cross-checked instrument shipment data against end-user procurement patterns across Germany's chemical corridor and the Boston-Cambridge biotech cluster.
Bottom-up modeling aggregated segment-level demand across product type, end user, application, and technology dimensions, while top-down approaches anchored total market scale against macroeconomic indicators and industry association data. Segmentation by deployment model, organization size, vertical, integration complexity, and regional regulatory cluster structured the analytical framework across the projection horizon. CAGRs derived from historical trajectory analysis and forward-looking regulatory enforcement intensity, with helium supply volatility and pharmacopeial harmonization progress serving as key forecast inputs.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to ICH Q6B pharmacopeial divergence between USP, EP, and JP monographs, mass spectrometry substitution rates in protein oligomerization studies, and helium auction disruption frequency. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Testing Equipment
Chemical Detection Equipment Market
Testing Equipment
Hydrogen Gas Analyzers Market
Testing Equipment
Laboratory Filtration Equipment and Supplies Market
Testing Equipment
Durability Testing Systems Market
Testing Equipment
Supercritical Fluid Chromatography (SFC) System Market
Testing Equipment
In-Line UV-Vis Spectroscopy Market
Testing Equipment
Europe Non-Destructive Testing Market
Testing Equipment
Rubber Testing Equipment Market
Testing Equipment
Water Penetration Tester Market
Testing Equipment
FTIR Fuel Analyzer Market
Testing Equipment
High Performance Liquid Chromatography-Tandem Mass Spectrometry System Market
Testing Equipment
Water Test Kits Market
Testing Equipment
Global Trace Metal Analysis Market
Testing Equipment
Ultrasonic Testing Market
Testing Equipment
Laboratory Mixer Market
Testing Equipment
Global Insulation Testers Market