
 Global Insulation Testers Market | 2026-2036
Global Insulation Testers Market Size, Share, and Industry Trends Forecast 2026-2036
Global Insulation Testers Market Outlook
Equipment leasing and project-based financing is tilting competitive dynamics toward vendors with asset-light service models. Fluke Corporation leverages its calibration network to sustain recurring revenue streams across North American industrial accounts. Megger anchors its position through deep specialization in high-voltage cable diagnostics for utility infrastructure.
Insulation testers are electrical safety instruments that apply controlled DC voltage—typically 250V to 15kV—to measure resistance across insulating materials and detect degradation before catastrophic failure. The devices serve critical functions in preventing equipment damage, ensuring personnel safety, and validating compliance with electrical installation codes. Handheld insulation testers dominate volume shipments due to portability requirements among electrical contractors, while digital insulation resistance testers command premium positioning through data logging and Bluetooth connectivity features. Smart insulation testing technology represents the fastest-expanding segment as utilities integrate predictive analytics platforms with field instrumentation.
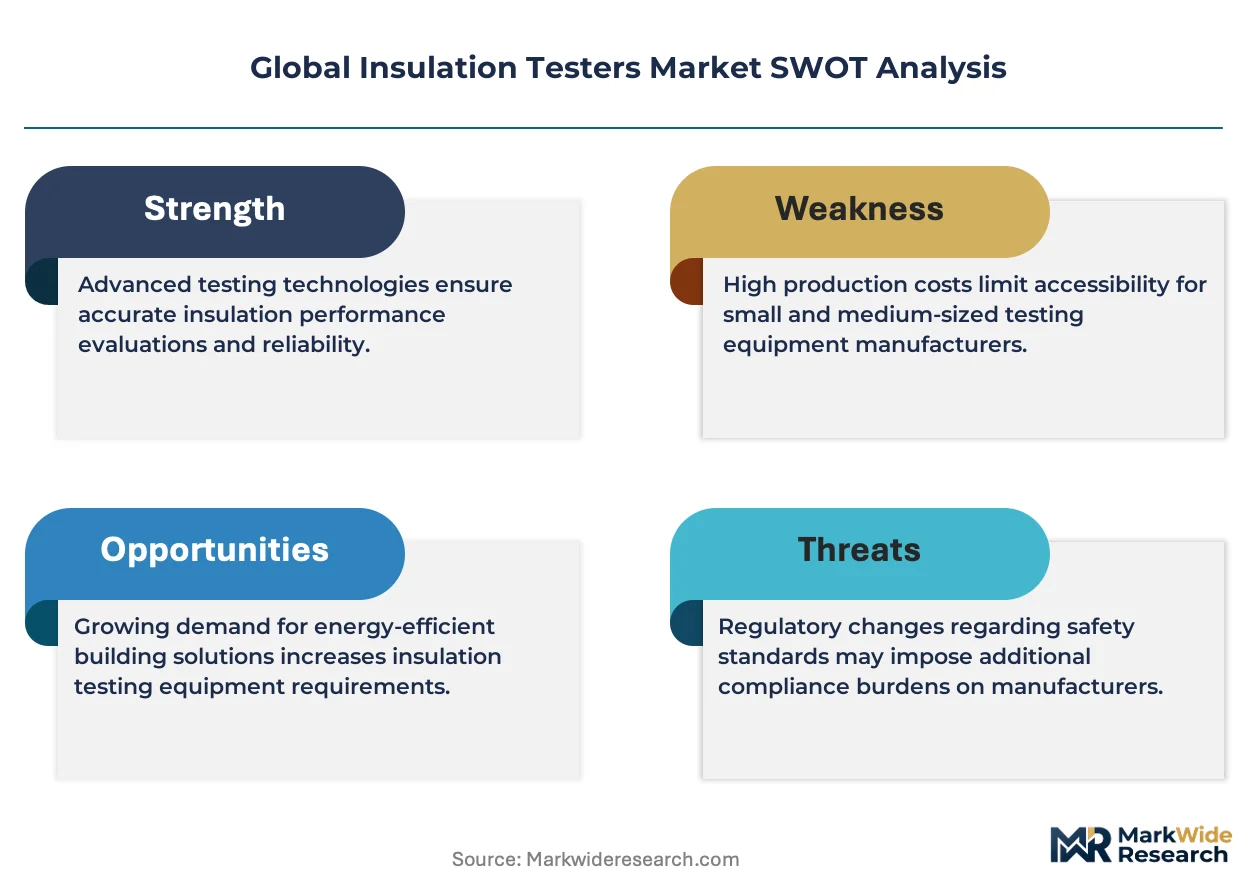
FDA oversight of medical device electrical safety, OSHA lockout-tagout enforcement, and IEC 61543 international standards collectively mandate periodic insulation verification across healthcare, industrial, and energy facilities. The European Union's CE marking requirements and REACH substance restrictions further shape product design and material selection for manufacturers serving EU member states. Stakeholders must monitor evolving smart grid interoperability protocols and embedded cybersecurity certifications as connected testers become standard deployment configurations.
Market Dynamics
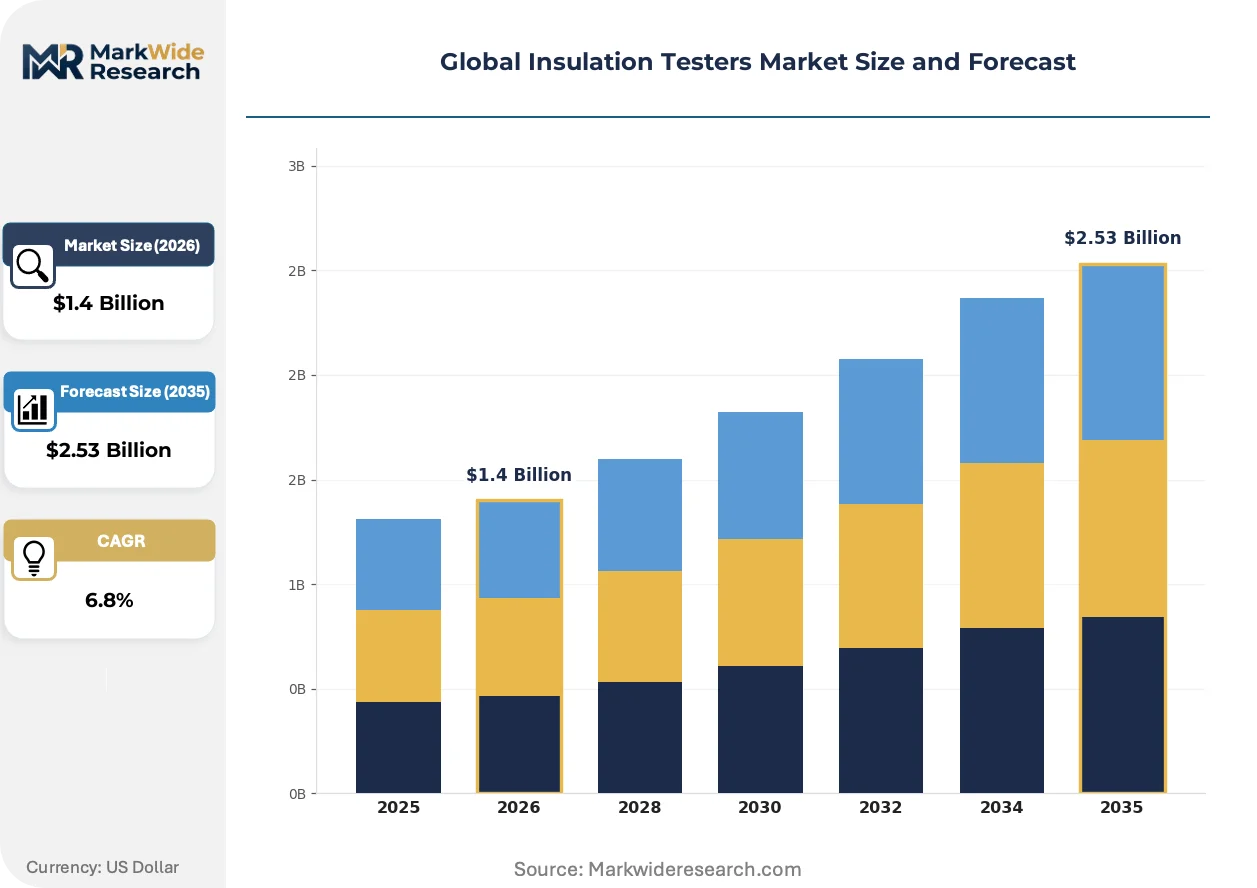
Smart grid digitization and IEC 61543 safety mandates are compressing replacement cycles for analogue insulation testers across electric utilities and industrial facilities worldwide.
Growth Catalysts
- Smart grid interoperability mandates:IEC 61850 protocol adoption in Germany, the United States, and Japan forces utilities to deploy digital testers with embedded communication modules for predictive maintenance platforms.
- OSHA lockout-tagout enforcement:Stricter workplace electrical safety audits in US manufacturing plants and healthcare facilities drive periodic insulation verification requirements.
- Industrial plant modernization:Germany's chemical and automotive sectors accelerate replacement of legacy testing equipment to meet CE marking and REACH substance compliance.
Market Restraints
- Semiconductor input volatility:Supply concentration for ADC chips and precision resistors in East Asian foundries creates production scheduling uncertainty for digital tester manufacturers.
- Calibration infrastructure gaps:Remote mining and offshore oil platforms in Australia, Brazil, and Norway lack accredited calibration laboratories, limiting digital tester deployment.
- Skilled technician scarcity:Shortages of certified high-voltage testing engineers constrain field deployment capacity for advanced diagnostic units.
Strategic Opportunities
- Equipment-as-a-service models:Leasing platforms with embedded calibration services penetrate US and German industrial accounts seeking to convert capex to opex.
- Medical device electrical safety:FDA oversight of hospital equipment maintenance creates dedicated demand for portable insulation testers in US healthcare networks.
- Bluetooth-enabled data logging:Convergence of field instrumentation with cloud analytics platforms opens utility digitization contracts in Japan and South Korea.
Industry Challenges
- Cybersecurity certification timelines:Embedded firmware for connected testers must achieve IEC 62443 compliance, extending product launch cycles by 8-14 months.
- Legacy system integration friction:Digital testers face protocol incompatibility with decades-old switchgear monitoring systems in European heavy industry.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Insulation Testers Market |
| Market Size in 2026 | $1.4 Billion |
| Market Size in 2035 | $2.53 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Handheld Insulation Testers, Cable Fault Testers, Multi-Function Testers, Digital Insulation Resistance Testers End User: Electrical Contractors, Utilities, Manufacturing Plants, Maintenance Services Technology: Analogue, Digital, Smart Insulation Testing, Automated Testing Technology Application: Building Inspection, Power Generation, Telecommunications, Electrical Maintenance |
| Companies Covered | Fluke Corporation, Megger, Yokogawa Electric Corporation, Hioki Corporation, Kyoritsu Electrical Instruments, Eaton Corporation, Chauvin Arnoux Metrix, B&K Precision Corporation, Meco Instruments Pvt. Ltd., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Insulation Testers Market Strategic Shifts
Connected diagnostics and predictive analytics platforms are redefining how insulation resistance data generates actionable maintenance intelligence across asset-intensive industries.
Cloud-native insulation testing software is virtualizing data storage and analysis workflows that once required dedicated on-premise servers. US electric utilities and German automotive manufacturers are adopting these architectures fastest, with field technicians uploading resistance measurements directly to centralized asset management systems. This shift is virtualizing the traditional boundary between field instrumentation and enterprise software, compressing margins for standalone hardware vendors.
REACH substance restrictions and RoHS amendments in the European Union are forcing material redesigns for tester housings and internal components. Manufacturers serving EU member states must eliminate specific flame retardants and heavy metals from production lines, raising compliance costs for non-EU exporters. German testing equipment suppliers have responded fastest, leveraging proximity to ECHA regulatory consultations to pre-certify replacement materials.
After-sales service unbundling is fragmenting traditional vendor-customer relationships in North American industrial markets. Large manufacturing accounts now separate hardware procurement from calibration contracts and software subscriptions, pitting specialized service providers against original equipment manufacturers. This pattern is most visible in Texas and California petrochemical clusters, where third-party metrology laboratories capture recurring revenue that previously flowed to equipment vendors.
Global Insulation Testers Market Segmentation
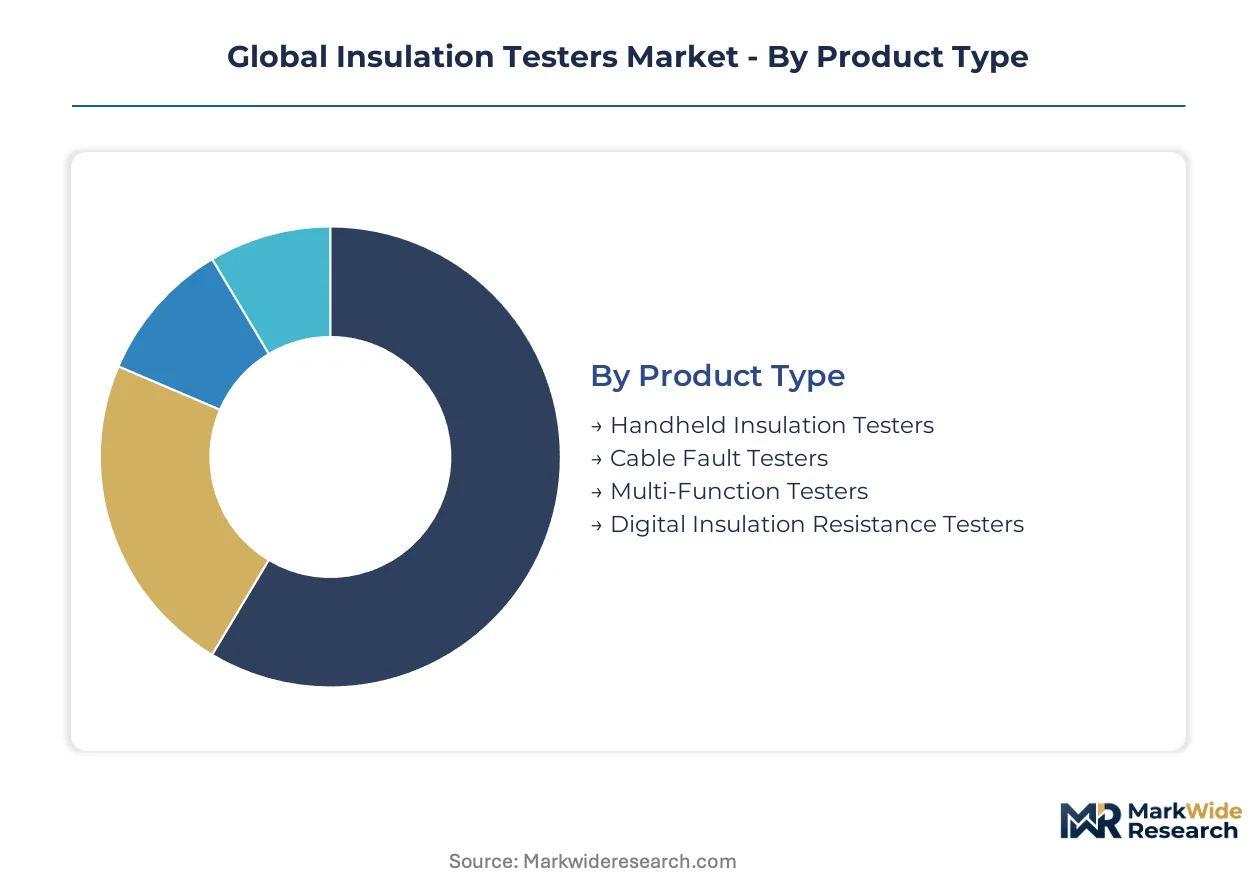
Insulation testers serve distinct operational contexts spanning field portability, high-voltage diagnostics, and predictive analytics integration. Equipment specifications diverge sharply across these use cases, driving specialized product architectures and pricing tiers.
Product Type:
Contractors demand portability for rooftop solar installations and commercial retrofits. Utilities prioritize diagnostic depth for transmission infrastructure.
- Handheld Insulation Testers:Compact battery-powered units deliver 250V to 5kV test ranges for electrical contractors servicing distributed solar arrays and commercial building retrofits. German and US contractors favor these for OSHA-compliant lockout-tagout verification in confined electrical rooms. Established volume favors this segment; emerging adoption favors cable fault diagnostics.
- Cable Fault Testers:High-voltage pulse generators and time-domain reflectometry modules pinpoint insulation breakdown locations in underground transmission and submarine power links. US electric utilities deploy these for predictive maintenance of aging urban distribution networks. Expanding most quickly as grid hardening accelerates.
- Multi-Function Testers:Integrated units combining insulation resistance, continuity, and earth bond testing for industrial maintenance crews.
- Digital Insulation Resistance Testers:Precision instruments with data logging and Bluetooth connectivity for compliance documentation in regulated facilities.
Established volume favors handheld units; emerging adoption favors cable fault systems.
End User:
Purchasing authority concentrates with technical buyers who specify test protocols and calibration intervals. Budget cycles and regulatory exposure shape procurement timing.
- Electrical Contractors:Independent and unionized tradespeople performing installation verification and periodic testing across commercial, residential, and light industrial projects. Japanese and South Korean contractors are digitizing field workflows fastest, uploading resistance data directly to cloud-based project management platforms. Volume concentrates here; margin expansion favors utilities.
- Utilities:Transmission and distribution operators managing generation assets, substations, and underground cable networks. German utilities lead IEC 61850 protocol adoption, forcing digital tester upgrades for smart grid interoperability. Steepest expansion trajectory among end-user categories.
- Manufacturing Plants:In-house electrical maintenance teams at automotive, chemical, and semiconductor fabrication facilities.
- Maintenance Services:Third-party providers offering contracted testing and calibration for facilities lacking in-house high-voltage expertise.
Contractor density drives unit shipments; utility digitization drives value growth.
Technology:
Technology migration reflects regulatory pressure and connectivity requirements. Analogue units face replacement mandates while smart systems capture predictive maintenance budgets.
- Smart Insulation Testing:Connected instruments with embedded sensors, edge computing, and API integration for enterprise asset management platforms. US utilities and German automotive manufacturers deploy these for real-time degradation trending and automated work order generation. Gaining share fastest as predictive maintenance budgets expand.
- Digital:Microprocessor-controlled units with automated range selection, stored test sequences, and USB data export for compliance reporting. IEC 61543 safety standard adoption in EU member states accelerates displacement of analogue equivalents. Revenue concentration sits here.
- Analogue:Electromechanical meters with needle displays, still deployed where electromagnetic interference disrupts digital electronics.
- Automated Testing Technology:Robotic and fixed-installation systems for production-line testing of motors, transformers, and cable assemblies.
Digital platforms anchor current revenue; smart systems capture incremental investment.
Application:
Application requirements range from portable spot-checking to continuous monitoring of critical infrastructure. Test voltage, data granularity, and environmental sealing specifications vary accordingly.
- Electrical Maintenance:Periodic verification of motors, switchgear, and distribution panels across industrial, commercial, and institutional facilities. FDA oversight of US hospital electrical safety and OSHA enforcement in manufacturing plants sustain demand for documented insulation verification. Largest application by unit volume.
- Power Generation:Testing of generators, transformers, and high-voltage buswork in thermal, renewable, and nuclear facilities. Offshore wind farms in the North Sea and utility-scale solar in the US Southwest require specialized testers for salt spray and desert temperature extremes. Climbing the fastest as renewable capacity expands.
- Building Inspection:Pre-occupancy verification of wiring insulation and post-fault diagnostics in residential and commercial structures.
- Telecommunications:Testing of power feed equipment and battery backup systems in data centers and central offices.
Maintenance routines dominate installed base; power generation drives replacement velocity.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Trade flows in insulation testing equipment tilt toward net-importing industrial economies with aging electrical infrastructure. Germany and the United States absorb premium digital units, while Chinese manufacturers supply cost-optimized handheld devices across Southeast Asian contractor markets.
United States
Electric utilities in Texas and California are expanding predictive maintenance programs to reduce wildfire and storm outage risks. OSHA lockout-tagout enforcement drives periodic insulation verification mandates across petrochemical clusters along the Gulf Coast. Hospital networks in the Northeast corridor face FDA oversight of medical device electrical safety, sustaining dedicated demand for portable testing units.
Germany
Industrial plant modernization in the chemical and automotive sectors accelerates replacement cycles for legacy testing equipment. CE marking requirements and REACH substance restrictions force material redesigns for tester housings and internal components. Bavarian automotive manufacturers and North Rhine-Westphalian chemical complexes lead IEC 61850 protocol adoption for smart grid interoperability.
Japan
Utilities in Tokyo and Osaka deploy connected testers with embedded communication modules for predictive maintenance platforms. METI industrial efficiency standards push digitization of field instrumentation across manufacturing maintenance crews. Yokohama and Nagoya industrial corridors exhibit fastest uptake of Bluetooth-enabled data logging for cloud analytics integration.
China
State Grid Corporation infrastructure hardening drives demand for high-voltage cable diagnostics in coastal provinces. GB standards for electrical safety equipment create domestic certification requirements that favor local manufacturers. Yangtze River Delta manufacturing hubs and Pearl River Delta export processing zones concentrate both production and consumption of handheld insulation testers.
India
Central Electricity Authority regulations mandate periodic insulation testing for transmission and distribution assets. BIS certification requirements for electrical safety equipment shape procurement specifications for state electricity boards. Maharashtra and Gujarat industrial corridors exhibit concentrated demand from textile and pharmaceutical manufacturing maintenance teams.
Global Insulation Testers Market Competitive Environment
Platform integrators command the system tier; component specialists sit upstream. The vendor base organizes around three strategic archetypes: diversified electrical instrumentation conglomerates with calibration service networks, specialized high-voltage diagnostics firms with utility-focused product depth, and regional manufacturers serving price-sensitive contractor markets through distribution partnerships. Consolidation pressures concentrate among mid-scale digital specialists facing cybersecurity certification delays and smart grid protocol fragmentation.
Within the diversified instrumentation tier, Fluke Corporation and Yokogawa Electric Corporation exemplify platform integrators with recurring revenue streams anchored in calibration networks and enterprise software integration. Megger occupies a position representing specialized high-voltage diagnostics expertise. These three firms illustrate how competitive positioning diverges between breadth-driven service models and depth-focused technical specialization.
| Leading Market Players |
|---|
| Fluke Corporation |
| Megger |
| Yokogawa Electric Corporation |
| Hioki Corporation |
| Kyoritsu Electrical Instruments |
| Eaton Corporation |
| Chauvin Arnoux Metrix |
| B&K Precision Corporation |
| Meco Instruments Pvt. Ltd. |
| Others |
Value Chain & Pricing Dynamics
Semiconductor input volatility in East Asian foundries determines both pricing tier spreads and supply chain shape for insulation tester manufacturers. ADC chip and precision resistor supply concentration compresses margins on digital units while forcing calibration-dependent vendors toward premium service bundling.
Pricing Analysis
Industrial OEM buyers anchor a three-tier pricing structure across premium, standard, and economy levels. Price differentiation rests on IEC 61543 certification grade and embedded connectivity features. Cost compression in the economy tier is intensifying because Chinese manufacturers flood contractor markets with uncalibrated handheld units. Electrical contractors exhibit highest price sensitivity; utilities purchasing cable fault diagnostics show lowest.
Supply Chain Analysis
Export-control restrictions on precision ADC technology limit component flows from Taiwan and South Korea to mainland China assembly operations. Manufacturing draws from Japan for high-voltage resistors, Germany for precision mechanical housings, and China for battery and plastic molding inputs. Single-source vulnerability concentrates in 24-bit sigma-delta ADC supply. Distribution runs through authorized electrical distributors serving contractor and utility accounts.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Equipment-as-a-service substitution threatens traditional hardware vendors with margin compression. Incumbents must defend against asset-light leasing platforms converting capex to opex.
For Market Incumbents: Build calibration network moats through accredited laboratory expansion in Germany and the United States. Incumbents should deepen backward integration into precision resistor manufacturing to offset East Asian foundry concentration. Channel control through exclusive distributor agreements defends against third-party metrology laboratories capturing recurring revenue. For New Entrants and Emerging Players: Pursue medical device electrical safety segments in US hospital networks where FDA oversight creates compliance barriers for unestablished vendors. White-space concentrates in Bluetooth-enabled data logging for Japanese and South Korean utility digitization contracts. Go-to-market through cloud analytics platform partnerships accelerates enterprise asset management integration. For Investors and Strategic Acquirers: IEC 62443 cybersecurity certification timelines reshape the acquisition landscape by extending product launch cycles and stranding non-compliant R&D pipelines. Long-term viability favors targets with pre-certified firmware and existing utility smart grid deployments. Watch for consolidation signals among mid-scale digital specialists facing protocol fragmentation.| Strategic Initiative | Industry Significance |
|---|---|
| Cybersecurity Certification Investment | IEC 62443 compliance accelerates smart grid deployment contracts with German utilities. |
| Calibration Network Expansion | Accredited laboratory presence in Texas and Bavaria captures recurring service revenue. |
| Platform Integration Partnership | API connectivity with Yokohama cloud analytics providers opens utility digitization channels. |
| Backward Integration into Precision Components | In-house resistor production reduces exposure to Taiwan foundry scheduling uncertainty. |
| Equipment-as-a-Service Launch | Leasing models with embedded calibration penetrate US petrochemical clusters seeking opex conversion. |
Study Parameters
Two parallel data streams informed the analysis: primary interviews with utility maintenance directors, electrical contractor fleet managers, OEM procurement teams, and aftermarket service heads; and secondary validation through IEC standards documentation, OSHA enforcement records, FDA medical device filings, and customs trade data. Bottom-up and top-down triangulation cross-checked unit shipment estimates against utility capital expenditure disclosures and industrial maintenance spending patterns.
Forecast inputs span product type, end-user category, technology tier, and regional regulatory cluster across the analysis window. CAGRs derive from regression modeling of replacement cycle compression against smart grid interoperability mandates. Industry-specific inputs include IEC 61850 protocol adoption curves and REACH substance restriction compliance timelines.
Sensitivities concentrate around semiconductor supply disruptions, cybersecurity certification delays, and utility capital allocation shifts. Forecasts reflect documented assumptions on regulatory enforcement intensity and technology migration rates. Material shifts in East Asian export controls or IEC 62443 implementation timelines would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Testing Equipment
US Eddy-Current Testing Market
Testing Equipment
In Vitro Toxicity Testing Market
Testing Equipment
Global Residue Testing Market
Testing Equipment
Materials Testing Equipment Market
Testing Equipment
Liquid Chromatography Mass Spectrometry (LCMS) Market
Testing Equipment
Liquid Analytical Instrument Market
Testing Equipment
Solar Testing Equipment Market
Testing Equipment
PFAS Ultra-Trace Water Analysis Test Instruments Market
Testing Equipment
Membrane Osmometer Market
Testing Equipment
Laboratory Filtration Equipment and Supplies Market
Testing Equipment
Paper Tester Market
Testing Equipment
Global Trace Metal Analysis Market
Testing Equipment
Steel Testing Equipment Market
Testing Equipment
Laboratory Balances and Scales Market
Testing Equipment
Europe Non-Destructive Testing Market
Testing Equipment
Global Dynamic Mechanical Analyzers Market