
 Water Analysis Instruments Market | 2026-2036
Water Analysis Instruments Market Size, Share, and Industry Trends Forecast 2026-2036
Water Analysis Instruments Market Outlook
Aftermarket service revenue is rewriting profit allocation across the Water Analysis Instruments landscape. Thermo Fisher Scientific leverages its global service infrastructure to capture recurring calibration and maintenance contracts. Hach (Veralto) anchors its position through deep integration with municipal utility workflows and consumable lock-in. Xylem Inc. competes by bundling instrumentation with digital water platform subscriptions.
Water analysis instruments comprise electrochemical and optical sensor assemblies, spectrophotometric detection modules, and chromatographic separation systems designed to quantify chemical, physical, and biological parameters in aqueous matrices with detection thresholds reaching parts-per-billion precision. Their primary commercial purpose centers on ensuring regulatory compliance, process optimization, and public health protection across water infrastructure. pH meters and dissolved oxygen meters command established installed bases in municipal treatment, while optical sensor platforms represent the fastest-expanding technology segment as utilities shift toward reagent-free continuous monitoring. Wastewater management and drinking water testing together absorb the dominant share of instrument deployment, with industrial process control emerging as a concentrated margin pool due to customized specification requirements and longer replacement cycles.
The EPA enforces method-specific detection limits under the Clean Water Act and Safe Drinking Water Act, compelling utilities to upgrade legacy analyzers or risk consent decree penalties. ISO 17025 accreditation requirements and the EU Drinking Water Directive reciprocally shape product development priorities for manufacturers seeking cross-border certification. Stakeholders must weigh the capital efficiency of modular sensor platforms against the operational risk of stranded assets as regulatory method updates accelerate.
Market Dynamics
Optical sensor platforms are collapsing the cost-per-test economics that sustained reagent-heavy legacy analyzers, forcing utilities to revalue their entire analytical infrastructure around continuous monitoring uptime rather than batch testing accuracy.
Growth Catalysts
- EPA Clean Water Act enforcement:Method-specific detection limit upgrades are compelling North American utilities to replace legacy analyzers or face consent decree penalties.
- Industrial process control:Customized specification requirements and extended replacement cycles in manufacturing water loops generate concentrated margin pools for instrument vendors.
- Germany Drinking Water Ordinance:Continuous monitoring mandates are driving systematic upgrade cycles across municipal treatment networks in Europe's largest water infrastructure market.
Market Restraints
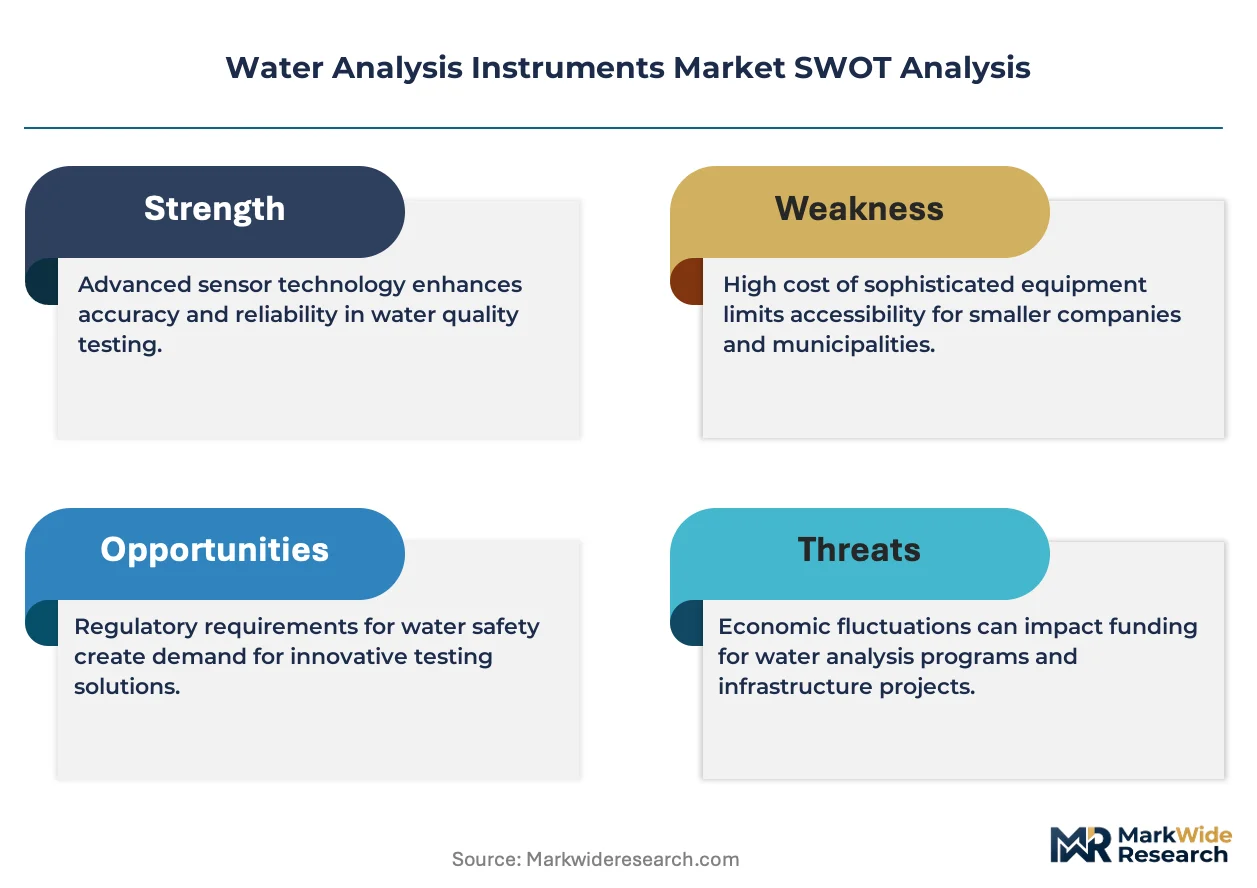
- Sensor membrane supply concentration:Specialized electrochemical membrane production clusters in select East Asian manufacturing zones create single-source vulnerability for pH and dissolved oxygen meter assembly.
- Reagent cost volatility:Chromatographic separation system operation depends on acetonitrile and methanol supply chains exposed to petrochemical feedstock price swings.
- ISO 17025 accreditation friction:Cross-border certification reciprocity gaps between national accreditation bodies delay product launches and fragment service standardization.
Strategic Opportunities
- India municipal water infrastructure:Underpenetrated continuous monitoring deployment in tier-2 and tier-3 city treatment plants offers first-mover positioning ahead of anticipated national drinking water quality mandates.
- Digital platform convergence:Bundling optical sensor hardware with predictive analytics software is collapsing traditional instrumentation-only procurement models.
- EU Drinking Water Directive revisions:Emerging contaminant monitoring requirements for microplastics and pharmaceuticals will mandate sensor platform upgrades across member state utilities.
Industry Challenges
- Field calibration expertise scarcity:Qualified technicians capable of maintaining parts-per-billion precision across electrochemical and optical sensor assemblies remain concentrated in legacy vendor training programs.
- Legacy system integration complexity:Municipal SCADA infrastructure predating open communication protocols requires costly middleware development to accommodate modular sensor platform deployment.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Water Analysis Instruments Market |
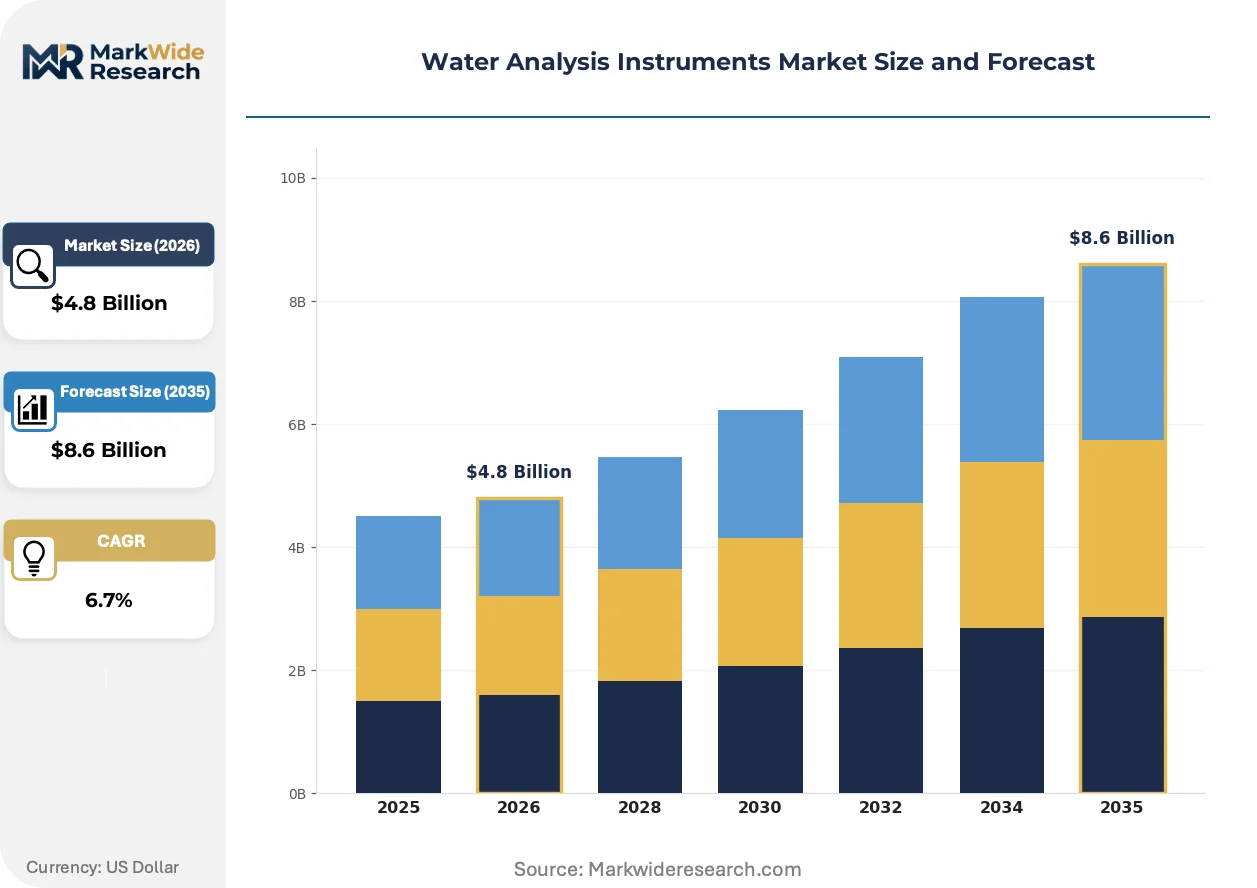
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $8.6 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: pH Meters, Turbidity Meters, Conductivity Meters, Dissolved Oxygen Meters End User: Environmental Agencies, Water Treatment Plants, Laboratories, Academic Institutions Technology: Optical Sensors, Electrochemical Sensors, Spectrophotometry, Chromatography Application: Wastewater Management, Drinking Water Testing, Aquaculture, Industrial Process Control |
| Companies Covered | Thermo Fisher Scientific, Hach (Veralto), Xylem Inc., Danaher Corporation, Horiba Ltd., ABB Ltd., Emerson, Endress+Hauser, Mettler Toledo, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Water Analysis Instruments Market Strategic Shifts
Reagent-free analytical modalities are compressing operational expenditure structures while expanding real-time parameter coverage, fundamentally altering how utilities justify capital replacement cycles.
Raman spectroscopy is collapsing the distinction between laboratory-grade chromatographic analysis and field-deployable continuous monitoring. German and Dutch water utilities are piloting submerged Raman probes for simultaneous multi-parameter detection of organic contaminants. The technology is collapsing the need for sample transport infrastructure and centralized lab capacity in distributed treatment networks.
REACH authorization requirements for analytical reagents are tightening supply chain documentation burdens across European instrument operators. The regulation is accelerating adoption of reagent-free optical methods in industrial process water applications. German chemical manufacturers are responding by vertically integrating sensor production to control substance compliance traceability.
Subscription-based service unbundling is fragmenting traditional instrument procurement into hardware, calibration, and data analytics components. North American municipal utilities are separating capital budgets for sensor platforms from operational contracts for predictive maintenance. The shift is most visible in California and Texas water districts facing ratepayer scrutiny over total cost of ownership transparency.
Water Analysis Instruments Market Segmentation
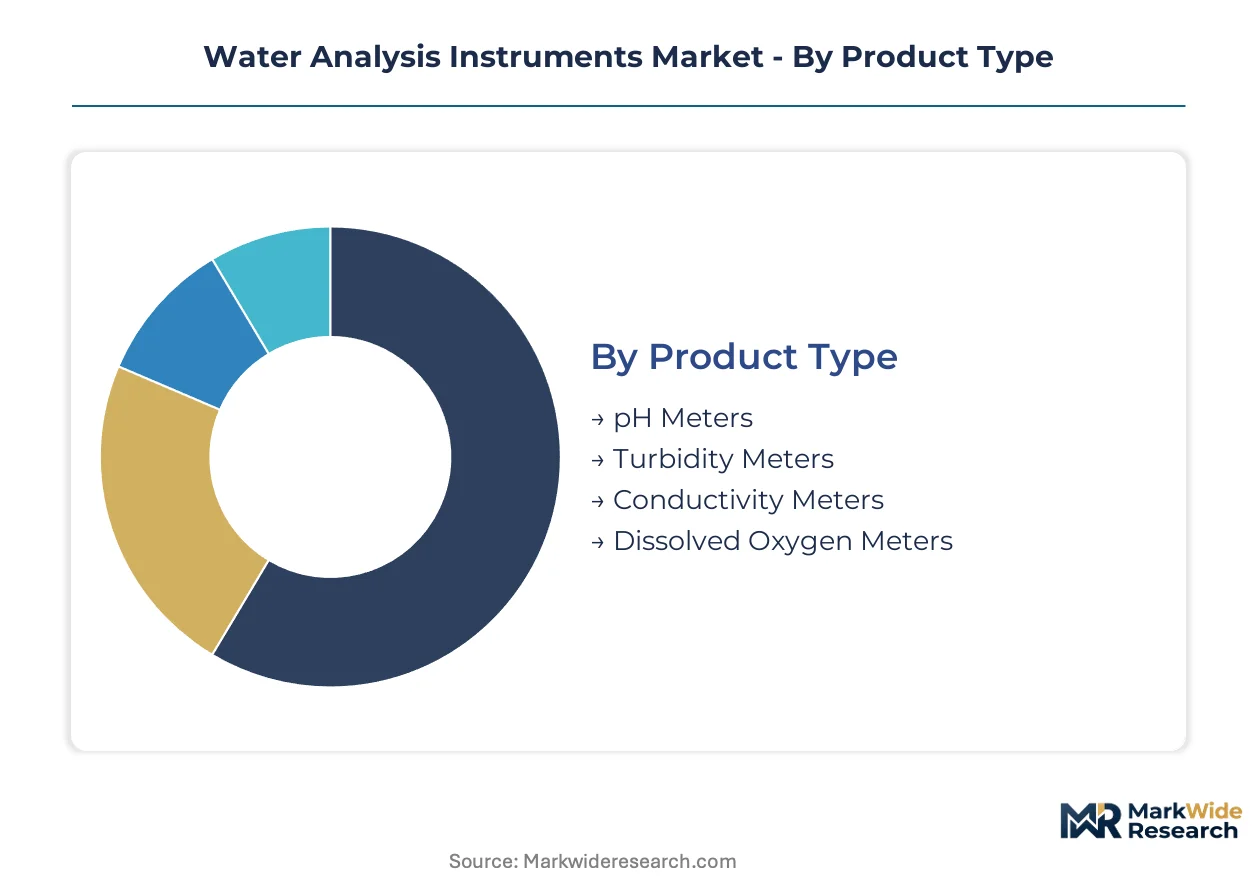
Water analysis instruments fragment across four critical dimensions that determine procurement priorities, margin structures, and replacement cycles. Product type reflects installed base maturity, while technology choice increasingly dictates operational expenditure profiles as utilities shift from reagent-heavy to reagent-free modalities.
Product Type:
Mature electrochemical platforms anchor utility procurement budgets while optical alternatives reshape upgrade roadmaps.
- pH Meters:Glass electrode and ISFET-based assemblies measure hydrogen ion activity with temperature compensation for process control. Municipal treatment plants in Germany and the Netherlands maintain extensive installed bases requiring continuous calibration service contracts.
- Dissolved Oxygen Meters:Clark-type polarographic and optical luminescent sensors quantify molecular oxygen for biological treatment optimization. Industrial process water loops in US manufacturing corridors generate replacement demand as membrane degradation accelerates in high-solids environments.
- Turbidity Meters:Nephelometric light-scatter detection for suspended particle quantification.
- Conductivity Meters:Contact and toroidal electrode designs for total dissolved solids estimation.
pH meters retain volume leadership; dissolved oxygen meters hold the steepest expansion curve.
End User:
Regulatory enforcement intensity varies sharply across customer categories, concentrating vendor sales effort on compliance-driven accounts.
- Water Treatment Plants:Continuous monitoring infrastructure for intake, process, and discharge compliance. US utilities under EPA consent decrees accelerate analyzer replacement cycles to meet method-specific detection limits.
- Environmental Agencies:Field-deployable and laboratory-grade instrumentation for enforcement sampling and watershed surveillance. German state environmental offices standardize on multi-parameter probe platforms for river basin monitoring networks.
- Laboratories:High-precision reference methods for regulatory certification and dispute resolution.
- Academic Institutions:Research-grade instrumentation for method development and sensor validation studies.
Water treatment plants dominate procurement volume; environmental agencies are climbing fastest as enforcement budgets expand.
Technology:
Detection modality selection increasingly hinges on total cost of ownership rather than capital expenditure alone.
- Optical Sensors:Reagent-free luminescent and absorbance-based detection for dissolved oxygen, turbidity, and emerging contaminant screening. Dutch utilities pilot submerged Raman probes for distributed treatment network decentralization.
- Electrochemical Sensors:Potentiometric and amperometric transducers for pH, conductivity, and selective ion measurement. Legacy dominance persists in municipal SCADA integration due to established 4-20mA output standardization.
- Spectrophotometry:UV-Vis and IR absorption for nutrient and organic compound quantification.
- Chromatography:Ion and gas chromatographic separation for trace-level contaminant identification.
Electrochemical sensors command the largest installed base; optical platforms are gaining share fastest as reagent costs escalate.
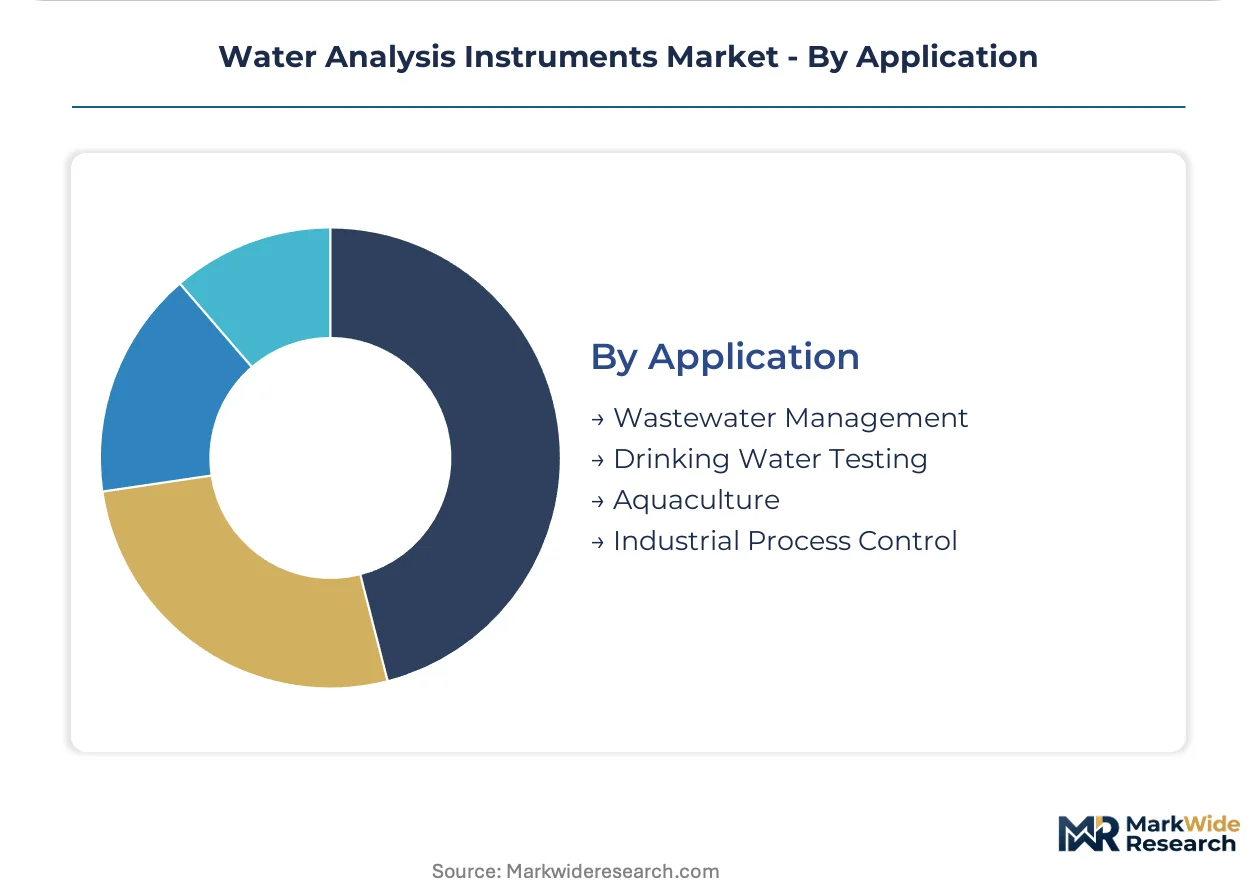
Application:
End-use specification requirements create divergent margin profiles across deployment contexts.
- Wastewater Management:Influent characterization and effluent compliance monitoring for biological treatment optimization. US municipal utilities under Clean Water Act enforcement replace legacy analyzers to avoid consent decree penalties.
- Industrial Process Control:Customized specification requirements for manufacturing water loops with extended replacement cycles. Semiconductor fabrication and pharmaceutical production generate concentrated margin pools due to contamination sensitivity.
- Drinking Water Testing:Source protection, treatment verification, and distribution system surveillance.
- Aquaculture:Dissolved oxygen and pH monitoring for intensive fish farming operations.
Wastewater management absorbs the dominant deployment volume; industrial process control offers the steepest margin expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Price elasticity varies sharply across geographies. German utilities absorb premium instrument costs under regulatory mandate while Indian municipal buyers face acute capital constraints. US utilities sit between these extremes, balancing EPA enforcement pressure against ratepayer resistance.
United States
EPA consent decree enforcement accelerates analyzer replacement cycles across Great Lakes and Chesapeake Bay watershed utilities. The Safe Drinking Water Act's emerging contaminant monitoring requirements drive continuous monitoring upgrades. California's Central Valley and Texas Gulf Coast water districts lead procurement volume as drought stress intensifies discharge scrutiny.
Germany
The Drinking Water Ordinance mandates real-time parameter surveillance across all municipal treatment networks. REACH authorization requirements for analytical reagents tighten supply chain documentation burdens. Industrial clusters in North Rhine-Westphalia and Bavaria pilot submerged Raman probes for distributed treatment decentralization.
China
MEE surface water quality monitoring expansion targets Yangtze and Pearl River Delta industrial corridors. National standards GB 3838 and GB 5749 tighten detection limit requirements for urban water utilities. Shanghai and Shenzhen municipal authorities deploy optical sensor platforms at scale to reduce reagent logistics costs.
India
Jal Jeevan Mission rural water supply expansion creates instrument demand across tier-2 and tier-3 city treatment plants. BIS drinking water quality standards adoption lags behind infrastructure deployment. Gujarat and Maharashtra industrial zones generate concentrated demand for process control analyzers in pharmaceutical and textile manufacturing loops.
Netherlands
EU Drinking Water Directive implementation drives systematic sensor platform upgrades across Randstad urban water networks. Dutch utilities pioneer reagent-free optical methods to eliminate hazardous substance handling. Rotterdam and Amsterdam water authorities deploy multi-parameter probe platforms for river basin monitoring networks.
Water Analysis Instruments Market Competitive Environment
Capability concentration sits with specialized sensor developers; scale advantage sits with diversified instrumentation conglomerates. The vendor base stratifies into three tiers: full-platform providers owning calibration service infrastructure, modular sensor specialists integrating via open protocols, and regional fabricators serving price-sensitive municipal procurement. Dominant competitive moves include predictive maintenance contract bundling and backward integration into membrane component production.
Within the full-platform tier, Thermo Fisher Scientific and Danaher Corporation exemplify scale-driven service infrastructure deployment. Hach (Veralto) occupies a position anchoring municipal utility workflow integration. Xylem Inc. represents the digital convergence archetype through platform subscription bundling. These three entities collectively illustrate how competitive positioning now hinges on recurring revenue capture rather than hardware shipment volume alone.
| Leading Market Players |
|---|
| Thermo Fisher Scientific |
| Hach (Veralto) |
| Xylem Inc. |
| Danaher Corporation |
| Horiba Ltd. |
| ABB Ltd. |
| Emerson |
| Endress+Hauser |
| Mettler Toledo |
| Others |
Value Chain & Pricing Dynamics
East Asian membrane manufacturing clusters for electrochemical sensors concentrate upstream supply leverage, positioning downstream margin capture with vendors owning captive calibration infrastructure and multi-year service contracts.
Pricing Analysis
After-sales revenue tiers—spanning recalibration subscriptions, consumable replenishment, and predictive maintenance contracts—generate lifetime value multiples exceeding hardware margins. Pricing stratifies across premium, standard, and economy tiers based on ISO 17025 certification grade and bundled service intensity. Cost compression in municipal procurement channels intensifies as ratepayer scrutiny spreads across US water districts. Industrial process control buyers exhibit lowest price sensitivity due to contamination liability exposure.
Supply Chain Analysis
Petrochemical feedstock volatility for acetonitrile and methanol draws from naphtha cracking capacity concentrated in China, South Korea, and Saudi Arabia. Specialized glass electrode production rests on borosilicate manufacturing in Germany and Japan. Single-source vulnerability for ISFET chip fabrication creates tariff exposure risk. Distribution runs through authorized service integrators holding regional calibration accreditation.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Municipal utility procurement consolidation into multi-year framework agreements shifts buyer power toward ratepayer-funded water districts, fragmenting vendor pricing autonomy.
For Market Incumbents: Pre-empt optical sensor platform commoditization by locking municipal utilities into predictive maintenance subscriptions before reagent-free technology standardizes. Anchor position through backward integration into membrane component production. Defend against modular sensor specialists by embedding proprietary communication protocols into SCADA integration layers.
For New Entrants and Emerging Players: Tier-2 and tier-3 Indian city treatment plants offer first-mover positioning ahead of BIS drinking water quality mandate enforcement. Target submerged Raman probe pilots in Dutch and German distributed treatment networks where reagent-handling costs burden incumbent workflows. Pursue white-label OEM partnerships with industrial automation distributors lacking water-specific application expertise.
For Investors and Strategic Acquirers: Capital is best deployed toward calibration service infrastructure owners in fragmented European accreditation markets. Long-term viability hinges on recurring revenue capture ratios exceeding hardware shipment dependence. Watch for EPA method-specific detection limit updates as inflection signals accelerating replacement cycles.
| Strategic Initiative | Industry Significance |
|---|---|
| Service Infrastructure Acquisition | Captures municipal calibration contracts under EPA consent decree pressure. |
| Optical Sensor Platform Launch | Displaces reagent-heavy analyzers as REACH documentation burdens tighten. |
| Membrane Component Integration | Secures supply continuity for pH and dissolved oxygen meter assembly. |
| Predictive Analytics Partnership | Bundles hardware with digital water platform subscriptions per Xylem model. |
| India Municipal Channel Development | Positions ahead of Jal Jeevan Mission quality mandate enforcement. |
Study Parameters
A spread of perspectives from municipal utility operations directors, environmental agency enforcement officers, instrument OEM product managers, and aftermarket service technicians converged on the working assumptions. Primary fieldwork combined with secondary validation against EPA enforcement databases, EU Drinking Water Directive implementation reports, and MEE surface water quality monitoring disclosures. Bottom-up unit deployment estimates triangulated against top-down infrastructure investment flows across the analysis window.
Demand-supply balance framing anchored the analytical framework across product type, technology modality, end-user regulatory intensity, and application margin profile dimensions. CAGRs derived from replacement cycle acceleration patterns under evolving detection limit requirements. Forecast inputs incorporated ISO 17025 accreditation reciprocity gaps and REACH reagent authorization timelines.
Practitioners should monitor EPA method update announcements, EU emerging contaminant list revisions, and Indian BIS standard adoption trajectories for early signals. Cross-checking against utility capital improvement plan disclosures and environmental agency enforcement settlement databases is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Testing Equipment
Laboratory Centrifuge and Accessories Market
Testing Equipment
Electrical Testing Equipment Market
Testing Equipment
In Line Process Viscometer (ILPV) Market
Testing Equipment
US Eddy-Current Testing Market
Testing Equipment
Chemical Reaction Monitoring Equipment Market
Testing Equipment
China Material Testing Market
Testing Equipment
Dynamic Vapor Sorption Analyzer Market
Testing Equipment
Chromatography Accessories and Consumables Market
Testing Equipment
Gold Purity Tester Market
Testing Equipment
Reagent Filling Systems Market
Testing Equipment
Chloride Reagents Kits Market
Testing Equipment
Global Online Coal Ash Analyzers Market
Testing Equipment
Geochemical Services Market
Testing Equipment
Global Liquid Chromatography Instruments Market
Testing Equipment
In Vitro Toxicity Testing Market
Testing Equipment
Liquid Chromatography Market