
 Global Chiral Chromatography Column Market | 2026-2036
Global Chiral Chromatography Column Market Size, Share, and Industry Trends Forecast 2026-2036
Global Chiral Chromatography Column Market Foresight
Column regeneration and performance monitoring subscriptions is decoupling hardware sales from recurring revenue in the chiral chromatography supply chain. Agilent Technologies leverages its CrossLab service portfolio to lock in pharmaceutical accounts with predictive maintenance contracts. Daicel Corporation anchors the polysaccharide-based stationary phase segment through captive cellulose and amylose derivative production in Japan. Waters Corporation competes on ultra-performance liquid chromatography integration, bundling columns with ACQUITY platform upgrades.
Chiral chromatography columns are separation devices packed with enantioselective stationary phases, typically 3–5 µm porous silica particles bonded with derivatized polysaccharides or macrocyclic glycopeptides, designed to resolve racemic mixtures into individual enantiomers for quantitative purity assessment. The polysaccharide-based product category dominates installed base value due to broad solvent compatibility and established validation libraries across regulatory laboratories. Ultra-performance liquid chromatography technology is gaining fastest adoption among contract research organizations seeking reduced solvent consumption and shorter method development cycles. Pharmaceutical synthesis applications command the largest application share, though environmental screening is emerging as a growth pocket driven by chiral pollutant detection requirements in the European Union.
FDA enantiomeric impurity guidelines and EMA Q3D elemental impurity standards shape column validation protocols, forcing manufacturers to document batch-to-batch reproducibility within tight tolerance bands. REACH registration requirements for silica-based stationary phases add compliance cost layers for European distribution, while Japan's PMDA mandates ichiral method transfer documentation for imported reference standards. Stakeholders must monitor how EPA expansion of chiral pesticide monitoring lists and China's NMPA bioequivalence testing reforms redirect procurement toward columns with demonstrated regulatory acceptance across multiple jurisdictions.
Market Dynamics
Supercritical fluid chromatography is compressing method development timelines and solvent consumption benchmarks, forcing incumbent HPLC column suppliers to defend installed bases through platform bundling and predictive service contracts.
Growth Catalysts
- FDA Enantiomeric Impurity Guidelines:Mandates for chiral purity documentation in new drug applications drive replacement cycles for validated column inventories across pharmaceutical quality control laboratories.
- Contract Research Organizations:Accelerated screening throughput requirements in drug discovery pipelines pull adoption of sub-2 µm particle columns with reduced solvent footprints.
- German Precision Instrumentation Cluster:Concentration of analytical method development expertise around Frankfurt and Munich sustains premium column demand for regulatory submission support.
Market Restraints
- Derivatized Polysaccharide Supply Concentration:Cellulose and amylose precursor production clusters in Japan create input bottleneck vulnerability for stationary phase manufacturers elsewhere.
- REACH Silica Registration Burden:ECHA documentation requirements for functionalized silica particles add fixed compliance costs that disproportionately burden smaller column suppliers serving European laboratories.
- Batch-to-Batch Reproducibility Tolerance:Tight validation windows for enantioselectivity factors force discard rates of 8-12% in polysaccharide phase coating operations, elevating effective production costs.
Strategic Opportunities
- Environmental Chiral Screening:EPA expansion of monitored pesticide enantiomers creates new demand pockets for columns validated against emerging pollutant reference standards.
- China NMPA Bioequivalence Reforms:Mandatory chiral method transfer documentation for generic drug approvals opens procurement channels for columns with demonstrated multi-jurisdictional acceptance.
- SFC-HPLC Platform Convergence:Instrument manufacturers bundling dual-technology capability create attach-rate opportunities for compatible column formats across unified workflows.
Industry Challenges
- Chiral Method Transfer Expertise Gap:Shortage of analytical chemists proficient in enantioselective validation protocol development extends customer onboarding timelines and strains technical support capacity.
- Legacy HPLC Integration Friction:Retrofitting sub-2 µm columns into existing ultra-performance systems requires hardware upgrades that delay purchasing decisions in budget-constrained quality control departments.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Chiral Chromatography Column Market |
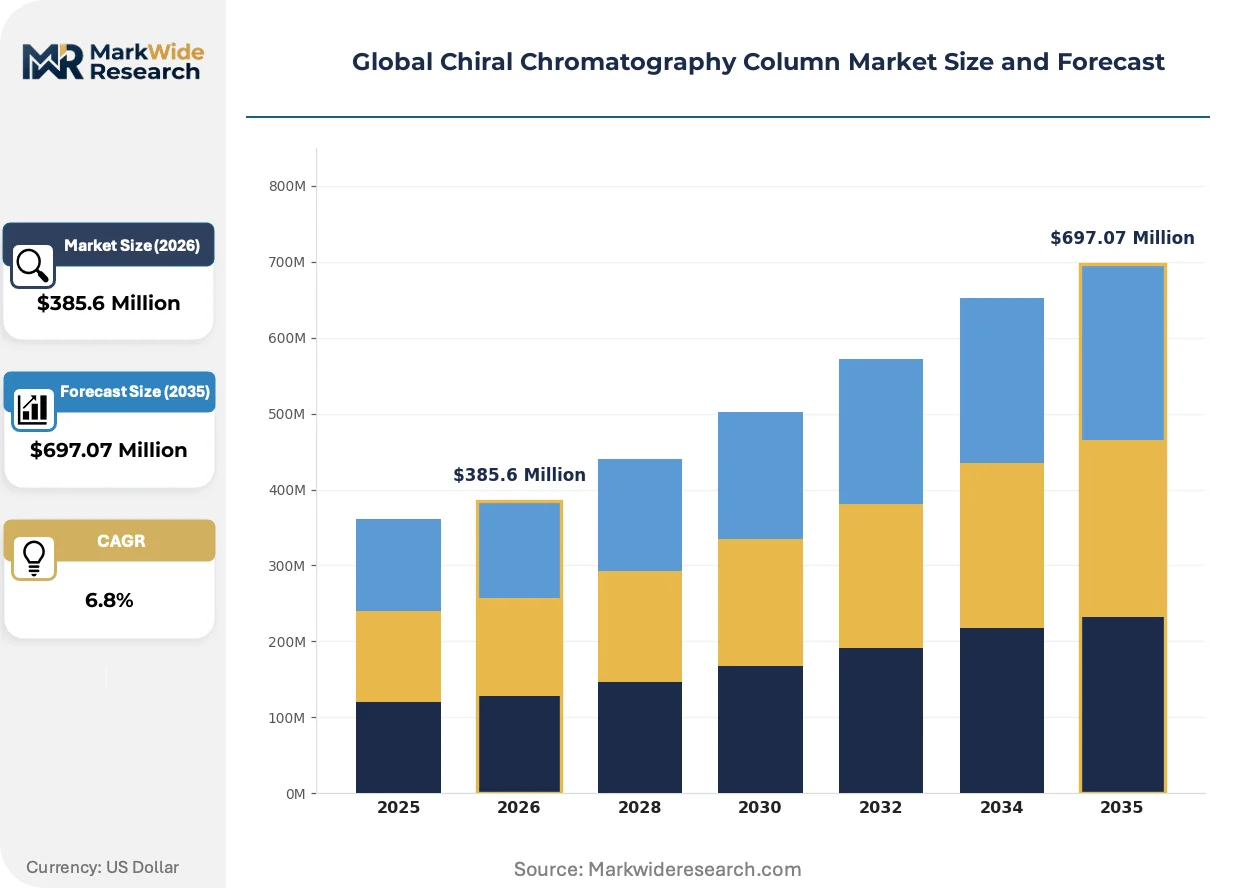
| Market Size in 2026 | $385.6 Million |
| Market Size in 2035 | $697.07 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Polysaccharide-Based, Protein-Based, Cyclodextrin-Based, Pirkle-Type, Other Synthetic Phases Technology: High-Performance Liquid Chromatography, Supercritical Fluid Chromatography, Gas Chromatography, Ultra-Performance Liquid Chromatography Application: Pharmaceutical Synthesis, Agrochemical Analysis, Food & Beverage Testing, Environmental Screening, Forensic Investigation End User: Pharmaceutical Manufacturers, Academic Research Institutes, Chemical Producers, Regulatory Laboratories |
| Companies Covered | Agilent Technologies, Thermo Fisher Scientific, Waters Corporation, Daicel Corporation, Merck KGaA, Shimadzu Corporation, Bio-Rad Laboratories, PerkinElmer, Cytiva, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Chiral Chromatography Column Market Shifts & Advancements
Chromatography workflows are fragmenting into specialized technology tracks, with solvent sustainability mandates and regulatory documentation requirements forcing divergent equipment and consumable investment patterns across end-use segments.
Immobilized polysaccharide stationary phases are expanding into aqueous-compatible method portfolios previously dominated by coated-phase columns. Biopharmaceutical analytical groups in Switzerland and the United States are adopting these chemistries for antibody-drug conjugate chirality assessment. The technology is expanding into applications requiring extended pH stability and aggressive solvent washing protocols that would degrade traditional coated phases.
EMA Q3D elemental impurity standards now mandate ICP-MS verification of metal content in silica substrates, adding analytical burden to column release testing. Manufacturers serving European pharmaceutical accounts must document trace metal profiles below specified thresholds for arsenic, cadmium, and lead. The policy is compressing supplier qualification timelines and favoring column producers with in-house elemental analysis capability.
Service unbundling is separating hardware procurement from method development support and performance monitoring subscriptions. Pharmaceutical quality control departments in Japan now purchase columns through tender processes while contracting predictive maintenance and batch-to-batch equivalency studies through separate service agreements. This bifurcation is visible most acutely in multi-site manufacturing organizations seeking centralized column standardization with localized technical support.
Global Chiral Chromatography Column Market Segmentation
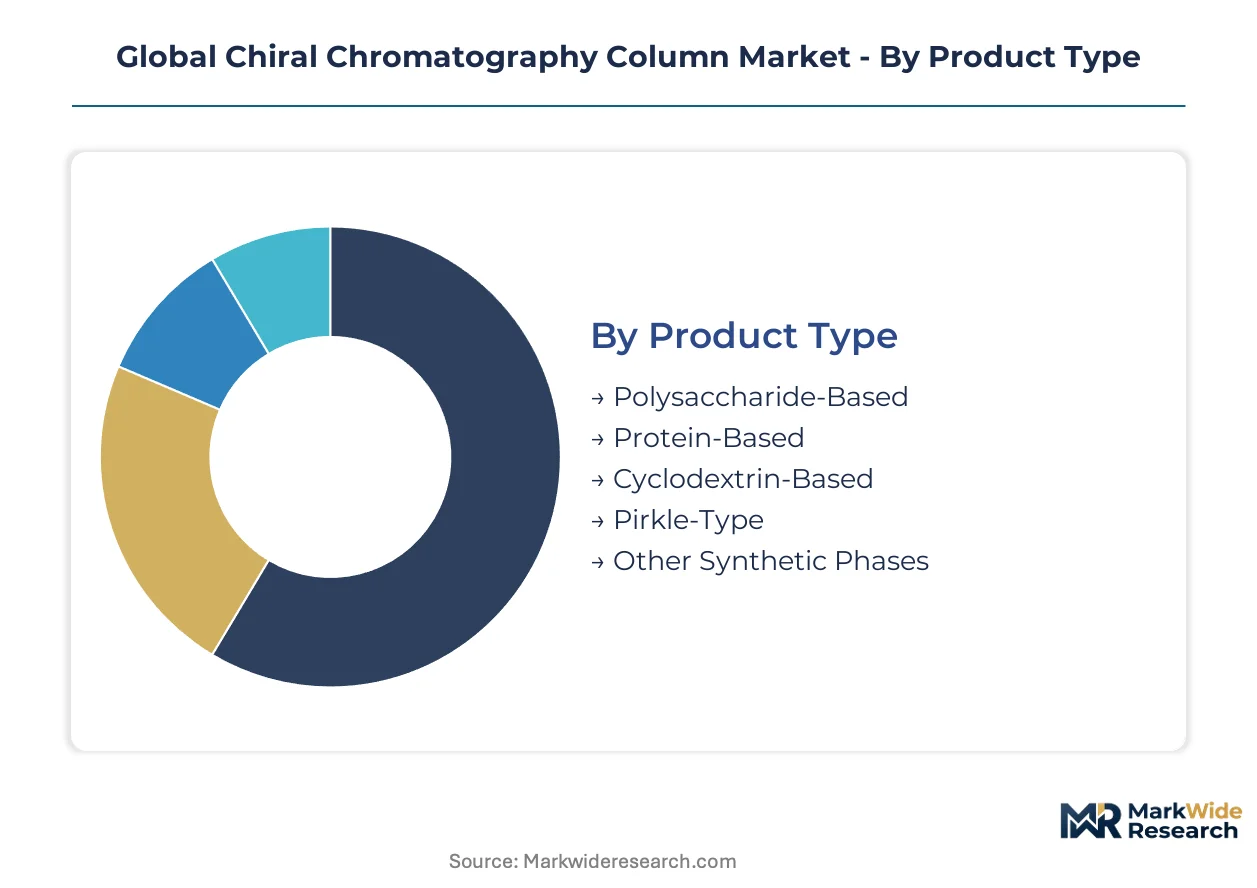
Segmentation in the chiral chromatography column market reveals how distinct technical requirements and regulatory pressures fragment procurement patterns across end-use environments. Product type and technology choices determine capital allocation cycles, while application specialization dictates validation protocol investments.
Product Type:
Replacement cycles for stationary phases accelerate when validated methods require documented batch-to-batch equivalency, forcing laboratories to maintain locked-inventory relationships with specific chemistries.
- Polysaccharide-Based:Derivatized cellulose and amylose coatings bonded to porous silica particles deliver broad enantioselectivity across pharmaceutical compound classes. Demand clusters in German regulatory laboratories serving EMA submission requirements, where established validation libraries reduce method development risk.
- Protein-Based:Immobilized albumin and glycoprotein phases target specific chiral recognition sites for acidic and basic pharmaceutical intermediates. Adoption concentrates in United States academic research institutes exploring novel enantioselective mechanisms for biologic drug candidates.
- Cyclodextrin-Based:Toroidal oligosaccharide cavities provide size-selective chiral separation for small aromatic molecules in forensic toxicology applications.
- Pirkle-Type:Synthetic chiral selectors with π-acidic or π-basic functional groups serve niche separations where polysaccharide phases fail.
- Other Synthetic Phases:Macrocyclic glycopeptide and ion-exchange chiral selectors address specialized method development challenges in agrochemical metabolite analysis.
Polysaccharide-Based phases occupy the volume apex across installed bases, with Protein-Based alternatives expanding most quickly in biopharmaceutical discovery workflows.
Technology:
Capital equipment refresh timelines determine column format adoption, with laboratories delaying UPLC investments until existing HPLC platforms reach depreciation endpoints.
- High-Performance Liquid Chromatography:3–5 µm particle columns operating at 400 bar maximum pressure dominate quality control laboratories with extensive validated method libraries. Procurement persists in Japanese pharmaceutical manufacturers where PMDA submission stability discourages platform migration.
- Supercritical Fluid Chromatography:Carbon dioxide-based mobile phase systems compress separation cycles and eliminate toxic solvent disposal costs. Contract research organizations in Switzerland deploy SFC for high-throughput enantiomeric excess screening in early-phase drug discovery.
- Gas Chromatography:Volatile chiral selectors on capillary columns serve forensic and environmental applications requiring vapor-phase analysis.
- Ultra-Performance Liquid Chromatography:Sub-2 µm particle columns demand specialized hardware but deliver reduced solvent consumption and sharper peak resolution.
HPLC retains the largest installed base footprint, while SFC gains share fastest among laboratories prioritizing solvent sustainability metrics.
Application:
Regulatory filing requirements concentrate procurement authority in specific application segments, with pharmaceutical quality control commanding premium pricing tolerance.
- Pharmaceutical Synthesis:Enantiomeric purity verification for active pharmaceutical ingredients and intermediates drives column consumption across development and manufacturing stages. FDA chiral impurity guidelines mandate documentation in United States new drug applications, sustaining replacement demand.
- Agrochemical Analysis:Chiral pesticide residue testing for enantioselective toxicity assessment expands under EPA monitoring list revisions. Laboratories in Germany validate methods for export compliance with emerging EU pollutant thresholds.
- Food & Beverage Testing:Aroma compound and additive chirality analysis supports authenticity verification in premium product categories.
- Environmental Screening:Chiral pollutant detection for persistent organic compounds gains regulatory traction in European Union water quality directives.
- Forensic Investigation:Enantiomeric discrimination of controlled substances supports toxicological evidence standards in criminal proceedings.
Pharmaceutical Synthesis generates the highest absolute column consumption, with Environmental Screening showing the steepest upward trajectory on regulatory expansion.
End User:
Procurement centralization varies by organizational scale, with multi-site pharmaceutical manufacturers demanding supply chain security and batch traceability.
- Pharmaceutical Manufacturers:Quality control and release testing departments maintain qualified supplier lists with documented column equivalency protocols. United States innovator drug companies drive premium column demand through FDA submission requirements.
- Academic Research Institutes:Method development flexibility and publication novelty priorities favor experimental stationary phase chemistries. Swiss and Japanese universities advance immobilized polysaccharide research for aqueous-compatible applications.
- Chemical Producers:Chiral intermediate suppliers require enantiomeric excess verification for custom synthesis contracts.
- Regulatory Laboratories:Reference standard validation and proficiency testing programs demand highest batch reproducibility specifications.
Pharmaceutical Manufacturers represent the dominant procurement volume, with Academic Research Institutes expanding most quickly on public funding for analytical method innovation.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany and the United States diverge in column procurement patterns, with German laboratories prioritizing regulatory submission support while American facilities emphasize high-throughput screening velocity. Japan maintains distinct validation protocols that favor established HPLC platforms over platform migration. Switzerland and China represent contrasting growth vectors, with Swiss CROs driving SFC adoption and Chinese manufacturers scaling bioequivalence testing capacity.
Germany
EMA submission requirements and REACH silica registration obligations sustain premium column demand for regulatory laboratories. The country's chemical sector concentrates method development expertise around Frankfurt and Munich, where precision instrumentation clusters serve pharmaceutical export compliance. Baden-Württemberg hosts specialized suppliers catering to agrochemical residue testing for EU pollutant thresholds.
United States
FDA enantiomeric impurity guidelines mandate chiral purity documentation in new drug applications, forcing replacement cycles across quality control departments. EPA expansion of monitored pesticide enantiomers creates emerging demand pockets for environmental screening columns. Greater Boston and San Diego biotech corridors prioritize sub-2 µm particle formats for accelerated drug discovery timelines.
Japan
PMDA method transfer documentation requirements for imported reference standards lock laboratories into validated column inventories with limited supplier switching. METI industrial policy supports domestic cellulose and amylose derivative production, securing precursor supply for stationary phase manufacturers. Osaka pharmaceutical manufacturers maintain extensive HPLC method libraries that resist platform migration pressures.
Switzerland
Swissmedic regulatory standards and proximity to European pharmaceutical headquarters position Basel and Zurich as method development hubs. Contract research organizations deploy SFC technology for high-throughput enantiomeric excess screening in early-phase drug discovery. Swiss academic institutes advance immobilized polysaccharide research for aqueous-compatible biopharmaceutical applications.
China
NMPA bioequivalence testing reforms mandate chiral method transfer documentation for generic drug approvals, opening procurement channels for validated columns. The Yangtze River Delta pharmaceutical manufacturing belt scales quality control capacity to serve domestic and export markets. Shanghai regulatory laboratories build reference standard capabilities aligned with international acceptance criteria.
Global Chiral Chromatography Column Market Competitive Landscape
Branded specialists and contract manufacturers split share differently across segments, with full-platform vendors capturing pharmaceutical accounts through bundled service contracts while independent column suppliers serve research institutes with flexible chemistries. The market exhibits moderate consolidation around polysaccharide stationary phase production, where captive cellulose supply creates defensive moats. Three archetypes dominate: integrated analytical platform providers, specialized stationary phase manufacturers, and regional distributors with technical service capabilities. Competitive dynamics center on predictive maintenance subscription attach rates and multi-jurisdictional validation documentation.
Among integrated platform providers, Agilent Technologies, Waters Corporation, and Thermo Fisher Scientific occupy positions spanning hardware, consumables, and service portfolios. Daicel Corporation anchors the specialized stationary phase tier through Japanese-based polysaccharide derivative production. These named entities exemplify how geographic concentration of raw material supply and regulatory expertise shapes competitive positioning across the value chain.
| Leading Market Players |
|---|
| Agilent Technologies |
| Thermo Fisher Scientific |
| Waters Corporation |
| Daicel Corporation |
| Merck KGaA |
| Shimadzu Corporation |
| Bio-Rad Laboratories |
| PerkinElmer |
| Cytiva |
| Others |
Supply & Pricing Matrix
Family-owned Japanese mid-caps with captive cellulose derivative production anchor supply-side discipline, translating raw material control into pricing power over polysaccharide-based stationary phases while European REACH compliance costs compress margins for distributors lacking upstream integration.
Pricing Analysis
Capacity additions in China are reshaping price floors for standard-grade HPLC columns, forcing incumbent Japanese and German manufacturers toward premium-mid-economy pricing differentiation anchored on batch reproducibility certification and FDA submission support. Pharmaceutical quality control departments show lowest price sensitivity due to locked-inventory validation requirements, while academic research institutes drive cost compression through competitive tendering for experimental chemistries.
Supply Chain Analysis
Regional distribution centers in Frankfurt, Osaka, and Boston coordinate hub-and-spoke patterns for time-sensitive column replenishment to pharmaceutical manufacturers. Production gravity centers on Japan for derivatized polysaccharides, Germany for precision silica processing, and the United States for UPLC hardware-coupled consumables. Single-source vulnerability in amylose precursor supply from Japanese chemical conglomerates threatens continuity for coated-phase manufacturers elsewhere, while distribution runs through authorized dealer networks with technical service bundling.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market reads as a late-cycle quality story where substitution toward immobilized polysaccharide phases with extended pH stability commands specification premiums over legacy coated columns.
For Market Incumbents: Hedge polysaccharide supply exposure through backward integration into cellulose derivative production or long-term offtake agreements with Japanese precursor suppliers. Defend pharmaceutical accounts by embedding predictive maintenance subscriptions that raise switching costs, while accelerating SFC-compatible column format development to capture contract research organization procurement.
For New Entrants and Emerging Players: Immobilized polysaccharide aqueous compatibility serves as the technology-first wedge into biopharmaceutical analytical workflows previously closed to new suppliers. Target environmental screening laboratories in Germany and the United States with columns pre-validated against EPA pesticide enantiomer reference standards, using regulatory documentation as the primary go-to-market credential.
For Investors and Strategic Acquirers: Valuations sit cheapest among regional distributors with technical service capabilities but lacking captive stationary phase production, offering consolidation platforms with attach-rate expansion potential. Long-term viability hinges on multi-jurisdictional validation libraries; the signal to monitor is NMPA bioequivalence testing reform implementation pace in China.
| Strategic Initiative | Industry Significance |
|---|---|
| Captive Polysaccharide Derivative Production | Secures input supply for Japanese manufacturers against REACH-pressured European competitors. |
| SFC-HPLC Platform Convergence | Enables instrument vendors to bundle dual-technology column formats across unified workflows. |
| Predictive Maintenance Subscription | Locks pharmaceutical accounts through CrossLab-style service portfolios with batch equivalency monitoring. |
| Multi-Jurisdictional Validation Documentation | Opens procurement channels for columns demonstrating FDA, EMA, and NMPA acceptance simultaneously. |
| Immobilized Phase Aqueous Expansion | Captures biopharmaceutical antibody-drug conjugate chirality assessment demand in Swiss and US laboratories. |
Research Methodology
Direct dialogue with analytical instrumentation product managers, pharmaceutical quality control directors, regulatory affairs specialists at column manufacturers, and contract research organization procurement leads grounded qualitative findings, cross-validated against FDA 483 inspection observations, EMA marketing authorization assessment reports, EPA pesticide registration documents, and customs trade data for silica-based chromatography consumables. Bottom-up demand modeling triangulated against top-down market sizing from instrument installation base estimates.
Top-down macroeconomic filters constrained bottom-up segment projections across the analysis window, with segmentation dimensions spanning product type, technology platform, application, and end-user organizational scale. CAGRs derived from logistic diffusion curves fitted to validated method replacement cycles and capital equipment depreciation timelines, incorporating SFC adoption velocity in Swiss CROs and NMPA bioequivalence testing capacity buildout in China as industry-specific trajectory inputs.
The model holds under stable regulatory documentation requirements and continued pharmaceutical R&D intensity; deviation in EPA environmental monitoring list expansion pace or Japan METI industrial policy toward precursor export restrictions would shift demand projections. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Testing Equipment
Global Residue Testing Market
Testing Equipment
Test Point Hoses Market
Testing Equipment
Bitumen and Asphalt Testing Services Market
Testing Equipment
Sample Preparation Market
Testing Equipment
Reagent Filling Systems Market
Testing Equipment
Water Analysis Instruments Market
Testing Equipment
Laboratory Centrifuge and Accessories Market
Testing Equipment
HPLC Market
Testing Equipment
Combustion Testing Equipment Market
Testing Equipment
Paper Moisture Meter Market
Testing Equipment
Chromatography Data Systems Market
Testing Equipment
Chemisorption Analyzer Market
Testing Equipment
U-Tube Viscometer Market
Testing Equipment
Flammability Test Chamber Market
Testing Equipment
Leather Testing Machine Market
Testing Equipment
Process Analytical Technology Market