
 Clean-Up Gel Permeation Chromatography Market | 2026-2036
Clean-Up Gel Permeation Chromatography Market Size, Share, and Industry Trends Forecast 2026-2036
Clean-Up Gel Permeation Chromatography Market Analytics
Consumables and service revenue is reconfiguring margin pools away from standalone instrument sales across the clean-up gel permeation chromatography value chain. Waters Corporation sustains technology leadership through proprietary column chemistries and detection architectures. Shimadzu Corporation anchors its position with integrated HPLC-GPC platforms that reduce sample prep workflows. Agilent Technologies differentiates via diagnostic software that predicts column degradation and automates maintenance scheduling.
Clean-up gel permeation chromatography separates macromolecules by hydrodynamic volume using porous stationary-phase beads with controlled pore size distributions, typically polystyrene-divinylbenzene or silica-based matrices. The technique removes low-molecular-weight contaminants prior to downstream analysis in polymer characterization, protein aggregation studies, and environmental pollutant screening. Automated systems command premium positioning due to throughput advantages in high-volume quality control environments. Pharmaceutical applications generate the strongest growth trajectory as peptide and antibody conjugates require rigorous aggregate removal. Detection instruments represent a mature segment where incremental innovation in multi-angle light scattering is reshaping performance benchmarks.
FDA cGMP guidelines and EMA ICH Q3D impurity testing standards directly shape instrument validation protocols and column qualification requirements for pharmaceutical end users. EPA Method 3640A for sample cleanup by GPC mandates specific pore-size specifications for environmental laboratories seeking regulatory compliance. ISO 17025 accreditation frameworks drive laboratory capital investment in traceable, calibrated separation systems. Stakeholders must monitor evolving biologic drug approval pathways and tightening particulate limits in parenteral formulations to anticipate equipment refresh cycles.
Market Dynamics
Pharmaceutical laboratories are consolidating analytical workflows around single-platform solutions, compressing vendor selection criteria toward integrated hardware-software ecosystems that compress total cost of ownership across multi-year qualification cycles.
Growth Catalysts
- Biologic drug pipelines:Peptide and antibody conjugate development requires rigorous aggregate removal protocols, expanding clean-up GPC deployment in CMO quality control suites.
- EPA Method 3640A:Environmental laboratories seeking compliance must adopt pore-size-specific GPC configurations, mandating equipment refresh cycles across certified testing facilities.
- Multi-angle light scattering:Detection sensitivity improvements enable quantification of previously undetectable low-abundance aggregates, opening new analytical service revenue streams.
Market Restraints
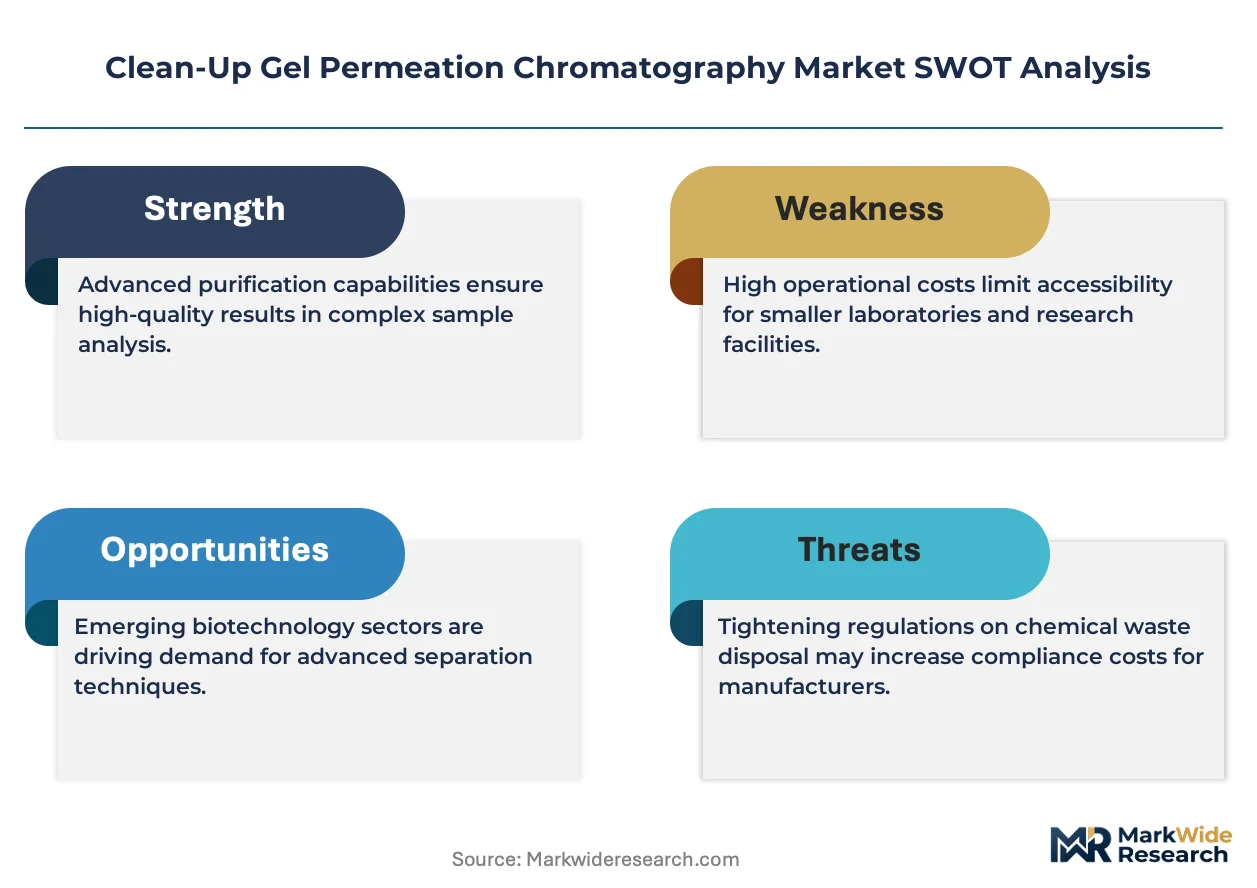
- Styrene-divinylbenzene resin supply:Controlled-pore bead manufacturing concentrates among three specialty chemical suppliers, exposing instrument OEMs to input cost volatility and allocation risk.
- Silica matrix degradation:Alkaline mobile phase compatibility limitations restrict column lifetime in high-pH bioprocessing applications, elevating consumables replacement frequency.
- ICH Q3D validation timelines:Elemental impurity testing protocol harmonization delays between FDA and EMA create dual-track qualification burdens for multinational pharmaceutical deployers.
Strategic Opportunities
- Cell and gene therapy manufacturing:Viral vector purification workflows lack standardized aggregate removal methods, creating first-mover advantage for GPC-optimized platform developers.
- India's CDMO expansion:Domestic biologics manufacturing incentives under PLI schemes attract analytical instrumentation investment from Western service providers establishing captive labs.
- HPLC-GPC convergence:Integrated dual-mode systems eliminate sample transfer steps, capturing preference from laboratories seeking footprint reduction and throughput gains.
Industry Challenges
- Metrology-qualified field service engineers:ISO 17025 traceability requirements demand specialized calibration expertise that outpaces training pipeline capacity, extending instrument commissioning timelines.
- Legacy data system integration:Pre-2015 chromatography software lacks modern cybersecurity architecture, forcing costly middleware development for regulated pharmaceutical environments.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Clean-Up Gel Permeation Chromatography Market |
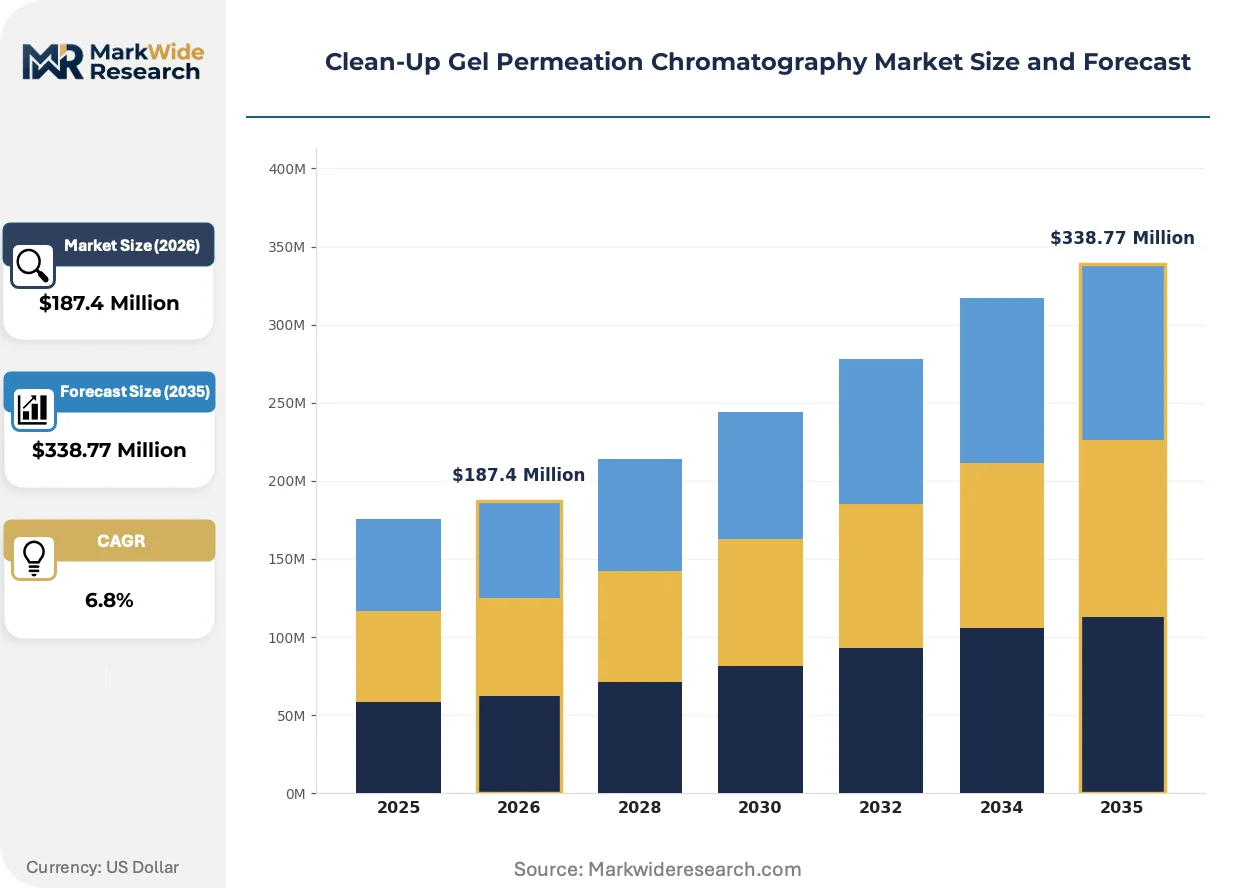
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $338.77 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Column Chromatography, Automated Systems, Manual Systems, Detection Instruments Application: Pharmaceuticals, Environmental Analysis, Biotechnology, Food Safety End User: Research Laboratories, Quality Control Labs, Academic Institutions, Pharmaceutical Companies Technology: Liquid Chromatography, High-Performance Liquid Chromatography, Supercritical Fluid Chromatography, Affinity Chromatography |
| Companies Covered | Agilent Technologies, Waters Corporation, Shimadzu Corporation, Thermo Fisher Scientific, Tosoh Corporation, Malvern Panalytical, Phenomenex, Gilson Inc., Hitachi High-Tech Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Clean-Up Gel Permeation Chromatography Market Evolving Landscape
Automation architectures are displacing manual sample prep workflows, while detection sensitivity thresholds compress and regulatory data integrity requirements harden across pharmaceutical and environmental testing verticals.
Multi-detector configurations combining refractive index with multi-angle light scattering are migrating from specialized polymer research installations toward routine quality control environments. Biopharmaceutical CMOs in the United States and Germany are standardizing these platforms for release testing of mRNA-lipid nanoparticle formulations. The technology shift is compressing competitive differentiation around detection limit specifications rather than separation resolution alone.
EMA's updated ICH Q5A viral safety guidelines now explicitly reference size-exclusion-based aggregate removal validation for recombinant protein processes. European biologics manufacturers must document GPC column qualification protocols in regulatory submissions, elevating instrument vendor documentation burdens. CDMOs serving both European and US markets are harmonizing validation templates to preempt divergent FDA and EMA inspection findings.
Service unbundling is fragmenting traditional instrument-plus-support procurement models. Large pharmaceutical buyers in Switzerland and Massachusetts now separate hardware acquisition from multi-vendor maintenance contracts, pressuring OEM service margin pools. Third-party ISO 17025-accredited calibration providers are capturing preference in high-throughput quality control environments where uptime guarantees outweigh brand loyalty.
Clean-Up Gel Permeation Chromatography Market Segmentation
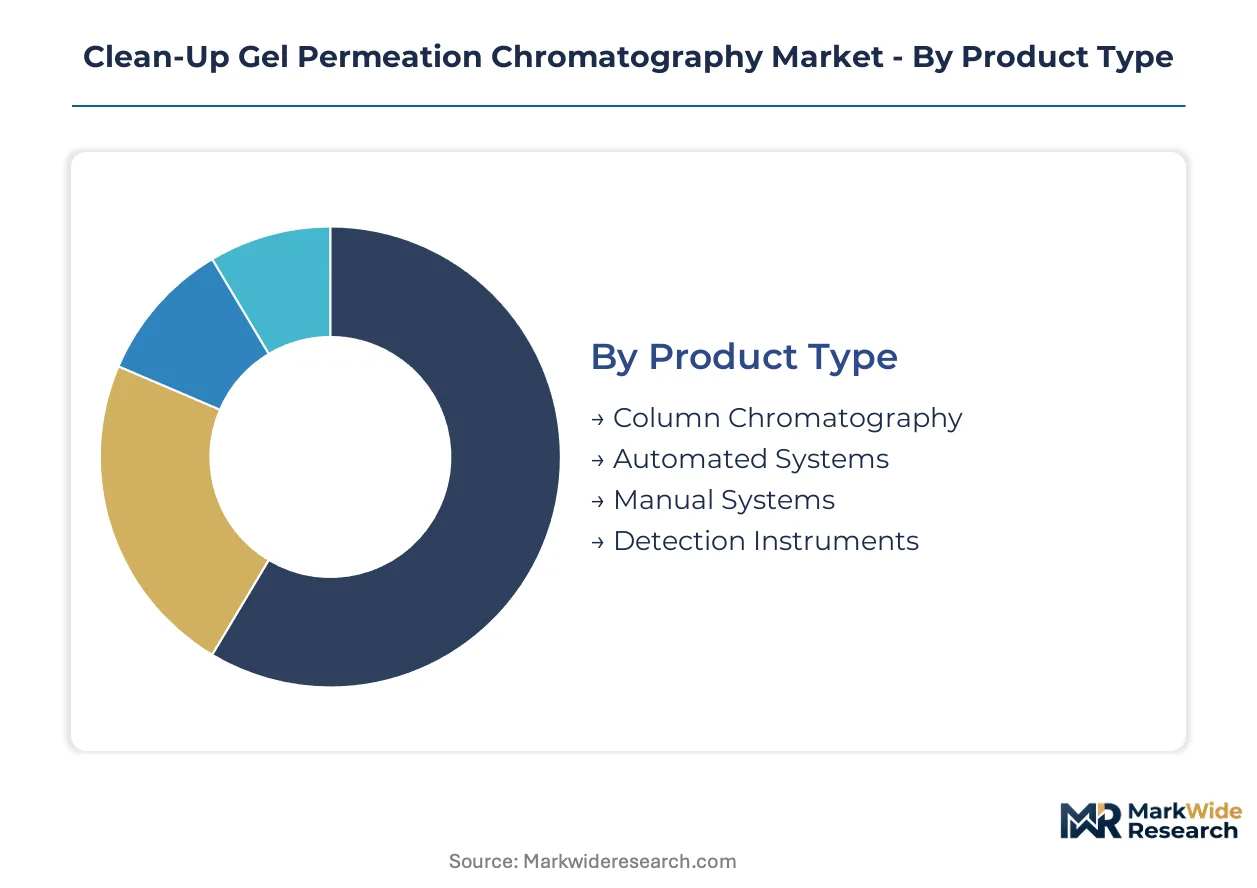
Clean-up GPC procurement decisions diverge sharply across user profiles, with pharmaceutical quality control suites demanding validated automation while environmental laboratories prioritize throughput economics. Technology choices cascade through consumables lifecycles, detection sensitivity requirements, and regulatory documentation burdens that reshape total cost structures.
Product Type:
Cost tier differentiation separates capital-intensive automated platforms from consumables-driven manual configurations in vendor pricing architectures.
- Column Chromatography:Polystyrene-divinylbenzene and silica-based stationary phases with controlled pore distributions constitute the recurring revenue backbone. Pharmaceutical companies in Massachusetts and Basel consume high-purity grades for biologic aggregate removal under FDA cGMP and Swissmedic protocols.
- Automated Systems:Integrated sample prep modules with robotic injection and fraction collection command premium positioning. United States CMOs scaling mRNA-lipid nanoparticle release testing are consolidating procurement around these platforms to compress qualification timelines.
- Manual Systems:Entry-level configurations serve academic laboratories and small environmental testing facilities with limited throughput requirements.
- Detection Instruments:Multi-angle light scattering and refractive index detectors represent mature technology with incremental sensitivity improvements reshaping performance benchmarks.
Column Chromatography holds installed capacity. Automated Systems is rotating up the share rankings.
Application:
End-use concentration in biologic drug development is compressing vendor R&D priorities toward pharmaceutical validation requirements.
- Pharmaceuticals:Peptide and antibody conjugate manufacturing mandates rigorous aggregate removal prior to downstream analysis. EMA ICH Q5A viral safety guidelines now explicitly document size-exclusion validation, forcing European manufacturers to qualify GPC protocols in regulatory submissions.
- Environmental Analysis:EPA Method 3640A mandates specific pore-size GPC configurations for pollutant screening. Certified laboratories in California and Texas face equipment refresh cycles to maintain compliance with tightened detection limits.
- Biotechnology:Cell and gene therapy viral vector purification lacks standardized methods, creating specification volatility for platform developers.
- Food Safety:Residue testing applications deploy clean-up GPC for mycotoxin and pesticide matrix interference removal in grain and dairy matrices.
Pharmaceuticals commands current revenue concentration. Environmental Analysis is gaining share fastest on regulatory compliance mandates.
End User:
Customer type determines procurement authority structures, with centralized pharmaceutical purchasing contrasting fragmented academic decision-making.
- Research Laboratories:Method development flexibility and multi-detector compatibility drive specification priorities in polymer chemistry and structural biology facilities.
- Quality Control Labs:High-throughput environments demand uptime guarantees and ISO 17025-traceable calibration protocols. Switzerland and Germany host concentrated CMO capacity with unbundled service contracts replacing traditional OEM maintenance agreements.
- Academic Institutions:Budget constraints favor manual systems and third-party refurbished instrumentation with limited validation documentation.
- Pharmaceutical Companies:Integrated hardware-software ecosystems with predictive maintenance diagnostics are compressing vendor selection criteria toward multi-year total cost of ownership models.
Quality Control Labs anchors instrument placements. Pharmaceutical Companies is climbing the fastest on biologics manufacturing expansion.
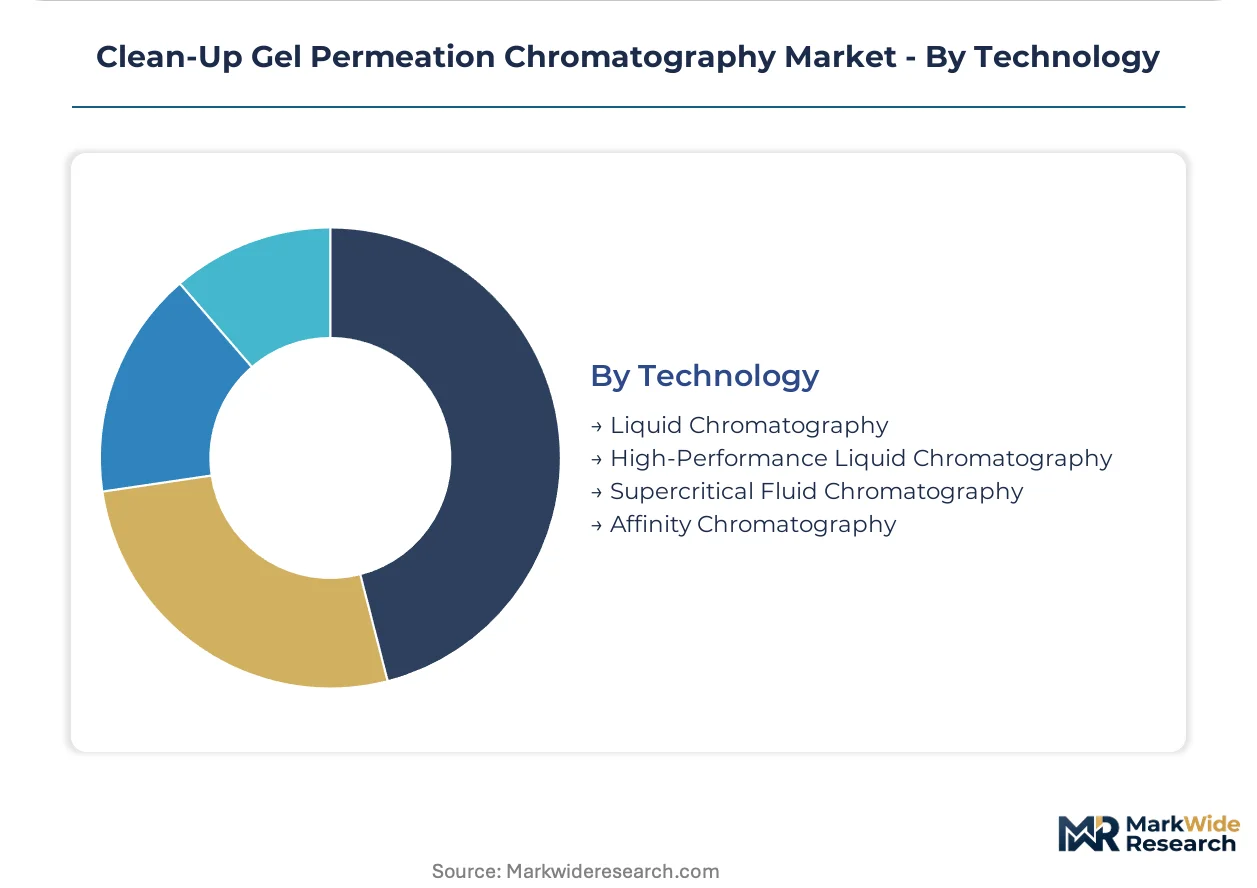
Technology:
Platform convergence between HPLC and GPC modalities is eliminating sample transfer steps in footprint-constrained laboratory environments.
- Liquid Chromatography:Conventional pressure regimes serve routine polymer characterization with established method libraries.
- High-Performance Liquid Chromatography:Elevated pressure capabilities enable sub-micron particle columns with superior resolution. United States and German biopharmaceutical CMOs are standardizing dual-mode HPLC-GPC platforms for mRNA-lipid nanoparticle release testing.
- Supercritical Fluid Chromatography:CO2-based mobile phases offer orthogonal selectivity for non-polar contaminant classes with reduced solvent disposal costs.
- Affinity Chromatography:Biospecific ligand interactions complement size-exclusion separation in complex bioprocessing workflows.
High-Performance Liquid Chromatography dominates capital allocation. Affinity Chromatography represents the steepest expansion trajectory on cell therapy purification demand.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pharmaceutical laboratories in the United States deploy clean-up GPC predominantly for biologic aggregate removal, while German environmental testing facilities emphasize high-throughput pollutant screening under stricter detection mandates. This consumption-mix differential shapes divergent vendor strategies across major markets.
United States
Contract research organizations in Massachusetts and North Carolina are scaling analytical service capacity for mRNA-lipid nanoparticle release testing. EPA Method 3640A mandates specific pore-size GPC configurations for certified environmental laboratories in California and Texas. Greater Boston hosts concentrated CMO quality control suites where automated clean-up GPC platforms compress qualification timelines.
Germany
Biopharmaceutical manufacturers in Baden-Württemberg and Bavaria standardize dual-mode HPLC-GPC platforms for viral vector purification workflows. EMA ICH Q5A viral safety guidelines now explicitly document size-exclusion validation requirements. The Rhine-Main cluster around Frankfurt anchors third-party ISO 17025-accredited calibration providers capturing unbundled service contracts.
Japan
PMDA oversight of biologic drug approvals drives instrument validation protocol harmonization for peptide and antibody conjugate manufacturers. METI industrial standards shape column qualification requirements in Osaka-based polymer research facilities. The Kansai region concentrates integrated detection system procurement for high-resolution aggregate profiling.
Switzerland
Swissmedic protocols for parenteral formulation particulate limits elevate documentation burdens for Basel-based pharmaceutical quality control labs. The country's CDMO sector separates hardware acquisition from multi-vendor maintenance contracts, pressuring OEM service margins. Zurich-area research institutions favor predictive maintenance diagnostics in total cost of ownership models.
India
Domestic biologics manufacturing incentives under PLI schemes attract analytical instrumentation investment from Western service providers establishing captive labs in Maharashtra and Karnataka. CDSCO alignment with ICH Q3D elemental impurity testing standards drives equipment refresh cycles. The Hyderabad-Visakhapatnam corridor concentrates contract manufacturing capacity requiring rigorous aggregate removal protocols.
Clean-Up Gel Permeation Chromatography Market Competitive Landscape
Capability concentration sits with integrated platform developers; scale advantage sits with diversified analytical instrument conglomerates. The vendor base organizes around three strategic archetypes: chromatography specialists with proprietary column chemistries, diversified life science conglomerates with broad detection portfolios, and precision instrument manufacturers with automated sample handling expertise. Competitive moves center on HPLC-GPC convergence platforms and unbundled service contract capture.
Among diversified analytical instrument conglomerates, Agilent Technologies, Waters Corporation, and Shimadzu Corporation occupy positions exemplifying distinct competitive vectors. Agilent Technologies represents the diagnostic software archetype with predictive maintenance capabilities. Waters Corporation anchors the proprietary column chemistry tier. Shimadzu Corporation exemplifies integrated platform convergence between HPLC and GPC modalities.
| Leading Market Players |
|---|
| Agilent Technologies |
| Waters Corporation |
| Shimadzu Corporation |
| Thermo Fisher Scientific |
| Tosoh Corporation |
| Malvern Panalytical |
| Phenomenex |
| Gilson Inc. |
| Hitachi High-Tech Corporation |
| Others |
Value Network & Pricing Analysis
Massachusetts-based contract research organizations anchor North American consumables demand, concentrating purchasing power that compresses margin structures for polystyrene-divinylbenzene resin suppliers serving pharmaceutical quality control suites.
Pricing Analysis
Long-term offtake agreements dominate consumables procurement for high-throughput CMOs, while spot purchasing persists among academic laboratories with irregular throughput. Three-tier pricing structure across premium, standard, and economy levels separates FDA-validated grades from research-use-only and refurbished configurations. Price differentiation hinges on ISO 17025 traceability documentation and bundled field service contracts. Cost compression in manual system tiers is intensifying because third-party calibration providers capture preference over OEM maintenance agreements. Academic institutions exhibit highest price sensitivity; Swiss pharmaceutical quality control labs show lowest sensitivity due to uptime guarantee requirements.
Supply Chain Analysis
Tariff exposure between the United States and China dominates raw material risk profiles for silica matrix suppliers serving environmental testing laboratories. Manufacturing concentrates in Germany, Japan, and the United States for high-performance liquid chromatography platforms. Controlled-pore bead production draws from specialty chemical suppliers in the Netherlands and Japan. Single-source vulnerability concentrates in styrene-divinylbenzene resin feedstocks. Distribution runs through authorized distributor networks for regulated pharmaceutical environments and direct e-commerce channels for research-use consumables.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Fragmentation across cell and gene therapy viral vector purification creates niche entry points as standardization lags behind biologics manufacturing expansion.
For Market Incumbents: Harden column chemistry IP positions against emerging platform developers integrating affinity chromatography modules. Secure captive supply of controlled-pore beads through backward integration into specialty resin manufacturing. Lock in multi-year consumables offtake with Massachusetts and Basel-based CMOs before qualification timelines compress vendor switching. For New Entrants and Emerging Players: India's Maharashtra CDMO corridor offers underpenetrated analytical service capacity as Western providers establish captive labs under PLI incentives. Target environmental testing facilities in California and Texas facing EPA Method 3640A equipment refresh cycles with refurbished automated platforms bundled with ISO 17025 accreditation support. Lead with unbundled service contracts that separate hardware acquisition from third-party calibration. For Investors and Strategic Acquirers: Long-term, this sits as a consumables-recurring-revenue play because column replacement frequency accelerates with biologic drug pipeline expansion. Acquisition targets should display proprietary detection architectures or validated viral vector purification protocols. Watch for CDSCO alignment with ICH Q3D standards as the signal triggering equipment refresh investment in Indian contract manufacturing.| Strategic Initiative | Industry Significance |
|---|---|
| Proprietary Column Chemistry Development | Waters Corporation's detection architectures defend pharmaceutical validation moats against integrated platform competitors. |
| HPLC-GPC Platform Convergence | Shimadzu Corporation eliminates sample transfer steps for footprint-constrained CMO quality control suites. |
| Predictive Maintenance Software Deployment | Agilent Technologies automates column degradation forecasting for Swissmedic-compliant Basel laboratories. |
| ISO 17025 Calibration Service Expansion | Third-party providers capture unbundled contracts from OEM service agreements in Germany's Rhine-Main cluster. |
| Cell Therapy Viral Vector Protocol Development | First-mover platforms secure regulatory precedence as EMA ICH Q5A guidelines harden aggregate removal requirements. |
Research Methodology
Desk research of SEC instrument manufacturer filings, EPA regulatory guidance documents, and EMA ICH submission precedents preceded structured interviews with pharmaceutical quality control directors, environmental laboratory managers, CMO procurement leads, and chromatography field service engineers. Secondary validation drew from FDA cGMP inspection databases, ISO 17025 accreditation registries, and customs trade data for chromatography instrument imports. Bottom-up instrument placement estimates triangulated against top-down consumables revenue analysis.
Assumptions held biologic drug approval pathways and EPA detection limit tightening trajectories within observed regulatory velocity patterns across the projection horizon. Segmentation modeling incorporated product type, application vertical, end-user category, and regional regulatory cluster dimensions. CAGRs derived from instrument replacement cycle analysis and consumables attach-rate projections. Viral vector purification standardization timelines and CDSCO harmonization progress served as industry-specific forecast inputs.
The forecast holds incumbent behavior within observed patterns; aggressive moves by integrated HPLC-GPC platform developers or specialty resin backward integrators would shift outcomes. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Testing Equipment
Elemental Analysis Market
Testing Equipment
FTIR Fuel Analyzer Market
Testing Equipment
Automated Solid Phase Extraction Systems Market
Testing Equipment
Stack Emissions Real-Time Speciation and Compliance Test Systems Market
Testing Equipment
Liquid Analytical Instrument Market
Testing Equipment
Global Online Coal Ash Analyzers Market
Testing Equipment
Cone Calorimeter Market
Testing Equipment
Flammability Tester Market
Testing Equipment
US Eddy-Current Testing Market
Testing Equipment
Binary High Pressure Gradient Liquid Chromatography System Market
Testing Equipment
Melting Point Apparatus Market
Testing Equipment
Mud Sediment Tester Market
Testing Equipment
Chloride Reagents Kits Market
Testing Equipment
Lactose Assay Kit Market
Testing Equipment
Laboratory Mixer Market
Testing Equipment
Drop Weight Tear Tester Market