
 US Eddy-Current Testing Market | 2026-2036
US Eddy-Current Testing Market Size, Share, and Industry Trends Forecast 2026-2036
US Eddy-Current Testing Market Insights
Buyer concentration in US aerospace MRO is decoupling from traditional defense primes as commercial airlines and regional jet operators build in-house eddy-current capabilities. Mistras Group leverages its refinery inspection footprint to cross-sell automated testing systems. Eddyfi anchors its position through advanced multi-frequency instrumentation for complex geometries. Bureau Veritas competes by bunding eddy-current services with broader asset-integrity programs.
Eddy-current testing employs electromagnetic induction to detect surface and near-surface defects in conductive materials without destroying the test piece, operating across frequency ranges from hertz to megahertz to penetrate varying depths. Portable systems lead equipment shipments due to field deployment demands in pipeline and power-plant inspections, while automated installations capture margin pools in high-volume automotive and aerospace production lines. Material inspection applications dominate volume as operators screen incoming bar stock and forgings, though weld testing grows fastest from pipeline construction codes and pressure-vessel standards.
FAA airworthiness regulations, ASME Section V codes, and OSHA process-safety mandates collectively shape equipment specifications and operator-certification requirements across US industrial facilities. The EPA's refinery-sector enforcement priorities further tighten inspection intervals for storage tanks and heat-exchanger tubing. Stakeholders must monitor how NIST calibration standards and evolving AI-assisted defect-recognition protocols reshape competitive requirements for instrumentation accuracy and data-traceability.
Market Dynamics
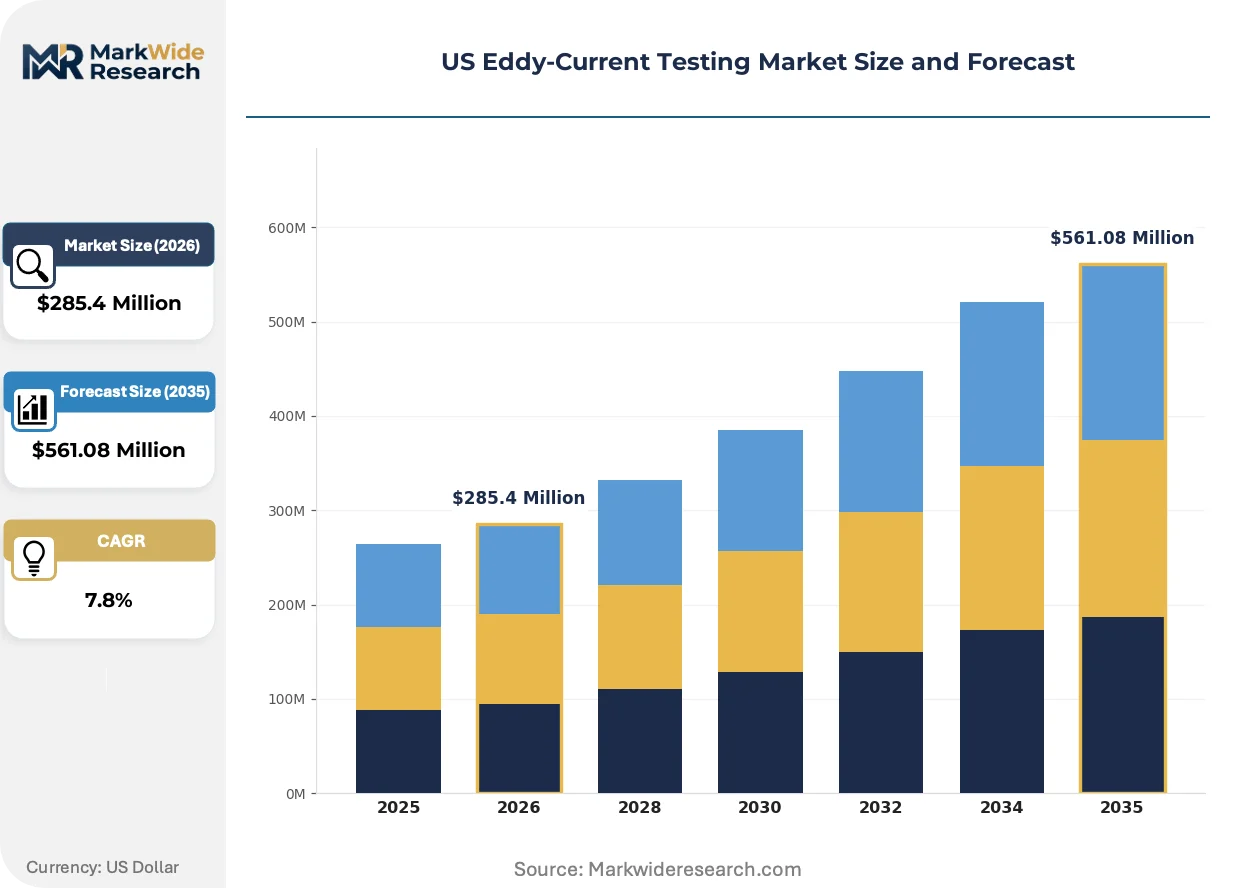
The US eddy-current testing market is compressing around automation mandates from FAA airworthiness directives and ASME Section V code revisions, forcing inspection providers to retire analog systems faster than replacement cycles would naturally allow.
Growth Catalysts
- FAA Airworthiness Directives:Mandated turbine blade inspections for commercial aviation fleets are expanding scheduled maintenance windows for eddy-current systems.
- Refinery cluster concentration:Texas and California petrochemical corridors drive recurring instrument procurement for heat-exchanger tubing inspection programs.
- Multi-frequency array probes:Advanced coil configurations now resolve complex geometries in additive-manufactured aerospace components previously requiring destructive testing.
Market Restraints
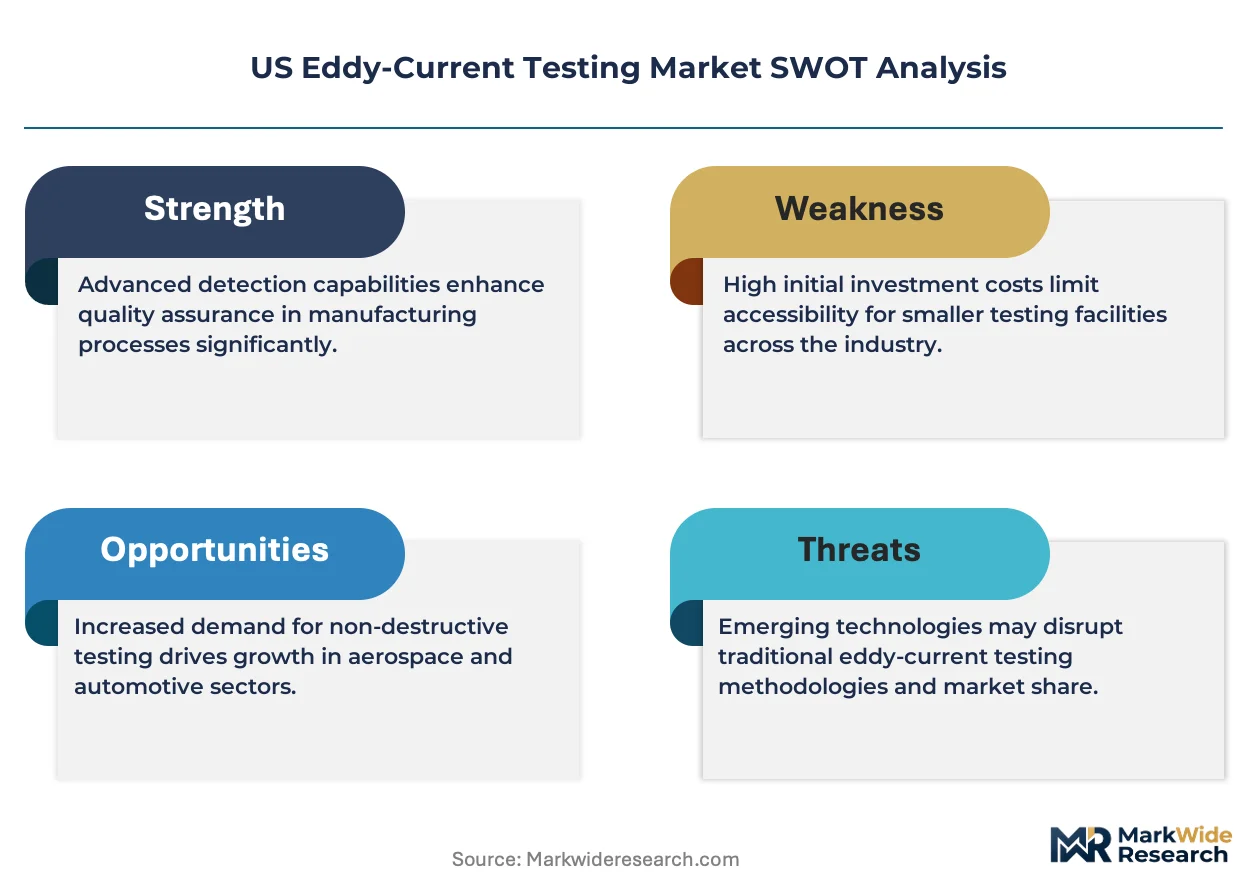
- Copper and rare-earth magnet costs:Probe manufacturing faces input volatility from concentrated Chinese refined copper supply.
- ASME Section V certification timelines:Operator qualification requirements extend deployment lead times for new inspection teams.
- Ultrasonic phased-array substitution:Alternative NDT methods capture share in thick-section weld applications where eddy-current penetration depth falls short.
Strategic Opportunities
- AI-assisted defect recognition:Machine learning integration with eddy-current data streams enables automated pass-fail decisions reducing interpreter dependency.
- In-house MRO capability builds:Regional airlines and cargo operators in the Southeast are establishing captive inspection shops outside traditional third-party networks.
- Pipeline construction codes:PHMSA integrity management rules for gas transmission lines mandate expanded crack detection coverage in high-consequence areas.
Industry Challenges
- ASNT Level III examiner scarcity:Certification bottlenecks constrain workforce scaling for peak turnaround seasons at Gulf Coast refineries.
- Legacy system integration:Field-proven analog instruments resist replacement due to embedded procedural documentation and operator familiarity.
- Data traceability mandates:NIST calibration standards and audit trail requirements complicate multi-site fleet standardization for distributed inspection operations.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | US Eddy-Current Testing Market |
| Market Size in 2026 | $285.4 Million |
| Market Size in 2035 | $561.08 Million |
| CAGR (2026 – 2036) | 7.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Handheld, Portable, Fixed, Automated End User: Aerospace, Automotive, Energy, Manufacturing Application: Material Inspection, Weld Testing, Surface Defect Detection, Thickness Measurement Technology: AC, DC, Multi-Frequency, Digital |
| Companies Covered | Mistras Group, Bureau Veritas, Element Materials Technology, Eddyfi, ETher NDE, Waygate Technologies, Magnetic Analysis Corporation, Zetec, Applied Technical Services, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
US Eddy-Current Testing Market Trends and Innovations
Digital instrumentation architectures are displacing analog signal chains across US inspection operations, compressing hardware replacement cycles while elevating software and data analytics to primary competitive differentiation.
Remote-field eddy-current technology is modularizing inspection system architecture for deep-ferrous penetration applications. Pipeline operators in the Permian Basin are adopting these systems for unpiggable line assessment. The technology is modularizing what were previously integrated probe-instrument combinations into swappable sensor heads compatible with shared acquisition platforms.
EPA refinery-sector enforcement priorities are tightening inspection intervals for storage tank floors and pressure-vessel circuits. Facilities in the Houston Ship Channel corridor are accelerating eddy-current deployment for corrosion under insulation detection. Heat-exchanger tubing bundles represent the most affected equipment category, with operators contracting specialized inspection services ahead of turnaround windows.
Equipment-as-a-service arrangements are displacing capital purchase models among mid-size aerospace subcontractors. Third-party providers now bundle instrument access with certified operator deployment and cloud-based data archiving. California and Washington State machine shops show the highest penetration of this consumption-pattern shift, driven by cash-flow sensitivity and irregular inspection volumes.
US Eddy-Current Testing Market Segmentation
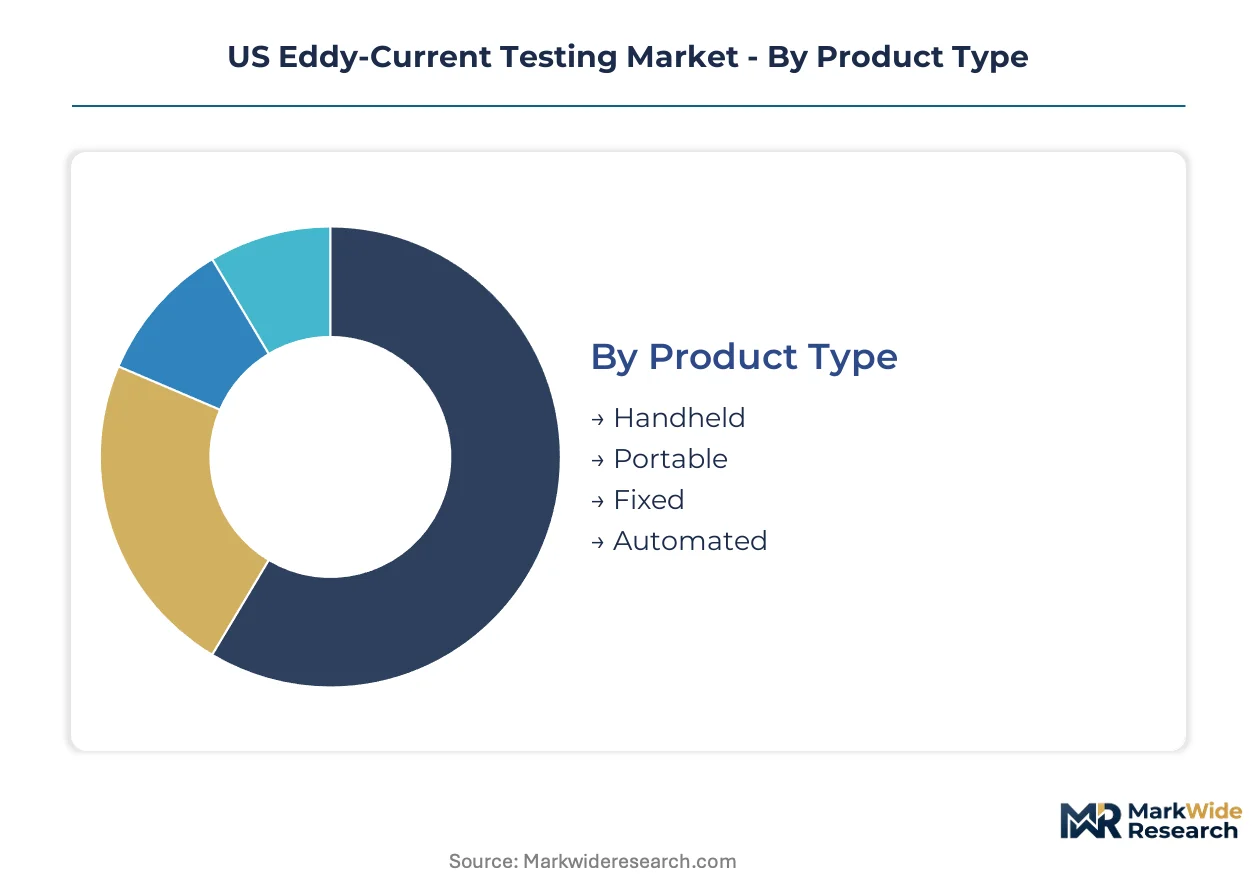
US eddy-current testing market segmentation reveals how FAA airworthiness directives and ASME Section V codes differentially burden each equipment category and end-use vertical. Certification requirements fragment procurement patterns across aerospace MRO shops, Gulf Coast refineries, and automotive production lines.
Product Type:
FAA Part 145 repair station certifications and OSHA process-safety mandates impose distinct operator-qualification burdens across portable versus fixed installations.
- Handheld:Single-operator units with simplified coil configurations target quick-turn airframe spot checks. Demand concentrates in California aerospace subcontractors facing irregular inspection volumes and cash-flow constraints that resist capital deployment.
- Portable:Battery-powered systems with modular probe arrays dominate pipeline integrity programs across Texas Permian Basin operations. PHMSA crack-detection mandates for high-consequence areas drive recurring procurement as operators field multiple crews simultaneously.
- Fixed:Bench-mounted installations serve incoming material screening at Ohio and Michigan forging facilities. ASME Section V compliance documentation favors permanent laboratory configurations with embedded calibration traceability.
- Automated:Robotic scanning arrays integrate with production lines at South Carolina and Washington aerospace manufacturing corridors. Multi-frequency probe synchronization enables complex geometry inspection of additive-manufactured turbine components.
Leading the category by volume: Portable systems. Growing fastest: Automated installations.
End User:
Customer procurement maturity spans captive in-house builds to third-party service outsourcing, reshaping equipment-versus-service revenue mix.
- Aerospace:OEM production lines and FAA-mandated MRO operations drive multi-frequency instrumentation for turbine blade and landing gear inspection. Southeast regional airlines are building captive capabilities outside traditional third-party networks.
- Automotive:High-volume production environments favor automated eddy-current systems for crankshaft and camshaft surface defect screening. Michigan and Ohio powertrain plants represent concentrated demand pockets.
- Energy:Texas and California refinery clusters sustain recurring heat-exchanger tubing inspection programs. EPA enforcement priorities tighten turnaround intervals for corrosion-under-insulation detection.
- Manufacturing:Machine shops and metal fabricators deploy portable systems for incoming bar stock verification and weld quality assurance. Equipment-as-a-service arrangements gain traction among mid-size California subcontractors.
Dominant by procurement value: Aerospace. Expanding most quickly: Energy sector integrity programs.
Application:
Defect-detection depth requirements and surface accessibility constraints determine frequency selection and probe configuration across use cases.
- Material Inspection:Incoming ferrous and non-ferrous stock screening at forging facilities and service centers. Bar stock diameter variations drive multi-frequency probe demand for consistent penetration depth.
- Weld Testing:Pipeline girth weld and pressure-vessel seam inspection face ASME Section V and API code mandates. Ultrasonic phased-array methods compete in thick-section applications where eddy-current penetration falls short.
- Surface Defect Detection:Crack and pit identification in aircraft skins, turbine blades, and heat-exchanger tubes. FAA airworthiness directives specifically prescribe eddy-current methods for certain fatigue-prone locations.
- Thickness Measurement:Corrosion monitoring in storage tank floors and insulated piping circuits. Remote-field technology extends measurement range in deep-ferrous structures common to refinery equipment.
Highest volume segment: Material inspection. Steepest expansion trajectory: Weld testing from pipeline construction codes.
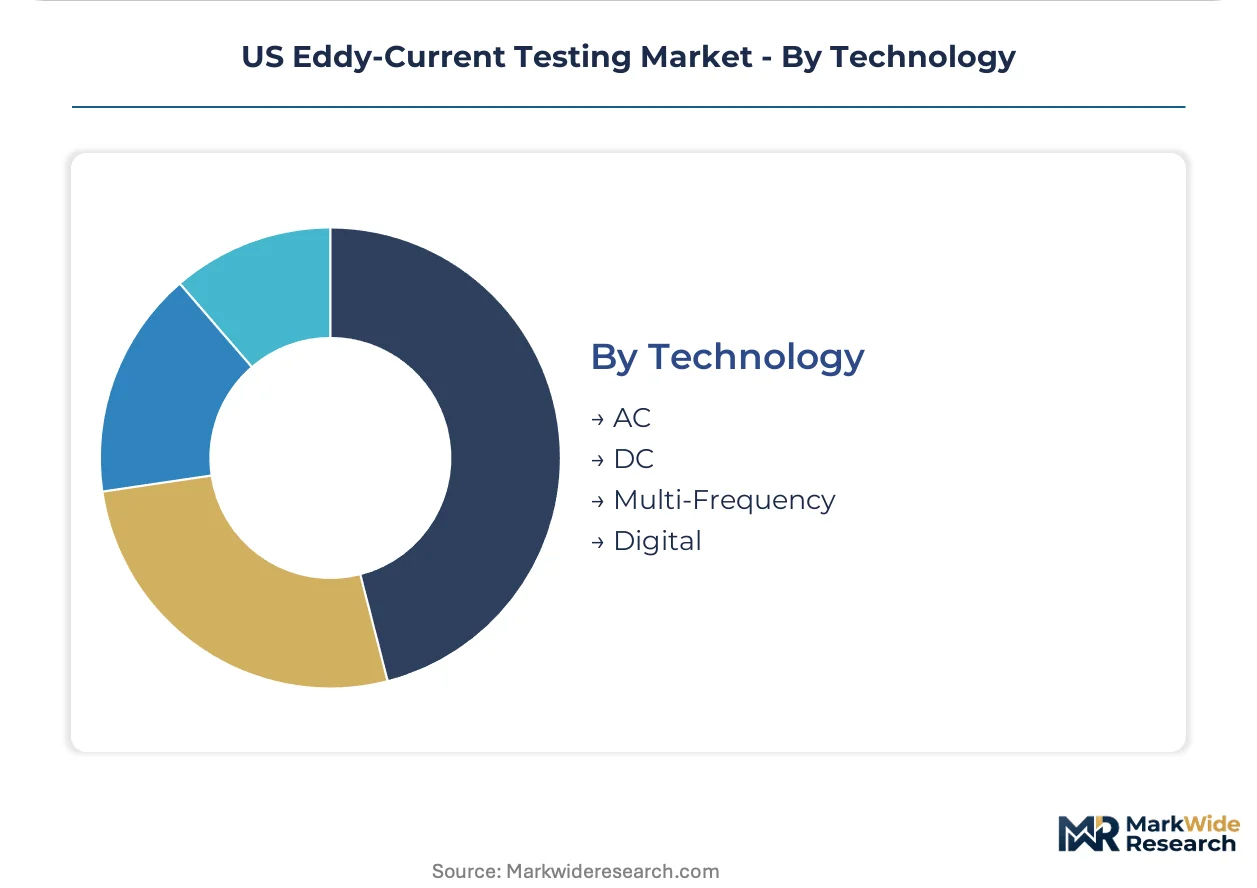
Technology:
Signal processing architecture choices determine calibration complexity, data traceability, and integration paths for AI-assisted defect recognition.
- AC:Alternating current excitation at single frequencies targets specific penetration depths in routine inspections. Legacy analog AC systems resist replacement due to embedded procedural documentation at established facilities.
- DC:Direct current methods penetrate subsurface features in ferromagnetic materials. Limited adoption outside specialized geological and structural applications constrains market presence.
- Multi-Frequency:Simultaneous excitation across harmonic bands resolves complex geometries in additive-manufactured aerospace components. Eddyfi and specialized vendors anchor competitive positioning through advanced coil configurations.
- Digital:Software-defined architectures displace analog signal chains, elevating data analytics and cloud archiving to primary differentiation. NIST calibration standards and audit trail requirements favor digital traceability for distributed operations.
Commanding current installed base: AC systems. Gaining share fastest: Digital architectures.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Copper refining capacity along the Gulf Coast anchors probe manufacturing supply chains for US eddy-current instrument production. Texas and California petrochemical corridors concentrate demand for heat-exchanger tubing inspection programs. FAA airworthiness enforcement and EPA refinery-sector priorities differentially shape procurement intensity across sub-regional industrial clusters.
Texas Gulf Coast
Houston Ship Channel refineries sustain recurring instrument procurement for corrosion-under-insulation detection in storage tank circuits. EPA enforcement priorities compress inspection intervals for pressure-vessel tubing bundles ahead of turnaround windows. Port Arthur and Baytown petrochemical complexes contract specialized eddy-current services for heat-exchanger integrity programs.
California
Aerospace subcontractors in Los Angeles and San Diego counties face irregular inspection volumes that favor equipment-as-a-service arrangements over capital deployment. FAA Part 145 repair station certifications impose distinct operator-qualification burdens on commercial MRO operations. Bay Area machine shops deploy portable systems for incoming bar stock verification in precision manufacturing.
Southeast
Regional airlines and cargo operators in Florida and Georgia are establishing captive inspection capabilities outside traditional third-party MRO networks. Boeing and Lockheed Martin supply chain proximity drives multi-frequency instrumentation demand for turbine component screening. Charleston and Savannah aerospace manufacturing corridors integrate automated scanning arrays with production lines.
Midwest
Ohio and Michigan forging facilities deploy bench-mounted installations for incoming material screening with embedded ASME Section V calibration traceability. Detroit powertrain plants favor automated eddy-current systems for crankshaft surface defect detection in high-volume environments. Chicago-area metal service centers use portable systems for weld quality assurance in structural fabrication.
Pacific Northwest
Boeing production lines in Washington State drive multi-frequency probe synchronization for additive-manufactured aerospace components. Portland-area precision machine shops show elevated penetration of consumption-based equipment access models. Hanford nuclear reservation and regional power plants deploy remote-field technology for deep-ferrous penetration in unpiggable line assessment.
US Eddy-Current Testing Market Competitive Landscape
Established producers occupy the standard tier; emerging entrants pursue AI-assisted defect recognition and cloud-based data archiving. The vendor base clusters around three archetypes: diversified inspection service conglomerates, specialized instrumentation manufacturers, and integrated NDT technology platforms. Consolidation pressure favors players with captive refinery and aerospace customer relationships. Dominant competitive moves include cross-selling automated systems through existing inspection service footprints and bundling hardware access with certified operator deployment.
Within the diversified service tier, Mistras Group and Bureau Veritas exemplify players leveraging refinery inspection footprints to anchor equipment procurement relationships. Eddyfi occupies a position among specialized instrumentation developers focused on advanced multi-frequency coil configurations. These three represent distinct strategic postures: service-led cross-selling, integrated asset-integrity bundling, and technology-driven product specialization.
| Leading Market Players |
|---|
| Mistras Group |
| Bureau Veritas |
| Element Materials Technology |
| Eddyfi |
| ETher NDE |
| Waygate Technologies |
| Magnetic Analysis Corporation |
| Zetec |
| Applied Technical Services |
| Others |
Pricing and Supply Chain Analysis
Digital instrumentation architectures displacing analog signal chains simultaneously compress hardware replacement cycles and concentrate margin capture among software-integrated vendors. Equipment-as-a-service arrangements reshape procurement economics across California aerospace subcontractors and Texas refinery operators.
Pricing Analysis
Warranty and calibration service bundling separates premium-tier vendors from unbundled equipment suppliers. Three-tier pricing structure across premium, standard, and economy levels tracks certification grade and probe frequency range. Price differentiation hinges on ASME Section V documentation depth and NIST traceability protocols. Cost compression in the standard tier intensifies as Chinese probe manufacturers expand direct distribution. Regional airlines building captive MRO capabilities exhibit highest price sensitivity; automated production-line buyers at South Carolina aerospace corridors show lowest.
Supply Chain Analysis
Dual-sourcing requirements for ASNT-certified probe coils mandate multi-supplier qualification across domestic and Mexican manufacturing facilities. Copper refining concentrates in Chile, Peru, and China. Rare-earth magnet processing draws from Chinese and Malaysian facilities. Coil winding and final assembly rests on Texas and Ohio production plants. Single-source vulnerability in refined rare-earth supply creates procurement risk. Distribution runs through authorized service centers co-located with Gulf Coast refinery clusters and California aerospace corridors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The US eddy-current testing market sits in a technology-transition phase where digital architectures and AI-assisted defect recognition displace legacy analog systems. FAA mandates and ASME code revisions accelerate this replacement cycle.
For Market Incumbents: Deepen vertical integration into probe coil manufacturing to offset Chinese rare-earth magnet volatility. Expand certified operator training programs to capture ASNT Level III examiner scarcity as a competitive moat against ultrasonic phased-array substitution threats. For New Entrants and Emerging Players: AI-assisted defect recognition software offers a technology-first wedge into the inspection services tier. Target Southeast regional airlines establishing captive MRO capabilities outside incumbent third-party networks. Lead with cloud-based data archiving bundled with equipment access to penetrate California equipment-as-a-service demand. For Investors and Strategic Acquirers: Exit pathways concentrate in strategic acquisitions by diversified inspection conglomerates seeking refinery and aerospace customer relationships. Long-term viability favors vendors with embedded software analytics and recurring service revenue. Watch FAA airworthiness directive expansion timelines as inflection indicators for replacement demand spikes.| Strategic Initiative | Industry Significance |
|---|---|
| AI-Assisted Defect Recognition Development | Machine learning integration reduces interpreter dependency for ASME-compliant inspection workflows. |
| Equipment-as-a-Service Model Expansion | Cloud-archived data and certified operator bundling penetrates California aerospace subcontractor demand. |
| Multi-Frequency Probe Specialization | Advanced coil configurations resolve additive-manufactured turbine geometries for FAA-mandated MRO. |
| ASNT Certification Program Investment | Captive examiner training addresses Gulf Coast refinery turnaround workforce bottlenecks. |
| Refinery Corridor Service Center Expansion | Co-located calibration and probe inventory tightens response times for EPA-mandated inspection intervals. |
Research Methodology
Document review covered FAA airworthiness directives, ASME Section V code revisions, EPA refinery enforcement priorities, and NIST calibration standards, complemented by interviews with NDT service company executives, aerospace MRO procurement managers, refinery turnaround planners, and instrument manufacturer product directors. Secondary sources included FAA certification databases, PHMSA pipeline integrity filings, and customs trade data on copper and rare-earth imports. Bottom-up equipment shipment estimates triangulated against top-down service revenue aggregates.
Cross-referencing historical replacement cycles with expert panel input on FAA mandate timing shaped the projection framework. Segmentation dimensions spanned product type, end-use vertical, application depth requirement, and technology architecture. CAGRs derived from equipment-as-a-service penetration curves and refinery capital expenditure patterns. Forecast inputs incorporated probe manufacturing cost indices and ASNT certification pipeline constraints.
Several conditions sit outside the modeled scope, including specific FAA directive issuance dates, tariff rate modifications on Chinese rare-earth imports, and breakthrough ultrasonic technologies penetrating eddy-current applications. Deviation in EPA enforcement intensity or ASME code revision timing would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Testing Equipment
Membrane Osmometer Market
Testing Equipment
Analytical Gel Permeation Chromatography Market
Testing Equipment
Polymer Testing Equipment Market
Testing Equipment
Pitting Machines Market
Testing Equipment
Hydrocarbon Tester Market
Testing Equipment
Benchtop Density Meter for Solids Market
Testing Equipment
Clean-Up Gel Permeation Chromatography Market
Testing Equipment
U-Tube Viscometer Market
Testing Equipment
Laboratory Balances and Scales Market
Testing Equipment
Global Oxidative Stress Assay Market
Testing Equipment
Global Dynamic Mechanical Analyzers Market
Testing Equipment
North America Dissolved Gas Analyzer Market
Testing Equipment
Durometers Market
Testing Equipment
Chemical Warfare Agent Detectors Market
Testing Equipment
Cone Calorimeter Market
Testing Equipment
Chemisorption Analyzer Market