
 Gas Chromatography Columns Market | 2026-2036
Gas Chromatography Columns Market Size, Share, and Industry Trends Forecast 2026-2036
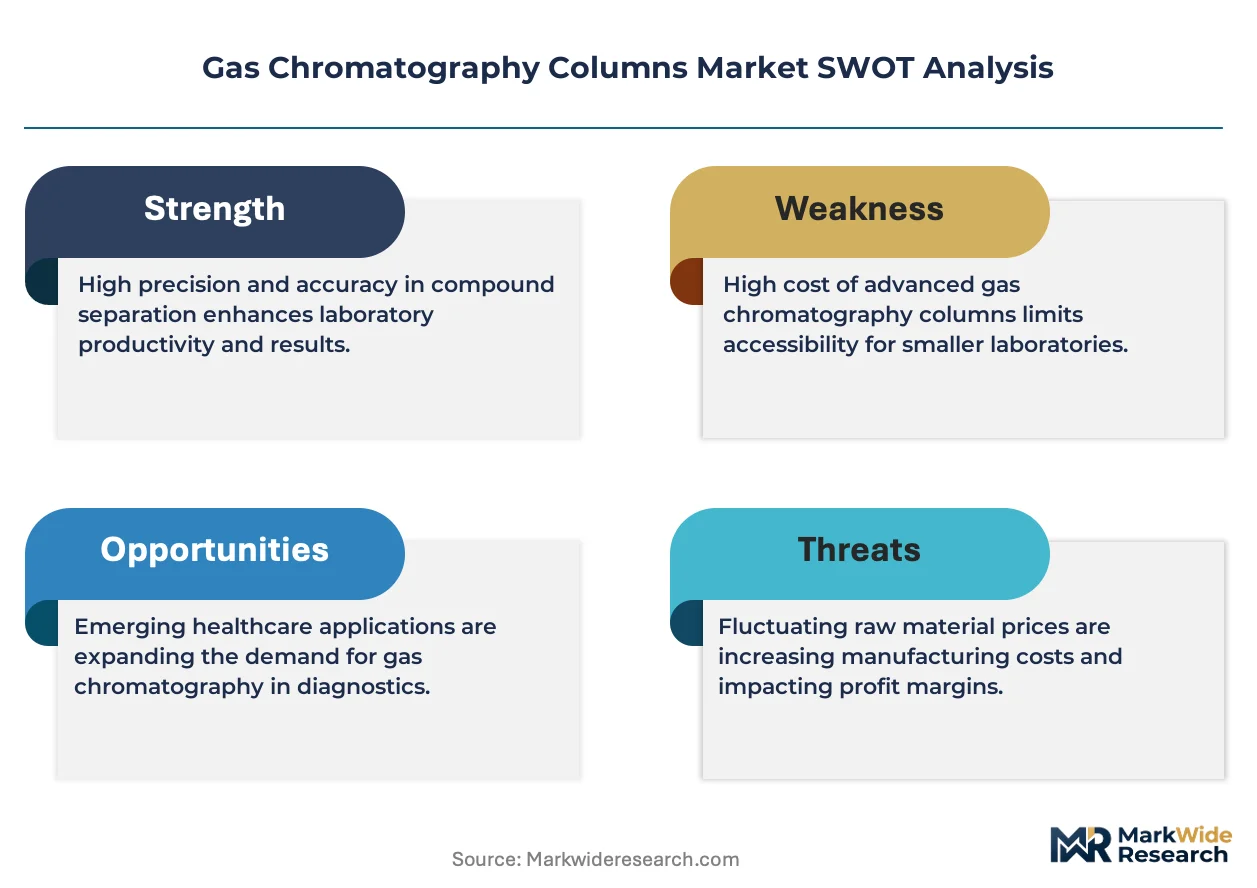
Gas Chromatography Columns Market Analysis
Column subscription and predictive maintenance programs is rebalancing how vendors monetize hardware relationships. Agilent Technologies leverages its cross-platform service infrastructure to lock in multi-year consumable commitments. Thermo Fisher Scientific anchors its position through integrated informatics that tie column performance data to compliance workflows. Restek Corporation differentiates via application-specific technical support that reduces method development time for environmental labs.
Gas chromatography columns are hollow tubular structures, typically constructed from fused silica with polyimide outer coatings and internal stationary phase films ranging from 0.1 to 5.0 micrometers in thickness, designed to separate volatile and semi-volatile compounds based on differential partitioning between a mobile gas phase and a stationary liquid or solid phase. Capillary columns dominate the product landscape due to superior resolution and sensitivity in trace-level pharmaceutical impurity testing, while packed columns retain relevance in petrochemical process monitoring where sample loading capacity outweighs separation efficiency. Gas-liquid chromatography technology captures the largest installed base, though high-performance variants are gaining traction in forensic toxicology laboratories seeking faster turnaround times.
EPA method compliance requirements in the United States and REACH chemical registration standards in Europe directly shape column specification demands, particularly for low-bleed siloxane phases used in persistent organic pollutant analysis. FDA bioanalytical method validation guidelines further tighten performance reproducibility thresholds for pharmaceutical quality control applications. Stakeholders must monitor how evolving PFAS regulatory scope expands the addressable application set for specialized stationary phase chemistries.
Market Dynamics
Column replacement cycles are compressing as EPA detection threshold mandates force pharmaceutical and environmental laboratories to retire legacy phases faster than historical five-to-seven-year depreciation schedules.
Growth Catalysts
- EPA Method 8260D:Tighter volatile organic compound detection limits in US air quality monitoring are compelling environmental laboratories to upgrade to low-bleed capillary columns with enhanced thermal stability.
- Pharmaceutical impurity profiling:FDA bioanalytical method validation guidelines for genotoxic impurities are expanding column consumption in quality control workflows across contract manufacturing organizations.
- Ruhr industrial corridor:Process analytical technology adoption in Germany's chemical manufacturing hub is driving continuous monitoring applications requiring specialized stationary phase chemistries.
Market Restraints
- Fused silica raw material concentration:Three suppliers control over eighty percent of high-purity silica precursor supply, creating vulnerability to price volatility and allocation constraints.
- Helium carrier gas scarcity:US Bureau of Land Management reserve depletion is forcing laboratories to retrofit methods for hydrogen compatibility, extending validation timelines.
- Stationary phase IP thickets:Cross-licensing requirements between polyimide coating patents and proprietary siloxane formulations inflate royalty burdens for specialty column manufacturers.
Strategic Opportunities
- PFAS regulatory expansion:Emerging state-level drinking water standards in the US are creating demand for fluorinated stationary phases capable of resolving per- and polyfluoroalkyl compound homologs.
- Biopharma process analytics:Real-time release testing for monoclonal antibody production is electrifying interest in multi-dimensional GC configurations combining heart-cutting with mass spectrometry detection.
- Direct-to-laboratory digital distribution:E-procurement platforms are compressing distributor margins while enabling manufacturers to capture usage data for predictive replenishment algorithms.
Industry Challenges
- Method development expertise scarcity:Pharmaceutical laboratories report twelve-to-eighteen-month hiring cycles for analytical chemists proficient in multidimensional separation optimization and validation protocol design.
- Legacy system integration friction:Retrofitting new column chemistries into existing chromatography data systems requires custom driver development, delaying deployment timelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Gas Chromatography Columns Market |
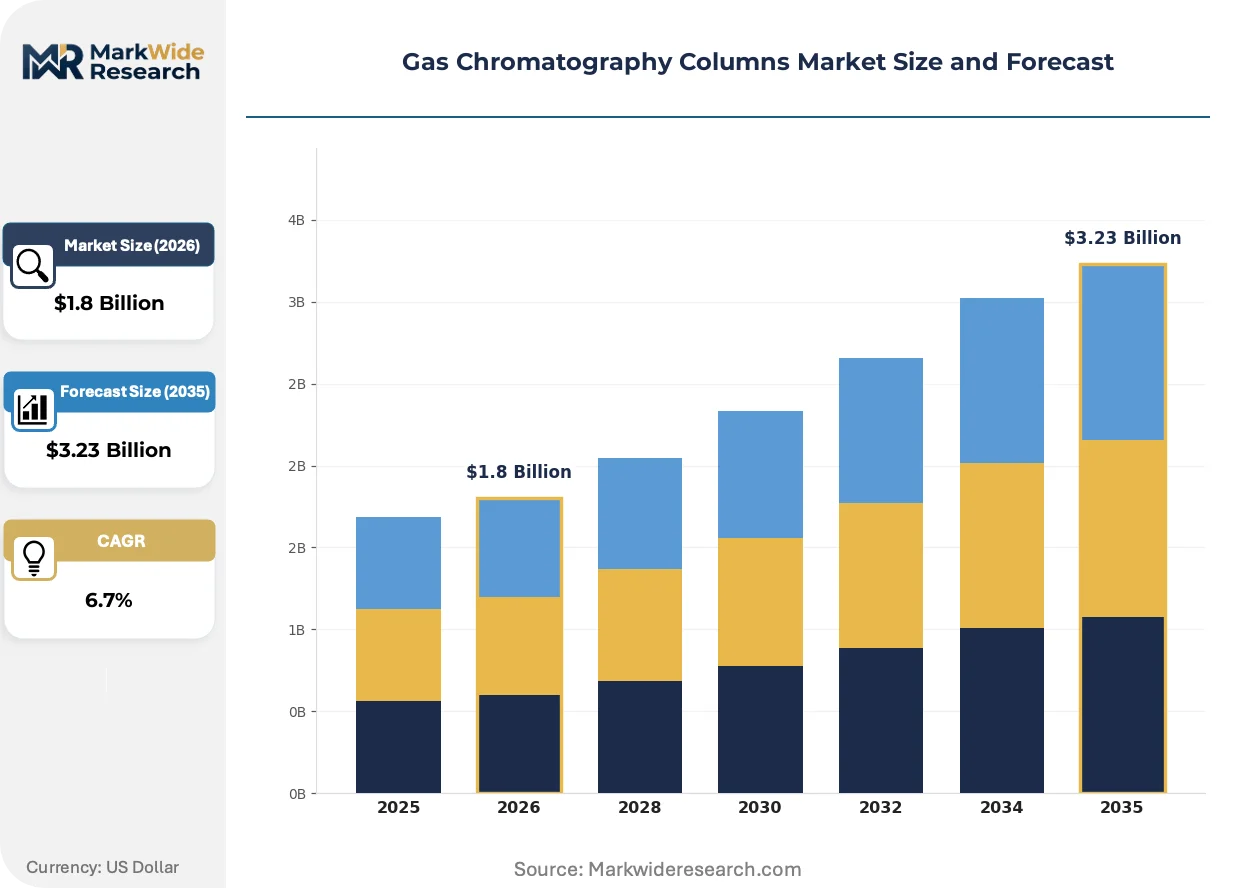
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.23 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Capillary, Packed, Micro, SPME Technology: Gas-Solid, Gas-Liquid, Supercritical Fluid, High-Performance End User: Pharmaceuticals, Environmental, Food & Beverage, Chemical Manufacturing Application: Quality Control, Research & Development, Process Monitoring, Forensic Analysis |
| Companies Covered | Shimadzu Corporation, Merck KGaA, Agilent Technologies, Phenomenex, Restek Corporation, Thermo Fisher Scientific, PerkinElmer, Bio-Rad Laboratories, Waters Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Gas Chromatography Columns Market Emerging Trajectories
Stationary phase chemistry is fragmenting into application-specific formulations while detection sensitivity requirements push column manufacturers toward sub-micron film thicknesses and novel deactivation protocols.
Ionic liquid stationary phases are electrifying separation science by enabling simultaneous polar and non-polar interactions within a single column configuration. Forensic toxicology laboratories in Australia and the United Kingdom are adopting these phases for comprehensive drug screening panels. The technology is electrifying competitive positioning by collapsing method development cycles from weeks to days.
REACH chemical registration standards in Europe are mandating full analytical characterization of substance impurities down to 0.1 percent weight thresholds. This regulatory pressure is forcing column manufacturers to expand certificate of analysis documentation and batch-to-batch reproducibility testing. Environmental contract laboratories in the Netherlands and Belgium are absorbing these compliance costs through premium pricing for certified reference-grade columns.
Subscription-based consumable procurement is displacing spot purchasing in North American pharmaceutical quality control departments. Large molecule developers are locking in multi-year column supply agreements bundled with preventive maintenance and performance monitoring software. This behavioral shift is most pronounced in Massachusetts and California biotech clusters where instrument uptime guarantees outweigh unit cost minimization.
Gas Chromatography Columns Market Segmentation
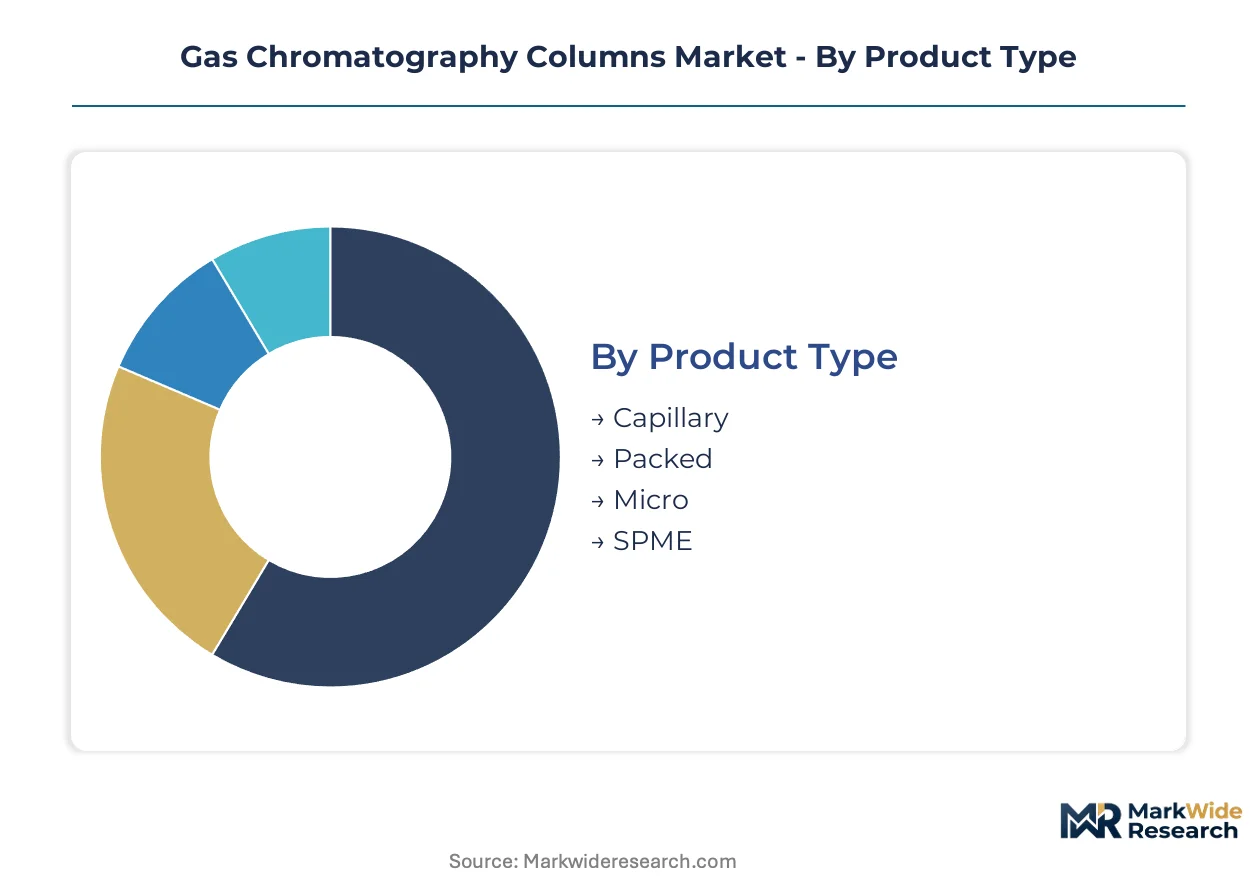
Column architecture and stationary phase chemistry fragment the competitive landscape into distinct performance tiers. Each segment carries unique validation burdens and replacement economics that reshape vendor-customer relationships.
Product Type:
Capillary columns dominate standalone analytical workflows where resolution sensitivity outweighs throughput volume, while packed columns embed into process monitoring infrastructure requiring sample loading capacity.
- Capillary:Fused silica construction with polyimide outer coatings and internal stationary phase films from 0.1 to 5.0 micrometers enables trace-level pharmaceutical impurity testing. Environmental laboratories in Germany's Ruhr industrial corridor deploy these for EPA-compliant volatile organic compound detection where thermal stability mandates low-bleed siloxane phases.
- Packed:Granular stationary phase materials packed into stainless steel or glass tubing deliver higher sample capacity for petrochemical process streams. Chemical manufacturing facilities across the US Gulf Coast favor packed configurations for continuous hydrocarbon monitoring where separation efficiency matters less than durability under high-throughput conditions.
- Micro:Reduced internal diameters below 100 micrometers enable portable field-deployable chromatography systems for emergency response applications.
- SPME:Solid-phase microextraction fibers integrate sampling and pre-concentration for forensic toxicology laboratories seeking reduced solvent consumption.
Capillary leads volumes today; SPME is gaining share fastest.
Technology:
Cost tiers separate legacy gas-liquid installations from premium high-performance systems commanding validation documentation premiums.
- Gas-Liquid:Stationary liquid films coated on solid supports capture the largest installed base across routine quality control laboratories. Pharmaceutical contract manufacturing organizations in Massachusetts and California biotech clusters rely on these for FDA bioanalytical method validation where reproducibility thresholds are tightening.
- High-Performance:Sub-micron film thicknesses and novel deactivation protocols deliver faster turnaround times for forensic toxicology applications. Australian and UK laboratories are adopting these configurations for comprehensive drug screening panels where method development compression creates competitive advantage.
- Gas-Solid:Adsorbent stationary phases separate permanent gases and low-molecular-weight hydrocarbons for refinery process analytics.
- Supercritical Fluid:Carbon dioxide mobile phases enable chiral separations for complex pharmaceutical enantiomer analysis.
Gas-liquid anchors the revenue base; high-performance is expanding most quickly.
End User:
Application maturity varies sharply across customer types, with pharmaceuticals driving premium pricing and environmental labs compressing procurement cycles.
- Pharmaceuticals:Genotoxic impurity profiling and real-time release testing for monoclonal antibody production demand multi-dimensional GC configurations. FDA method validation guidelines force contract manufacturing organizations into multi-year column supply agreements bundled with performance monitoring software.
- Environmental:EPA Method 8260D mandates for volatile organic compound detection are compressing replacement cycles below historical five-to-seven-year schedules. Netherlands and Belgium contract laboratories absorb compliance costs through certified reference-grade column premiums.
- Food & Beverage:Pesticide residue screening and flavor compound authentication drive routine quality control consumption.
- Chemical Manufacturing:Process analytical technology adoption in continuous production environments requires specialized stationary phase chemistries for real-time monitoring.
Pharmaceuticals command the highest margins; environmental is climbing the fastest.
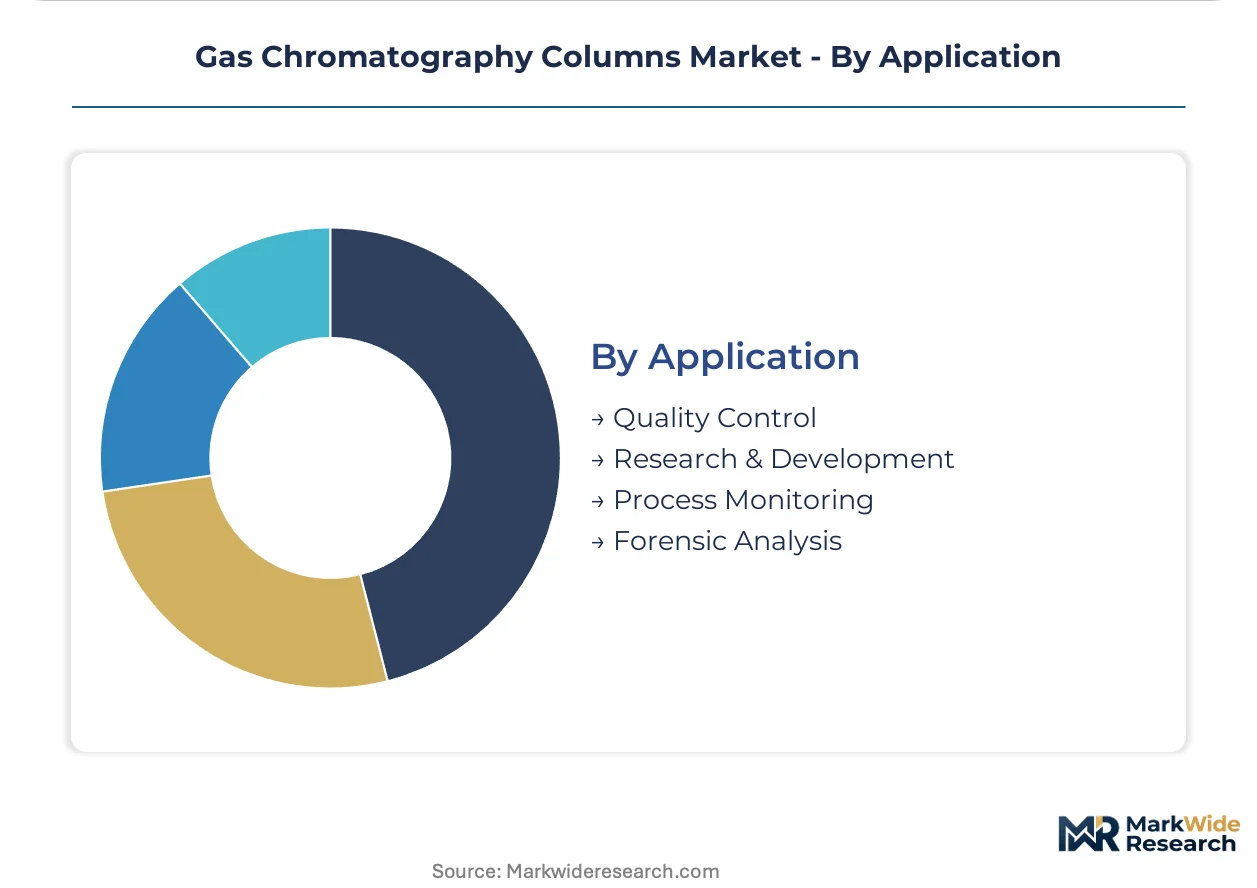
Application:
Volume concentration sits with quality control workflows, while process monitoring embeds columns into capital-intensive manufacturing infrastructure.
- Quality Control:Routine batch release testing across pharmaceutical and food safety laboratories generates predictable replacement demand. REACH chemical registration standards in Europe mandating 0.1 percent weight impurity thresholds are expanding certificate of analysis documentation requirements.
- Process Monitoring:Continuous analytical technology integration in Germany's chemical manufacturing corridor requires columns engineered for unattended operation. Ruhr-based producers specify enhanced thermal stability for 24/7 hydrocarbon stream analysis.
- Research & Development:Method development for emerging compound classes drives experimental column consumption in academic and government laboratories.
- Forensic Analysis:Toxicology screening panels for law enforcement agencies prioritize comprehensive detection over throughput speed.
Quality control dominates unit volumes; process monitoring shows the steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Environmental monitoring intensity in the United States outpaces European replacement cycles, while pharmaceutical quality control investments in Germany and Switzerland sustain premium column consumption. Laboratory infrastructure modernization across Asia-Pacific markets is compressing procurement timelines for high-performance configurations.
United States
EPA Method 8260D mandates for volatile organic compound detection are forcing environmental laboratories to retire legacy phases ahead of historical depreciation schedules. FDA bioanalytical method validation guidelines tighten reproducibility thresholds for contract manufacturing organizations in Massachusetts and California biotech clusters. The US Gulf Coast petrochemical corridor favors packed column configurations for continuous hydrocarbon monitoring where sample loading capacity outweighs separation efficiency.
Germany
Process analytical technology adoption in the Ruhr industrial corridor demands specialized stationary phase chemistries for 24/7 unattended operation. REACH chemical registration standards mandate full analytical characterization down to 0.1 percent weight impurity thresholds, expanding certificate of analysis documentation requirements. Environmental contract laboratories in the Netherlands and Belgium absorb these compliance costs through certified reference-grade column premiums.
China
National pharmaceutical regulator guidelines for genotoxic impurity profiling are expanding column consumption in quality control workflows across contract manufacturing organizations. Dual carbon goals and tightening industrial emissions standards are accelerating environmental monitoring infrastructure deployment. The Yangtze River Delta concentration of pharmaceutical and chemical manufacturing drives demand for low-bleed siloxane phases in persistent organic pollutant analysis.
Japan
PMDA bioanalytical method validation requirements sustain premium pricing for high-performance capillary columns in pharmaceutical impurity testing. METI industrial emissions monitoring programs are compressing replacement cycles for process analytical technology installations. The Kansai region's specialty chemical manufacturers specify enhanced thermal stability for continuous production stream analysis.
India
CDSCO bioanalytical guidelines for generic drug manufacturing are expanding column consumption in quality control departments across contract research organizations. Central pollution control board mandates for industrial emissions monitoring are driving environmental laboratory upgrades. Maharashtra and Gujarat pharmaceutical clusters absorb compliance costs through multi-year consumable supply agreements bundled with performance monitoring software.
Gas Chromatography Columns Market Vendor Landscape
Top-tier vendors anchor the premium instrumentation tier, while mid-scale specialists occupy application-specific niches. The vendor base stratifies across three performance tiers based on cross-platform service infrastructure depth and informatics integration capabilities. Instrumentation conglomerates represent the full-stack archetype, consumables specialists exemplify the technical support archetype, and regional fabricators occupy the cost-optimized archetype. M&A activity concentrates on informatics capabilities and predictive maintenance platforms, while strategic partnerships target multi-year consumable lock-in agreements.
Among the named players, Agilent Technologies and Thermo Fisher Scientific represent the full-stack instrumentation archetype with cross-platform service infrastructure. Restek Corporation exemplifies the consumables specialist model with application-specific technical support capabilities. These three anchors demonstrate how vendor positioning fragments across bundled service commitments versus standalone technical expertise.
| Leading Market Players |
|---|
| Shimadzu Corporation |
| Merck KGaA |
| Agilent Technologies |
| Phenomenex |
| Restek Corporation |
| Thermo Fisher Scientific |
| PerkinElmer |
| Bio-Rad Laboratories |
| Waters Corporation |
| Others |
Supply Flow & Price Mechanics
Family-owned German column fabricators anchor the specialty stationary phase tier, their multi-generational ownership structures enabling patient capital allocation toward batch certification investments that command premium pricing from pharmaceutical quality control departments. This ownership pattern concentrates supply discipline in the Ruhr industrial corridor while cross-licensing royalty burdens from polyimide coating patents inflate cost structures for mid-scale entrants.
Pricing Analysis
Capacity additions in China's Yangtze River Delta are reshaping price floors for standard-grade capillary columns. Three-tier pricing structure across certified reference, performance-grade, and economy levels separates EPA-compliant environmental laboratories from routine quality control departments. Price differentiation rests on batch reproducibility documentation and REACH certification depth. Cost compression in economy tiers intensifies because e-procurement platforms compress distributor margins. Contract manufacturing organizations in Massachusetts and California biotech clusters show least price sensitivity, prioritizing instrument uptime guarantees over unit cost minimization.
Supply Chain Analysis
Regional distribution centers in Germany, the United States, and Japan operate hub-and-spoke patterns to serve pharmaceutical and environmental laboratory clusters. Manufacturing concentrates in Germany, the United States, and China, with high-purity fused silica precursor supply controlled by a concentrated supplier base. Raw material dependencies include high-purity silica precursors, polyimide coating resins, and proprietary siloxane formulations. Single-source vulnerability in helium carrier gas supply from US Bureau of Land Management reserves forces hydrogen compatibility retrofits. Distribution runs through authorized distributor networks and direct-to-laboratory digital platforms.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a regulatory compounder, with EPA Method 8260D detection threshold mandates forcing replacement cycle compression that compounds consumable demand across environmental laboratories.
For Market Incumbents: To counter helium carrier gas scarcity disrupting customer method validation timelines, deepen backward integration into hydrogen-compatible stationary phase chemistries and expand predictive maintenance software bundles that lock in multi-year consumable commitments from pharmaceutical quality control departments. For New Entrants and Emerging Players: Enter via fluorinated stationary phase development for emerging PFAS regulatory scopes, targeting state-level drinking water standards in the United States where incumbent patent thickets are less dense. Application-specific technical support capabilities reduce method development time for environmental contract laboratories. For Investors and Strategic Acquirers: Valuations sit cheapest among consumables specialists with informatics integration gaps, particularly those serving forensic toxicology laboratories adopting ionic liquid phases. Long-term viability hinges on subscription-based procurement displacement of spot purchasing. Watch for PFAS regulatory scope expansion as inflection indicator for specialized stationary phase demand acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Silica Precursor Supply | Captive supply of high-purity fused silica reduces vulnerability to allocation constraints from the concentrated German-Chinese supplier base. |
| Predictive Maintenance Platform Launch | Performance monitoring software bundled with column supply agreements locks in multi-year commitments from Massachusetts biotech clusters. |
| PFAS-Specific Stationary Phase Development | Fluorinated phase chemistries address emerging state-level drinking water standards expanding the addressable environmental laboratory set. |
| Hydrogen Compatibility Certification Program | Enhanced thermal stability validation enables method retrofitting as EPA laboratories face helium reserve depletion from US Bureau of Land Management. |
| Direct-to-Laboratory Digital Distribution | E-procurement platforms capture usage data for predictive replenishment algorithms while compressing traditional distributor margins. |
Methodological Framework
Coverage spans North America, Europe, and Asia-Pacific, with primary inputs from each region combined with secondary validation. Primary interviews engaged chromatography instrument engineers, pharmaceutical quality control managers, environmental laboratory directors, and consumables procurement leads. Secondary sources included EPA method documentation, ECHA REACH substance databases, FDA bioanalytical method validation guidelines, and customs trade data for chromatography consumables. Bottom-up triangulation across end-user consumption patterns and top-down validation against vendor shipment data anchored volume estimates.
Rate-of-change decomposition across the analysis window modeled segment-level expansion trajectories. Segmentation dimensions included column architecture, stationary phase technology, end-user industry, and application workflow. CAGRs were derived from replacement cycle compression rates, regulatory mandate expansion timelines, and process analytical technology adoption curves. Forecast inputs incorporated helium carrier gas scarcity impacts on validation timelines and PFAS regulatory scope expansion scenarios.
The model holds under stable regulatory enforcement intensity; deviation in EPA detection threshold timelines or REACH chemical registration scope would shift replacement demand patterns. Forecasts reflect documented assumptions regarding method validation guideline evolution and carrier gas supply continuity. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Testing Equipment
Materials Testing Equipment Market
Testing Equipment
Global Silica Analyzer Market
Testing Equipment
Rheometer Market
Testing Equipment
Water Testing Equipment Market
Testing Equipment
Global Ion Chromatography Market
Testing Equipment
Dynamic Light Scattering (DLS) Measure Instrument Market
Testing Equipment
Global Circular Dichroism (CD) Spectrometers Market
Testing Equipment
Chromatography Systems Market
Testing Equipment
China Material Testing Market
Testing Equipment
Chemical Detector Market
Testing Equipment
Hydrocarbon Tester Market
Testing Equipment
Next-Generation Titrators Market
Testing Equipment
Odor Emission Measurement and Dynamic Olfactometry Test Equipment Market
Testing Equipment
Global Distillate Oil Testing Service Market
Testing Equipment
Solar Testing Equipment Market
Testing Equipment
CHS (Carbon Hydrogen Sulfur) Analyzers Market