
 Canned Pet Food Market | 2026-2036
Canned Pet Food Market Size, Share, and Industry Trends Forecast 2026-2036
Canned Pet Food Market Analysis
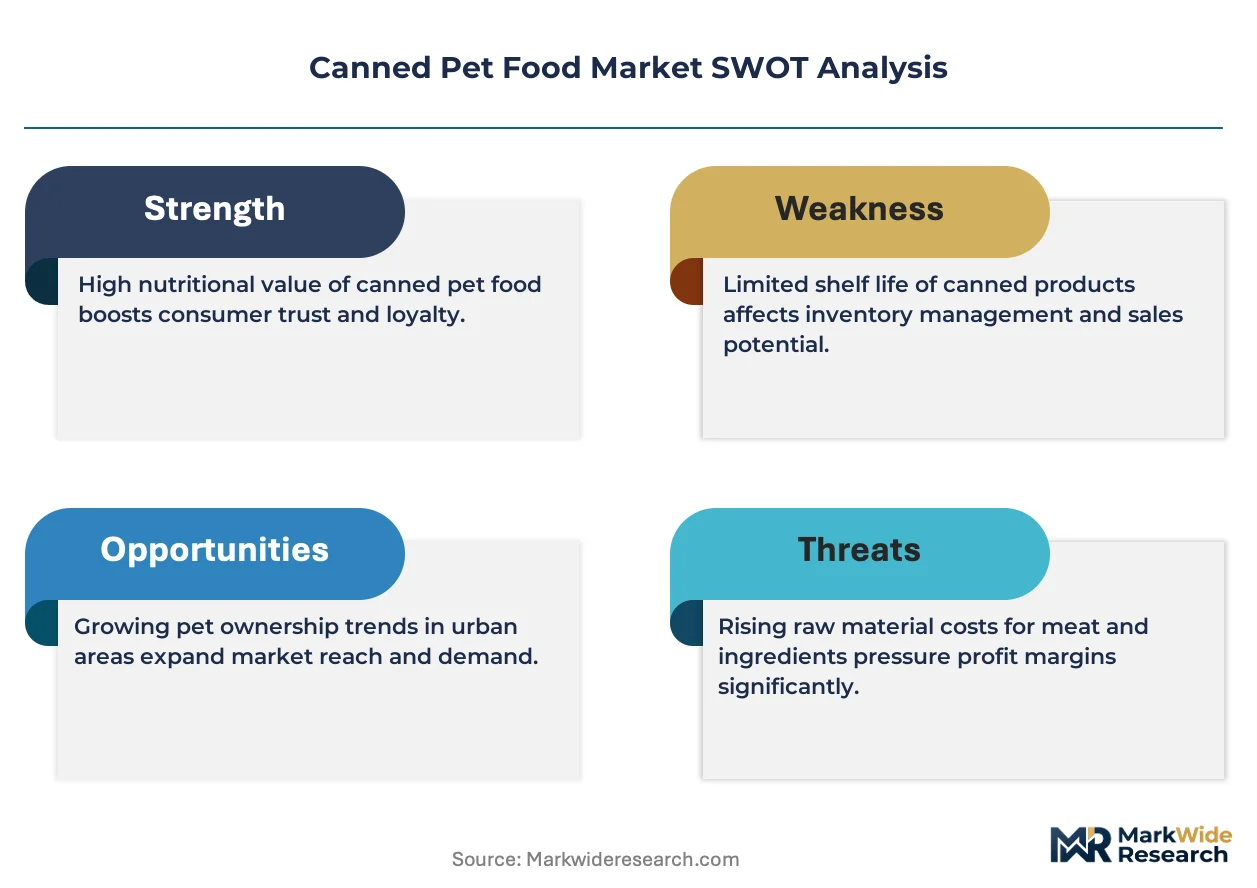
Single-serve pouch formats is decoupling from traditional multi-can bundles, giving buyers flexibility to trial flavors without inventory risk. Mars Petcare leverages its global manufacturing scale to dominate shelf-stable wet food production across multiple continents. Nestlé Purina PetCare anchors its position through R&D intensity in therapeutic and prescription diet formulations. Blue Buffalo differentiates by specializing in grain-free and limited-ingredient canned recipes targeting allergy-sensitive pets.
Canned pet food comprises moisture-rich animal protein products sealed in hermetically sealed metal or composite containers, typically containing 75-85% water content and undergoing commercial sterilization at 121°C to achieve shelf stability without refrigeration. The primary purpose is to deliver complete nutrition in palatable form for domestic carnivores requiring high protein and hydration support. Meat-based formulations occupy the largest margin pool due to premium positioning, while fish-based recipes represent the fastest-growing category as omega-3 functional claims attract health-conscious owners. Online retail channels are capturing disproportionate growth as subscription models and direct-to-consumer platforms reshape replenishment behavior.
The FDA Center for Veterinary Medicine enforces ingredient safety and facility registration requirements, while AAFCO establishes model nutritional adequacy standards that most US states adopt into feed control laws. The USDA Agricultural Marketing Service oversees certain meat and poultry inputs entering pet food supply chains, creating multi-layer compliance obligations for manufacturers. Stakeholders must monitor evolving state-level packaging waste legislation and extended producer responsibility frameworks that could reshape container economics.
Market Dynamics
Urban millennial pet ownership patterns are fragmenting demand into micro-batch, flavor-trial formats that strain legacy canning line economics optimized for 24-can case production. This decoupling of consumption from traditional inventory models is forcing capital reallocation across manufacturing footprints.
Growth Catalysts
- AAFCO Model Bill Adoption:State-level feed control laws incorporating AAFCO nutritional adequacy standards create uniform compliance baselines that reduce interstate distribution friction for multi-regional manufacturers.
- Omega-3 Functional Positioning:Fish-based formulations leveraging EPA/DHA claims capture veterinary endorsement channels that drive prescription-tier pricing power in clinical settings.
- Brazil Urbanization:São Paulo and Rio de Janeiro apartment-dwelling pet populations concentrate demand for moisture-rich diets addressing hydration constraints in confined indoor environments.
Market Restraints
- Aluminum Input Volatility:Two-piece can body stock and easy-open end specifications tie margin stability to London Metal Exchange pricing and rolling mill capacity allocation decisions.
- Retort Sterilization Energy Intensity:Commercial sterilization at 121°C demands saturated steam infrastructure that concentrates viable production in regions with reliable natural gas or biomass thermal supply.
- Refrigerated Fresh Substitutes:Chilled raw and lightly cooked formats in specialty pet retail erode wet food's hydration-value proposition among premium-tier buyers.
Strategic Opportunities
- Germany Extended Producer Responsibility:Packaging waste legislation mandating producer-funded recycling infrastructure creates first-mover advantage for aluminum-to-aluminum closed-loop can designs.
- Subscription Replenishment Platforms:Direct-to-consumer auto-ship models bypass slotting fee structures and capture lifetime value data that informs flavor portfolio optimization.
- Therapeutic Diet Convergence:Renal support, urinary care, and weight management formulations bridge veterinary prescription channels and over-the-counter premium positioning.
Industry Challenges
- Retort Technician Scarcity:Thermal process authority certification and scheduled process validation expertise concentrate among aging workforce cohorts with limited apprenticeship pipeline replenishment.
- Legacy ERP Integration:Batch record systems designed for dry extrusion operations require substantial reconfiguration to accommodate wet food's time-temperature critical control point documentation.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Canned Pet Food Market |
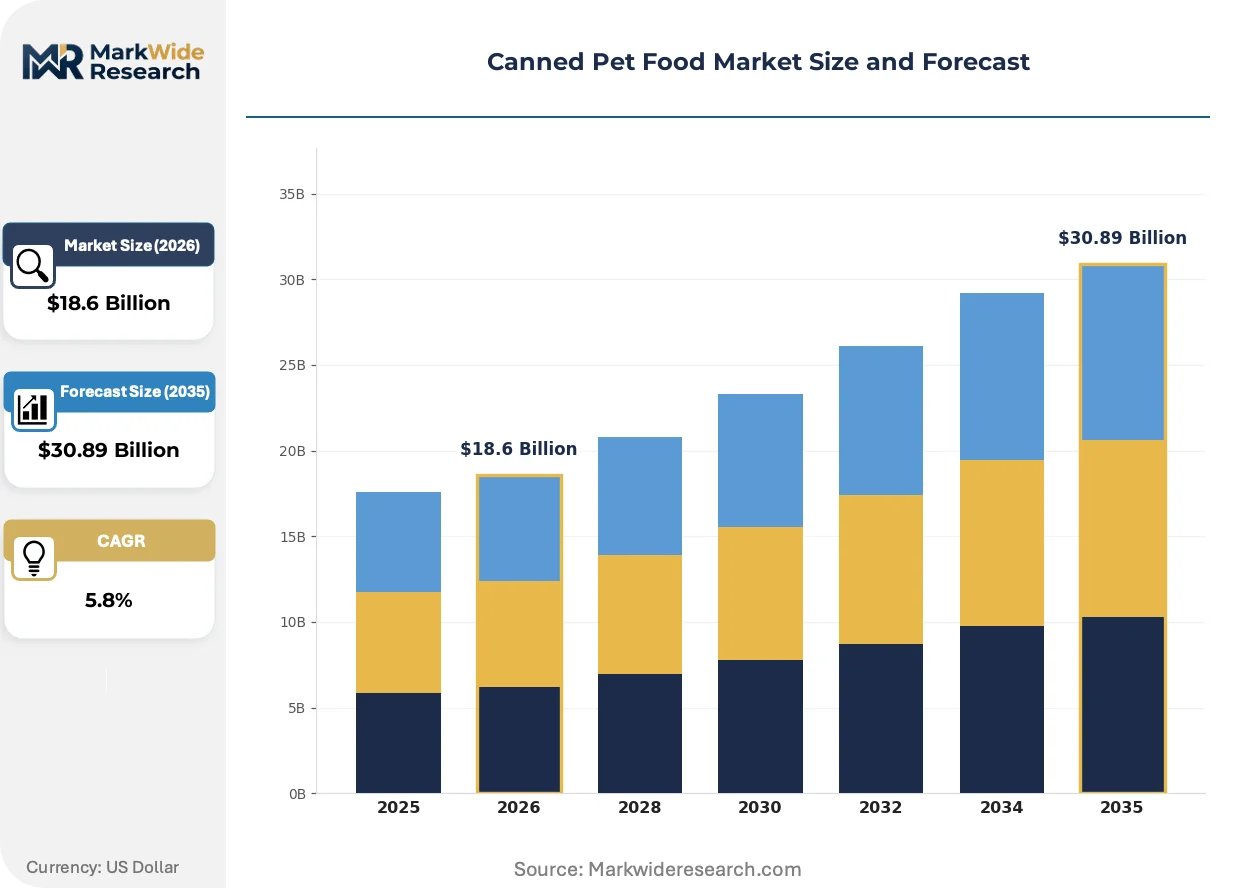
| Market Size in 2026 | $18.6 Billion |
| Market Size in 2035 | $30.89 Billion |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Meat-based, Fish-based, Poultry-based, Mixed End User: Pet Owners, Veterinary Clinics, Pet Retailers, Animal Shelters Packaging Type: Tins, Pouches, Tetra Packs, Cans Distribution Channel: Online Retail, Supermarkets, Pet Specialty Stores, Wholesale |
| Companies Covered | Nestlé Purina PetCare, Mars Petcare, Hill's Pet Nutrition, General Mills, The J.M. Smucker Company, Colgate-Palmolive, Blue Buffalo, WellPet, Thai Union Group, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Canned Pet Food Market Emerging Trajectories
Moisture retention technologies and packaging format diversification are compressing the traditional trade-off between shelf stability and palatability that has defined canned pet food since mid-century commercialization.
High-pressure processing (HPP) is rewriting the thermal sterilization paradigm by inactivating pathogens at ambient temperatures, preserving heat-sensitive vitamin bioavailability and protein texture that retort methods degrade. Boutique manufacturers in California and Pacific Northwest metro corridors are adopting HPP for refrigerated distribution formats that command per-ounce premiums. The technology is compressing the viable market for traditional retort infrastructure by enabling cold-chain players to claim "minimally processed" positioning without compromising safety margins.
EU Single-Use Plastics Directive implementation is forcing composite can body innovation as member states interpret scope coverage for multi-material pet food containers. Manufacturers serving German, French, and Benelux markets are accelerating paperboard-based barrier development to preempt regulatory reclassification. The directive is most acutely affecting fish-based premium lines where transparent lid windows currently rely on polyethylene terephthalate laminates.
Flavor rotation fatigue among urban cat owners is fragmenting household inventory into 2-3 concurrent protein varieties rather than single-formula loyalty. Specialty pet retailers in Manhattan, Brooklyn, and Chicago lakefront neighborhoods report basket composition shifting toward 3-ounce trial sizes across 4+ SKUs per transaction. This pattern is most visible in single-cat households where anthropomorphized feeding rituals displace nutritional consistency as the primary purchase driver.
Canned Pet Food Market Segmentation
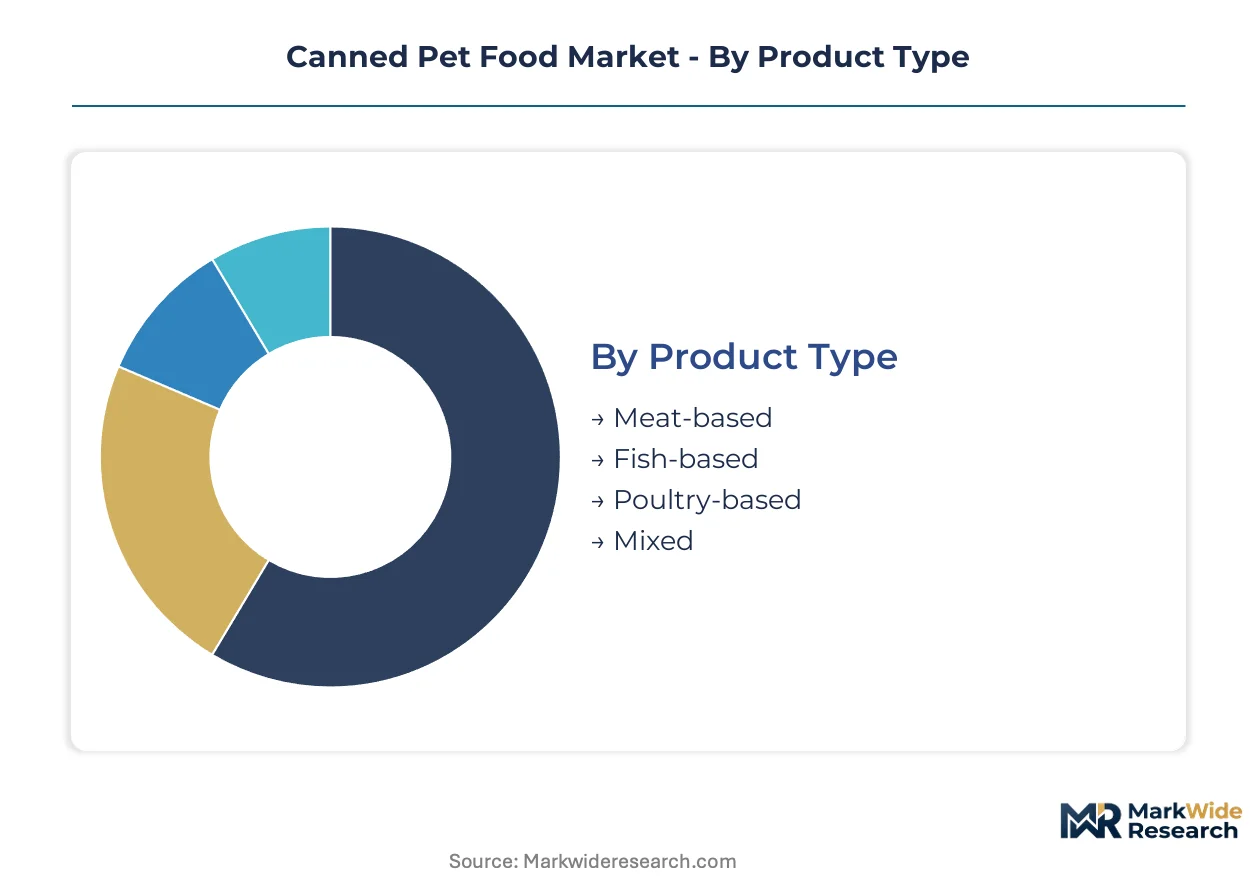
Canned pet food segmentation reveals how formulation chemistry, packaging engineering, and channel economics fragment demand across distinct buyer workflows. Each axis carries unique margin profiles and regulatory exposure that reshape capital allocation for manufacturers.
Product Type:
Protein source specifications determine thermal processing parameters, palatability engineering, and veterinary endorsement pathways.
- Meat-based:Beef, pork, and lamb formulations dominate premium positioning through high biological value protein claims. Demand concentrates among urban millennial pet owners in São Paulo and Manhattan who prioritize ancestral diet narratives for carnivore nutrition.
- Fish-based:Salmon, tuna, and whitefish recipes leverage EPA/DHA omega-3 functional claims. Veterinary clinics in Germany and the United States drive prescription-tier pricing for renal support and coat health applications.
- Poultry-based:Chicken and turkey offer cost-efficient protein density with lower allergenicity profiles than red meat alternatives.
- Mixed:Multi-protein blends target flavor rotation preferences among single-cat households seeking variety without inventory proliferation.
Mature deployment sits with meat-based formulations. Newer deployment is concentrated in fish-based recipes.
End User:
Buyer type dictates order frequency, batch size, and compliance documentation intensity.
- Pet Owners:Direct consumers purchase through subscription platforms and retail channels, prioritizing convenience and palatability over clinical validation.
- Veterinary Clinics:Prescription diet dispensing requires AAFCO nutritional adequacy verification and therapeutic claim substantiation.
- Pet Retailers:Specialty stores in Brooklyn and Chicago lakefront neighborhoods curate 2-3 ounce trial formats across 4+ SKUs per transaction.
- Animal Shelters:High-volume procurement emphasizes cost-per-calorie efficiency and donation-funded supply chain reliability.
Established volume flows through pet retailers. Expanding most quickly are veterinary clinic channels bridging prescription and over-the-counter positioning.
Packaging Type:
Container engineering determines shelf stability, portion control flexibility, and extended producer responsibility compliance exposure.
- Tins:Traditional three-piece steel construction with soldered side seams offers lowest unit cost for 24-can case production.
- Pouches:Single-serve flexible formats enable flavor trial without inventory risk, decoupling consumption from legacy canning line economics optimized for bulk packaging.
- Tetra Packs:Aseptic carton technology reduces aluminum input dependency but requires chilled distribution infrastructure.
- Cans:Two-piece aluminum bodies with easy-open ends dominate shelf-stable wet food production across Mars Petcare global manufacturing footprint.
Legacy infrastructure serves can formats. Steepest expansion trajectory belongs to pouches capturing subscription replenishment platform demand.
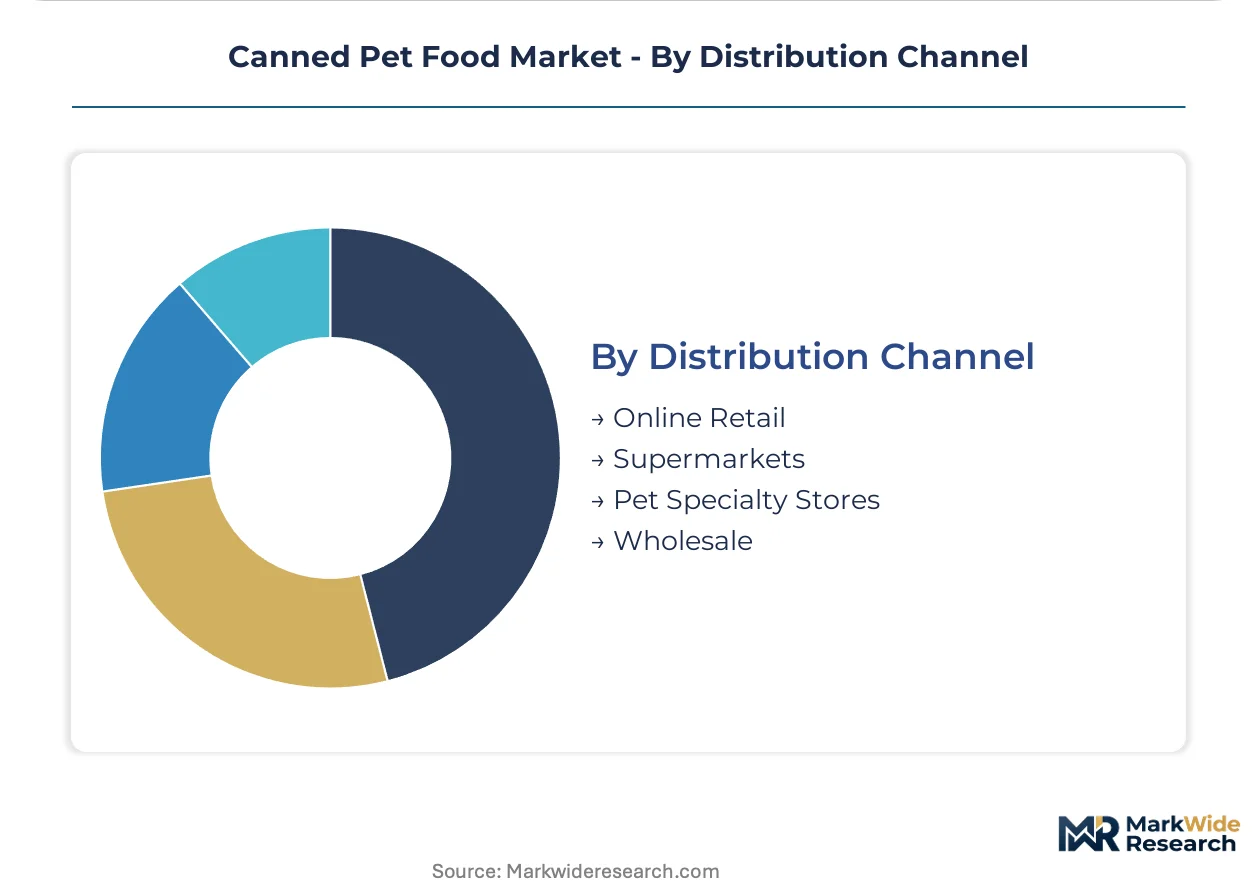
Distribution Channel:
Channel selection shapes slotting fee structures, data capture capabilities, and replenishment automation potential.
- Online Retail:Direct-to-consumer auto-ship models bypass traditional retail margin stacking and capture lifetime value data informing flavor portfolio optimization.
- Supermarkets:Mass merchandisers concentrate volume for standard-tier formulations with limited SKU breadth compared to specialty channels.
- Pet Specialty Stores:Manhattan and Pacific Northwest boutiques drive premium-tier adoption through staff-curated recommendations and anthropomorphized feeding ritual merchandising.
- Wholesale:Distributor networks serve veterinary clinics and animal shelters requiring pallet-scale procurement with extended payment terms.
Conventional volume remains anchored in supermarkets. Gaining share fastest are online retail channels as millennial pet owners abandon brick-and-mortar replenishment workflows.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Production capacity clusters in Germany and the United States while consumption concentrates in Brazil's expanding urban centers. This geographic split creates freight-intensive supply chains and regulatory complexity for multinational manufacturers.
United States
Urban millennial pet ownership in Manhattan and Brooklyn drives single-serve pouch adoption through subscription platforms. FDA Center for Veterinary Medicine enforces ingredient safety and facility registration requirements that shape interstate distribution compliance. Pacific Northwest metro corridors host boutique manufacturers adopting high-pressure processing for refrigerated premium formats.
Germany
Veterinary clinic channels in Berlin and Munich drive prescription-tier fish-based formulations with omega-3 functional claims. Extended Producer Responsibility legislation mandates producer-funded recycling infrastructure for aluminum can designs. The Rhine-Ruhr industrial region concentrates Mars Petcare manufacturing scale for European shelf-stable wet food supply.
Brazil
São Paulo and Rio de Janeiro apartment-dwelling cat populations generate concentrated demand for moisture-rich diets addressing indoor hydration constraints. ANVISA oversees pet food safety standards that align with Mercosur trade bloc harmonization efforts. The São Paulo metropolitan area anchors retail distribution networks serving Latin America's largest pet owner base.
Japan
Tokyo and Osaka single-cat households fragment purchase patterns into flavor-rotation behaviors across micro-batch SKUs. METI standards and JIS specifications govern manufacturing quality benchmarks for imported and domestic products. The Kanto region's specialty pet retailers curate premium-tier wet food assortments targeting anthropomorphized feeding rituals.
United Kingdom
London and Southeast England premium pet retail channels emphasize grain-free and limited-ingredient positioning for allergy-sensitive animals. FSA and DEFRA regulations coordinate with EU-derived feed safety frameworks post-Brexit transition. The Midlands manufacturing corridor supplies private-label canned formulations for major supermarket chains.
Canned Pet Food Market Vendor Landscape
Diversified conglomerates compete with focused pure-play specialists across tiered price positioning. Mars Petcare and Nestlé leverage global manufacturing scale and R&D intensity to dominate shelf-stable and therapeutic segments respectively. Three strategic archetypes define competitive positioning: multinational CPG conglomerates with pet care divisions, mid-cap specialists in grain-free or limited-ingredient formulations, and regional private-label manufacturers serving price-sensitive channels. Capacity expansion and portfolio diversification represent the dominant competitive moves as legacy canning infrastructure faces format disruption.
Within the multinational conglomerate tier, Mars Petcare and Nestlé Purina PetCare exemplify scale-driven positioning through global manufacturing footprints and therapeutic diet R&D pipelines. Blue Buffalo occupies the specialist archetype, representing focused differentiation in grain-free and limited-ingredient recipes. Thai Union Group anchors the protein-integrated segment, exemplifying backward integration from seafood supply chains into fish-based pet food formulations.
| Leading Market Players |
|---|
| Nestlé Purina PetCare |
| Mars Petcare |
| Hill's Pet Nutrition |
| General Mills |
| The J.M. Smucker Company |
| Colgate-Palmolive |
| Blue Buffalo |
| WellPet |
| Thai Union Group |
| Others |
Supply Flow & Price Mechanics
Retort technician certification scarcity in the Rhine-Ruhr industrial region and São Paulo metropolitan corridor widens labor-cost differentials between premium therapeutic formulations and mass-market standard tiers. This workforce concentration pattern feeds directly into pricing spreads that separate prescription-grade fish-based diets from economy poultry lines.
Pricing Analysis
Margin tightening in standard-tier poultry formulations reflects aluminum input volatility tied to London Metal Exchange pricing swings. Three-tier pricing structure across premium, standard, and economy levels separates therapeutic diets with AAFCO nutritional adequacy verification from unverified private-label alternatives. Price differentiation hinges on certification grade and veterinary endorsement intensity. Cost-down pressure on economy segments accelerates because Brazilian and German supermarket buyers prioritize cost-per-calorie efficiency over palatability claims. Pet specialty retailers in Manhattan and Brooklyn show lowest price sensitivity, while animal shelters and donation-funded procurement channels exhibit highest elasticity.
Supply Chain Analysis
Regional distribution centers in Germany, the United States, and Brazil operate hub-and-spoke patterns to serve fragmented urban demand. Manufacturing gravity draws from aluminum rolling mill capacity in Germany, steam retort infrastructure in the United States, and Mercosur-aligned protein sourcing in Brazil. Raw material dependencies center on two-piece can body stock, easy-open end specifications, and omega-3 fish oil concentrates. Single-source vulnerability concentrates in London Metal Exchange-linked aluminum supply. Distribution runs through veterinary clinic wholesale networks and direct-to-consumer subscription platforms.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The canned pet food sector sits in a technology-transition phase as high-pressure processing displaces legacy retort sterilization for refrigerated premium formats.
For Market Incumbents: Cement manufacturing scale advantages by retrofitting Rhine-Ruhr and São Paulo facilities for flexible pouch production that accommodates micro-batch flavor trials. Prioritize backward integration into omega-3 fish oil supply chains to defend margin position against Thai Union Group's captive sourcing. Retort technician apprenticeship pipelines represent the critical capability investment to offset workforce aging. For New Entrants and Emerging Players: Launch via direct-to-consumer subscription platforms targeting single-cat households in Pacific Northwest metro corridors and Tokyo apartment markets. White-space concentration sits with HPP-enabled refrigerated formats claiming minimally processed positioning. Veterinary endorsement channels for renal support formulations offer the most penetrable prescription-tier entry point. For Investors and Strategic Acquirers: Re-rating potential sits with mid-cap specialists possessing grain-free certification and limited-ingredient R&D depth given AAFCO disclosure tightening. Long-term viability favors assets with therapeutic diet convergence capabilities bridging over-the-counter and prescription positioning. Watch for inflection signals in state-level extended producer responsibility legislation adoption rates.| Strategic Initiative | Industry Significance |
|---|---|
| Pouch Format Manufacturing Conversion | Flexible packaging lines capture subscription platform demand from urban millennial pet owners. |
| High-Pressure Processing Adoption | Cold-chain premium positioning preserves vitamin bioavailability that retort methods degrade. |
| Therapeutic Diet R&D Expansion | Renal and urinary formulations unlock veterinary clinic dispensing margins. |
| Extended Producer Responsibility Compliance | German aluminum-to-aluminum closed-loop designs preempt packaging waste legislation. |
| Direct-to-Consumer Platform Launch | Auto-ship models bypass slotting fees and capture lifetime value data for flavor optimization. |
Methodological Framework
Multi-period observation of pouch format adoption rates, HPP infrastructure deployment, and veterinary clinic channel expansion anchored the trend analysis, supplemented by interviews with retort operations managers, pet specialty retail buyers, AAFCO regulatory affairs specialists, and subscription platform supply chain directors. Secondary validation drew from FDA Center for Veterinary Medicine facility registration databases, ANVISA pet food safety filings, USDA Agricultural Marketing Service meat input tracking, and London Metal Exchange aluminum pricing series. Bottom-up SKU-level volume aggregation and top-down macroeconomic factor weighting provided cross-verification.
Segment-weighting across protein source, packaging format, distribution channel, and end-user type dimensions structured the analytical framework over the projection horizon. CAGRs were derived from fitted growth curves applied to normalized baseline data. Industry-specific forecast inputs included urban millennial pet ownership density indices and state-level extended producer responsibility legislative tracking.
Aluminum price volatility, retort technician workforce replenishment rates, and refrigerated fresh substitute penetration velocity are the dominant revision risks that could alter trajectory assumptions. Forecasts reflect documented assumptions about regulatory harmonization and technology adoption curves. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Baby Food and Infant Formula
A2 Infant Formula Market
Baby Food and Infant Formula
Wet Cat Food Market
Baby Food and Infant Formula
United States Baby Food and Infant Formula Market
Baby Food and Infant Formula
India Baby Food Market
Baby Food and Infant Formula
Europe Baby Food and Infant Formula Market
Baby Food and Infant Formula
Baby Food Testing Market
Baby Food and Infant Formula
Middle-Aged and Elderly Milk Powder Market
Baby Food and Infant Formula
Middle East and Africa Baby Food Market
Baby Food and Infant Formula
Europe Baby Food Market
Baby Food and Infant Formula
Kids Food and Beverages Market
Baby Food and Infant Formula
Japan Baby Food and Infant Formula Market
Baby Food and Infant Formula
South America Baby Food Market
Baby Food and Infant Formula
Anti-Spit Up Formula Market
Baby Food and Infant Formula
Second Stage Organic Infant Formula Market
Baby Food and Infant Formula
Follow on Formula Milk Market
Baby Food and Infant Formula
Asia-Pacific Prebiotics for Infant Formula Market