
 Baby Infant Formula Market | 2026-2036
Baby Infant Formula Market Size, Share, and Industry Trends Forecast 2026-2036
Baby Infant Formula Market Analysis
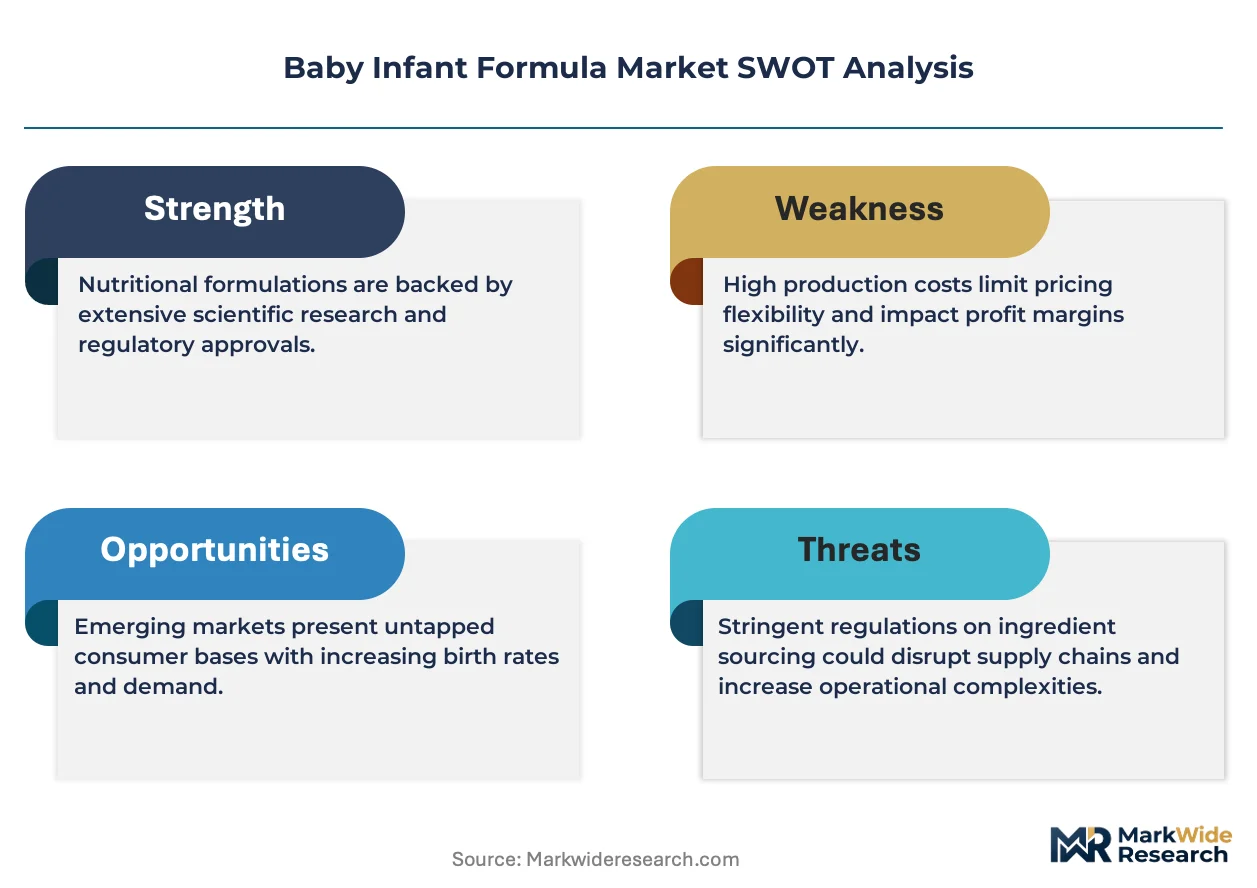
EU MDR is consolidating the cost-of-entry calculus for new entrants seeking European market access, forcing substantial investment in clinical substantiation and traceability infrastructure. Nestle leverages its vertically integrated nutrition science platform to sustain formulation leadership across premium tiers. Danone anchors its competitive position through specialized hypoallergenic and organic lines that command shelf space in pharmacy channels. Abbott competes on medical credibility, extending its hospital-origin brand equity into retail environments.
Baby infant formula constitutes a nutritionally complete breast milk substitute manufactured through wet-mixing or dry-blending processes, typically containing demineralized whey, vegetable oils, lactose, and micronutrient premixes standardized to Codex Alimentarius protein and fat profiles. Its primary commercial purpose is delivering regulated infant nutrition during the first twelve months when breastfeeding is insufficient or unavailable. Powder formats dominate volume due to lower logistics costs and extended shelf stability, while ready-to-feed liquid commands disproportionate margin pools in convenience-oriented urban markets. Hydrolyzed protein segments attract premium positioning as pediatric allergy diagnoses expand, and organic ingredient classifications increasingly differentiate shelf offerings in North American and European retail.
FDA infant formula regulations, EFSA novel food assessments, and China's SAMR registration requirements collectively shape formulation standards, labeling mandates, and import clearance timelines across major supply corridors. These frameworks elevate compliance spending but simultaneously protect incumbent positions by raising barriers for unverified suppliers. Stakeholders must monitor evolving WHO Code enforcement intensity and emerging microbiome-related health claims as the next frontier of competitive differentiation and regulatory scrutiny.
Market Dynamics
Dual-income household proliferation is compressing preparation time windows and elevating ready-to-feed liquid formats from convenience niche to primary purchase criterion in urban retail.
Growth Catalysts
- GB Standard 10765:China's SAMR registration mandates for imported formula tighten purity thresholds, filtering marginal suppliers and elevating compliant incumbents.
- Hypoallergenic hydrolyzation:Pediatric allergy diagnosis expansion pulls protein-modified formulations into pharmacy-channel premium positioning.
- Metropolitan birth concentration:Megacities in India and China concentrate demand density, reducing last-mile distribution cost per serving.
Market Restraints
- Whey protein concentrate volatility:Dairy commodity price swings compress margin predictability for powder-format producers dependent on demineralized whey inputs.
- EU REACH chemical registration:Novel ingredient authorization timelines extend 18-24 months, freezing formulation innovation cycles for European market entrants.
- Breastfeeding promotion mandates:WHO Code enforcement intensity in hospital channels restricts sampling and advertising, capping trial-to-purchase conversion rates.
Strategic Opportunities
- Tier-two Chinese cities:SAMR registration holders can extend distribution into underpenetrated provincial capitals before local brand consolidation completes.
- Microbiome health claims:Emerging HMO and probiotic positioning opens differentiation white space pending EFSA novel food assessment clarity.
- Subscription direct-to-home:Urban parent convenience demand enables bypass of traditional pharmacy and grocery slotting fee structures.
Industry Challenges
- Clinical substantiation capacity:Pediatric nutrition trials require specialized investigator networks and extended enrollment timelines that strain R&D throughput.
- Legacy ERP integration:Batch-level traceability mandates for FDA infant formula regulations force costly MES overlay deployment onto decades-old manufacturing execution infrastructure.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Baby Infant Formula Market |
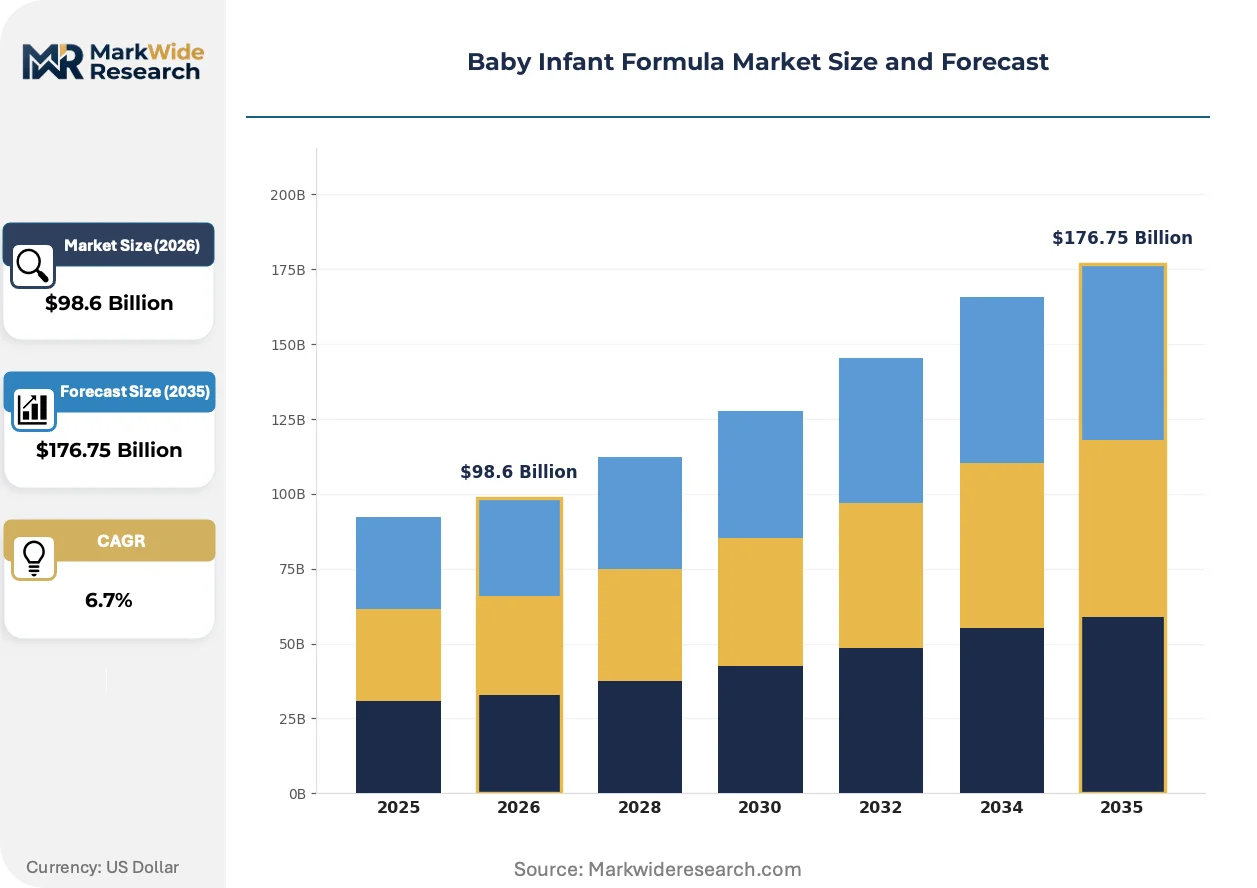
| Market Size in 2026 | $98.6 Billion |
| Market Size in 2035 | $176.75 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Powder, Liquid, Concentrate, Ready-to-Feed Age Group: Newborn, Infant, Toddler, Preschooler Ingredient Type: Soy, Cow's Milk, Hydrolyzed, Organic Distribution Channel: Retail Stores, Online, Pharmacies, Supermarkets |
| Companies Covered | Reckitt Benckiser, FrieslandCampina, Nestle, Yili Group, Arla Foods, Danone, Perrigo Company, Meiji Holdings, Abbott, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Baby Infant Formula Market Emerging Trajectories
Precision fermentation and biosynthetic ingredient platforms are destabilizing traditional dairy-derived supply assumptions while regulatory frameworks race to validate novel protein safety profiles.
Precision fermentation for lactoferrin and HMO production is automating upstream ingredient manufacturing, reducing batch-to-batch variation that plagued agricultural extraction. European and North American ingredient suppliers are scaling demonstration facilities to 10,000-liter bioreactor volumes. This platform is automating quality control throughput and compressing supplier qualification timelines from years to months.
EFSA novel food assessments are extending evaluation windows for microbiome-related health claims, forcing reformulation roadmaps into contingency planning mode. The industrial consequence is deferred launch timelines and frozen marketing positioning for premium tier entrants. Specialized hypoallergenic segments face the greatest exposure, as these formulations most frequently incorporate novel protein structures requiring full toxicological dossiers.
Urban parent purchasing is consolidating around pharmacy-channel credibility over mass retail price competition, elevating clinical endorsement and healthcare professional recommendation as decisive selection criteria. E-commerce platforms are displacing traditional grocery aisle discovery in tier-one Chinese and Indian cities. This rotation is most visible in Shanghai, Beijing, Mumbai, and Delhi, where same-day delivery infrastructure supports replenishment buying patterns incompatible with periodic retail stock-up trips.
Baby Infant Formula Market Segmentation
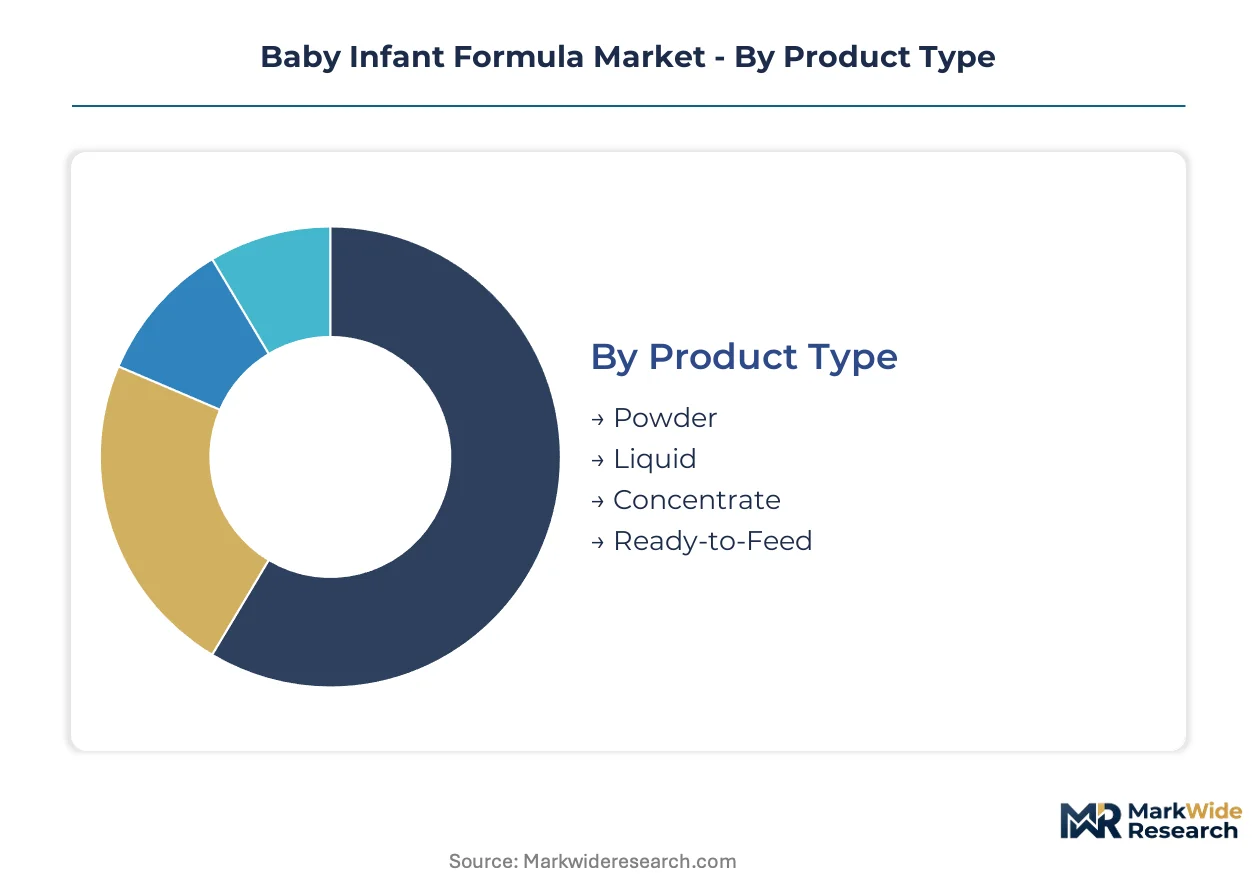
Segmentation in infant formula reveals how formulation chemistry, age-appropriate nutrition, and channel credibility intersect to determine purchase decisions. Powder formats dominate developing markets while ready-to-feed liquids capture urban convenience premiums. Understanding these divides exposes where margin pools concentrate versus where volume scales.
Product Type:
Customization spans minimal-preparation convenience at one pole and cost-optimized bulk purchasing at the other, with storage requirements and shelf stability driving the trade-off calculus.
- Powder:Dry-blended formulations requiring reconstitution with water, packaged in metal cans or flexible pouches with nitrogen flushing for oxidation protection. Demand concentrates in provincial India and tier-two Chinese cities where refrigeration infrastructure remains inconsistent and price sensitivity dominates household budgets.
- Ready-to-Feed:Sterile liquid formulations in single-serve bottles or multi-serve cartons, eliminating preparation error risk and reducing contamination exposure. Urban dual-income households in Shanghai, Mumbai, and São Paulo drive adoption as time compression outweighs per-serving cost premiums.
- Liquid:Concentrated liquid requiring dilution, occupying a narrowing middle ground as powder improves dispersibility and ready-to-feed penetrates convenience segments.
- Concentrate:Reduced-volume liquid requiring water addition, retaining niche positioning in institutional settings and emergency preparedness kits where storage density matters.
Leading the category by volume: Powder. Growing fastest: Ready-to-Feed.
Age Group:
Regulatory frameworks and developmental biology create sharp formulation boundaries that manufacturers must navigate with distinct nutrient density profiles.
- Newborn:First-month formulations with elevated whey-to-casein ratios mimicking colostrum composition and reduced renal solute load. Hospital discharge protocols in the US and EU increasingly mandate ready-to-feed formats for supplementation.
- Infant:Standardized 0-12 month formulations governed by Codex Alimentarius protein and fat specifications, representing the volume anchor across all geographies.
- Toddler:Reduced-regulation follow-on formulas with adjusted micronutrient levels, facing intensifying WHO Code scrutiny for marketing practices targeting 12-36 month transitions.
- Preschooler:Growing-up milks with added prebiotics and DHA positioning, concentrated in East Asian markets where extended formula consumption persists beyond breastfeeding norms.
Infant formulations generate the dominant revenue share. Toddler segments face the steepest regulatory headwinds.
Ingredient Type:
Protein sourcing decisions cascade through allergenicity profiles, organic certification premiums, and supply chain traceability requirements.
- Cow's Milk:Demineralized whey and casein derivatives standardized to breast milk amino acid profiles, commanding baseline market presence across all geographies.
- Hydrolyzed:Enzymatically fragmented proteins reducing allergenic peptide size, positioned in pharmacy channels for pediatric allergy management and reflux mitigation.
- Soy:Plant-based isolates for lactose intolerance and galactosemia cases, facing declining preference as hydrolyzed dairy options improve palatability.
- Organic:Certified ingredient streams with prohibited synthetic pesticide residues and GMO exclusion, capturing shelf space premiums in North American and European natural retail.
Cow's Milk maintains volume leadership. Hydrolyzed formulations expand most quickly on allergy diagnosis growth.
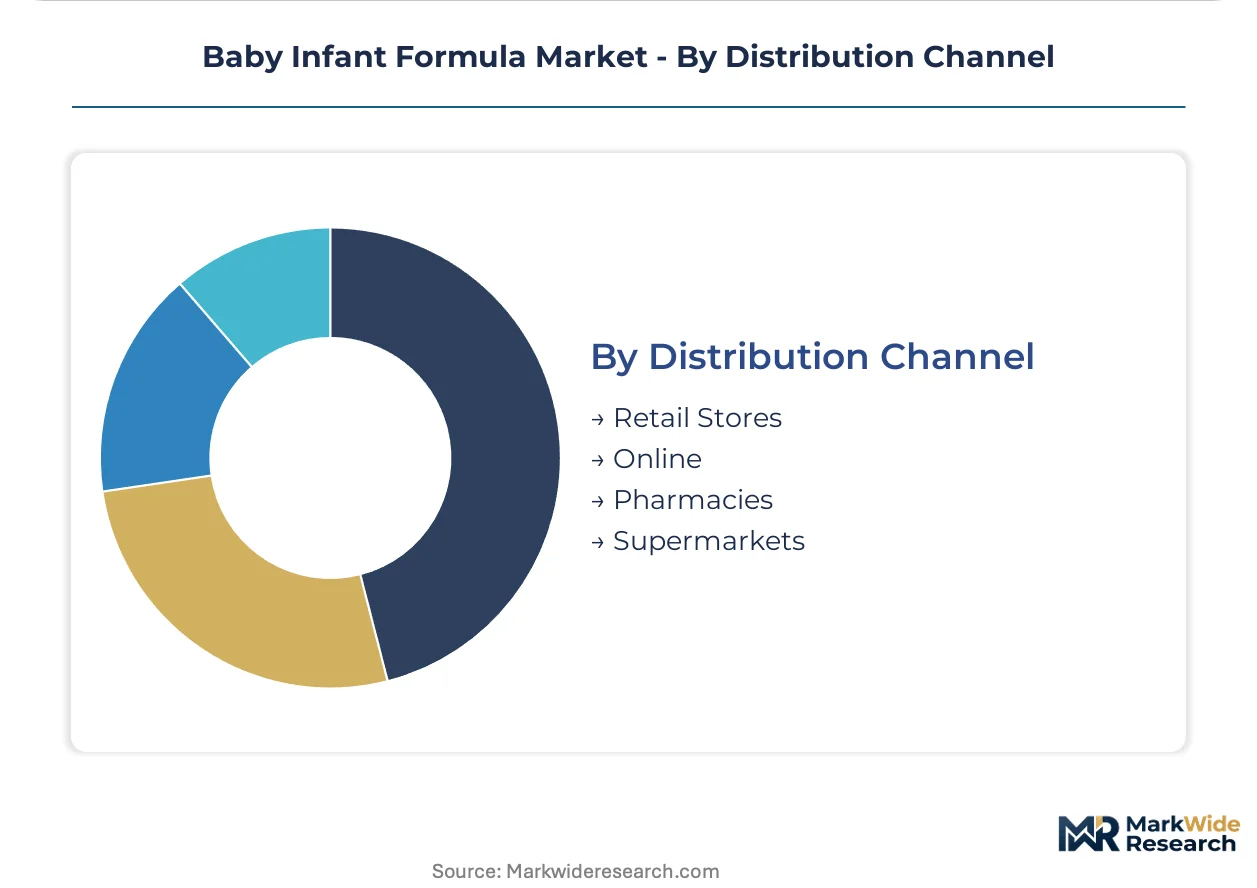
Distribution Channel:
Channel selection signals trust hierarchy, with clinical endorsement outweighing price transparency in first-purchase decisions.
- Pharmacies:Credibility-driven positioning with healthcare professional recommendation, dominating hypoallergenic and specialty formula distribution in Germany, France, and Japan.
- Supermarkets:Mass-market accessibility with promotional intensity, retaining volume concentration in North American suburban markets.
- Online:Subscription replenishment and cross-border import platforms, displacing traditional discovery in tier-one Chinese and Indian metropolitan areas.
- Retail Stores:General merchandisers and convenience outlets, serving emergency purchase occasions and rural catchment areas with limited pharmacy density.
Pharmacies command the highest margin per unit. Online channels gain share fastest on urban logistics infrastructure maturation.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China's Hainan Free Trade Port tax incentives concentrate formula import processing and cross-border e-commerce fulfillment, drawing multinational registration holders to island-based bonded warehousing facilities.
China
Metropolitan birth concentration in Shanghai and Beijing compresses distribution radius for ready-to-feed formats, while SAMR's GB 10765 purity mandates filter marginal importers. The Yangtze River Delta clusters domestic blending facilities serving tier-two provincial capitals with powder formulations.
United States
Hospital discharge protocols in Texas and Florida metro areas mandate sterile liquid formats for newborn supplementation, accelerating pharmacy-channel penetration. FDA infant formula regulations enforce batch-level traceability that elevates compliance spending for powder producers dependent on demineralized whey supply chains.
Germany
Pharmacy-channel credibility in Bavaria and North Rhine-Westphalia sustains premium positioning for hypoallergenic formulations, with EFSA novel food assessments extending evaluation windows for microbiome-related claims. The country's central European location anchors distribution hubs serving adjacent EU markets under REACH chemical registration frameworks.
India
FSSAI import clearance requirements and BIS certification standards tighten ingredient documentation for multinational entrants, while metropolitan birth shifts toward Mumbai and Delhi concentrate demand density. Maharashtra and Gujarat host domestic dry-blending operations targeting tier-two city expansion before local brand consolidation completes.
Japan
PMDA pharmaceutical-grade manufacturing standards and METI industrial policy support specialized hypoallergenic production in the Kanto region around Tokyo. Aging demographics and declining birth rates compress volume growth, elevating premium per-unit positioning through healthcare professional endorsement channels.
Baby Infant Formula Market Vendor Landscape
Swiss and Dutch producers anchor the premium-tier formulation segment; Chinese domestic specialists hold volume positions in provincial distribution. The vendor base structures around three archetypes: vertically integrated nutrition science platforms, pharmacy-channel hypoallergenic specialists, and contract manufacturing organizations serving private-label retail. Competitive moves concentrate on SAMR registration acquisition in China and precision fermentation capacity buildout for biosynthetic ingredients.
Among European-based nutrition conglomerates, Nestle and Danone occupy positions spanning premium and specialty tiers, with Nestle exemplifying the vertically integrated science platform archetype and Danone anchoring pharmacy-channel credibility through specialized lines. FrieslandCampina represents the cooperative-structured dairy processor archetype, leveraging upstream milk supply control to secure demineralized whey input stability for powder-format producers.
| Leading Market Players |
|---|
| Reckitt Benckiser |
| FrieslandCampina |
| Nestle |
| Yili Group |
| Arla Foods |
| Danone |
| Perrigo Company |
| Meiji Holdings |
| Abbott |
| Others |
Supply Flow & Price Mechanics
China's GB 10765 purity mandates and evolving EU REACH frameworks gate qualified supply access and premium-tier pricing power, compressing margins for non-compliant suppliers while elevating certified incumbents who capture pharmacy-channel premiums through traceability investments.
Pricing Analysis
Lead-time-driven pricing stratification rewards short replenishment cycles with pharmacy-channel premiums while spot inventory in tier-two Chinese cities trades at discounts. Three-tier pricing structure across premium, standard, and economy levels reflects certification grade and volume scale, with hydrolyzed protein formulations commanding the widest spreads. Pricing pressure stems from whey protein concentrate commodity volatility that erodes powder-format margins. Mass-market supermarket buyers exhibit highest price sensitivity; hospital-discharge and pharmacy-channel purchasers prioritize clinical endorsement over per-serving cost.
Supply Chain Analysis
SAMR registration and FDA infant formula batch-level traceability requirements gate supplier qualification, extending onboarding timelines and freezing marginal entrants out of premium tiers. Demineralized whey sourcing concentrates in the Netherlands, New Zealand, and Ireland; vegetable oil inputs and micronutrient premixes draw from specialized chemical processors in Germany and Switzerland. Single-source vulnerability in precision fermentation capacity for lactoferrin and HMO production threatens novel ingredient pipelines. Distribution runs through pharmacy and e-commerce platforms in urban China and India, with bonded warehousing at Hainan Free Trade Port anchoring cross-border fulfillment.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Precision fermentation platforms are displacing agricultural extraction for lactoferrin and HMO production, compressing supplier qualification timelines and rewriting cost structures for biosynthetic ingredient categories.
For Market Incumbents: Lock in backward integration into precision fermentation capacity before demonstration facilities reach commercial scale, securing captive supply of novel proteins that EFSA novel food assessments will gate for late entrants. Extend SAMR registration coverage into tier-two Chinese provincial capitals before domestic brand consolidation completes, defending pharmacy-channel shelf space against emerging hypoallergenic specialists. For New Entrants and Emerging Players: GB 10765 registration in China opens a window for specialized organic and microbiome-positioned formulations in underpenetrated tier-two cities where multinational coverage remains thin. Target subscription direct-to-home models in Mumbai and Delhi metropolitan clusters, bypassing traditional grocery slotting fee structures through same-day delivery infrastructure partnerships with established logistics platforms. For Investors and Strategic Acquirers: EFSA novel food assessment clarity for HMO and probiotic health claims is the leading indicator that microbiome-positioned premium tiers will unlock marketing differentiation and margin expansion. Position acquisition screening around precision fermentation technology holders and SAMR-registered blending facilities with traceability-compliant MES infrastructure. Watch for clinical substantiation capacity bottlenecks as the signal that pediatric nutrition trial networks have become strategic moats.| Strategic Initiative | Industry Significance |
|---|---|
| Precision Fermentation Capacity Buildout | Automated lactoferrin production reduces agricultural extraction dependency and compresses batch variation for EFSA submissions. |
| SAMR Registration Acquisition | GB 10765 compliance filters marginal importers and secures pharmacy-channel access in Shanghai and Beijing metropolitan clusters. |
| Subscription Direct-to-Consumer Launch | Urban parent convenience demand enables bypass of traditional grocery slotting fees in tier-one Chinese and Indian cities. |
| Backward Integration into Whey Processing | Captive demineralized whey supply insulates margin predictability against dairy commodity price swings. |
| Microbiome Health Claims Development | HMO and probiotic positioning opens differentiation white space pending EFSA novel food assessment resolution. |
Methodological Framework
Multi-period observation of SAMR registration timelines, EFSA novel food assessment windows, and precision fermentation facility commissioning anchored the trend analysis, supplemented by interviews with pediatric nutrition R&D directors, pharmacy category managers in Germany and Japan, dairy commodity procurement leads, and regulatory affairs specialists at multinational formula registrants. Secondary validation drew from FDA infant formula enforcement reports, EFSA novel food opinions, Chinese customs import clearance data, and Codex Alimentarius standard revisions. Bottom-up volume modeling across powder, ready-to-feed, and liquid formats triangulated against top-down value estimates from channel margin analysis.
Segment-weighting applied age-group, ingredient-type, and distribution-channel dimensions across the projection horizon, with hydrolyzed protein and organic certification tiers receiving distinct growth coefficients based on pediatric allergy diagnosis expansion and pharmacy-channel premium capture. CAGRs derived from regression analysis of historical birth rate trajectories, urbanization patterns, and dual-income household proliferation in metropolitan India and China. Forecast inputs incorporated precision fermentation scale-up curves and SAMR registration approval velocity assumptions.
The model assumes a particular technology adoption path for biosynthetic lactoferrin and HMO production; alternative pathways for agricultural extraction efficiency gains would alter the outlook for ingredient cost compression and novel food assessment timelines. Forecasts reflect these assumptions alongside breastfeeding promotion intensity under WHO Code enforcement and dairy commodity price volatility. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Baby Food and Infant Formula
Global DHA Algae Oil for Infant Formula Market
Baby Food and Infant Formula
Asia-Pacific Baby Food Market
Baby Food and Infant Formula
Goat Milk Formula Market
Baby Food and Infant Formula
Baby Cereal-Based Complementary Food Market
Baby Food and Infant Formula
Hydrolyzed Formula Milk Powder Market
Baby Food and Infant Formula
Baby Formula Market
Baby Food and Infant Formula
Standard Milk Formula Market
Baby Food and Infant Formula
Parenteral Formula Market
Baby Food and Infant Formula
Cow Milk Infant Formula Market
Baby Food and Infant Formula
North America Baby Food and Infant Formula Market
Baby Food and Infant Formula
Baby Food Products Market
Baby Food and Infant Formula
Baby Formula Ingredients Market
Baby Food and Infant Formula
Infant Nutritional Premix Market
Baby Food and Infant Formula
Pureed Food Market
Baby Food and Infant Formula
GCC Baby Food and Infant Formula Market
Baby Food and Infant Formula
Baby Fruit Puree Market