
 Middle-Aged and Elderly Milk Powder Market | 2026-2036
Middle-Aged and Elderly Milk Powder Market Size, Share, and Industry Trends Forecast 2026-2036
Middle-Aged and Elderly Milk Powder Market Insights
China's dairy processing corridor is reconfiguring capacity for age-targeted nutrition. Nestlé leverages its clinical nutrition heritage to sustain premium positioning in hospital channels. Abbott Laboratories anchors its presence through science-backed cardiovascular and bone-health formulations. Mead Johnson competes via pediatric-to-geriatric brand extension strategies.
Middle-aged and elderly milk powder denotes spray-dried or roller-dried dairy formulations with elevated protein density, added calcium, vitamin D, and bioactive peptides engineered for digestive tolerance and sarcopenia mitigation in consumers over 50 years. Fortified powder leads product type value pools due to clinical-grade additive premiums, while organic powder captures fastest trajectory among health-literate urban retirees. Online stores outpace supermarkets in channel growth as direct-to-consumer subscription models reduce price transparency friction.
NMPA fortification mandates and China's GB standards govern label claims and micronutrient ceilings, while FDA GRAS notifications shape export eligibility for Asian manufacturers targeting North American diaspora consumers. EFSA health claim authorizations determine which physiological benefit statements survive European market entry scrutiny. Stakeholders must monitor evolving silver-economy procurement specifications from care home chains and national insurance reimbursement lists.
Market Dynamics
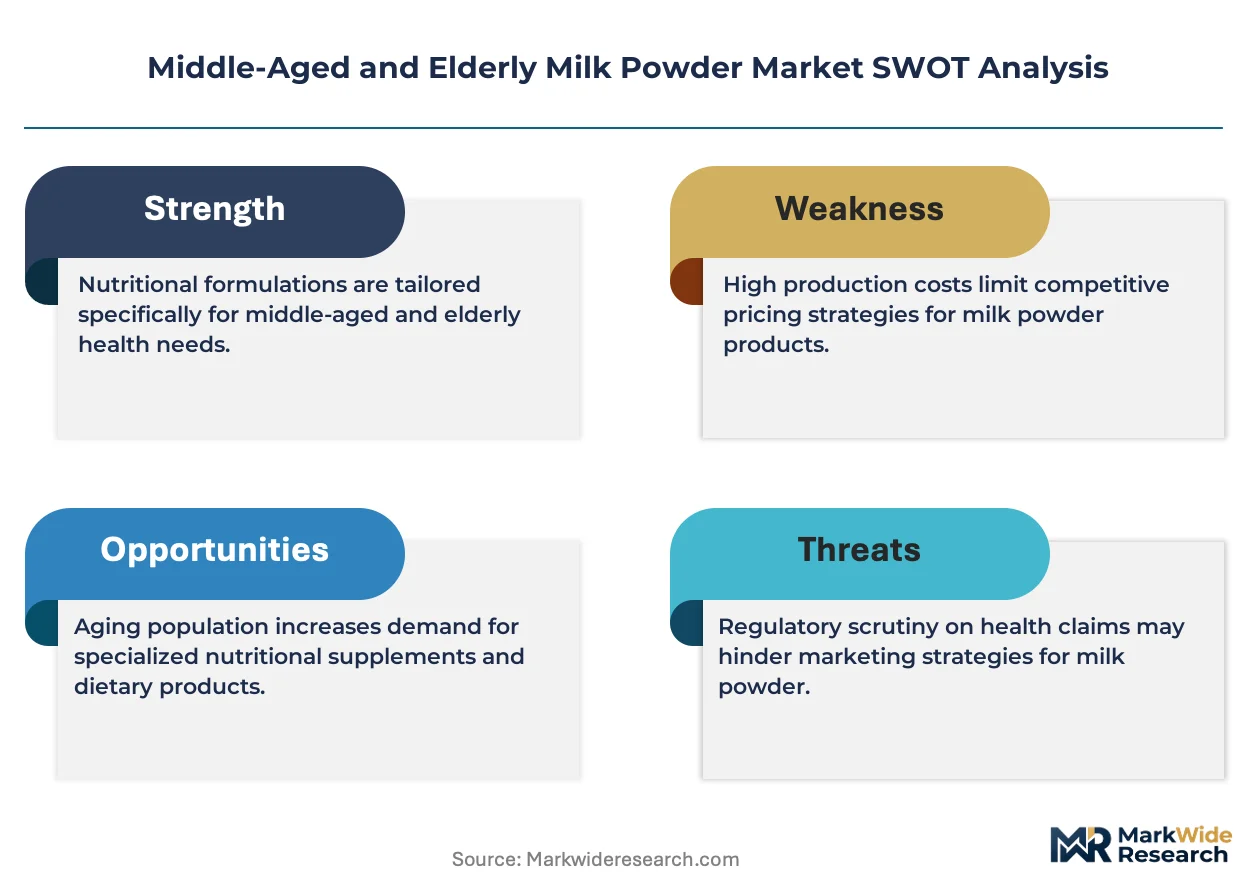
NMPA fortification mandates and China's GB standards are compressing formulation freedom while elevating compliance costs for cross-border manufacturers targeting hospital procurement channels.
Growth Catalysts
- GB 19644 fortification standards:China's micronutrient density requirements create clinical-grade product tiers that command premium pricing in institutional channels.
- Sarcopenia mitigation protocols:Japanese long-term care facilities are integrating protein-dense formulations into standardized meal plans for residents over 75.
- Direct-to-consumer subscription platforms:Online stores bypass traditional retail markups, enabling manufacturers to capture margin while offering personalized nutrition bundles.
Market Restraints
- Raw milk input volatility:New Zealand dairy commodity auctions expose processors to margin compression during feed-cost spikes.
- Cross-border e-commerce friction:SAMR registration timelines for imported formulations extend 18-24 months, freezing market access for new entrants.
- Plant-protein substitution:Pea and oat protein isolates in ready-to-drink formats capture health-literate consumers seeking non-dairy alternatives.
Strategic Opportunities
- Tier-3 Chinese city penetration:Aging demographics in Hefei, Changzhou, and Zhongshan remain underserved by clinical nutrition distribution networks.
- Dual carbon incentive alignment:China's MEE carbon intensity targets favor domestic processors with renewable energy certificates in procurement scoring.
- AI-driven personalization engines:Machine learning platforms analyze biomarker data to recommend micronutrient blends, collapsing the gap between mass-market and clinical nutrition.
Industry Challenges
- Clinical nutrition specialist scarcity:Formulation chemists with geriatric metabolism expertise command premium compensation, constraining R&D team scaling.
- Legacy ERP integration:Batch traceability requirements under China's food safety law force costly upgrades to manufacturing execution systems.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Middle-Aged and Elderly Milk Powder Market |
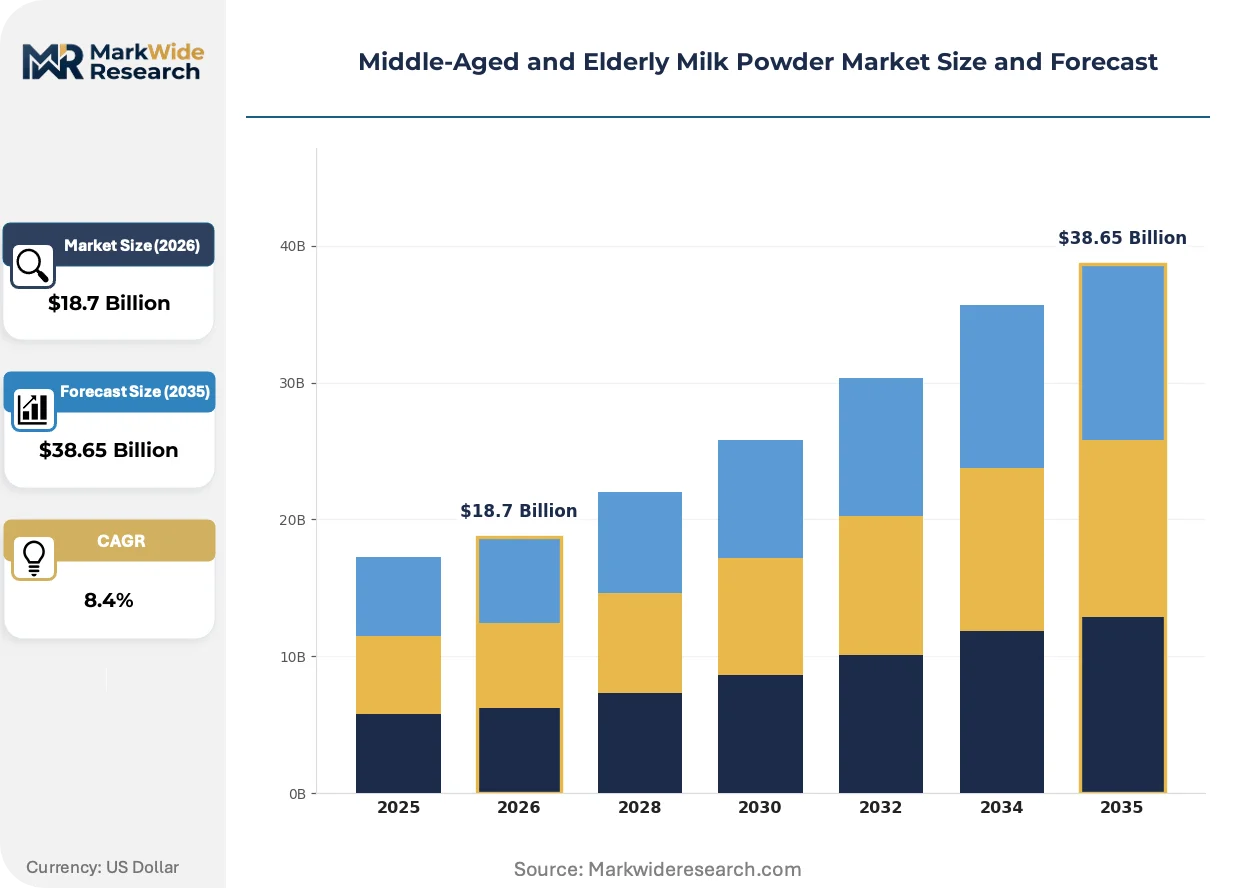
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $38.65 Billion |
| CAGR (2026 – 2036) | 8.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Skimmed Powder, Whole Powder, Fortified Powder, Organic Powder Customer Type: Individuals, Care Homes, Hospitals, Retailers Distribution Channel: Supermarkets, Online Stores, Pharmacies, Direct Sales Packaging Type: Boxes, Tetra Paks, Sachets, Cans |
| Companies Covered | Nestlé, Abbott Laboratories, Mead Johnson, Yili Group, Mengniu Dairy, Danone, Fonterra, China Feihe, The a2 Milk Company, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Middle-Aged and Elderly Milk Powder Market Trends and Innovations
Formulation science and distribution architecture are converging to collapse traditional boundaries between clinical nutrition and consumer wellness categories.
Microencapsulation technology for heat-sensitive bioactive peptides is collapsing the stability gap between pharmaceutical-grade and food-grade delivery systems. Japanese and South Korean manufacturers are adopting fluid-bed coating equipment at pilot scale. This compression enables shelf-stable formulations previously restricted to cold-chain clinical products.
EFSA health claim authorization pathways are tightening evidentiary standards for bone-density and cardiovascular benefit statements. European manufacturers must now submit human intervention trials rather than observational data. Premium-positioned brands are responding by funding proprietary clinical studies to defend label differentiation.
Hospital discharge protocols are embedding six-month nutrition prescriptions into post-acute care plans. Direct-to-patient fulfillment platforms are replacing pharmacy intermediaries in Tokyo, Seoul, and Shanghai metropolitan corridors. This channel shift concentrates purchasing influence with discharge coordinators rather than retail buyers.
Middle-Aged and Elderly Milk Powder Market Segmentation
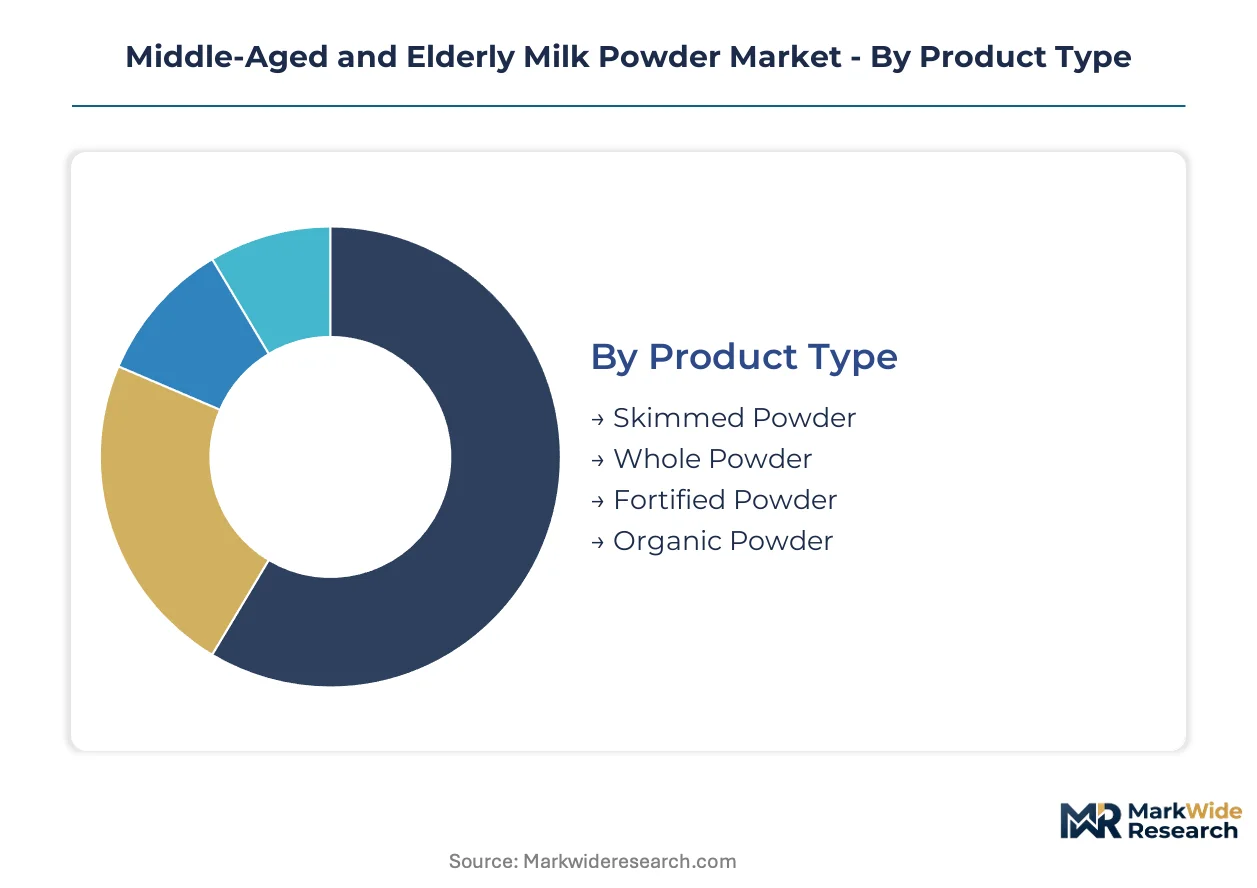
Segmentation in the Middle-Aged and Elderly Milk Powder Market reveals distinct procurement rhythms across institutional and retail channels. Care homes rotate inventory monthly while individual consumers purchase quarterly, creating divergent cash flow patterns for manufacturers.
Product Type:
Fortified powder turns inventory fastest in hospital channels, while organic powder sits longest on specialty retail shelves due to price sensitivity among health-literate urban retirees.
- Fortified Powder:Spray-dried formulations with clinical-grade calcium, vitamin D, and bioactive peptides engineered for sarcopenia mitigation. Hospital procurement channels in Shanghai and Tokyo concentrate demand as discharge protocols embed six-month nutrition prescriptions into post-acute care plans.
- Organic Powder:Certified dairy inputs from pasture-based systems with no synthetic micronutrient fortification. Premium positioning in East Asian metropolitan corridors attracts aging consumers seeking clean-label alternatives, though SAMR registration timelines stretch 18-24 months for imported organic certifications.
- Skimmed Powder:Reduced-fat formulations targeting cardiovascular health positioning in Japanese and South Korean long-term care facilities.
- Whole Powder:Full-fat dairy base preferred by traditional taste profiles in tier-3 Chinese cities with limited clinical nutrition penetration.
Fortified powder dominates installed base in institutional channels. Organic powder is where expansion concentrates among health-literate urban retirees.
Customer Type:
Cost tier separation runs deepest here: hospitals negotiate volume contracts with clinical-grade specifications while individual consumers absorb retail markups for convenience.
- Hospitals:Procurement departments specify micronutrient density thresholds aligned with NMPA fortification mandates. China's GB 19644 standards create compliance barriers that favor domestic processors with established regulatory relationships in Beijing and Guangzhou hospital networks.
- Care Homes:Japanese long-term care facilities integrate protein-dense formulations into standardized meal plans for residents over 75, driving recurring bulk orders with limited brand switching.
- Individuals:Direct-to-consumer subscription platforms bypass traditional retail markups, enabling personalized nutrition bundles based on biomarker data.
- Retailers:Supermarket buyers in Seoul and Shanghai metropolitan corridors face margin compression as online stores capture health-literate consumers seeking price transparency.
Hospitals dominate installed base through volume contracting. Care homes represent the most stable expansion trajectory as aging demographics strain institutional capacity.
Distribution Channel:
Volume concentration separates high-frequency replenishment channels from episodic purchase patterns in direct sales.
- Online Stores:E-commerce platforms with AI-driven personalization engines analyze consumer biomarker data to recommend micronutrient blends. Direct-to-consumer subscription models reduce price transparency friction and capture margin previously lost to retail intermediaries.
- Supermarkets:Traditional retail footprint remains significant in tier-3 Chinese cities where clinical nutrition distribution networks remain underdeveloped.
- Pharmacies:Hospital discharge protocols in Tokyo and Seoul are shifting fulfillment toward direct-to-patient platforms, displacing pharmacy intermediaries.
- Direct Sales:Relationship-based selling persists in aging rural demographics with limited digital literacy.
Supermarkets dominate installed base in underserved geographies. Online stores are climbing the fastest as subscription models collapse traditional channel economics.
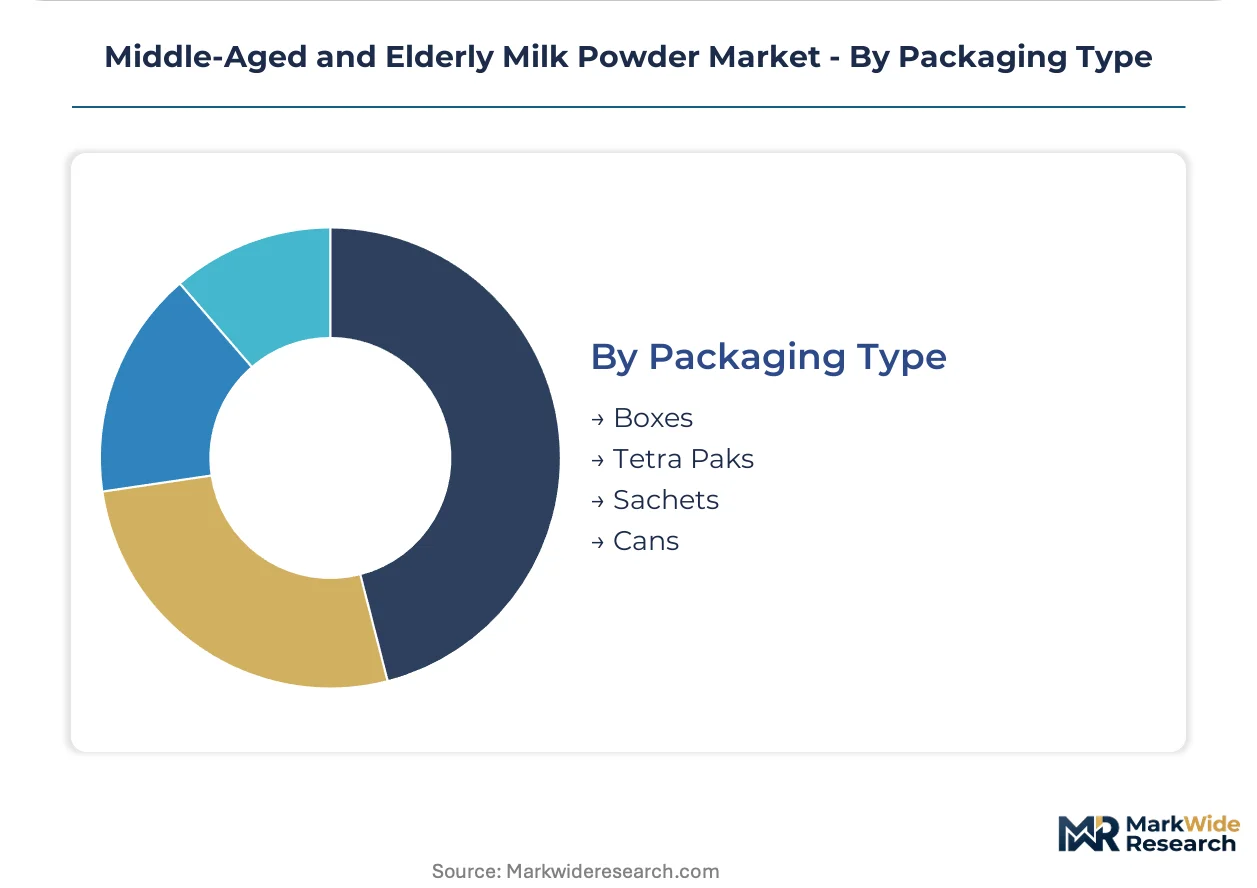
Packaging Type:
Supply concentration favors metal canning infrastructure in dairy processing corridors, while flexible formats require specialized equipment with longer amortization cycles.
- Cans:Metal containers with nitrogen flushing provide 24-month shelf stability for fortified formulations with heat-sensitive bioactives. Chinese dairy processors with renewable energy certificates gain procurement scoring advantages under MEE carbon intensity targets.
- Sachets:Single-serve flexible packaging enables precise portion control in Japanese long-term care facilities with standardized meal plans.
- Boxes:Paperboard secondary packaging supports retail shelf differentiation in supermarket channels.
- Tetra Paks:Aseptic carton technology remains marginal in powder applications due to moisture sensitivity requirements.
Cans dominate installed base for clinical-grade formulations. Sachets represent the steepest expansion trajectory as portion-controlled institutional feeding protocols proliferate.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Dairy processors cluster in East Asian manufacturing corridors where aging demographics concentrate purchasing power. Hospital procurement networks and direct-to-consumer platforms are rewiring traditional distribution economics across metropolitan hubs.
China
GB 19644 fortification standards and NMPA registration mandates reshape formulation requirements for clinical-grade tiers. SAMR cross-border e-commerce timelines stretch 18-24 months, freezing market access for new entrants. Yangtze River Delta processors in Shanghai and Hangzhou reconfigure capacity for age-targeted nutrition.
Japan
Long-term care facilities integrate protein-dense formulations into standardized meal plans for residents over 75. METI silver-economy procurement specifications influence national insurance reimbursement lists. Kanto corridor hospitals in Tokyo embed six-month nutrition prescriptions into post-acute discharge protocols.
South Korea
MFDS health claim authorizations determine physiological benefit survival on domestic labels. Seoul metropolitan pharmacies face displacement as direct-to-patient fulfillment platforms capture hospital discharge traffic. Busan-Ulsan dairy processors pilot microencapsulation equipment for heat-sensitive bioactive stability.
Australia
TGA therapeutic goods frameworks create parallel regulatory tracks for clinical versus consumer positioning. New South Wales and Victoria dairy commodity auctions expose processors to feed-cost margin compression. Sydney-based exporters target North American and Asian diaspora channels with fortification-adapted formulations.
United States
FDA GRAS notifications shape export eligibility for Asian manufacturers targeting domestic diaspora consumers. Medicare Advantage supplemental benefit expansions create institutional procurement opportunities. California and Wisconsin dairy cooperatives explore spray-dried capacity conversion for specialized nutrition segments.
Middle-Aged and Elderly Milk Powder Market Competitive Landscape
Multinational nutrition conglomerates and Asia-Pacific dairy specialists split the market along clinical-channel versus mass-retail vectors. Consolidation pressure concentrates in hospital procurement networks where volume contracting favors established regulatory relationships. Three archetypes dominate: pharmaceutical-nutrition hybrids with clinical heritage, integrated dairy processors with domestic fortification compliance, and pediatric-to-geriatric brand extenders. Competitive moves center on hospital channel anchoring and direct-to-consumer subscription platform deployment.
Within the pharmaceutical-nutrition hybrid tier, Nestlé and Abbott Laboratories occupy positions defined by clinical trial infrastructure and hospital discharge protocol integration. Mead Johnson exemplifies the pediatric-to-geriatric extension archetype, leveraging existing brand equity across life-stage transitions. Among Asia-Pacific integrated processors, Yili Group and Mengniu Dairy anchor domestic supply chains with GB standards compliance and renewable energy procurement scoring advantages under MEE carbon intensity frameworks.
| Leading Market Players |
|---|
| Nestlé |
| Abbott Laboratories |
| Mead Johnson |
| Yili Group |
| Mengniu Dairy |
| Danone |
| Fonterra |
| China Feihe |
| The a2 Milk Company |
| Others |
Pricing and Supply Chain Analysis
Yangtze River Delta freight corridors concentrate dairy processing capacity and dictate logistics cost dynamics for clinical-grade formulations, compressing margin structures for cross-border manufacturers while enabling domestic processors to capture premium pricing in hospital procurement channels.
Pricing Analysis
GB 19644 fortification standards dictate the pricing tier structure across clinical and consumer segments. Three-tier pricing structure across premium, standard, and economy levels separates NMPA-registered clinical formulations from retail-adjacent fortified powders and unfortified commodity dairy. Price differentiation hinges on micronutrient certification grade and volume contracting scale. Pricing pressure stems from New Zealand dairy commodity auction volatility feeding into raw milk input costs. Individual consumers in East Asian metropolitan corridors exhibit highest price sensitivity, while hospital procurement departments absorb premiums for compliance-guaranteed supply.
Supply Chain Analysis
Chinese dairy processors with renewable energy certificates and established NMPA relationships hold contract-manufacturing concentration for clinical-grade output. Geographic supply concentrates in China, New Zealand, and Australia, with spray-drying infrastructure clustering in Yangtze River Delta and Victoria dairy corridors. Raw material dependencies center on pasture-based milk solids, whey protein isolates, and heat-sensitive bioactive peptide inputs. Single-source vulnerability runs through New Zealand dairy auction pricing mechanisms. Distribution runs through hospital procurement networks and direct-to-consumer subscription platforms, displacing traditional retail intermediaries in Tokyo, Seoul, and Shanghai metropolitan corridors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Middle-Aged and Elderly Milk Powder Market sits in a cyclical recovery phase as China's silver-economy procurement specifications expand institutional demand following pandemic-era care home disruptions.
For Market Incumbents: Harden regulatory compliance infrastructure against NMPA fortification mandate evolution, embedding GB standards expertise into formulation teams to defend hospital channel positioning. Deepen backward integration into pasture-based milk supply through renewable energy-certified processing capacity in Yangtze River Delta corridors, insulating margin from New Zealand commodity auction volatility while capturing MEE carbon intensity procurement scoring advantages. For New Entrants and Emerging Players: Pursue tier-3 Chinese city penetration where clinical nutrition distribution networks remain underdeveloped, targeting Hefei, Changzhou, and Zhongshan aging demographics with whole powder formulations adapted to traditional taste profiles. Leverage AI-driven personalization engines as go-to-market angle, offering biomarker-based micronutrient bundles through direct-to-consumer subscription platforms that bypass SAMR registration timelines via domestic partnership structures. For Investors and Strategic Acquirers: Carve-out targets emerge from pharmaceutical-nutrition hybrids seeking to divest non-core geriatric dairy assets amid portfolio rationalization. Long-term viability centers on clinical trial infrastructure and hospital discharge protocol integration as moat sources. Watch for inflection in national insurance reimbursement list expansions for sarcopenia mitigation protocols, signaling institutional demand acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Microencapsulation Technology Adoption | Japanese and South Korean manufacturers pilot fluid-bed coating equipment to collapse stability gaps between pharmaceutical-grade and food-grade bioactive peptide delivery. |
| Direct-to-Consumer Subscription Launch | AI-driven personalization engines analyze biomarker data to recommend micronutrient blends, capturing margin previously lost to retail intermediaries in Seoul and Shanghai corridors. |
| Renewable Energy Certification Investment | Domestic Chinese processors with MEE carbon intensity compliance gain procurement scoring advantages in hospital and care home channel bidding. |
| EFSA Health Claim Authorization Pursuit | European manufacturers fund proprietary human intervention trials to defend bone-density and cardiovascular benefit statements against tightening evidentiary standards. |
| Tier-3 Distribution Network Expansion | Clinical nutrition penetration in Hefei, Changzhou, and Zhongshan addresses underserved aging demographics with limited hospital procurement access. |
Research Methodology
Cross-validation between primary interviews with industry stakeholders and secondary data sources anchors the qualitative findings in this analysis. Formulation chemists, hospital procurement managers, care home nutrition directors, and regulatory affairs specialists at NMPA-registered processors provided operational perspective. Secondary validation drew from SAMR registration databases, GB standards documentation, EFSA health claim authorization records, and hospital procurement contract disclosures. Bottom-up demand modeling triangulates against top-down macroeconomic overlays across the analysis window.
Calibration against historical volume trajectories and installed capacity utilization rates shapes the projection framework. Segmentation dimensions span product type, customer archetype, distribution channel, and packaging format, with regional regulatory cluster as cross-cutting variable. CAGRs derive from slope analysis of adoption curves and capacity expansion announcements. Forecast inputs incorporate NMPA fortification mandate evolution timelines and METI silver-economy procurement specification updates.
Macroeconomic conditions sit as an overlay; deviation in Chinese healthcare expenditure growth rates, New Zealand dairy commodity auction pricing, or yen-won-yuan exchange volatility would shift the trajectory. Forecasts reflect documented assumptions regarding regulatory stability and institutional procurement protocol persistence. Quarterly review of SAMR registration approval velocity, hospital discharge prescription embedding rates, and care home capacity expansion permits is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Baby Food and Infant Formula
Baby Food Testing Market
Baby Food and Infant Formula
Cow Milk Infant Formula Market
Baby Food and Infant Formula
Baby Food and Infant Formula Market
Baby Food and Infant Formula
Pet Milk Replacement Products Market
Baby Food and Infant Formula
Baby Juice Market
Baby Food and Infant Formula
Goat Milk Formula Market
Baby Food and Infant Formula
North America Baby Food Market
Baby Food and Infant Formula
North America Baby Food and Infant Formula Market
Baby Food and Infant Formula
Hydrolyzed Formula Milk Powder Market
Baby Food and Infant Formula
Ready to Use Supplementary Food Market
Baby Food and Infant Formula
Pureed Food Market
Baby Food and Infant Formula
Human Milk Oligosaccharides in Infant Formula Market
Baby Food and Infant Formula
India Baby Food Market
Baby Food and Infant Formula
Fortified Pet Food Market
Baby Food and Infant Formula
Russia Pet Food Market
Baby Food and Infant Formula
Europe Organic Baby Food Market