
 Omega 3 Ingredients for Infant Food Market | 2026-2036
Omega 3 Ingredients for Infant Food Market Size, Share, and Industry Trends Forecast 2026-2036
Omega 3 Ingredients for Infant Food Market Insights
Premium organic infant formula manufacturers are redrawing procurement priorities away from conventional fish oil toward traceable algal DHA sources. Koninklijke DSM anchors this transition through its controlled fermentation platforms that deliver EPA-free DHA with batch-level transparency. Aker BioMarine competes via its Antarctic krill fishery certification, leveraging Marine Stewardship Council chain-of-custody protocols to sustain supply security for European blenders. BASF extends its position through backward integration into Schizochytrium strain development, reducing reliance on wild-catch variability.
Omega 3 ingredients for infant food encompass refined long-chain polyunsaturated fatty acids—principally docosahexaenoic acid (DHA) and eicosapentaenoic acid (EPA)—delivered at minimum 35% concentration for neural and retinal development in neonates. These lipids undergo molecular distillation or cold-pressing followed winterization to remove contaminants and achieve oxidative stability below 5 meq/kg peroxide value. Algal oil now leads ingredient type growth due to vegetarian positioning and absence of marine allergen risk, while fish oil occupies mature volume pools tied to cost-sensitive formula segments. Powder form dominates manufacturing throughput for dry-blend infant formula, though oil-in-water emulsions are gaining fastest in ready-to-feed liquid formats where homogenization tolerance determines shelf stability.
The FDA's GRAS notification framework and EFSA's novel food approval pathway jointly govern DHA inclusion thresholds in infant nutrition, with both agencies tightening limits on 3-MCPD ester and glycidyl ester contaminants. China's National Health Commission maintains separate DHA usage standards for GB 10765-compliant infant formula, creating a three-jurisdiction compliance burden for multinational suppliers. Stakeholders must monitor divergence between algal fermentation capacity expansion and the pace of regulatory harmonization across these jurisdictions to avoid stranded inventory or reformulation costs.
Market Dynamics
Algal fermentation technology is compressing the omega-3 supply base by eliminating marine catch variability and enabling EPA-free DHA production at pharmaceutical-grade purity. This shift forces incumbent fish oil refiners to reconfigure extraction assets or exit infant nutrition entirely.
Growth Catalysts
- China's GB 10765 standards:Mandatory DHA fortification thresholds in first-stage infant formula create fixed demand volumes for certified suppliers.
- Controlled fermentation platforms:Photobioreactor-based Schizochytrium cultivation delivers batch-level traceability that satisfies clean-label procurement mandates.
- Urban middle-class parents:Concentrated demand in Shanghai, Beijing, and Shenzhen prioritizes certified organic omega-3 sourcing regardless of price position.
Market Restraints
- Algal oil production cost structure:Fermentation capex and carbohydrate feedstock expenses maintain a 40-60% premium over refined anchovy oil.
- Antarctic krill supply concentration:Marine Stewardship Council-certified Antarctic fisheries face annual catch quota compression from Commission for the Conservation of Antarctic Marine Living Resources.
- 3-MCPD ester regulatory ceilings:EFSA's tightening contaminant limits for processed lipids force reformulation of legacy fish oil concentrates.
Strategic Opportunities
- India's infant formula market:FSSAI's pending DHA fortification guidelines for Stage 1 products open a 1.2 billion population addressable market.
- Ready-to-feed liquid formats:Oil-in-water emulsion stability requirements create premium positioning for microencapsulated algal DHA with extended shelf life.
- EU Green Deal bioeconomy incentives:Horizon Europe funding streams subsidize fermentation facility expansion for sustainable lipid production.
Industry Challenges
- Novel food approval timelines:EFSA's 18-24 month strain safety evaluation window delays market entry for new algal DHA producers.
- Cross-jurisdiction compliance burden:Simultaneous FDA GRAS, EFSA novel food, and NHC GB standard adherence requires redundant toxicology dossiers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Omega 3 Ingredients for Infant Food Market |
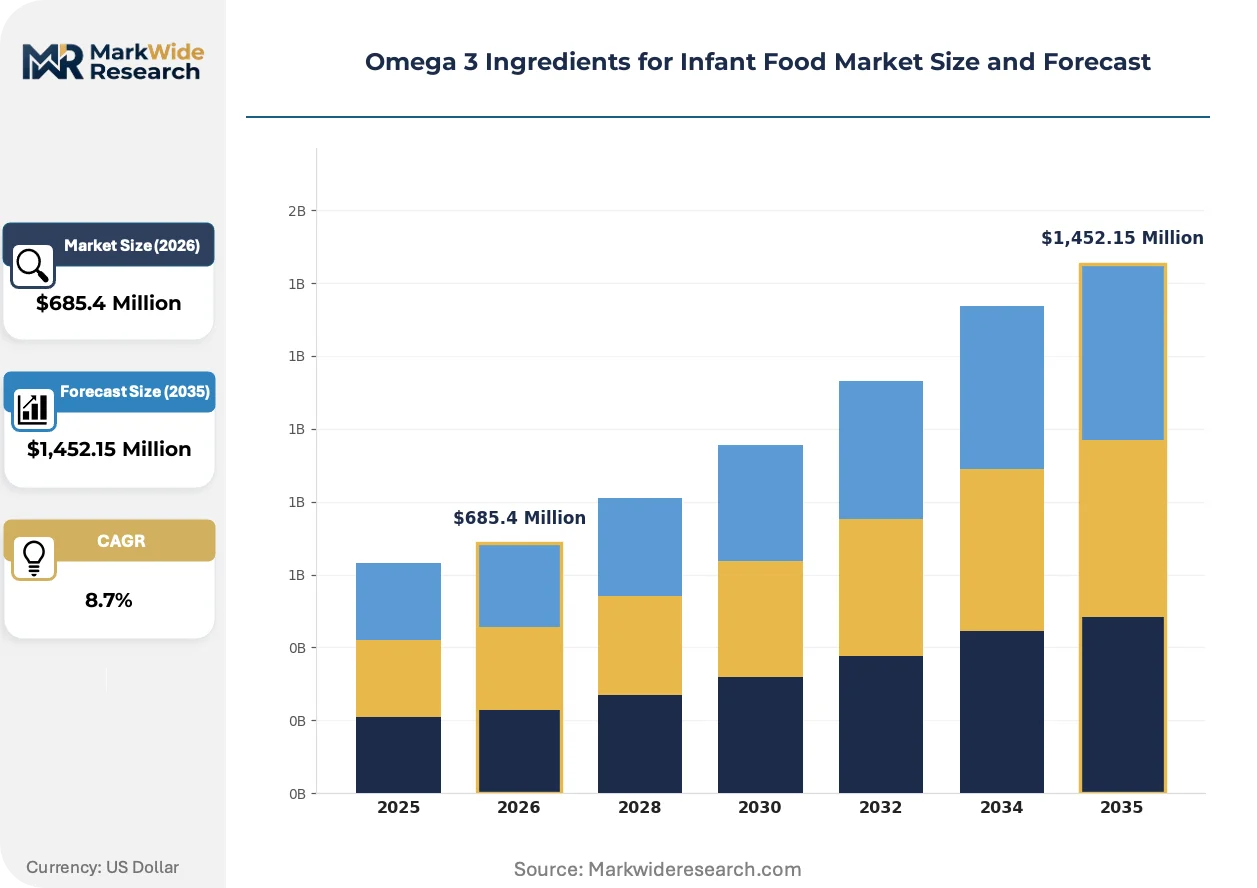
| Market Size in 2026 | $685.4 Million |
| Market Size in 2035 | $1,452.15 Million |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Ingredient Type: Fish Oil, Algal Oil, Flaxseed Oil, Krill Oil Form: Liquid, Powder, Emulsion, Capsule Certification: Organic, Non-GMO, Gluten-Free, FDA Approved Application: Infant Formula, Baby Snacks, Dietary Supplements, Cereal |
| Companies Covered | Aker BioMarine, BASF, Koninklijke DSM, Cargill Incorporated, Croda International, EPAX, Martek Biosciences, Ocean Nutrition Canada, Clover Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Omega 3 Ingredients for Infant Food Market Trends and Innovations
Fermentation-derived lipids are rewriting technical specifications for infant formula fortification. Manufacturers now compete on oxidative stability metrics and single-origin traceability rather than crude concentration alone.
Single-cell algal oil produced via heterotrophic fermentation is displacing traditional marine sources in premium organic formulations. European and North American blenders are adopting EPA-free DHA to eliminate allergen labeling requirements and extend clean-label claims. This displacement compresses demand for Peruvian anchovy and North Atlantic cod liver refiners, forcing asset redeployment toward pet food or aquaculture feed.
EFSA's 2023 updated guidance on 3-MCPD and glycidyl ester limits in infant formula lipids imposes sub-ppm maximum residue thresholds. Refiners must install additional molecular distillation or enzymatic interesterification capacity to achieve compliance. Algal fermentation operators gain relative advantage as their process avoids high-temperature deodorization that generates these contaminants.
Chinese parents now demand batch-level blockchain traceability from DHA suppliers, with QR-code verification becoming standard in tier-one cities. Domestic formula brands are bypassing distributors to contract directly with DSM and BASF fermentation facilities. This disintermediation collapses traditional import agent margins and accelerates supplier concentration among vertically integrated multinationals.
Omega 3 Ingredients for Infant Food Market Segmentation
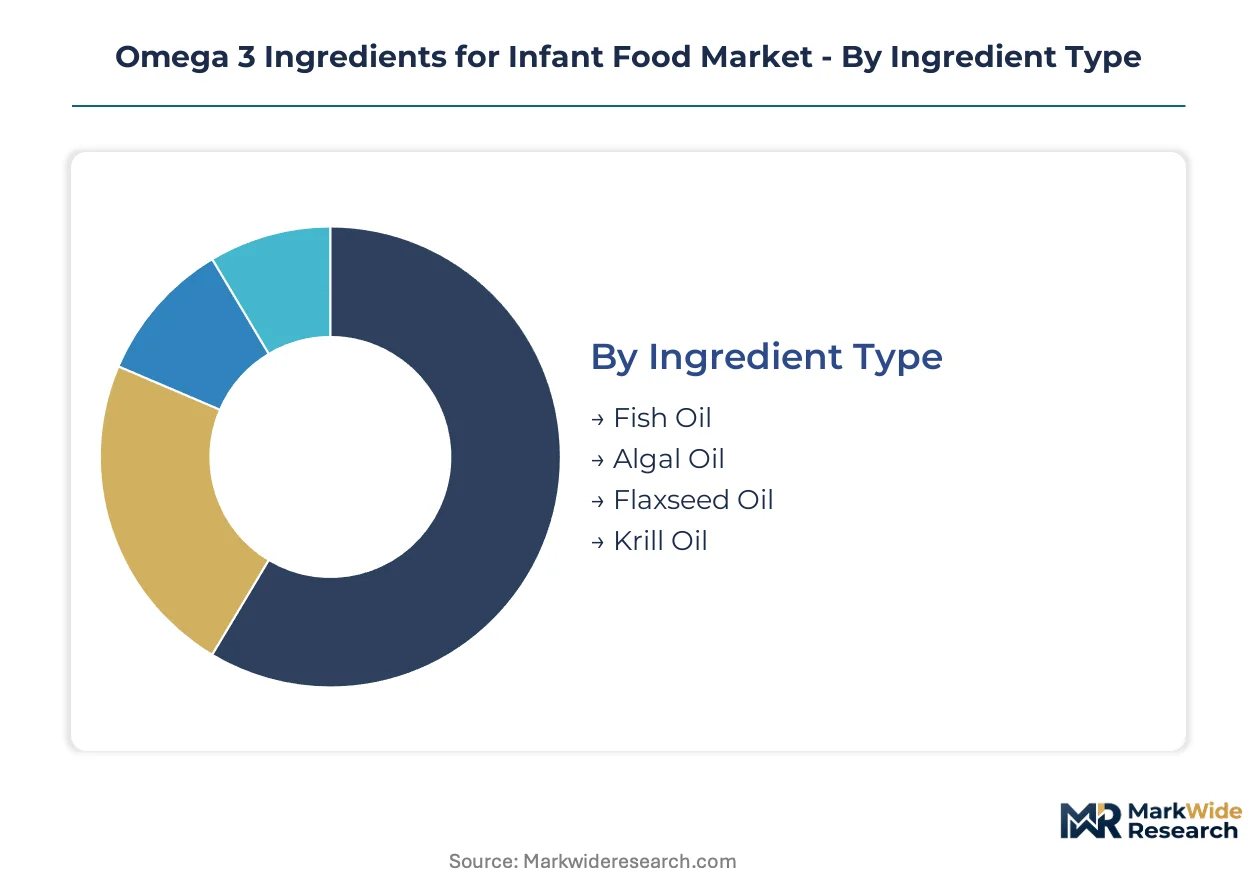
Ingredient sourcing decisions in infant nutrition increasingly hinge on allergen risk profiles and clean-label positioning rather than cost optimization alone. Segmentation reveals where substitution pressure from algal fermentation is compressing traditional marine oil volumes.
Ingredient Type:
Algal oil substitution pressure weighs most heavily on legacy fish oil refiners as fermentation platforms eliminate EPA contamination and supply variability.
- Fish Oil:Refined anchovy and cod liver concentrates deliver DHA-EPA blends at 35-50% purity through molecular distillation. Demand concentrates in cost-sensitive formula segments across Latin America and Southeast Asia where price positioning trumps vegetarian claims.
- Algal Oil:Schizochytrium-derived DHA achieves pharmaceutical-grade purity without marine allergens. Urban middle-class parents in Shanghai and Beijing prioritize certified algal sourcing for first-stage formulas regardless of 40-60% cost premium over refined fish oil.
- Flaxseed Oil:Alpha-linolenic acid precursor requires metabolic conversion to DHA with inefficient infant physiology.
- Krill Oil:Antarctic fishery certification through Marine Stewardship Council protocols sustains European premium positioning despite quota compression.
Fish oil retains volume leadership; algal oil holds the steepest expansion curve.
Form:
Manufacturing throughput requirements differentiate segments by processing compatibility with dry-blend versus liquid formula formats.
- Liquid:Unrefined or partially refined oils suit in-house emulsification by large formula manufacturers with dedicated lipid handling infrastructure.
- Powder:Spray-dried or plated lipid powders dominate dry-blend infant formula production for oxidative stability and metering precision.
- Emulsion:Oil-in-water microencapsulated formats enable ready-to-feed liquid formulas with extended shelf stability. Demand clusters in North American convenience-oriented formats where single-serve packaging commands premium positioning.
- Capsule:Unit-dose delivery serves dietary supplement applications outside core infant formula fortification.
Powder retains volume leadership; emulsion gains share fastest in liquid format expansion.
Certification:
Regulatory compliance tiers create pricing stratification across premium, standard, and economy levels with jurisdiction-specific requirements.
- Organic:USDA NOP and EU Organic certification mandates fermentation feedstock traceability and solvent-free extraction. European blenders prioritize organic algal DHA to satisfy clean-label procurement mandates from premium formula brands.
- Non-GMO:Project Verified and equivalent EU standards address parental concern over genetic modification in strain development.
- Gluten-Free:Certification addresses cross-contamination risk in shared processing facilities rather than intrinsic lipid composition.
- FDA Approved:GRAS notification pathway for DHA sources creates baseline market access threshold for US infant formula inclusion.
Organic certification commands premium positioning; FDA approval represents mandatory baseline entry requirement.
Application:
End-use concentration determines formulation complexity and regulatory scrutiny intensity across product categories.
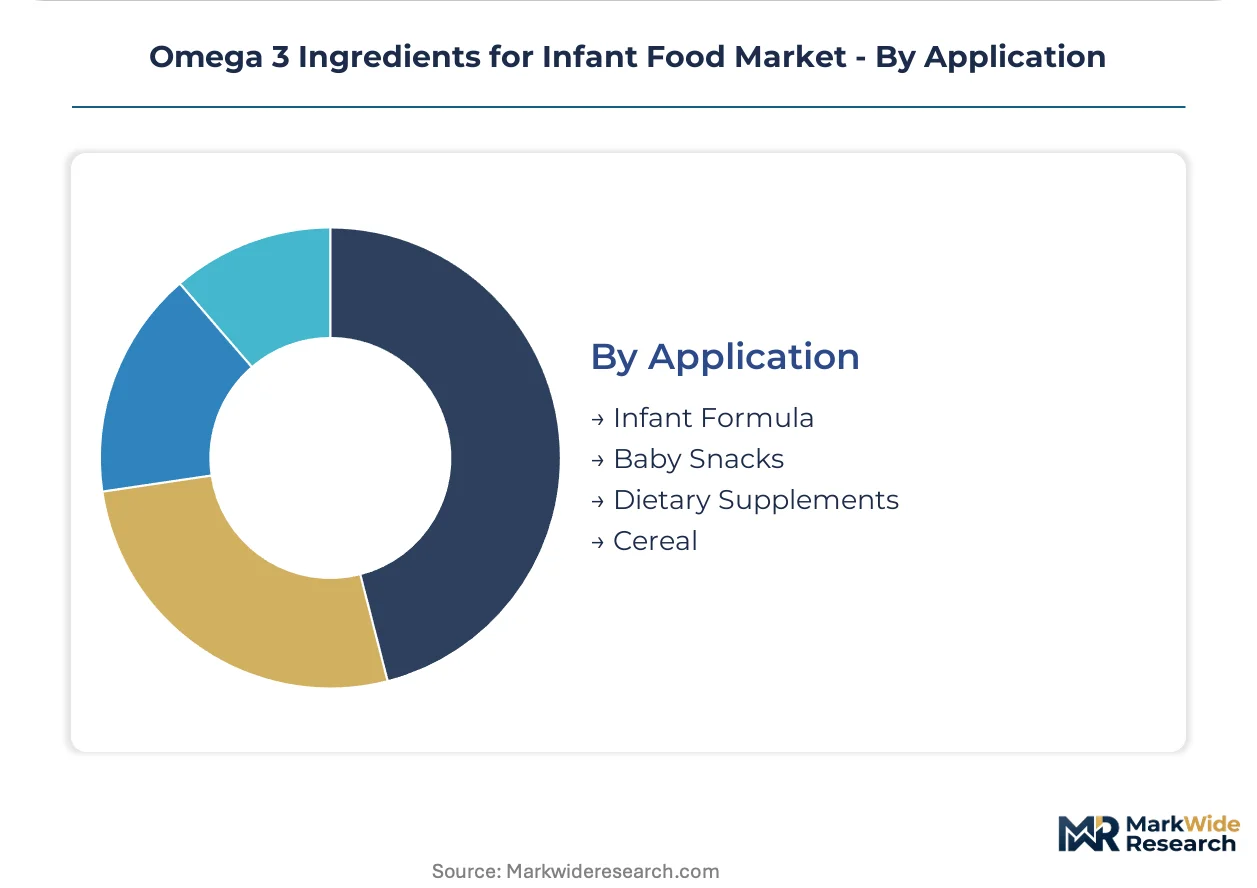
- Infant Formula:Stage 1 products require DHA fortification at specified thresholds under China's GB 10765, FDA infant formula regulations, and EU food standards. Multi-jurisdiction compliance burden concentrates supplier selection among vertically integrated multinationals with redundant toxicology dossiers.
- Baby Snacks:Puffed cereals and teething biscuits incorporate microencapsulated omega-3 for functional positioning.
- Dietary Supplements:Standalone DHA drops target breastfeeding mothers and toddlers outside formula-fed populations.
- Cereal:Fortified grain-based products for infants 6+ months represent secondary fortification channel with lower purity requirements.
Infant formula dominates volume concentration; baby snacks expand most quickly as category innovation accelerates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Algal DHA fermentation facilities in the Netherlands export EPA-free concentrates to infant formula blenders in Shanghai and Beijing, creating a specialized trade corridor that bypasses traditional marine oil supply chains.
China
Urban middle-class parents in Shanghai, Beijing, and Shenzhen prioritize certified algal DHA sourcing for first-stage formulas regardless of cost premiums. The National Health Commission's GB 10765 standards mandate specific DHA fortification thresholds, creating fixed procurement volumes for compliant suppliers. Domestic brands now contract directly with DSM and BASF fermentation facilities, collapsing traditional import agent margins.
United States
FDA GRAS notification pathways establish baseline market access for DHA sources, with the agency tightening limits on 3-MCPD ester and glycidyl ester contaminants. North American blenders favor ready-to-feed liquid formats requiring microencapsulated algal DHA with extended shelf stability. California-based organic infant formula manufacturers lead procurement shifts toward EPA-free fermentation-derived lipids.
Germany
EFSA's novel food approval pathway and updated contaminant guidance impose sub-ppm maximum residue thresholds on infant formula lipids. Bavarian and North Rhine-Westphalian blending facilities prioritize Marine Stewardship Council-certified krill oil despite Antarctic quota compression. Horizon Europe bioeconomy funding subsidizes domestic fermentation facility expansion for sustainable lipid production.
India
FSSAI's pending DHA fortification guidelines for Stage 1 infant formula products open procurement opportunities across a 1.2 billion population base. Maharashtra and Gujarat-based dairy cooperatives explore algal oil integration for value-added formula lines. Domestic regulators align toxicology dossier requirements with FDA and EFSA precedents to accelerate multinational supplier entry.
Netherlands
Rotterdam and Eindhoven fermentation clusters supply pharmaceutical-grade DHA to European blenders through controlled photobioreactor platforms. EU organic certification mandates drive solvent-free extraction investments at algal oil refineries. Dutch facilities leverage backward integration into Schizochytrium strain development to reduce wild-catch supply variability.
Omega 3 Ingredients for Infant Food Market Competitive Landscape
Listed leaders compete with private specialists across fermentation technology and marine certification vectors. The supplier base concentrates among vertically integrated multinationals with redundant toxicology dossiers for multi-jurisdiction compliance. Three archetypes dominate: fermentation platform operators, Antarctic fishery certificate holders, and backward-integrated strain developers. Capacity expansion and direct-to-brand procurement partnerships constitute the dominant competitive moves as distributors face disintermediation.
Within the fermentation platform tier, Koninklijke DSM and BASF exemplify controlled production capabilities that deliver batch-level traceability for clean-label procurement mandates. Aker BioMarine occupies a distinct position anchored to Marine Stewardship Council chain-of-custody protocols for Antarctic krill sourcing. These three entities represent the convergence of pharmaceutical-grade purity standards with geographic diversification across European, North American, and Asia-Pacific supply nodes.
| Leading Market Players |
|---|
| Aker BioMarine |
| BASF |
| Koninklijke DSM |
| Cargill Incorporated |
| Croda International |
| EPAX |
| Martek Biosciences |
| Ocean Nutrition Canada |
| Clover Corporation |
| Others |
Pricing and Supply Chain Analysis
Long-term offtake contracts between DSM and Chinese infant formula manufacturers lock in multi-year supply access while establishing price visibility through fixed-volume, indexed-pricing structures that buffer against algal fermentation feedstock volatility. These arrangements concentrate procurement power among vertically integrated multinationals with redundant toxicology dossiers for FDA, EFSA, and NHC compliance.
Pricing Analysis
Fermentation-generation algal DHA commands a 40-60% premium over refined anchovy oil concentrates, with pricing stratifying across organic certification tiers, pharmaceutical-grade purity thresholds, and EPA-free positioning. Price differentiation centers on batch-level traceability systems and blockchain verification demanded by Shanghai and Beijing parents. Cost compression in conventional fish oil tiers is intensifying because EFSA's tightened 3-MCPD ester limits force legacy refiners into costly molecular distillation upgrades. Cost-sensitive Latin American and Southeast Asian blenders exhibit highest price sensitivity, while China's urban middle-class shows least elasticity for certified organic sourcing.
Supply Chain Analysis
Port congestion at Rotterdam and container availability constraints on Asia-Europe trade lanes elevate inbound logistics costs for Dutch fermentation facilities exporting to Chinese blenders. Supply concentrates in the Netherlands, China, and Germany, with Rotterdam and Eindhoven photobioreactor clusters feeding Shanghai and Beijing formula manufacturers. Raw material dependencies include Schizochytrium carbohydrate feedstocks, Antarctic krill harvest quotas, and molecular distillation catalysts. Single-source vulnerability from Commission for the Conservation of Antarctic Marine Living Resources quota compression threatens krill oil availability. Distribution runs through direct manufacturer-to-brand contracts that disintermediate traditional import agents.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market sits at a platform-economics inflection where fermentation-derived DHA interoperability with blockchain traceability systems is reshaping supplier-buyer relationships toward direct contracting ecosystems.
For Market Incumbents: Consolidate fermentation capacity expansion with backward integration into Schizochytrium strain development to defend against algal oil substitution pressure from emerging biotech entrants. Prioritize redundant toxicology dossier maintenance across FDA GRAS, EFSA novel food, and NHC GB 10765 pathways as the regulatory compliance lever. Lock in direct procurement partnerships with Chinese domestic brands before distributor relationships fully collapse. For New Entrants and Emerging Players: Anchor in India's pending FSSAI DHA fortification guidelines as the most penetrable geography, where Maharashtra and Gujarat dairy cooperatives seek value-added formula partnerships. Target ready-to-feed liquid format emulsion stability as the underserved application segment. Pursue microencapsulation technology licensing as the go-to-market angle to bypass 18-24 month EFSA strain safety evaluation timelines. For Investors and Strategic Acquirers: Capital is best deployed toward vertically integrated fermentation platform operators with existing multi-jurisdiction regulatory dossiers rather than single-source marine oil refiners facing asset stranding. Long-term viability favors pharmaceutical-grade purity capabilities and direct-to-brand channel control. Monitor EFSA-EFSA regulatory harmonization progress as the inflection signal for stranded inventory risk among non-compliant suppliers.| Strategic Initiative | Industry Significance |
|---|---|
| Fermentation Capacity Expansion | Photobioreactor scale-up at Rotterdam facilities secures EPA-free DHA supply for Chinese GB 10765 compliance. |
| Backward Integration into Strain Development | In-house Schizochytrium cultivation reduces carbohydrate feedstock cost exposure and wild-catch variability. |
| Blockchain Traceability Implementation | QR-code verification systems satisfy Shanghai and Beijing parental demands for batch-level transparency. |
| Direct-to-Brand Procurement Partnerships | Bypassing import agents captures margin compression from distributor disintermediation in China. |
| Multi-Jurisdiction Regulatory Dossier Investment | Simultaneous FDA GRAS, EFSA novel food, and NHC compliance prevents market exclusion from approval delays. |
Research Methodology
Cross-validation between primary interviews with infant formula procurement directors, fermentation facility operations managers, and regulatory affairs specialists and secondary validation through FDA GRAS notifications, EFSA novel food approvals, and Chinese customs trade data anchors the qualitative findings. Bottom-up triangulation from ingredient supplier capacity disclosures and top-down reconciliation with National Health Commission GB standard implementation timelines ensure consistency. Conversations with Marine Stewardship Council certification auditors and Antarctic fishery quota administrators supplement supply-side validation.
Sensitivity analysis across algal fermentation yield assumptions, krill harvest quota scenarios, and Chinese birth rate projections informs the analytical framework over the projection horizon. Segmentation dimensions modeled include ingredient type, form factor, certification tier, application category, and regional regulatory cluster. CAGRs derive from regression against infant formula volume forecasts and DHA fortification penetration curves. Industry-specific inputs include EFSA 3-MCPD ester limit compliance costs and photobioreactor capex depreciation schedules.
Underlying assumptions cover sustained Chinese middle-class demand for certified organic sourcing, stable carbohydrate feedstock pricing, and EFSA-FDA regulatory convergence, with deviation risk concentrated in Antarctic fishery quota compression and novel food approval timeline extensions. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Baby Food and Infant Formula
North America Baby Food and Infant Formula Market
Baby Food and Infant Formula
Middle-Aged and Elderly Milk Powder Market
Baby Food and Infant Formula
Hypo Anti Allergic Baby Food Market
Baby Food and Infant Formula
Pureed Food Market
Baby Food and Infant Formula
Vietnam Pet Food Market
Baby Food and Infant Formula
A2 Infant Formula Market
Baby Food and Infant Formula
Organic Infant Formula Market
Baby Food and Infant Formula
Follow on Formula Milk Market
Baby Food and Infant Formula
Canned Pet Food Market
Baby Food and Infant Formula
Baby Formula Market
Baby Food and Infant Formula
India Baby Food Market
Baby Food and Infant Formula
Fortified Pet Food Market
Baby Food and Infant Formula
North America Organic Baby Food Market
Baby Food and Infant Formula
Infant Nutrition Market
Baby Food and Infant Formula
Anti-Spit Up Formula Market
Baby Food and Infant Formula
Growing Up Milk Market