
 Machine Tool Oils Market | 2026-2036
Machine Tool Oils Market Size, Share, and Industry Trends Forecast 2026-2036
Machine Tool Oils Market Foresight
Aerospace manufacturing is decoupling from general metal fabrication as the dominant demand vertical for premium machine tool oils. ExxonMobil Corporation leverages its synthetic formulation portfolio to anchor long-term supply contracts with tier-one aerospace suppliers. Fuchs SE differentiates through specialized grinding oils for turbine blade finishing, while Kluber Lubrication competes on high-temperature stability in titanium machining applications.
Machine tool oils are formulated lubricants designed to reduce friction, dissipate heat, and evacuate chips during metal cutting and grinding operations, typically containing base oils plus sulfurized, chlorinated, or phosphorus-based extreme-pressure additives. Their primary purpose is extending tool life and maintaining dimensional accuracy in precision machining. Synthetic technology commands the fastest expansion as manufacturers abandon conventional mineral formulations under pressure from tighter discharge regulations. CNC Machining generates the largest volume consumption, though Gear Cutting applications yield higher per-liter margins due to specialized additive requirements.
The EPA governs waste oil discharge and recycling protocols in the United States, while REACH restricts certain chlorinated paraffins and heavy-metal additives across Europe, forcing reformulation investments. Japan's METI promotes JIS-standard biodegradable alternatives through industrial efficiency programs. Stakeholders must monitor evolving chemical restrictions and decide whether to absorb compliance costs or accelerate bio-based technology transitions before regulatory deadlines tighten further.
Market Dynamics
Synthetic formulation mandates across industrial clusters are compressing mineral oil demand while forcing capital reallocation toward bio-based and re-refined base stock capacity.
Growth Catalysts
- Aerospace Precision Machining:Turbine blade finishing and titanium alloy cutting operations in Germany and the United States demand sulfurized synthetic formulations with extreme-pressure stability.
- REACH Phase-Out Deadlines:ECHA restrictions on short-chain chlorinated paraffins accelerate reformulation investments toward phosphorus-based extreme-pressure additives.
- Japan's METI Efficiency Programs:JIS-standard biodegradable lubricant adoption receives tax incentives and technical subsidies through designated machinery upgrade schemes.
Market Restraints
- Base Oil Supply Concentration:Group III and Group IV synthetic base stock production clusters in South Korea and Qatar create input vulnerability for European blenders.
- Additive Cost Volatility:Molybdenum disulfide and sulfurized olefin prices fluctuate with mining output and petrochemical feedstock spreads.
- Water-Based Minimum Quantity Lubrication:MQL systems in Swiss and German precision engineering reduce per-machine fluid consumption by 90% versus flood cooling.
Strategic Opportunities
- India's PLI Scheme for Machine Tools:Domestic manufacturing incentives expand precision component production in Pune and Bengaluru industrial corridors.
- Re-Refined Base Oil Integration:Circular feedstock partnerships with automotive waste oil collectors create cost-advantaged synthetic formulations for mid-tier CNC operators.
- EU Green Deal Public Procurement:Bio-based lubricant mandates in government-funded infrastructure projects create preferential tender access.
Industry Challenges
- Formulation Chemist Scarcity:Expertise in sulfur-phosphorus additive synergy and tribological testing protocols concentrates among retiring specialists in Solingen and Detroit.
- Dual Certification Timelines:Concurrent ISO 6743 and OEM factory fill approvals for new synthetic grades extend commercialization cycles by 18-24 months.
- Legacy System Compatibility:Bio-based ester formulations degrade seals and coatings in machine tools commissioned before 2010, requiring retrofit consultation services.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Machine Tool Oils Market |
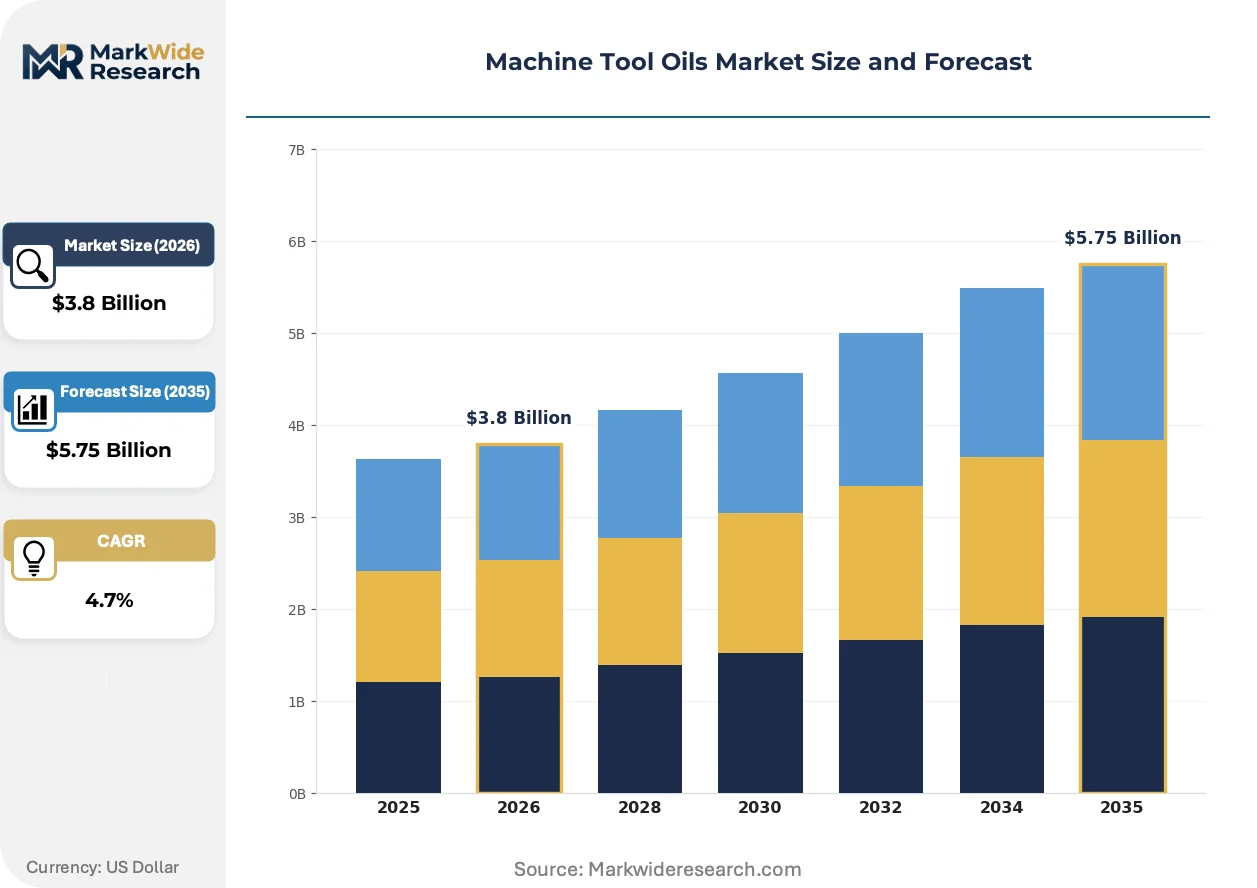
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $5.75 Billion |
| CAGR (2026 – 2036) | 4.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Cutting Oil, Grinding Oil, Rust Preventive, General Purpose Oil Application: CNC Machining, Manual Machining, Gear Cutting, Metal Forming Technology: Conventional, Synthetic, Semi-Synthetic, Bio-Based End User: Aerospace, Automotive, Metal Fabrication, Electronics |
| Companies Covered | ExxonMobil Corporation, Shell plc, Chevron Corporation, BP plc, Fuchs SE, TotalEnergies SE, Phillips 66, Kluber Lubrication, Quaker Houghton, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Machine Tool Oils Market Shifts & Advancements
Formulation science is pivoting from performance maximization toward regulatory pre-emption and circular material flows. Three developments dominate competitive positioning.
Ionic liquid lubricants are electrifying high-speed machining applications through non-volatile, thermally stable molecular structures that eliminate mist generation. Japanese and German automotive suppliers pilot these fluids in aluminum powertrain component machining. The technology is electrifying the premium synthetic segment by compressing tool-change intervals and enabling unmanned night shifts.
REACH authorization requirements for boron and formaldehyde-releasing biocides force biocide-free formulation architectures. European metalworking fluid blenders accelerate enzyme-based tank-side preservation systems. Small-batch precision engineering shops in Stuttgart and Milan face the steepest compliance cost absorption.
Fluid management as a service is displacing bulk purchase contracts among mid-sized job shops. Independent distributors in the United States Midwest bundle sensor-based concentration monitoring with scheduled top-off logistics. The model concentrates most rapidly among automotive tier-two suppliers in Ohio and Michigan seeking to outsource chemical handling liability.
Machine Tool Oils Market Segmentation
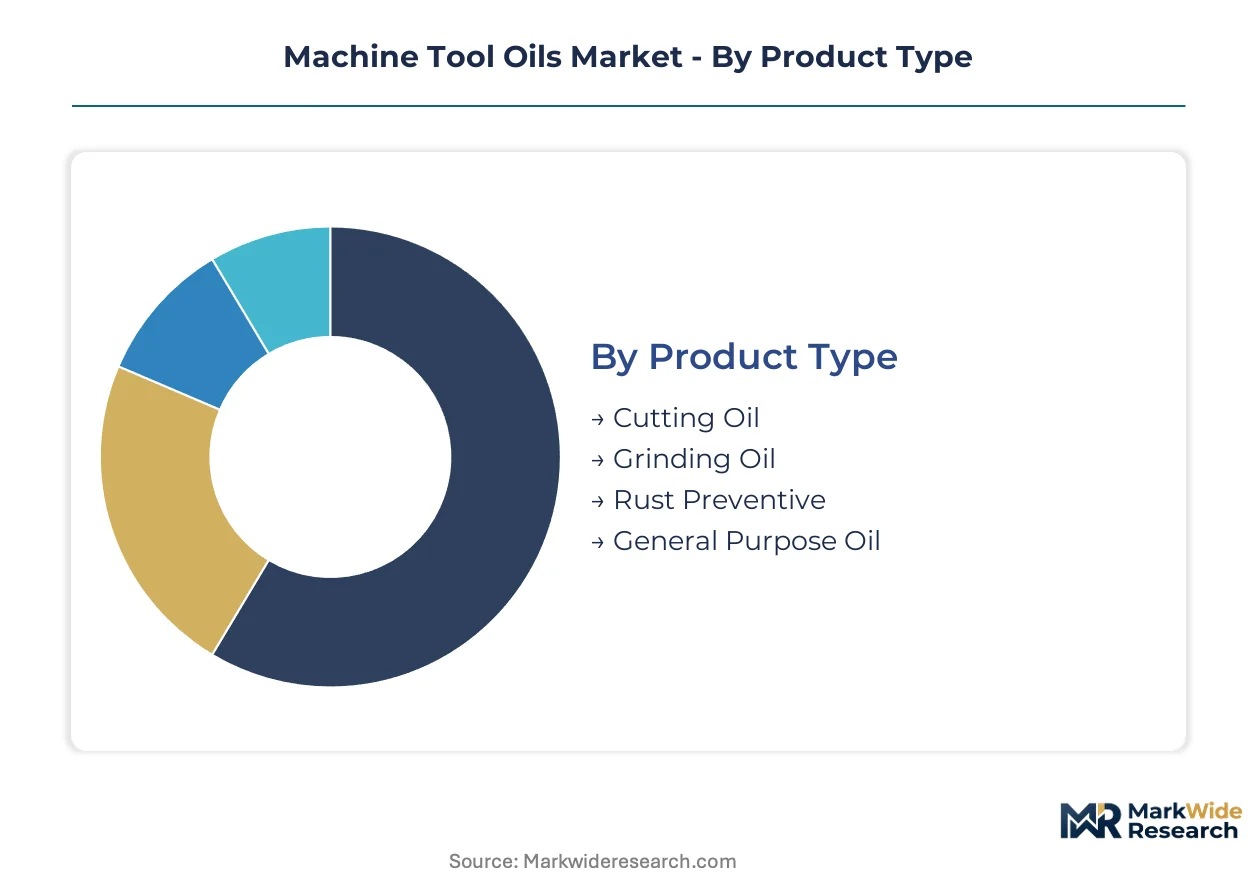
Machine tool oil purchasing decisions cascade through four interdependent dimensions. Product chemistry determines regulatory compliance pathways, while application severity dictates additive loading and service intervals. Technology selection locks customers into base stock supply chains, and end-user industry concentration shapes regional distribution footprints.
Product Type:
Standalone fluids dominate high-volume metal removal operations, while embedded rust preventives integrate into multi-stage finishing systems.
- Cutting Oil:Formulations carry sulfurized or chlorinated extreme-pressure additives to manage tool-chip interface temperatures during heavy-duty turning and milling. Aerospace turbine blade machining in Germany and the United States consumes premium synthetic grades with tight viscosity control for unmanned CNC operations.
- Grinding Oil:Low-viscosity base stocks with enhanced mist suppression properties enable precision surface finishing without thermal damage to workpieces. Fuchs SE anchors market position through specialized turbine blade finishing formulations serving Stuttgart-area precision engineering clusters.
- Rust Preventive:Thin-film corrosion inhibitors protect machined components during inter-process storage and shipping.
- General Purpose Oil:Multi-functional lubricants serve mixed-machine job shops with moderate performance requirements.
Cutting oil leads volumes today; grinding oil is gaining share fastest through aerospace precision demand.
Application:
Volume concentration versus margin extraction varies sharply across automation levels and process complexity.
- CNC Machining:Automated production cells demand synthetic formulations with extended sump life and predictable viscosity stability across temperature swings. Japan's METI efficiency programs accelerate biodegradable synthetic adoption in designated machinery upgrade corridors.
- Gear Cutting:Hobbing and shaping operations require specialized sulfur-phosphorus additive packages to handle high-contact-pressure metal removal. Per-liter margins exceed CNC machining grades due to formulation complexity and smaller batch production economics.
- Manual Machining:Operator-controlled equipment tolerates broader specification ranges with shorter fluid change intervals.
- Metal Forming:Stamping and drawing lubricants prioritize boundary lubrication over cooling capacity.
CNC machining commands volume leadership; gear cutting delivers margin concentration.
Technology:
Base stock selection determines regulatory risk exposure and circular economy integration potential.
- Synthetic:Group III and Group IV base stocks deliver thermal stability and low volatility for high-speed machining without mist generation. REACH phase-out deadlines for chlorinated paraffins accelerate phosphorus-based synthetic reformulation investments across European blending facilities.
- Bio-Based:Ester and vegetable-derived formulations satisfy EU Green Deal public procurement mandates and biodegradability requirements. Seal compatibility limitations in pre-2010 machine tools constrain retrofit deployment without consultation services.
- Conventional:Mineral oil formulations face compressed demand as discharge regulations tighten.
- Semi-Synthetic:Hybrid technologies balance performance upgrade costs against mineral oil replacement economics.
Synthetic technology anchors volume today; bio-based formulations climb fastest on regulatory tailwinds.
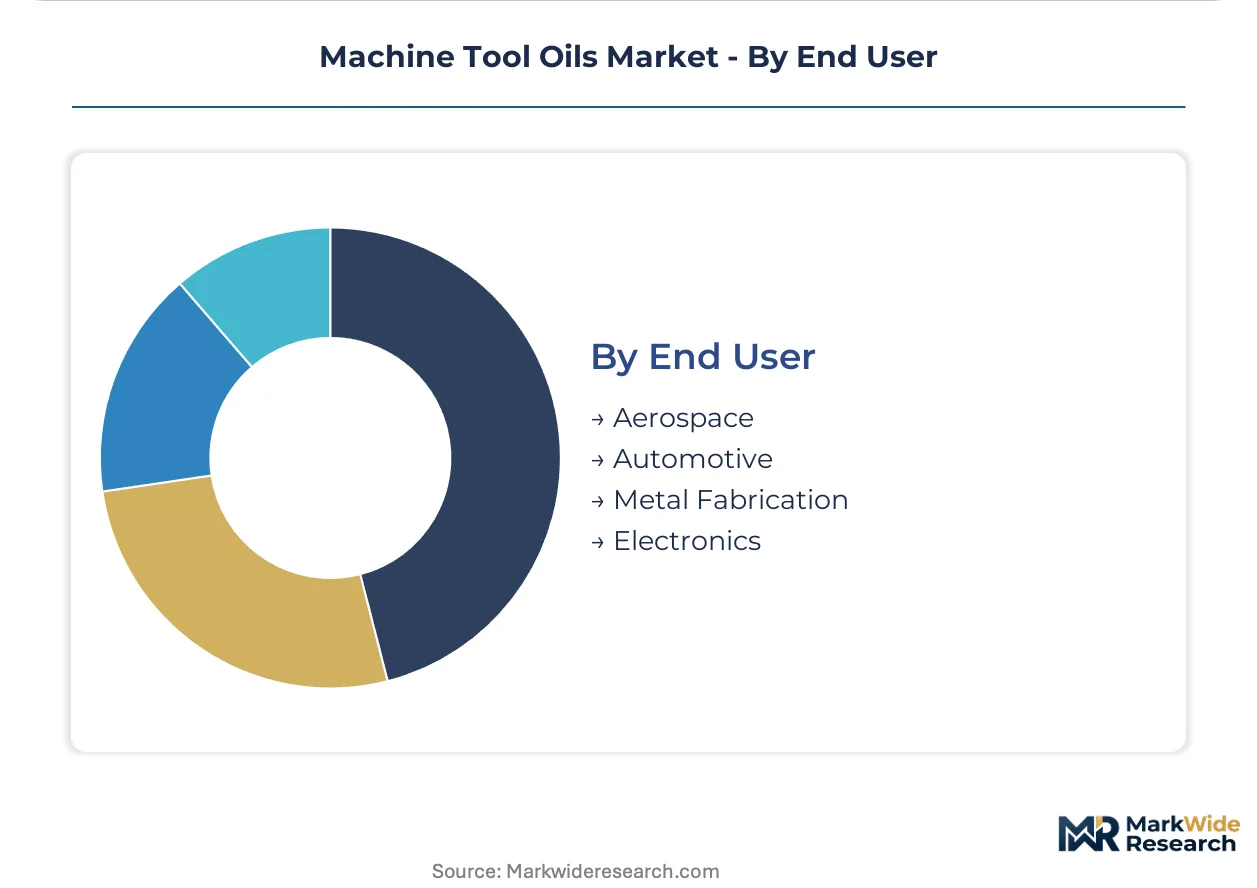
End User:
Industry-specific certification requirements and precision tolerances fragment demand specifications.
- Aerospace:Titanium alloy machining and turbine blade finishing demand sulfurized synthetic formulations with documented batch traceability. ExxonMobil Corporation secures long-term supply contracts through synthetic portfolio depth and OEM factory fill approvals.
- Automotive:Powertrain component machining favors high-volume synthetic supply with fluid management service bundling. Tier-two suppliers in Ohio and Michigan outsource chemical handling liability through sensor-based concentration monitoring contracts.
- Metal Fabrication:General structural steel processing tolerates lower-specification mineral formulations with shorter service intervals.
- Electronics:Precision component manufacturing requires ultra-clean formulations with minimal residue and controlled particulate contamination.
Aerospace leads premium segment volumes; automotive drives total consumption scale.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory-arbitrage dynamics are redirecting blending capacity toward jurisdictions with lower compliance burdens, even as end-use demand concentrates in precision engineering clusters facing the strictest discharge standards.
Germany
Aerospace turbine blade machining and titanium alloy finishing drive sulfurized synthetic consumption across Stuttgart and Munich industrial corridors. ECHA restrictions on short-chain chlorinated paraffins force reformulation investments toward phosphorus-based extreme-pressure additives. The Baden-Württemberg precision engineering cluster absorbs premium grinding oil volumes for unmanned CNC operations.
United States
Automotive tier-two suppliers in Ohio and Michigan outsource chemical handling liability through bundled fluid management services. EPA waste oil discharge protocols govern recycling investments across Midwestern metalworking corridors. Greater Detroit anchors high-volume synthetic supply contracts with powertrain component manufacturers.
Japan
METI efficiency programs accelerate JIS-standard biodegradable lubricant adoption through designated machinery upgrade schemes. Kanto and Chubu regions concentrate CNC machining demand for aluminum powertrain components. Nagoya-area automotive suppliers pilot ionic liquid formulations in unmanned night-shift operations.
China
Domestic machine tool production expansion in Yangtze River Delta clusters generates base synthetic demand for mid-tier CNC operators. National dual carbon goals pressure conventional mineral oil displacement toward Group III formulations. Shanghai-area precision component manufacturers face tightening municipal discharge standards.
India
PLI scheme incentives expand precision component production across Pune and Bengaluru industrial corridors. Central electricity authority efficiency mandates nudge adoption toward extended-sump-life synthetics. Maharashtra and Karnataka machining clusters represent the fastest-growing demand geography for reformulated cutting oils.
Machine Tool Oils Market Competitive Landscape
Portfolio diversification dominates the current landscape as incumbents reallocate mineral oil capacity toward synthetic and bio-based formulation assets. The vendor base stratifies across three tiers: integrated petrochemical majors with captive base stock supply, specialized metalworking fluid blenders with application expertise, and regional distributors bundling fluid management services. Strategic archetypes include sulfur-phosphorus formulation specialists, re-refined base oil integrators, and sensor-based monitoring service providers. M&A activity concentrates on bio-based technology acquisitions, while capacity expansion clusters in South Korea and Qatar for Group III and Group IV base stock security.
Among integrated petrochemical majors, ExxonMobil Corporation and Shell plc anchor the premium synthetic segment through factory fill approvals and long-term aerospace supply relationships. Fuchs SE occupies a specialized position within the grinding oil niche, exemplifying the European precision-engineering-focused archetype. These three entities represent contrasting scale-versus-specialization positioning strategies without implying specific market share claims.
| Leading Market Players |
|---|
| ExxonMobil Corporation |
| Shell plc |
| Chevron Corporation |
| BP plc |
| Fuchs SE |
| TotalEnergies SE |
| Phillips 66 |
| Kluber Lubrication |
| Quaker Houghton |
| Others |
Supply & Pricing Matrix
Group III base oil spot prices in Singapore and Rotterdam set the floor for synthetic formulation tiers, cascading through South Korean refinery exports into European blender cost structures and ultimately compressing margin pools for mid-tier CNC machining distributors.
Pricing Analysis
Distributor margins absorb the steepest compression as fluid management service contracts displace bulk purchase arrangements across automotive tier-two suppliers. Three-tier pricing structure across premium, standard, and economy levels separates aerospace-certified sulfurized synthetics from general-purpose mineral formulations and re-refined base stock blends. Cost compression in mid-tier synthetics is intensifying because REACH reformulation investments concentrate among European blenders with limited backward integration into additive production. Job shops with legacy pre-2010 machine tools prove most price-sensitive due to seal compatibility retrofit requirements, while aerospace OEMs accept premium positioning for documented batch traceability.
Supply Chain Analysis
Re-refined base oil collection networks from automotive waste oil recyclers feed circular feedstock partnerships that lower input costs for mid-tier CNC operators without compromising JIS-standard biodegradability claims. Geographic supply concentration clusters in South Korea, Qatar, and the Netherlands for Group III and Group IV synthetic base stocks, while sulfurized olefin additive production draws from Belgian and Japanese petrochemical complexes. Single-source vulnerability runs through South Korean Group IV PAO capacity for European precision engineering demand. Distribution runs through independent Midwestern US distributors bundling sensor-based concentration monitoring with scheduled top-off logistics.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Machine tool oils function as a stable compounder anchored by aerospace precision machining demand that sustains premium pricing through mandatory OEM factory fill approvals and documented batch traceability requirements.
For Market Incumbents: Anticipate biocide-free formulation mandates by accelerating enzyme-based tank-side preservation system partnerships with Stuttgart-area precision engineering clusters. Defensive consolidation should prioritize synthetic base stock supply security through long-term offtake agreements with South Korean Group IV producers, while certification investments in concurrent ISO 6743 and OEM approvals protect against 18-24 month commercialization cycle delays from emerging phosphorus-based additive specialists.
For New Entrants and Emerging Players: EU Green Deal public procurement mandates in Germany open a window for bio-based ester formulations targeting government-funded infrastructure projects with preferential tender access. White-space targets include re-refined base oil integration partnerships with automotive waste oil collectors serving mid-tier CNC operators in Ohio and Michigan, plus ionic liquid lubricant pilots for unmanned night-shift aluminum powertrain machining in Japan. Go-to-market positioning should emphasize fluid management as a service bundling to outsource chemical handling liability.
For Investors and Strategic Acquirers: Asymmetric upside sits with specialized grinding oil formulators possessing turbine blade finishing expertise and established relationships with Stuttgart-area precision engineering clusters. Long-term viability favors acquisition targets with demonstrated sulfur-phosphorus additive synergy capabilities and existing OEM factory fill approvals, given formulation chemist scarcity among retiring specialists. Monitor ECHA authorization timelines for boron and formaldehyde-releasing biocides as inflection indicators for enzyme-based preservation system adoption rates.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Group IV Base Stocks | Captive PAO supply from South Korean or Qatari production clusters secures formulation cost stability for European blenders facing REACH deadlines. |
| Biocide-Free Formulation Architecture | Enzyme-based tank-side preservation systems satisfy ECHA restrictions while opening premium positioning in Stuttgart precision engineering corridors. |
| Fluid Management as a Service | Sensor-based concentration monitoring contracts with Ohio and Michigan automotive tier-two suppliers outsource chemical handling liability. |
| Re-Refined Base Oil Integration | Circular feedstock partnerships with automotive waste oil collectors create cost-advantaged synthetics for price-sensitive mid-tier CNC operators. |
| Ionic Liquid Lubricant Pilot Programs | Non-volatile molecular structures enable unmanned night-shift operations for Nagoya-area aluminum powertrain component suppliers. |
Research Methodology
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with plant engineers at Stuttgart and Munich precision engineering clusters, procurement leads at aerospace tier-one suppliers, fluid management service distributors in the US Midwest, and technical R&D directors at European blending facilities. Secondary validation drew from customs and trade data on base oil flows, SEC filings of integrated petrochemical majors, ECHA substance restriction notifications, and METI industrial efficiency program disclosures. Bottom-up demand modeling across CNC machining, gear cutting, and grinding applications triangulated against top-down synthetic base stock production capacity assessments.
Segment-weighting distributed value estimates across product chemistry tiers, application severity levels, technology base stock categories, and end-user industry concentrations. The analytical framework applied growth coefficients derived from aerospace production forecasts, automotive powertrain machining volumes, and regulatory phase-out timelines across the projection horizon. Modeled inputs included REACH authorization status for chlorinated paraffins, JIS-standard biodegradable lubricant adoption curves under METI incentive programs, and MQL system penetration rates in Swiss and German precision engineering.
Forecast precision tightens around the base case; tail outcomes carry wider variance under sudden ECHA restrictions on phosphorus-based additives or accelerated South Korean export license limitations for Group IV base stocks. Practitioners should monitor ionic liquid formulation pilot results from Nagoya-area automotive suppliers and EU Green Deal public procurement award patterns for early signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Industrial Chemicals
Activated Carbon for Sugar Decolorization Market
Industrial Chemicals
Global Low GWP Refrigerants Market
Industrial Chemicals
Europe Surface Treatment Chemicals Market
Industrial Chemicals
Drag Reducing Agents Market
Industrial Chemicals
Global Metalworking Fluids Market
Industrial Chemicals
Industrial Closures Market
Industrial Chemicals
Soil Hardening Agent Market
Industrial Chemicals
Global Antifreeze/Coolant Market
Industrial Chemicals
Soap Noodles Market
Industrial Chemicals
Global Plating on Plastics Market
Industrial Chemicals
Calciner Market
Industrial Chemicals
Chemical Reactors Market
Industrial Chemicals
Continuous Reactors Market
Industrial Chemicals
Bio Derived Enzymes for Detergents Market
Industrial Chemicals
Methyl Isobutyl Carbinol Market
Industrial Chemicals
Propylene Oxide Market