
 Czech Republic Freight and Logistics Market | 2026-2036
Czech Republic Freight and Logistics Market Size, Share, and Industry Trends Forecast 2026-2036
Czech Republic Freight and Logistics Market Outlook
Software-defined freight brokerage is consolidating how Czech shippers procure transport capacity, replacing traditional spot-market phone calls with algorithmic load-matching platforms. DSV A/S anchors its Central European hub in Prague with integrated warehousing and customs brokerage. Raben Group specializes in contract logistics for temperature-sensitive automotive components across the Plzeň region. Geis Group leverages its Moravian distribution network to compete on last-mile density in Brno and Ostrava.
Czech Republic freight and logistics encompasses the physical movement, storage, and information management of goods across road, rail, air, and sea modes, typically operating within EU-standardized dimensions and weight limits while coordinating multimodal handoffs through the Port of Hamburg and Adriatic corridors. Road Freight dominates tonnage moved but faces margin compression from EU Mobility Package compliance costs, while E-commerce end users are driving fastest growth in Last Mile delivery infrastructure. Rail Transport occupies a structural niche for bulk commodities and automotive parts between the Polish border and German networks, though terminal capacity constraints limit expansion.
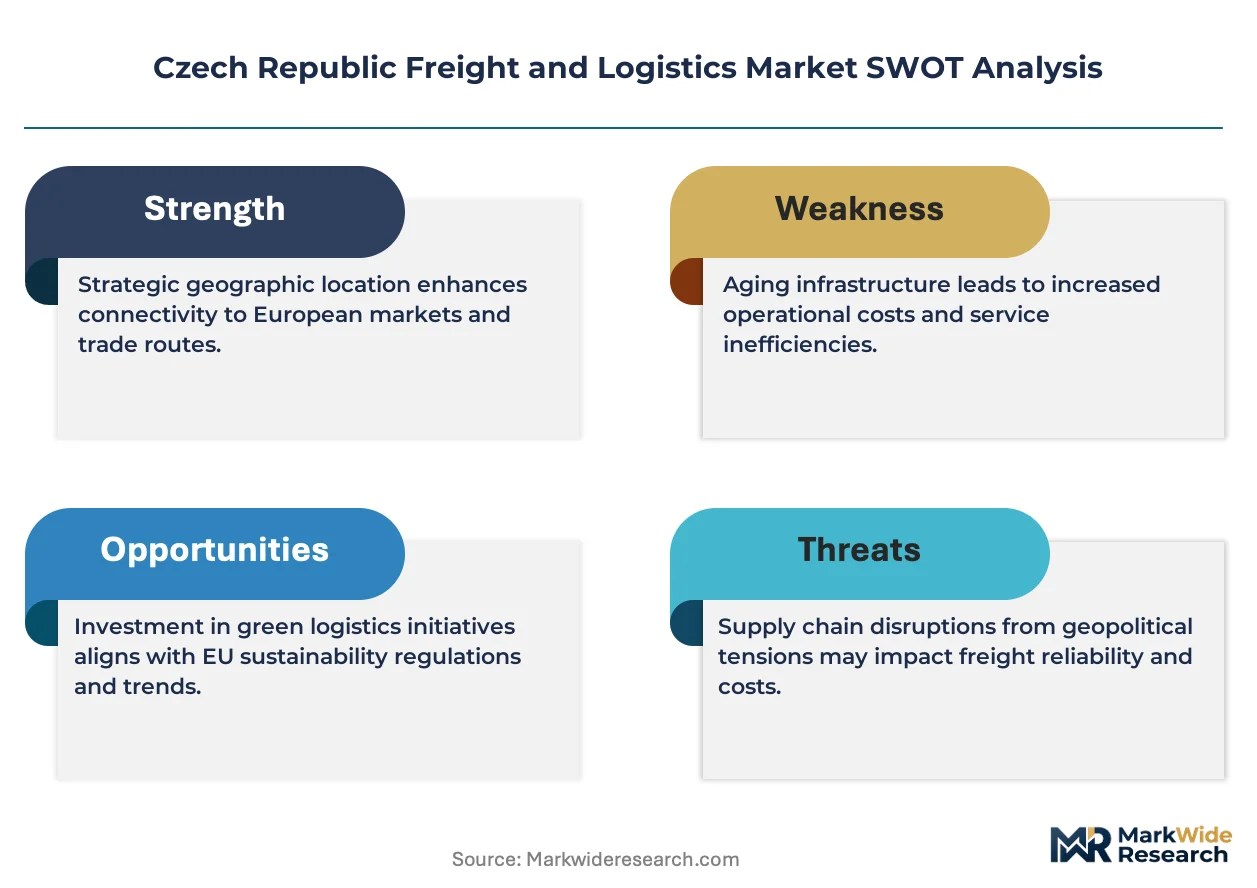
The Czech Ministry of Transport enforces EU Mobility Package cabotage restrictions and driver rest-period rules that reshape fleet utilization models for international operators. BIS certification requirements for telematics hardware and the EU Green Deal emissions benchmarks push carriers toward alternative-fuel vehicle procurement. Stakeholders must monitor how the planned Děčín-Prague-Břeclav rail corridor upgrades and evolving EU carbon-border adjustment mechanisms alter modal competitiveness before committing to long-term asset positions.
Market Dynamics
EU Mobility Package cabotage restrictions and driver rest-period mandates are compressing fleet utilization rates for cross-border road operators while simultaneously accelerating software-defined freight brokerage adoption across Czech shipper networks.
Growth Catalysts
- Just-in-Time Delivery Mandates:Automotive manufacturers along the Ostrava and Mladá Boleslav corridors are tightening delivery windows for inbound components, forcing logistics providers to upgrade real-time tracking and predictive scheduling capabilities.
- EU Green Deal Emissions Benchmarks:Alternative-fuel vehicle procurement incentives are pulling fleet operators toward electric and hydrogen-powered trucks for last-mile routes serving Prague's logistics ring.
- Warehousing Capacity Tightness:The Brno-Győr-Vienna triangle is experiencing acute industrial real estate scarcity, driving premium pricing for temperature-controlled facilities serving pharmaceutical and automotive clients.
Market Restraints
- Driver Availability Compression:EU Mobility Package rest-period regulations and cabotage restrictions are shrinking effective driving hours per international route, raising per-kilometer labor costs.
- Rail Terminal Bottlenecks:Limited intermodal terminal capacity at Czech-Polish border crossings constrains modal shift away from road freight for bulk automotive components.
- Telematics Certification Burden:BIS hardware certification requirements for onboard monitoring devices impose compliance timelines that delay fleet modernization programs.
Strategic Opportunities
- Cross-Border Digital Freight Matching:Algorithmic load-matching platforms are penetrating spot-market procurement in Moravia, displacing traditional phone-based broker relationships.
- Děčín-Prague-Břeclav Rail Upgrades:Planned corridor modernization will expand container terminal throughput, enabling new multimodal services for exporters targeting Adriatic ports.
- Last-Mile Electrification:E-commerce fulfillment density in Brno and Ostrava is creating viable deployment zones for electric van fleets operating under urban low-emission zone exemptions.
Industry Challenges
- Telematics Integration Complexity:Legacy fleet management systems require costly middleware development to interface with EU-mandated digital tachograph and remote monitoring standards.
- Multimodal Coordination Skill Gaps:Shortages of professionals capable of optimizing rail-road handoffs through Hamburg and Adriatic corridors limit operational efficiency gains.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Czech Republic Freight and Logistics Market |
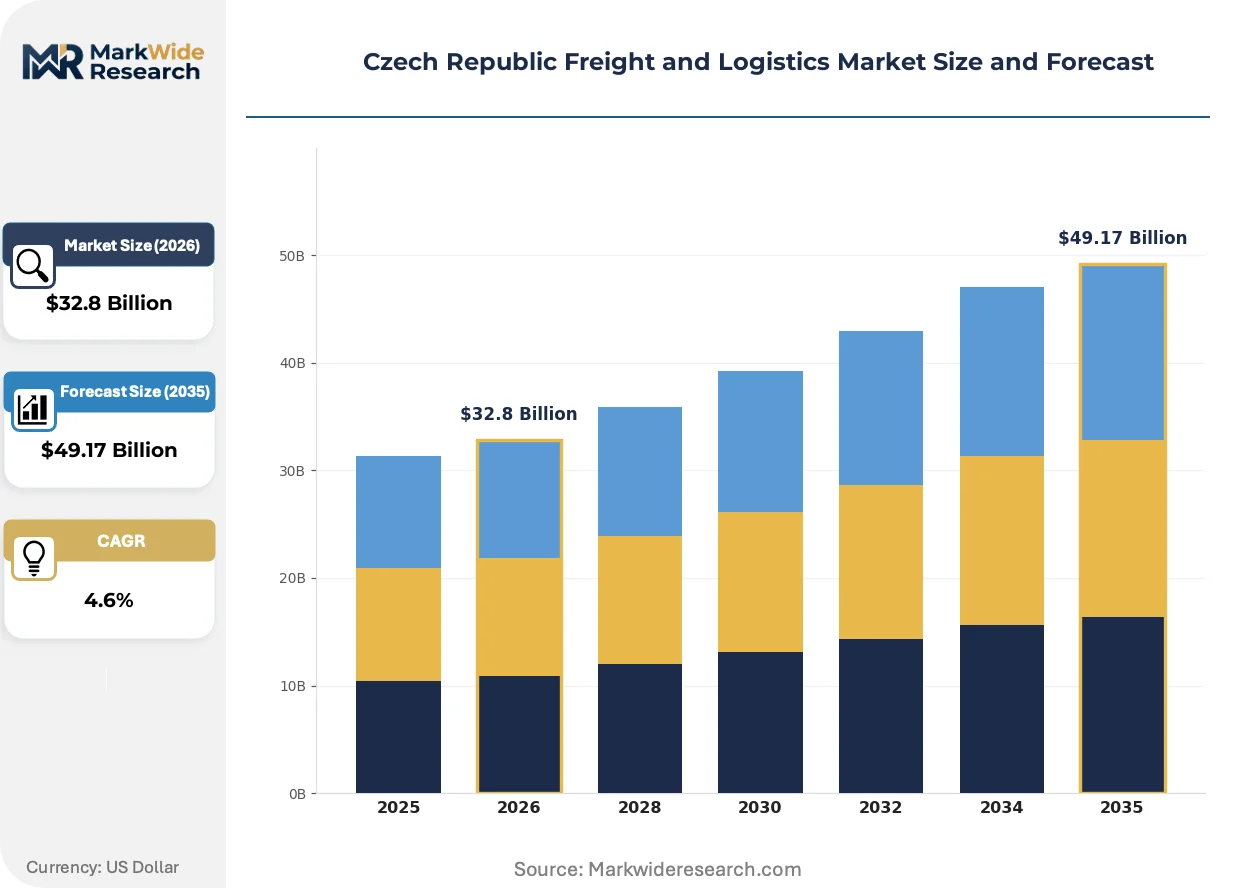
| Market Size in 2026 | $32.8 Billion |
| Market Size in 2035 | $49.17 Billion |
| CAGR (2026 – 2036) | 4.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Road Freight, Air Cargo, Sea Freight, Rail Transport End User: Manufacturers, Retailers, E-commerce, Wholesalers Delivery Model: Direct Delivery, Cross-docking, Last Mile, Consolidation Technology: Telematics, TMS, AI Optimization, RFID Tracking |
| Companies Covered | CMA CGM Group, Kuehne + Nagel, DSV A/S, XPO Logistics, DHL Supply Chain, Raben Group, AGROFERT AS, DB Schenker, Geis Group, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Czech Republic Freight and Logistics Market Strategic Shifts
Software-defined automation is penetrating freight procurement and warehouse operations simultaneously, compressing traditional intermediary roles while generating new data-rich service layers.
Algorithmic freight-matching platforms are consolidating how Czech shippers procure transport capacity. Mid-sized manufacturers in Plzeň and Liberec are adopting API-connected brokerage tools within eighteen-month procurement cycles. This technology is consolidating spot-market liquidity onto centralized platforms, reducing phone-based broker margins while expanding carrier access to fragmented demand.
EU Mobility Package cabotage restrictions are reshaping fleet deployment patterns across Central European road networks. International operators now face compressed utilization windows for cross-border routes, forcing asset repositioning strategies that prioritize domestic Czech loops. Small and mid-sized carriers serving German export corridors are responding by consolidating onto fewer, higher-frequency lanes.
Shippers are unbundling transportation from warehousing contracts in favor of modular, event-priced service tiers. Automotive suppliers in Mladá Boleslav are disaggregating long-term logistics agreements into separate freight, storage, and value-added service components. This pattern is most visible among Tier 1 component manufacturers facing volatile production schedules from German OEMs.
Czech Republic Freight and Logistics Market Segmentation
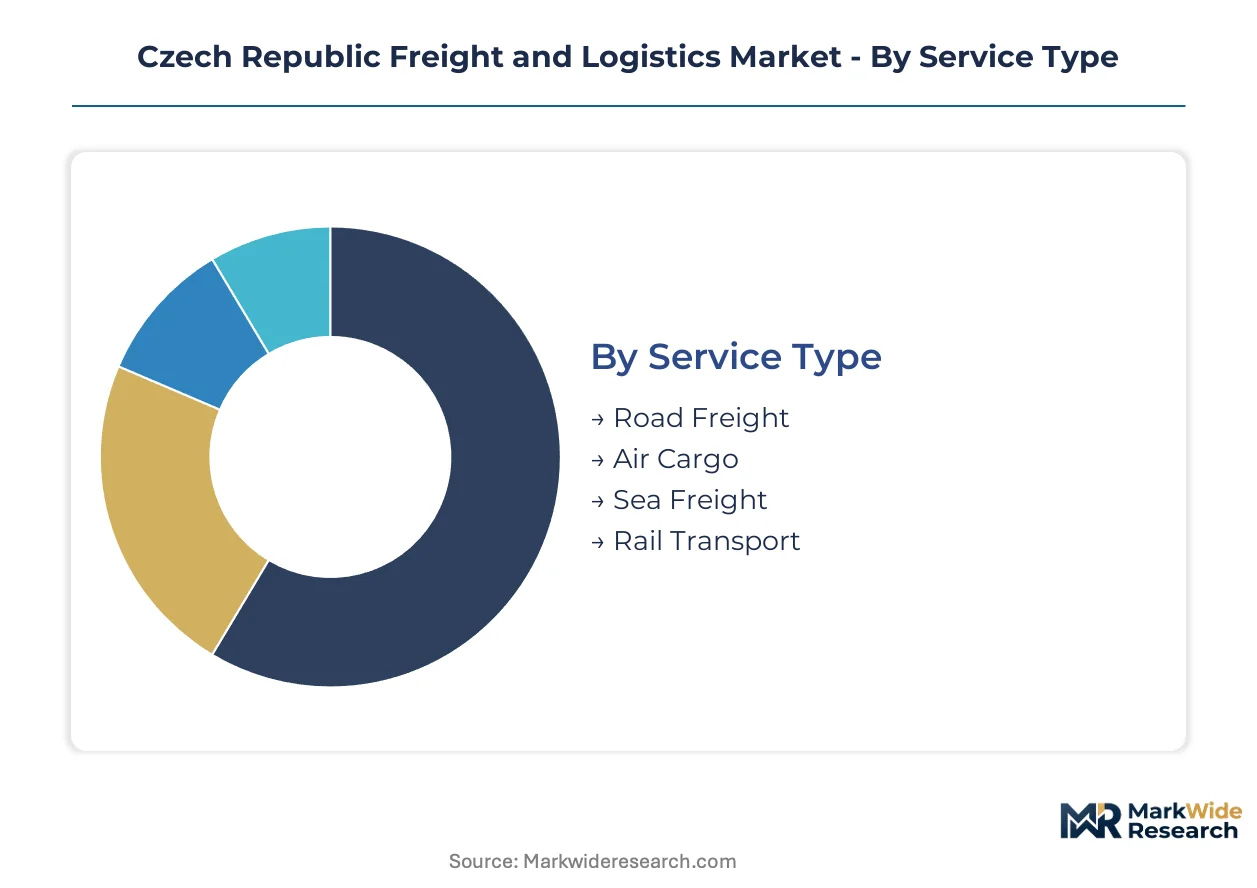
Segmentation in the Czech freight and logistics market reveals how modal specialization, end-use concentration, and technology adoption create distinct competitive arenas. Service type splits expose the tension between road dominance and rail modernization, while end-user categories illuminate diverging requirements for inventory velocity versus cost efficiency.
Service Type:
Road freight commands volume leadership while rail transport captures premium positioning on bulk corridors.
- Road Freight:Heavy-duty trucking networks handle the majority of tonnage moved across Czech territory, operating under EU-standardized dimensions and weight limits. Demand concentrates in Prague's logistics ring and the Brno-Győr-Vienna triangle, where just-in-time automotive supply chains compress delivery windows and elevate real-time tracking requirements.
- Rail Transport:Bulk commodity movement and automotive parts transit between Polish border terminals and German networks, occupying a structural niche for high-volume, lower-velocity cargo. Terminal capacity constraints at Czech-Polish crossings limit modal shift acceleration despite corridor upgrade plans.
- Air Cargo:Time-critical shipments and high-value electronics move through Prague Václav Havel Airport, serving pharmaceutical and precision manufacturing clients with temperature-controlled handling protocols.
- Sea Freight:Containerized goods access Adriatic and North Sea ports via multimodal handoffs, with Hamburg and Koper serving as primary maritime gateways for Czech exporters.
Mature deployment sits with Road Freight. Newer deployment is concentrated in Rail Transport as Děčín-Prague-Břeclav corridor upgrades advance.
End User:
Application-driven segmentation separates production-linked logistics from consumption-facing fulfillment networks.
- Manufacturers:Automotive OEMs and component suppliers in Ostrava and Mladá Boleslav corridors drive contract logistics demand with stringent just-in-time delivery mandates. EU Mobility Package compliance costs reshape procurement patterns for inbound component flows.
- E-commerce:Digital retail fulfillment generates fastest-expanding demand for last-mile infrastructure in Brno and Ostrava urban zones. Electric van fleet deployment accelerates under low-emission zone exemptions and EU Green Deal procurement incentives.
- Retailers:Brick-and-mortar distribution networks prioritize cross-docking efficiency and seasonal inventory surge capacity.
- Wholesalers:Consolidated procurement and break-bulk operations serve fragmented regional demand with cost-optimized transport modes.
Margin compression concentrates in Retailer segments. Value capture is expanding most quickly in E-commerce through technology-enabled service tiering.
Delivery Model:
Cost tier differentiation separates asset-heavy dedicated networks from flexible shared infrastructure.
- Last Mile:Urban delivery density in Prague, Brno, and Ostrava creates viable electrification zones for van fleets serving e-commerce and pharmaceutical clients. Algorithmic route optimization and dynamic pricing platforms reshape carrier economics.
- Cross-docking:High-velocity freight transfer without long-term storage meets automotive and retail demands for inventory minimization. Moravian distribution networks compete on throughput speed and modal handoff precision.
- Direct Delivery:Point-to-point dedicated transport serves high-value manufacturing inputs with minimal handling.
- Consolidation:Multi-shipment aggregation reduces per-unit transport costs for mid-sized manufacturers in Plzeň and Liberec regions.
Established infrastructure dominates Direct Delivery. Capability investment is flowing fastest into Last Mile as urban emission regulations tighten.
Technology:
Maturity gradients separate regulatory-mandated baseline systems from competitive-differentiation platforms.
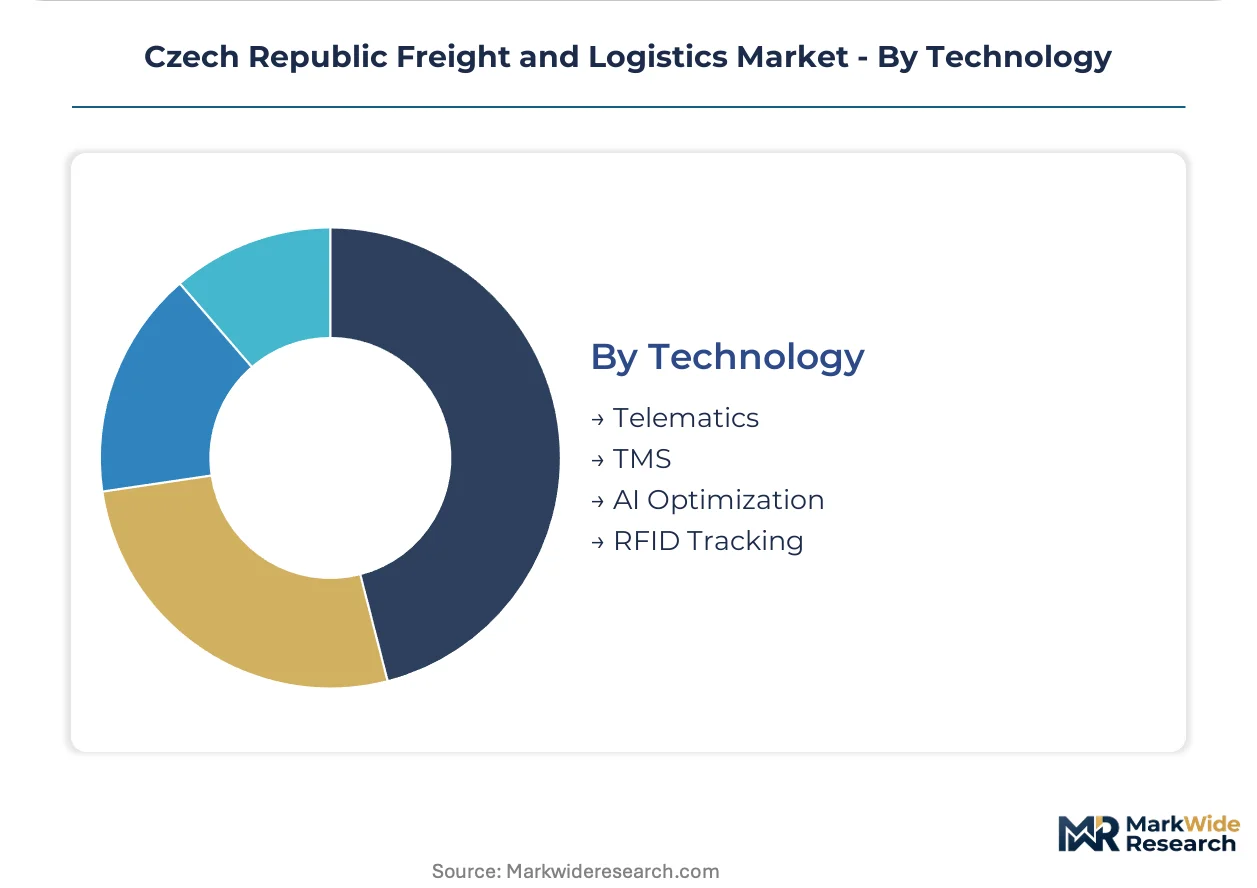
- Telematics:Onboard monitoring hardware with BIS certification requirements tracks vehicle location, driver behavior, and fuel consumption across fleet operations. EU-mandated digital tachograph integration imposes compliance timelines that delay modernization for smaller carriers.
- TMS:Transport management systems coordinate multimodal execution and carrier selection, with API-connected platforms displacing phone-based brokerage in Moravian spot markets.
- AI Optimization:Predictive scheduling and dynamic load-matching algorithms penetrate shipper procurement cycles in eighteen-month adoption windows.
- RFID Tracking:Automated inventory visibility solutions deploy in temperature-controlled automotive and pharmaceutical warehousing.
Regulatory compliance anchors Telematics deployment. Steepest expansion trajectory belongs to AI Optimization as algorithmic freight-matching consolidates procurement liquidity.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Czech logistics infrastructure serves as a consumption hub for German manufacturing exports while generating production-linked demand from automotive corridors. The Ostrava and Mladá Boleslav industrial zones anchor inbound component flows. Prague's logistics ring concentrates warehousing capacity for Central European distribution.
Prague and Central Bohemia
E-commerce fulfillment and pharmaceutical distribution drive warehousing demand in Prague's logistics ring. EU Green Deal emissions benchmarks accelerate electric van fleet procurement for last-mile routes. DSV A/S operates an integrated hub with customs brokerage serving cross-border automotive supply chains.
Moravia and Brno
Just-in-time automotive delivery mandates from German OEMs compress transit windows through the Brno-Győr-Vienna triangle. Geis Group leverages its Moravian distribution network for last-mile density. Rail terminal capacity constraints at Czech-Polish crossings limit modal shift for bulk components.
Ostrava and Silesia
Steel and heavy manufacturing clusters generate project cargo demand for specialized transport equipment. EU Mobility Package cabotage restrictions reshape fleet utilization for cross-border Polish and Slovak routes. Raben Group manages temperature-controlled automotive components across the corridor.
Plzeň and Western Bohemia
Mid-sized manufacturers adopt API-connected freight brokerage tools within eighteen-month procurement cycles. BIS certification requirements for telematics hardware delay fleet modernization for regional carriers. The region serves as a multimodal gateway to German networks through the D5 corridor.
Liberec and Northern Bohemia
Textile and electronics exporters generate consolidated shipment demand for cost-optimized transport. Algorithmic load-matching platforms penetrate spot-market procurement, displacing traditional phone-based broker relationships. The Děčín-Prague-Břeclav rail corridor upgrades will expand container terminal throughput for Adriatic port access.
Czech Republic Freight and Logistics Market Competitive Environment
Asset-heavy integrated logistics providers compete with asset-light freight brokerage platforms for shipper procurement relationships. The market structures around three tiers: global network operators with captive warehousing, regional specialists with modal expertise, and digital-native platforms with algorithmic matching capabilities. Consolidation pressures favor scale players with cross-border customs capabilities. Competitive dynamics center on technology integration speed and multimodal coordination precision.
Among global network operators, DSV A/S anchors Central European operations through its Prague hub with integrated warehousing and customs brokerage. Raben Group occupies a position within the regional specialist tier, focusing on contract logistics for temperature-sensitive automotive components. Geis Group exemplifies the density-driven competitor, leveraging its Moravian distribution network for last-mile competitiveness in Brno and Ostrava.
| Leading Market Players |
|---|
| CMA CGM Group |
| Kuehne + Nagel |
| DSV A/S |
| XPO Logistics |
| DHL Supply Chain |
| Raben Group |
| AGROFERT AS |
| DB Schenker |
| Geis Group |
| Others |
Value Chain & Pricing Dynamics
Driver wage inflation under EU Mobility Package rest-period mandates propagates through contract logistics tiers, compressing margins for cross-border operators while elevating spot-market premiums for domestic Czech loops serving automotive corridors.
Pricing Analysis
Margin tightening in contract logistics reflects EU Mobility Package compliance costs and driver availability compression. Three-tier pricing structure across premium just-in-time, standard scheduled, and economy consolidated tiers separates automotive OEM contracts from retail distribution. Price differentiation hinges on real-time tracking certification and cross-border customs capability. Small carriers exhibit highest price sensitivity; integrated operators with captive warehousing capture pricing power.
Supply Chain Analysis
Diesel and hydrogen fuel supply rests on German refinery networks and emerging Czech electrolyzer projects. Automotive components draw from German Tier 1 suppliers, Polish steel processors, and Slovak electronics manufacturers. Single-source vulnerability concentrates in specialized telematics hardware certified to BIS standards. Distribution runs through Prague's logistics ring for Central European fulfillment, with Adriatic corridor handoffs serving export-oriented manufacturers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Freight operators face a vertical-integration race toward captive warehousing and algorithmic brokerage platforms, with control over Prague's logistics ring and Moravian distribution density serving as the decisive downstream lever.
For Market Incumbents: Acquire temperature-controlled warehousing capacity in the Brno-Győr-Vienna triangle to defend against digital-native freight platforms. Consolidate spot-market liquidity through API-connected brokerage tools before algorithmic competitors capture Moravian shipper relationships. Prioritize EU Green Deal compliance certification to access premium automotive contracts.
For New Entrants and Emerging Players: Launch via electric van fleet services targeting last-mile density in Ostrava and Brno urban zones under low-emission zone exemptions. Penetrate mid-sized manufacturers in Plzeň and Liberec with modular event-priced service tiers unbundled from long-term contracts. Compete on dynamic pricing transparency rather than asset-heavy infrastructure.
For Investors and Strategic Acquirers: Distressed-cycle entries favor regional specialists with modal expertise in Czech-Polish cross-border corridors. Long-term viability hinges on multimodal coordination capabilities and rail terminal access through Děčín-Prague-Břeclav corridor positioning. Monitor EU carbon-border adjustment mechanism implementation as inflection signal for alternative-fuel fleet valuations.
| Strategic Initiative | Industry Significance |
|---|---|
| Warehouse Capacity Expansion | Captures premium pricing in Brno-Győr-Vienna industrial real estate scarcity. |
| Backward Integration into Telematics | Bypasses BIS certification delays through in-house hardware development. |
| Algorithmic Freight Platform Launch | Displaces phone-based brokerage margins in Moravian spot markets. |
| Electric Fleet Procurement | Secures EU Green Deal incentives and urban low-emission zone access. |
| Rail Corridor Joint Venture | Expands container terminal throughput for Adriatic port connectivity. |
Study Parameters
Independent corroboration across fleet operations managers, automotive procurement directors, customs brokerage specialists, and EU regulatory affairs leads underwrites the qualitative findings. Secondary validation draws from EU Mobility Package legislative texts, Czech Ministry of Transport enforcement guidelines, BIS certification databases, and customs trade flow records. Bottom-up carrier capacity assessments and top-down macroeconomic indicators triangulate market sizing.
Rate-of-change decomposition across service type, end user, delivery model, and technology adoption segments structures the analytical framework. Mode share evolution, warehousing utilization rates, and driver hour productivity metrics inform growth trajectory modeling throughout the forecast period. CAGRs derive from segment-level demand elasticity and capacity expansion schedules.
The model assumes a particular technology adoption path; alternative pathways for hydrogen fuel cell deployment would alter the outlook. Forecasts reflect assumptions around EU Green Deal implementation timing and Děčín-Prague-Břeclav corridor upgrade completion. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Logistics and Shipping
New Zealand Freight and Logistics Market
Logistics and Shipping
Secure Logistics Market
Logistics and Shipping
Japan Domestic Courier, Express, and Parcel (CEP) Market
Logistics and Shipping
Indonesia Courier, Express, and Parcel (CEP) Market
Logistics and Shipping
California Freight and Logistics Market
Logistics and Shipping
Chile Freight and Logistics Market
Logistics and Shipping
Remanufacturing and Core Returns Logistics Management Market
Logistics and Shipping
US Mexico Cross Border FTL Freight Transport Market
Logistics and Shipping
Intralogistics Containers Market
Logistics and Shipping
Turkey Cold Chain Logistics Market
Logistics and Shipping
Germany Freight and Logistics Market
Logistics and Shipping
Thailand E-Commerce Logistics Market
Logistics and Shipping
United States Freight Brokerage Market
Logistics and Shipping
Brazil Freight and Logistics Market
Logistics and Shipping
Japan Freight and Logistics Market
Logistics and Shipping
Russia 3PL Market