
 US Dangerous-Hazardous Goods Logistics Market | 2026-2036
US Dangerous-Hazardous Goods Logistics Market Size, Share, and Industry Trends Forecast 2026-2036
US Dangerous-Hazardous Goods Logistics Market Insights
The capability gap between asset-heavy tanker fleets and digital brokerage models is bifurcating competitive returns in US dangerous-hazardous goods logistics. DSV leverages its European pharma-cold chain expertise to win FDA-regulated pharmaceutical contracts. Kenan Advantage Group anchors bulk chemical road transport through its dedicated tanker infrastructure. Schneider Logistics differentiates via proprietary driver training academies certified under DOT hazardous materials endorsement programs.
US dangerous-hazardous goods logistics encompasses the specialized movement of substances classified under 49 CFR as posing risks of explosion, flammability, toxicity, or corrosivity during transit, requiring placarded vehicles, segregated storage, and emergency response protocols. The sector serves chemical manufacturers, energy producers, and pharmaceutical firms whose supply chains cannot function without compliant transport infrastructure. Flammable liquids dominate product type volume due to petroleum derivatives and ethanol blending demand, while toxic substances generate premium pricing from pharmaceutical and agricultural chemical shippers. Road transport leads delivery mode utilization for last-mile flexibility to chemical plants, though rail transport sustains bulk chlorine and anhydrous ammonia flows to agricultural heartland states.
DOT regulations administered through PHMSA mandate carrier registration, security planning, and incident reporting that shape market entry costs and operational compliance burdens. OSHA workplace safety standards intersect with EPA spill prevention rules to create layered liability frameworks for handlers and transporters. IATA regulations govern air freight of lithium batteries and radioactive diagnostic materials, restricting eligible carriers to certified cargo operators. Stakeholders must monitor PHMSA's pending rulemakings on electronic hazardous materials documentation and emerging battery chemistry classifications that will reshape carrier certification requirements and facility investment priorities.
Market Dynamics
EPA enforcement actions against hazmat documentation violations have intensified carrier liability exposure, pushing chemical shippers toward outsourced logistics partnerships with certified compliance infrastructure. PHMSA's pending electronic hazmat documentation mandate compounds this structural pressure.
Growth Catalysts
- Petrochemical corridor expansion:Texas and Louisiana refinery complexes require specialized tanker fleets for flammable liquid throughput. Midstream operators lack captive logistics capacity.
- 49 CFR placarding automation:Digital hazmat classification systems reduce driver detention time at loading facilities. Shippers adopt integrated ERP-to-DOT compliance platforms.
- Pharmaceutical cold chain extension:FDA-regulated biologics transport demands temperature-validated hazmat handling. Cell and gene therapy distribution networks expand beyond traditional pharma hubs.
Market Restraints
- Specialized driver scarcity:DOT hazardous materials endorsement holders represent under 15 percent of commercial license holders. Training pipelines cannot match carrier fleet expansion targets.
- Tank trailer manufacturing concentration:Three domestic fabricators control stainless steel tanker production. Lead times extend 14-18 months for corrosion-resistant chemical transport units.
- Insurance capacity constraints:Hazmat liability underwriters restrict coverage for carriers with incident histories above PHMSA reporting thresholds. Premiums scale non-linearly with fleet size.
Strategic Opportunities
- Appalachian shale chemical feedstock growth:Ohio and Pennsylvania ethane cracker projects generate new origin points for flammable liquid distribution. Regional carriers lack certified infrastructure.
- Lithium battery ground transport specialization:Electric vehicle manufacturing clusters in Michigan and Tennessee require UN 38.3 compliant last-mile logistics. Air freight restrictions push volume to road.
- Intermodal tank container adoption:ISO tank units enable rail-to-road hazmat transfers without transloading. Chemical shippers reduce handling risk and customs documentation duplication.
Industry Challenges
- Emergency response certification gaps:CHEMTREC registration and spill containment training requirements vary by state. Carriers operating across jurisdictions face fragmented compliance obligations.
- Legacy TMS integration failures:Older transportation management systems cannot ingest real-time hazmat position data from ELD-mandated devices. Carriers maintain parallel paper documentation workflows.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | US Dangerous-Hazardous Goods Logistics Market |
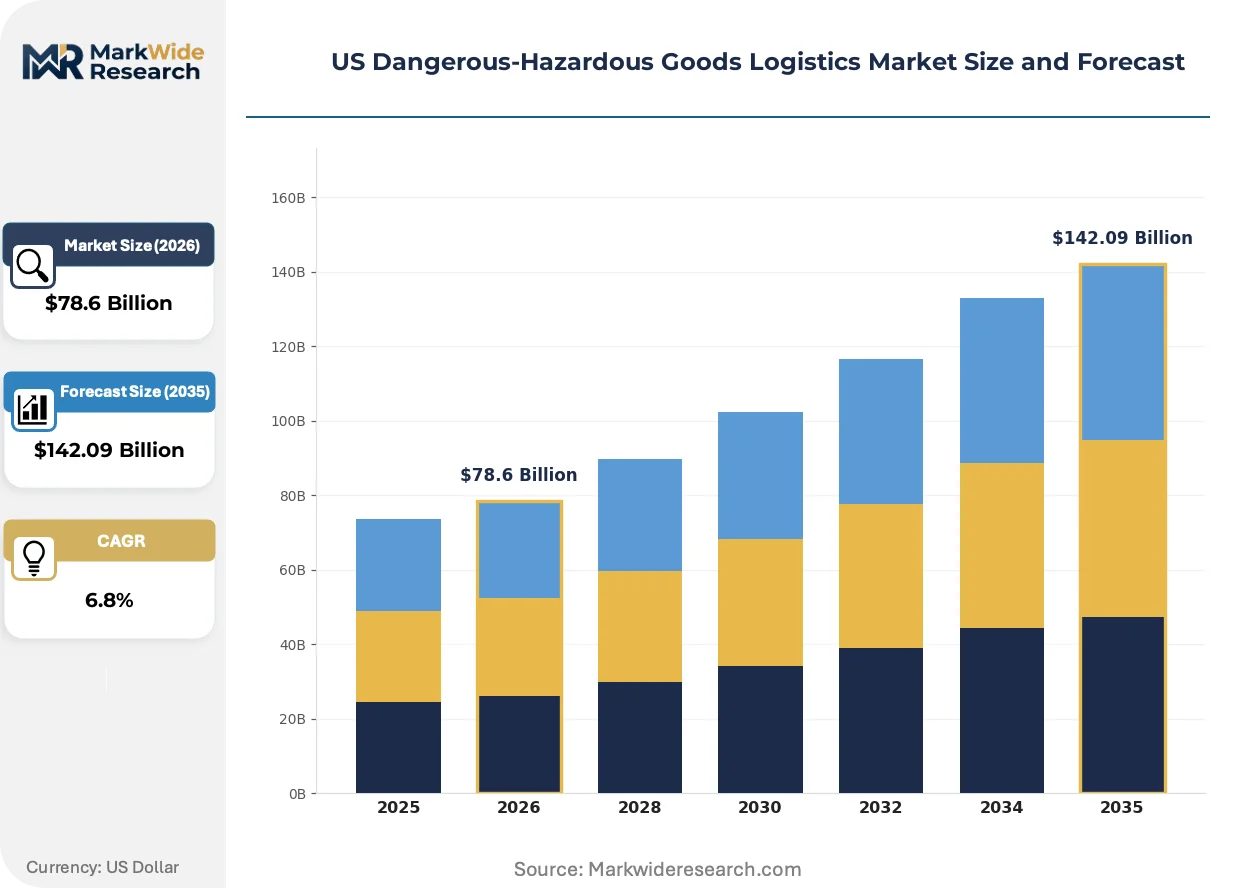
| Market Size in 2026 | $78.6 Billion |
| Market Size in 2035 | $142.09 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Explosives, Flammable Liquids, Toxic Substances, Corrosives Delivery Mode: Road Transport, Rail Transport, Air Freight, Sea Freight End User: Chemical Manufacturers, Pharmaceuticals, Agriculture, Construction Regulatory Compliance: DOT Regulations, IMDG Code, IATA Regulations, ICAO Standards |
| Companies Covered | DSV, Kenan Advantage Group, Deutsche Post DHL Group, Schneider Logistics, United Parcel Service Inc., XPO Logistics, Landstar System Inc., GEODIS, Kuehne + Nagel, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
US Dangerous-Hazardous Goods Logistics Market Trends and Innovations
Telematics and predictive analytics are compressing incident response windows while reshaping carrier-shipper contractual risk allocation. Technology investment concentrates among mid-sized fleet operators seeking differentiation from asset-light brokers.
Blockchain-anchored hazmat documentation is fragmenting carrier competitive positioning. The distributed ledger technology creates immutable chain-of-custody records for 49 CFR regulated shipments. Large chemical manufacturers pilot vendor-agnostic platforms to reduce audit preparation burden. PHMSA's electronic documentation rulemaking accelerates adoption timelines, compressing competitive advantage windows for early implementers.
EPA's updated Risk Management Plan requirements for chemical facilities are tightening transport partner vetting standards. The regulation mandates documented carrier safety performance metrics as prequalification criteria. Petrochemical shippers in Texas and Louisiana now require three-year incident-free histories for contract eligibility. Smaller carriers face exclusion from major chemical company approved vendor lists.
Shippers are consolidating carrier relationships around integrated compliance service bundles. Chemical manufacturers reduce vendor counts from fifteen-plus regional operators to three national partners with captive training academies. This procurement compression favors asset-heavy tanker fleets over digital freight brokers. The Gulf Coast petrochemical corridor exhibits the most pronounced consolidation, where integrated safety and logistics offerings displace price-based selection criteria.
US Dangerous-Hazardous Goods Logistics Market Segmentation
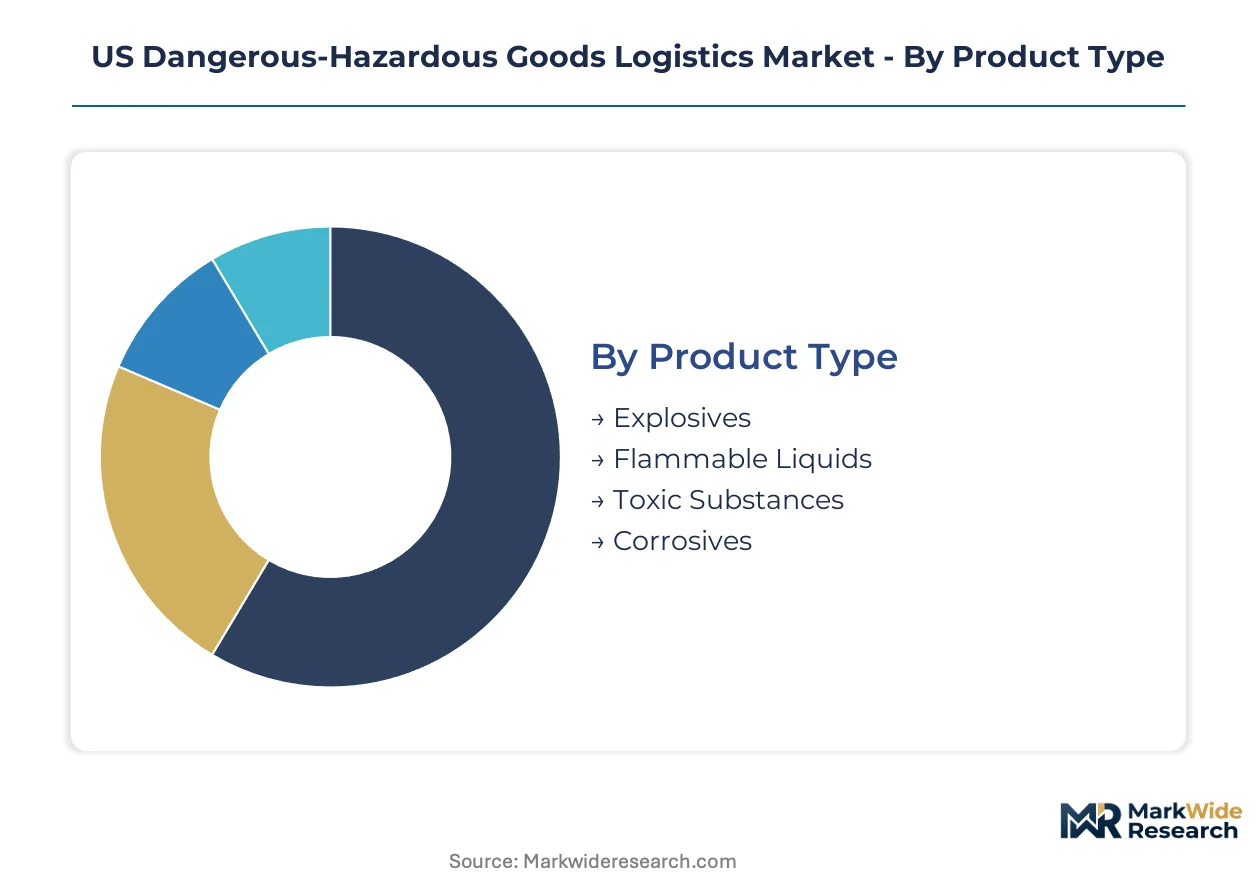
Hazmat logistics segmentation reveals how regulatory complexity and cargo physics dictate specialized infrastructure investments. Each dimension shapes carrier certification requirements, insurance structures, and customer procurement criteria.
Product Type:
Flammable liquids face the strongest substitution pressure from pipeline alternatives, while toxic substances remain irreplaceable for pharmaceutical and agricultural chemical distribution.
- Flammable Liquids:Petroleum derivatives, ethanol blends, and solvent-based chemicals require DOT-certified tanker fleets with vapor recovery systems. Demand concentrates in Texas and Louisiana petrochemical corridors where refinery output exceeds captive pipeline capacity.
- Toxic Substances:Agricultural pesticides, pharmaceutical intermediates, and industrial chemicals generate premium pricing from shippers requiring specialized containment and driver medical monitoring. Cell and gene therapy distribution networks in Massachusetts and North Carolina drive temperature-validated handling requirements.
- Explosives:Mining and demolition sectors require ATF-licensed carriers with segregated storage facilities and blast-radius routing protocols.
- Corrosives:Acid and caustic soda transport demands stainless steel or rubber-lined tankers with neutralization kit mandates.
Flammable liquids anchor the volume base while toxic substances gain share at the steepest rate.
Delivery Mode:
Cost tier stratification separates asset-heavy dedicated fleets from variable-cost brokerage arrangements across modal alternatives.
- Road Transport:Tanker trucks and van units provide last-mile flexibility to chemical plants, refineries, and pharmaceutical manufacturing sites. Ohio and Pennsylvania shale chemical projects generate new origin points where certified regional carriers remain scarce.
- Rail Transport:Bulk chlorine, anhydrous ammonia, and liquefied petroleum gas move via pressure tank cars to agricultural heartland states. Norfolk Southern and Union Pacific maintain dedicated hazmat corridors with emergency response staging points.
- Air Freight:Lithium batteries, radioactive diagnostic materials, and temperature-critical biologics face IATA restrictions limiting eligible carriers to certified cargo operators.
- Sea Freight:ISO tank containers enable intermodal transfers without transloading for international chemical trade through Houston and New Orleans port complexes.
Road transport captures the highest shipment frequency while rail transport handles the largest single-commodity tonnage flows.
End User:
Application-specific requirements create divergent procurement patterns across customer types, with pharmaceutical and agricultural sectors imposing the most stringent carrier qualification standards.
- Chemical Manufacturers:Petrochemical and specialty chemical producers require integrated compliance bundles spanning transport, documentation, and spill response. Gulf Coast facilities now mandate three-year incident-free carrier histories under EPA Risk Management Plan updates.
- Pharmaceuticals:FDA-regulated biologics and cell therapy products demand temperature-validated cold chain infrastructure with continuous monitoring. Distribution networks extend beyond traditional pharma hubs into regional hospital systems.
- Agriculture:Seasonal fertilizer and pesticide applications require flexible fleet scaling with CHEMTREC registration and state-specific applicator licensing.
- Construction:Explosives and compressed gas cylinders for demolition and welding operations need localized delivery windows with blast zone coordination.
Chemical manufacturers anchor contract value while pharmaceuticals expand most quickly through biologics distribution requirements.
Regulatory Compliance:
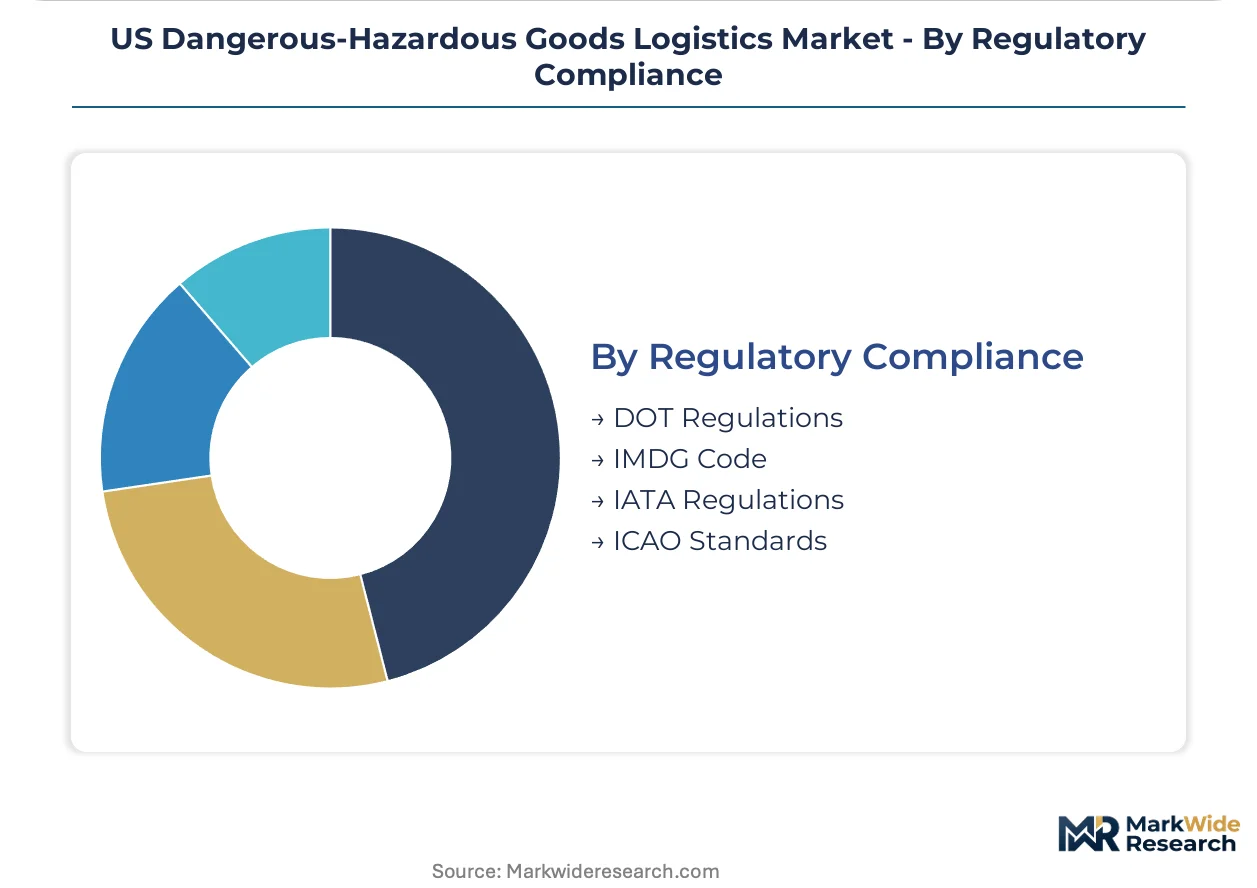
Customer type determines which regulatory frameworks dominate compliance investment, with DOT-registered carriers serving domestic shippers and multi-modal operators pursuing stacked certifications.
- DOT Regulations:PHMSA-administered 49 CFR mandates govern placarding, driver endorsement, security planning, and incident reporting for domestic road and rail movements. Pending electronic documentation rulemakings will reshape carrier technology investment priorities.
- IATA Regulations:Lithium battery classifications and radioactive material handling restrictions limit air freight eligibility to certified cargo operators with specialized loading protocols.
- IMDG Code:International Maritime Dangerous Goods standards govern ocean container stowage and segregation for chemical exports through US port facilities.
- ICAO Standards:Technical instructions for safe transport of dangerous goods by air align with IATA provisions for cross-border pharmaceutical and diagnostic material movements.
DOT regulations anchor domestic operational compliance while IATA certification commands the steepest carrier investment premiums.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pricing power concentrates in Texas and Louisiana corridors where petrochemical density outstrips certified carrier supply, while Appalachian shale regions lag in hazmat infrastructure investment. This asymmetry reshapes carrier deployment strategies across domestic chemical logistics networks.
Texas Gulf Coast
Flammable liquid throughput from Port Arthur and Baytown refineries exceeds dedicated pipeline capacity, forcing reliance on DOT-certified tanker fleets. EPA Risk Management Plan updates mandate three-year incident-free carrier histories for contract eligibility at Beaumont chemical complexes. Specialized stainless steel tanker demand concentrates along the Houston Ship Channel where ethylene crackers expand output.
Louisiana Chemical Corridor
Baton Rouge and Lake Charles petrochemical facilities generate bulk hazardous cargo flows requiring CHEMTREC-registered emergency response protocols. DOT hazardous materials endorsement scarcity constrains carrier fleet scaling despite OSHA workplace safety standard enforcement intensification. Mississippi River barge-to-truck transloading operations at St. Gabriel industrial parks demand multimodal hazmat certification.
Appalachian Shale Belt
Ohio and Pennsylvania ethane cracker projects in Belmont County and Monaca create new origin points for flammable liquid distribution. PHMSA electronic documentation rulemakings compound compliance burdens for regional carriers lacking integrated ERP platforms. Pittsburgh-based chemical manufacturers face certified carrier scarcity for temperature-validated pharmaceutical intermediates transport.
California Industrial Hubs
Bay Area biologics manufacturers and Los Angeles County aerospace chemical suppliers drive FDA-regulated cold chain hazmat demand. IATA lithium battery air freight restrictions push UN 38.3 compliant ground transport volume through Ontario and Fontana distribution corridors. CARB emissions standards intersect with DOT placarding requirements for drayage operators at Long Beach port complexes.
Midwest Manufacturing Belt
Michigan electric vehicle battery plants and Tennessee lithium-ion cell manufacturing clusters require specialized ground transport for Class 9 hazardous materials. Norfolk Southern and Union Pacific maintain dedicated hazmat rail corridors through Illinois and Indiana with emergency response staging points. Chicago intermodal terminals enable ISO tank container transfers for chemical shippers reducing handling risk.
US Dangerous-Hazardous Goods Logistics Market Competitive Landscape
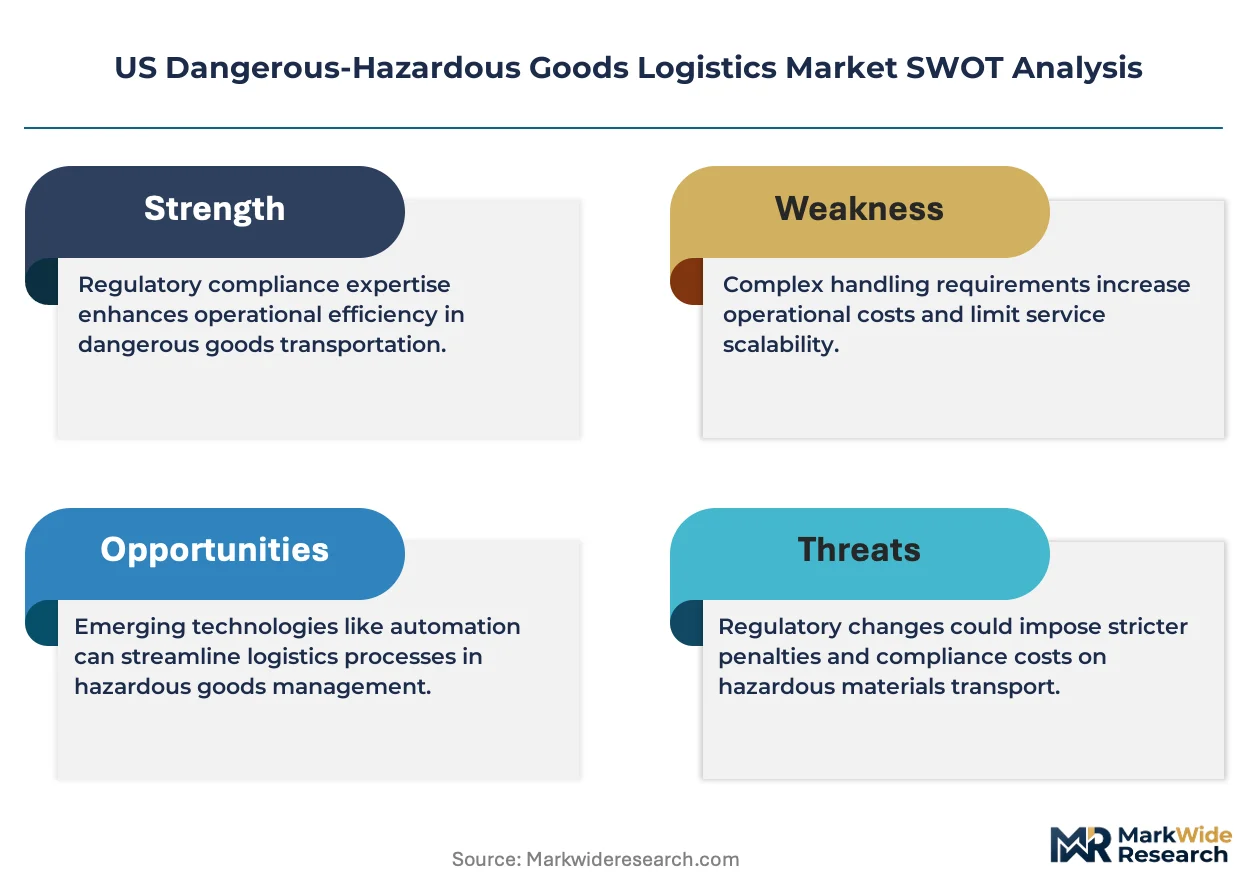
Concentration sits with asset-heavy tanker fleets holding captive driver training academies and stainless steel trailer manufacturing relationships. The market structure bifurcates between integrated compliance service providers and digital freight brokers lacking hazardous materials endorsement infrastructure. Three strategic archetypes dominate: European pharma-cold chain specialists, dedicated bulk chemical road operators, and diversified parcel carriers with hazmat certification overlays. Carrier competitive moves center on CHEMTREC registration expansion and proprietary driver academy scaling.
Within the European specialist tier, DSV leverages pharmaceutical cold chain expertise for FDA-regulated biologics contracts, while Kuehne + Nagel occupies a position in intermodal tank container orchestration. Among dedicated bulk operators, Kenan Advantage Group anchors chemical road transport through tanker fleet density, and Schneider Logistics exemplifies the training-academy differentiation model with DOT endorsement program certification. Deutsche Post DHL Group represents the diversified parcel carrier archetype applying hazmat overlays to existing ground networks.
| Leading Market Players |
|---|
| DSV |
| Kenan Advantage Group |
| Deutsche Post DHL Group |
| Schneider Logistics |
| United Parcel Service Inc. |
| XPO Logistics |
| Landstar System Inc. |
| GEODIS |
| Kuehne + Nagel |
| Others |
Pricing and Supply Chain Analysis
Tank trailer fleet utilization rates above 85 percent in Texas and Louisiana petrochemical corridors create natural price floors that smaller carriers cannot undercut. Scale economies in stainless steel tanker procurement and captive driver training academies concentrate pricing power among asset-heavy operators with CHEMTREC registration and three-year incident-free histories.
Pricing Analysis
Configured-to-order hazmat transport commands 25-40 percent premiums over standard spot-market movements due to EPA Risk Management Plan documentation requirements and dedicated equipment specifications. Three-tier pricing structure separates premium certified carriers with integrated compliance bundles from mid-tier regional operators and economy digital brokers lacking hazardous materials endorsement infrastructure. Cost compression in the broker tier intensifies as chemical manufacturers consolidate vendor relationships around integrated safety and logistics offerings. Pharmaceutical shippers exhibit the lowest price sensitivity, prioritizing FDA-validated cold chain documentation over transport cost minimization.
Supply Chain Analysis
Just-in-time chemical feedstock delivery dominates Texas and Louisiana refinery operations, while strategic stockpiling persists for seasonal agricultural pesticide movements. Stainless steel tanker fabrication concentrates in Wisconsin, Ohio, and Pennsylvania, with raw material dependencies on nickel alloy feedstocks and specialized welding consumables. Single-source vulnerability in DOT-certified driver training pipelines constrains fleet expansion timelines. Distribution runs through dedicated chemical transport corridors with Norfolk Southern and Union Pacific maintaining hazmat-specific rail infrastructure.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Compliance-as-a-service revenue layers expand faster than base transport fees as chemical shippers outsource EPA documentation and PHMSA incident reporting. Recurring safety audit subscriptions and CHEMTREC registration management now represent the fastest-growing revenue component in carrier portfolios.
For Market Incumbents: Consolidate regional carrier relationships through integrated compliance service bundles that combine transport, documentation, and spill response. Acquire distressed tank trailer assets to secure stainless steel manufacturing slots amid 14-18 month lead times. Defensive positioning against digital freight brokers requires deepening proprietary driver academy scale to maintain DOT endorsement density.
For New Entrants and Emerging Players: Differentiate on lithium battery ground transport specialization targeting Michigan and Tennessee electric vehicle manufacturing clusters with UN 38.3 compliant last-mile infrastructure. White-space opportunity concentrates in Appalachian shale chemical corridors where Ohio and Pennsylvania ethane cracker projects outstrip certified regional carrier supply. Go-to-market positioning should emphasize ISO tank container intermodal orchestration for chemical shippers reducing handling risk.
For Investors and Strategic Acquirers: Mid-cycle technology positioning favors asset-heavy operators with captive training academies over digital brokerage models lacking hazardous materials endorsement infrastructure. Long-term viability across the projection horizon rests on carriers with integrated ERP-to-DOT compliance platforms ready for PHMSA electronic documentation mandates. Acquisition target archetype: mid-sized fleets with CHEMTREC registration and stainless steel tanker manufacturing relationships. Signal to watch: EPA enforcement action intensity against hazmat documentation violations as carrier liability exposure indicator.
| Strategic Initiative | Industry Significance |
|---|---|
| Driver Academy Expansion | DOT hazardous materials endorsement scarcity constrains fleet scaling across Texas and Louisiana corridors. |
| Electronic Documentation Platform | PHMSA pending rulemakings reshape carrier certification requirements and technology investment priorities. |
| Intermodal Tank Container Adoption | ISO tank units enable rail-to-road transfers without transloading for chemical shippers. |
| Cold Chain Infrastructure Extension | FDA-regulated biologics transport demands temperature-validated handling beyond traditional pharma hubs. |
| Emergency Response Certification | CHEMTREC registration requirements vary by state, creating fragmented compliance obligations for multi-jurisdictional operators. |
Research Methodology
Findings reconcile primary fieldwork against secondary review of DOT PHMSA incident databases, EPA enforcement records, and chemical industry trade publications. Primary interviews engaged fleet operations directors, chemical shipper procurement leads, tank trailer manufacturing executives, and hazardous materials safety consultants. Secondary validation drew from 49 CFR regulatory filings, American Chemistry Council distribution reports, and SEC 10-K disclosures from listed logistics operators. Bottom-up carrier capacity modeling and top-down chemical production flow analysis provided cross-verification.
Segmentation dimensions modeled include product type classification, delivery mode infrastructure, end-use industry requirements, and regulatory compliance tier across the analysis window. CAGRs derive from historical volume trajectories in petrochemical corridor throughput and projected capacity additions in shale chemical feedstock regions. Industry-specific forecast inputs incorporate DOT hazardous materials endorsement issuance rates and stainless steel tanker manufacturing lead times.
Forecasts assume regulatory continuity in EPA Risk Management Plan enforcement and PHMSA documentation requirements; material policy shifts would require re-modeling carrier liability exposure and compliance investment burdens. Practitioners should keep alternative scenarios live as electronic hazmat documentation rulemaking timelines and lithium battery classification updates evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Logistics and Shipping
Uruguay Freight and Logistics Market
Logistics and Shipping
Asia Pacific Sea Freight Forwarding Market
Logistics and Shipping
United Arab Emirates Freight and Logistics Market
Logistics and Shipping
China Project Logistics Market
Logistics and Shipping
Germany Freight and Logistics Market
Logistics and Shipping
Turkey Third Party Logistics (3PL) Market
Logistics and Shipping
Shipping Container Modification Market
Logistics and Shipping
Nordics Freight and Logistics Market
Logistics and Shipping
On-Demand Logistics Market
Logistics and Shipping
China Shipping Agency Services Market
Logistics and Shipping
Tanker Cargo Ship Market
Logistics and Shipping
Netherlands Cold Chain Logistics Market
Logistics and Shipping
GCC Finished Vehicle Logistics Market
Logistics and Shipping
Europe Sea Freight Forwarding Market
Logistics and Shipping
Same Day Delivery Service Market
Logistics and Shipping
UAE Logistics Market