
 Canada Courier, Express, and Parcel (CEP) Market | 2026-2036
Canada Courier, Express, and Parcel (CEP) Market Size, Share, and Industry Trends Forecast 2026-2036
Canada Courier, Express, and Parcel (CEP) Market Insights
Modular service bundling is decoupling express delivery from traditional freight contracts, letting buyers mix same-day, next-day, and scheduled delivery without annual volume commitments. FedEx leverages its integrated air-ground network to sustain premium express margins across Canadian urban corridors. Purolator Inc. anchors domestic parcel density through its Canada Post partnership and dedicated B2B routing infrastructure. Intelcom Courrier Canada Inc. specializes in gig-economy last-mile fulfillment, competing on variable cost structures in dense residential zones.
Courier, express, and parcel services constitute a logistics subsystem involving time-definite collection, sortation, line-haul transport, and last-mile distribution of documents and goods, with operational parameters measured in transit-time guarantees, dimensional weight pricing, and real-time tracking granularity. The delivery mode dimension shows same-day and next-day segments capturing margin-rich e-commerce volumes while standard delivery occupies the cost-sensitive bulk parcel tier. Customer type segmentation reveals B2C and e-commerce channels outpacing traditional B2B freight in volume growth, though recurring deliveries and domestic shipping sustain the revenue base for established carriers.
Transport Canada governs commercial vehicle safety standards and driver hours-of-service rules that directly constrain fleet utilization and route economics for CEP operators. Provincial regulators in Ontario and British Columbia enforce emissions benchmarks and low-impact zone restrictions that shape vehicle procurement and depot siting decisions. Health Canada and the PMRA maintain protocols for pharmaceutical and biological shipments that create specialized handling requirements within temperature-controlled parcel segments. Stakeholders must monitor how evolving carbon pricing mechanisms and municipal curbside management policies will redistribute competitive advantage between owned-fleet operators and platform-based delivery networks.
Market Dynamics
E-commerce fulfillment windows are compressing from next-day to same-day across Ontario and British Columbia corridors, forcing parcel networks to reconfigure sortation infrastructure and driver shift patterns around four-hour delivery guarantees rather than traditional twenty-four-hour cycles.
Growth Catalysts
- Transport Canada Motor Vehicle Safety Regulations:Updated commercial vehicle standards are accelerating fleet electrification timelines, creating procurement momentum for zero-emission last-mile vehicles in urban delivery zones.
- Pharmaceutical cold-chain protocols:Health Canada and PMRA temperature-controlled shipment requirements are expanding specialized handling revenue pools within biological specimen and vaccine distribution segments.
- Ontario-Quebec warehousing density:Concentrated fulfillment center placement along Highway 401 and 20 corridors enables sub-two-hour ground transit to fourteen million consumers.
Market Restraints
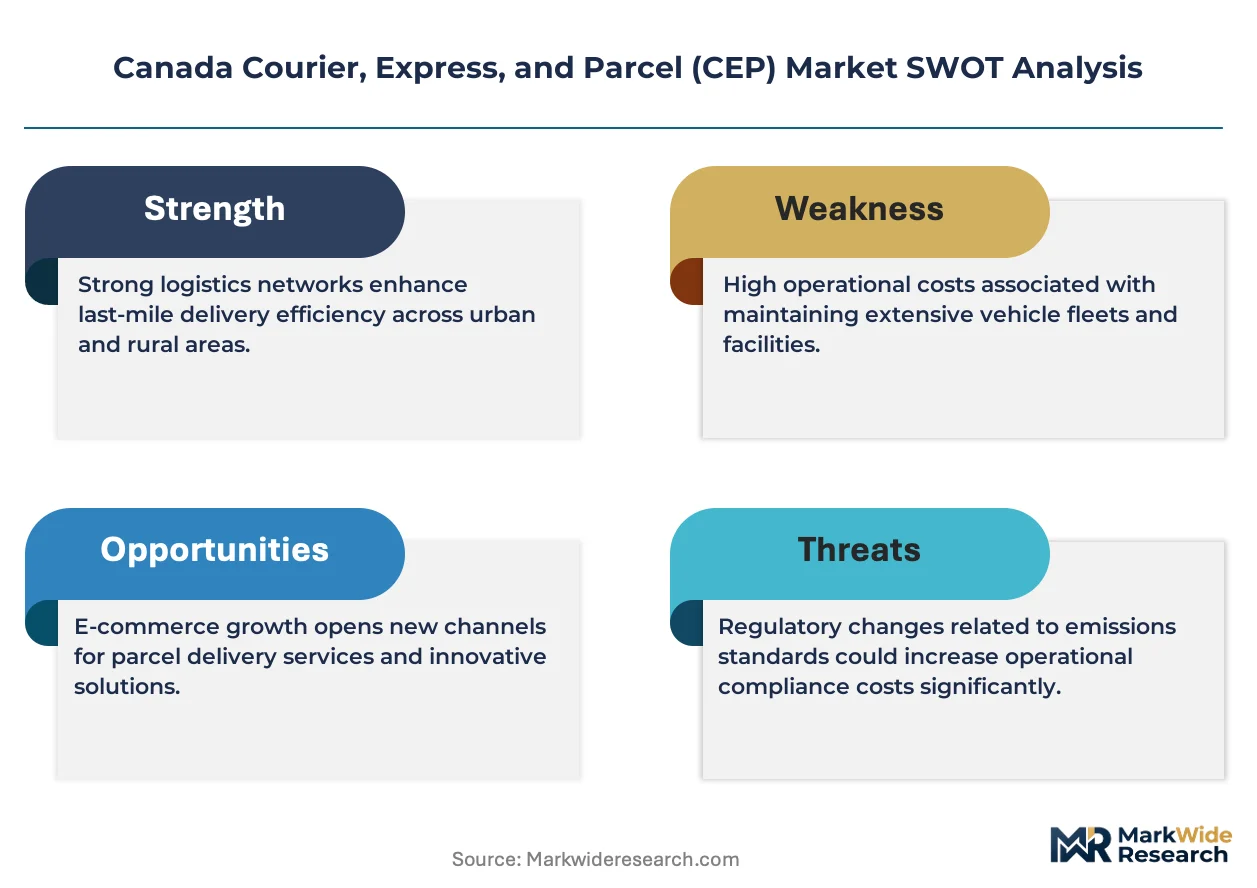
- Diesel price volatility:Fuel represents thirty-five to forty percent of line-haul operating costs for long-haul parcel contractors, with no hedging instruments available to mid-tier operators.
- Greater Toronto Area depot scarcity:Industrial land constraints within forty kilometers of downtown Toronto limit sortation facility expansion for regional carriers.
- Interprovincial weight regulations:Provincial variations in axle load limits complicate cross-border trailer utilization between Ontario, Quebec, and Atlantic provinces.
Strategic Opportunities
- Alberta and Saskatchewan e-commerce penetration:Underdeveloped same-day infrastructure in Calgary-Edmonton and Regina-Saskatoon corridors offers first-mover positioning for dedicated fulfillment networks.
- Municipal curbside management pilots:Vancouver and Montreal micro-hub and cargo bike incentive programs are creating regulatory preference for low-emission last-mile operators.
- AI-powered dynamic routing:Machine learning convergence with telematics is enabling real-time dispatch optimization that compresses cost per stop in dense residential zones.
Industry Challenges
- Commercial driver credentialing timelines:Class 3 and Class 1 license backlogs in Ontario and British Columbia extend hiring cycles to twelve to sixteen weeks, constraining peak season capacity scaling.
- Legacy warehouse management system integration:Real-time API connectivity between carrier tracking platforms and merchant ERP systems requires expensive middleware development for mid-market retailers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Canada Courier, Express, and Parcel (CEP) Market |
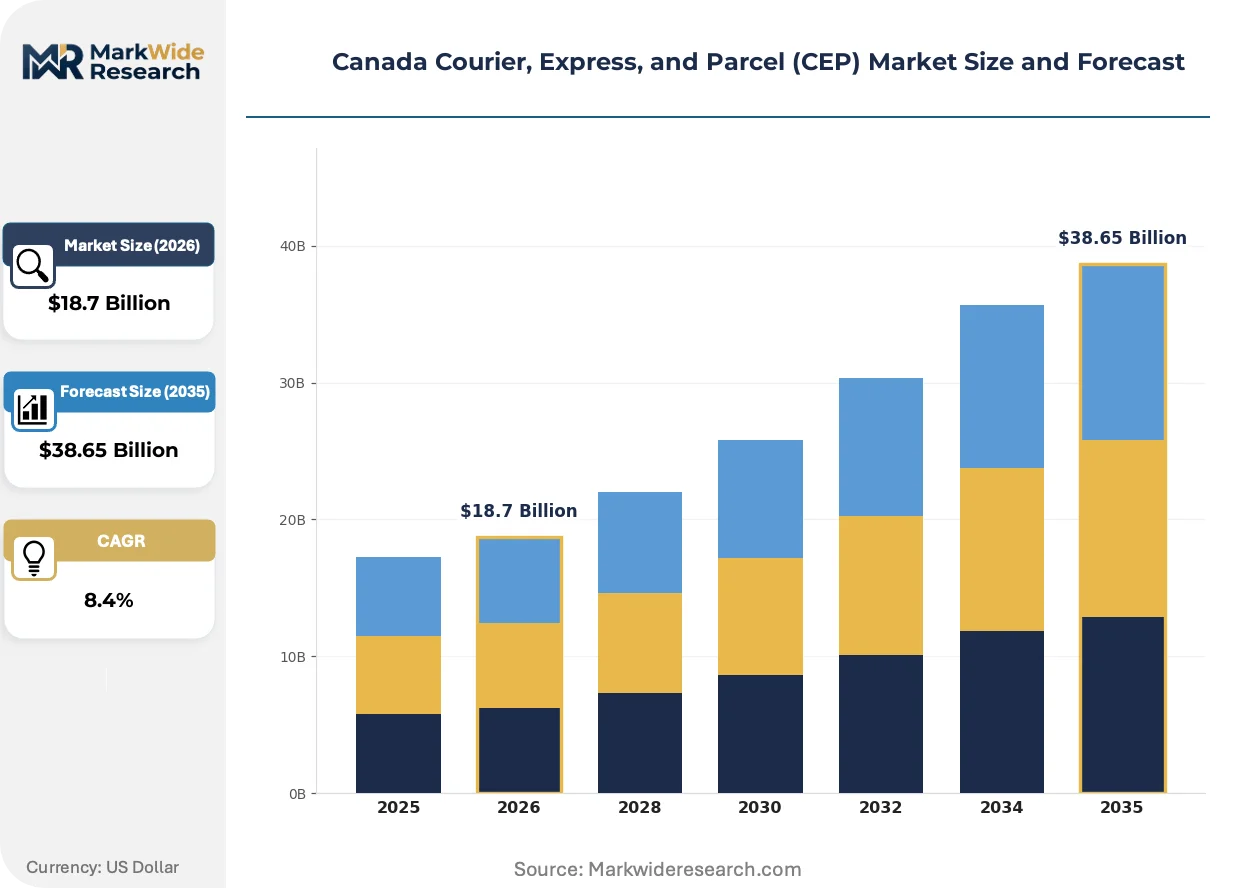
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $38.65 Billion |
| CAGR (2026 – 2036) | 8.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Delivery Mode: Same-Day Delivery, Next-Day Delivery, Standard Delivery, Scheduled Delivery Service Type: Domestic Shipping, International Shipping, Freight Services, Recurring Deliveries Customer Type: B2B, B2C, E-Commerce, Retail Package Size: Small Packages, Medium Packages, Large Packages, Oversized Packages |
| Companies Covered | Canada Post Corporation, FedEx, United Parcel Service of America, Inc., TFI International Inc., DHL Group, Purolator Inc., Intelcom Courrier Canada Inc., Globex Courrier Express International Inc., DTDC Express Limited, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Canada Courier, Express, and Parcel (CEP) Market Trends and Innovations
Parcel networks are abandoning hub-and-spoke consolidation in favor of distributed micro-fulfillment nodes positioned within fifteen kilometers of dense consumption clusters, compressing final-mile transit times while elevating inventory carrying costs.
Telematics-enabled predictive maintenance is converging with battery-electric vehicle fleets to eliminate unscheduled downtime in last-mile operations. Canada Post and major regional carriers are deploying these systems across Ontario-based depots to sustain vehicle availability above ninety-five percent during peak volume periods. This convergence is compressing total cost of ownership calculations for electric commercial vehicles against diesel equivalents.
British Columbia's Low Carbon Fuel Standard and Ontario's emissions performance standards are mandating progressive fleet decarbonization with compliance deadlines tightening through 2030. Transport Canada is harmonizing provincial rules through updated Motor Vehicle Safety Regulations that prescribe zero-emission vehicle procurement percentages for federally regulated operators. Parcel carriers serving Vancouver's downtown core are responding with cargo bike and electric van deployments to maintain access within municipal low-emission zones.
Merchant procurement of delivery services is fragmenting from annual volume contracts toward modular, transaction-based platform access. Small and mid-sized e-commerce sellers in Toronto and Montreal are abandoning exclusive carrier relationships in favor of multi-carrier rate shopping that selects optimal service levels per shipment. This pattern is most visible in fashion and consumer electronics verticals where margin pressure demands granular cost control over delivery experience consistency.
Canada Courier, Express, and Parcel (CEP) Market Segmentation
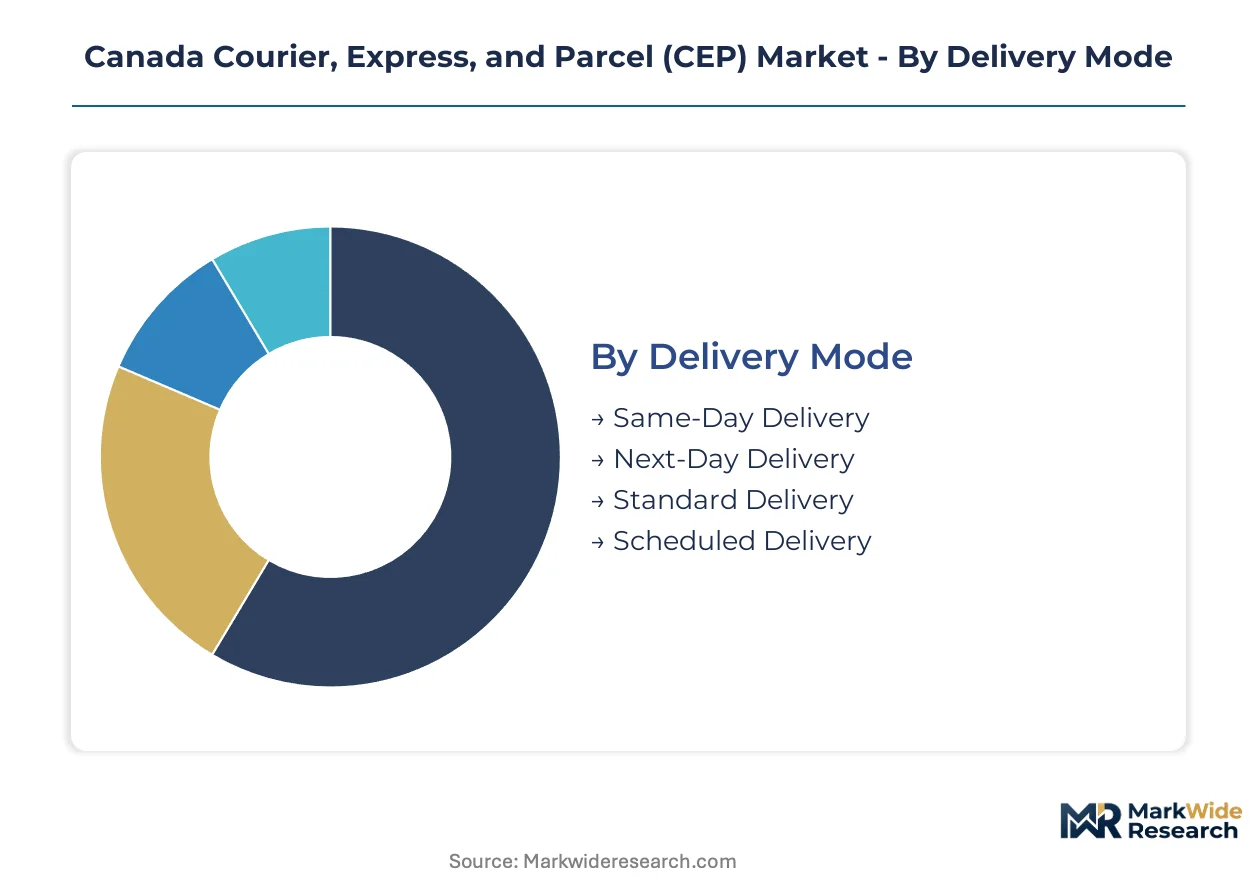
Canada's CEP market segments reflect divergent infrastructure requirements and margin structures. Delivery mode and customer type dimensions command the most strategic attention from carriers reconfiguring networks around compressed fulfillment windows and shifting volume concentration between B2B and e-commerce channels.
Delivery Mode:
Upgrade cycles from standard to expedited service tiers are shortening as merchant procurement shifts from annual contracts to transaction-based platform access, forcing carriers to maintain redundant capacity across all speed tiers simultaneously.
- Same-Day Delivery:Four-hour fulfillment guarantees require distributed micro-fulfillment nodes within fifteen kilometers of dense consumption clusters. Demand concentrates in Toronto's downtown core and Vancouver's Lower Mainland, where municipal curbside management pilots favor cargo bike and electric van deployments for zone access.
- Next-Day Delivery:Twenty-four-hour transit commitments leverage Ontario-Quebec warehousing density along Highway 401 and 20 corridors. Health Canada pharmaceutical cold-chain protocols are expanding specialized handling requirements within this tier for biological specimen distribution.
- Standard Delivery:Cost-sensitive bulk parcel tier serving price-driven B2B freight and non-urgent residential shipments across secondary markets.
- Scheduled Delivery:Appointment-based window fulfillment for oversized goods and white-glove residential service in Calgary-Edmonton corridors.
Volume placements concentrate in Next-Day Delivery; the faster expansion belongs to Same-Day Delivery.
Service Type:
Cost tier differentiation separates premium international express from commoditized domestic ground service, with recurring delivery contracts anchoring revenue stability for established carriers.
- Domestic Shipping:Canada Post partnership networks and dedicated B2B routing infrastructure anchor parcel density across provincial corridors. Purolator leverages this segment for recurring delivery contracts with enterprise shippers.
- International Shipping:Cross-border line-haul faces interprovincial weight regulation friction between Ontario, Quebec, and Atlantic provinces.
- Freight Services:Less-than-truckload consolidation for medium and large package tiers.
- Recurring Deliveries:Subscription-based replenishment and scheduled B2B routing.
Revenue stability clusters in Recurring Deliveries; cross-border complexity elevates International Shipping margins.
Customer Type:
Application-driven segmentation separates enterprise procurement patterns from fragmented e-commerce merchant behavior, with B2C volume expansion forcing network reconfiguration toward residential density.
- E-Commerce:Multi-carrier rate shopping and modular service bundling dominate merchant procurement in Toronto and Montreal fashion and consumer electronics verticals. Intelcom Courrier Canada Inc. competes on variable cost structures in dense residential zones.
- B2C:Direct-to-consumer shipments from retail and service providers.
- B2B:Enterprise freight contracts and recurring delivery relationships.
- Retail:Store-to-consumer and buy-online-pickup-in-store fulfillment.
Network investment prioritizes E-Commerce; margin protection depends on B2B contract retention.
Package Size:
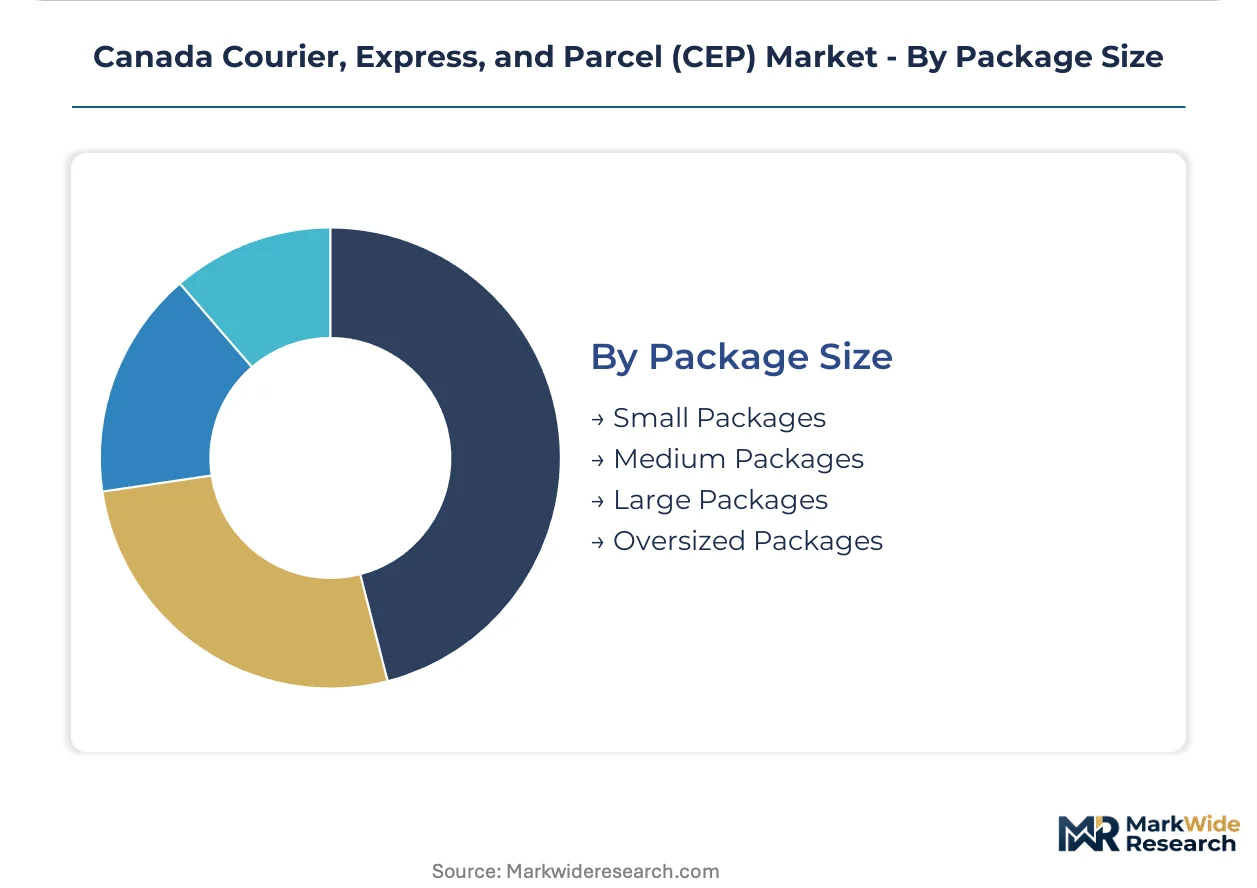
Handling infrastructure and vehicle fleet composition segment around dimensional weight pricing thresholds, with small package automation contrasting oversized manual sortation requirements.
- Small Packages:Automated sortation and conveyor-based processing dominate at Ontario and British Columbia hubs.
- Medium Packages:Hybrid handling requirements across standard delivery networks.
- Large Packages:Specialized line-haul and liftgate equipment for freight-adjacent service.
- Oversized Packages:Appointment-based scheduled delivery with white-glove handling protocols.
Automation returns concentrate in Small Packages; capacity constraints elevate Oversized Package pricing power.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Canada's CEP production capacity concentrates in Ontario and British Columbia warehousing corridors, while consumption spreads across all ten provinces with pronounced density in the Quebec-Windsor axis and Vancouver's Lower Mainland.
Ontario
E-commerce fulfillment and pharmaceutical distribution drive volume growth in the Greater Toronto Area. Transport Canada Motor Vehicle Safety Regulations mandate progressive fleet electrification for federally regulated operators serving the province. Mississauga-Brampton industrial clusters host the densest concentration of automated sortation facilities in Canada.
Quebec
Montreal's fashion and consumer electronics verticals generate substantial cross-border parcel flows to the United States. Provincial emissions performance standards accelerate zero-emission vehicle procurement timelines for last-mile operators. Laval and Longueuil distribution nodes enable sub-two-hour ground transit to fourteen million consumers along the Highway 20 corridor.
British Columbia
Vancouver's downtown core and Lower Mainland residential density create natural throughput advantages for same-day delivery networks. The provincial Low Carbon Fuel Standard mandates progressive fleet decarbonization with compliance deadlines tightening through 2030. Municipal curbside management pilots in Vancouver favor cargo bike and electric van deployments for zone access.
Alberta
Calgary-Edmonton corridor e-commerce penetration lags Ontario and British Columbia, creating first-mover positioning opportunities for dedicated fulfillment networks. Provincial weight regulations and axle load limits shape cross-border trailer utilization with Saskatchewan and British Columbia. Industrial land availability near Calgary's airport zone enables sortation facility expansion unavailable in Toronto or Vancouver markets.
Atlantic Canada
Halifax and Moncton serve as consolidation hubs for interprovincial freight moving between central Canada and Atlantic provinces. Interprovincial weight regulation variations complicate trailer utilization between New Brunswick, Nova Scotia, and Quebec. St. John's isolated geography sustains premium pricing for air freight-dependent express services.
Canada Courier, Express, and Parcel (CEP) Market Competitive Landscape
The competitive structure tilts toward integrated national networks with dedicated air-ground infrastructure. Two distinct tiers operate: premium express carriers sustaining margin-rich expedited service, and variable-cost platform operators competing on residential last-mile density. Strategic archetypes include postal-affiliated domestic networks, global integrators with Canadian hub operations, and gig-economy last-mile specialists. Dominant competitive moves center on fleet electrification procurement and micro-fulfillment node placement in urban cores.
Within the integrated carrier tier, FedEx and United Parcel Service of America, Inc. occupy positions anchored by cross-border air-ground networks. Purolator Inc. represents the postal-affiliated domestic archetype through its Canada Post partnership. Intelcom Courrier Canada Inc. exemplifies the gig-economy specialist model competing on variable cost structures in dense residential zones.
| Leading Market Players |
|---|
| Canada Post Corporation |
| FedEx |
| United Parcel Service of America, Inc. |
| TFI International Inc. |
| DHL Group |
| Purolator Inc. |
| Intelcom Courrier Canada Inc. |
| Globex Courrier Express International Inc. |
| DTDC Express Limited |
| Others |
Pricing and Supply Chain Analysis
Class 3 commercial driver concentration in Ontario's Greater Toronto Area and British Columbia's Lower Mainland feeds labor-cost differentials that widen pricing-tier spreads between premium same-day guarantees and standard deferred service across the Canada CEP market.
Pricing Analysis
Margin tightening in standard delivery reflects diesel price volatility and mid-tier operator inability to hedge fuel exposure. Three-tier pricing structure across premium express, standard deferred, and economy bulk levels stratifies by transit-time guarantee and real-time tracking granularity. Cost compression accelerates in the bulk parcel tier as merchant procurement shifts toward transaction-based platform access. E-commerce merchants in Toronto and Montreal fashion verticals exhibit highest price sensitivity, while pharmaceutical shippers under Health Canada cold-chain protocols accept premium pricing for temperature-controlled handling.
Supply Chain Analysis
Electric commercial vehicle supply rests on battery cell production concentrated in China, South Korea, and Japan, with charging infrastructure deployment tethered to provincial utility timelines. Sortation automation equipment draws from German and Japanese material handling specialists, while line-haul trailer manufacturing sources from domestic and cross-border suppliers. Single-source vulnerability sits with lithium-ion battery procurement for zero-emission fleet conversion mandated by Transport Canada regulations. Distribution runs through Ontario-Quebec warehousing clusters along Highway 401 and 20 corridors, with final-mile density concentrated in Toronto and Vancouver urban cores.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Canada CEP market functions as a vertical-integration race where fleet electrification procurement and micro-fulfillment node placement represent the decisive upstream and downstream levers separating integrated carriers from platform-dependent operators.
For Market Incumbents: Acquire automated sortation facilities in Mississauga-Brampton industrial clusters to defend density advantages against gig-economy entrants. Secure exclusive access to cargo bike and electric van incentive programs in Vancouver and Montreal municipal curbside management pilots. Threat exposure centers on Intelcom Courrier Canada Inc.'s variable-cost model compressing margins in dense residential zones. For New Entrants and Emerging Players: Launch via dedicated fulfillment networks in Calgary-Edmonton and Regina-Saskatoon corridors where same-day infrastructure remains underdeveloped. Target Alberta's industrial land availability near Calgary airport zones for sortation facility expansion unavailable in Toronto or Vancouver markets. Go-to-market positioning should emphasize AI-powered dynamic routing to compress cost per stop against incumbent legacy systems. For Investors and Strategic Acquirers: Re-rating potential sits with postal-affiliated domestic networks given Canada Post partnership exclusivity and recurring B2B contract stability. Long-term viability over a multi-year horizon depends on fleet electrification compliance timelines and provincial emissions performance standard adherence. Signal to monitor: Transport Canada harmonization of zero-emission vehicle procurement percentages across federally regulated operators.| Strategic Initiative | Industry Significance |
|---|---|
| Fleet Electrification Procurement | Transport Canada Motor Vehicle Safety Regulations mandate zero-emission vehicle percentages that reshape total cost of ownership calculations. |
| Micro-Fulfillment Node Placement | Fifteen-kilometer proximity to dense consumption clusters in Toronto and Vancouver enables four-hour delivery guarantees. |
| Multi-Carrier Platform Integration | Real-time API connectivity with merchant ERP systems captures transaction-based procurement shifts in fashion and consumer electronics. |
| Cargo Bike and Electric Van Deployment | Vancouver and Montreal municipal curbside management pilots create regulatory preference for low-emission last-mile operators. |
| Pharmaceutical Cold-Chain Certification | Health Canada and PMRA temperature-controlled protocols expand specialized handling revenue pools in biological specimen distribution. |
Research Methodology
Document review covered Transport Canada regulatory filings, provincial emissions standards, and carrier fleet procurement disclosures, complemented by interviews with fleet operations directors, sortation facility managers, e-commerce logistics procurement leads, and municipal transportation planning officers. Secondary validation drew from Canada Post annual reports, FedEx and UPS SEC 10-K filings, and Ontario Ministry of Transportation commercial vehicle registration data. Bottom-up volume modeling across delivery modes and customer types triangulated against top-down market sizing from trade association aggregates.
Historical volume trajectories cross-referenced against carrier capacity expansion announcements and warehousing development permits informed projection parameters across the analysis window. Segmentation dimensions modeled include delivery mode tiers, customer type channels, package size handling categories, and provincial regulatory clusters. CAGRs derived from regression analysis of e-commerce penetration rates, fleet electrification compliance timelines, and interprovincial freight flow patterns. Industry-specific forecast inputs incorporated diesel price volatility assumptions and commercial driver credentialing backlog durations.
Regulatory enforcement delays, battery supply chain disruptions, and municipal curbside policy reversals are the dominant revision risks to modeled outcomes. Forecasts reflect assumptions regarding Transport Canada harmonization progress and provincial emissions standard alignment. A concentrated set of fleet procurement and infrastructure deployment triggers warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Logistics and Shipping
Germany Automotive 3PL Market
Logistics and Shipping
Air Freight Market
Logistics and Shipping
Spare Part Logistics Market
Logistics and Shipping
Uruguay Freight and Logistics Market
Logistics and Shipping
Internet of Things (IoT) in Logistics Market
Logistics and Shipping
China Freight and Logistics Market
Logistics and Shipping
Cross-Border Logistics Services Market
Logistics and Shipping
Nigeria Third-Party Logistics (3PL) Market
Logistics and Shipping
Canada Road Freight Transport Market
Logistics and Shipping
Europe Refrigerated Container Shipping Market
Logistics and Shipping
Freight and Logistics Market
Logistics and Shipping
South America Freight and Logistics Market
Logistics and Shipping
Government and Education Logistics Market
Logistics and Shipping
South Africa Air Freight Market
Logistics and Shipping
GCC Automotive Logistics Market
Logistics and Shipping
Logistics Automation Market