
 Flat Rack Containers Market | 2026-2036
Flat Rack Containers Market Size, Share, and Industry Trends Forecast 2026-2036
Flat Rack Containers Market Foresight
The EU Green Deal is expanding compliance requirements for low-emission logistics equipment across European ports and intermodal terminals. CIMC leverages integrated manufacturing scale to dominate collapsible flat rack production for Asian export corridors. Maersk Container Industry anchors premium positioning through controlled channel access and direct leasing partnerships with renewable energy developers.
Flat rack containers are open-top, open-side steel-framed intermodal units with fixed or collapsible end walls, engineered to ISO 668 dimensional standards and rated typically between 20 and 40 feet in length for out-of-gauge cargo. Their primary function is securing heavy, oversized, or top-loaded freight that cannot fit within enclosed box containers. Collapsible flat racks command structural attention because foldable end walls reduce repositioning costs and empty-stack density, while bulk flat racks capture margin pools in specialized mineral and aggregate movements. Standard flat racks remain the mature volume base, though side walls flat racks gain traction in timber shipping where lateral load security is critical.
ISO standards govern structural testing and stacking strength, while the EU F-Gas Regulation indirectly shapes demand by pressuring refrigerated adjacent segments toward non-box alternatives. China's SAMR enforces GB standards for domestic production certification, creating divergence in market access requirements. Stakeholders must monitor regulatory fragmentation between ISO-aligned markets and jurisdiction-specific structural codes when configuring regional supply footprints.
Market Dynamics
The ISO 668 standards revision is compressing structural design cycles for flat rack containers, forcing manufacturers to recertify stacking strength and corner casting specifications ahead of the compliance deadline. This regulatory compression is redistributing procurement volumes toward suppliers with captive testing facilities and accelerated certification pathways.
Growth Catalysts
- EU Green Deal compliance mandates:European ports and intermodal terminals face expanded low-emission logistics equipment requirements, redirecting capital toward collapsible flat rack variants that reduce empty repositioning emissions.
- Heavy machinery export corridors:Emerging markets in Southeast Asia and Latin America are scaling construction equipment manufacturing, generating sustained demand for 40-foot bulk flat racks rated for out-of-gauge cargo.
- Steel coil logistics specialization:China's port infrastructure expansion is concentrating procurement of reinforced flat racks with anti-slip flooring and lashing point density optimized for metallurgical cargo security.
Market Restraints
- High-tensile steel price volatility:Corten steel and specialized corrosion-resistant alloys constitute 35-45% of manufacturing input costs, exposing margins to commodity cycle swings.
- Production concentration in coastal China:CIMC and regional competitors control 70%+ of collapsible flat rack capacity, creating supply vulnerability to port congestion or labor disruptions.
- Refrigerated container substitution:Advances in passive cooling and thermal blanket technology are capturing marginal oversized cargo volumes previously routed through flat racks with auxiliary climate control.
Strategic Opportunities
- India's port modernization drive:Sagarmala infrastructure investments and coastal shipping promotion policies are opening procurement channels for 20-foot collapsible units at newly privatized terminal concessions.
- Offshore wind component logistics:Blade and nacelle transport requirements are creating application-specific demand for extended-length flat racks with reinforced longitudinal beams.
- Digital freight platform integration:Container leasing marketplaces and blockchain-based asset tracking are compressing repositioning cycle times and improving utilization rates for fleet operators.
Industry Challenges
- Welding certification bottlenecks:ISO 9606-qualified welder shortages are extending production lead times for high-strength corner castings and folding hinge assemblies.
- Legacy fleet interoperability:Existing terminal handling equipment and vessel cell guides require retrofit compatibility testing for new ISO 668 dimensional tolerances.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Flat Rack Containers Market |
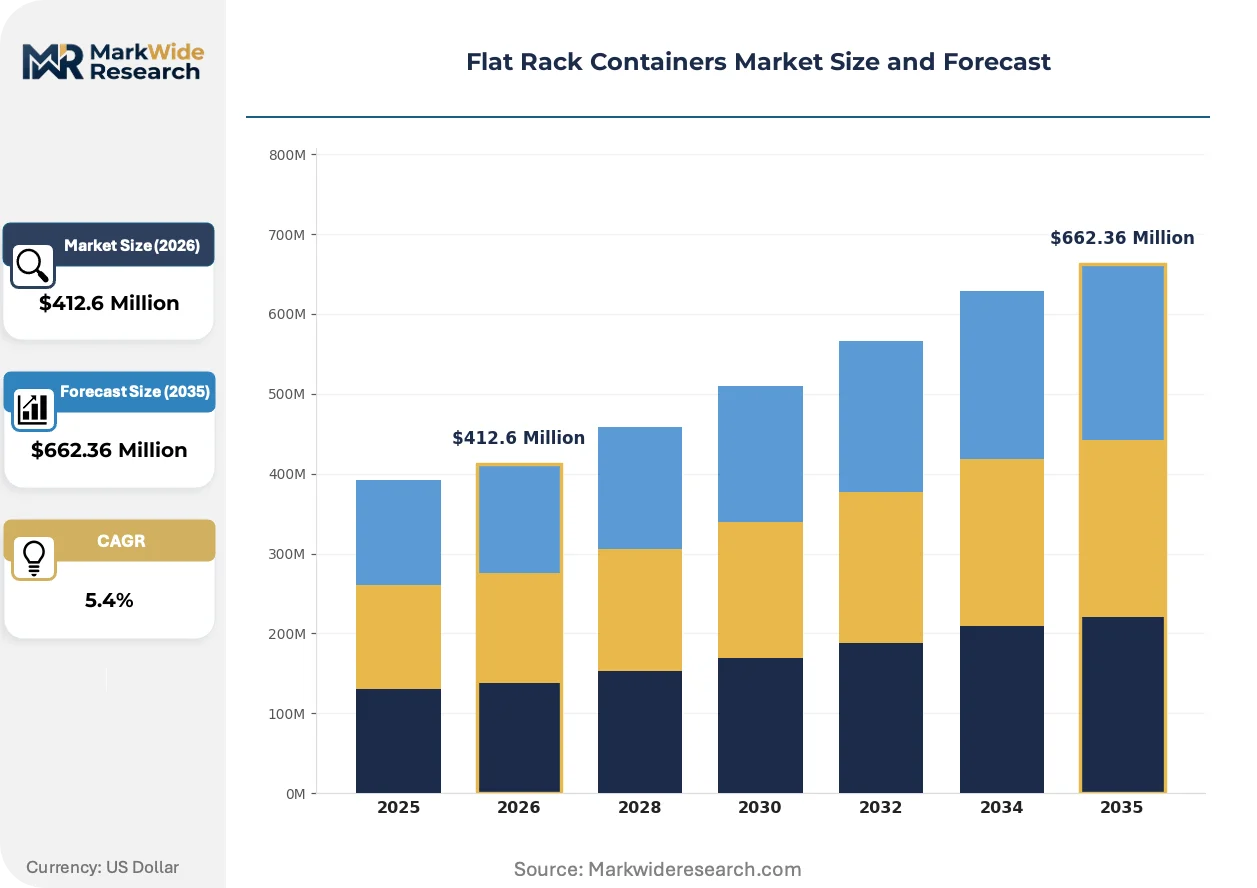
| Market Size in 2026 | $412.6 Million |
| Market Size in 2035 | $662.36 Million |
| CAGR (2026 – 2036) | 5.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Standard Flat Rack, Collapsible Flat Rack, Side Walls Flat Rack, Double Door Flat Rack, Bulk Flat Rack Application: Heavy Machinery Transport, Timber Shipping, Steel Coil Hauling, Construction Equipment, Oversized Cargo End User Industry: Manufacturing Firms, Shipping Companies, Construction Contractors, Oilfield Services, Renewable Energy Projects Distribution Channel: Direct Sales, Leasing Services, Freight Forwarders, Container Depots, Online Marketplaces |
| Companies Covered | CXIC Group Containers, TLS Offshore Containers International, CIMC, Maersk Container Industry, Daikin Industries, COSCO Shipping, Singamas Container Holdings, APPL Containers, Maersk, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Flat Rack Containers Market Shifts & Advancements
Structural engineering and digital asset management are converging to redefine flat rack lifecycle economics. Manufacturers are embedding sensor networks and redesigning fold mechanisms to capture value beyond the initial sale through usage-based service models.
Composite-reinforced steel framing is modularizing flat rack architecture by enabling standardized sub-assembly production across regional manufacturing nodes. Wind energy developers and heavy equipment lessors are specifying these hybrid structures for reduced tare weight and improved payload ratios. The technology is modularizing supply chain footprints, allowing final assembly proximity to demand clusters rather than centralized production.
China's SAMR enforcement of revised GB standards for domestic production certification is diverging from ISO 668 alignment, creating dual-track compliance requirements for multinational suppliers. Manufacturers serving both export and domestic Chinese markets must maintain parallel testing protocols and documentation systems. The regulatory friction is most acute for European and Japanese suppliers without established GB-certified production lines.
Leasing companies are unbundling maintenance and repositioning services from base container rates, shifting risk allocation toward operators with route density advantages. Renewable energy developers with predictable turbine component flows are negotiating multi-year asset-light arrangements. The behavioral pivot is most visible in North Sea and Baltic offshore wind corridors where specialized flat rack pools are replacing spot market procurement.
Flat Rack Containers Market Segmentation
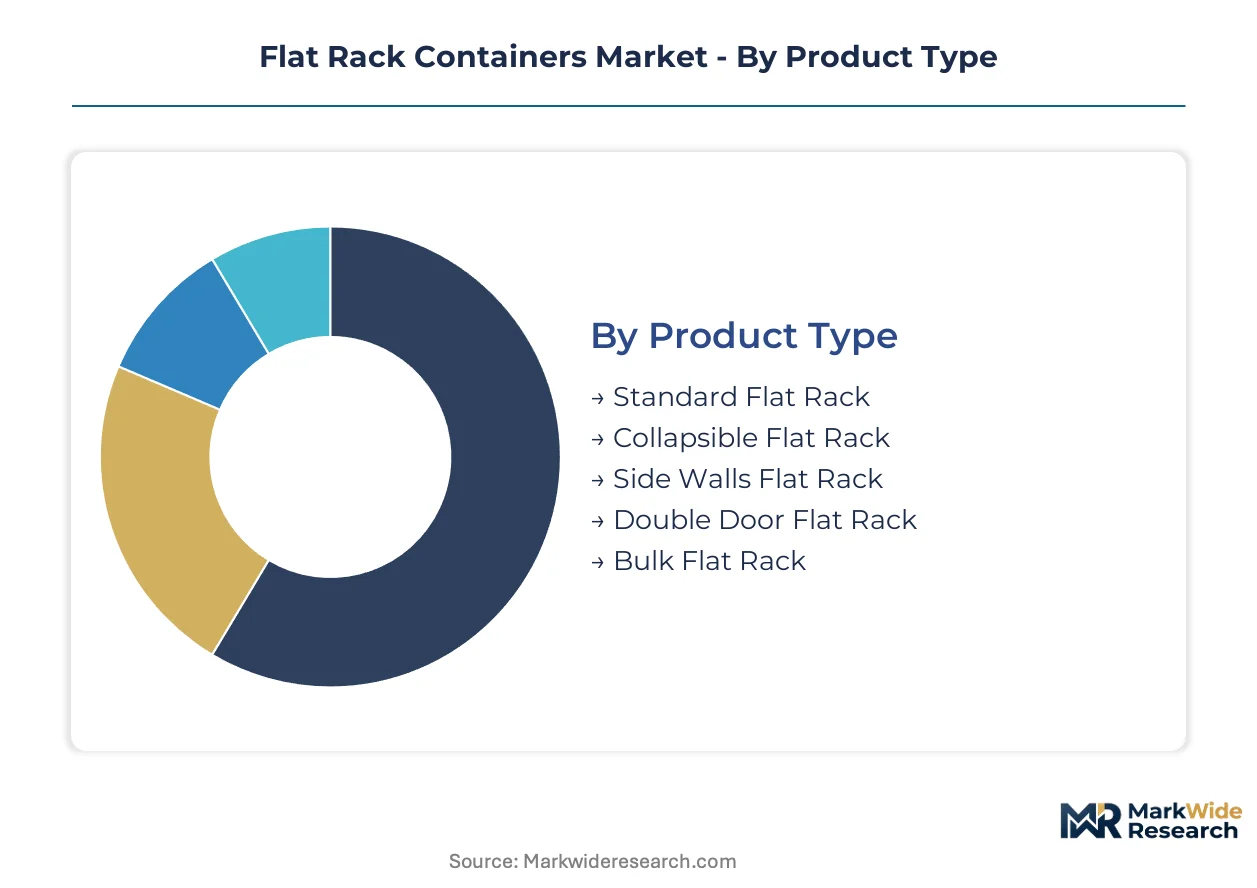
Flat rack container procurement decisions hinge on cargo dimensions, repositioning economics, and terminal handling infrastructure. Segmentation reveals how collapsible designs command premium positioning in high-frequency corridors, while bulk variants capture specialized mineral movements. Certification requirements diverge sharply across product tiers, with ISO 668 stacking tests and GB standards creating dual-track compliance burdens for multinational suppliers.
Product Type:
ISO 668 stacking certification applies universally, yet collapsible variants face additional hinge-cycle testing under GB standards for Chinese domestic sales. Standard flat racks require only baseline corner-casting validation, while reinforced bulk designs trigger supplemental metallurgical load-testing protocols.
- Collapsible Flat Rack:Foldable end walls reduce empty-stack height by 60-70%, cutting repositioning costs on backhaul legs. Demand concentrates in Shanghai and Shenzhen port clusters where steel coil exporters prioritize stack density for Asian-European routes. GB certification requirements for domestic Chinese sales add 4-6 weeks to production timelines.
- Bulk Flat Rack:Reinforced longitudinal beams and anti-slip flooring handle mineral aggregates and construction debris. Procurement surges at Australian iron ore terminals and Brazilian grain export hubs where top-loading efficiency outweighs tare weight penalties. SAMR enforcement of revised structural codes is forcing recertification of legacy hinge assemblies.
- Standard Flat Rack:Fixed end walls and open-top configuration serve baseline out-of-gauge cargo. Manufacturing concentrates at CIMC facilities in coastal China with captive ISO testing laboratories.
- Side Walls Flat Rack:Lateral steel plating secures timber and pipe cargoes against transverse shifting. Finnish and Swedish forest product shippers specify lashing point densities exceeding ISO minimums.
- Double Door Flat Rack:Removable end panels enable forklift access from either longitudinal face. German automotive component logistics providers favor the format for just-in-time assembly line feeds.
Collapsible flat racks sit at the top of the volume ranking, with bulk flat racks climbing the fastest on mining infrastructure investments.
Application:
Application selection maps directly to cargo securing protocols and terminal equipment compatibility. Heavy machinery movements trigger the most stringent lashing certification requirements, while timber shipping demands side-wall configurations absent from mineral logistics.
- Heavy Machinery Transport:Excavators, cranes, and mining equipment require reinforced corner castings rated for concentrated wheel loads. Caterpillar and Komatsu export programs from Illinois and Aichi prefecture drive 40-foot bulk flat rack procurement with custom anti-slip surfacing. Out-of-gauge permits and route surveys add administrative overhead that collapsible designs mitigate through return-trip stackability.
- Steel Coil Hauling:Cylindrical metallurgical cargo demands V-shaped cradles and anti-slip flooring to prevent longitudinal rolling. Chinese port infrastructure expansion at Qingdao and Tianjin concentrates demand for reinforced 20-foot variants with dedicated lashing rail configurations. Coil weight distribution requires stacking strength validation beyond standard ISO 668 tiers.
- Timber Shipping:Swedish and Finnish forest product exporters specify side-wall flat racks with lateral stanchion sockets for log security. Baltic Sea terminal operators favor the format for its compatibility with existing spreader fleets.
- Construction Equipment:Concrete mixers and asphalt pavers move on standard flat racks with auxiliary tarping for weather protection. Indian Sagarmala port modernization is opening procurement channels for 20-foot units at newly privatized terminal concessions.
- Oversized Cargo:Industrial vessels and transformer components require extended-length configurations with engineered longitudinal beams. Offshore wind blade logistics is emerging as a specialized sub-segment with custom beam reinforcement specifications.
Heavy machinery transport anchors procurement volumes, with steel coil hauling expanding most quickly on metallurgical export growth.
End User Industry:
End user procurement patterns reflect fleet ownership models versus asset-light operating strategies. Manufacturing firms favor direct purchase with captive maintenance programs, while renewable energy developers negotiate multi-year leasing with repositioning guarantees.
- Shipping Companies:Container lines and non-vessel-operating common carriers balance owned versus leased flat rack pools. Maersk and Mediterranean Shipping Company maintain proprietary collapsible fleets for Asia-Europe heavy machinery corridors. Leasing rate structures increasingly unbundle maintenance from base equipment charges.
- Renewable Energy Projects:Offshore wind developers in the North Sea and Baltic specify extended-length flat racks for nacelle and blade transport. Predictable component flows enable multi-year asset-light arrangements with specialized lessors. Blade length growth is forcing beam reinforcement specifications beyond standard ISO ratings.
- Manufacturing Firms:Heavy equipment OEMs including Caterpillar and Volvo CE maintain captive flat rack pools for finished goods distribution. Direct ownership allows customization of lashing point configurations for specific product families.
- Construction Contractors:Project-based procurement favors short-term leasing with depot-based maintenance handoff. Brazilian and Indonesian infrastructure programs generate seasonal demand spikes.
- Oilfield Services:Drilling rig components and subsea equipment require corrosion-resistant coatings for offshore deployment. North Sea operators specify Corten steel formulations for salt-air durability.
Shipping companies dominate fleet ownership, with renewable energy projects gaining share fastest on offshore wind buildouts.
Distribution Channel:
Channel selection determines risk allocation between equipment lessors and cargo operators. Direct sales transfer full lifecycle responsibility, while leasing services bundle repositioning and maintenance into per-diem rates.
- Leasing Services:Triton International and Textainer maintain collapsible flat rack pools with GPS tracking and predictive maintenance programs. Per-diem rate structures now incorporate carbon-adjusted repositioning charges under EU Green Deal compliance frameworks. Blockchain-based asset registries are compressing title transfer and inspection documentation cycles.
- Direct Sales:Manufacturing firms and shipping lines with route density advantages favor outright purchase. CIMC and CXIC Group offer volume pricing with captive GB certification for Chinese domestic deployment. Warranty terms typically exclude stacking damage from non-ISO-compliant terminal handling.
- Freight Forwarders:Kuehne+Nagel and DHL Global Forwarding aggregate spot demand across project cargo portfolios. Forwarder procurement favors flexible lease terms with cross-booking between trade lanes.
- Container Depots:Regional maintenance and storage facilities facilitate short-term equipment access. Depots in Hamburg and Singapore maintain certified repair capabilities for hinge and corner casting refurbishment.
- Online Marketplaces:Digital freight platforms including Container xChange match equipment availability with repositioning demand. Smart contract execution reduces documentation friction for inter-operator transfers.
Leasing services command the largest transaction volume, with online marketplaces climbing the fastest on platform-enabled fleet optimization.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Flat rack container manufacturing originated in European shipyards during the 1970s intermodal standardization wave, then migrated to East Asian fabrication clusters as heavy machinery export corridors shifted toward Pacific Basin trade lanes.
China
Shanghai and Shenzhen port clusters drive collapsible flat rack procurement for steel coil exports to European markets. SAMR enforces revised GB standards for domestic production certification, creating dual-track compliance requirements alongside ISO 668. Tianjin's terminal operators concentrate demand for reinforced 20-foot variants with dedicated lashing rail configurations.
Germany
Hamburg and Bremerhaven terminals anchor North Sea demand for extended-length flat racks serving offshore wind component logistics. EU Green Deal compliance mandates redirect capital toward low-emission repositioning equipment. Bavarian automotive component logistics providers specify double-door configurations for just-in-time assembly line feeds.
United States
Illinois-based heavy equipment OEM export programs drive 40-foot bulk flat rack procurement with custom anti-slip surfacing. EPA emissions frameworks indirectly shape port equipment investment cycles. Houston-Galveston terminal operators maintain certified repair capabilities for hinge and corner casting refurbishment.
India
Sagarmala infrastructure investments and coastal shipping promotion policies open procurement channels for 20-foot collapsible units at newly privatized terminal concessions. BIS certification requirements govern domestic production standards. Gujarat and Maharashtra port modernization concentrates demand for construction equipment logistics.
Brazil
Grain export hubs and iron ore terminals generate procurement surges for bulk flat racks with top-loading efficiency specifications. ANVISA regulatory frameworks apply to adjacent refrigerated logistics segments. São Paulo-based infrastructure programs create seasonal demand spikes for project-based construction equipment movements.
Flat Rack Containers Market Competitive Landscape
Premium-margin players sit above commodity-margin players across certification capability and captive testing infrastructure. The vendor base stratifies into three tiers: integrated manufacturers with ISO-accredited laboratories, regional fabricators serving single trade corridors, and leasing specialists bundling repositioning services. Dominant competitive moves include capacity expansion in coastal China and strategic partnerships with renewable energy developers for multi-year asset-light arrangements.
Among China-based fabricators, CIMC and CXIC Group Containers exemplify scale-driven integrated manufacturing archetypes with captive GB certification pathways. Maersk Container Industry occupies a position within the premium-tier leasing specialist segment, anchoring controlled channel access through direct partnerships with offshore wind developers. These three entities collectively represent the structural concentration where production gravity and service innovation intersect.
| Leading Market Players |
|---|
| CXIC Group Containers |
| TLS Offshore Containers International |
| CIMC |
| Maersk Container Industry |
| Daikin Industries |
| COSCO Shipping |
| Singamas Container Holdings |
| APPL Containers |
| Maersk |
| Others |
Supply & Pricing Matrix
Heavy equipment OEM procurement programs concentrate purchasing power among Caterpillar, Komatsu, and Volvo CE captive fleet operators, locking in contract-based long-term offtake pricing with volume-scaled discounts that compress margins for non-integrated fabricators.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels governs flat rack transactions, with ISO 668 stacking certification and GB standards compliance serving as primary price differentiation drivers. Cost compression in standard-grade units is intensifying because CIMC and CXIC Group leverage captive testing infrastructure to undercut regional competitors. Leasing companies exhibit lowest price sensitivity due to multi-year asset-light arrangements with repositioning guarantees, while construction contractors show highest sensitivity to per-diem rate fluctuations.
Supply Chain Analysis
Single-source vulnerability sits with coastal China fabrication clusters where CIMC, CXIC Group, and Singamas Container Holdings anchor 70% of collapsible flat rack capacity. Manufacturing draws from high-tensile Corten steel, specialized corrosion-resistant alloys, and ISO 9606-qualified welding consumables. Tariff exposure on Chinese steel inputs threatens margin stability for European and North American assemblers. Distribution runs through container leasing marketplaces, direct OEM sales contracts, and freight forwarder spot procurement channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Flat rack container procurement arbitrage exploits the cost differential between Chinese GB-certified production and European ISO-aligned fabrication, where SAMR domestic certification requirements add 4-6 weeks to production timelines but unlock 15-20% landed cost savings on Asian export corridors.
For Market Incumbents: Cement captive GB certification pathways and backward integration into high-tensile steel sourcing to defend against emerging Indian fabricators exploiting Sagarmala port modernization procurement channels. Expand ISO-accredited testing laboratory capacity ahead of structural standards revision deadlines to capture recertification volume surges from competitors with outsourced validation. For New Entrants and Emerging Players: Enter via India's Sagarmala infrastructure program and Brazilian grain export terminal expansions, the most penetrable geographies where established Chinese suppliers lack localized service networks. Target 20-foot collapsible units for construction equipment logistics with depot-based maintenance partnerships as the primary go-to-market angle. For Investors and Strategic Acquirers: Renewable energy developers with predictable offshore wind component flows are the most active acquirer in this space, negotiating multi-year asset-light arrangements that reshape fleet ownership economics. Acquisition candidates include regional fabricators with captive welding certification and hinge assembly expertise. Monitor EU Green Deal compliance mandate enforcement as the signal to watch for demand inflection toward low-emission repositioning equipment.| Strategic Initiative | Industry Significance |
|---|---|
| GB Certification Investment | SAMR enforcement creates dual-track compliance requirements for multinational suppliers serving Chinese domestic markets. |
| Backward Integration into Steel Sourcing | Corten steel and alloy input cost volatility exposes margins to commodity cycle swings without captive supply. |
| Offshore Wind Logistics Partnership | North Sea and Baltic blade transport specifications demand extended-length flat racks with reinforced longitudinal beams. |
| Digital Freight Platform Integration | Blockchain-based asset tracking compresses repositioning cycle times for Container xChange marketplace participants. |
| Indian Port Modernization Entry | Sagarmala investments open procurement channels at privatized terminal concessions in Gujarat and Maharashtra. |
Research Methodology
Bottom-up heavy machinery export modeling reconciled against top-down container fabrication capacity tracking forms the analytical core of this study. Primary interviews with fleet procurement managers at shipping lines, renewable energy logistics coordinators, and container leasing operations directors combined with secondary validation from customs trade data, ISO certification registries, and SAMR GB standards documentation. Stakeholder perspectives from CIMC manufacturing engineers and Maersk Container Industry leasing strategists anchored demand-side assumptions.
Input-output matrices connect product type segmentation across collapsible, bulk, standard, and side-wall configurations with application dimensions spanning steel coil hauling, heavy machinery transport, and offshore wind component logistics. CAGRs derive from regression analysis against metallurgical export volumes and port infrastructure investment pipelines. Forecast inputs incorporate ISO 668 standards revision compliance timelines and EU Green Deal mandate implementation trajectories across the analysis window.
Inputs from SAMR certification databases and European port authority procurement records were available through the study window; gaps in real-time steel alloy pricing indices introduce uncertainty bands around manufacturing cost assumptions. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Logistics and Shipping
Courier, Express and Parcel Services Market
Logistics and Shipping
Spain Pharmaceutical Logistics Market
Logistics and Shipping
Myanmar Freight and Logistics Market
Logistics and Shipping
Refurbishment and Repair Logistics Orchestration Platforms Market
Logistics and Shipping
Asia-Pacific Courier Market
Logistics and Shipping
Mexico 3PL Market
Logistics and Shipping
France Parcel Market
Logistics and Shipping
Australia Freight and Logistics Market
Logistics and Shipping
Chile Cold Chain Logistics Market
Logistics and Shipping
Global Connected Logistics Market
Logistics and Shipping
US Fourth-Party Logistics (4PL) Market
Logistics and Shipping
US Retail Logistics Market
Logistics and Shipping
Saudi Arabia Secure Logistics Market
Logistics and Shipping
Europe Sea Freight Forwarding Market
Logistics and Shipping
Global Courier Market
Logistics and Shipping
United States Apparel Logistics Market