
 Personal Data Recovery Software Market | 2026-2036
Personal Data Recovery Software Market Size, Share, and Industry Trends Forecast 2026-2036
Personal Data Recovery Software Market Outlook
Buyer concentration across the enterprise segment is broadening as mid-sized organizations build internal IT resilience capabilities alongside traditional large-account procurement. Stellar Data Recovery anchors its position through deep specialization in photo and multimedia restoration workflows. EaseUS Data Recovery Wizard leverages freemium distribution to capture individual users before upselling enterprise licenses. Disk Drill competes on macOS-native engineering, sustaining premium pricing in creative-industry verticals where Apple hardware dominates.
Personal data recovery software comprises applications engineered to reconstruct lost, corrupted, or deleted digital files from storage media including HDDs, SSDs, USB drives, and RAID arrays through file-system analysis, signature-based carving, and logical reconstruction algorithms. The technology serves commercial and consumer users who require restoration of operational data following hardware failure, accidental deletion, malware encryption, or partition corruption. File recovery tools occupy the largest volume tier, while partition recovery commands higher per-license pricing due to technical complexity and enterprise deployment patterns. Cloud-based deployment is expanding fastest as organizations integrate recovery into continuous backup architectures, though on-premises installations persist in regulated sectors where data sovereignty requirements restrict external hosting.
The Federal Trade Commission enforces data security standards affecting how recovery vendors handle customer metadata, while NIST publishes cybersecurity framework guidelines that shape enterprise procurement specifications for data protection tools. ISO 27001 certification increasingly gates vendor participation in enterprise RFP processes, particularly for cloud-based deployment options. Stakeholders must monitor evolving state privacy legislation, as fragmented compliance obligations across California, Virginia, and Colorado will determine which deployment architectures and data-handling protocols receive sustained investment.
Market Dynamics
Ransomware encryption incidents are forcing enterprise IT departments to integrate recovery tools into continuous backup architectures, tightening the link between data protection and operational resilience.
Growth Catalysts
- NIST Cybersecurity Framework:Enterprise procurement specifications increasingly mandate ISO 27001-certified recovery tools, expanding vendor addressable market in regulated sectors.
- Hybrid work architectures:Distributed endpoints generate persistent file loss incidents, sustaining demand for remote deployment capabilities across mid-sized organizations.
- Cloud migration velocity:Organizations rebuilding legacy on-premises archives in AWS, Azure, and Google Cloud environments require cross-platform recovery solutions.
Market Restraints
- Data sovereignty requirements:GDPR Article 44 restrictions on cross-border data transfers block cloud-based recovery adoption in European financial services.
- SSD controller fragmentation:Proprietary NAND flash management algorithms from Samsung, SK Hynix, and Kioxia limit signature-based carving effectiveness on modern solid-state media.
- Freemium saturation:Zero-cost entry-level tools commoditize basic file recovery, compressing pricing power in the individual user segment.
Strategic Opportunities
- India's Digital Personal Data Protection Act:Mandatory breach notification rules create compliance-driven procurement of audit-capable recovery platforms.
- Container-native storage:Kubernetes persistent volume recovery represents an underserved technical frontier as stateful workloads multiply.
- AI-assisted file reconstruction:Machine learning models trained on corrupted multimedia patterns enable premium pricing for photo and video restoration workflows.
Industry Challenges
- Forensic certification timelines:ENFSI and ASCLD accreditation requirements delay enterprise sales cycles by six to twelve months in law enforcement verticals.
- Legacy file system integration:Ext2, HFS+, and FAT32 archives in industrial control systems demand maintenance of obsolete parsing engines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Personal Data Recovery Software Market |
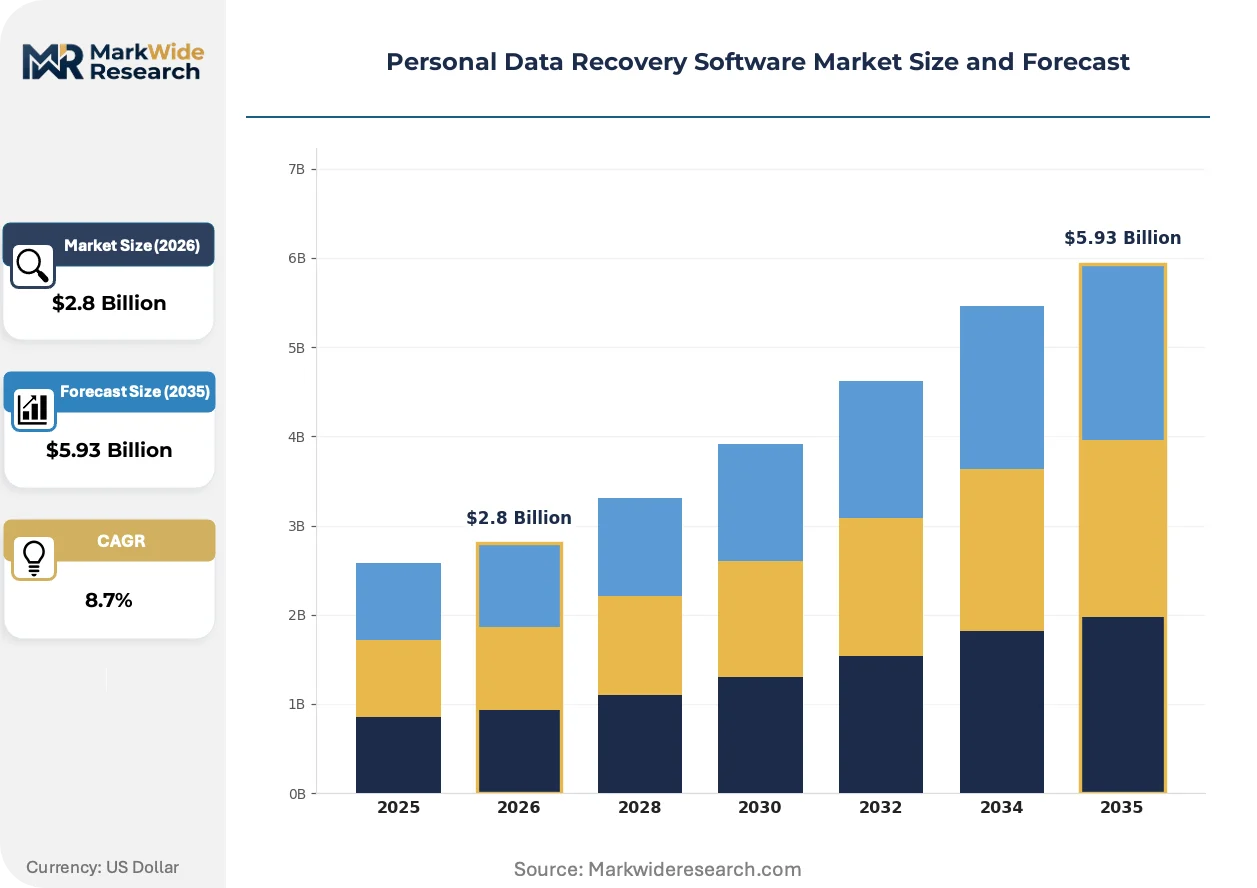
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $5.93 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: File Recovery, Partition Recovery, Email Recovery, Photo Recovery End User: Individuals, Enterprises, IT Service Providers, Educational Institutions Deployment: Cloud-Based, On-Premises, Hybrid, Remote Application: Data Backup, Data Migration, System Restore, Disk Imaging |
| Companies Covered | Stellar Data Recovery, EaseUS Data Recovery Wizard, Disk Drill, R-Studio, Recuva, DMDE, BLR Data Recovery Tool, Acronis Cyber Protect, IDrive, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Personal Data Recovery Software Market Strategic Shifts
Recovery software architectures are pivoting from reactive scan-and-restore models toward continuous data protection with instant rollback capabilities, embedding resilience deeper into storage infrastructure.
Immutable backup integration is overtaking traditional scheduled snapshots as the dominant enterprise data protection paradigm. Financial services institutions and healthcare providers are adopting write-once-read-many storage with embedded recovery triggers. This convergence is compressing the distinction between backup and recovery software categories.
REACH restrictions on persistent organic pollutants are reshaping hardware disposal protocols for failed storage media. Certified data destruction services must now document recovery-proof sanitization under audit trails. European enterprise buyers are prioritizing vendors with integrated chain-of-custody documentation.
Subscription licensing is displacing perpetual ownership across the mid-market segment. Value-added resellers and managed service providers are capturing recurring revenue streams through bundled recovery-as-a-service offerings. This shift is most pronounced in United States healthcare and legal verticals where OpEx preference dominates capital budgeting cycles.
Personal Data Recovery Software Market Segmentation
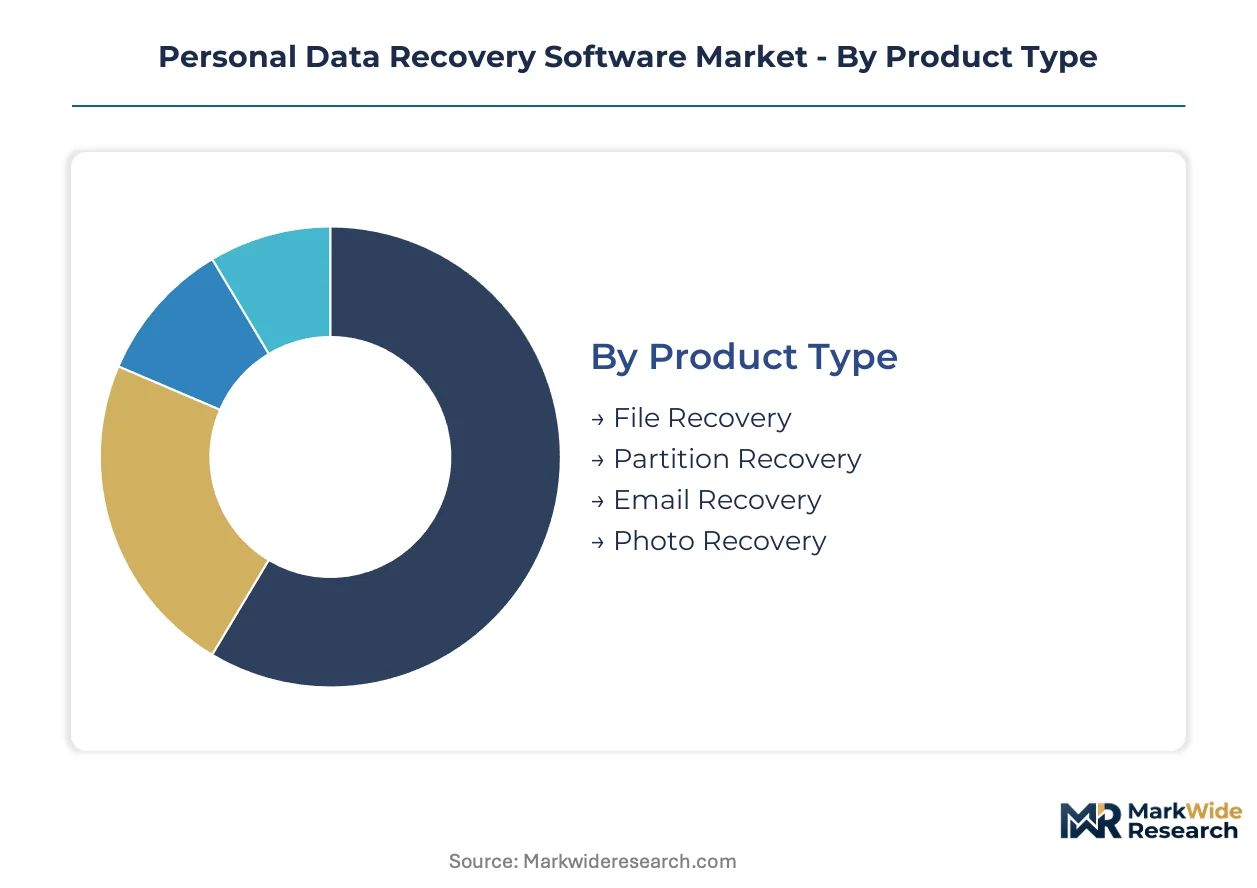
Segmentation in the personal data recovery software market reveals how technical complexity and deployment context shape purchasing behavior. Recovery tools span from lightweight consumer utilities to enterprise-grade platforms embedded in continuous data protection architectures, with pricing and procurement patterns diverging sharply across these boundaries.
Product Type:
Standalone recovery tools dominate consumer and small-business procurement, while embedded modules integrate into broader backup platforms for enterprise buyers seeking unified management consoles.
- File Recovery:Signature-based carving algorithms reconstruct deleted documents, images, and archives from logical storage failures. Mid-sized organizations in the United States deploy these tools across distributed endpoints as hybrid work architectures multiply incident volumes.
- Partition Recovery:Logical reconstruction engines restore corrupted partition tables and boot sectors, commanding premium per-license pricing due to technical sophistication. Enterprise IT departments in regulated sectors prioritize these capabilities for mission-critical infrastructure restoration following ransomware incidents.
- Email Recovery:Specialized parsers for PST, OST, and MBOX formats target Microsoft 365 and Google Workspace migration failures.
- Photo Recovery:Multimedia-focused workflows address camera storage corruption and accidental deletion in creative-industry verticals.
File Recovery leads volumes today; Partition Recovery is gaining share fastest.
End User:
Procurement authority concentrates differently across cost tiers, with enterprise buyers demanding ISO 27001 certification while individual users prioritize freemium accessibility.
- Individuals:Single-license consumers drive volume through direct digital distribution channels. Freemium saturation in this segment compresses pricing power, though photo and multimedia restoration features sustain premium tier conversions.
- Enterprises:IT departments mandate audit-capable platforms with immutable backup integration and chain-of-custody documentation. India's Digital Personal Data Protection Act is accelerating compliance-driven procurement of enterprise-grade recovery platforms with breach notification capabilities.
- IT Service Providers:Managed service providers bundle recovery-as-a-service offerings, capturing recurring revenue through subscription licensing models.
- Educational Institutions:Budget-constrained buyers favor site licensing agreements with volume discounts for campus-wide deployment.
Individuals lead volumes today; Enterprises are climbing the fastest.
Deployment:
Data sovereignty requirements and operational resilience priorities determine whether organizations externalize recovery infrastructure or retain on-premises control.
- Cloud-Based:Continuous data protection with instant rollback capabilities integrates recovery into AWS, Azure, and Google Cloud storage architectures. GDPR Article 44 restrictions on cross-border transfers block adoption in European financial services despite technical advantages.
- On-Premises:Air-gapped installations satisfy data sovereignty mandates in healthcare and government verticals where external hosting remains prohibited. These deployments persist in regulated sectors requiring physical control over recovery infrastructure.
- Hybrid:Split architectures balance cloud scalability with on-premises control for tiered data classification policies.
- Remote:Endpoint-native agents address file loss incidents without centralized infrastructure dependency.
On-Premises leads volumes today; Cloud-Based is expanding most quickly.
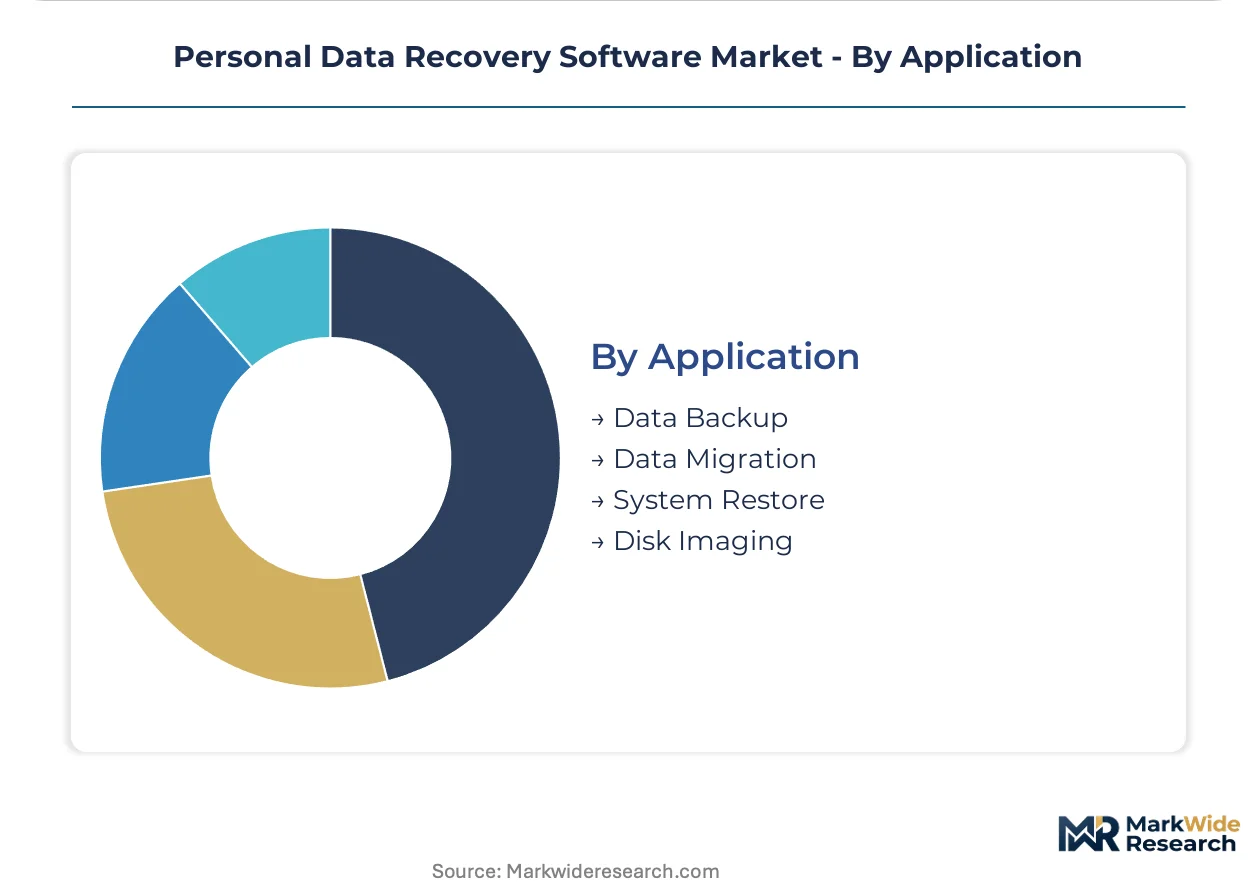
Application:
Functional use cases determine integration depth, with reactive restoration giving way to proactive resilience embedding.
- Data Backup:Immutable backup integration with write-once-read-many storage is overtaking traditional scheduled snapshots in financial services and healthcare. This convergence compresses categorical distinctions between backup and recovery software.
- Data Migration:Cross-platform reconstruction tools support legacy on-premises archive rebuilding in cloud environments. Organizations migrating to AWS, Azure, and Google Cloud require these capabilities for historical data continuity.
- System Restore:Bare-metal recovery capabilities restore entire operating environments following catastrophic hardware failures.
- Disk Imaging:Forensic-grade bit-stream copying supports law enforcement and litigation hold requirements with ENFSI and ASCLD accreditation timelines extending sales cycles.
Data Backup leads volumes today; Data Migration is gaining share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The United States generates more enterprise recovery software revenue than any other single country, while India's regulatory momentum is accelerating faster than comparable emerging markets. European data sovereignty requirements create structural friction that North American vendors navigate through localized hosting partnerships.
United States
Cloud migration velocity and hybrid work architectures sustain persistent demand for endpoint recovery tools across mid-sized organizations. State-level data breach notification laws in California, Virginia, and Colorado tighten compliance obligations for data protection vendors. Austin and Seattle host concentrated development clusters where vendors engineer immutable backup integrations for healthcare and financial services verticals.
Germany
Industrial automation and automotive manufacturing generate specialized recovery needs for legacy control system archives. GDPR Article 44 restrictions on cross-border data transfers block cloud-based adoption in financial services despite technical advantages. Munich and Stuttgart industrial corridors prioritize on-premises deployment with ENFSI-accredited chain-of-custody documentation for forensic-grade applications.
India
Digital Personal Data Protection Act mandates breach notification rules that create compliance-driven procurement of audit-capable recovery platforms. The country's national cybersecurity regulator shapes enterprise procurement specifications through mandatory incident reporting frameworks. Bangalore and Hyderabad technology clusters drive domestic vendor development for regional language support and localized cloud hosting.
Japan
Manufacturing digitization and precision electronics sectors demand high-reliability recovery for proprietary file formats. METI cybersecurity guidelines influence enterprise procurement standards for data protection tool certification. Tokyo and Osaka metropolitan areas concentrate financial services adoption where immutable backup integration commands premium pricing.
United Kingdom
Legal services and creative industries sustain demand for multimedia restoration workflows following camera storage corruption incidents. Post-Brexit data adequacy negotiations complicate cross-border recovery hosting arrangements with EU-based infrastructure. London financial district procurement prioritizes ISO 27001-certified platforms with forensic audit capabilities for litigation hold requirements.
Personal Data Recovery Software Market Competitive Environment
United States-based vendors anchor the premium enterprise tier; European specialists hold compliance-driven niches where data sovereignty requirements dominate procurement. The vendor base structures around three strategic archetypes: multimedia restoration specialists, freemium-to-enterprise converters, and platform-integrated resilience providers. M&A activity concentrates on immutable backup convergence plays, while geographic expansion through localized hosting partnerships addresses GDPR friction.
Within the multimedia specialization tier, Stellar Data Recovery exemplifies deep workflow engineering for photo and video restoration. EaseUS Data Recovery Wizard occupies the freemium conversion archetype, capturing individual users through zero-cost entry before upselling enterprise licenses. Disk Drill anchors the platform-native positioning vector, sustaining premium pricing in creative-industry verticals where Apple hardware dominates procurement decisions.
| Leading Market Players |
|---|
| Stellar Data Recovery |
| EaseUS Data Recovery Wizard |
| Disk Drill |
| R-Studio |
| Recuva |
| DMDE |
| BLR Data Recovery Tool |
| Acronis Cyber Protect |
| IDrive |
| Others |
Value Chain & Pricing Dynamics
Private-equity-rolled-up specialists in the backup and recovery software space have consolidated fragmented tool vendors into platform suites, tightening pricing discipline while compressing channel margins for standalone recovery products. This ownership concentration feeds directly into supply chain decisions, as consolidated vendors prioritize cloud-native delivery infrastructure over legacy boxed-software distribution networks.
Pricing Analysis
Capacity additions in India and Southeast Asia are reshaping price floors for entry-tier recovery tools as domestic vendors compete aggressively on subscription rates. Three-tier pricing structure across premium, standard, and economy levels separates ISO 27001-certified enterprise platforms from freemium consumer utilities and mid-market SaaS tiers. Price differentiation centers on audit capability and chain-of-custody documentation, with regulated healthcare buyers showing lowest price sensitivity due to compliance mandates. Cost compression in the individual user segment is intensifying because zero-cost alternatives commoditize basic file recovery functions.
Supply Chain Analysis
Direct-to-OEM channels handle hyperscale buyer demand for embedded recovery modules, while value-added resellers and managed service providers distribute standalone licenses to mid-market accounts. Software development concentrates in the United States, India, and Germany, with cloud infrastructure sourcing from AWS, Azure, and Google Cloud data centers regionally. Raw material dependencies include NAND flash storage for testing environments, encryption chipsets for secure boot architectures, and API access licenses for Microsoft 365 and Google Workspace integration. Supply chain risk centers on single-source vulnerability for forensic certification bodies, where ENFSI and ASCLD accreditation delays extend enterprise sales cycles.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market compounds regulatory tailwinds into structural demand, with India's Digital Personal Data Protection Act mandating breach notification capabilities that drive audit-grade platform procurement.
For Market Incumbents: Deepen immutable backup integration to defend against platform convergence threats from adjacent cybersecurity vendors expanding into recovery. Prioritize ISO 27001 certification maintenance as procurement gating requirements tighten across healthcare and financial services verticals. Expand channel control through managed service provider partnerships that capture recurring revenue streams and reduce customer acquisition costs. For New Entrants and Emerging Players: Begin with container-native storage recovery for Kubernetes persistent volumes, the most penetrable technical frontier where established vendors lack specialized tooling. Target India's compliance-driven enterprise segment, where localized hosting requirements and breach notification mandates favor domestic or regionally committed vendors. Pursue a strategic partnership route with cloud infrastructure providers to embed recovery capabilities into native storage services. For Investors and Strategic Acquirers: Valuations sit cheapest among freemium-to-enterprise conversion specialists with undermonetized installed bases but proven upsell mechanics. Long-term viability favors vendors with forensic certification credentials and healthcare vertical penetration, given durable compliance spending patterns. Watch for inflection signals in state-level data breach notification law proliferation across the United States, which accelerates enterprise procurement cycles.| Strategic Initiative | Industry Significance |
|---|---|
| Immutable Backup Integration | Compresses categorical boundaries between backup and recovery software in financial services procurement. |
| Forensic Certification Investment | Unlocks law enforcement and litigation hold verticals with six-to-twelve-month sales cycle premiums. |
| Cloud Infrastructure Partnership | Embeds recovery capabilities into AWS, Azure, and Google Cloud native storage service offerings. |
| Container-Native Development | Addresses Kubernetes persistent volume recovery as stateful workloads multiply in enterprise deployments. |
| Localized Hosting Expansion | Resolves GDPR Article 44 friction for European financial services buyers requiring data sovereignty compliance. |
Study Parameters
Bottom-up enterprise deployment modeling reconciled against top-down vendor revenue tracking forms the analytical core of this study. Primary interviews with IT procurement officers, cybersecurity framework consultants, managed service provider operators, and forensic laboratory directors combined with secondary validation from SEC filings, hyperscaler capex disclosures, and NIST cybersecurity framework documentation. Triangulation across these sources ensures segmentation outputs reflect actual procurement patterns rather than vendor-reported aspirations.
Historical trendline analysis of recovery software adoption rates across deployment models, organization size tiers, vertical industries, integration complexity levels, and regional regulatory clusters established baseline growth trajectories. CAGRs were derived through regression analysis of these historical patterns adjusted for identified catalysts and restraints. Forecast inputs include ransomware incident frequency reporting, cloud migration velocity indicators, and state-level data breach notification law enactment tracking.
Several conditions sit outside the modeled scope, including catastrophic encryption algorithm breakthroughs rendering current recovery methods obsolete and geopolitical disruptions severing cross-border data transfer mechanisms. Forecasts reflect assumptions about sustained regulatory enforcement intensity and stable NAND flash storage cost curves. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Security Software
Identity-As-A-Service (Idaas) Market
Security Software
Data Privacy Software Market
Security Software
Data Loss Prevention Market
Security Software
Device Vulnerability Management Market
Security Software
Software Defined Perimeter (SDP) Market
Security Software
Mobile Threat Management Security Software Market
Security Software
Europe Lawful Interception Market
Security Software
Global Network Security Software Market
Security Software
Embedded Security Market
Security Software
Digital Credential Management Software Market
Security Software
Mobile Data Protection Solutions and Services Market
Security Software
Mobile Antivirus Software Market
Security Software
Stalkerware Market
Security Software
Bot Mitigation Market
Security Software
SSL Inspection Solution Market
Security Software
Global Automatic Number Plate Recognition (ANPR) System Market