
 Europe Lawful Interception Market | 2026-2036
Europe Lawful Interception Market Size, Share, and Industry Trends Forecast 2026-2036
Europe Lawful Interception Market Intelligence
Project finance and government leasing arrangements for surveillance infrastructure is narrowing the competitive field to vendors with sovereign security clearances and long-term service contracts. Utimaco GmbH leverages its German engineering base and BSI certifications to dominate domestic public-sector procurement. BAE Systems anchors its position through deep integration with UK intelligence community frameworks and bespoke system architectures. Ericsson competes by extending its telecom equipment installed base into lawful interception overlays for European mobile operators.
Lawful interception denotes the legally authorized capture and monitoring of telecommunications traffic by state agencies, encompassing real-time data extraction from packet-switched networks, circuit-switched voice channels, VoIP streams, and mobile data sessions with timestamp correlation and metadata preservation. The technology serves counterterrorism, criminal prosecution, and national security operations requiring judicial oversight and chain-of-custody integrity. Packet-switched and mobile data interception segments lead current deployment volumes as 5G and encrypted IP traffic displace legacy circuit-switched voice. Cloud-based and hybrid deployment models represent the fastest-expanding configuration category as agencies seek elastic compute for storage-intensive analytics while retaining classified processing on-premise. Managed services capture expanding margin pools by bundling system maintenance, lawful intercept compliance audits, and operator training under multi-year contracts.
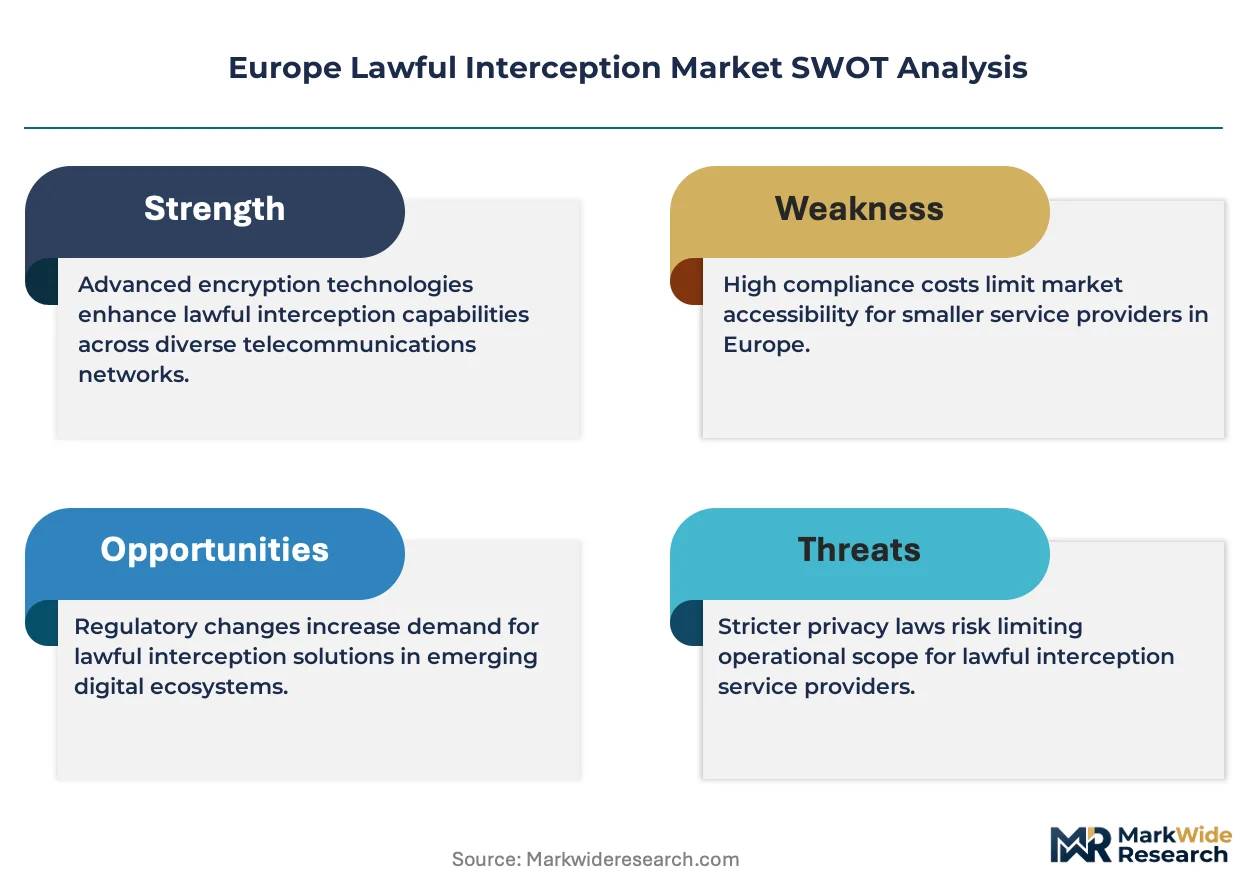
EU member states operate under the European Data Protection Board guidance, national implementations of the ePrivacy Directive, and country-specific telecommunications interception mandates such as Germany's Telecommunications Act and France's LCEN framework, collectively requiring providers to engineer intercept capabilities into network infrastructure from design phase. ETSI standards for handover interfaces and 3GPP lawful interception specifications shape product interoperability requirements and vendor qualification pathways. Stakeholders must monitor proposed EU Cybersecurity Act expansions and national encryption-debate outcomes that could mandate backdoor architectures or shift liability models for intercept-capability gaps.
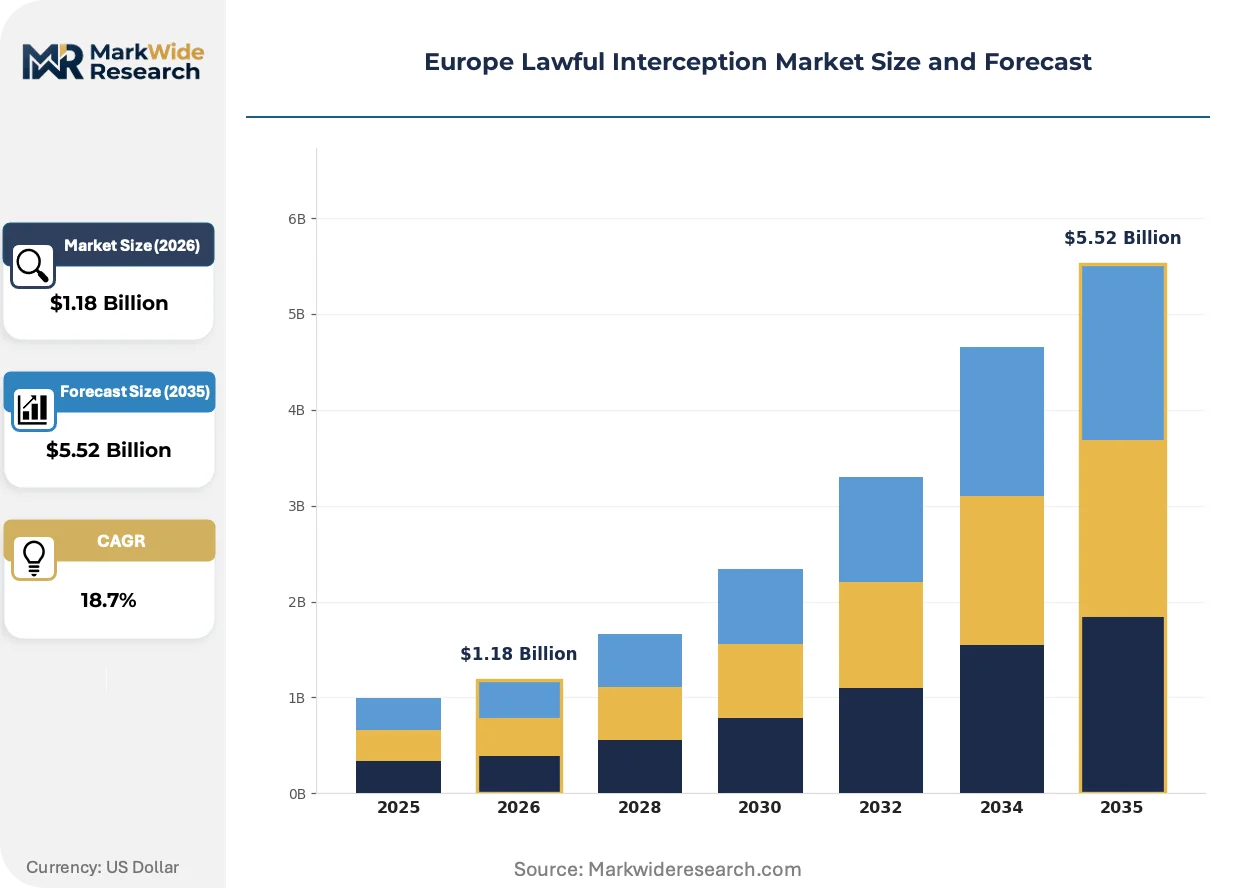
Market Dynamics
The encryption arms race between law enforcement and organized crime networks is forcing European governments to rebuild interception infrastructure around packet-switched analytics and real-time metadata correlation, compressing procurement cycles and elevating technical qualification barriers for vendors.
Growth Catalysts
- Germany's Telecommunications Act mandates:Network operators must maintain intercept-ready infrastructure, creating recurring demand for compliance audits and system upgrades.
- 5G network densification:Mobile operators across France and Italy require lawful interception overlays for packet-switched voice and data sessions.
- Counterterrorism operations:Joint EUROPOL task forces drive investments in cross-border intercept data sharing and timestamp correlation systems.
Market Restraints
- BSI certification scarcity:German Federal Office for Information Security approval timelines extend vendor qualification cycles, limiting supplier pool depth.
- Semiconductor supply concentration:Specialized packet-processing ASICs source predominantly from East Asian foundries, creating input vulnerability.
- End-to-end encryption proliferation:Signal, WhatsApp, and Telegram default encryption degrades intercept yield rates for content-level surveillance.
Strategic Opportunities
- Poland and Baltic states:These jurisdictions show underpenetrated intercept infrastructure relative to Western European maturity, opening greenfield deployment windows.
- AI-driven anomaly detection:Convergence of machine learning with metadata analytics enables predictive targeting for security agencies.
- Cloud-hybrid architectures:The EU Cybersecurity Act's proposed certification frameworks for classified cloud processing create compliant service delivery pathways.
Industry Challenges
- Telecommunications engineer scarcity:Deep expertise in SS7, Diameter, and 5G core protocols remains concentrated among legacy vendor workforces.
- Judicial authorization latency:Chain-of-custody documentation requirements compress operational response windows for real-time intercepts.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe Lawful Interception Market |
| Market Size in 2026 | $1.18 Billion |
| Market Size in 2035 | $5.52 Billion |
| CAGR (2026 – 2036) | 18.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Technology: Packet Switched, Circuit Switched, VoIP, Mobile Data End User: Government Agencies, Law Enforcement, Intelligence Services, Telecommunications Providers Deployment: On-Premise, Cloud-Based, Hybrid, Managed Services Application: Criminal Investigation, National Security, Fraud Detection, Cybersecurity |
| Companies Covered | Utimaco GmbH, BAE Systems, Ericsson, Matison, AQSACOM, Verint Systems, SS8 Networks, Cisco Systems, Vocal Technologies, Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe Lawful Interception Market Strategic Shifts & Innovations
European lawful interception is pivoting from passive storage-heavy architectures toward active analytics platforms that preprocess intercepted data before judicial review, compressing investigation timelines and expanding system complexity.
Deep packet inspection technology is migrating from standalone hardware appliances toward virtualized network functions embedded in operator core infrastructure. French and German mobile carriers are deploying these software-defined intercept points at 5G standalone core nodes. This migration from physical to virtualized architectures collapses deployment timelines and enables elastic scaling during high-volume intercept events.
France's LCEN framework and Germany's updated Telecommunications Act are mandating intercept capability preservation across network virtualization migrations. Operators must demonstrate functional equivalence between legacy circuit-switched and next-generation packet-switched intercept handover interfaces. The ETSI-compliant product segment faces compressed recertification cycles as standards evolve for 5G and beyond.
Security agencies are consolidating vendor relationships around multi-year managed service contracts that bundle system maintenance, operator training, and compliance audit functions. France's domestic intelligence services pioneered this bundled procurement model. Southern European agencies in Spain and Italy are adopting similar structures to offset internal technical capacity constraints.
Europe Lawful Interception Market Segmentation
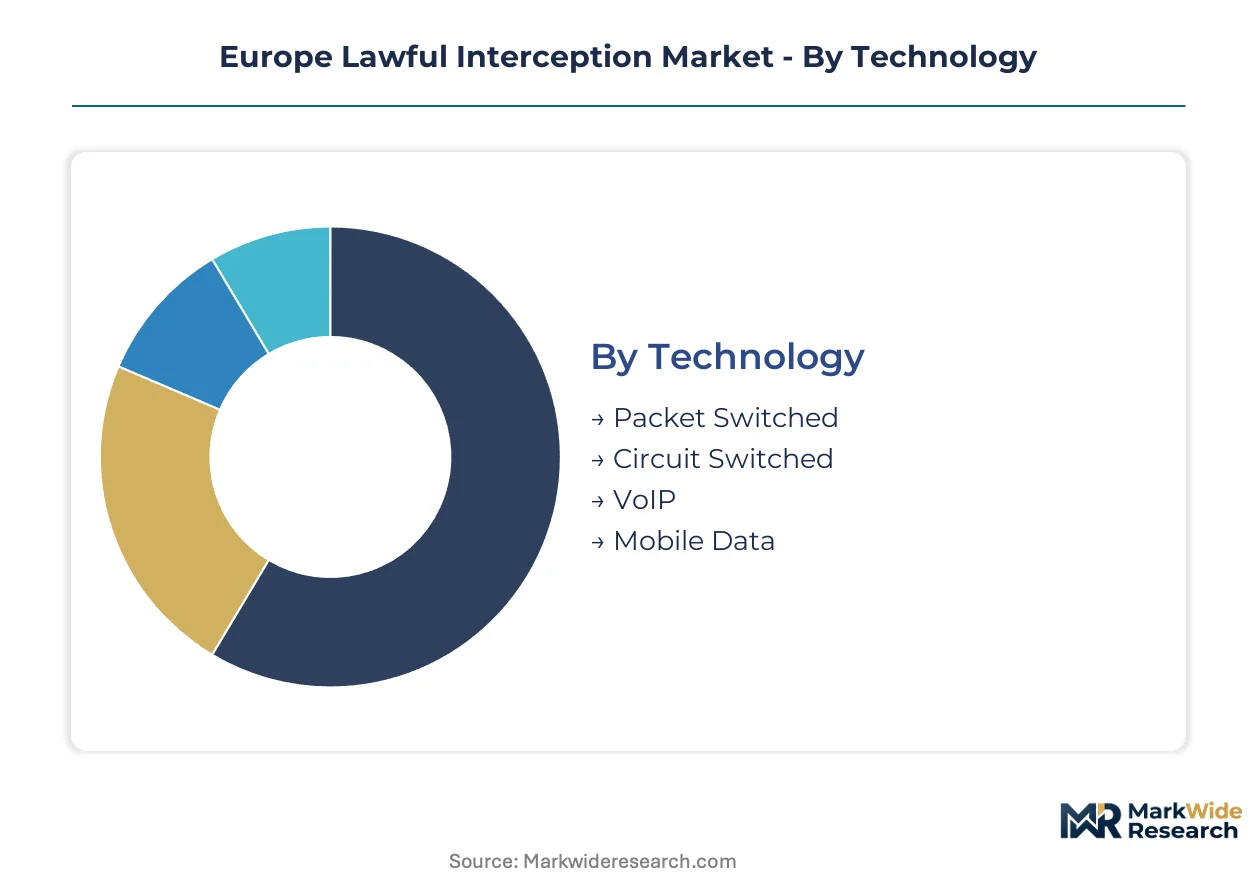
Lawful interception systems require sustained technical support across certification maintenance, protocol updates, and judicial compliance documentation. Segmentation reveals where service intensity concentrates and which configurations demand specialized engineering resources.
Technology:
After-sales service intensity varies sharply by underlying network architecture, with packet-switched deployments requiring continuous signature updates and real-time metadata correlation support.
- Packet Switched:Deep packet inspection engines process IP traffic streams through virtualized network functions embedded at 5G core nodes. German Federal Criminal Police Office procurement prioritizes these systems as encrypted communications displace circuit-switched voice.
- Mobile Data:Intercept overlays for 4G/5G sessions capture subscriber identity, location, and bearer traffic through standardized handover interfaces. French mobile operators drive deployment volumes as network densification accelerates.
- Circuit Switched:Legacy TDM voice interception remains operational in Eastern European infrastructure with declining maintenance contracts.
- VoIP:Session initiation protocol monitoring targets encrypted voice streams with diminishing content-level yield.
Packet switched holds the largest share; momentum sits with mobile data as 5G standalone cores expand.
End User:
Procurement authority and technical sophistication diverge across buyer categories, shaping contract structures from turnkey installations to multi-year managed service bundles.
- Government Agencies:National interior ministries and justice departments operate centralized intercept management facilities with dedicated secure processing environments. Italy's Ministry of Interior maintains the largest facility footprint in Southern Europe.
- Intelligence Services:Domestic and foreign intelligence agencies demand bespoke architectures with air-gapped classified processing and specialized chain-of-custody protocols. UK intelligence community frameworks set integration standards.
- Law Enforcement:Federal and state police forces require rapid deployment capabilities for targeted investigations with compressed judicial authorization windows.
- Telecommunications Providers:Operators bear regulatory-mandated intercept readiness obligations under Germany's Telecommunications Act and France's LCEN framework.
Government agencies command the largest installed base; intelligence services are expanding most quickly through classified modernization programs.
Deployment:
Margin structures shift dramatically with delivery model, as cloud-hybrid configurations capture recurring service revenue while on-premise systems concentrate capital expenditure.
- Hybrid:Agencies retain classified processing on-premise while leveraging elastic cloud compute for storage-intensive analytics and cross-border data sharing. EU Cybersecurity Act certification pathways enable compliant service delivery.
- Managed Services:Multi-year contracts bundle system maintenance, lawful intercept compliance audits, and operator training. France's domestic intelligence services pioneered this procurement model now spreading to Spain and Italy.
- On-Premise:Fully captive infrastructure persists in agencies with stringent data sovereignty requirements and established secure facilities.
- Cloud-Based:Pure cloud deployments remain limited by classification constraints though expanding for lower-sensitivity metadata processing.
Hybrid architectures dominate new procurement; managed services are gaining share fastest as agencies offset internal technical capacity constraints.
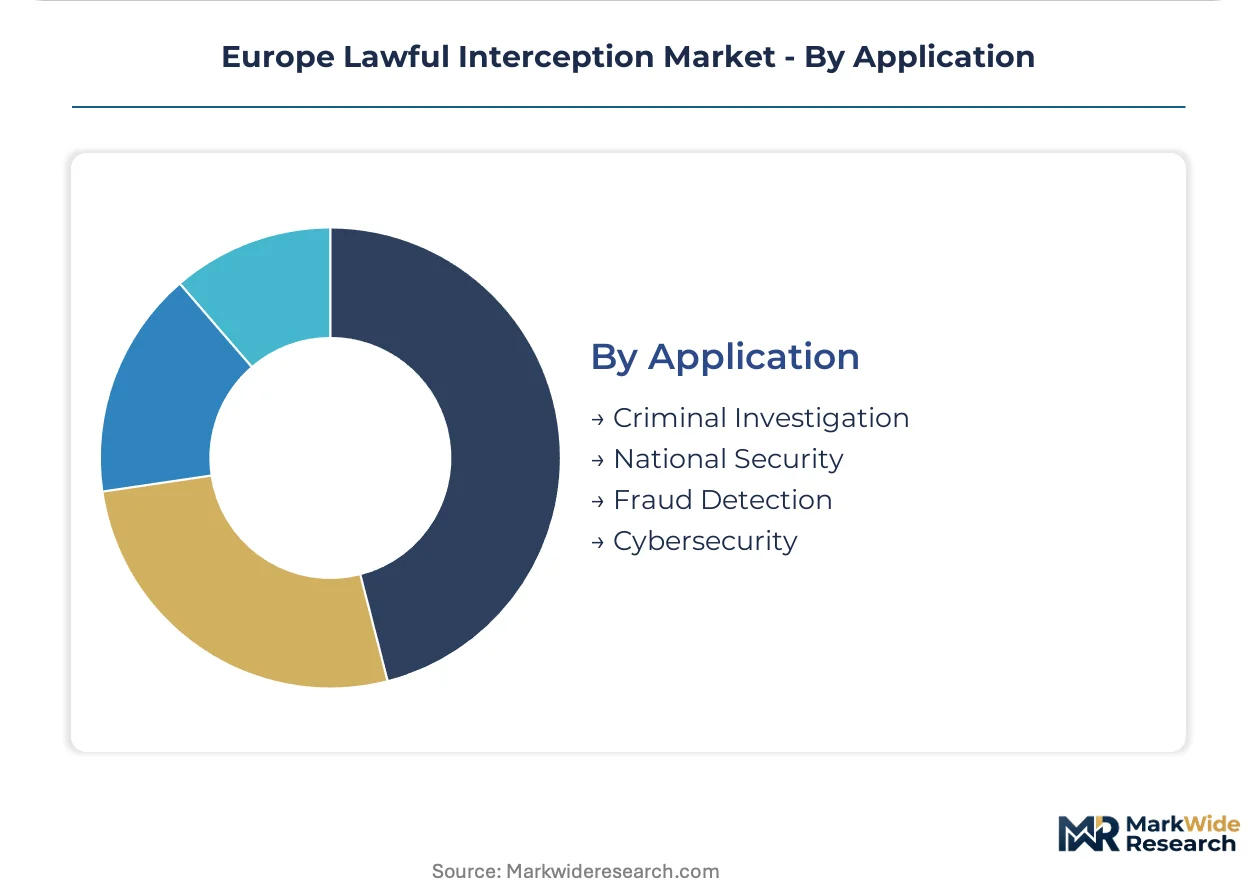
Application:
Operational tempo and judicial oversight stringency vary by mission type, driving differentiation in system response latency and documentation automation.
- National Security:Counterterrorism operations demand real-time intercept activation with automated metadata correlation across EUROPOL task force networks. Joint intelligence sharing protocols require timestamp synchronization standards.
- Criminal Investigation:Organized crime and drug trafficking cases drive investments in predictive targeting through AI-driven anomaly detection on historical intercept datasets.
- Cybersecurity:State-sponsored intrusion monitoring expands intercept scope to command-and-control traffic identification.
- Fraud Detection:Financial crime applications leverage metadata patterns without content-level interception, reducing judicial authorization complexity.
National security holds the largest share; criminal investigation shows the steepest expansion trajectory as encryption proliferation forces analytical capability upgrades.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The EU's updated ePrivacy Directive and national transpositions across member states mandate telecommunications providers to maintain intercept-ready infrastructure, creating sustained procurement demand from Berlin to Rome.
Germany
The Federal Criminal Police Office and domestic intelligence services drive investments in next-generation packet-switched interception systems. Germany's Telecommunications Act requires network operators to engineer intercept capabilities from the design phase, with BSI certification timelines extending vendor qualification cycles. Berlin anchors the largest concentration of secure processing facilities for classified intercept operations.
France
Mobile operators require lawful interception overlays for 4G/5G packet-switched voice and data sessions as network densification accelerates. France's LCEN framework mandates intercept capability preservation across virtualization migrations, with functional equivalence requirements for legacy and next-generation handover interfaces. Paris hosts the domestic intelligence services that pioneered bundled managed service procurement models now spreading southward.
United Kingdom
Intelligence community frameworks set integration standards for bespoke architectures with air-gapped classified processing. UK agencies demand specialized chain-of-custody protocols and deep system integration that narrow the competitive field to vendors with sovereign security clearances. London concentrates the technical workforce for SS7, Diameter, and 5G core protocol expertise.
Italy
The Ministry of Interior maintains the largest facility footprint in Southern Europe for centralized intercept management. Italian procurement follows French and Spanish adoption of multi-year managed service contracts bundling maintenance, compliance audits, and operator training. Rome anchors counterterrorism coordination with EUROPOL task forces requiring cross-border timestamp synchronization.
Poland
Underpenetrated intercept infrastructure relative to Western European maturity opens greenfield deployment windows for packet-switched and mobile data systems. Polish agencies seek elastic compute for storage-intensive analytics while retaining classified processing on-premise under emerging EU Cybersecurity Act certification pathways. Warsaw represents the fastest-expanding procurement frontier for hybrid cloud-hybrid architectures.
Europe Lawful Interception Market Key Industry Players
On the supply side, the industry is consolidating around vendors with sovereign security clearances and long-term service contracts, compressing the competitive field to three strategic tiers. National champions with domestic engineering bases leverage BSI and intelligence community certifications to dominate public-sector procurement. Telecom equipment incumbents extend installed bases into lawful interception overlays for mobile operators. Specialized intercept vendors compete through ETSI-compliant handover interfaces and 3GPP specification expertise. Dominant competitive moves include multi-year managed service bundling and cloud-hybrid architecture certification.
Within the national champion tier, Utimaco GmbH and BAE Systems exemplify divergent geographic anchoring strategies. Utimaco leverages its German engineering base and BSI certifications to dominate domestic public-sector procurement, while BAE Systems anchors its position through deep integration with UK intelligence community frameworks. Ericsson represents the telecom equipment incumbent archetype, extending its mobile network installed base into lawful interception overlays for European operators. These three companies illustrate how certification pathways and customer relationship structures determine competitive positioning.
| Leading Market Players |
|---|
| Utimaco GmbH |
| BAE Systems |
| Ericsson |
| Matison |
| AQSACOM |
| Verint Systems |
| SS8 Networks |
| Cisco Systems |
| Vocal Technologies |
| Others |
Cost & Logistics Intelligence
Undercapacity in specialized packet-processing ASIC fabrication across East Asian foundries compresses supplier margins while elevating pricing power for BSI-certified vendors serving German Federal Criminal Police Office procurement cycles. This utilization squeeze forces buyers into longer contract lock-ins and accelerates the shift toward managed service bundles that smooth capital expenditure spikes.
Pricing Analysis
Certification level creates the primary spread between domestic champions and non-compliant vendors, with BSI-approved systems commanding substantial premiums over ETSI-only alternatives. Three-tier pricing structure across premium, standard, and economy levels reflects handover interface complexity, cloud-hybrid integration depth, and bundled compliance audit coverage. Price erosion runs through the standard tier as Ericsson and telecom equipment incumbents leverage installed base relationships. Intelligence services show the lowest price sensitivity due to bespoke architecture requirements, while telecommunications providers face acute pressure from regulatory-mandated intercept readiness obligations.
Supply Chain Analysis
Specialized semiconductor feedstock draws from Taiwan, South Korea, and Japan, with packet-processing ASICs and cryptographic acceleration modules concentrated among a handful of foundry operators. Deep packet inspection engines rest on FPGA substrates, high-speed memory buffers, and precision timing components. Single-source vulnerability in East Asian foundry capacity exposes delivery timelines to geopolitical friction. Distribution runs through direct vendor-to-agency contracting for classified systems, with telecommunications providers procuring through equipment-integrated overlays.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Managed service contracts expanding faster than hardware sales signal a durable service-attach opportunity, as agencies outsource compliance audits, operator training, and certification maintenance to narrow their internal technical capacity gaps.
For Market Incumbents: Insulate core relationships by embedding deeper into UK intelligence community frameworks and German BSI certification pathways before emerging cloud-native vendors achieve equivalent security clearances. Prioritize backward integration into specialized packet-processing component supply to offset East Asian foundry concentration. Capture recurring revenue through multi-year managed service bundling that locks out competitors.
For New Entrants and Emerging Players: Poland and the Baltic states present the most penetrable intercept infrastructure relative to Western European maturity, with greenfield deployment windows for hybrid cloud-hybrid architectures. Target telecommunications providers in Southern Europe seeking elastic compute for storage-intensive analytics without classified processing expertise. Enter through ETSI-compliant handover interface specialization that satisfies France's LCEN functional equivalence mandates.
For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among vendors with sovereign security clearances and long-term government leasing arrangements. Long-term viability hinges on certification moats deepening through EU Cybersecurity Act expansion and national encryption-debate outcomes. Monitor proposed backdoor architecture mandates as inflection signals that would reshape liability models and vendor qualification barriers.
| Strategic Initiative | Industry Significance |
|---|---|
| Managed Service Contract Bundling | France's domestic intelligence services pioneered this procurement model now spreading to Spain and Italy. |
| Cloud-Hybrid Architecture Certification | EU Cybersecurity Act pathways enable compliant classified processing alongside elastic cloud analytics. |
| BSI Certification Investment | German Federal Office for Information Security approval narrows competitive fields to qualified vendors. |
| Deep Integration with Intelligence Frameworks | UK intelligence community standards demand bespoke architectures with air-gapped processing environments. |
| Virtualized Network Function Deployment | French and German mobile carriers deploy software-defined intercept points at 5G standalone core nodes. |
Research Approach
Operator-level perspectives from telecommunications network engineers, security agency procurement officers, lawful intercept system integrators, and BSI certification auditors anchored the qualitative base. Primary fieldwork combined structured interviews with secondary validation against ETSI technical specifications, 3GPP lawful interception documentation, and national transpositions of the ePrivacy Directive across Germany, France, and Italy. Customs data on specialized telecommunications equipment, SEC filings from exposed vendors, and EU regulatory proposal tracking supplied quantitative boundaries. Bottom-up deployment modeling and top-down market sizing triangulated volume estimates.
Scenario-bracketing framed projections across encryption proliferation, backdoor mandate adoption, and cloud-hybrid migration speed. Segmentation dimensions spanned technology architecture, end-user sophistication, deployment model, and application mission type. CAGRs derived from fitted adoption curves against historical procurement cycles and regulatory compliance deadlines. Forecast inputs incorporated 5G standalone core rollout schedules and EUROPOL task force expansion patterns.
The forecast holds incumbent behavior within observed patterns; aggressive cloud-native entry or sovereign foundry capacity buildout would shift outcomes. Encryption-debate resolution and EU Cybersecurity Act implementation pace constitute primary revision risks. Quarterly review of BSI certification queue lengths and Polish procurement tender releases is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Security Software
Global Email Verification Tools Market
Security Software
Secure Web Gateway Market
Security Software
Quantum Key Distribution System Market
Security Software
Global Cloud IAM Market
Security Software
United States Lawful Interception Market
Security Software
Stalkerware Market
Security Software
Cybersecurity Software Market
Security Software
Global Mobile Identification Market
Security Software
Global Reputation Protection Software Market
Security Software
Network Security Appliance Market
Security Software
Europe IP Video Intercom Device and Equipment Market
Security Software
Software Assurance Market
Security Software
Global Consumer IAM Market
Security Software
Global IMSI Catcher Market
Security Software
Smart Video Doorbell Market
Security Software
Security Information and Event Management Software Market