
 Data Loss Prevention Market | 2026-2036
Data Loss Prevention Market Size, Share, and Industry Trends Forecast 2026-2036
Data Loss Prevention Market Intelligence
A scarcity of trained cybersecurity analysts capable of managing complex policy engines is rotating the market towards AI-driven and managed service models. Microsoft Purview leverages its deep integration within the Azure and Office 365 ecosystems to offer a unified data governance solution. Forcepoint DLP specializes in behavior-based analytics to identify and mitigate insider threats before data exfiltration occurs. Trellix competes by offering a broad XDR platform that incorporates advanced DLP capabilities.
Data loss prevention comprises a set of tools and processes designed to ensure that sensitive data is not lost, misused, or accessed by unauthorized users. These systems use techniques like content inspection and contextual analysis to classify and protect data in use, in motion, and at rest. Within solution types, Endpoint DLP remains a foundational component, while Cloud DLP represents the fastest-growing segment due to cloud migration. Regulatory Compliance and Intellectual Property Protection dominate application segments, driven by high financial and reputational risks.
The EU's General Data Protection Regulation (GDPR) imposes strict breach notification requirements and fines, directly compelling investment in DLP. Similarly, the Health Insurance Portability and Accountability Act (HIPAA) in the United States and China's Cybersecurity Law (CSL) mandate stringent controls over personal and sensitive information. Vendor selection will increasingly hinge on a platform’s ability to automate policy enforcement and reduce the burden on security operations teams.
Market Dynamics
The convergence of stringent regulatory mandates and a persistent cybersecurity skills shortage is the central force shaping the Data Loss Prevention market. This dynamic pressures organizations to adopt more automated and intelligent solutions, moving away from manually intensive, rule-based systems toward platforms that reduce operational burdens.
Growth Catalysts
- Regulatory Mandates:The enforcement of comprehensive data privacy laws, including Europe's GDPR and China's CSL, creates a non-negotiable requirement for organizations to monitor, classify, and control the flow of sensitive personal information, directly compelling investment in DLP solutions.
- BFSI Sector Adoption:The banking, financial services, and insurance sector faces exceptionally high financial and reputational risks from data breaches, driving sustained demand for advanced DLP capabilities to protect customer financial data and comply with industry-specific regulations.
- Cloud Migration:The rapid enterprise shift of workloads and sensitive data to public and hybrid cloud environments necessitates specialized Cloud DLP solutions that can enforce policies across platforms like Azure and AWS, a segment which represents the fastest-growing.
Market Restraints
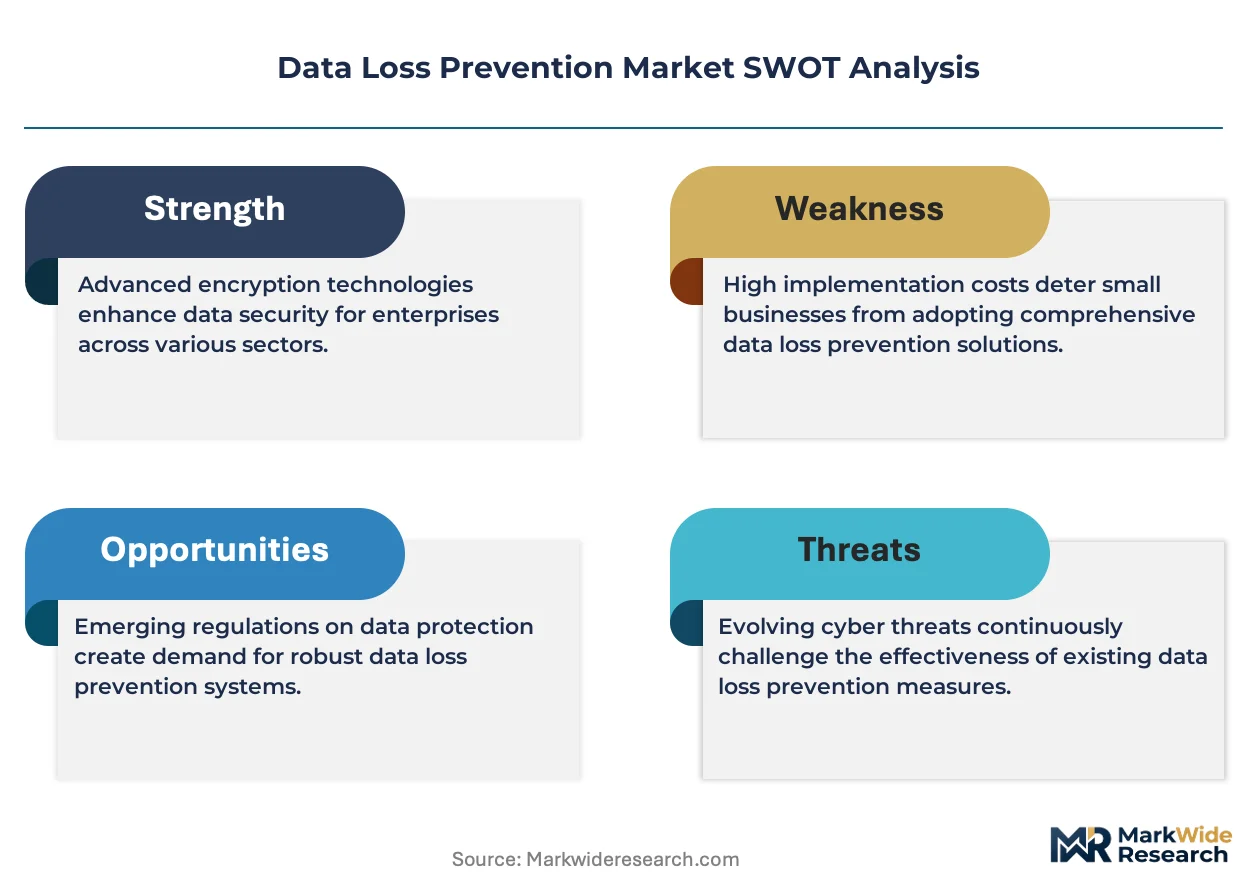
- High Implementation Cost:The significant initial investment required for enterprise-wide DLP deployment, including software licenses, hardware infrastructure, and professional integration services, can be a major barrier for small and medium-sized enterprises.
- Operational Complexity:Configuring and fine-tuning DLP policy engines to minimize false positives without creating security gaps is a complex, ongoing task that demands specialized expertise, often leading to alert fatigue and inefficient security operations.
- Integration with Legacy Systems:Integrating modern DLP solutions with older, disparate IT infrastructure presents significant technical hurdles, frequently requiring custom development that extends deployment timelines and increases total cost of ownership.
Strategic Opportunities
- AI-Driven Policy Automation:Developing AI and machine learning capabilities to automate policy creation, enforcement, and incident triage can dramatically reduce the reliance on scarce cybersecurity talent and lower the operational overhead for security teams.
- Managed DLP Services for SMEs:Offering turnkey, subscription-based managed DLP services provides a cost-effective solution for small and medium-sized enterprises that lack the in-house cybersecurity expertise and resources to manage complex platforms themselves.
- Intellectual Property Protection:Extending DLP focus beyond personal data to protect sensitive intellectual property, such as design schematics and R&D data within the manufacturing and technology sectors, offers a significant growth avenue.
Industry Challenges
- Cybersecurity Skills Gap:A persistent shortage of security analysts trained to manage complex DLP policies, investigate alerts, and respond to incidents effectively limits the value organizations can derive from their technology investments.
- Balancing Security and Productivity:Implementing overly restrictive DLP policies can hinder employee productivity and legitimate business processes, leading users to find workarounds that may bypass security controls entirely and create shadow IT risks.
- Evolving Threat Landscape:Data exfiltration techniques are constantly evolving, with attackers using sophisticated methods to bypass traditional defenses, requiring DLP vendors to continuously update their threat intelligence and detection capabilities.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Data Loss Prevention Market |
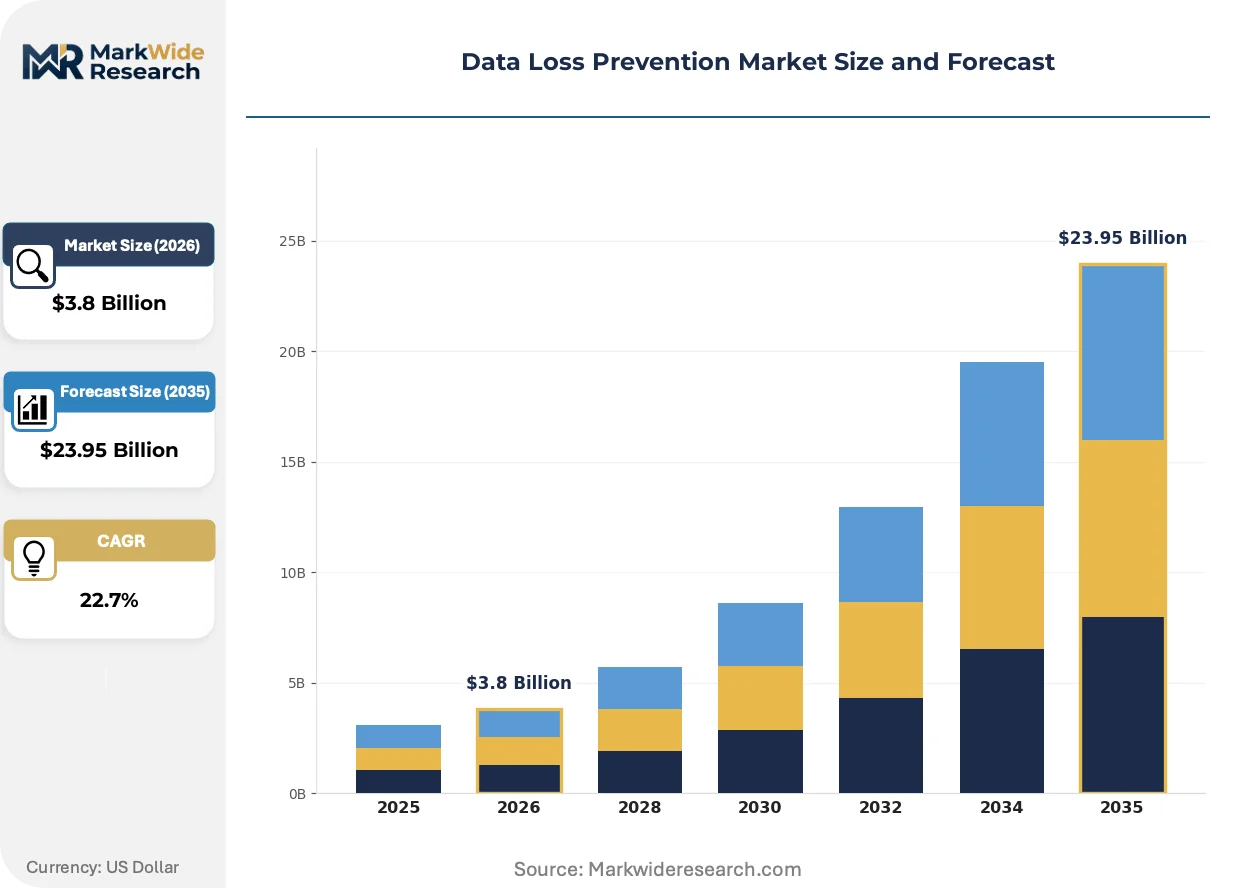
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $23.95 Billion |
| CAGR (2026 – 2036) | 22.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Deployment: On-Premises, Cloud-Based, Hybrid, Virtual Appliance Solution Type: Network DLP, Endpoint DLP, Cloud DLP, Storage DLP, Discovery DLP Application: Regulatory Compliance, Insider Threat Protection, Intellectual Property Protection, Data Monitoring, Access Control End User: BFSI, Government Agencies, Telecom Operators, IT & Telecom, Energy & Utilities |
| Companies Covered | Digital Guardian, Trellix, Forcepoint DLP, Cyberhaven, Trend Micro, Symantec DLP, Proofpoint DLP, Teramind, Microsoft Purview, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Data Loss Prevention Market Strategic Shifts & Innovations
The market's evolution is defined by a decisive shift from static, reactive data protection to proactive, context-aware security postures. This transition is driven by the need to manage data across increasingly complex and distributed IT environments, from on-premise servers to multi-cloud deployments and countless endpoint devices.
Behavior-based analytics, powered by machine learning, function by establishing a baseline of normal user and system activity to detect anomalies indicative of a threat. Financial services and healthcare organizations are rapidly adopting these systems to combat sophisticated insider threats. This proactive, context-aware approach is displacing traditional static, signature-based rule sets that are ineffective against novel or zero-day threats.
Europe’s General Data Protection Regulation (GDPR) set a global precedent for data privacy, influencing legislation worldwide. Its strict breach notification rules and potential for substantial fines directly mandate investment in tools that can discover, classify, and protect personal data. The healthcare and retail sectors, which handle vast amounts of consumer data, are most affected and are prioritizing DLP systems that provide robust GDPR compliance reporting.
Enterprises are moving away from procuring standalone DLP point solutions toward adopting integrated data security platforms or managed security services. This shift reflects a demand for unified visibility and simplified management, disrupting the traditional model of purchasing separate tools for endpoint, network, and cloud. This trend is most prominent in mid-market companies in North America and Europe that lack large, dedicated security operations teams.
Data Loss Prevention Market Segmentation
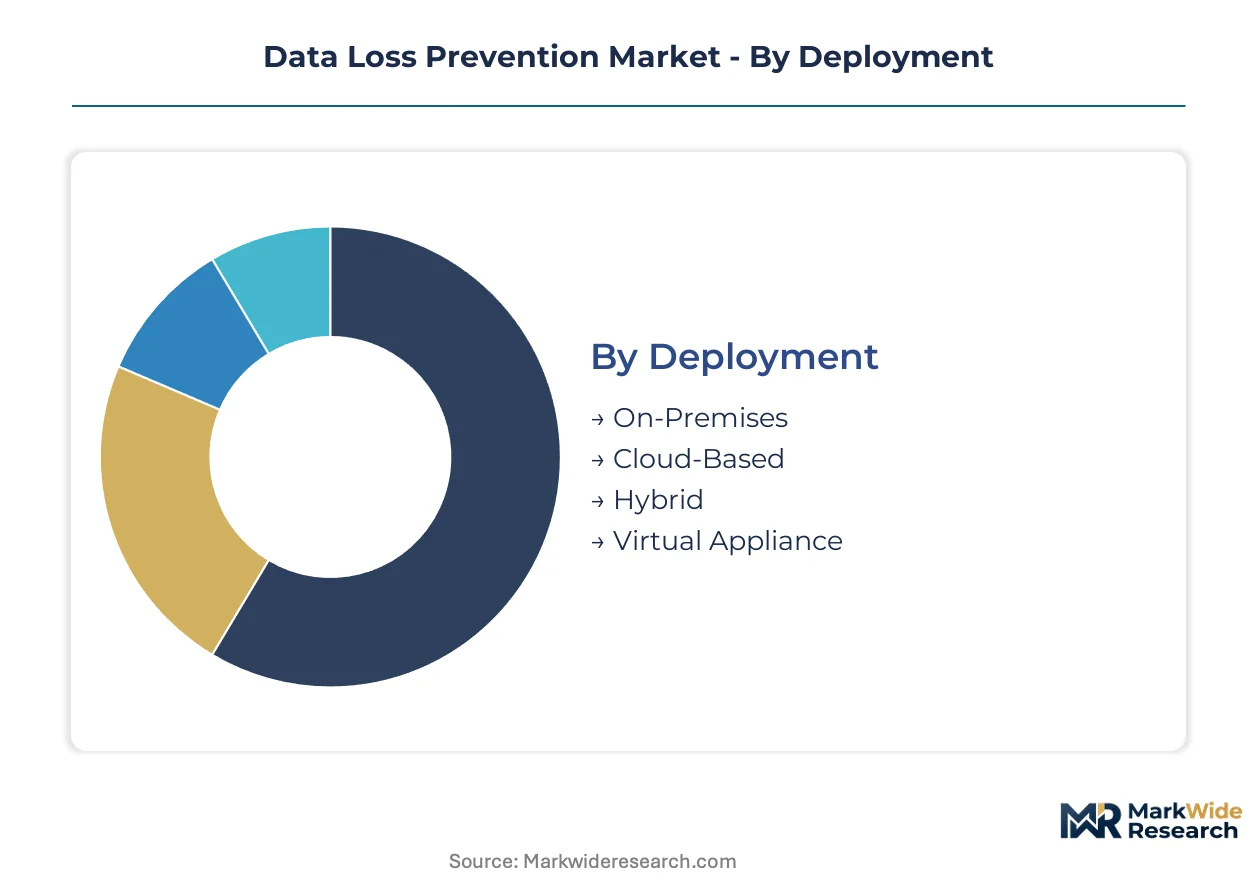
The Data Loss Prevention market exhibits distinct segments driven by evolving deployment models and diverse organizational needs. Understanding these classifications reveals how enterprises deploy solutions to safeguard sensitive information effectively across varied IT environments.
Deployment:
Regulatory bodies often dictate the permissible deployment architectures for data protection, influencing how organizations implement DLP solutions.
- Cloud-Based:Cloud-Based DLP systems protect sensitive data residing in public cloud environments, SaaS applications, and IaaS platforms by enforcing policies directly within the cloud provider's infrastructure. Demand for these solutions is concentrating in the United States, driven by the widespread migration of financial and healthcare data to platforms like Azure and AWS.
- Hybrid:Hybrid DLP integrates on-premises and cloud-based controls, creating a unified data protection strategy across complex, distributed IT landscapes. European organizations increasingly adopt hybrid models to comply with GDPR data residency requirements while leveraging cloud scalability.
- On-Premises:On-Premises DLP solutions involve deploying hardware and software within an organization's own data center, offering complete control over data and infrastructure.
- Virtual Appliance:Virtual Appliance DLP delivers DLP capabilities through software-based virtual machines, simplifying deployment and management within virtualized environments.
On-Premises DLP handles the majority of throughput; Cloud-Based DLP is the fastest mover on share.
Solution Type:
The functional application of DLP technologies varies significantly, reflecting different attack vectors and data states that require protection.
- Cloud DLP:Cloud DLP specifically safeguards data within cloud services, monitoring information as it moves to, from, and within cloud platforms. This segment represents the fastest-growing trajectory, as enterprises increasingly store critical data in public and hybrid cloud environments.
- Endpoint DLP:Endpoint DLP monitors and controls data on user devices such as laptops, desktops, and mobile phones, preventing unauthorized data transfers or exfiltration. Financial institutions prioritize Endpoint DLP to protect customer records even when devices are offline or outside the corporate network.
- Network DLP:Network DLP inspects data traversing network egress points, identifying and blocking sensitive information leaving the organization's perimeter.
- Storage DLP:Storage DLP scans data at rest in file shares, databases, and cloud storage, discovering and classifying sensitive content for remediation.
- Discovery DLP:Discovery DLP identifies sensitive data across an organization's entire infrastructure, including unstructured and structured data sources, to assess risk posture.
Endpoint DLP forms the foundational layer for most deployments; Cloud DLP expands most quickly.
Application:
Different organizational risk profiles and compliance obligations drive the specific applications of data loss prevention capabilities.
- Regulatory Compliance:Regulatory Compliance applications ensure adherence to data protection laws like Europe's GDPR and the US HIPAA, automating the identification and safeguarding of personal and sensitive information. The BFSI sector heavily invests in this application to avoid substantial fines and reputational damage from breaches.
- Intellectual Property Protection:Intellectual Property Protection focuses on preventing the unauthorized disclosure of proprietary designs, trade secrets, and research data. Technology and manufacturing firms in China prioritize this application to secure their competitive advantage against industrial espionage.
- Insider Threat Protection:Insider Threat Protection detects malicious or accidental data exfiltration by employees, contractors, or partners through behavior-based analytics.
- Data Monitoring:Data Monitoring provides real-time visibility into data movement and access patterns across various systems, enabling proactive threat detection.
- Access Control:Access Control ensures only authorized users can interact with sensitive data, enforcing granular permissions based on roles and contexts.
Regulatory Compliance applications command the largest market share; Intellectual Property Protection shows a steep expansion trajectory.
End User:
The volume and sensitivity of data handled by various industries directly influence their adoption patterns for data loss prevention solutions.
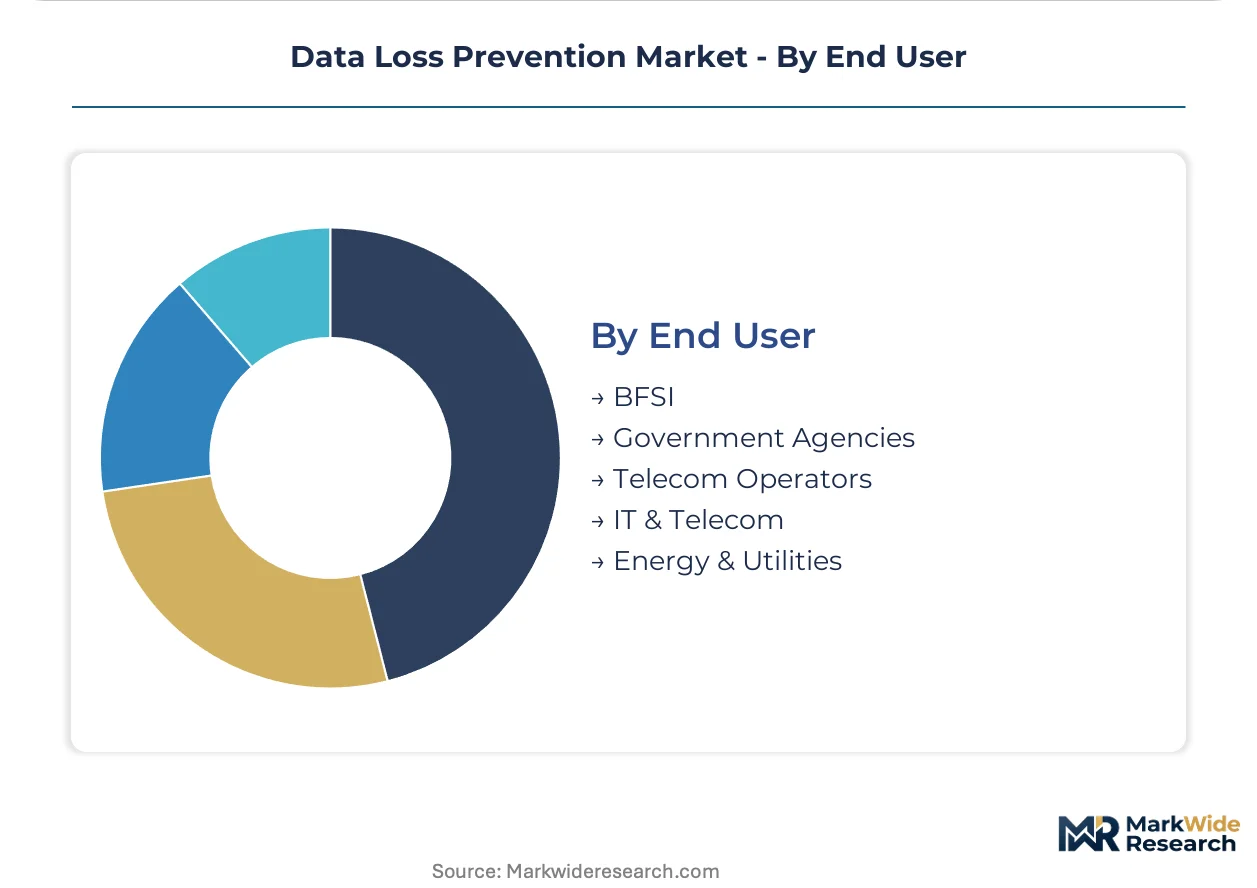
- BFSI:The Banking, Financial Services, and Insurance sector implements comprehensive DLP to protect vast amounts of customer financial data, comply with regulations like PCI DSS, and mitigate fraud risks. Organizations in the United States within this sector are major adopters of advanced DLP solutions.
- IT & Telecom:The IT & Telecom sector deploys DLP to secure intellectual property, customer data, and network infrastructure from breaches and insider threats. This sector in India increasingly adopts Cloud DLP to protect data across complex network architectures and service offerings.
- Government Agencies:Government Agencies utilize DLP to protect classified information, citizen data, and national security assets from cyber threats and unauthorized access.
- Telecom Operators:Telecom Operators leverage DLP to safeguard subscriber data, billing information, and network configurations against misuse and regulatory non-compliance.
- Energy & Utilities:Energy & Utilities firms employ DLP to protect critical infrastructure data, operational technology information, and customer records from cyberattacks.
The BFSI sector drives the highest revenue; the IT & Telecom sector demonstrates the fastest growth in new deployments.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Health Insurance Portability and Accountability Act (HIPAA) significantly drives demand for data loss prevention solutions across the United States. This legislation compels organizations to secure sensitive information. Enterprises globally are investing in DLP to manage complex regulatory environments and mitigate data breach risks.
United States
Demand for advanced DLP solutions in the United States concentrates within financial and healthcare firms. HIPAA mandates stringent controls over personal health information, directly compelling investment. Major financial hubs like New York City are rapidly adopting Cloud DLP to protect sensitive customer data.
Germany
Europe's General Data Protection Regulation (GDPR) profoundly influences data protection strategies for German organizations. The regulation imposes strict breach notification requirements and substantial fines, driving comprehensive DLP adoption. Industrial centers such as Bavaria prioritize DLP for both regulatory compliance and intellectual property protection.
China
China's Cybersecurity Law (CSL) and Personal Information Protection Law (PIPL) compel stringent data governance within Chinese enterprises. These regulations mandate robust controls over sensitive information for technology and manufacturing firms. Shenzhen and Shanghai, as key technology hubs, see increased investment in DLP to secure proprietary designs.
India
The rapid growth of the IT & Telecom sector in India accelerates data loss prevention technology adoption. The upcoming Digital Personal Data Protection Act will further strengthen data privacy requirements. Bengaluru and Hyderabad, as major IT centers, experience high demand for Cloud DLP to protect customer data.
Japan
Japan's Act on Protection of Personal Information (APPI) drives the need for sophisticated data loss prevention within Japanese businesses. This legislation emphasizes secure handling of personal data, influencing financial services and technology sectors. Tokyo's financial district implements behavior-based analytics to combat insider threats.
Data Loss Prevention Market Key Industry Players
Technology leadership and cost leadership are held by different player archetypes within the data loss prevention market. The market exhibits a tiered structure, with established cybersecurity vendors alongside specialized DLP providers. Strategic archetypes include integrated platform providers, niche behavior-based analytics specialists, and managed service providers. Competitive moves often involve strategic partnerships to broaden ecosystem integration and continuous innovation in AI-driven automation.
Integrated platform providers, exemplified by Microsoft Purview, leverage extensive ecosystem integration to offer unified data governance solutions. Security specialists such as Forcepoint DLP anchor the market for behavior-based analytics, focusing on insider threat mitigation before data exfiltration. Trellix, another prominent vendor, represents firms offering broad XDR platforms that incorporate advanced DLP capabilities for comprehensive security postures. These companies collectively demonstrate the market's shift towards automated and intelligent solutions, reducing operational burdens on security teams.
| Leading Market Players |
|---|
| Digital Guardian |
| Trellix |
| Forcepoint DLP |
| Cyberhaven |
| Trend Micro |
| Symantec DLP |
| Proofpoint DLP |
| Teramind |
| Microsoft Purview |
| Others |
Cost & Logistics Intelligence
Europe's GDPR mandates comprehensive data protection, directly gating the qualification of DLP solution providers and influencing pricing structures based on compliance assurance and robust capabilities.
Pricing Analysis
Pricing structures for Data Loss Prevention solutions exhibit regional variations, with higher average costs observed in North America and Europe. The dominant pricing model is subscription-based, often tiered by user count or data volume. Customization levels for complex policy engines and comprehensive after-sales managed services drive significant price differentiation. Pricing softness reflects intensifying competition from integrated platforms and emerging managed service providers. Small and medium-sized enterprises remain the most price-sensitive buyers, contrasting with large financial institutions.
Supply Chain Analysis
Deployment complexity and integration lead times for Data Loss Prevention solutions vary significantly based on organizational infrastructure. Supply concentration resides primarily in the United States, home to major platform providers, alongside development hubs in India. The market draws from a talent pool of cybersecurity experts and relies on advanced AI/ML algorithms and cloud infrastructure components. A key structural risk involves the persistent cybersecurity skills gap, complicating effective solution deployment. Distribution runs through a hybrid model, combining direct enterprise sales with extensive channel partnerships and cloud marketplace offerings.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Data Loss Prevention market experiences a buyer power shift as enterprises consolidate security budgets onto unified data governance platforms.
For Market Incumbents: Secure existing enterprise accounts by deepening integration within broader security ecosystems like XDR platforms. Secure market share against evolving insider threats through continuous investment in behavior-based analytics and AI-driven automation. This strategy addresses the threat of niche specialists and the persistent cybersecurity skills gap by reducing operational burdens. Further investment in cloud-native DLP capabilities will protect against cloud migration risks.
For New Entrants and Emerging Players: Anchor in underserved segments by offering specialized, AI-driven managed DLP services for small and medium-sized enterprises. Anchor in specific vertical applications like intellectual property protection for manufacturing firms in regions with high industrial espionage risk. The most penetrable segment remains mid-market companies in North America and Europe. A strong go-to-market angle involves subscription-based, easy-to-deploy cloud DLP solutions with automated policy management.
For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting upward across AI-driven policy automation and Cloud DLP solution development due to complex R&D. The long-term viability of the DLP market remains strong, driven by non-negotiable regulatory compliance and evolving threat landscapes. Acquisition targets should include niche providers specializing in behavior-based analytics and firms with strong cloud-native DLP integration capabilities. The signal to watch is the increasing consolidation of standalone DLP vendors into broader cybersecurity platforms.
| Strategic Initiative | Industry Significance |
|---|---|
| Expand Cloud DLP Capabilities | Protects sensitive data across rapidly migrating cloud environments for enterprises. |
| Invest in AI-driven Policy Automation | Reduces operational overhead and reliance on scarce cybersecurity talent for security teams. |
| Offer Managed DLP Services | Provides cost-effective, expert-managed solutions for small and medium-sized enterprises. |
| Deepen XDR Platform Integration | Delivers unified visibility and simplified management across diverse security tools. |
| Target Intellectual Property Protection | Addresses a significant growth avenue beyond personal data, especially in manufacturing. |
Research Approach
A standing panel of cybersecurity analysts, IT security managers, compliance officers, and cloud architects provided ongoing calibration for this study. This approach combined in-depth primary interviews with rigorous secondary validation using regulatory guidelines from GDPR and HIPAA, industry association reports, and vendor whitepapers. Bottom-up data aggregation and top-down market sizing ensured comprehensive triangulation.
Outputs underwent consistency checks against external cybersecurity spending benchmarks and regulatory compliance trends. The analytical framework modeled market dynamics across the forecast period, segmenting by deployment, solution type, application, and end-user industry. Compound annual growth rates were derived from historical data and projected impacts of cloud migration rates and evolving cybersecurity spending. Regulatory enforcement intensity served as a key forecast input.
Decision-makers should treat outputs as directional under base assumptions regarding regulatory stability and cybersecurity investment trends; material deviation would warrant model refresh. Forecasts reflect assumptions concerning the rapid evolution of the threat landscape and potential shifts in global economic conditions. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Security Software
Stalkerware Market
Security Software
Risk-Based Authentication (RBA) Market
Security Software
Global Consumer Identity and Access Management Market
Security Software
Parental Monitoring Software Market
Security Software
Intrusion Detection System / Intrusion Prevention System (IDS / IPS) Market
Security Software
Source Code Escrow Market
Security Software
Antivirus Software Market
Security Software
Mobile Threat Management Security Software Market
Security Software
Global Consumer IAM Market
Security Software
Public Key Infrastructure (PKI) Market
Security Software
DNS Protection Software Market
Security Software
Asia Pacific Anti Money Laundering Solutions Market
Security Software
Global Security Operation Center As a Service Market
Security Software
Asia Pacific Video Management System Market
Security Software
Internet Filter Software Market
Security Software
Digital Risk Protection Platform Market