
 Global Data Recovery Software Market | 2026-2036
Global Data Recovery Software Market Size, Share, and Industry Trends Forecast 2026-2036
Global Data Recovery Software Market Foresight
Market Context
Israel is rewriting its data protection infrastructure through expanded cybersecurity R&D clusters and sovereign cloud investments. Microsoft Corporation leverages its Azure ecosystem to anchor enterprise recovery workflows across hybrid environments. Veeam Software Group GmbH sustains dominance in virtual machine backup through specialized agentless architectures. IBM Corporation differentiates via quantum-safe encryption layers embedded in its recovery orchestration platform.
Technical Definition and Structural Segments
Global Data Recovery Software comprises algorithmic systems engineered to reconstruct corrupted, deleted, or encrypted digital assets from magnetic, solid-state, or tape-based storage media, typically supporting file systems including NTFS, APFS, ext4, and VMFS with block-level granularity. The primary commercial purpose centers on minimizing recovery time objectives and recovery point objectives for enterprise continuity planning. Cloud-based deployment leads absolute revenue contribution as organizations abandon capital-intensive tape libraries, while SSD recovery features command premium pricing due to proprietary controller-level reconstruction demands and flash translation layer complexity. Partition recovery functions occupy a mature, high-volume position among small and medium IT enterprises seeking low-cost disaster preparedness.
Regulatory Frame and Outlook
GDPR in Europe, HIPAA in the United States, and China's Personal Information Protection Law collectively mandate demonstrable data restoration capabilities with auditable recovery timelines, directly shaping procurement specifications and vendor qualification criteria. The EU AI Act and SEC cybersecurity disclosure rules further tighten accountability for data integrity failures in regulated sectors. Stakeholders must monitor evolving cross-border data localization mandates that threaten to fragment cloud recovery architectures and force territorial infrastructure duplication.
Market Dynamics
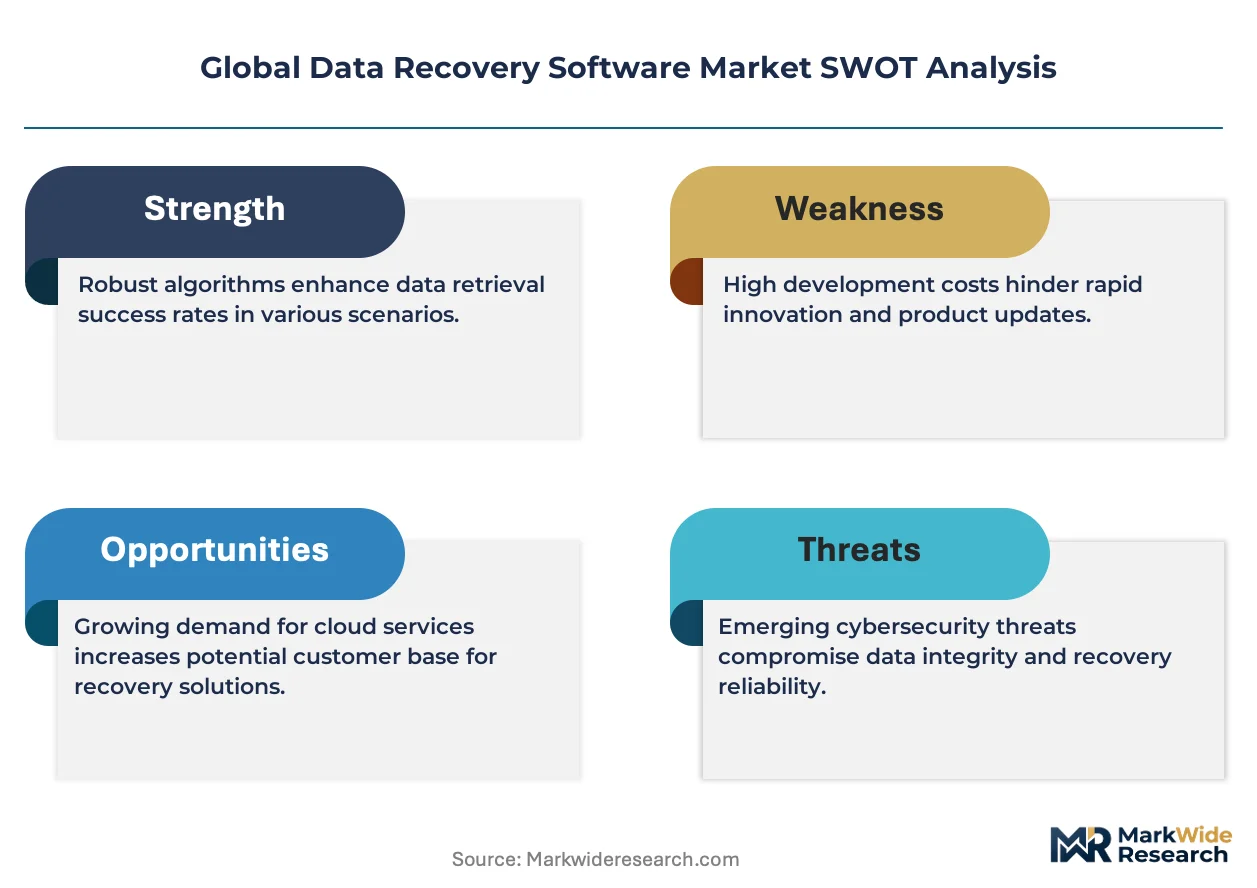
Ransomware frequency and GDPR audit intensity are compressing recovery time objectives, forcing enterprises to abandon tape-based archives for continuous data protection architectures with sub-hour restoration guarantees.
Growth Catalysts
- GDPR Article 32 mandates:European enterprises must demonstrate restoration capabilities with documented timelines, creating procurement urgency for automated recovery orchestration platforms.
- Healthcare digitization:HIPAA-covered entities in the United States face OCR enforcement actions for inadequate backup procedures, accelerating investment in immutable snapshot technologies.
- Flash storage proliferation:NAND controller complexity and wear-leveling algorithms drive premium demand for specialized SSD reconstruction tools.
Market Restraints
- Specialized engineering scarcity:Flash translation layer reverse-engineering requires rare firmware expertise concentrated in Taiwan and South Korea.
- Input cost volatility:Enterprise-grade NVMe arrays for recovery target infrastructure fluctuate with memory contract pricing.
- Regulatory friction:China's Personal Information Protection Law imposes cross-border transfer restrictions that complicate cloud-based disaster recovery architectures.
Strategic Opportunities
- India's sovereign cloud push:MeitY mandates data localization for government and financial sectors, creating demand for indigenous recovery infrastructure.
- Quantum-safe encryption convergence:NIST post-quantum cryptography standards intersect with backup integrity requirements, opening premium positioning for algorithmically agile vendors.
- Edge computing expansion:Manufacturing IoT deployments in Germany generate distributed recovery needs unmet by centralized enterprise tools.
Industry Challenges
- Firmware extraction expertise:Controller-level SSD recovery demands skills absent from standard computer science curricula.
- Legacy tape integration:Long-term archive migration projects stall on proprietary format obsolescence.
- ISO 27001 certification timelines:Recovery service providers face 12-18 month audit cycles that delay market entry.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Data Recovery Software Market |
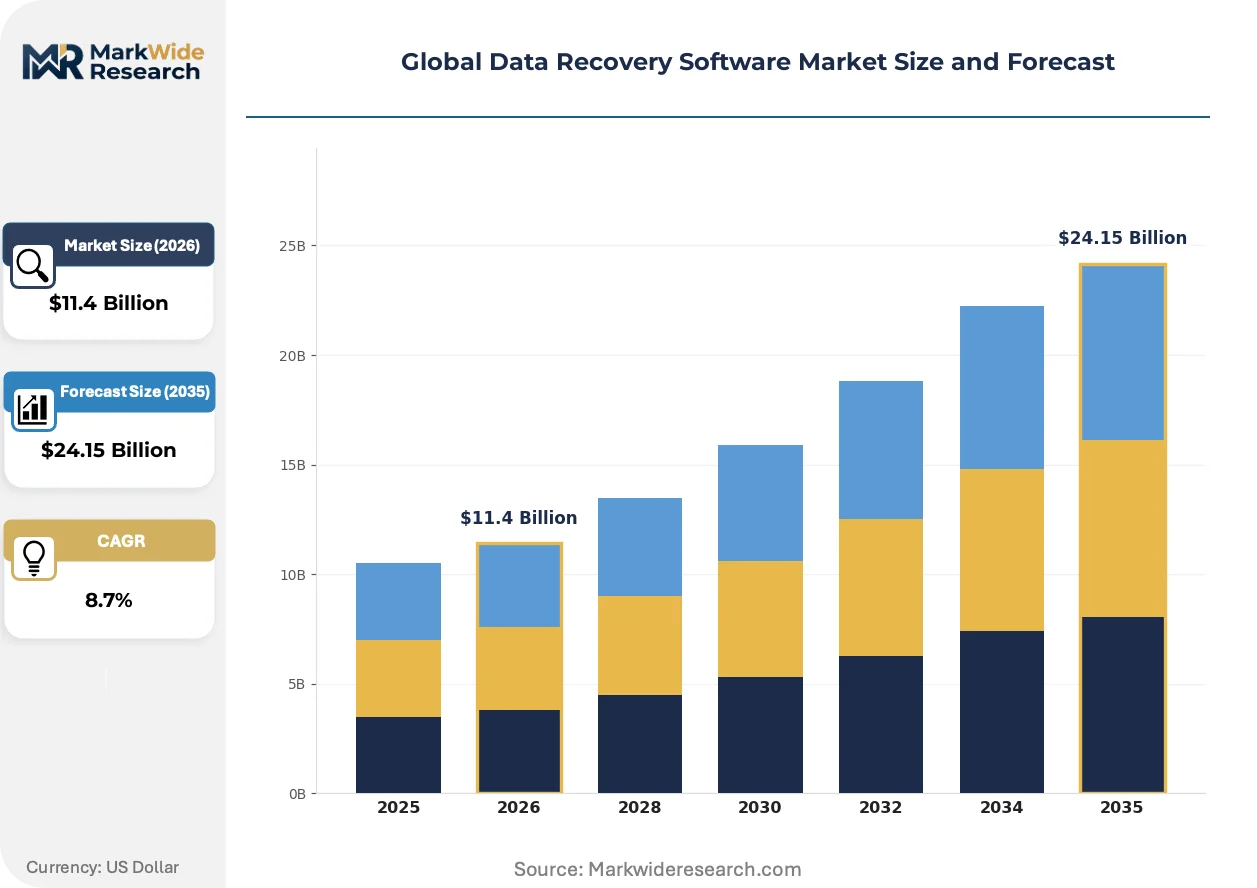
| Market Size in 2026 | $11.4 Billion |
| Market Size in 2035 | $24.15 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Deployment: On-Premise, Cloud-Based, Hybrid, Virtual Environment Data Type: Documents, Multimedia Files, Databases, Emails, Archives End User: IT Enterprises, Managed Service Providers, Government Agencies, Educational Institutions Feature: File Recovery, Partition Recovery, RAID Recovery, Mobile Device Recovery, SSD Recovery |
| Companies Covered | Acronis International GmbH, Microsoft Corporation, Veeam Software Group GmbH, IBM Corporation, Dell Technologies Inc., Veritas Technologies LLC, NetApp Inc., Cohesity Inc., Commvault Systems Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Data Recovery Software Market Shifts & Advancements
Agentless recovery architectures are displacing conventional backup agents, while regulatory pressure fuses compliance documentation directly into restoration workflows. Vendors race to embed immutability and encryption verification as standard features rather than premium modules.
Immutable snapshot technology is migrating from financial services compliance tools to standard enterprise offerings. Mid-market IT departments in Germany and the United States adopt air-gapped recovery targets at accelerating rates. This migration from niche to baseline functionality compresses pricing for basic recovery tiers while expanding premium attach rates for cryptographic verification.
EU AI Act documentation requirements now extend to automated recovery decision systems. Enterprises must maintain audit trails for algorithmic restoration prioritization. Financial services institutions in France and the Netherlands respond by demanding explainable AI modules from vendors, reshaping RFP specifications.
Consumption-based recovery pricing disrupts perpetual license models in the United States and United Kingdom. Enterprises prefer operational expenditure alignment with actual data volumes rather than capacity-based upfront commitments. Managed service providers capture margin by bundling storage, compute, and recovery orchestration into unified subscriptions.
Global Data Recovery Software Market Segmentation
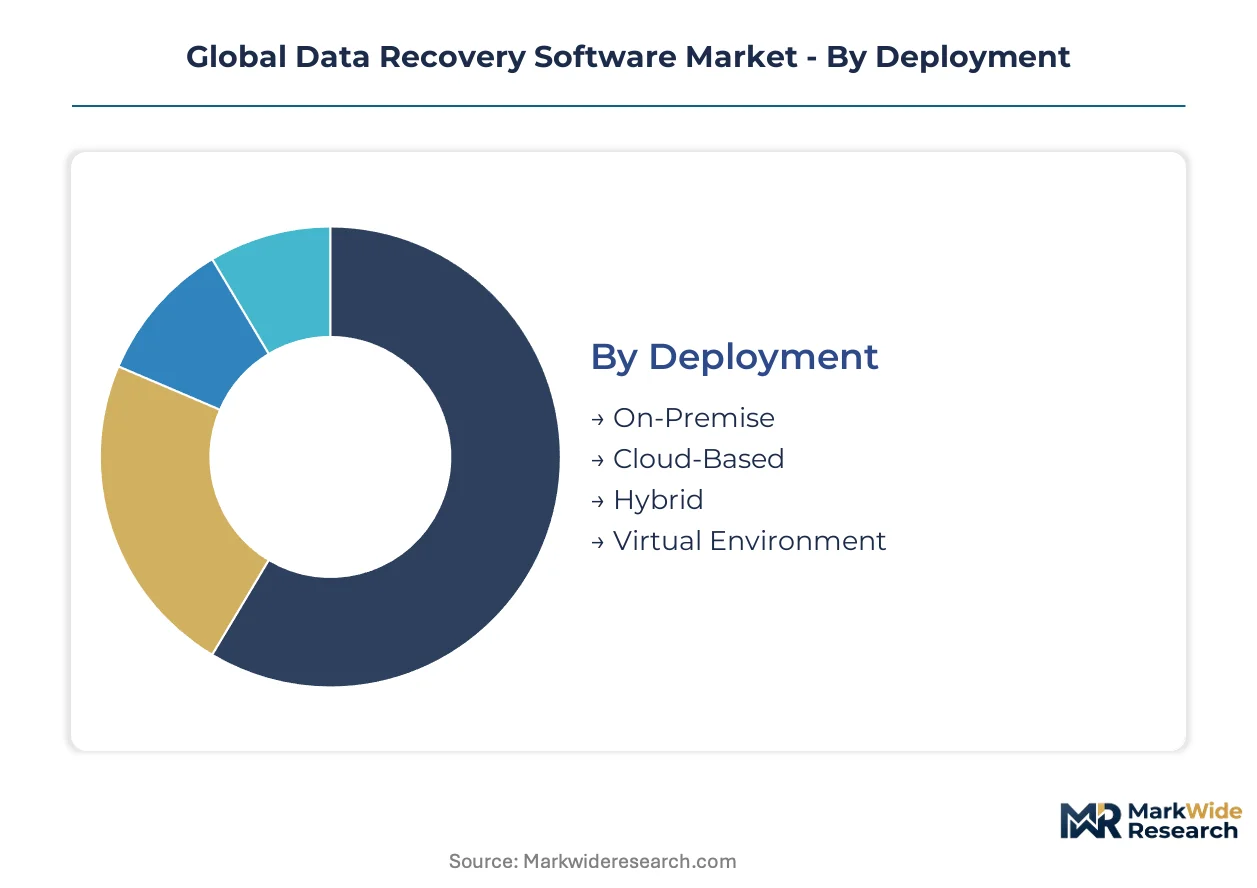
Segmentation in data recovery software reveals divergent procurement cycles across deployment architectures and feature complexity tiers. Cloud-based solutions refresh on 18-24 month subscription cycles while specialized SSD recovery tools command 5-7 year replacement horizons due to firmware engineering scarcity.
Deployment:
Cloud-based deployments turn over fastest through consumption-based billing, while on-premise infrastructure lingers in extended depreciation cycles.
- On-Premise:Perpetual-license architectures deployed within enterprise data centers demand dedicated hardware maintenance and internal IT staffing. Financial services institutions in Frankfurt and Singapore retain these systems for air-gapped compliance requirements despite higher capital intensity.
- Cloud-Based:Subscription models integrate directly with Azure, AWS, and Google Cloud storage tiers, enabling elastic scaling without hardware procurement delays. Healthcare providers across the United States accelerate migration here to satisfy HIPAA audit documentation through automated compliance dashboards.
- Hybrid:Architectures synchronize on-premise immutable snapshots with cloud tiering for ransomware resilience. Manufacturing clusters in Stuttgart and Detroit favor this model for operational technology isolation combined with enterprise backup consolidation.
- Virtual Environment:Agentless recovery for VMware, Hyper-V, and KVM hypervisors eliminates guest OS footprint. Managed service providers in London and Sydney standardize on these tools for multi-tenant infrastructure efficiency.
On-Premise anchors the volume base while Cloud-Based gains share at the steepest rate.
Data Type:
Recovery complexity and pricing stratify sharply across data categories, with structured databases commanding premium engineering support.
- Documents:Office productivity files, PDFs, and text formats constitute high-frequency, low-margin recovery volume. Small IT departments in India and Brazil prioritize these capabilities for basic business continuity preparedness.
- Multimedia Files:Video production studios and creative agencies in Los Angeles and Seoul drive specialized tools for corrupted codec reconstruction and timeline recovery. Storage controller failures in NVMe arrays disproportionately impact this segment.
- Databases:Oracle, SQL Server, and PostgreSQL transaction log replay demands granular point-in-time restoration. European banks under ECB supervision specify sub-15 minute recovery point objectives here.
- Emails:Microsoft Exchange and cloud mailbox recovery supports e-discovery and regulatory retention mandates. Legal departments in New York and London consume these features for litigation hold compliance.
- Archives:Long-term tape migration and cold storage retrieval face format obsolescence challenges. Government agencies in Canberra and Ottawa allocate budget for legacy media conversion services.
Databases generate the highest margin per recovery incident while Multimedia Files expand most quickly with content creation proliferation.
End User:
Procurement authority and technical sophistication vary dramatically across buyer categories, shaping sales cycle duration and support intensity.
- IT Enterprises:Internal infrastructure teams in Fortune 500 corporations negotiate enterprise agreements with embedded professional services. Ransomware response retainers now accompany core licensing in the United States and Germany.
- Managed Service Providers:Multi-tenant platforms demand white-label recovery portals and automated tenant isolation. MSPs in Manchester and Toronto consolidate vendor relationships to reduce integration overhead across heterogeneous client bases.
- Government Agencies:Sovereign cloud mandates and classified network requirements drive specialized procurement channels. India's MeitY certification and FedRAMP authorization in the United States create extended qualification timelines.
- Educational Institutions:Constrained budgets favor open-source tools or heavily discounted academic licensing. University IT departments in Melbourne and Amsterdam prioritize endpoint recovery for researcher workstation protection.
IT Enterprises dominate absolute spending while Managed Service Providers climb fastest as outsourcing accelerates.
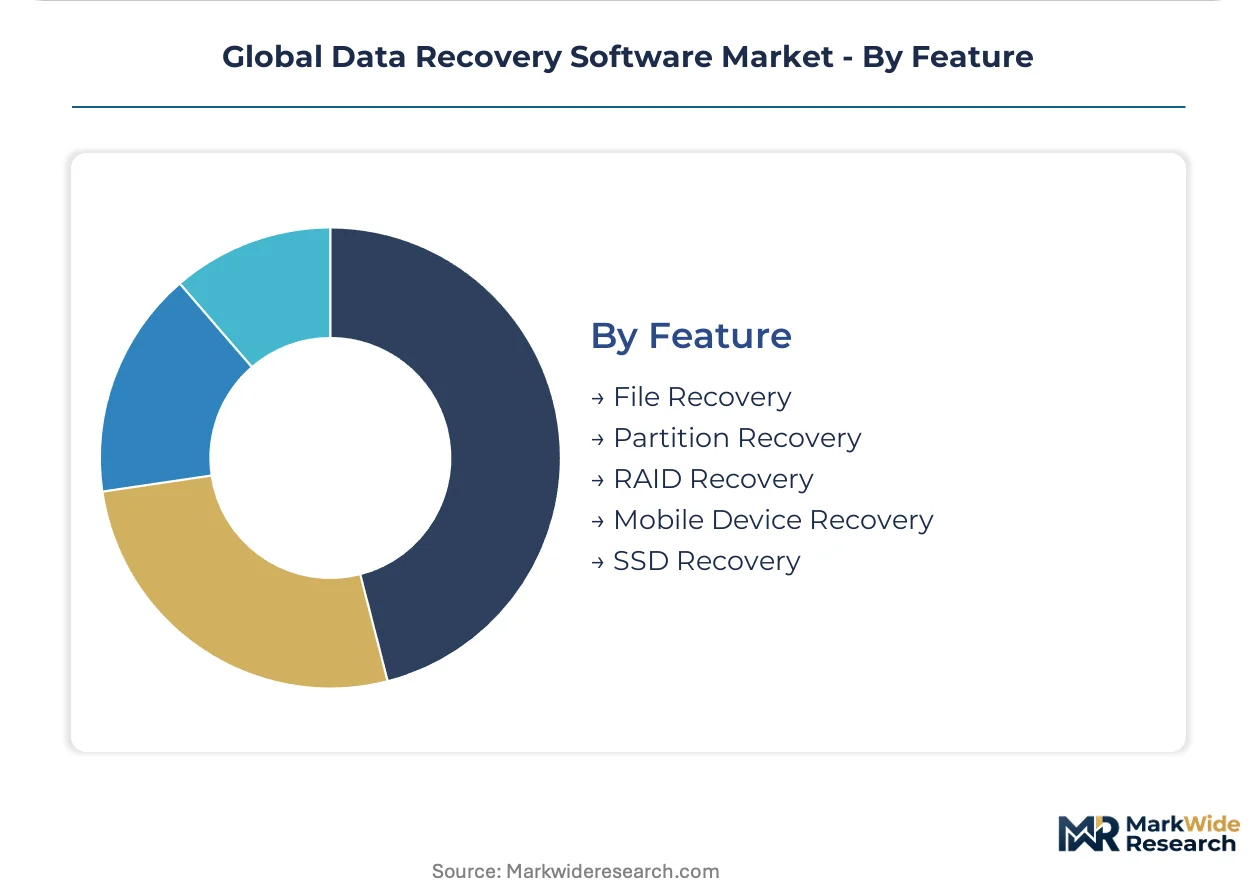
Feature:
Technical differentiation and pricing power concentrate in controller-level reconstruction capabilities.
- File Recovery:Basic undeletion and formatted drive reconstruction represents commoditized functionality. Consumer-grade tools saturate this tier with minimal vendor differentiation.
- Partition Recovery:Corrupted boot sector and partition table repair serves system administrators in small-to-mid enterprises. MBR and GPT reconstruction utilities remain standard in IT toolkit portfolios.
- RAID Recovery:Striping algorithm reconstruction for failed arrays demands proprietary parity calculation engines. Data centers in Singapore and Amsterdam deploy these for storage pool integrity assurance.
- Mobile Device Recovery:iOS and Android logical extraction supports law enforcement and corporate e-discovery. Israeli and South Korean vendors lead in chip-off forensics for damaged handsets.
- SSD Recovery:Flash translation layer reverse-engineering and wear-leveling bypass commands premium pricing. Controller firmware expertise concentrates in Taiwan and California engineering labs, limiting vendor supply.
File Recovery sustains the broadest installed base while SSD Recovery commands the steepest expansion trajectory as NAND deployment accelerates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
SEC cybersecurity disclosure rules compress recovery timelines for publicly traded enterprises. HIPAA enforcement actions from OCR accelerate immutable backup adoption across healthcare networks. GDPR Article 32 mandates drive procurement urgency for automated restoration platforms in European financial centers.
United States
Ransomware incident frequency forces sub-hour recovery point objectives across Fortune 500 infrastructure teams. HIPAA-covered entities face OCR enforcement actions for inadequate backup procedures, accelerating investment in immutable snapshot technologies. Healthcare providers in Nashville and Boston migrate to cloud-based recovery to satisfy audit documentation requirements through automated compliance dashboards.
Germany
Manufacturing IoT deployments in Stuttgart generate distributed recovery needs unmet by centralized enterprise tools. The EU AI Act documentation requirements extend to automated recovery decision systems, forcing audit trail maintenance for algorithmic restoration prioritization. Automotive suppliers in Bavaria adopt air-gapped recovery targets at accelerating rates for operational technology isolation.
India
MeitY mandates data localization for government and financial sectors, creating demand for indigenous recovery infrastructure. The country's sovereign cloud push requires extended certification timelines for recovery service providers entering public sector procurement channels. IT enterprises in Bangalore and Hyderabad expand backup infrastructure investments following rising ransomware incidents targeting financial services networks.
Israel
Expanded cybersecurity R&D clusters and sovereign cloud investments rewrite national data protection infrastructure. Mobile device recovery specialists concentrate in Tel Aviv and Haifa, serving law enforcement and corporate e-discovery demand for chip-off forensics. The country's national cyber regulator tightens accountability standards for data integrity failures in critical infrastructure sectors.
China
The Personal Information Protection Law imposes cross-border transfer restrictions that complicate cloud-based disaster recovery architectures. State-owned enterprises in Shenzhen and Beijing deploy hybrid architectures synchronizing on-premise immutable snapshots with domestic cloud tiering. Memory contract pricing volatility for enterprise-grade NVMe arrays influences recovery target infrastructure investment cycles.
Global Data Recovery Software Market Competitive Landscape
Capability concentration sits with specialized firmware engineering labs; scale advantage sits with hyperscale cloud platform operators. The vendor base organizes around three strategic archetypes: agentless virtual environment specialists, quantum-safe encryption integrators, and consumption-based managed service orchestrators. Dominant competitive moves include strategic partnerships with sovereign cloud providers and portfolio diversification into edge computing recovery modules.
Within the scale-driven tier, Microsoft Corporation and IBM Corporation anchor enterprise recovery workflows across hybrid environments. Veeam Software Group GmbH exemplifies the agentless architecture specialist archetype, occupying a position concentrated in virtual machine backup efficiency. These three entities represent divergent strategic vectors: hyperscale platform integration, quantum-safe encryption layering, and specialized hypervisor optimization.
| Leading Market Players |
|---|
| Acronis International GmbH |
| Microsoft Corporation |
| Veeam Software Group GmbH |
| IBM Corporation |
| Dell Technologies Inc. |
| Veritas Technologies LLC |
| NetApp Inc. |
| Cohesity Inc. |
| Commvault Systems Inc. |
| Others |
Supply & Pricing Matrix
Taiwanese firmware engineering labs anchor the premium tier of SSD recovery tools, their scarce controller-level expertise translating directly into pricing power for vendors serving NAND-dependent enterprises. Cloud-based subscription models in the United States and Germany compress margins at the volume base while amplifying attach rates for cryptographic verification modules.
Pricing Analysis
Geographic price spreads separate North American enterprise deployments from Indian mid-market procurement by a factor reflecting firmware engineering scarcity and sovereign cloud certification overhead. Three-tier pricing structure across premium, standard, and economy levels dominates: premium tiers embed quantum-safe encryption and immutable snapshot orchestration; standard tiers cover agentless virtual machine recovery; economy tiers address basic file undeletion. Cost compression in the standard tier intensifies as hyperscale cloud operators bundle recovery into storage subscriptions. Managed service providers exhibit highest price sensitivity due to multi-tenant margin pressure, while financial services institutions under SEC and ECB oversight show least sensitivity given compliance-driven procurement mandates.
Supply Chain Analysis
Export-control regimes limiting flash translation layer reverse-engineering tools constrain talent flows from Taiwan and South Korea to Western vendors. Supply concentrates in Taiwan for NAND controller firmware expertise, the United States for hyperscale cloud orchestration platforms, and Israel for mobile device chip-off forensics. Raw material dependencies include enterprise-grade NVMe arrays, cryptographic hardware security modules, and specialized probe stations for semiconductor failure analysis. Single-source vulnerability runs through Taiwan's concentrated controller engineering talent. Distribution runs through direct enterprise sales for on-premise perpetual licenses and hyperscaler marketplaces for cloud-native deployments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is concentrating through Fortune 500 procurement consolidation and managed service provider vendor rationalization, fragmenting vendor leverage across heterogeneous client bases.
For Market Incumbents: Insulate premium positioning through captive firmware engineering capacity in Taiwan and South Korea, countering emerging specialist entrants from Israel. Vertical integration into immutable snapshot hardware appliances defends margin against hyperscale cloud bundling. Quantum-safe encryption certification investment locks in financial services procurement specifications before NIST standards fully propagate. For New Entrants and Emerging Players: Build out sovereign cloud recovery infrastructure for India's government and financial sectors, where MeitY localization mandates create procurement barriers for foreign incumbents. Edge computing recovery modules for German manufacturing IoT deployments represent the most penetrable white space. Go-to-market through regional managed service provider partnerships bypasses direct enterprise sales cycle disadvantages. For Investors and Strategic Acquirers: Long-term, this sits as a compliance-technology play because regulatory disclosure requirements from the SEC, EU AI Act, and China's Personal Information Protection Law permanently expand addressable spend on auditable recovery systems. Acquisition targets should display controller-level firmware expertise or FedRAMP/MeitY certification pathways. The signal to watch is sovereign cloud procurement volume acceleration in India and the Middle East as data localization mandates proliferate.| Strategic Initiative | Industry Significance |
|---|---|
| Quantum-Safe Encryption Integration | NIST post-quantum standards intersect with backup integrity requirements for financial services procurement. |
| Sovereign Cloud Partnership | MeitY certification in India and FedRAMP authorization create extended but defensible market entry barriers. |
| Edge Computing Recovery Module Development | German manufacturing IoT deployments generate distributed needs unmet by centralized enterprise tools. |
| Immutable Snapshot Hardware Appliance Launch | Air-gapped compliance requirements in Frankfurt and Singapore sustain capital-intensive tier demand. |
| Consumption-Based Pricing Transition | Operational expenditure alignment with actual data volumes displaces perpetual license models in US and UK. |
Research Methodology
Operator-level perspectives from CTOs at Fortune 500 enterprises, IT procurement officers at healthcare networks, platform engineers at hyperscale cloud providers, and integration specialists at managed service providers anchored the qualitative base. Secondary validation drew from SEC cybersecurity disclosure filings, HIPAA OCR enforcement action records, EU AI Act documentation requirements, and hyperscaler capex disclosures. Bottom-up sizing of deployment model segments and top-down cross-check against aggregate infrastructure spend established numerical integrity.
Scenario bracketing bounded projections across regulatory enforcement intensity variants and ransomware incident frequency assumptions. Segmentation dimensions modeled encompass deployment architecture, data type complexity, end-user procurement authority, and regional regulatory cluster. CAGRs derived from segment-level growth rate synthesis weighted by revenue contribution shifts. Forecast inputs included sovereign cloud procurement pipeline data and flash storage penetration curves.
The forecast holds incumbent behavior within observed patterns; aggressive moves by hyperscale cloud operators bundling recovery into storage tiers would shift outcomes. Material shifts in cross-border data localization mandates or NIST post-quantum cryptography standard timelines would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Software & Services
Equipment Management Software Market
Software & Services
Freight Management Software Market
Software & Services
Office Software Market
Software & Services
Global Brand Management Software Market
Software & Services
Inventory Management Software Market
Software & Services
Labor Management Software Market
Software & Services
Global Sales Enablement Platform Market
Software & Services
Global Handyman Software Market
Software & Services
Photobooth Software Market
Software & Services
Global Pre-Employment Testing Software Market
Software & Services
Global Rapid Application Development Market
Software & Services
Global Electronic Dictionary Market
Software & Services
Stock Footage Software Market
Software & Services
Global Diagram Software Market
Software & Services
Photo Editor App Market
Software & Services
K8s Market