
 Identity-As-A-Service (Idaas) Market | 2026-2036
Identity-As-A-Service (Idaas) Market Size, Share, and Industry Trends Forecast 2026-2036
Identity-As-A-Service (Idaas) Market Foresight
Subscription-based access to authentication and directory services is restructuring how organizations procure identity infrastructure. Microsoft Corporation leverages its Azure Active Directory integration to dominate enterprise renewals. Okta, Inc. specializes in cloud-native single sign-on for hybrid workforces. Ping Identity Corporation anchors high-assurance federal deployments with FIPS-validated hardware modules.
Identity-As-A-Service delivers cloud-hosted identity and access management through multi-tenant platforms that federate user credentials across distributed applications, typically employing SAML 2.0 or OIDC protocols with token-based session management. Its primary commercial purpose is to eliminate on-premises identity infrastructure while enforcing consistent policy enforcement across SaaS, PaaS, and private workloads. Public cloud deployments now capture the majority of new bookings as lift-and-shift migrations accelerate, though hybrid cloud configurations retain margin concentration due to complex integration requirements. Single sign-on solutions lead solution-category revenue, while identity governance represents the fastest-expanding segment as SOX and GDPR audit scopes widen.
GDPR enforcement by EU national data protection authorities and the EU AI Act's risk-classification framework are mandating granular access logging and automated provisioning controls. In the United States, NIST SP 800-63 digital identity guidelines and SEC cybersecurity disclosure rules are reshaping buyer specifications for audit trails and privileged access monitoring. Stakeholders must weigh cloud-native platform consolidation against sovereign-cloud deployment requirements as regulatory fragmentation deepens.
Market Dynamics
Zero-trust architecture mandates are compressing replacement cycles for legacy identity infrastructure, forcing organizations to abandon perimeter-based security models in favor of continuous verification frameworks.
Growth Catalysts
- NIS2 Directive:European network security obligations are compelling mid-market enterprises to outsource identity governance to compliant cloud platforms rather than maintain on-premises directories.
- Financial services procurement:Banks and insurers are consolidating fragmented authentication systems to meet SEC cybersecurity disclosure requirements for privileged access monitoring.
- Biometric liveness detection:FIDO2 and WebAuthn standards are displacing password-based workflows in high-assurance deployments across federal and healthcare sectors.
Market Restraints
- Sovereign cloud fragmentation:Data localization requirements in Germany, France, and Saudi Arabia are forcing vendors to maintain separate infrastructure stacks, elevating operational costs.
- Skills scarcity:Shortages of identity architects certified in SCIM provisioning and SAML federation are extending implementation timelines for complex hybrid deployments.
- Vendor concentration risk:Reliance on hyperscaler identity layers creates single points of failure when regional outages disrupt authentication flows across dependent SaaS ecosystems.
Strategic Opportunities
- Machine identity expansion:Service account proliferation in Kubernetes and serverless environments is opening adjacent revenue streams beyond human user management.
- India's digital public infrastructure:The country's Aadhaar-linked identity stack and RBI guidelines on digital payments are accelerating demand for interoperable authentication services.
- Passwordless convergence:Integration of passkey standards with physical security keys is creating unified credential ecosystems that span consumer and workforce use cases.
Industry Challenges
- Legacy directory synchronization:Maintaining bidirectional flows between Active Directory and cloud identity providers introduces latency and conflict resolution complexity during migration windows.
- Cross-border audit fragmentation:Reconciling GDPR's data minimization principles with NIST SP 800-63 identity assurance levels demands redundant logging architectures that inflate storage costs.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Identity-As-A-Service (Idaas) Market |
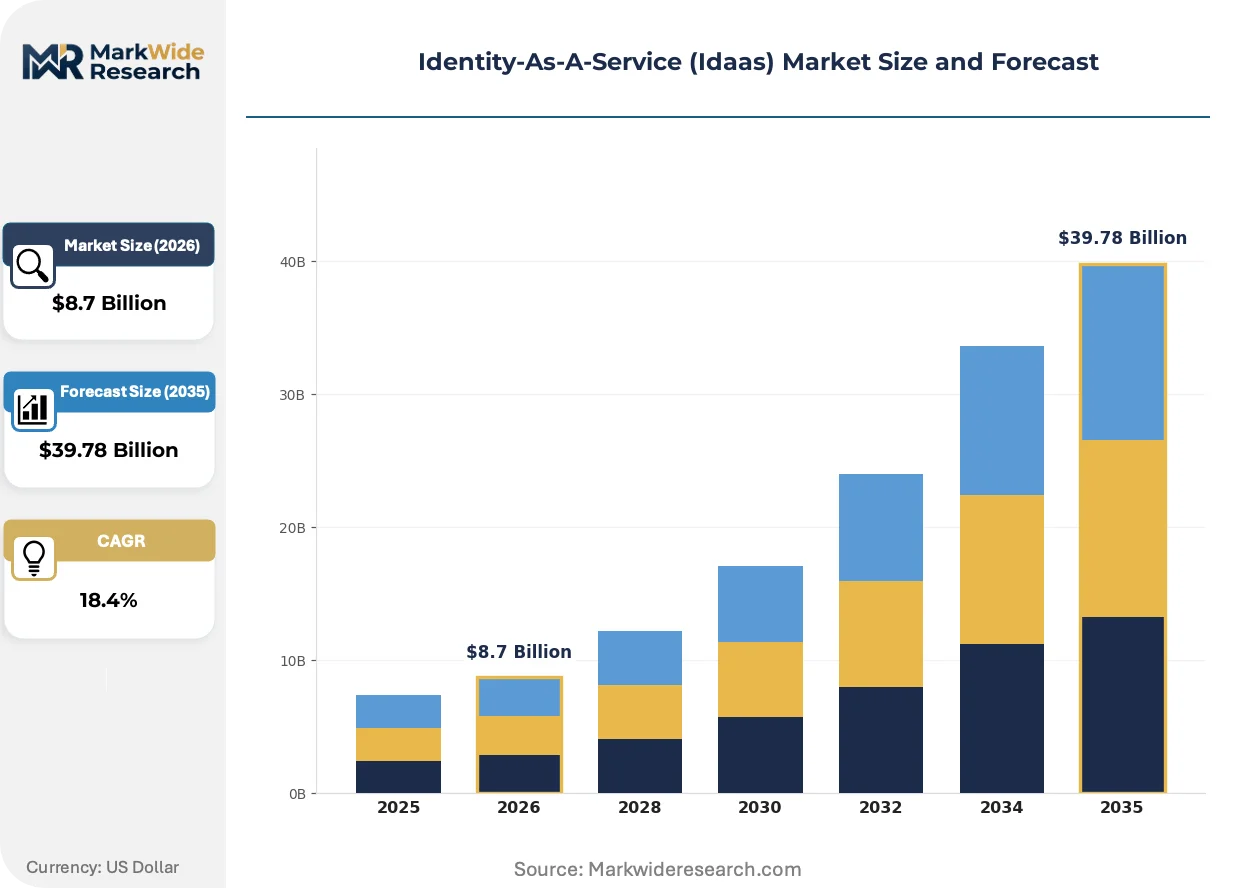
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $39.78 Billion |
| CAGR (2026 – 2036) | 18.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Authentication, Authorization, User Management, Directory Services Deployment Model: Public Cloud, Private Cloud, Hybrid Cloud, On-Premises End User: Enterprises, SMBs, Government Agencies, Educational Institutions Solution: Single Sign-On, Multi-Factor Authentication, Access Management, Identity Governance |
| Companies Covered | Okta, Inc., Microsoft Corporation, Ping Identity Corporation, Oracle Corporation, IBM Corporation, Google LLC, Thales Group, OneLogin, Inc., SailPoint Technologies, Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Identity-As-A-Service (Idaas) Market Shifts & Advancements
Identity infrastructure is converging around continuous authentication models that replace static credential checks with behavioral signals and device posture telemetry.
Passwordless authentication is consolidating enterprise authentication stacks by unifying phishing-resistant credentials across workforce and consumer-facing applications. Manufacturing and energy firms are deploying FIDO2 security keys at scale to eliminate credential reuse risks. This consolidation is compressing the addressable market for standalone multi-factor authentication point solutions.
The EU AI Act's risk-classification framework is mandating automated access logging for high-risk AI systems that process biometric or financial data. Organizations deploying machine learning for fraud detection must now maintain immutable audit trails of model training data access. German industrial conglomerates are responding by embedding identity governance directly into MLOps pipelines.
Consumption-based licensing is displacing per-seat subscription models as IoT and machine identity volumes render user-count pricing economically unworkable. Automotive and logistics buyers are negotiating API-call-based contracts that scale with connected vehicle and sensor authentication events. This shift is most pronounced in fleet management deployments across North American and European markets.
Identity-As-A-Service (Idaas) Market Segmentation
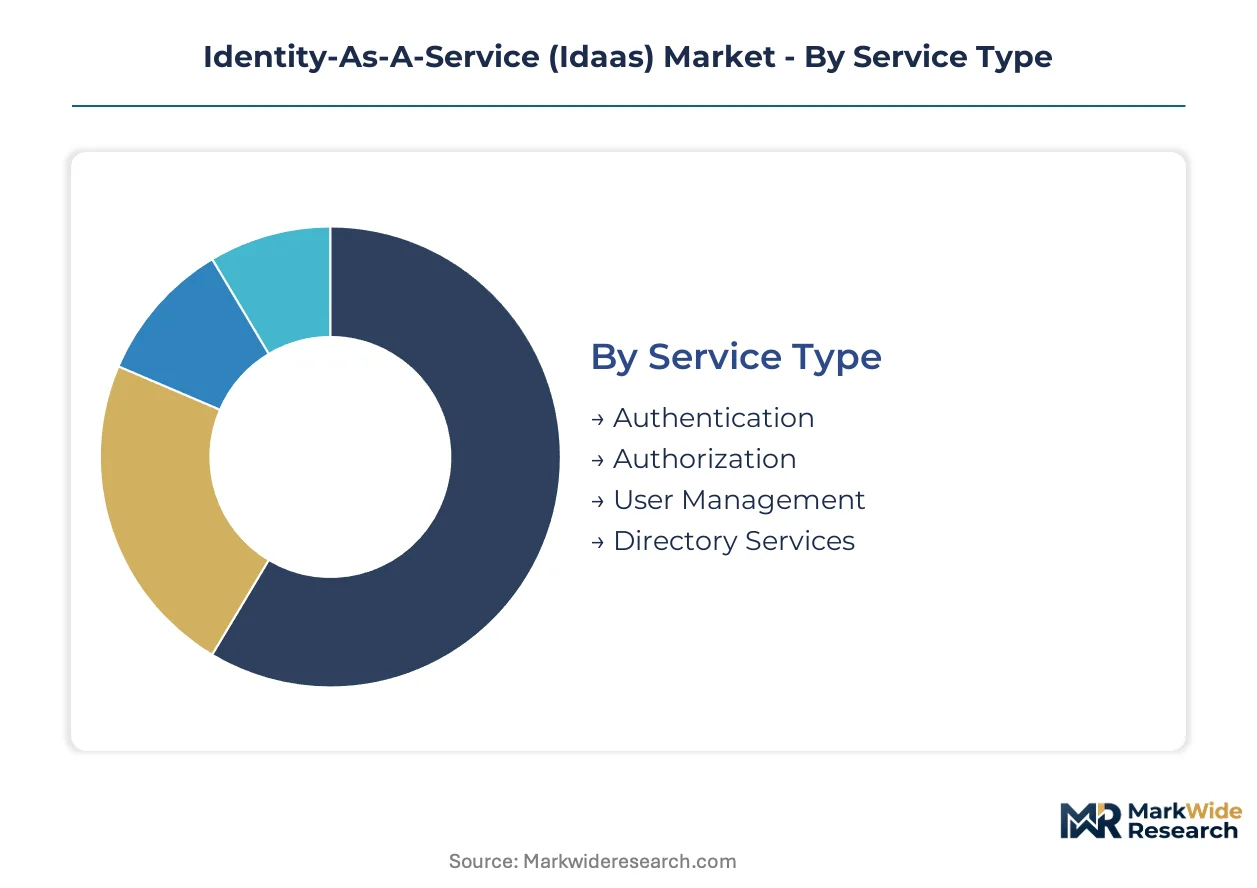
IdaaS procurement hinges on matching identity workload sensitivity to deployment architecture and compliance posture. Buyers segment investments across four dimensions that determine integration complexity, recurring cost structure, and regulatory coverage.
Service Type:
Organizations prioritize service bundles that reduce vendor sprawl while preserving specialized capabilities for high-assurance use cases.
- Authentication:Cloud-hosted credential verification using FIDO2, WebAuthn, and biometric liveness detection protocols. German automotive manufacturers and US federal contractors are standardizing on phishing-resistant methods to satisfy NIS2 and NIST SP 800-63 requirements.
- Authorization:Policy engines that enforce attribute-based access control across distributed microservices. Financial services firms in Frankfurt and London are deploying fine-grained authorization to meet SEC cybersecurity disclosure mandates for privileged access monitoring.
- User Management:Lifecycle automation for provisioning, deprovisioning, and role recertification workflows.
- Directory Services:Cloud-native LDAP and Active Directory alternatives with multi-tenant scalability.
Volume sits with Authentication; growth tilts toward Authorization.
Deployment Model:
Data residency requirements and latency constraints fragment infrastructure decisions across sovereignty boundaries.
- Public Cloud:Multi-tenant platforms delivering elastic scale without dedicated infrastructure. SaaS-native enterprises in Bangalore and São Paulo favor public deployments for rapid workforce onboarding.
- Private Cloud:Single-tenant instances hosted in customer-controlled environments. Saudi Aramco and European defense contractors mandate private stacks to satisfy data localization under national cybersecurity frameworks.
- Hybrid Cloud:Federated architectures synchronizing on-premises directories with cloud identity providers. German industrial conglomerates rely on hybrid configurations during Active Directory migration windows.
- On-Premises:Legacy appliance-based deployments retained for air-gapped operational technology networks.
Deployment share concentrates in Public Cloud; steepest expansion trajectory belongs to Hybrid Cloud.
End User:
Budget cycles and audit sophistication separate buyer tiers more sharply than organization size alone.
- Enterprises:Global organizations with 10,000+ identities requiring unified governance across subsidiaries. Japanese automotive groups and Swiss pharmaceutical multinationals are consolidating fragmented identity estates.
- SMBs:Mid-market buyers outsourcing directory maintenance to reduce IT headcount. Indian fintech startups and Australian professional services firms are adopting pre-configured IdaaS bundles.
- Government Agencies:Federal, state, and municipal entities with FIPS 140-2 or Common Criteria certification requirements.
- Educational Institutions:Universities and K-12 districts managing seasonal enrollment spikes and research data access.
Revenue accrues to Enterprises; SMBs are climbing the fastest.
Solution:
Integration depth and audit automation capability determine solution selection within procurement evaluations.
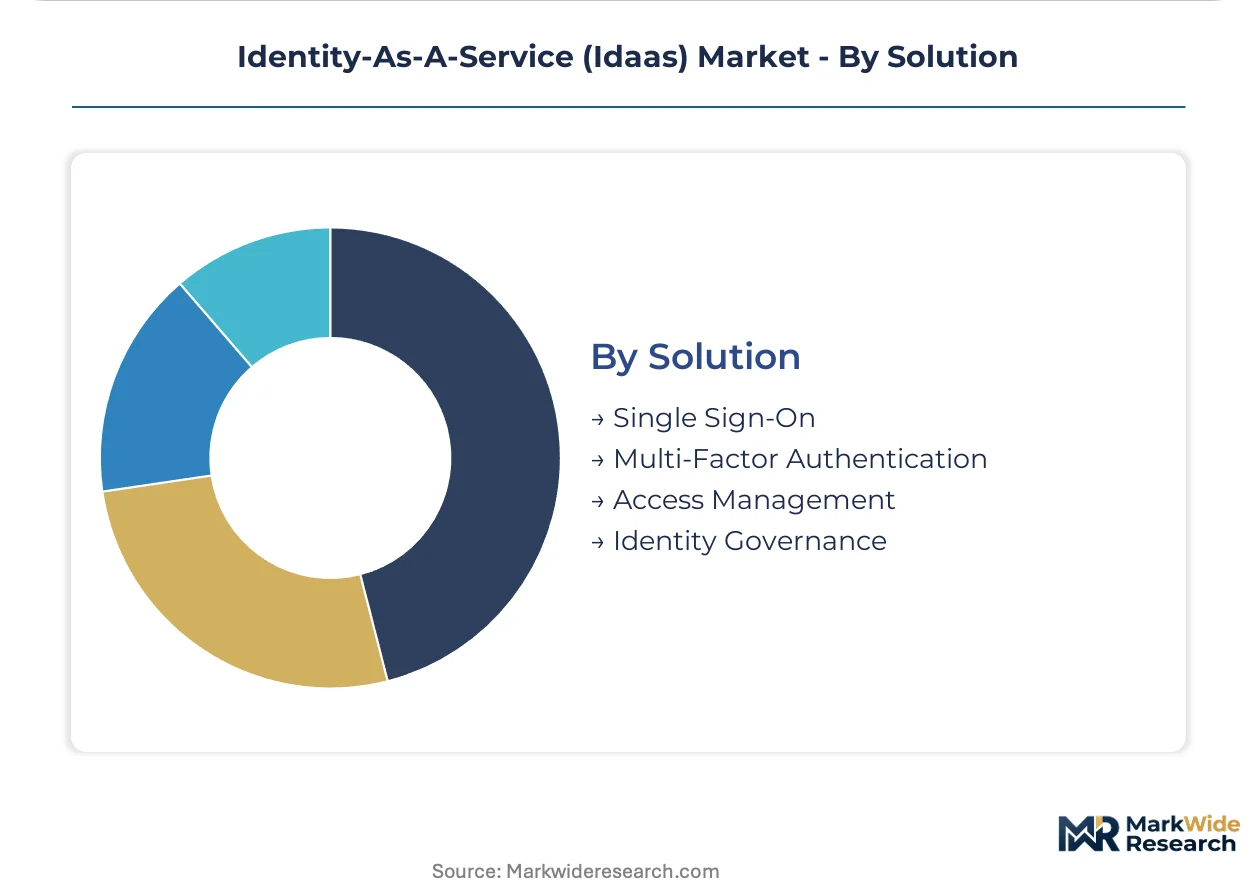
- Single Sign-On:SAML 2.0 and OIDC federation for seamless application access. US healthcare systems and UK financial services deploy SSO to satisfy HIPAA and FCA operational resilience rules.
- Multi-Factor Authentication:Step-up authentication using push notifications, TOTP, and hardware tokens. Brazilian banks and South Korean e-commerce platforms are displacing SMS-based methods.
- Access Management:Session monitoring and risk-based step-up for dynamic policy enforcement.
- Identity Governance:Automated certification campaigns and segregation-of-duties analysis. French insurers and Dutch pension funds are expanding governance coverage to meet CSRD audit scope requirements.
Single Sign-On dominates current bookings; Identity Governance is gaining share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
IdaaS consumption concentrates in economies with stringent cybersecurity mandates and fragmented legacy identity estates. Production of cloud-native identity platforms originates primarily from US and European technology hubs. Sovereign data requirements are fragmenting deployment architectures across national boundaries.
United States
Financial services and federal contractors drive procurement intensity. SEC cybersecurity disclosure rules and NIST SP 800-63 guidelines mandate privileged access monitoring with immutable audit trails. New York and Washington DC metro areas host the densest concentrations of zero-trust migration projects.
Germany
Industrial conglomerates consolidate fragmented Active Directory estates under NIS2 Directive pressure. The EU AI Act's risk-classification framework requires automated provisioning controls for high-risk systems. Munich and Stuttgart manufacturing clusters embed identity governance into operational technology networks.
United Kingdom
London financial services firms displace perimeter-based security models with continuous verification frameworks. FCA operational resilience rules and GDPR enforcement reshape authentication procurement specifications. The Thames Valley technology corridor anchors cloud-native single sign-on deployments for hybrid workforces.
India
Fintech startups and digital payment platforms accelerate demand for interoperable authentication services. RBI guidelines on digital payments and the Aadhaar-linked identity stack create regulatory tailwinds. Bangalore and Mumbai technology clusters adopt pre-configured IdaaS bundles to reduce IT headcount.
Japan
Automotive groups and pharmaceutical multinationals unify governance across subsidiary identity estates. METI cybersecurity frameworks and data localization preferences favor hybrid cloud configurations. Tokyo and Osaka enterprise hubs prioritize FIDO2 security key deployments for phishing-resistant workforce authentication.
Identity-As-A-Service (Idaas) Market Competitive Landscape
Capital-heavy hyperscalers compete with asset-light identity specialists for enterprise authentication workloads. The vendor base stratifies across three tiers: cloud-native platforms with multi-tenant scale, legacy infrastructure vendors pivoting to subscription models, and point-solution specialists in high-assurance niches. Dominant competitive moves include strategic partnerships with SaaS ecosystems and vertical integration into adjacent security categories.
Within the cloud-native tier, Microsoft Corporation and Google LLC anchor hyperscaler identity layers that capture public cloud bookings through native integration. Okta, Inc. and Ping Identity Corporation occupy positions as independent specialists serving hybrid and multi-cloud deployments. Thales Group represents the hardware-anchored archetype with FIPS-validated modules for federal and defense segments.
| Leading Market Players |
|---|
| Okta, Inc. |
| Microsoft Corporation |
| Ping Identity Corporation |
| Oracle Corporation |
| IBM Corporation |
| Google LLC |
| Thales Group |
| OneLogin, Inc. |
| SailPoint Technologies, Inc. |
| Others |
Supply & Pricing Matrix
Financial services procurement concentration anchors subscription-based pricing models across the Identity-As-A-Service landscape, with tiered SaaS contracts scaling according to identity volume and compliance certification levels. Sovereign cloud mandates in Germany and Saudi Arabia fragment infrastructure economics, forcing vendors to maintain parallel operational stacks that inflate cost-to-serve calculations.
Pricing Analysis
Margin tightening in hybrid cloud configurations reflects complex Active Directory synchronization requirements and extended implementation timelines. Three-tier pricing structure across premium FIPS-validated, standard enterprise, and economy SMB levels separates federal-grade deployments from mid-market bundles. Pricing pressure intensifies in the public cloud tier as hyperscaler-native identity layers commodify basic authentication workloads. SMB buyers exhibit highest price sensitivity, while federal contractors absorb certification premiums without volume negotiation.
Supply Chain Analysis
Data localization mandates in Germany, France, and Saudi Arabia are reshaping vendor sourcing strategies toward in-region infrastructure deployment. Cloud-native identity platforms draw from US and European software development centers, with hardware security module production anchored in Thales Group's French and US facilities. Single-source vulnerability concentrates in FIPS 140-2 validated semiconductor supply for federal deployments. Distribution runs through direct enterprise sales teams for large accounts and hyperscaler marketplaces for mid-market procurement.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Identity infrastructure is transitioning from perimeter-based directories to continuous verification frameworks, with FIDO2 and WebAuthn protocols displacing password-dependent architectures across enterprise and consumer deployments.
For Market Incumbents: Cement dominance in hybrid cloud configurations by deepening Active Directory migration tooling and SCIM provisioning automation. Threats from hyperscaler-native identity layers require defensive certification investments in Common Criteria and FIPS 140-2 validation to preserve federal market access. Channel control through SaaS marketplace integration represents the priority lever for mid-market retention. For New Entrants and Emerging Players: Launch via API-call-based consumption models targeting automotive fleet management and IoT machine identity expansion in North American markets. India's Aadhaar-linked digital payment infrastructure offers the most penetrable geography for interoperable authentication services. Vertical specialization in MLOps pipeline governance for EU AI Act compliance creates differentiation against generalized platforms. For Investors and Strategic Acquirers: The window for entry favors identity governance specialists with automated certification campaign capabilities and CSRD audit scope coverage. Long-term viability hinges on machine identity management adjacencies beyond human user provisioning. Watch for passkey standard convergence across consumer and workforce use cases as inflection signal for platform consolidation acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Platform Integration | Embedding identity governance into MLOps pipelines satisfies EU AI Act automated logging mandates for German manufacturers. |
| Strategic Partnership | SaaS ecosystem alliances with Microsoft Azure and Google Cloud capture enterprise renewal workflows through native directory synchronization. |
| Acquisition of Specialist Firm | Consolidating SCIM provisioning and SAML federation capabilities addresses skills scarcity extending hybrid deployment timelines. |
| Geographic Expansion | Sovereign cloud infrastructure in Riyadh and Paris satisfies data localization under Saudi and French national cybersecurity frameworks. |
| Product Launch | Consumption-based API licensing for connected vehicle authentication aligns with automotive fleet management procurement patterns. |
Research Methodology
Trade association data, regulatory filings, and customs records anchored secondary inputs for this analysis, supplemented by primary interviews with CISOs, identity architects, cloud procurement officers, and federal IT security leads. SEC cybersecurity disclosure submissions, EU NIS2 implementation guidance, NIST SP 800-63 documentation, and hyperscaler capex disclosures provided validation benchmarks. Bottom-up identity volume estimates triangulated against top-down enterprise IT spending projections.
Granularity-level modeling distinguished deployment architecture, organization size tier, vertical industry, integration complexity, and regional regulatory cluster across the projection horizon. CAGRs derived from segment-level identity volume trajectories and pricing evolution assumptions. FIDO2 adoption curves, machine identity proliferation rates, and sovereign cloud deployment timelines served as industry-specific forecast inputs.
Regulatory enforcement variance, hyperscaler outage frequency, and biometric standard fragmentation are the dominant revision risks to modeled assumptions. Forecasts reflect documented scenario parameters without contingency buffers for unmandated compliance acceleration. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Security Software
Global Software-Defined Security Market
Security Software
Global Advanced Authentication Market
Security Software
Smartphone Security Market
Security Software
Application Control Market
Security Software
Wi-Fi Based Home Camera Market
Security Software
United States Lawful Interception Market
Security Software
Secure Email Gateway Market
Security Software
Asia-Pacific Fraud Detection & Prevention Market
Security Software
Website Monitoring Software Market
Security Software
Secure Flash Drive Market
Security Software
Global Enterprise Data Loss Prevention Software Market
Security Software
Bot Mitigation Market
Security Software
Enterprise Rights Management Solution Market
Security Software
Embedded Security Market
Security Software
Web Content Filtering Market
Security Software
Asia-Pacific Extended Detection and Response Market